
 Middle-East and Africa Colorectal Cancer Market | 2026-2036
Middle-East and Africa Colorectal Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Colorectal Cancer Market Foresight
Modular diagnostic service bundling is pivoting how hospitals procure colorectal cancer workflows across the Middle-East and Africa. Koninklijke Philips N.V. leverages integrated imaging-to-pathology platforms to anchor multi-year service contracts with large hospital chains. Quest Diagnostics Incorporated competes through centralized reference laboratory networks that extend molecular testing reach into secondary cities.
Colorectal cancer encompasses malignancies of the colon and rectum, diagnosed through histopathological examination of tissue biopsies, immunohistochemistry profiling, and circulating tumor DNA analysis, with treatment spanning surgical resection, systemic chemotherapy, and targeted monoclonal antibody therapy. Biologics and targeted therapy segments command premium positioning due to patent-protected mechanisms and biomarker-driven patient selection. Hospitals dominate end-user demand through high-volume screening colonoscopy programs and multidisciplinary tumor boards, while homecare settings represent an emerging channel for oral chemotherapy administration.
Saudi FDA, South African Health Products Regulatory Authority, and UAE Ministry of Health and Prevention shape market access through divergent registration timelines and biologics licensing requirements that fragment product launch sequencing. WHO prequalification standards and national essential medicines lists further filter which therapies enter public procurement channels. Stakeholders must monitor harmonization efforts between Gulf Cooperation Authority regulatory frameworks and sub-Saharan national control laboratories to anticipate portfolio prioritization shifts.
Market Dynamics
Molecular diagnostics capacity expansion across tertiary oncology departments is restructuring competitive positioning in the Middle-East and Africa colorectal cancer market, with integrated imaging-to-pathology platforms displacing standalone testing workflows.
Growth Catalysts
- SFDA companion diagnostics registration pathways:Saudi FDA's streamlined biomarker approval frameworks accelerate market entry for precision oncology assays, reducing time-to-revenue for diagnostic manufacturers targeting the Kingdom's hospital chains.
- South African private healthcare investment:Tertiary hospitals in Johannesburg and Cape Town are expanding molecular pathology laboratories, creating concentrated demand hubs for immunohistochemistry and circulating tumor DNA platforms.
- National screening program mandates:Government-led colorectal cancer screening initiatives across Gulf Cooperation Authority member states are institutionalizing colonoscopy volume growth and anchoring multi-year service contracts.
Market Restraints
- Reagent import dependency:Molecular testing workflows rely on temperature-controlled supply chains from European and North American manufacturers, exposing laboratories to currency volatility and customs clearance friction.
- Pathologist workforce scarcity:Sub-Saharan Africa operates with fewer than 100 board-certified gastrointestinal pathologists across 46 countries, creating diagnostic bottleneck capacity constraints.
- Biologics cold chain infrastructure gaps:Targeted monoclonal antibody therapies require uninterrupted 2-8°C distribution networks that remain underdeveloped outside South Africa, Saudi Arabia, and UAE urban centers.
Strategic Opportunities
- Homecare oral chemotherapy administration:Emerging channel expansion for capecitabine and regorafenib regimens enables patient adherence monitoring through remote pharmacy networks, particularly in South African metropolitan peripheries.
- UAE Ministry of Health and Prevention harmonization:Convergence of Gulf Cooperation Authority regulatory frameworks is creating unified registration pathways that reduce duplicate submission costs across Bahrain, Kuwait, Oman, Qatar, Saudi Arabia, and UAE.
- AI-augmented histopathology:Integration of digital pathology platforms with machine learning algorithms is compressing diagnostic turnaround times for tissue biopsy analysis in high-volume screening programs.
Industry Challenges
- Multidisciplinary tumor board coordination:Synchronous participation of surgical oncologists, medical oncologists, radiologists, and pathologists requires dedicated scheduling infrastructure that many secondary hospitals lack.
- WHO prequalification timeline variability:Essential medicines list inclusion processes for bevacizumab biosimilars and cetuximab generics extend 18-36 months, delaying public procurement access in price-sensitive markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Colorectal Cancer Market |
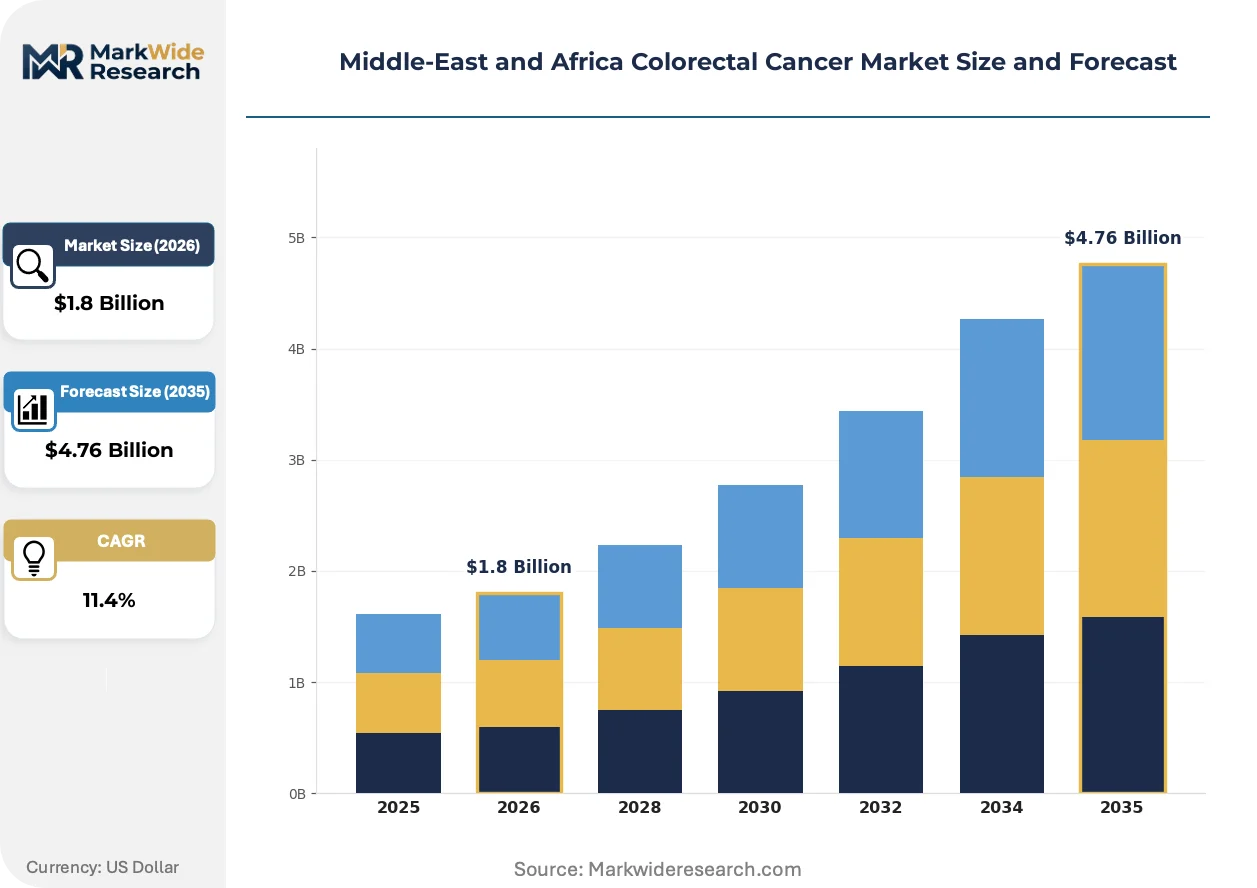
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Chemotherapy, Targeted Therapy, Radiation Therapy End User: Hospitals, Clinics, Research Institutes, Homecare Settings Delivery Mode: Intravenous, Oral, Subcutaneous, Topical Application: Screening, Diagnosis, Treatment, Palliative Care |
| Companies Covered | Koninklijke Philips N.V., Quest Diagnostics Incorporated, Bio-Rad Laboratories, Inc., Merck KGaA, FUJIFILM Corporation, Agilent Technologies, Inc., BD, General Electric Company, Siemens Healthcare GmbH, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Colorectal Cancer Market Shifts & Advancements
Liquid biopsy platforms are restructuring diagnostic workflows across Middle-East and Africa oncology departments, with circulating tumor DNA analysis enabling real-time treatment monitoring without invasive tissue sampling.
Next-generation sequencing panels are electrifying precision oncology adoption in Saudi Arabian and South African tertiary centers, with molecular tumor boards at King Faisal Specialist Hospital and Groote Schuur Hospital integrating comprehensive genomic profiling into first-line treatment selection. Academic medical centers are compressing the interval between biopsy collection and actionable biomarker reporting from fourteen days to seventy-two hours, enabling faster enrollment in targeted therapy protocols.
South African Health Products Regulatory Authority biologics licensing requirements are tightening manufacturing quality documentation standards for imported originator and biosimilar monoclonal antibodies, forcing suppliers to submit extended stability data and local storage validation studies. Oncology departments are responding by consolidating purchasing through prequalified distributor networks that maintain temperature-controlled warehousing in Johannesburg, Durban, and Cape Town.
Service contract unbundling is fragmenting how hospital procurement teams acquire colorectal cancer diagnostics, with separate negotiations emerging for instrument placement, reagent supply, and bioinformatics interpretation. Large private hospital chains in UAE and Saudi Arabia are displacing bundled agreements with modular pricing structures that match payment to actual test volumes, transferring utilization risk from capital budgets to operational expenditure lines.
Middle-East and Africa Colorectal Cancer Market Segmentation
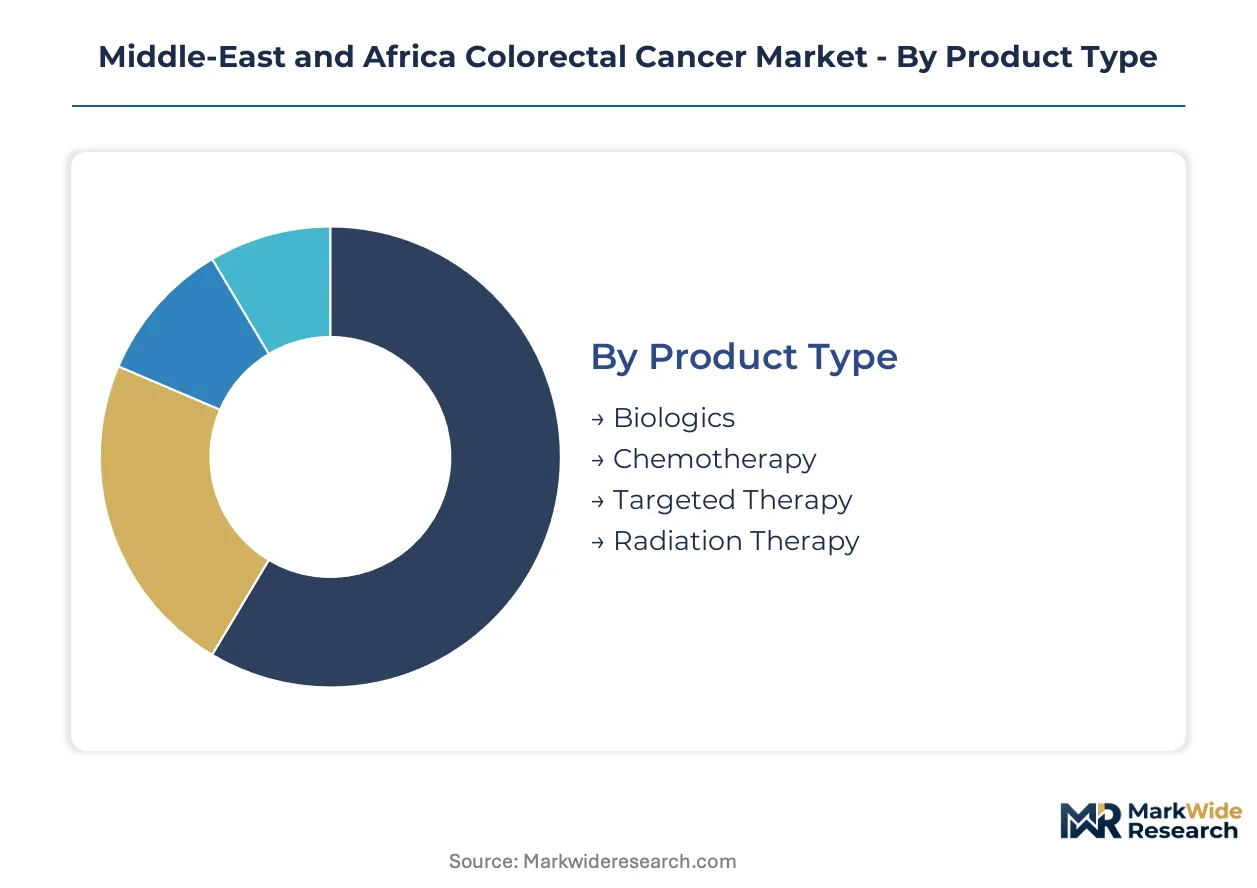
Colorectal cancer market segmentation across the Middle-East and Africa reflects divergent healthcare infrastructure maturity, with tertiary hospital capacity in Saudi Arabia and South Africa driving premium therapy uptake while resource-limited settings sustain demand for conventional chemotherapy protocols.
Product Type:
Procurement patterns diverge sharply between public tenders prioritizing cost containment and private hospital chains seeking biomarker-driven precision therapies.
- Biologics:Patent-protected monoclonal antibodies including bevacizumab and cetuximab require cold chain distribution validated through Saudi FDA and South African Health Products Regulatory Authority licensing. Demand concentrates in King Faisal Specialist Hospital and Groote Schuur Hospital molecular tumor boards where comprehensive genomic profiling guides first-line patient selection.
- Targeted Therapy:Biomarker-directed small molecule inhibitors and antibody-drug conjugates command premium positioning through companion diagnostic requirements. Saudi Arabia's SFDA streamlined registration pathways accelerate market entry for precision oncology assays paired with these agents.
- Chemotherapy:Oxaliplatin and fluorouracil regimens dominate public procurement channels across Gulf Cooperation Authority member states.
- Radiation Therapy:External beam and brachytherapy protocols serve neoadjuvant and palliative indications in tertiary oncology departments.
Biologics leads volumes today; targeted therapy is gaining share fastest.
End User:
Facility certification tiers determine reimbursement eligibility and therapy access corridors across national health systems.
- Hospitals:Tertiary oncology departments anchor high-volume screening colonoscopy programs and multidisciplinary tumor boards requiring synchronous participation of surgical oncologists, medical oncologists, radiologists, and pathologists. Johannesburg and Cape Town private hospital chains are expanding molecular pathology laboratory capacity.
- Homecare Settings:Oral capecitabine and regorafenib administration enables patient adherence monitoring through remote pharmacy networks, particularly in South African metropolitan peripheries where transport burdens limit hospital visit frequency.
- Clinics:Secondary city facilities rely on centralized reference laboratory networks for molecular testing reach.
- Research Institutes:Academic medical centers at King Faisal Specialist Hospital and Groote Schuur Hospital compress biopsy-to-biomarker reporting intervals.
Hospitals dominate current demand; homecare settings are expanding most quickly.
Delivery Mode:
Route selection intertwines with cold chain infrastructure availability and patient self-administration capacity.
- Intravenous:Infusion center capacity constraints at tertiary hospitals limit throughput for monoclonal antibody therapies requiring supervised administration.
- Oral:Capecitabine and regorafenib formulations bypass cold chain dependencies and enable decentralized treatment delivery.
- Subcutaneous:Reduced infusion time protocols are gaining traction in UAE private hospital chains seeking throughput optimization.
- Topical:Rectal application routes serve localized palliative indications with minimal systemic exposure.
Intravenous administration retains the largest patient volume; oral delivery is climbing the fastest.
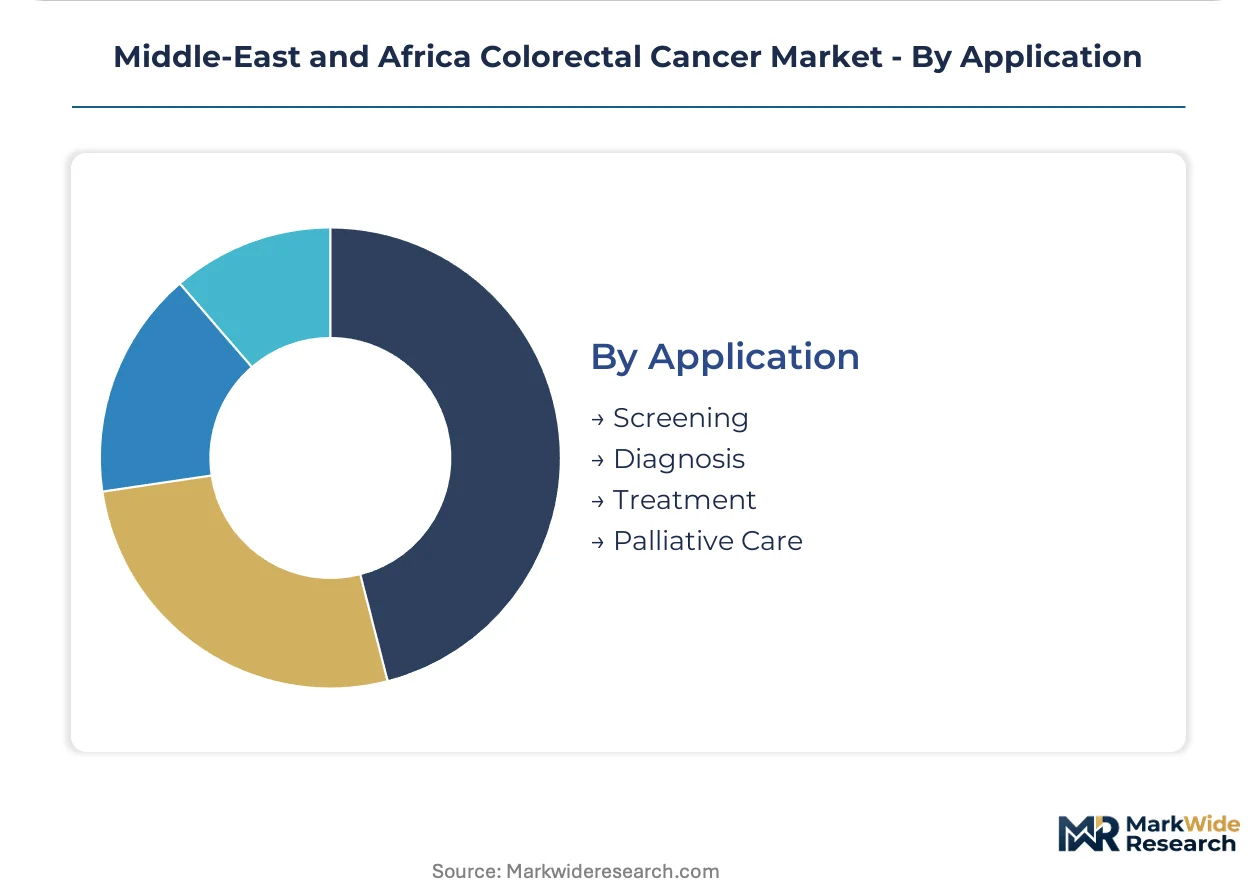
Application:
Clinical utility stages map to distinct reimbursement codes and procurement budgeting cycles across national health systems.
- Screening:Government-led colorectal cancer initiatives across Gulf Cooperation Authority member states institutionalize colonoscopy volume growth. SFDA registration pathways for companion diagnostics accelerate biomarker adoption in screening workflows.
- Treatment:Curative-intent surgical resection combined with neoadjuvant and adjuvant systemic therapy commands the largest share of pharmaceutical expenditure. Integrated imaging-to-pathology platforms at Saudi Arabian and South African tertiary centers are displacing standalone testing workflows.
- Diagnosis:Histopathological examination, immunohistochemistry profiling, and circulating tumor DNA analysis enable molecular tumor board treatment selection.
- Palliative Care:Symptom-focused protocols prioritize oral chemotherapy regimens minimizing hospital dependency.
Treatment applications anchor current spending; screening programs show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Colorectal cancer diagnostics and therapeutics first achieved commercial scale in South African tertiary hospitals during the 1990s, with molecular pathology capacity later expanding northward through Gulf Cooperation Authority investment cycles.
South Africa
Private hospital chains in Johannesburg and Cape Town anchor molecular diagnostics demand, with Groote Schuur Hospital compressing biopsy-to-biomarker reporting intervals. The South African Health Products Regulatory Authority enforces tightened biologics licensing documentation. Durban maintains temperature-controlled warehousing networks for monoclonal antibody distribution.
Saudi Arabia
King Faisal Specialist Hospital integrates comprehensive genomic profiling into first-line treatment selection. The Saudi FDA operates streamlined companion diagnostics registration pathways. Riyadh-based tertiary oncology departments anchor multi-year service contracts for integrated imaging-to-pathology platforms.
United Arab Emirates
Dubai private hospital chains pursue throughput optimization through reduced-infusion-time subcutaneous protocols. The Ministry of Health and Prevention drives Gulf Cooperation Authority regulatory harmonization. Abu Dhabi academic medical centers deploy digital pathology platforms with machine learning algorithms.
Egypt
Cairo tertiary facilities rely on centralized reference laboratory networks for molecular testing reach. The national pharmaceutical regulator filters essential medicines list inclusion for bevacizumab biosimilars. Alexandria oncology departments face pathologist workforce scarcity constraints.
Nigeria
Lagos secondary city clinics depend on South African and UAE laboratory networks for circulating tumor DNA analysis. The national control laboratory coordinates WHO prequalification alignment efforts. Kano experiences cold chain infrastructure gaps for targeted monoclonal antibody therapies.
Middle-East and Africa Colorectal Cancer Market Competitive Landscape
Premium-margin players sit above commodity-margin players across biomarker-driven precision oncology segments, with integrated platform vendors commanding multi-year service contracts while standalone reagent suppliers compete on price. The market exhibits tiered consolidation around imaging-to-pathology workflows and centralized reference laboratory networks. Three archetypes dominate: diversified health technology conglomerates anchoring hospital chain relationships, specialized diagnostics companies extending molecular testing reach, and pharmaceutical manufacturers with companion diagnostic portfolios. Competitive moves concentrate on modular service contract unbundling and AI-augmented histopathology integration.
Within the diversified health technology tier, Koninklijke Philips N.V. and Siemens Healthcare GmbH exemplify integrated platform strategies, while Quest Diagnostics Incorporated occupies a position representing centralized reference laboratory expansion. These three entities anchor different competitive vectors—imaging-to-pathology integration, diagnostic instrumentation, and laboratory network reach—without overlapping positioning.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Quest Diagnostics Incorporated |
| Bio-Rad Laboratories, Inc. |
| Merck KGaA |
| FUJIFILM Corporation |
| Agilent Technologies, Inc. |
| BD |
| General Electric Company |
| Siemens Healthcare GmbH |
| Others |
Supply & Pricing Matrix
Captive temperature-controlled warehousing in Johannesburg, Riyadh, and Dubai anchors supply positioning and pricing power for biologics distributors serving Middle-East and Africa oncology departments. This vertical integration choice concentrates margin capture with prequalified distributors while fragmenting pricing leverage among standalone reagent suppliers competing on instrument placement terms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates patent-protected monoclonal antibodies from biosimilar alternatives and conventional chemotherapy protocols. Price differentiation hinges on Saudi FDA registration tier and cold chain validation documentation, with public procurement channels in Gulf Cooperation Authority states driving cost compression in the economy tier. Private hospital chains in South Africa and UAE demonstrate lowest price sensitivity due to biomarker-driven patient selection requirements.
Supply Chain Analysis
Reagent supply rests on European and North American specialty manufacturers, with diagnostic workflows drawing from German, Swiss, and US production facilities. Molecular testing inputs including polymerase chain reaction enzymes, next-generation sequencing consumables, and immunohistochemistry antibodies face single-source vulnerability from temperature-controlled logistics dependencies. Distribution runs through prequalified distributor networks maintaining validated 2-8°C warehousing in Johannesburg, Durban, Cape Town, Riyadh, and Dubai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle-East and Africa colorectal cancer market represents a late-cycle quality story as demand shifts toward comprehensive genomic profiling and companion diagnostic requirements that favor integrated platform vendors over standalone suppliers.
For Market Incumbents: Anchor multi-year service contracts through integrated imaging-to-pathology platforms at Saudi Arabian and South African tertiary hospitals. Consolidate reagent supply relationships to defend against modular procurement unbundling. Invest in AI-augmented histopathology capabilities to compress diagnostic turnaround times and lock in laboratory loyalty. For New Entrants and Emerging Players: Begin with homecare oral chemotherapy networks in South African metropolitan peripheries where transport burdens limit hospital visit frequency. Target secondary city clinics in Egypt and Nigeria dependent on centralized reference laboratory reach. Pursue partnerships with existing temperature-controlled distributors rather than building captive cold chain infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for specialized diagnostics companies because molecular pathology capacity scarcity across sub-Saharan Africa creates acquisition currency for platforms extending testing reach. Monitor SFDA companion diagnostics registration pathway velocity as the inflection indicator for precision oncology adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostics Registration | SFDA streamlined pathways accelerate biomarker assay market entry for Saudi Arabian hospital chains. |
| Temperature-Controlled Warehousing Expansion | Prequalified distributor networks in Johannesburg and Riyadh secure monoclonal antibody supply integrity. |
| AI-Augmented Histopathology Integration | Machine learning algorithms at Abu Dhabi academic centers compress biopsy-to-biomarker reporting intervals. |
| Homecare Pharmacy Network Development | Remote capecitabine administration monitoring addresses transport burdens in South African metropolitan peripheries. |
| Gulf Cooperation Authority Regulatory Harmonization | UAE Ministry of Health and Prevention convergence reduces duplicate submission costs across six member states. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down molecular diagnostics capacity tracking forms the analytical core of this study. Primary interviews with pathology laboratory directors, hospital procurement managers, regulatory affairs specialists at Saudi FDA and South African Health Products Regulatory Authority, and biologics distribution executives combined with secondary validation from SFDA registration databases, WHO prequalification listings, hospital procurement records, and Gulf Cooperation Authority harmonization policy documents.
Historical trendline analysis of colonoscopy volume growth and companion diagnostic adoption rates informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type, end-user facility tier, delivery mode, and application stage, with CAGRs derived from weighted capacity expansion trajectories at King Faisal Specialist Hospital, Groote Schuur Hospital, and Dubai private hospital chains.
Caveats apply where pathologist workforce scarcity, currency volatility affecting reagent imports, or biologics cold chain infrastructure gaps could materially shift the outlook. A small set of triggers including SFDA registration timeline changes, WHO prequalification decisions for bevacizumab biosimilars, and Gulf Cooperation Authority harmonization implementation velocity warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Food Allergy Treatment Market
Specialty Medicine
Cystic Fibrosis Transmembrane Conductance Regulator (CFTR) Market
Specialty Medicine
Cutaneous Radiation Injury Treatment Market
Specialty Medicine
Breakthrough Therapy Designation Market
Specialty Medicine
Chronic Idiopathic Constipation Treatment Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Gerontology/Aging Market
Specialty Medicine
Chronic Urticaria Market
Specialty Medicine
Major Depressive Disorder (MDD) Treatment Market
Specialty Medicine
Acute Lymphoblastic Leukemia Therapeutics Market
Specialty Medicine
Thyroid Cancer Therapeutics Market
Specialty Medicine
Soft Tissue Sarcoma Market
Specialty Medicine
Neurodegenerative Disease Market
Specialty Medicine
Global Neurotrophic Keratitis Treatment Market
Specialty Medicine
Bipolar Disorders Treatment Market
Specialty Medicine
Buruli Ulcer Treatment Market