
 Cytomegalovirus Retinitis Market | 2026-2036
Cytomegalovirus Retinitis Market Size, Share, and Industry Trends Forecast 2026-2036
Cytomegalovirus Retinitis Market Outlook
EU orphan drug designation and priority review voucher programs for rare infectious diseases is repositioning commercial incentives toward CMV retinitis drug development. Gilead Sciences, Inc leverages its nucleotide analog expertise to sustain leadership in systemic antiviral therapy for CMV complications. F. Hoffmann-La Roche Ltd anchors its position through diagnostic-therapeutic integration in immunocompromised patient management. Chimerix, Inc competes on brincidofovir's differentiated safety profile versus traditional nephrotoxic agents.
Cytomegalovirus retinitis constitutes an opportunistic viral infection of the retina caused by human cytomegalovirus, characterized by full-thickness necrotizing retinitis with hemorrhagic appearance, primarily affecting CD4+ T-cell depleted patients and requiring either intravitreal ganciclovir injection or systemic valganciclovir suppression to prevent irreversible vision loss. Among product types, valganciclovir dominates outpatient prophylaxis due to oral bioavailability advantages over intravenous ganciclovir, while intraocular administration routes command premium positioning for sight-threatening breakthrough infections in non-compliant patients. The inpatient treatment setting retains structural importance for initial induction therapy in acute retinal necrosis presentations, though outpatient treatment segments are expanding with improved oral antiviral potency.
The FDA's orphan drug regulations and EMA's PRIME designation framework for rare diseases shape clinical trial design and market exclusivity periods for CMV retinitis developers. WHO prequalification standards and national essential medicine lists in high-HIV-burden countries determine access pathways for generic antiviral procurement. Stakeholders must monitor emerging resistance patterns to first-line nucleoside analogs and the pipeline progression of novel viral terminase inhibitors that could displace existing standards of care.
Market Dynamics
Orphan drug incentives from the FDA and EMA are compressing development timelines for novel CMV therapeutics while expanding the addressable patient base through transplant and oncology unit expansion.
Growth Catalysts
- FDA Orphan Drug Designation:Accelerated approval pathways and extended market exclusivity periods incentivize developers to pursue CMV retinitis indications despite limited prevalence.
- Solid organ transplantation:Rising volumes of kidney and liver transplants create sustained demand for prophylactic antiviral therapy in immunosuppressed recipients.
- Long-acting injectable formulations:Sustained-release intravitreal implants reduce treatment burden and improve compliance in non-adherent patient populations.
Market Restraints
- Nephrotoxicity of first-line agents:Intravenous ganciclovir and foscarnet require renal monitoring that limits outpatient deployment and increases hospitalization costs.
- Generic valganciclovir concentration:Patent expiry has commoditized oral prophylaxis, eroding branded pricing power and compressing R&D returns.
- Cross-resistance to nucleoside analogs:UL97 kinase mutations in CMV strains eliminate sequential treatment options and necessitate salvage therapy with maribavir.
Strategic Opportunities
- WHO prequalification pathways:Essential medicine list inclusion in high-HIV-burden African nations opens procurement channels for generic antiviral manufacturers.
- Diagnostic-therapeutic integration:Quantitative PCR monitoring platforms enable preemptive treatment protocols that reduce progression to sight-threatening retinitis.
- Viral terminase inhibitors:Letermovir and related compounds target the terminase complex, offering mechanistic differentiation from DNA polymerase inhibitors.
Industry Challenges
- Retinal specialist workforce density:Intravitreal injection administration requires ophthalmologists trained in posterior segment surgery, creating access bottlenecks in rural and underserved regions.
- CMV genotyping infrastructure:Resistance testing for UL97 and UL54 mutations demands molecular diagnostic capabilities unavailable in many treatment settings.
- Drug-drug interaction management:Antiretroviral regimens containing protease inhibitors complicate dosing of antiviral prophylaxis in HIV-positive patients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cytomegalovirus Retinitis Market |
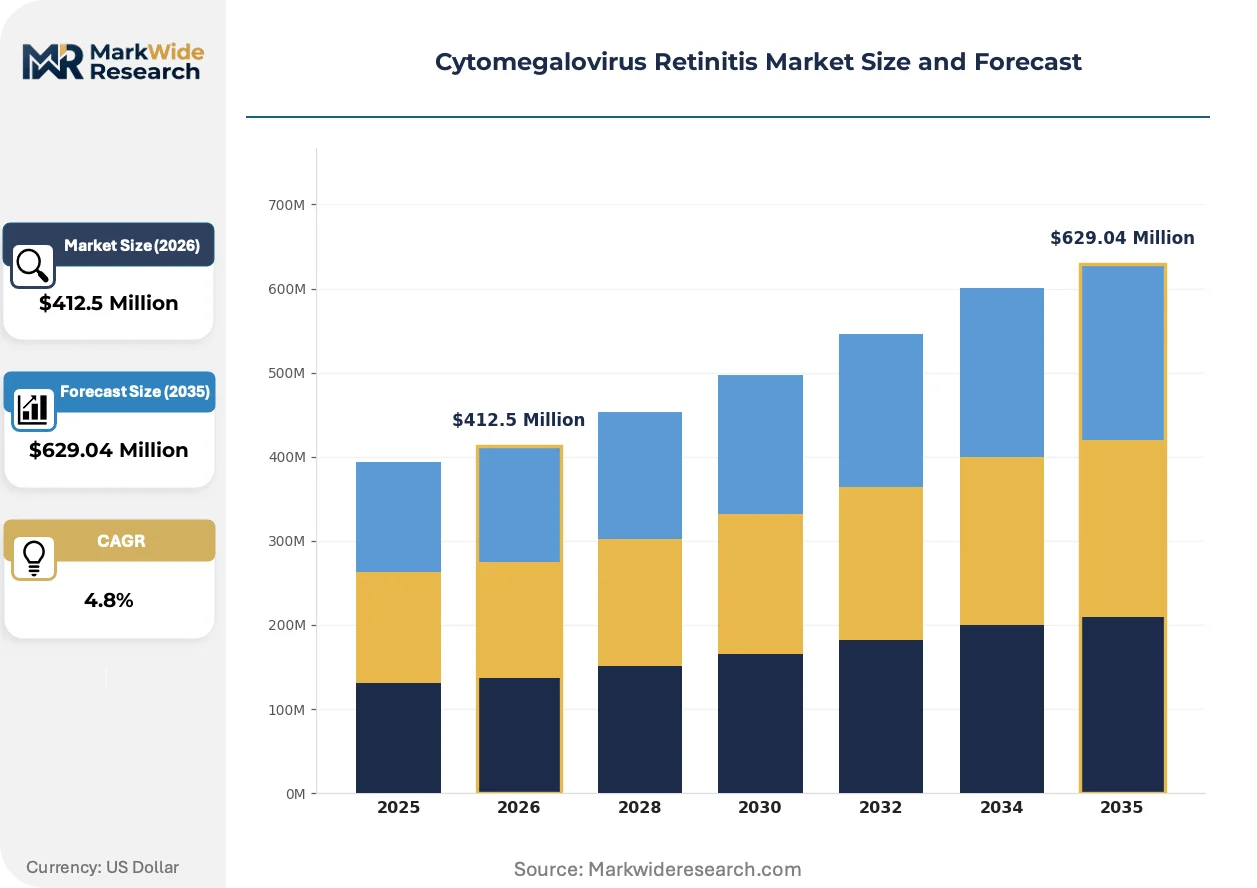
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ganciclovir, Foscarnet, Cidofovir, Valganciclovir End User: Hospitals, Specialty Clinics, Research Institutions, Home Healthcare Treatment Setting: Outpatient Treatment, Inpatient Treatment, Prophylactic Care, Hospice Care Administration Route: Intravenous, Oral, Intraocular, Subcutaneous |
| Companies Covered | F. Hoffmann-La Roche Ltd, Gilead Sciences, Inc, Chimerix, Inc, Ionis Pharmaceuticals, EyePoint Pharmaceuticals, Inc, Sanofi, CSL Behring, Merck & Co., Inc, Pfizer Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cytomegalovirus Retinitis Market Strategic Shifts
Antiviral development is pivoting toward resistance-proof mechanisms and sustained-release delivery systems that reduce treatment burden in chronic immunosuppression.
Maribavir, a benzimidazole riboside targeting the viral UL97 kinase, is integrating into salvage protocols for ganciclovir-resistant CMV retinitis. Transplant centers in the United States are adopting this agent for refractory infections despite its oral-only formulation. The compound is compressing reliance on nephrotoxic foscarnet and cidofovir in multidrug-resistant cases.
EMA's PRIME designation framework for rare infectious diseases is streamrolling pediatric investigation plans and accelerating conditional marketing authorizations for novel CMV therapeutics. This regulatory pathway reduces time-to-revenue for developers targeting orphan indications. European transplant networks are responding by incorporating preemptive treatment protocols into standard-of-care guidelines.
Preemptive therapy guided by quantitative PCR viral load monitoring is displacing universal prophylaxis in high-volume transplant programs. This surveillance-driven approach reduces antiviral exposure and associated toxicities in low-risk recipients. Adoption concentrates in German and French academic medical centers with integrated microbiology and ophthalmology services.
Cytomegalovirus Retinitis Market Segmentation
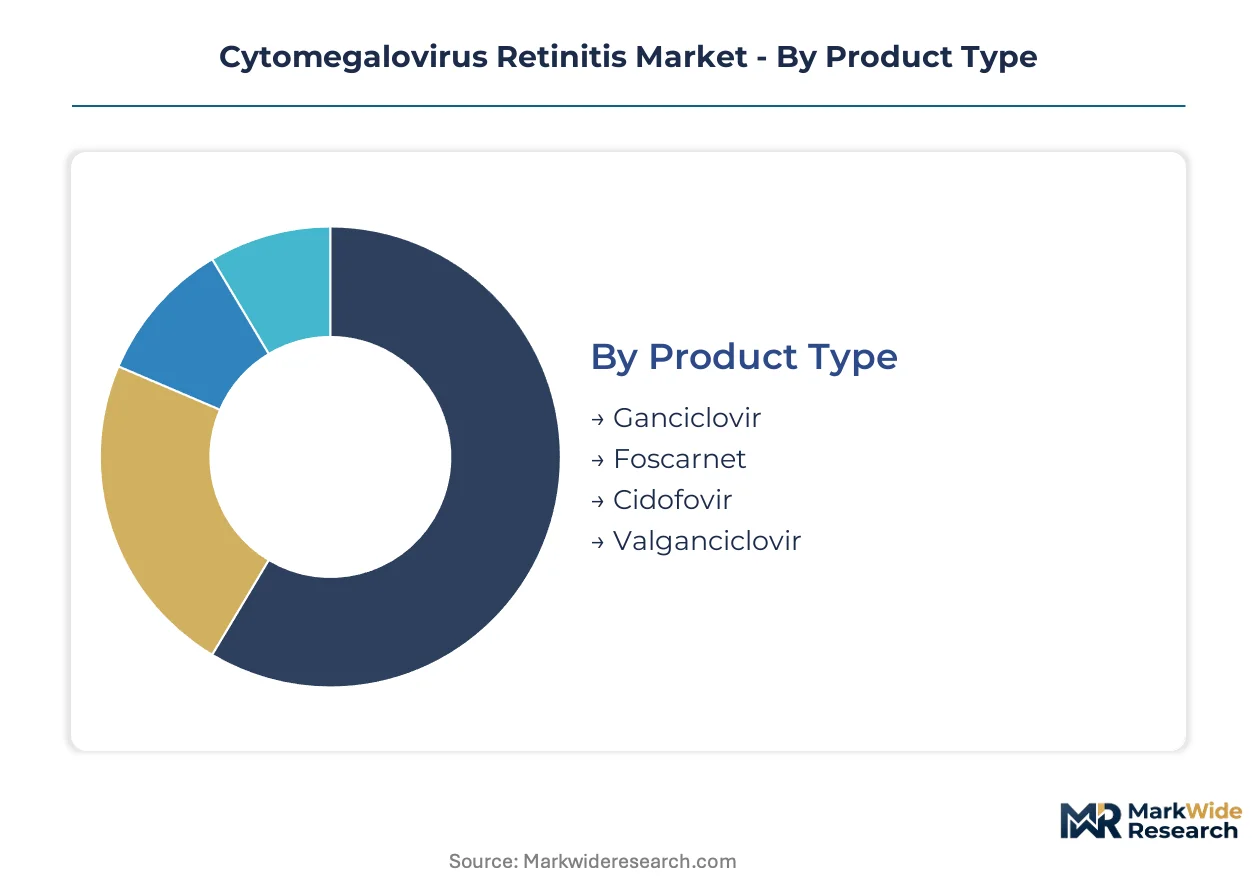
Segmentation in the Cytomegalovirus retinitis market reveals how treatment protocols fragment across clinical settings and patient acuity levels. Each axis—product chemistry, care venue, therapeutic intent, and delivery mechanism—carries distinct regulatory, reimbursement, and competitive dynamics.
Product Type:
Nucleoside analogs and pyrophosphate analogs differ in renal clearance profiles, resistance barriers, and outpatient suitability.
- Valganciclovir:The L-valyl ester prodrug of ganciclovir achieves systemic exposure comparable to intravenous therapy through oral administration. Demand concentrates in solid organ transplant prophylaxis programs at US academic medical centers where outpatient conversion reduces hospitalization costs. The FDA's orphan drug exclusivity framework initially protected branded formulations, though generic erosion has compressed pricing power.
- Ganciclovir:The parent nucleoside analog requires intravenous infusion for induction therapy in acute retinal necrosis, with intravitreal injection reserved for sight-threatening breakthrough infections. German and French transplant networks favor this agent for preemptive protocols guided by quantitative PCR monitoring. Nephrotoxicity and myelosuppression limit sequential use in renally impaired recipients.
- Foscarnet:Pyrophosphate analog with activity against ganciclovir-resistant UL97 kinase mutants, administered via central venous catheter with mandatory hydration protocols.
- Cidofovir:Cytosine phosphonate with extended intracellular half-life permitting weekly dosing, though proximal tubular toxicity restricts use to salvage settings.
Mature deployment sits with ganciclovir. Newer deployment is concentrated in valganciclovir oral prophylaxis.
End User:
Care venue determines reimbursement codes, staffing requirements, and infection control protocols.
- Hospitals:Tertiary centers manage acute retinal necrosis with intravenous induction and intravitreal rescue therapy. US urban safety-net hospitals retain significant HIV-associated CMV retinitis volume despite ART advances. Medicare severity-adjusted diagnosis-related groups govern inpatient reimbursement for induction therapy.
- Specialty Clinics:Ophthalmology subspecialty practices deliver intravitreal ganciclovir implants and monitor for immune recovery uveitis. Concentration in metropolitan areas with retinal specialist density creates access deserts in rural regions. Outpatient procedural reimbursement under Medicare Physician Fee Schedule sustains clinic economics.
- Home Healthcare:Infusion nursing services administer prolonged intravenous therapy in compliant patients with adequate vascular access and caregiver support.
- Research Institutions:Academic medical centers conduct Phase II trials for novel viral terminase inhibitors and resistance surveillance protocols.
Volume concentrates in hospitals. Margin expansion is steepest in specialty clinics.
Treatment Setting:
Therapeutic intent shapes antiviral exposure duration, resistance selection pressure, and cost accumulation.
- Prophylactic Care:Universal or preemptive antiviral suppression in high-risk transplant recipients prevents viremia progression to end-organ disease. German and Austrian transplant networks favor PCR-guided preemptive approaches over universal prophylaxis. Duration extends through peak immunosuppression, typically 100 days post-transplant.
- Outpatient Treatment:Oral valganciclovir maintenance following inpatient induction enables discharge and reduces nosocomial exposure. US Medicare home health benefit covers home infusion nursing for selected patients. Non-adherence drives breakthrough retinitis requiring salvage therapy.
- Inpatient Treatment:Acute retinal necrosis with macular threat mandates hospitalization for intravenous induction and daily ophthalmologic examination.
- Hospice Care:Palliative antiviral suppression in end-stage AIDS with limited life expectancy prioritizes comfort over vision preservation.
Standard-of-care sits with prophylactic protocols. Adoption is climbing fastest in outpatient treatment.
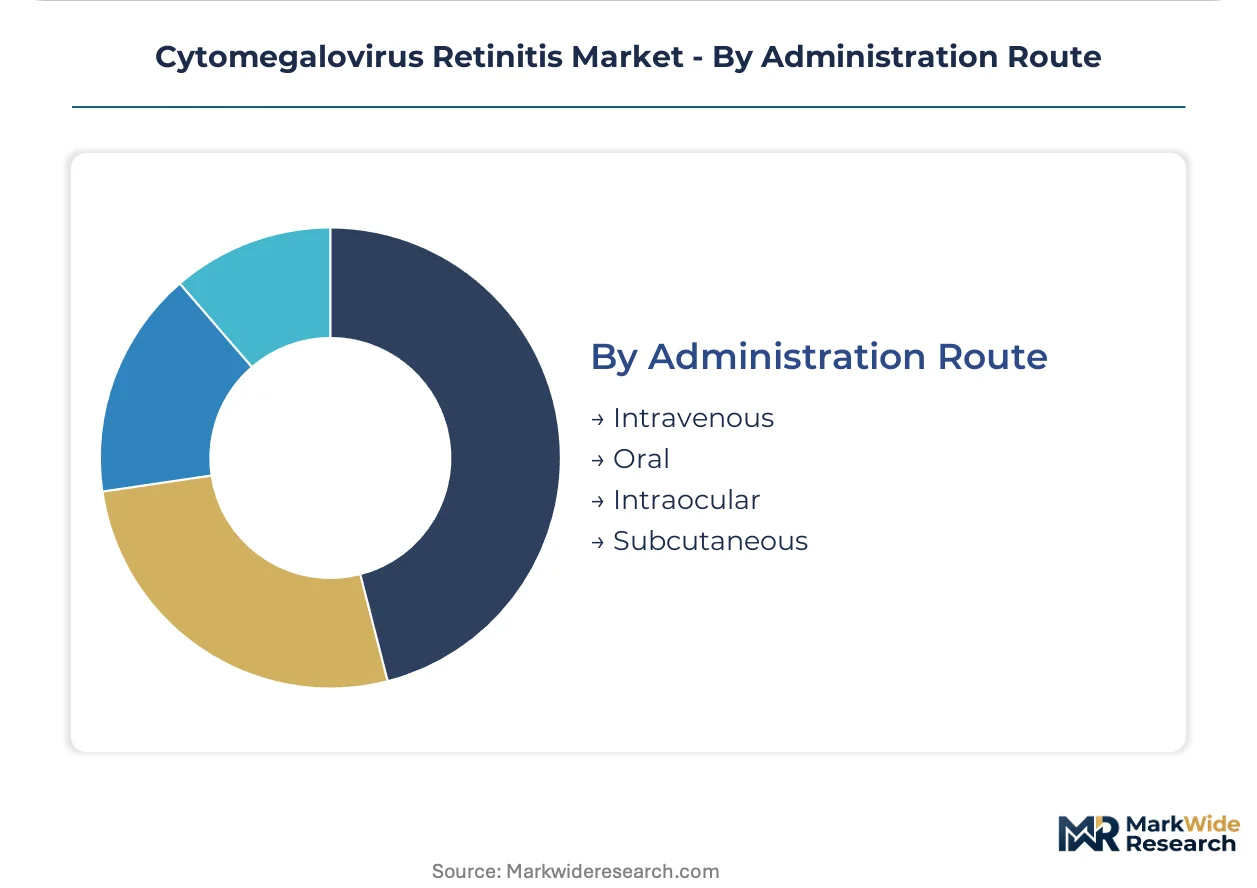
Administration Route:
Delivery mechanism determines bioavailability, tissue penetration, and healthcare utilization intensity.
- Intravenous:Central or peripheral venous access delivers ganciclovir and foscarnet with therapeutic drug monitoring for cytopenias and renal function. US hospital systems bear infusion nursing and pharmacy compounding costs. Port-a-cath placement in prolonged therapy increases infection risk.
- Oral:Valganciclovir tablets achieve therapeutic vitreous levels with patient-administered dosing, enabling prophylaxis and maintenance without facility visits. Bioavailability advantages over ganciclovir capsules drove rapid formulary adoption. Food effects and gastrointestinal intolerance limit tolerability.
- Intraocular:Intravitreal injection or sustained-release implant delivers high local drug concentrations with minimal systemic exposure. Retinal specialists at US academic medical centers administer injections; implant placement requires surgical expertise.
- Subcutaneous:Investigational depot formulations seek to bridge oral convenience with sustained release, though no approved products exist.
Established practice centers on intravenous delivery. Development pipelines are concentrating in intraocular sustained-release systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's academic medical corridor anchors CMV retinitis clinical trial density, with transplant centers at Massachusetts General Hospital and Brigham and Women's Hospital driving preemptive therapy protocol development.
United States
HIV-associated CMV retinitis persists in urban safety-net hospitals despite ART advances, while solid organ transplant volumes at Cleveland Clinic and Mayo Clinic sustain prophylactic demand. FDA orphan drug incentives compress development timelines for novel viral terminase inhibitors. Retinal specialist concentration in Manhattan and Los Angeles creates access deserts in rural Appalachia and the Great Plains.
Germany
German transplant networks at Charité Berlin and University Hospital Heidelberg favor PCR-guided preemptive protocols over universal prophylaxis. EMA's PRIME designation framework accelerates conditional marketing authorizations for rare infectious disease therapeutics. Bavarian academic centers coordinate resistance surveillance across the German-speaking transplant consortium.
France
French immunology centers at Hôpital Pitié-Salpêtrière manage CMV complications in hematologic malignancy patients. ANSM's early access programs enable compassionate use of maribavir for multidrug-resistant retinitis. The Paris-Saclay biomedical cluster integrates quantitative PCR diagnostics with ophthalmologic intervention workflows.
Japan
Japanese transplant centers report rising CMV reactivation in aging kidney recipient populations. PMDA's sakigake designation system fast-tracks innovative antiviral formulations for rare diseases. Osaka and Nagoya university hospitals pilot sustained-release intravitreal implant protocols.
United Kingdom
NHS England's specialized commissioning framework concentrates CMV retinitis care at Moorfields Eye Hospital and Manchester Royal Eye Hospital. MHRA's innovation passport program supports developer engagement for orphan antiviral indications. The Oxford-Cambridge life sciences corridor hosts resistance genotyping research consortia.
Cytomegalovirus Retinitis Market Competitive Environment
Premium-margin players sit above commodity-margin players across the nucleoside analog versus novel mechanism divide, with DNA polymerase inhibitors facing generic erosion while viral terminase inhibitors command orphan pricing. The vendor base separates into three tiers: large-cap diversified pharmaceutics with transplant portfolios, mid-cap antiviral specialists leveraging nucleotide expertise, and emerging biotechs targeting resistance-proof mechanisms. Dominant competitive moves include diagnostic-therapeutic integration partnerships and sustained-release formulation licensing.
Within the antiviral specialist tier, Gilead Sciences, Inc and Chimerix, Inc exemplify differentiated safety-profile positioning against nephrotoxic legacy agents. F. Hoffmann-La Roche Ltd anchors the diagnostic-integrated segment through ophthalmologic and molecular diagnostics convergence. These three entities collectively represent the strategic archetypes now reshaping competitive positioning: nucleotide analog incumbency, mechanistic differentiation, and diagnostic-capture integration.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Gilead Sciences, Inc |
| Chimerix, Inc |
| Ionis Pharmaceuticals |
| EyePoint Pharmaceuticals, Inc |
| Sanofi |
| CSL Behring |
| Merck & Co., Inc |
| Pfizer Inc |
| Others |
Value Chain & Pricing Dynamics
Captive integration into nucleoside analog manufacturing anchors both supply security and pricing power for developers of CMV retinitis therapeutics. FDA orphan drug exclusivity periods protect branded formulations from immediate generic erosion, while backward integration into active pharmaceutical ingredient production insulates margins from raw material volatility.
Pricing Analysis
Value-based pricing anchored to vision preservation outcomes dominates CMV retinitis therapeutics, with orphan drug premiums reflecting irreversible blindness avoidance rather than cost-plus calculations. Price differentiation separates intravitreal implant formulations from oral prophiclovir prophylaxis across premium, standard, and economy tiers. Pricing pressure stems from generic valganciclovir commoditization in transplant prophylaxis. Academic medical centers exhibit lowest price sensitivity; safety-net hospitals in high-HIV-burden urban corridors face acute budget constraints.
Supply Chain Analysis
WHO prequalification and FDA current good manufacturing practice certification gate entry for generic antiviral suppliers serving high-HIV-burden African markets. Active pharmaceutical ingredient production concentrates in India, China, and the United States. Supply chains draw from specialized fermentation capacity for nucleoside analog precursors and isolated synthetic chemistry for viral terminase inhibitors. Single-source vulnerability persists for ganciclovir API following consolidation among contract manufacturers. Distribution runs through hospital pharmacy procurement, specialty distributor networks, and direct government tender programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retinal specialist workforce scarcity props pricing for intravitreal administration services, constraining capacity expansion regardless of antiviral molecule availability.
For Market Incumbents: Cement diagnostic-therapeutic integration partnerships with quantitative PCR platform developers to preempt resistance surveillance revenue capture by molecular diagnostics specialists. Deepen backward integration into viral terminase inhibitor manufacturing ahead of letermovir patent cliff pressures. Maribavir salvage protocol adoption threatens nucleoside analog incumbency in multidrug-resistant cases. For New Entrants and Emerging Players: FDA orphan drug designation in the United States opens a window for mechanistic differentiation plays targeting UL97 kinase mutations and viral terminase complexes. White-space concentrates in sustained-release intraocular depot formulations reducing treatment burden in non-adherent transplant recipients. Preemptive therapy protocols in German and Austrian transplant networks offer the most penetrable entry point. Go-to-market should prioritize ophthalmology-retina specialist detailing over infectious disease generalism. For Investors and Strategic Acquirers: Exit pathways concentrate in large-cap pharmaceutics seeking transplant portfolio expansion through antiviral mechanism diversification. Long-term viability hinges on resistance-proof mechanism validation and sustained-release formulation differentiation. Acquisition target archetype: mid-cap antiviral specialists with terminase inhibitor Phase II assets and integrated diagnostic partnerships. The signal to watch is maribavir salvage protocol penetration rates displacing foscarnet and cidofovir in multidrug-resistant CMV retinitis.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | EMA PRIME designation accelerates conditional marketing authorizations for rare infectious disease therapeutics. |
| Regulatory Approval Pathway | FDA orphan drug exclusivity extends protected revenue periods for novel CMV retinitis mechanisms. |
| Licensing Agreement | Sustained-release intravitreal implant partnerships reduce treatment burden in non-compliant patient populations. |
| Manufacturing Scale-Up | WHO prequalification opens procurement channels for generic antiviral suppliers in high-HIV-burden African nations. |
| Pipeline Diversification | Viral terminase inhibitor development addresses cross-resistance limitations of nucleoside analog standards of care. |
Study Parameters
Document review covered FDA orphan drug designation records, EMA PRIME designation decisions, ClinicalTrials.gov protocol registrations, and WHO prequalification assessments, complemented by interviews with transplant infectious disease specialists, retinal surgeons, hospital formulary directors, and molecular diagnostics laboratory directors. Secondary validation drew from CMS Medicare reimbursement databases, hospital procurement records, and resistance surveillance consortium publications. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored market size estimates.
Cross-referencing historical approval timelines against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry class, administration route, care venue, therapeutic intent, and regional regulatory cluster. CAGRs derived from epidemiological trend extrapolation and therapy penetration scenario analysis. Forecast inputs incorporated transplant volume projections and HIV care continuum advancement patterns.
The model assumes a particular technology adoption path for viral terminase inhibitors; alternative pathways for maribavir and letermovir positioning would alter the outlook. Forecasts reflect assumptions regarding resistance mutation prevalence and preemptive therapy protocol adoption. A model refresh is warranted upon material change in UL97 kinase mutation surveillance data or terminase inhibitor regulatory approvals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Treatment-Resistance Depression Treatment Market
Specialty Medicine
US Opioid Use Disorder (OUD) Market
Specialty Medicine
Progressive Supranuclear Palsy (PSP) Market
Specialty Medicine
Interstitial Lung Disease Treatment Market
Specialty Medicine
Growth Hormone Deficiency Market
Specialty Medicine
Nephroblastoma Therapeutics Market
Specialty Medicine
Global Liver Cancer Therapeutics Market
Specialty Medicine
Lung Cancer Therapeutics Market
Specialty Medicine
Cirrhosis Management Market
Specialty Medicine
Gaucher and Pompe Diseases Enzyme Replacement Therapy (ERT) Market
Specialty Medicine
Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Head and Neck Cancer Therapeutics Market
Specialty Medicine
South America Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market
Specialty Medicine
Microcephaly Market
Specialty Medicine
Disruptive Behavior Disorder (DBD) Treatment Market