
 Global Corneal Topographers Market | 2026-2036
Global Corneal Topographers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Corneal Topographers Market Intelligence
The availability of ophthalmic technicians trained in advanced imaging analytics is bifurcating the market between high-volume surgical centers and smaller independent clinics. Carl Zeiss Meditec AG leverages its integrated diagnostic and surgical ecosystem to capture premium segments. Topcon Corporation specializes in comprehensive eye care solutions, including advanced topography, while Nidek Co., Ltd. competes on the reliability of its placido-based systems, particularly in key Asian markets.
A corneal topographer is a non-invasive medical imaging device that maps the surface curvature of the cornea, creating a detailed three-dimensional map. These instruments are critical for diagnosing and managing various ocular conditions. Demand for refractive surgery planning and early keratoconus detection propels the market. While placido disk systems maintain a large installed base, combined technology devices integrating Scheimpflug imaging are gaining share due to superior diagnostic capabilities.
Regulatory frameworks such as the FDA's 510(k) clearance in the United States and the CE marking under the EU's Medical Device Regulation (MDR) govern market access. China's National Medical Products Administration (NMPA) imposes its own stringent approval processes for medical devices. These standards enforce rigorous clinical validation and quality control. Future competitive advantage will be determined by a device's ability to integrate data with AI-driven analytics for personalized treatment planning.
Market Dynamics
The integration of artificial intelligence with advanced imaging modalities, particularly Scheimpflug technology, is the central force shaping the corneal topographers market. This convergence is shifting the competitive landscape from hardware specifications alone to the diagnostic power of data analytics.
Growth Catalysts
- AI-Powered Diagnostics:The incorporation of AI algorithms to analyze topography maps enhances the early and accurate detection of conditions like keratoconus, driving adoption in specialized ophthalmology clinics.
- Refractive Surgery Volume:A rising global prevalence of myopia and astigmatism is increasing the volume of refractive procedures such as LASIK, which depend on precise corneal mapping for surgical planning.
- Regulatory Emphasis on Clinical Data:Frameworks like the EU's Medical Device Regulation (MDR) demand extensive clinical evidence for diagnostic claims, favoring advanced topographers with proven accuracy and repeatability.
Market Restraints
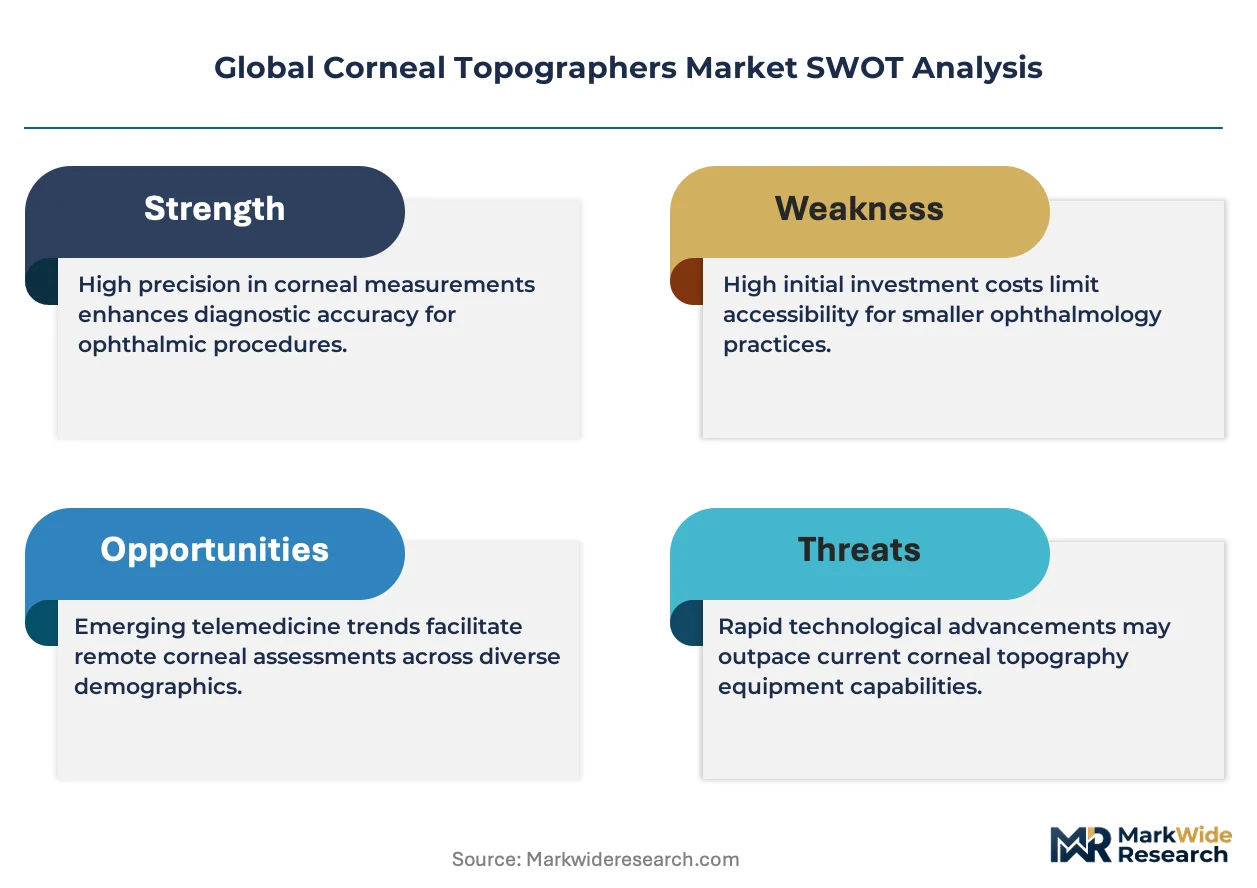
- High Acquisition Cost:The significant capital investment required for combined placido-Scheimpflug topographers restricts their adoption by smaller independent clinics and in price-sensitive healthcare systems.
- Component Supply Concentration:Critical optical components, including high-resolution cameras and specialized light sources, are sourced from a limited number of global suppliers, posing a risk to production continuity.
- Technical Limitations of Legacy Systems:A large installed base of older placido disk-only systems lacks the ability to measure the posterior corneal surface, a critical data point for identifying ectatic risk.
Strategic Opportunities
- Expansion in Emerging Economies:There is a significant opportunity for market entry and expansion in countries across Southeast Asia and Latin America, where private investment in advanced eye care infrastructure is increasing.
- Development of Portable Devices:Creating handheld, battery-operated topographers can open new channels for corneal screening in remote areas, pediatric ophthalmology, and primary care settings.
- Integration with OCT Technology:Combining corneal topography with Optical Coherence Tomography (OCT) data offers a more complete picture of the anterior segment, creating value for complex cataract and refractive surgery planning.
Industry Challenges
- Specialized Technician Shortage:A deficit of ophthalmic technicians trained to operate and interpret the complex data from advanced topography systems limits the effective utilization of these devices in clinical practice.
- Data Interoperability:Ensuring seamless integration of topography data with diverse Electronic Health Record (EHR) systems and surgical planning platforms remains a significant technical hurdle for manufacturers.
- Divergent Regulatory Pathways:Navigating the distinct and lengthy approval processes of the FDA in the United States, the NMPA in China, and CE marking requirements in Europe adds complexity and cost to market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Corneal Topographers Market |
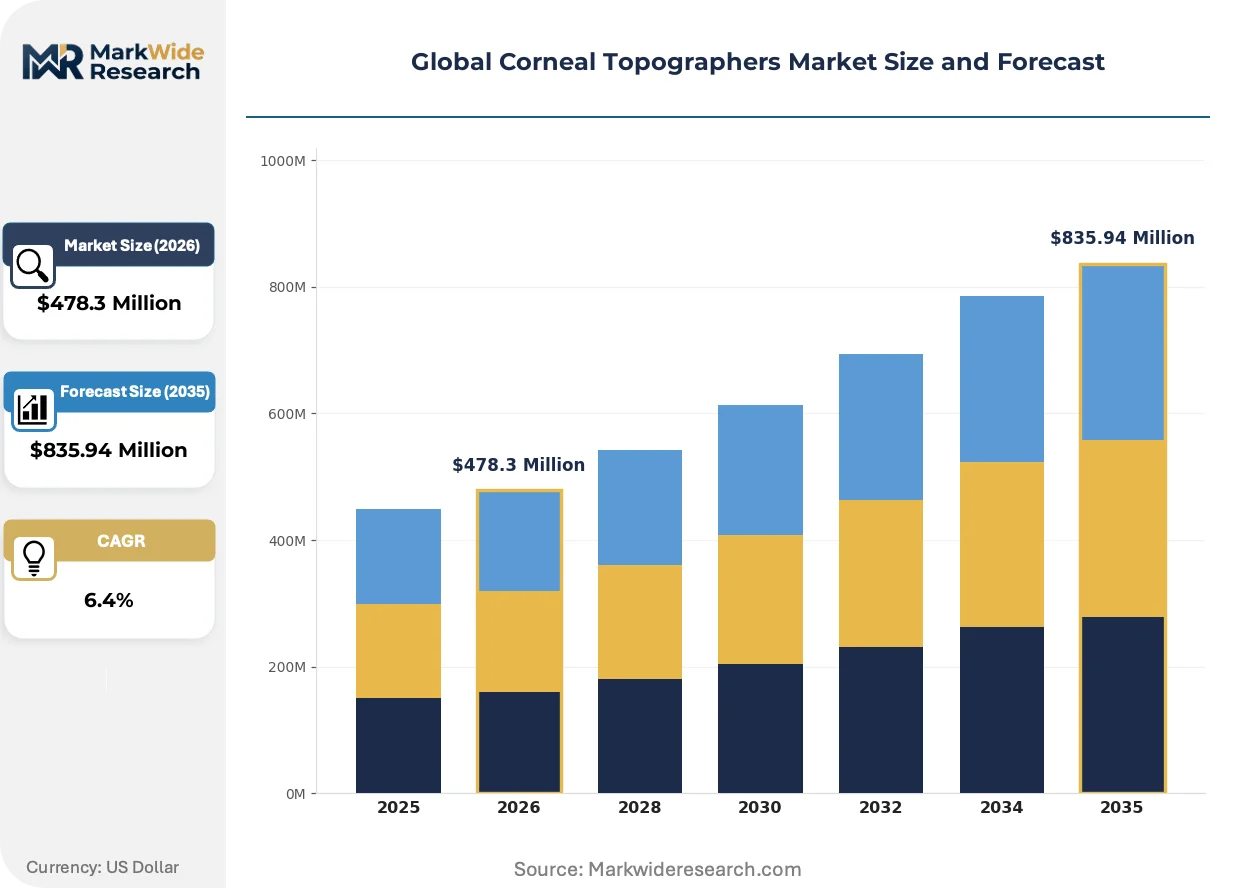
| Market Size in 2026 | $478.3 Million |
| Market Size in 2035 | $835.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Placido Disk, Scanning Slit, Scheimpflug Imaging, Combined Technology Technology: Optical Coherence Tomography, Reflection-Based, Video Keratoscopy, Interferometry Application: Refractive Surgery, Keratoconus Detection, Contact Lens Fitting, Cataract Surgery Planning End User: Ophthalmic Clinics, Eye Research Centers, Ambulatory Surgical Centers, Optical Retailers |
| Companies Covered | Carl Zeiss Meditec AG, Topcon Corporation, Nidek Co., Ltd, OCULUS Optikgeräte GmbH, Ziemer Ophthalmic Systems AG, Cassini Technologies, Tomey Corporation, EyeSys Vision, Tracey Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Corneal Topographers Market Strategic Shifts & Innovations
The market is evolving toward data-centric, portable, and interconnected diagnostic solutions. This shift prioritizes analytical software and device interoperability over standalone hardware performance, changing how clinicians procure and utilize corneal data.
Advanced sensor and processing technology is enabling a new generation of more compact diagnostic instruments. Ophthalmic practices and mobile screening programs are adopting these smaller form factors at an accelerating pace. The core diagnostic engine of the topographer is miniaturizing, which facilitates the design of portable and handheld devices for use outside of traditional clinic environments.
The European Union's Medical Device Regulation (MDR) is elevating the standard for clinical validation across the industry. This regulation forces manufacturers to provide more extensive clinical evidence and conduct rigorous post-market surveillance. Devices combining multiple imaging technologies, which make sophisticated diagnostic claims, are most affected as they seek or maintain their CE marking.
A notable behavioral shift involves clinics moving from one-time capital purchases toward software-as-a-service (SaaS) models for analytical tools. This trend disrupts the traditional hardware-centric sales cycle, favoring vendors who offer integrated ecosystems with continuous software updates. This model is gaining traction primarily in high-volume surgical centers in North America and Europe that require access to the latest AI-driven treatment planning algorithms.
Global Corneal Topographers Market Segmentation
The corneal topographers market segmentation highlights the diverse technological approaches and clinical applications driving adoption across various end-user settings. Understanding these segments is crucial for manufacturers to tailor product development and market strategies effectively. Each segment addresses specific diagnostic needs and operational requirements within ophthalmology.
Product Type:
The product type segment faces substitution pressure from advanced systems displacing older, less comprehensive devices.
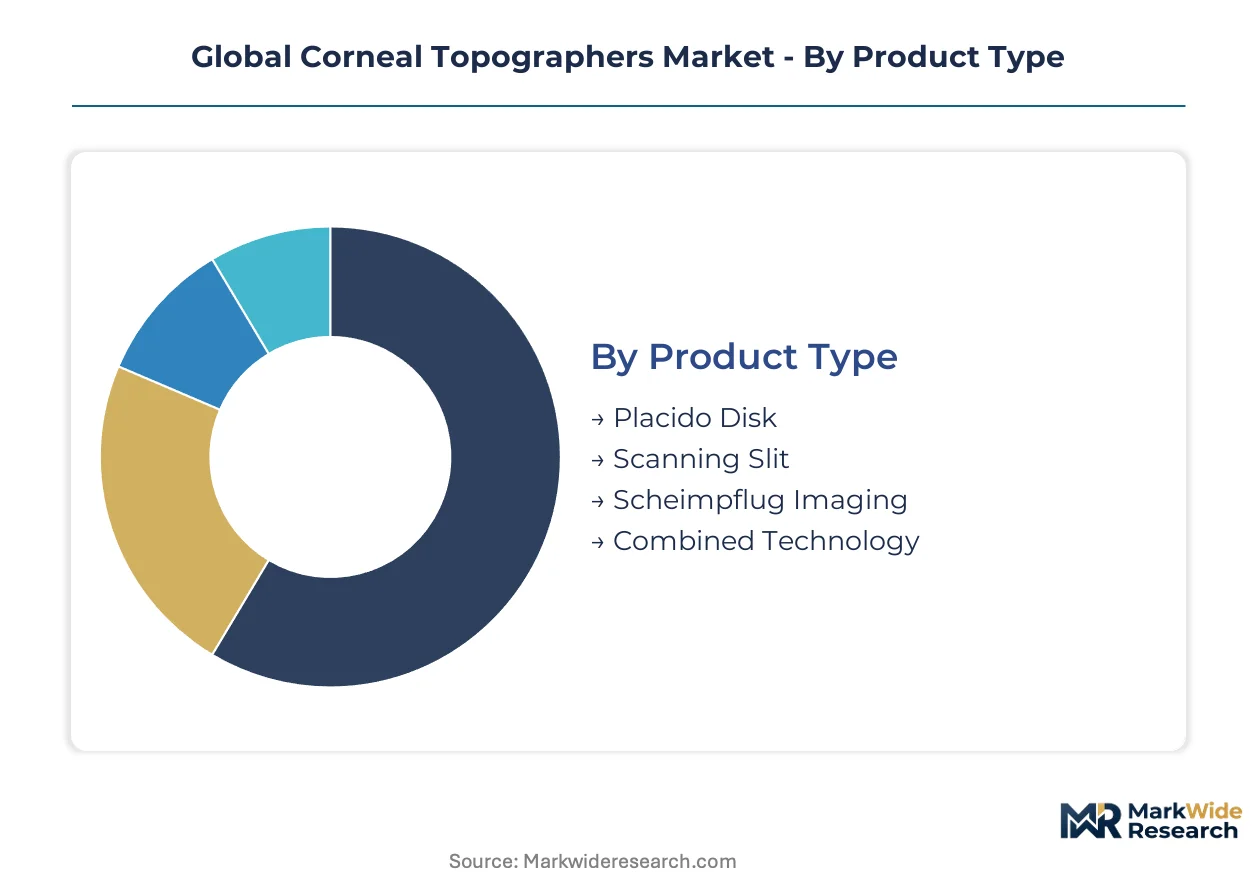
- Combined Technology:These devices integrate multiple imaging modalities, such as Scheimpflug and placido disk, offering superior diagnostic capabilities for both anterior and posterior corneal surfaces. Demand concentrates in high-volume refractive surgery centers requiring comprehensive pre-operative planning.
- Scheimpflug Imaging:This technology provides cross-sectional images of the cornea, enabling precise measurement of corneal thickness and posterior surface elevation, critical for ectasia detection. Specialized ophthalmology clinics heavily adopt Scheimpflug imaging for advanced keratoconus diagnosis.
- Placido Disk:Placido disk systems map the anterior corneal surface using reflected light, representing a large installed base in general ophthalmic practices.
- Scanning Slit:Scanning slit technology uses a narrow light beam to create corneal profiles, though it is largely superseded by more advanced imaging methods today.
Placido Disk anchors the volume base while Combined Technology gains share at the steepest rate.
Technology:
Cost tiers within technology differentiate devices based on their inherent complexity and diagnostic breadth.
- Optical Coherence Tomography:OCT technology provides high-resolution cross-sectional images of the anterior segment, often integrated with topography for a complete ocular assessment. This technology is increasingly utilized in complex cataract and refractive surgery planning.
- Reflection-Based:This fundamental technology relies on analyzing reflected light patterns from the corneal surface, forming the basis for placido disk systems. Reflection-based systems are widely used for routine corneal mapping and contact lens fitting.
- Video Keratoscopy:Video keratoscopy systems capture and analyze images of reflected Placido rings, providing detailed maps of anterior corneal curvature. These systems are still prevalent in many general ophthalmology settings.
- Interferometry:Interferometry measures corneal thickness and other parameters with high precision, often employed in research settings and for specialized diagnostic applications.
Optical Coherence Tomography technology commands premium pricing due to its comprehensive imaging capabilities.
Application:
Application segments reflect varying procedure volumes, with some representing core diagnostic needs and others specialized surgical planning.
- Refractive Surgery:This application involves precise corneal mapping for procedures like LASIK and PRK, which correct myopia, hyperopia, and astigmatism. A rising global prevalence of myopia drives demand for topographers in refractive surgery clinics.
- Keratoconus Detection:Corneal topographers are indispensable for early and accurate diagnosis of keratoconus, a progressive corneal thinning disorder. Specialized ophthalmology clinics prioritize advanced topographers with AI-powered diagnostics for this application.
- Cataract Surgery Planning:Topography aids in calculating intraocular lens (IOL) power and selecting toric IOLs, improving refractive outcomes in cataract surgery.
- Contact Lens Fitting:Detailed corneal maps assist practitioners in fitting contact lenses, ensuring optimal comfort and visual acuity for patients.
Refractive Surgery drives significant demand for corneal topographers, indicating a high procedural volume.
End User:
End-user segments highlight distinct customer profiles, from specialized medical facilities to consumer-facing retail environments.
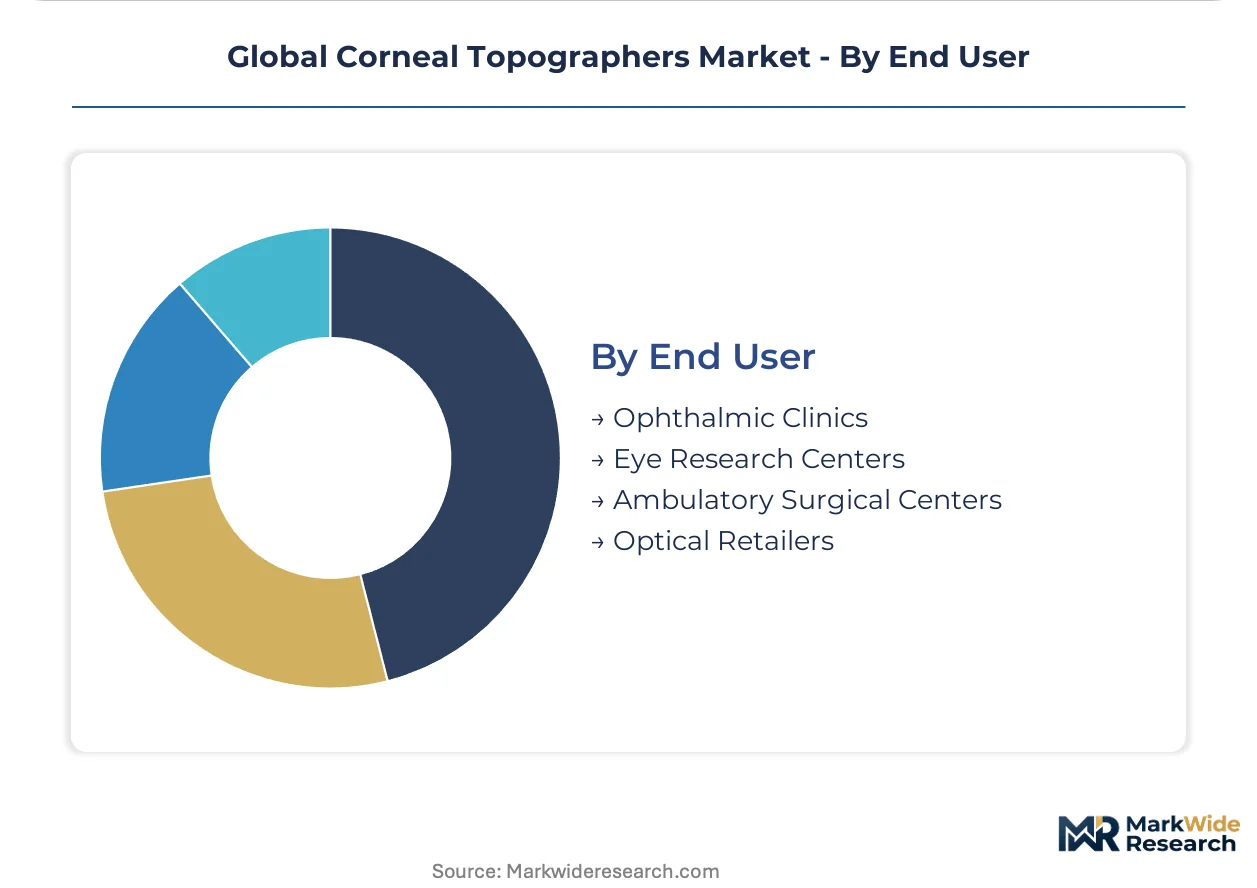
- Ophthalmic Clinics:These clinics represent the largest end-user segment, utilizing corneal topographers for routine diagnostics, disease management, and pre-surgical evaluations. Ophthalmic clinics require versatile devices capable of handling a broad range of patient needs.
- Ambulatory Surgical Centers:ASCs primarily focus on surgical procedures, integrating topographers for precise pre-operative planning in refractive and cataract surgeries. These centers demand high accuracy and integration with surgical planning platforms.
- Eye Research Centers:Research centers employ advanced corneal topographers for clinical trials, academic studies, and the development of new diagnostic and therapeutic approaches. These facilities often require devices with specialized measurement capabilities.
- Optical Retailers:Optical retailers are increasingly adopting basic corneal topography for preliminary screening, contact lens assessments, and patient education before referral to ophthalmologists.
Ophthalmic Clinics represent the largest end-user segment for corneal topographers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for corneal topographers varies regionally, with advanced markets prioritizing combined technologies for complex surgeries while emerging economies focus on foundational diagnostic capabilities. This differentiation influences adoption rates and technology preferences across diverse healthcare infrastructures. Regulatory frameworks also play a significant role in shaping market access and product development.
United States
Demand for refractive surgery and advanced diagnostics drives the market for corneal topographers. The FDA's 510(k) clearance process ensures rigorous validation for new devices entering the market. Major ophthalmic research centers in Boston and San Francisco lead innovation in AI-driven analytics for corneal mapping.
China
A large patient population and increasing ophthalmic procedure volumes fuel demand for corneal topographers. The National Medical Products Administration (NMPA) enforces stringent approval processes for medical devices. High-tech medical device clusters in Shanghai and Shenzhen are developing new imaging solutions for eye care.
Germany
The robust healthcare system and high adoption of advanced medical technologies support market growth for corneal topographers. CE marking under the EU's Medical Device Regulation (MDR) requires extensive clinical evidence for diagnostic claims. Specialized eye clinics in Berlin and Munich are early adopters of combined technology devices.
India
Growing private investment in eye care infrastructure and rising awareness of ocular conditions boost corneal topographer adoption. The Central Drugs Standard Control Organization (CDSCO) regulates medical device imports and manufacturing standards. Major medical hubs in Bangalore and Chennai are expanding access to advanced diagnostics.
Global Corneal Topographers Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the market structure for corneal topographers. This tiered landscape features global conglomerates alongside specialized innovators focusing on specific imaging modalities and software solutions. Strategic archetypes include comprehensive eye care solution providers, niche technology developers, and diagnostic platform integrators. Companies are engaging in strategic partnerships and portfolio diversification to enhance their market reach and integrate AI-driven analytics.
On the premium-tier vector, Carl Zeiss Meditec AG exemplifies the integrated diagnostic and surgical ecosystem approach, offering comprehensive solutions that extend beyond topography. Topcon Corporation, a Japan-based company, sits within the broader specialist tier, representing providers of comprehensive eye care solutions including advanced topography and integrated diagnostics. Nidek Co., Ltd., also from Japan, anchors the segment for reliable placido-based systems, particularly in key Asian markets, demonstrating a strong focus on established, proven technologies and their continuous refinement. These entities collectively highlight the market's blend of integrated platforms and specialized device offerings.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| Topcon Corporation |
| Nidek Co., Ltd |
| OCULUS Optikgeräte GmbH |
| Ziemer Ophthalmic Systems AG |
| Cassini Technologies |
| Tomey Corporation |
| EyeSys Vision |
| Tracey Technologies |
| Others |
Cost & Logistics Intelligence
The substitution of hardware-centric sales with software-as-a-service (SaaS) models is reconfiguring both the supply geography of analytical talent and the pricing economics for advanced corneal topographers. This shift prioritizes data analytics over physical device manufacturing.
Pricing Analysis
Long-term service contracts and software-as-a-service subscriptions define a growing portion of corneal topographer procurement, particularly for AI-driven analytics. Pricing stratifies across premium-mid-economy tiers, driven by comprehensive diagnostic capabilities, AI integration, and bundled after-sales support. Legacy placido-disk systems face pricing softness due to the superior diagnostic breadth of combined technology devices. Smaller independent clinics exhibit high price sensitivity, contrasting with high-volume surgical centers prioritizing advanced features regardless of cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate for high-value corneal topographers, minimizing holding costs for complex medical devices. Component supply concentrates in Japan, Germany, and the United States, drawing from specialized manufacturers of high-resolution cameras and precision optics. This reliance creates a single-source vulnerability for critical optical components, posing risks to production continuity. Distribution runs through direct sales forces and specialized medical device distributors, ensuring clinical support and integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The corneal topographers market presents a fragmentation opportunity, driven by a demand-side shift towards portable devices for remote screening and pediatric ophthalmology. This creates distinct niches beyond traditional clinic settings.
For Market Incumbents: Compound existing integrated diagnostic and surgical ecosystems by accelerating AI-driven analytics development to counter niche technology developers. Invest in rigorous clinical validation to meet evolving regulatory frameworks like the EU's MDR, reinforcing premium positioning. Control key component supply through strategic partnerships to mitigate single-source vulnerability. Broaden software-as-a-service offerings to capture recurring revenue streams against hardware-centric margin pressures.
For New Entrants and Emerging Players: Anchor in underserved segments like remote care and pediatric ophthalmology with portable, battery-operated devices. Target optical retailers for preliminary screening and contact lens assessments, offering accessible, user-friendly systems. Develop AI-powered diagnostic software that integrates seamlessly with existing EHR systems, providing a strong value proposition for data interoperability. Focus on a SaaS-first model to lower acquisition costs for smaller clinics.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized imaging software integrators and niche portable device manufacturers. Long-term viability depends on acquiring companies with proven AI algorithms for personalized treatment planning and robust data interoperability solutions over the next five to ten years. Watch for shifts in regulatory approval processes favoring combined technology devices as an inflection indicator. Prioritize firms demonstrating strong intellectual property in Scheimpflug imaging.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Portable Topographers | Opens new market channels in remote areas and primary care, expanding diagnostic reach. |
| Platform Integration: AI-Powered Diagnostics | Enhances diagnostic accuracy and treatment planning, driving adoption in specialized clinics. |
| Strategic Partnership: Optical Component Manufacturers | Secures critical supply chains and mitigates risks from component concentration. |
| Geographic Expansion: Southeast Asia | Captures growth in emerging economies with increasing investment in eye care infrastructure. |
| Software Companion Development: EHR Interoperability | Addresses a significant technical hurdle, improving clinical workflow and data utilization. |
Research Approach
Operator-level perspectives from ophthalmic surgeons, clinic administrators, medical device engineers, and regulatory affairs specialists anchored the qualitative base for this analysis. This primary research combined with extensive secondary validation drew from FDA filings, NMPA reports, medical journals, and company annual reports. Both bottom-up and top-down triangulation methods ensured data consistency across various sources.
Sensitivity analysis was applied across the modeling period to assess the impact of various market conditions on projected outcomes. The framework modeled segmentation dimensions including product type, technology, application, end-user, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected adoption rates. Key forecast inputs included refractive surgery volumes and healthcare infrastructure investment.
Decision-makers should treat outputs as directional under assumptions of regulatory stability and consistent technological advancement; material deviation would warrant model refresh. Forecasts reflect these base assumptions; component supply disruptions or AI integration challenges could alter trajectories. Practitioners should keep alternative scenarios live.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Catheter Coatings Market
Medical Devices
Global Closed System Transfer Devices Market
Medical Devices
Smart Pills Technology Market
Medical Devices
Global Image Guided Surgery Devices Market
Medical Devices
Soft Tissue Markers Market
Medical Devices
Global Implantable Drug Delivery Market
Medical Devices
North America Intraocular Lens Market
Medical Devices
Mexico Ultrasound Devices Market
Medical Devices
Balloon Catheters for Bile Stone Removal Market
Medical Devices
Hydrogel Contact Lenses Market
Medical Devices
Germany Artificial Organs and Bionics Market
Medical Devices
Snoring Control Devices Market
Medical Devices
US Peripheral Vascular Devices and Accessories Market
Medical Devices
Spectacle Lens Market
Medical Devices
Recanalization System Market
Medical Devices
Insulin Delivery Devices (Idd) Market