
 Aicardi Syndrome Market | 2026-2036
Aicardi Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Aicardi Syndrome Market Analysis
Modular service bundling around genetic testing, neurology consultation, and long-term seizure management is hardening as the dominant care configuration for Aicardi syndrome. Novartis AG leverages its orphan disease portfolio to sustain competitive positioning in neurodevelopmental therapeutics. Siemens Healthineers anchors diagnostic workflows through its MRI and EEG platform integration for pediatric epilepsy centers. Canon Medical Systems Europe B.V. competes on imaging resolution parameters tailored to infant neuroimaging protocols.
Aicardi syndrome constitutes a rare X-linked dominant neurodevelopmental disorder characterized by agenesis of the corpus callosum, infantile spasms, and chorioretinal lacunae, with diagnosis relying on MRI neuroimaging, EEG pattern recognition, and genetic confirmation of pathogenic variants. The condition demands lifelong multidisciplinary management spanning antiepileptic pharmacotherapy, visual rehabilitation, and developmental support. Medications and genetic testing represent the core revenue pools, with medical devices capturing ancillary value through diagnostic hardware placement. Hospitals dominate end-user demand due to the intensive monitoring requirements for infantile spasms and the need for integrated pediatric neurology, ophthalmology, and genetics services.
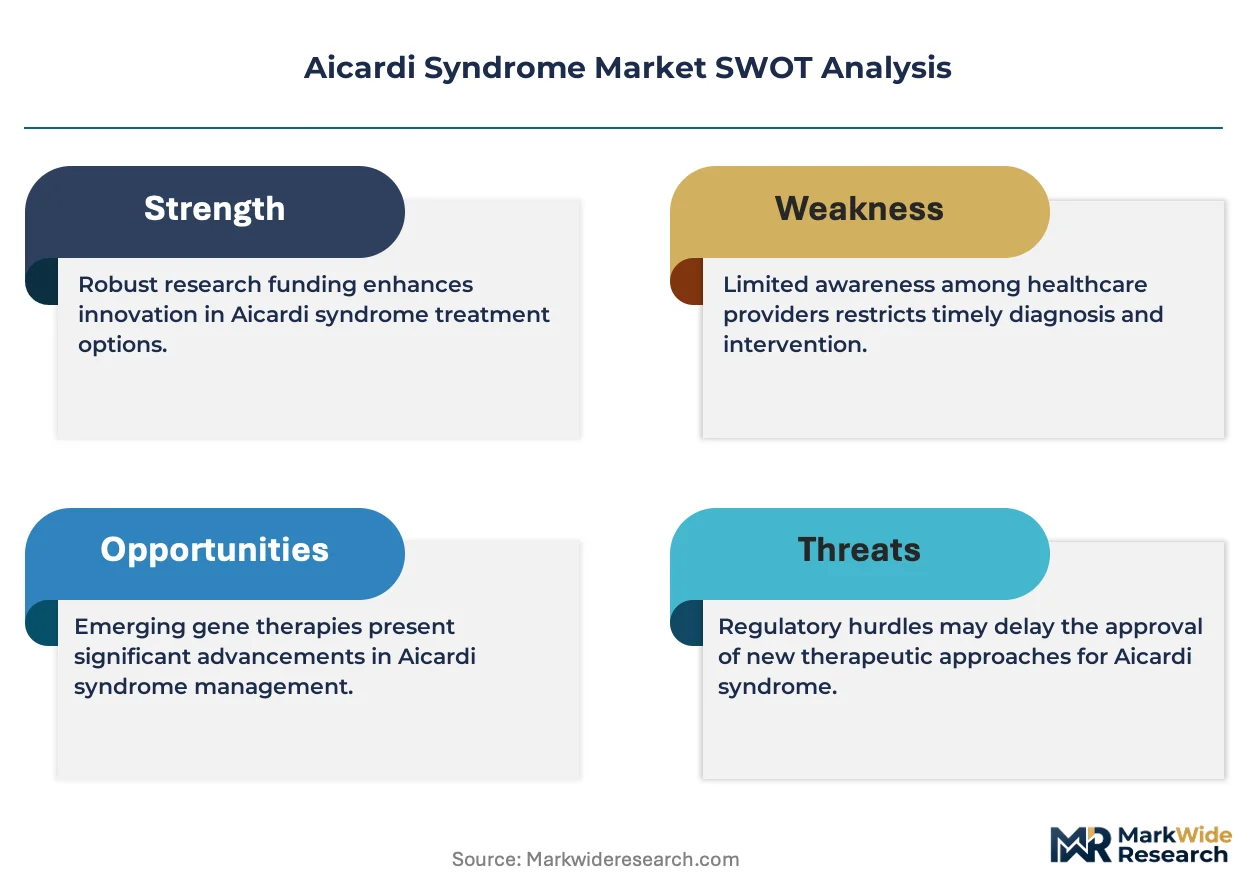
FDA orphan drug designation and expanded access frameworks shape pharmaceutical development incentives for Aicardi syndrome therapeutics, while HIPAA governs cross-institutional data sharing for rare disease registries. The EU's CE marking and Medical Device Regulation (MDR) determine market access for neuroimaging and neuromodulation devices used in pediatric populations. Stakeholders must monitor regulatory harmonization between FDA and EMA rare disease pathways, as divergent evidentiary standards for ultra-orphan indications will determine which experimental therapies reach clinical adoption.
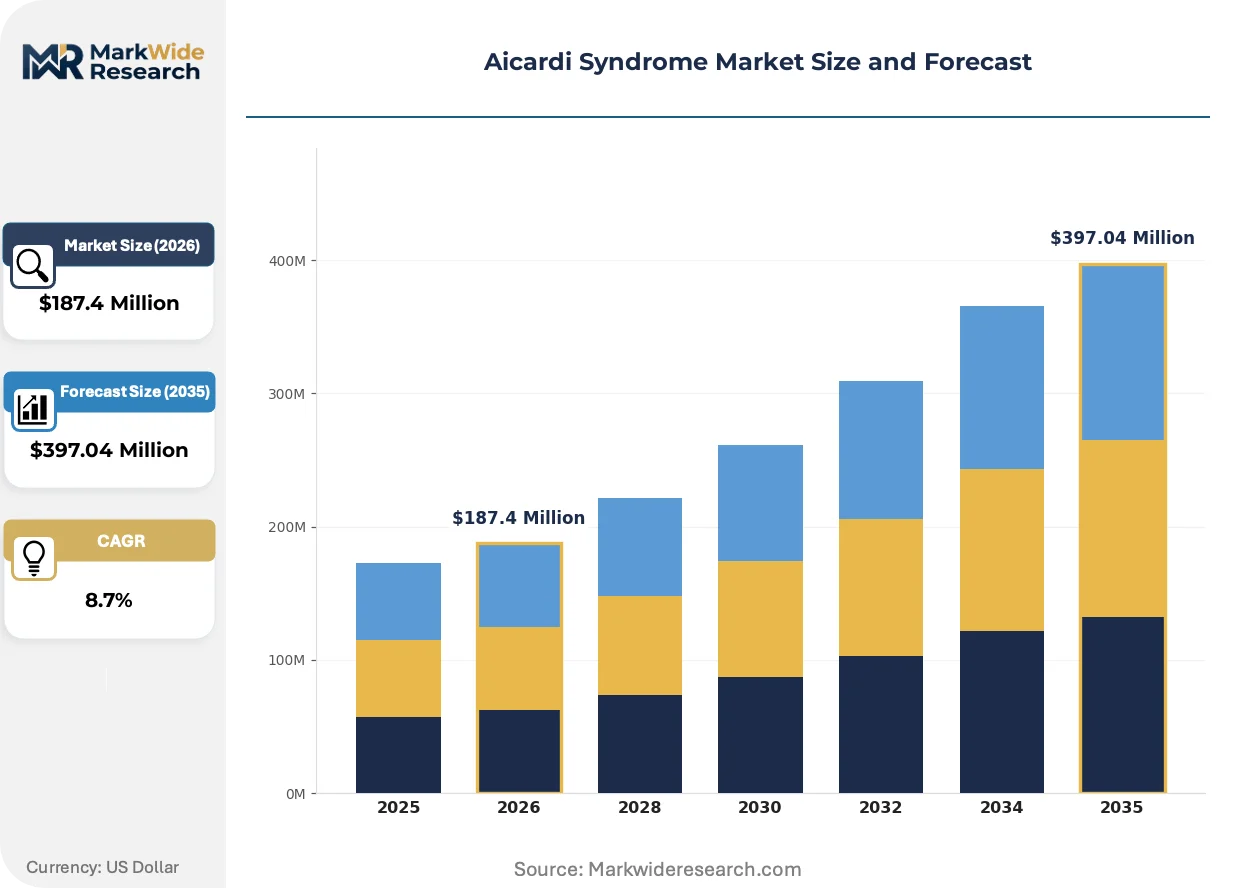
Market Dynamics
FDA orphan drug designation and expanded access frameworks are compressing development timelines for ultra-rare neurodevelopmental therapeutics, while pediatric neurology departments at tertiary hospitals harden dedicated care pathways around genetic testing, neurology consultation, and long-term seizure management bundles.
Growth Catalysts
- Orphan Drug Incentives:FDA tax credits and market exclusivity provisions accelerate pharmaceutical investment in neurodevelopmental disorder pipelines. Pediatric epilepsy centers expand specialized intake protocols for rare genetic conditions.
- Diagnostic Platform Integration:MRI and EEG workflow convergence at tertiary hospitals reduces time-to-diagnosis for infantile spasms. Siemens Healthineers and Canon Medical Systems anchor hardware placement through pediatric neuroimaging protocols.
- Cross-Border Patient Referral Concentration:United States specialized centers attract international cases seeking integrated genetics, neurology, and ophthalmology services. Tertiary hospital networks consolidate regional referral hierarchies.
Market Restraints
- Ultra-Small Patient Populations:Aicardi syndrome incidence below one per 100,000 live births constrains clinical trial enrollment and statistical power for regulatory submissions. Pharmaceutical developers face prolonged recruitment timelines.
- High Diagnostic Capital Requirements:MRI and EEG infrastructure demands substantial upfront investment at pediatric centers. Resource-constrained institutions defer rare disease pathway development.
- Genetic Heterogeneity Complexity:Pathogenic variant spectrum across NDP and other X-linked genes complicates standardized therapeutic targeting. Personalized medicine approaches fragment addressable patient segments.
Strategic Opportunities
- Natural History Registry Expansion:HIPAA-compliant cross-institutional data sharing frameworks enable longitudinal outcome tracking. Rare disease registries attract pharmaceutical sponsorship for real-world evidence generation.
- Gene Therapy Platform Adaptation:Viral vector delivery systems developed for comparable neurodevelopmental disorders transfer to Aicardi syndrome targets. Preclinical programs leverage existing CNS biodistribution data.
- Telemedicine Neurology Extension:Remote consultation protocols extend specialized epilepsy expertise to underserved geographic regions. Tertiary centers capture follow-up volume without physical infrastructure expansion.
Industry Challenges
- Pediatric Neurogenetics Workforce Scarcity:Fellowship-trained specialists capable of integrating MRI interpretation, EEG pattern recognition, and genetic variant classification remain concentrated at academic medical centers. Community hospitals lack diagnostic capacity.
- Reimbursement Code Fragmentation:Genetic testing, neuroimaging, and multidisciplinary care coordination bill across separate coding systems. Payers apply inconsistent medical necessity criteria for ultra-orphan indications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aicardi Syndrome Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Genetic Testing, Medical Devices, Supportive Care Application: Pediatric Neurology, Genetic Counseling, Rehabilitation, Clinical Trials End User: Hospitals, Research Institutions, Outpatient Clinics, Home Care Providers Treatment Type: Symptomatic Treatment, Preventive Care, Surgical Intervention, Experimental Therapies |
| Companies Covered | Novartis AG, General Electric Company, Koninklijke Philips N.V., Canon Medical Systems Europe B.V., Therapy Solutions Inc., Hitachi Ltd., Siemens Healthineers, Medtronic, Aicardi Syndrome Foundation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aicardi Syndrome Market Emerging Trajectories
Diagnostic workflow automation and regulatory pathway specialization are compressing time-to-treatment for rare neurodevelopmental disorders. Three converging developments reshape competitive positioning.
Multimodal neuroimaging is consolidating diagnostic confidence for agenesis of the corpus callosum and chorioretinal lacunae detection. Pediatric epilepsy centers at Boston Children's Hospital and Children's Hospital of Philadelphia integrate high-resolution MRI with optical coherence tomography protocols. This technology convergence reduces reliance on invasive procedures and compresses referral-to-diagnosis intervals.
EMA's PRIME designation and FDA's Breakthrough Therapy pathways are accelerating evidentiary flexibility for ultra-orphan neurodevelopmental indications. Regulators accept smaller trial populations and surrogate endpoints when natural history data demonstrates severe unmet need. Pharmaceutical sponsors prioritize European and North American submissions where regulatory science alignment permits cross-referral.
Academic medical centers are unbundling long-term seizure management from acute diagnostic services. Tertiary hospitals retain complex genetic counseling and surgical evaluation while transferring stable patients to regional neurology practices. This channel segmentation concentrates high-margin procedures at flagship institutions while extending geographic reach through affiliate networks.
Aicardi Syndrome Market Segmentation
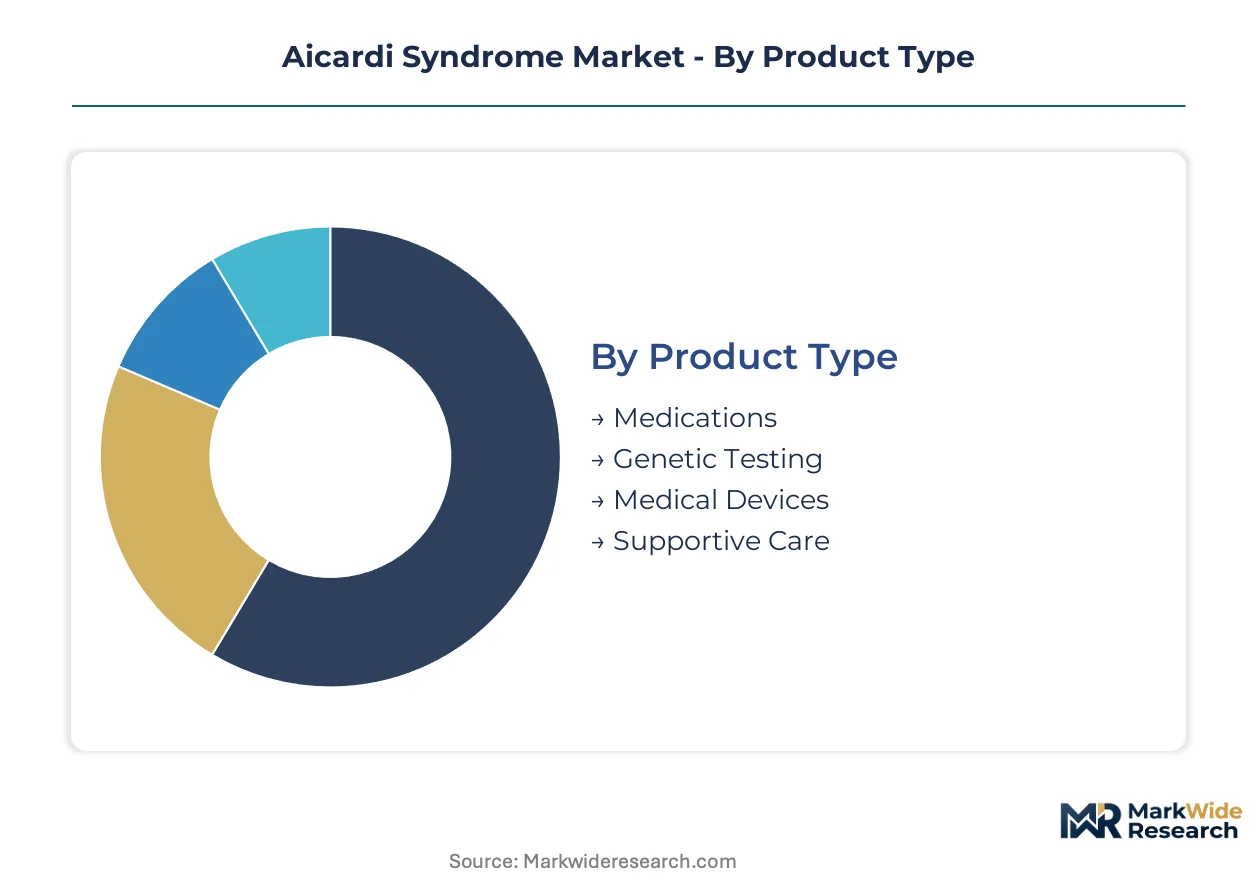
Aicardi syndrome demands precise segmentation due to its ultra-rare incidence and complex multidisciplinary care requirements. Product and application boundaries blur as genetic testing workflows integrate with ongoing seizure management protocols.
Product Type:
Standalone therapeutic products dominate revenue capture, while embedded diagnostic systems harden into bundled care pathways.
- Medications:Antiepileptic drugs constitute the foundational pharmacotherapy for infantile spasms, with vigabatrin and adrenocorticotropic hormone anchoring first-line protocols. Tertiary pediatric epilepsy centers in the United States concentrate demand through specialized intake pathways. FDA orphan drug incentives compress development timelines for neurodevelopmental disorder pipelines.
- Genetic Testing:Next-generation sequencing panels identify pathogenic NDP variants and X-linked chromosomal abnormalities essential for definitive diagnosis. Academic medical centers in Boston and Philadelphia anchor testing volume through integrated neurogenetics workflows. Reimbursement code fragmentation across molecular pathology and genetic counseling complicates payer navigation.
- Medical Devices:MRI and EEG hardware placement supports diagnostic confirmation and seizure monitoring.
- Supportive Care:Visual rehabilitation and developmental therapy services extend across the patient lifespan.
Medications lead volumes today; genetic testing is gaining share fastest.
Application:
High-acuity settings anchor initial diagnosis, while longitudinal management fragments across community and home-based channels.
- Pediatric Neurology:Fellowship-trained specialists integrate MRI interpretation, EEG pattern recognition, and antiepileptic titration at academic medical centers. Boston Children's Hospital and Children's Hospital of Philadelphia concentrate complex case volume through dedicated Aicardi syndrome care pathways. Workforce scarcity limits diagnostic capacity at community hospitals.
- Genetic Counseling:Certified counselors navigate X-linked inheritance patterns and family planning decisions for affected families. Tertiary centers retain high-complexity cases while telemedicine extension reaches underserved regions. Cross-institutional data sharing frameworks under HIPAA enable longitudinal outcome tracking.
- Rehabilitation:Occupational and physical therapy addresses developmental delays and motor dysfunction.
- Clinical Trials:Natural history registries attract pharmaceutical sponsorship for real-world evidence generation.
Pediatric neurology captures the dominant share; genetic counseling is expanding most quickly.
End User:
Capital intensity and regulatory compliance requirements stratify end users across institutional tiers.
- Hospitals:Tertiary pediatric centers anchor integrated care through dedicated epilepsy and neurogenetics units. MRI and EEG infrastructure demands substantial upfront investment that resource-constrained institutions defer. United States specialized centers attract international cross-border referrals.
- Research Institutions:Academic medical centers drive natural history registry expansion and preclinical therapeutic development. Gene therapy platform adaptation leverages existing CNS biodistribution data from comparable neurodevelopmental disorders.
- Outpatient Clinics:Regional neurology practices absorb stable patients following acute diagnosis at flagship institutions.
- Home Care Providers:Nursing support extends seizure management and developmental therapy to residential settings.
Hospitals dominate value capture; research institutions are climbing the fastest.
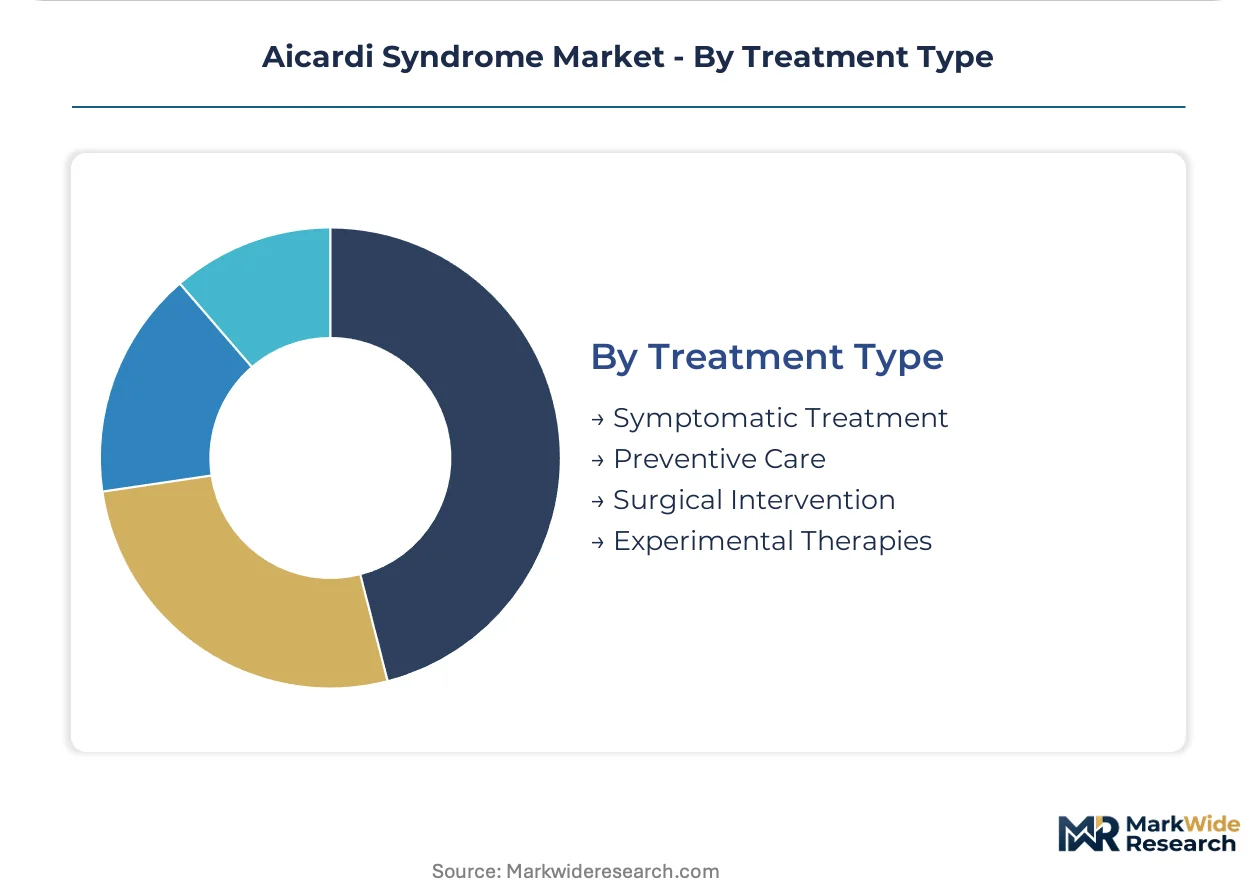
Treatment Type:
Evidentiary standards and regulatory pathways fragment therapeutic approaches across approved and experimental categories.
- Symptomatic Treatment:Antiepileptic pharmacotherapy and visual rehabilitation address presenting clinical manifestations without modifying underlying pathology. FDA-approved agents anchor immediate clinical management while experimental programs pursue disease-modifying targets.
- Preventive Care:Early developmental intervention and nutritional support mitigate secondary complications. Genetic counseling integration reduces recurrence risk in family planning decisions.
- Surgical Intervention:Corpus callosotomy and vagus nerve stimulation address refractory seizure patterns in select candidates.
- Experimental Therapies:Gene therapy vectors and antisense oligonucleotides target NDP pathogenic variants in preclinical and early-phase programs. EMA PRIME designation and FDA Breakthrough Therapy pathways accelerate evidentiary flexibility for ultra-orphan indications.
Symptomatic treatment anchors current practice; experimental therapies show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
French neurologist Jean Aicardi first described this rare neurodevelopmental disorder in 1965, establishing the diagnostic triad that now anchors clinical recognition worldwide. Subsequent decades saw diagnostic protocols migrate from Parisian academic centers into tertiary pediatric neurology units across North America, Europe, and East Asia. Today, specialized epilepsy centers in the United States, Germany, Japan, and the United Kingdom concentrate the majority of confirmed cases and drive therapeutic innovation.
United States
Pediatric epilepsy centers at Boston Children's Hospital and Children's Hospital of Philadelphia anchor North American diagnostic capacity through integrated MRI-EEG-genetics workflows. FDA orphan drug tax credits and expanded access frameworks accelerate pharmaceutical development timelines for ultra-rare neurodevelopmental indications. Cross-border patient referrals from Canada and Latin America concentrate at these tertiary hubs, consolidating regional expertise and clinical trial enrollment.
Germany
University hospitals in Munich and Heidelberg maintain Europe's densest concentration of pediatric neurogenetics specialists capable of variant interpretation across X-linked dominant disorders. EMA PRIME designation and CE marking under MDR determine market access for neuroimaging devices and experimental therapeutics. The country's statutory health insurance system provides more consistent reimbursement for genetic testing than fragmented payer environments elsewhere.
Japan
Designated pediatric epilepsy centers in Tokyo and Osaka integrate high-resolution neuroimaging with optical coherence tomography for chorioretinal lacunae detection. PMDA's sakigake designation pathway accelerates regulatory review for drugs addressing severe unmet need in ultra-small populations. Domestic pharmaceutical developers leverage existing CNS viral vector platforms from comparable neurodevelopmental gene therapy programs.
United Kingdom
Genomics England's rare disease sequencing infrastructure supports diagnostic confirmation at tertiary centers in London and Manchester. NHS specialized commissioning frameworks concentrate Aicardi syndrome care within designated pediatric neurology networks. Brexit-related regulatory divergence from EMA pathways creates uncertainty for parallel submission strategies, though MHRA maintains alignment on orphan drug evidentiary standards.
Switzerland
Swissmedic's streamlined pediatric orphan drug review attracts pharmaceutical sponsors seeking rapid European market authorization. University hospitals in Zurich and Geneva anchor alpine region referral patterns from Austria, Italy, and France. The country's precision medicine initiatives fund natural history registry development for ultra-rare neurodevelopmental conditions.
Aicardi Syndrome Market Vendor Landscape
Premium-margin players sit above commodity-margin players across the diagnostic hardware and therapeutic development vectors in this ultra-rare disease space. The market structure bifurcates between diversified conglomerates with orphan disease portfolios and specialized neurology-focused device manufacturers. Three archetypes dominate: integrated neuroimaging platform vendors, antiepileptic drug developers with rare disease pipelines, and genetic testing service laboratories. Competitive dynamics center on strategic partnerships between diagnostic hardware suppliers and tertiary hospital networks, alongside portfolio diversification into adjacent neurodevelopmental indications.
Within the diversified pharmaceutical tier, Novartis AG exemplifies orphan disease portfolio leverage, while Siemens Healthineers anchors diagnostic workflow integration. Canon Medical Systems Europe B.V. occupies a position competing on imaging resolution specifications tailored to infant neuroimaging protocols. These three entities represent distinct strategic postures: therapeutic development incentives, diagnostic platform convergence, and specialized hardware differentiation.
| Leading Market Players |
|---|
| Novartis AG |
| General Electric Company |
| Koninklijke Philips N.V. |
| Canon Medical Systems Europe B.V. |
| Therapy Solutions Inc. |
| Hitachi Ltd. |
| Siemens Healthineers |
| Medtronic |
| Aicardi Syndrome Foundation |
| Others |
Supply Flow & Price Mechanics
Academic medical center consortiums with embedded pharmaceutical sponsorship programs anchor procurement volume for Aicardi syndrome therapeutics, concentrating purchasing power at tertiary pediatric epilepsy centers while fragmenting price negotiation leverage across smaller regional hospitals. This ownership pattern compresses margins on antiepileptic drugs and genetic testing services as flagship institutions extract volume discounts, while supply chain resilience hinges on single-source dependencies for specialized neuroimaging hardware and viral vector manufacturing platforms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the Aicardi syndrome market, with FDA-designated orphan drugs commanding premium positioning against generic antiepileptic alternatives and bundled care pathway subscriptions. Price differentiation rests on certification tier — FDA Breakthrough Therapy versus standard approval — and geographic delivery cost, with cross-border patient referrals to United States centers absorbing elevated logistics premiums. Cost compression in genetic testing is intensifying because next-generation sequencing panel commoditization erodes laboratory margins. Community hospitals exhibit highest price sensitivity due to capital constraint, while academic medical centers prioritize clinical outcomes over procurement cost.
Supply Chain Analysis
Domestic-content mandates for critical medical devices under FDA and EMA frameworks are reshaping sourcing patterns for MRI and EEG hardware, pushing manufacturers toward regional assembly hubs to maintain market access. Manufacturing concentrates in the United States, Germany, and Japan for high-field MRI systems, while viral vector production for gene therapy candidates clusters in Switzerland and the United Kingdom. Raw material dependencies include superconducting magnet wire, specialized semiconductor detectors, and GMP-grade plasmid DNA. Single-source vulnerability pervades the viral vector tier where qualified manufacturing capacity remains scarce. Distribution runs through tertiary hospital procurement committees and integrated delivery networks rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Aicardi syndrome therapeutics rests on gene therapy platform standardization reducing per-patient manufacturing cost, alongside diagnostic workflow automation compressing labor intensity at pediatric neurology centers.
For Market Incumbents: Anticipate gene therapy vector manufacturing scale-up as the critical defensive maneuver, securing GMP capacity ahead of regulatory submission waves while consolidating diagnostic hardware placement contracts against emerging imaging AI competitors. Vertical integration into viral vector production insulates supply security. FDA orphan drug exclusivity windows provide temporary pricing power that must be converted to registry data assets before expiration. For New Entrants and Emerging Players: The mid-tier pricing gap between premium orphan biologics and generic antiepileptics offers viable entry positioning for biosimilar developers and telemedicine neurology platforms targeting underserved geographic regions. White-space concentration lies in Latin American and Southeast Asian referral markets lacking specialized pediatric epilepsy infrastructure. A direct-to-hospital genetic testing service model bypasses incumbent laboratory networks. For Investors and Strategic Acquirers: Diversified rare disease pharmaceutical developers are the most active acquirer in this space, seeking preclinical gene therapy assets with existing CNS biodistribution data. Long-term viability over the next decade hinges on successful translation of antisense oligonucleotide platforms from comparable neurodevelopmental indications. The signal to watch is EMA PRIME designation frequency for ultra-orphan neurodevelopmental programs as inflection indicator for regulatory pathway maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Natural History Registry Expansion | HIPAA-compliant data sharing attracts pharmaceutical sponsorship for real-world evidence generation. |
| Gene Therapy Platform Adaptation | Viral vector delivery systems transfer from comparable neurodevelopmental disorder programs. |
| Telemedicine Neurology Extension | Remote consultation protocols extend specialized epilepsy expertise to underserved regions. |
| Diagnostic Workflow Integration | MRI-EEG convergence at Boston Children's Hospital and CHOP reduces time-to-diagnosis. |
| Orphan Drug Regulatory Pathway | FDA tax credits and market exclusivity provisions accelerate neurodevelopmental pipeline investment. |
Methodological Framework
Multiple input streams — structured interviews with pediatric neurologists and genetic counselors, regulatory filing analysis, and hospital procurement database review — were reconciled to construct demand estimates for Aicardi syndrome therapeutics and diagnostics. Primary fieldwork encompassed discussions with formulary directors at tertiary pediatric centers, payer access specialists managing ultra-orphan indications, and biomedical engineers optimizing neuroimaging protocols. Secondary validation drew from FDA orphan drug designations, EMA PRIME eligibility assessments, ClinicalTrials.gov enrollment data, and CMS Medicare claims patterns. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Data-stream reconciliation across the projection horizon applied analytical frameworks segmenting by treatment line, genetic confirmation status, and regional regulatory cluster. Modeled dimensions encompassed symptomatic versus experimental therapeutic categories, hospital-based versus outpatient care settings, and United States versus European versus Asia-Pacific adoption patterns. CAGRs were derived from longitudinal natural history registry enrollment trends and pharmaceutical pipeline progression rates. Forecast inputs incorporated FDA expanded access program utilization and cross-border referral volume concentration at specialized epilepsy centers.
Caveats apply where regulatory evidentiary standard shifts, gene therapy manufacturing scale-up delays, or pediatric neurogenetics workforce scarcity could materially shift the outlook. Forecasts embed assumptions regarding orphan drug incentive continuity and reimbursement code consolidation for multidisciplinary care coordination. A small set of named triggers — EMA-FDA regulatory divergence on ultra-orphan endpoints, viral vector supply disruption, and telemedicine reimbursement parity legislation — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Treatment Market
Rare Diseases
Global Guillain-Barre Syndrome Market
Rare Diseases
Rosai-Dorfman Disease (RDD) Therapeutics Market
Rare Diseases
Canavan Disease Treatment Market
Rare Diseases
Achondrogenesis Market
Rare Diseases
Byler Disease Market
Rare Diseases
Methylmalonic Acidemia Market
Rare Diseases
Middle East and Africa Rett Syndrome Market
Rare Diseases
Europe Down Syndrome Market
Rare Diseases
Rare Neurological Disease Treatment Market
Rare Diseases
Asia-Pacific Down Syndrome Market
Rare Diseases
Rare Inflammatory Disease Treatment Market
Rare Diseases
Churg Strauss Syndrome Market
Rare Diseases
Hutchinson-Gilford Progeria Syndrome Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Management Market