
 Lubricating Eye Drops Market | 2026-2036
Lubricating Eye Drops Market Size, Share, and Industry Trends Forecast 2026-2036
Lubricating Eye Drops Market Insights
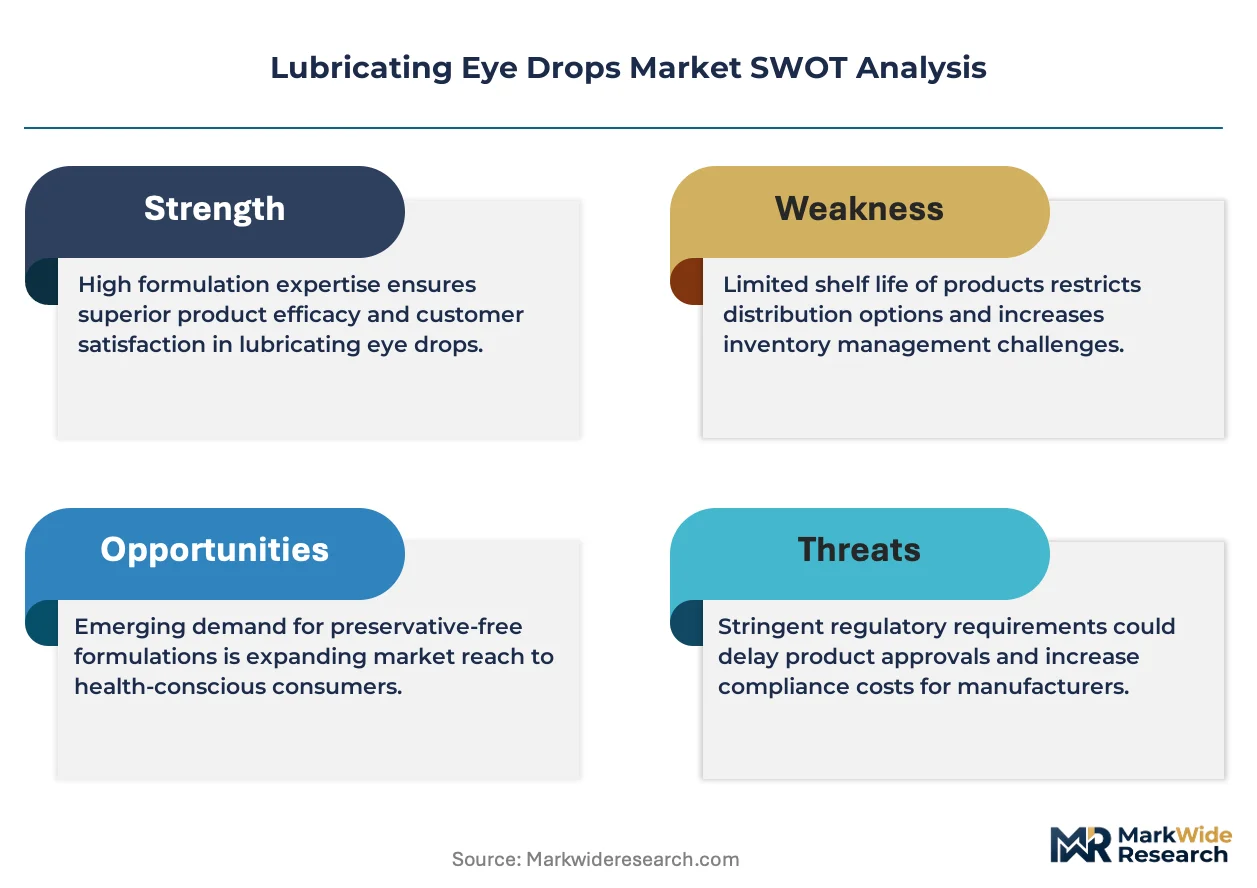
Preservative-free formulation technology is tilting manufacturing investments toward unit-dose blow-fill-seal lines and aseptic filling infrastructure. Alcon leverages its surgical ophthalmology heritage to anchor premium dry eye portfolios across hospital and clinic channels. Bausch + Lomb sustains broad retail pharmacy distribution that competes on shelf presence and consumer recognition. Santen Pharmaceutical specializes in Asian-market formulations with differentiated viscosity profiles for contact lens wearers.
Lubricating eye drops are sterile, isotonic aqueous or oil-based solutions containing demulcents such as carboxymethylcellulose, hyaluronic acid, or polyethylene glycol, formulated within pH 6.5–8.0 and osmolality 200–400 mOsm/kg to restore tear film stability and ocular surface lubrication. The preservative-free segment occupies the fastest-expanding margin pool as regulatory scrutiny of benzalkonium chloride toxicity intensifies across multiple jurisdictions. Dry eye syndrome applications dominate volume consumption, while post-surgery relief formulations command premium positioning due to stricter sterility and endotoxin standards. Gel drops and ointments extend nighttime retention for severe evaporative dry eye, though their blurred-vision trade-off limits daytime adoption.
The FDA oversees over-the-counter monograph compliance and new drug application pathways for novel active ingredients, while the EMA's Medical Device Regulation reclassifies certain combination drop-device products, altering market access requirements for European suppliers. ISO 11930 and USP <51> antimicrobial effectiveness testing shape preservative system validation, with preservative-free alternatives requiring alternative sterility assurance strategies. Stakeholders must monitor how evolving regulatory distinctions between drugs and medical devices reshape competitive boundaries and investment thresholds for new market entrants.
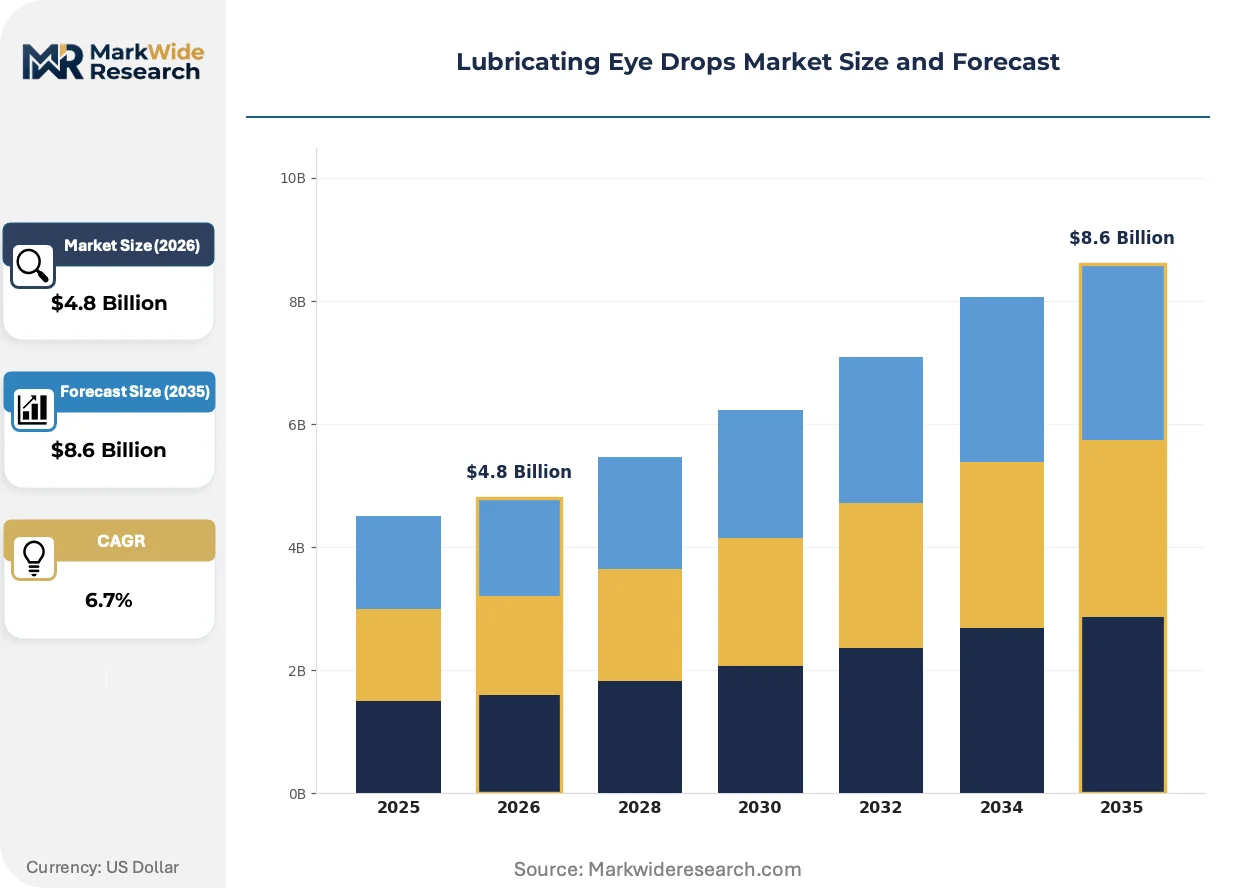
Market Dynamics
Preservative-free formulation mandates from the FDA are compressing manufacturing timelines while forcing capital redeployment into aseptic blow-fill-seal infrastructure. This regulatory compression is reshaping competitive entry barriers and margin structures simultaneously.
Growth Catalysts
- Digital workforce expansion:Screen-time exposure among remote workers and knowledge professionals is enlarging the addressable patient pool for evaporative dry eye therapies across North American and European labor markets.
- REACH regulatory tightening:The ECHA's scrutiny of benzalkonium chloride environmental persistence is accelerating European manufacturer migration toward preservative-free alternatives and unit-dose formats.
- Hyaluronic acid stabilization:Advances in molecular weight engineering are extending drop residence time on the ocular surface, improving therapeutic efficacy for moderate-to-severe dry eye presentations.
Market Restraints
- Aseptic filling capex intensity:Blow-fill-seal line installation and validation costs exceed $15 million per facility, concentrating production scale among established pharmaceutical manufacturers.
- API supply concentration:High-purity sodium hyaluronate production clusters in Chinese and Japanese fermentation facilities, creating geographic single-source vulnerability for Western formulators.
- Contact lens compatibility limitations:Viscosity-enhancing polymers in gel-drop formulations compromise lens wettability, restricting daytime use among the 150 million global contact lens wearers.
Strategic Opportunities
- Indian pharmacy modernization:CDSCO streamlining of OTC monograph pathways is opening direct-to-consumer channels for preservative-free formulations in India's expanding retail pharmacy network.
- Post-refractive surgery protocols:LASIK and PRK volume recovery is creating sustained demand for prescription-grade lubrication with endotoxin specifications stricter than standard OTC products.
- Telehealth integration:Remote diagnostic platforms for dry eye severity scoring are enabling direct-to-patient subscription models bypassing traditional ophthalmology clinic gatekeepers.
Industry Challenges
- Aseptic process engineering talent scarcity:Qualified personnel for isolator technology operation and media-fill validation are concentrated among contract manufacturing organizations with limited capacity expansion.
- USP <51> antimicrobial testing bottlenecks:Preservative-free alternative validation requires extended sterility assurance studies, compressing product development timelines by 12–18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lubricating Eye Drops Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preservative-Free, Gel Drops, Ointments, Dropper Bottles Delivery Mode: Single Use, Multi Dose, Squeeze Bottles, Sprays End User: Hospitals, Clinics, Pharmacies, Home Care Application: Allergic Conjunctivitis, Dry Eye Syndrome, Post-Surgery Relief, Contact Lens Care |
| Companies Covered | Alcon, Bausch + Lomb, Abbott Medical Optics, Johnson & Johnson Vision, Novartis, Santen Pharmaceutical, Rohto Pharmaceutical, Otsuka Pharmaceutical, Clear Eyes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lubricating Eye Drops Market Trends and Innovations
Formulation science is converging with device engineering to create combination products that extend residence time while preserving visual clarity. This convergence is blurring historical boundaries between pharmaceutical and medical device regulatory pathways.
Lipid-based nanoemulsion technology is hybridizing aqueous and oil-phase tear film components into single-drop delivery. Contact lens manufacturers in Japan and South Korea are adopting these hybrid formulations for co-branded lens care portfolios. The technology is hybridizing competitive positioning between traditional artificial tear producers and ocular surface disease pharmaceutical developers.
The FDA's evolving OTC monograph reform initiative is collapsing the distinction between cosmetic eye drops and therapeutic lubricants for dry eye syndrome. Manufacturers must now navigate NDA pathways for novel active ingredients previously grandfathered under older monographs. Preservative-free combination products with device elements face reclassification scrutiny that is extending pre-market review timelines.
Subscription-based replenishment models are displacing pharmacy shelf purchasing for chronic dry eye patients in the United States and United Kingdom. Direct-to-consumer platforms capture patient usage data that informs personalized formulation recommendations and automated reorder timing. This channel migration is most visible among millennials and Generation X demographics managing screen-related ocular surface stress.
Lubricating Eye Drops Market Segmentation
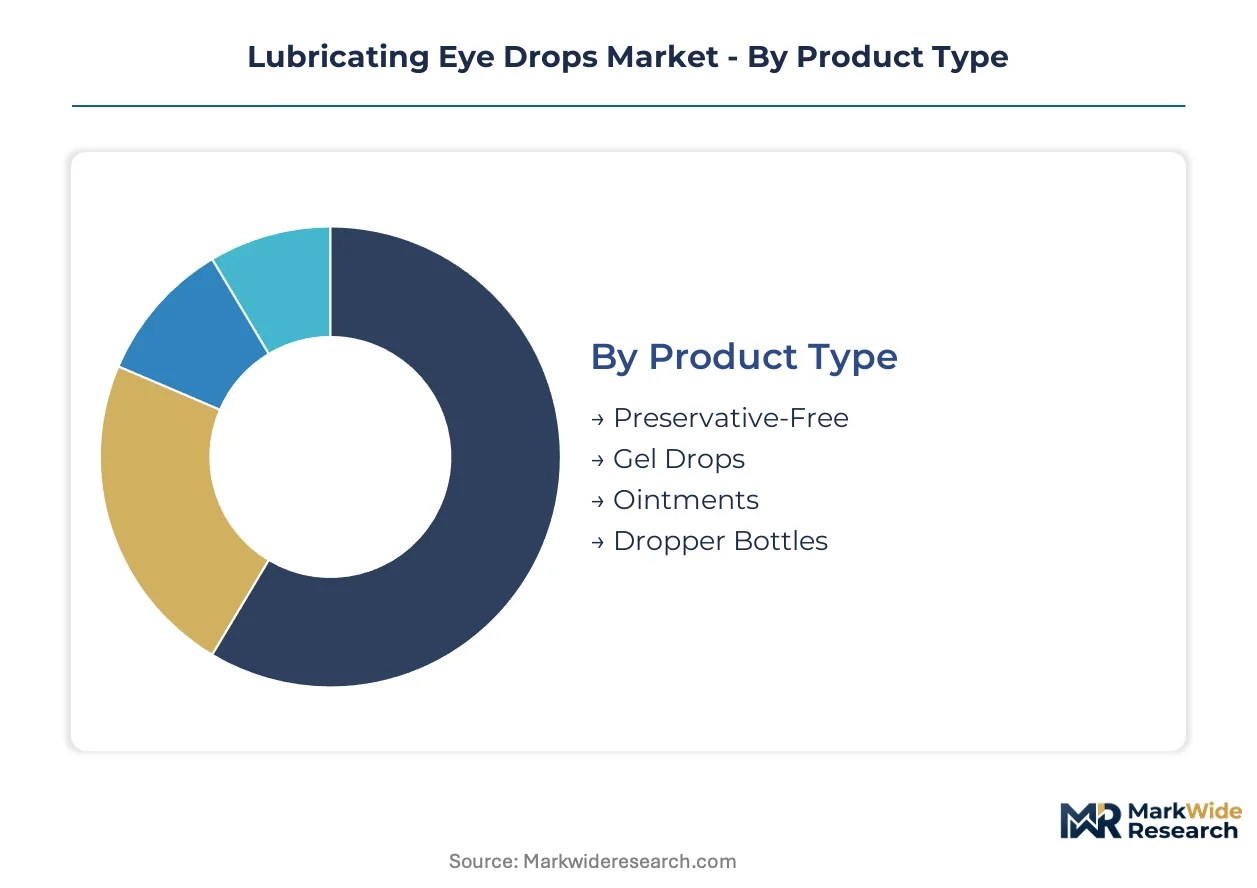
Segmentation in lubricating eye drops reveals how formulation technology, delivery engineering, and care setting economics split manufacturing investment and margin capture. Each dimension carries distinct regulatory load and channel access requirements.
Product Type:
Mature preservative systems face displacement as unit-dose formats scale, while viscosity engineering creates tiered performance positioning.
- Preservative-Free:Aseptic blow-fill-seal manufacturing eliminates benzalkonium chloride through single-use polymer vials. United States demand concentrates among post-surgical patients and chronic dry eye sufferers with corneal sensitivity. FDA monograph reform is compressing approval timelines for novel actives in this format.
- Gel Drops:High-molecular-weight polymer matrices extend ocular surface residence time through carbomer or cellulose thickening. Nighttime use dominates as visual clarity trade-offs restrict daytime adoption among screen workers. Japanese and Korean formulators lead viscosity optimization for contact lens compatibility.
- Ointments:Petrolatum and mineral oil bases provide overnight lubrication for severe evaporative dry eye.
- Dropper Bottles:Multi-dose containers with preserved formulations retain cost advantage in emerging pharmacy channels.
Preservative-Free handles the majority of throughput; Gel Drops is the fastest mover on share.
Delivery Mode:
Unit economics and sterility assurance requirements divide manufacturing scale between high-throughput multi-dose lines and flexible aseptic packaging.
- Single Use:Polypropylene vials produced via blow-fill-seal technology eliminate contamination risk for immunocompromised patients. REACH regulatory tightening in Europe accelerates migration from preserved multi-dose formats. CDSCO pathway streamlining in India is opening direct-to-consumer channels for unit-dose portfolios.
- Multi Dose:Bottled formulations with antimicrobial preservatives serve price-sensitive chronic users through retail pharmacy networks. Bausch + Lomb and Alcon maintain shelf presence dominance via this format's distribution economics.
- Squeeze Bottles:Soft plastic containers enable controlled drop dispensing for elderly patients with dexterity limitations.
- Sprays:Mist delivery systems target pediatric and geriatric populations with blink reflex coordination challenges.
Multi Dose retains volume leadership; Single Use is climbing the fastest on regulatory tailwinds.
End User:
Channel economics and reimbursement structures concentrate premium positioning in institutional settings while home care scales through retail and subscription.
- Hospitals:Surgical ophthalmology departments demand endotoxin-tested formulations for LASIK and cataract recovery protocols. Alcon leverages its surgical heritage to anchor premium dry eye portfolios in this channel. Stricter sterility standards support pricing premiums above standard OTC tiers.
- Clinics:Ophthalmology and optometry practices serve as gatekeepers for prescription-grade lubrication with diagnostic-linked severity scoring.
- Pharmacies:Retail distribution competes on shelf presence and pharmacist recommendation in India's expanding network.
- Home Care:Direct-to-consumer subscription platforms capture millennials and Generation X demographics managing screen-related ocular stress.
Hospitals command the steepest pricing; Home Care is expanding most quickly through telehealth integration.
Application:
Disease severity and acute-versus-chronic presentation determine formulation specification and reimbursement pathway.
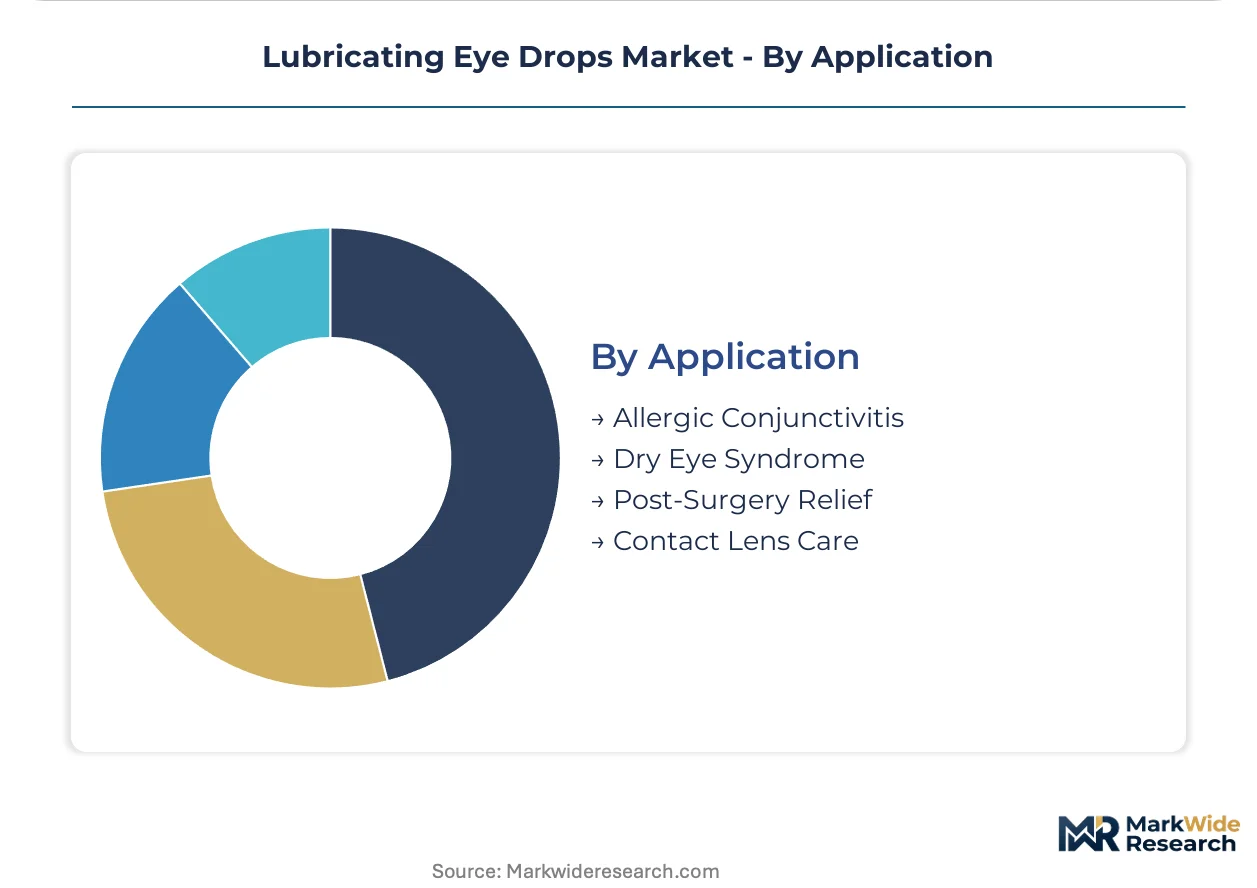
- Dry Eye Syndrome:Evaporative and aqueous-deficient subtypes drive volume consumption across all delivery modes. Digital workforce expansion in North American and European labor markets enlarges the addressable patient pool. Hyaluronic acid molecular weight engineering is extending drop residence time for moderate-to-severe presentations.
- Post-Surgery Relief:LASIK and PRK volume recovery creates sustained demand for prescription-grade lubrication with endotoxin specifications stricter than standard OTC products. Santen Pharmaceutical specializes in Asian-market formulations for this indication.
- Allergic Conjunctivitis:Antihistamine-lubricant combination products address seasonal ocular surface inflammation.
- Contact Lens Care:Viscosity-enhancing polymers in gel-drop formulations compromise lens wettability, restricting daytime use among the 150 million global contact lens wearers.
Dry Eye Syndrome generates the dominant volume share; Post-Surgery Relief carries the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in lubricating eye drops tilt toward import dependence in Western markets while Asian producers build export-oriented fermentation capacity for hyaluronic acid raw materials. The United States absorbs premium formulations from Swiss and Japanese manufacturers. European demand pulls concentrated supply from German and Italian aseptic filling facilities.
United States
Digital workforce expansion across technology and financial services sectors enlarges the chronic dry eye patient pool. FDA monograph reform is compressing approval timelines for preservative-free novel actives. The Research Triangle Park corridor in North Carolina hosts contract manufacturing organizations scaling blow-fill-seal capacity for unit-dose ophthalmic products.
Germany
Aging demographics and high ophthalmic care access rates sustain category expansion across pharmacy networks. ECHA scrutiny of benzalkonium chloride environmental persistence is accelerating manufacturer migration toward preservative-free alternatives. The Frankfurt-Rhine-Main biopharma cluster concentrates aseptic filling infrastructure serving pan-European distribution.
Japan
Contact lens wearer density and screen-intensive work cultures drive volume consumption of viscosity-optimized formulations. PMDA oversight of combination drop-device products shapes regulatory pathways for novel delivery systems. The Kansai region around Osaka anchors fermentation-based sodium hyaluronate production for regional formulators.
India
Retail pharmacy network expansion and rising self-medication awareness enlarge the addressable consumer base. CDSCO streamlining of OTC monograph pathways is opening direct-to-consumer channels for preservative-free formulations. Maharashtra's Mumbai-Pune pharmaceutical corridor concentrates formulation and packaging capacity for domestic and export markets.
China
Urbanization-linked screen exposure and aging population dynamics expand dry eye syndrome diagnosis rates. NMPA alignment with international ICH guidelines is harmonizing approval pathways for imported ophthalmic products. The Yangtze River Delta around Shanghai hosts fermentation facilities supplying high-purity hyaluronic acid to Western formulators.
Lubricating Eye Drops Market Competitive Landscape
On the supply side, the industry is consolidating around pharmaceutical conglomerates with legacy ophthalmology portfolios and specialized Asian formulators with differentiated viscosity engineering. Tiered competitive positioning separates surgical-channel premium suppliers from retail pharmacy volume players. Strategic archetypes include integrated surgical ophthalmology platforms, fermentation-derived API specialists, and regional pharmacy distribution networks. Capacity expansion into aseptic blow-fill-seal infrastructure and technology licensing for preservative-free stabilization represent dominant competitive moves.
Among the integrated multinational tier, Alcon and Bausch + Lomb exemplify divergent channel strategies—Alcon anchoring premium hospital and clinic positioning through surgical heritage, Bausch + Lomb sustaining broad retail pharmacy shelf presence. Santen Pharmaceutical occupies a position within the Asian-market specialization archetype, representing differentiated formulation approaches for contact lens compatibility and post-surgical protocols. These three anchors illustrate how geographic origin and channel concentration shape competitive differentiation in formulation technology and regulatory navigation.
| Leading Market Players |
|---|
| Alcon |
| Bausch + Lomb |
| Abbott Medical Optics |
| Johnson & Johnson Vision |
| Novartis |
| Santen Pharmaceutical |
| Rohto Pharmaceutical |
| Otsuka Pharmaceutical |
| Clear Eyes |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta around Shanghai anchors global hyaluronic acid fermentation capacity, and its output fluctuations transmit directly into Western formulators' raw material costs and downstream pricing power for premium preservative-free formulations.
Pricing Analysis
Hospital procurement committees anchor three-tier pricing structure across premium, standard, and economy levels in the lubricating eye drops market. Price differentiation rests on endotoxin certification grade and aseptic manufacturing scale, with post-surgical formulations commanding substantial premiums over standard OTC tiers. Pricing pressure stems from CDSCO pathway streamlining in India opening direct-to-consumer channels that compress retail pharmacy markups. Retail pharmacy networks exhibit highest price sensitivity, while surgical channel buyers prioritize sterility assurance over unit cost.
Supply Chain Analysis
Extended payment terms from Japanese and Korean contact lens manufacturers now stretch to ninety days, tightening working capital for mid-tier formulators competing in Asian markets. Geographic supply concentrates in China, Japan, and Germany, with high-purity sodium hyaluronate fermentation drawing from the Yangtze River Delta and Osaka-Kansai corridor. Single-source vulnerability runs through Chinese fermentation facilities for Western pharmaceutical companies lacking backward integration into API production. Distribution runs through hospital purchasing committees, retail pharmacy networks, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lubricating eye drops market sits in cyclical recovery mode as LASIK and PRK surgical volumes rebound from pandemic-era deferrals, creating sustained demand for prescription-grade lubrication with stricter endotoxin specifications.
For Market Incumbents: Build regulatory moat through preemptive FDA NDA submissions for novel active ingredients ahead of OTC monograph reform completion. Alcon and Bausch + Lomb should accelerate blow-fill-seal capacity expansion in Research Triangle Park to capture preservative-free volume migration. Defensive consolidation through acquisition of Asian fermentation specialists would secure hyaluronic acid supply amid Chinese single-source concentration.
For New Entrants and Emerging Players: India's underpenetrated retail pharmacy modernization offers the most accessible white-space target for preservative-free unit-dose formulations. CDSCO pathway streamlining enables direct-to-consumer channels bypassing traditional ophthalmology gatekeepers. New entrants should target millennial and Generation X demographics managing screen-related ocular stress through telehealth-integrated subscription models.
For Investors and Strategic Acquirers: Long-term, this sits as a defensive healthcare staple play because chronic dry eye syndrome exhibits non-discretionary demand characteristics with recurring purchase patterns. Acquisition targets should profile as aseptic filling specialists with isolator technology capabilities and existing FDA establishment registrations. The signal to watch is FDA monograph reform implementation pace, which would compress approval timelines for novel preservative-free actives and reshape competitive entry economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Blow-Fill-Seal Capacity Expansion | Research Triangle Park contract manufacturers are scaling isolator technology to serve unit-dose preservative-free demand. |
| FDA New Drug Application Submission | Preemptive NDA filings for novel hyaluronic acid molecular weights secure regulatory exclusivity ahead of monograph reform. |
| Backward Integration into Fermentation | Western formulators are acquiring Japanese and Chinese sodium hyaluronate producers to reduce single-source API vulnerability. |
| Telehealth Platform Partnership | Dry eye diagnostic remote scoring enables direct-to-patient subscription models bypassing ophthalmology clinic gatekeepers. |
| REACH Compliance Repositioning | European manufacturers are accelerating benzalkonium chloride elimination to preempt ECHA environmental persistence restrictions. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with ophthalmology clinic administrators, hospital purchasing committee members, retail pharmacy category managers, aseptic manufacturing engineers, and regulatory affairs specialists at FDA-registered establishments. Secondary validation drew from FDA 510(k) and NDA filings, EMA Medical Device Regulation guidance documents, CDSCO OTC monograph publications, and USP antimicrobial effectiveness testing standards. Bottom-up patient population estimates and top-down pharmaceutical manufacturer revenue triangulation anchored market sizing.
Calibration against historical prescription volume data and surgical procedure registries informed trajectory assumptions across the analysis window. Segmentation modeling incorporated product type, delivery mode, end user channel, and application severity dimensions. CAGRs were derived from regression analysis of procedure volume growth, demographic aging curves, and digital workforce expansion patterns. Forecast inputs included LASIK and PRK surgical recovery timelines, REACH regulatory implementation schedules, and telehealth platform adoption rates.
Practitioners should monitor FDA monograph reform implementation, ECHA benzalkonium chloride restriction timelines, and Chinese fermentation facility regulatory inspections for early signals of forecast deviation. Forecasts reflect assumptions regarding sustained digital workforce expansion and surgical volume recovery. Macroeconomic recession impacting discretionary surgical procedures, regulatory reclassification of combination drop-device products, or API supply disruption from fermentation facility shutdowns would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Eye Allergy Treatment Market
Ophthalmology
Thyroid Eye Disease Treatment Market
Ophthalmology
Japan Ophthalmic Devices and Drugs Market
Ophthalmology
Ophthalmic Tonometers Market
Ophthalmology
Ophthalmic Loupes Market
Ophthalmology
Extended and Continuous Wear Lenses Market
Ophthalmology
Europe Dry Eye Syndrome Market
Ophthalmology
Global Ophthalmic Viscoelastic Devices Market
Ophthalmology
Global Vitreous Tamponades Market
Ophthalmology
Corneal Pachymetry Market
Ophthalmology
Global Ocular Inflammation Treatment Market
Ophthalmology
Vitrectomy Machines Market
Ophthalmology
Ophthalmic Suspension Market
Ophthalmology
Exophthalmos Treatment Market
Ophthalmology
Keratoconus Treatment Market
Ophthalmology
Global Glaucoma Treatment Market