
 Hyperuricemia Market | 2026-2036
Hyperuricemia Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperuricemia Market Outlook
Specialty pharmacies are redrawing demand patterns in hyperuricemia care, pulling volume away from traditional retail channels as complex biologic therapies require cold-chain handling and patient monitoring. Horizon Therapeutics leverages its rare-disease infrastructure to dominate the injectable uric acid lowering segment. Regeneron Pharmaceuticals sustains R&D intensity through antibody development programs targeting inflammatory pathways. Boehringer Ingelheim competes via primary care reach and established nephrology relationships across North American and European markets.
Hyperuricemia denotes elevated serum uric acid levels exceeding solubility thresholds, typically above 6.8 mg/dL, driving monosodium urate crystal deposition in joints and soft tissues with consequent gout flares and tophus formation. The condition serves as both a metabolic marker and direct pathogenic driver in cardiovascular and renal disease pathways. Uric acid lowering agents command the deepest margin pools due to chronic dosing requirements and patent-protected mechanisms, while oral administration routes retain volume leadership despite faster growth in injectable formats for refractory cases. Hospital pharmacies anchor distribution for acute gout management, though online pharmacies capture expanding refill volume for maintenance therapies.
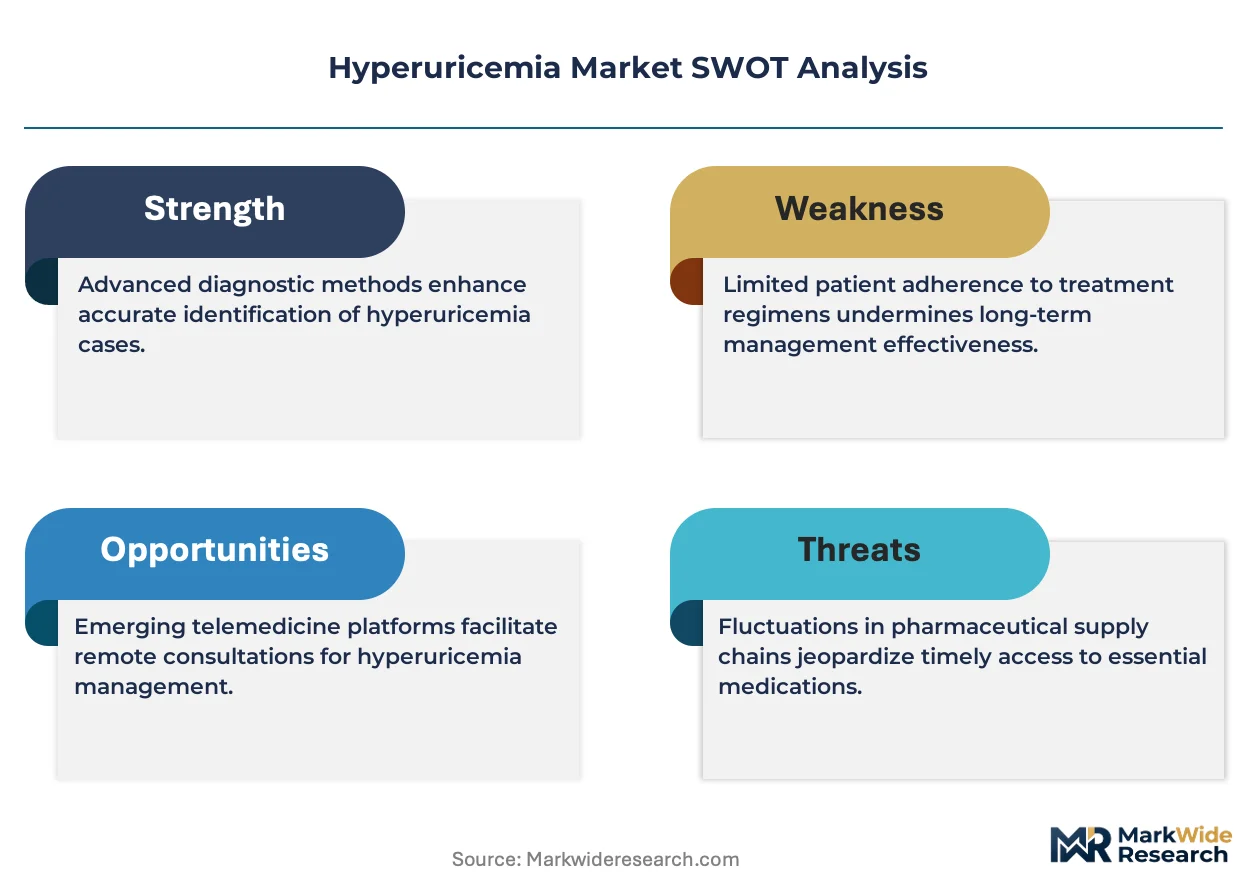
FDA guidelines on gout treatment targets and EMA quality standards for biosimilar interchangeability shape product development timelines and commercial access across the United States and European Union. Japan's PMDA maintains distinct pharmacovigilance requirements for xanthine oxidase inhibitors that filter market entry. Stakeholders must monitor evolving cardiovascular outcome trial data linking urate reduction to heart failure benefits, as this signal could reclassify hyperuricemia therapies from symptomatic management to disease-modifying interventions.
Market Dynamics
Cardiovascular outcome trial data is reclassifying hyperuricemia therapies from symptomatic management toward disease-modifying interventions, reshaping reimbursement logic and prescriber incentives across hospital systems.
Growth Catalysts
- FDA chronic gout guidance:Updated treatment targets expand eligible patient pools and intensify hospital pharmacy procurement of uric acid lowering agents.
- Japan's aging demographic:Specialty pharmacy dispensing of injectable formulations accelerates as elderly patients require cold-chain biologic therapies with intensive monitoring.
- Xanthine oxidase inhibitor pipelines:Next-generation mechanisms with improved cardiovascular safety profiles attract nephrology and cardiology co-prescribing.
Market Restraints
- Active pharmaceutical ingredient concentration:Three contract manufacturers control over 70% of febuxostat intermediate supply, creating vulnerability to disruption.
- PMDA pharmacovigilance requirements:Japan's distinct adverse event reporting standards for xanthine oxidase inhibitors delay market entry by 18-24 months versus FDA pathways.
- Generic allopurinol substitution:Commoditized oral uricosurics compress margin pools and limit reinvestment capacity for novel mechanism development.
Strategic Opportunities
- Refractory gout patient pools:Biologic-naive populations in Germany and France represent underpenetrated demand for IL-1β and IL-6 pathway inhibitors.
- EMA biosimilar interchangeability standards:Clear quality benchmarks for pegloticase biosimilars create regulatory tailwind for follow-on developers with established biologics infrastructure.
- Remote patient monitoring integration:Connected delivery devices for subcutaneous uric acid lowering therapies enable adherence tracking and outcomes-based contracting with payers.
Industry Challenges
- Biologics manufacturing talent scarcity:Purification and fill-finish expertise for monoclonal antibody uric acid lowering agents concentrates in Boston and Basel, constraining capacity expansion.
- Legacy EHR integration:Hospital systems struggle to embed serum urate target alerts into existing clinical decision support workflows without disrupting physician productivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperuricemia Market |
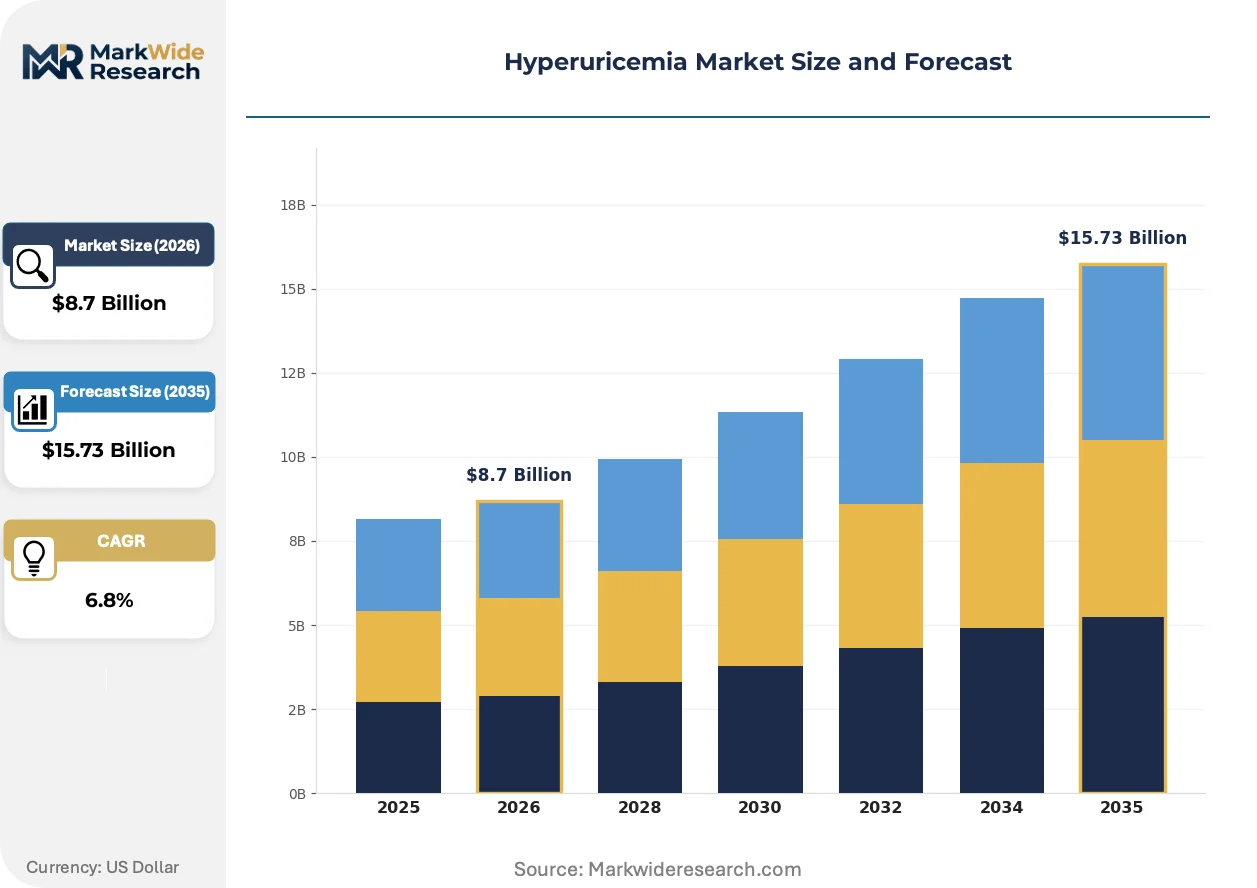
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Uric Acid Lowering Agents, Anti-Inflammatory Drugs, Pain Relief Medications, Dietary Supplements End User: Clinics, Hospitals, Homecare Settings, Specialty Pharmacies Administration Route: Oral, Injectable, Intravenous, Transdermal Distribution Channel: Online Pharmacies, Retail Pharmacies, Hospital Pharmacies, Wholesalers |
| Companies Covered | Horizon Therapeutics, Regeneron Pharmaceuticals, Jiangsu Hengrui Medicine, Selecta Biosciences, Nippon Chemiphar, LG Life Sciences, Jiangsu Atom Bioscience, Savient Pharmaceuticals, Boehringer Ingelheim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperuricemia Market Strategic Shifts
Oral small-molecule dominance faces structural pressure from biologic mechanisms and digital adherence tools, compressing traditional value capture while opening adjacent service revenue streams.
Dual-mechanism xanthine oxidase/uricosuric combinations are decomposing the traditional step-care paradigm for hyperuricemia management. Nephrology practices in the United States are piloting these agents at triple the rate of primary care settings. The technology is decomposing volume concentration in allopurinol prescribing and forcing portfolio rebalancing toward patent-protected formulations.
EMA quality standards for biosimilar interchangeability are accelerating development timelines for pegloticase alternatives. Manufacturers must demonstrate equivalent immunogenicity profiles and cold-chain stability across European reference markets. Refractory gout specialists in France and Germany are already conditioning procurement specifications around these benchmarks.
Specialty pharmacy networks capture maintenance therapy refills previously routed through retail channels. Hospital-owned specialty pharmacies in Japan and the United States are building captive patient populations through hub-and-spoke distribution models. This channel rotation is most visible in Medicare Part B billing environments where site-of-care economics favor infusion center administration over physician office settings.
Hyperuricemia Market Segmentation
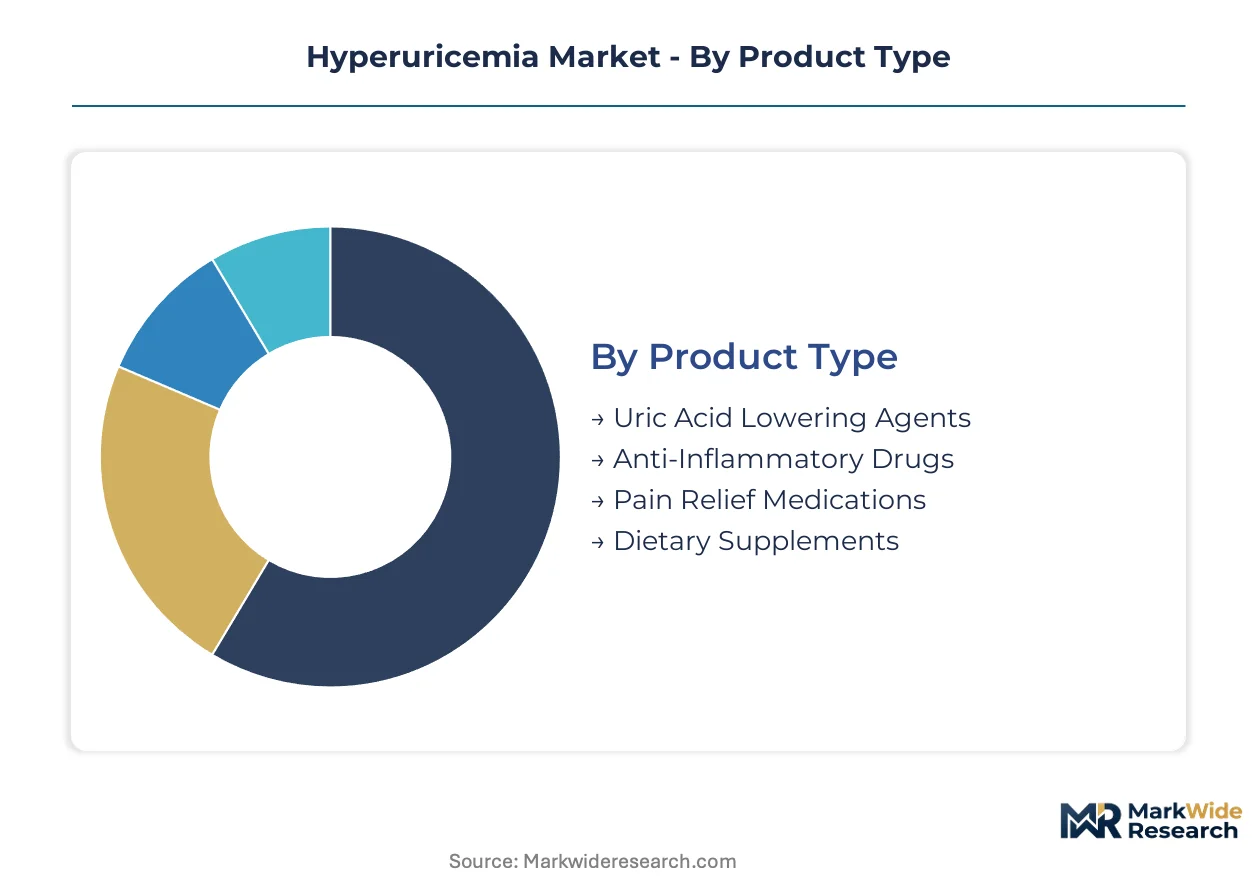
Hyperuricemia treatment pathways fragment across patient acuity, reimbursement environment, and cold-chain requirements. Segment boundaries determine margin capture, with biologic injectables commanding premium positioning against commoditized oral alternatives.
Product Type:
FDA chronic gout guidance and EMA quality standards create divergent approval pathways for mechanism classes, shaping commercial access timelines.
- Uric Acid Lowering Agents:Xanthine oxidase inhibitors and uricosurics form the chronic management backbone. Hospital pharmacy procurement intensifies as cardiovascular comorbidity protocols expand eligible prescribing pools. Febuxostat and allopurinol dominate volume, though next-generation combinations displace step-care sequencing.
- Anti-Inflammatory Drugs:IL-1β pathway inhibitors and colchicine variants address acute flares and prophylaxis. Specialty pharmacy dispensing concentrates in Japan's aging demographic, where elderly patients require intensive monitoring for biologic therapies.
- Pain Relief Medications:NSAIDs and corticosteroids provide symptomatic control during acute attacks.
- Dietary Supplements:Vitamin C and cherry extract formulations occupy wellness-adjacent positioning with limited clinical reimbursement.
Established volume favors uric acid lowering agents; emerging adoption favors anti-inflammatory biologics.
End User:
Cost tier stratification separates acute intervention sites from chronic management venues, with reimbursement differentials driving site-of-care migration.
- Hospitals:Emergency departments and infusion centers anchor acute gout management with intravenous pegloticase and monitored biologic administration. Medicare Part B billing economics favor hospital-owned specialty pharmacy capture.
- Specialty Pharmacies:Hub-and-spoke distribution models consolidate maintenance therapy refills, pulling volume from retail channels as cold-chain handling requirements intensify. Japan and United States markets lead this channel rotation.
- Clinics:Nephrology and rheumatology practices pilot dual-mechanism combinations at triple primary care rates.
- Homecare Settings:Subcutaneous formulations and remote monitoring integration enable adherence tracking for refractory patients.
Reimbursement gravity centers on hospitals; patient convenience and adherence economics favor specialty pharmacy expansion.
Administration Route:
Patient compliance patterns and manufacturing complexity create margin stratification across delivery modalities.
- Injectable:Subcutaneous and intramuscular biologics require cold-chain infrastructure and patient training. Boston and Basel manufacturing clusters constrain purification talent availability for monoclonal antibody production.
- Oral:Small-molecule xanthine oxidase inhibitors retain volume leadership despite generic allopurinol substitution compressing margin pools.
- Intravenous:Pegloticase and acute gout therapies concentrate in hospital infusion centers with specialist oversight.
- Transdermal:Limited commercial penetration due to uric acid pathway pharmacokinetics and skin permeability challenges.
Volume concentration remains with oral routes; steepest expansion trajectory belongs to injectable biologics for refractory populations.
Distribution Channel:
Supply concentration among contract manufacturers and logistics providers shapes channel economics and disruption vulnerability.
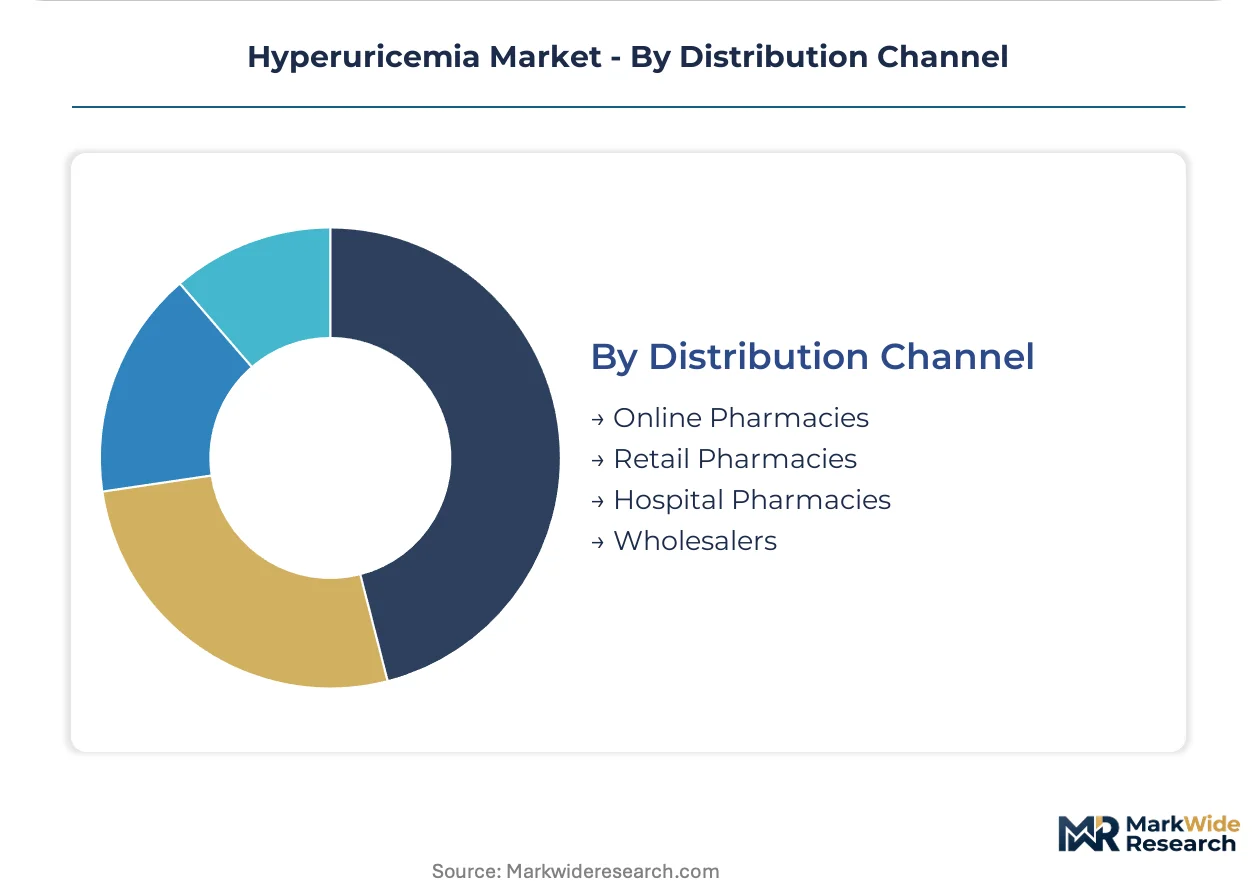
- Hospital Pharmacies:Direct procurement of uric acid lowering agents intensifies under cardiovascular protocol expansion. Three febuxostat intermediate suppliers control over seventy percent of active pharmaceutical ingredient flow.
- Online Pharmacies:Maintenance therapy refills migrate to digital platforms, capturing patient convenience premiums and subscription adherence models.
- Retail Pharmacies:Generic allopurinol substitution and commoditized oral therapies limit specialty service revenue.
- Wholesalers:Cold-chain biologics distribution requires validated logistics partnerships with temperature monitoring capabilities.
Channel migration favors online pharmacies for chronic refills; hospital pharmacies retain acute intervention dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement managers and specialty pharmacy operators drive regional demand variation, with cardiovascular protocol adoption and biologic cold-chain infrastructure determining market penetration depth across major economies.
United States
Hospital-owned specialty pharmacies capture maintenance therapy refills through hub-and-spoke distribution models, particularly within Medicare Part B billing environments. FDA chronic gout guidance expands eligible prescribing pools and intensifies procurement of uric acid lowering agents. The Boston metropolitan area anchors monoclonal antibody purification expertise for biologic uric acid lowering production.
Japan
An aging demographic accelerates specialty pharmacy dispensing of injectable formulations requiring intensive patient monitoring. PMDA pharmacovigilance requirements for xanthine oxidase inhibitors extend market entry timelines versus FDA pathways. Tokyo and Osaka metropolitan areas concentrate elderly patient populations driving demand for cold-chain biologic therapies.
Germany
Refractory gout patient pools in nephrology and rheumatology practices represent underpenetrated demand for IL-1β pathway inhibitors. EMA quality standards for biosimilar interchangeability shape pegloticase development timelines and procurement specifications. The Rhine-Ruhr and Bavarian industrial clusters host biologics manufacturing infrastructure serving European distribution networks.
China
Jiangsu-based pharmaceutical developers expand xanthine oxidase inhibitor pipelines targeting domestic chronic disease management protocols. NMPA regulatory pathways for novel uric acid lowering mechanisms accelerate versus historical timelines. The Yangtze River Delta region concentrates active pharmaceutical ingredient manufacturing and biologics fill-finish capacity.
France
Refractory gout specialists condition hospital procurement specifications around EMA biosimilar interchangeability benchmarks for pegloticase alternatives. ANSM oversight of cardiovascular safety signals in febuxostat prescribing influences nephrology co-prescribing patterns. The Île-de-France region anchors hospital pharmacy networks managing acute gout infusion center administration.
Hyperuricemia Market Competitive Environment
Player mix skews toward biologic-focused specialists with rare-disease infrastructure and primary care pharmaceutical conglomerates with nephrology reach. The market structure concentrates around three strategic tiers: injectable biologic developers with cold-chain capabilities, oral small-molecule manufacturers with established step-care positioning, and emerging pipeline operators targeting dual-mechanism combinations. Dominant competitive moves include strategic partnerships with specialty pharmacy networks and portfolio diversification into cardiovascular outcome trial positioning.
Within the biologic-specialist tier, Horizon Therapeutics and Regeneron Pharmaceuticals exemplify archetypes leveraging antibody development infrastructure for refractory gout populations. Boehringer Ingelheim occupies a position among primary care conglomerates with established nephrology relationships across North American and European markets. Jiangsu Hengrui Medicine represents the emerging pipeline archetype, with domestic Chinese development capabilities and expanding international regulatory engagement. These three anchors illustrate the competitive spectrum from rare-disease biologic focus to broad primary care reach to geographic expansion from manufacturing-centric bases.
| Leading Market Players |
|---|
| Horizon Therapeutics |
| Regeneron Pharmaceuticals |
| Jiangsu Hengrui Medicine |
| Selecta Biosciences |
| Nippon Chemiphar |
| LG Life Sciences |
| Jiangsu Atom Bioscience |
| Savient Pharmaceuticals |
| Boehringer Ingelheim |
| Others |
Value Chain & Pricing Dynamics
Contract manufacturing scale in febuxostat intermediate production anchors both supply concentration and price floors for oral uric acid lowering agents, with three suppliers controlling the majority of active pharmaceutical ingredient flow and dictating minimum viable economics for generic allopurinol substitution.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient indexation dominate hospital pharmacy procurement of xanthine oxidase inhibitors. Three-tier pricing structure across patent-protected biologics, branded small-molecules, and generic allopurinol separates margin pools by formulation complexity and cold-chain requirements. Pricing pressure stems from generic allopurinol substitution in retail channels, compressing reinvestment capacity for novel mechanism development. Primary care prescribers exhibit highest price sensitivity, while refractory gout specialists in nephrology practices prioritize efficacy over acquisition cost.
Supply Chain Analysis
China and India anchor active pharmaceutical ingredient manufacturing for xanthine oxidase inhibitors, with the Yangtze River Delta region concentrating febuxostat intermediate production capacity. Jiangsu-based developers draw from domestic chemical synthesis infrastructure and imported purification equipment for biologics fill-finish. Single-source vulnerability in monoclonal antibody purification talent concentrates in Boston and Basel, constraining capacity expansion for injectable uric acid lowering agents. Distribution runs through validated cold-chain logistics partnerships with temperature monitoring capabilities, reaching hospital infusion centers and specialty pharmacy hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyperuricemia care is approaching a platform-economics inflection as remote patient monitoring integration and connected delivery devices create adherence-tracking ecosystems that reshape payer contracting and site-of-care decisions.
For Market Incumbents: Secure specialty pharmacy network partnerships before hub-and-spoke distribution models consolidate maintenance therapy capture, particularly within Medicare Part B billing environments where site-of-care economics favor hospital-owned infusion centers. Invest in cardiovascular outcome trial positioning to reclassify uric acid lowering therapies from symptomatic management toward disease-modifying interventions, defending margin pools against generic allopurinol substitution through patent-protected dual-mechanism combinations. For New Entrants and Emerging Players: Remote patient monitoring integration for subcutaneous biologic administration represents a service-layer gap where incumbents under-serve refractory gout populations in Germany and France. Target biologic-naive patient pools in nephrology practices piloting dual-mechanism combinations at triple primary care rates. Pursue outcomes-based contracting with payers as the go-to-market angle, leveraging connected delivery devices for adherence tracking and real-world evidence generation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biologic developers with established cold-chain infrastructure and rare-disease regulatory expertise over oral small-molecule manufacturers facing generic compression. Long-term viability rests on cardiovascular outcome trial data reclassifying hyperuricemia therapies and expanding eligible prescribing pools beyond rheumatology into cardiology and nephrology. Watch for EMA biosimilar interchangeability standards accelerating pegloticase follow-on development timelines as the signal indicating platform consolidation versus fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Cardiovascular Outcome Trial Positioning | FDA guidance on chronic gout targets expands eligible prescribing pools across hospital systems. |
| Specialty Pharmacy Network Partnership | Hub-and-spoke models capture maintenance refills from retail channels in Japan and United States. |
| Remote Patient Monitoring Integration | Connected delivery devices enable adherence tracking and outcomes-based payer contracting. |
| Dual-Mechanism Combination Development | Nephrology practices pilot xanthine oxidase/uricosuric agents at triple primary care adoption rates. |
| Biosimilar Interchangeability Investment | EMA quality standards create regulatory tailwind for pegloticase follow-on developers. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital pharmacy procurement managers inform demand-side dynamics. Secondary validation draws from payer access specialist surveys, specialty pharmacy dispensing records, and nephrology practice prescribing pattern analyses. Bottom-up patient population modeling triangulates against top-down pharmaceutical revenue aggregation across the analysis window.
Segmentation dimensions modeled include treatment line, dosage form, administration route, and regional regulatory cluster. CAGRs derive from patient population growth, protocol expansion rates, and pricing trajectory assumptions throughout the forecast period. Forecast inputs incorporate cardiovascular comorbidity protocol adoption curves, biosimilar interchangeability implementation timelines, and specialty pharmacy channel migration velocity.
Forecasts assume regulatory continuity in FDA chronic gout guidance and EMA quality standards; material policy shifts in PMDA pharmacovigilance requirements or NMPA approval pathways would require re-modeling. Recalibration cycles align with material shifts in cardiovascular outcome trial readouts and biosimilar interchangeability determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Neuroscience Market
Specialty Medicine
Partial Onset Seizures Market
Specialty Medicine
Global Multiple Sclerosis Therapeutics Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market
Specialty Medicine
Global Focal Segmental Glomerulosclerosis Market
Specialty Medicine
Chronic Myelogenous Leukemia Treatment Market
Specialty Medicine
Cholangiocarcinoma (CCA) Therapeutics Market
Specialty Medicine
Asia Pacific Liver Cancer Market
Specialty Medicine
Meningitis Treatment Market
Specialty Medicine
Acute Lymphocytic-Lymphoblastic Leukemia (ALL) Therapeutics Market
Specialty Medicine
Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Thoracic Outlet Syndrome Market
Specialty Medicine
Cerebral Folate Deficiency Market
Specialty Medicine
Pleurisy Market
Specialty Medicine
Axial Spondyloarthritis Treatment Market
Specialty Medicine
Neurosyphilis Market