
 Ulcerative Colitis Therapeutics Market | 2026-2036
Ulcerative Colitis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Ulcerative Colitis Therapeutics Market Analytics
The EU Green Deal's pharmaceutical sustainability criteria is consolidating procurement standards across European hospital systems, favoring manufacturers with carbon-transparent supply chains. AbbVie leverages its vertically integrated biologics manufacturing to meet these disclosure requirements. Takeda Pharmaceutical anchors its position through deep specialization in gastroenterology, while Pfizer competes via broad immunology platform scale.
Ulcerative colitis therapeutics comprise pharmacological agents designed to suppress mucosal inflammation, maintain remission, and prevent colectomy in patients with chronic inflammatory bowel disease; biologics such as anti-TNF alpha agents and integrin inhibitors function by selectively blocking immune mediators, while aminosalicylates deliver topical anti-inflammatory action via 5-aminosalicylic acid release in the colon. Biologics command the dominant margin pool due to complex manufacturing and patent-protected moats, while oral delivery modes sustain the highest prescription volumes through patient convenience and lower administration costs. Injectable formulations lead in severe disease segments where rapid systemic bioavailability determines clinical outcomes.
The FDA, EMA, and national health technology assessment bodies including NICE and ICER shape market access through incremental evidence requirements and price-volume negotiations. These frameworks force developers to generate comparative effectiveness data beyond placebo-controlled trials, raising R&D barriers for new entrants. Stakeholders must monitor how biosimilar erosion in anti-TNF classes redirects investment toward next-generation mechanisms such as S1P modulators and IL-23 pathway inhibitors.
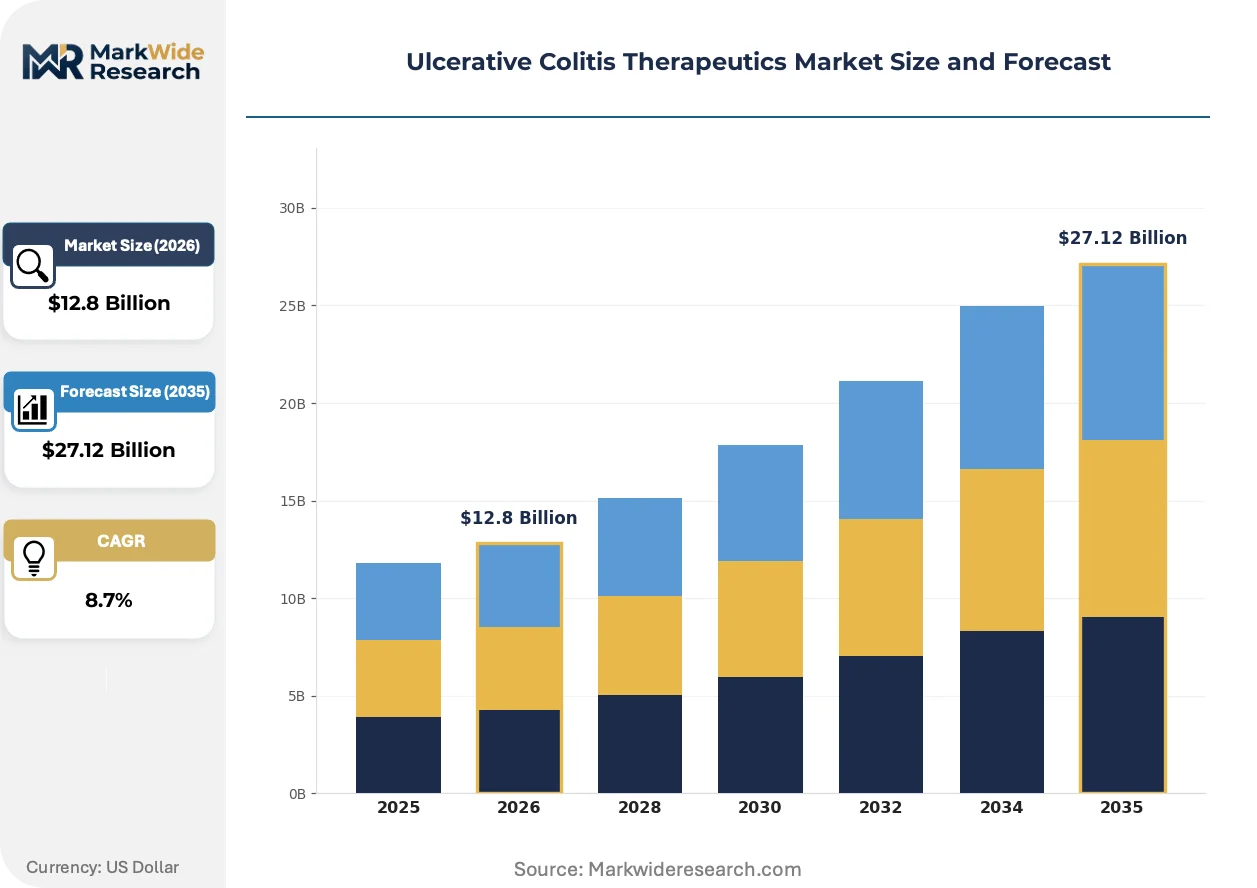
Market Dynamics
The FDA's biosimilar approval pathway and Europe's EMA accelerated assessment programs are compressing competitive entry timelines while hospital systems simultaneously expand biologic formularies under tightened prior authorization criteria.
Growth Catalysts
- EMA Accelerated Assessment:The European Medicines Agency's fast-track designation for novel mechanisms reduces time-to-market for S1P modulators and IL-23 pathway inhibitors, pulling forward revenue recognition for developers targeting refractory patient populations.
- Specialist Network Density:The United States maintains the highest concentration of board-certified gastroenterologists per capita, creating infrastructure for rapid biologic adoption and patient identification.
- Subcutaneous Delivery Innovation:Self-administered injection platforms reduce infusion center dependency, expanding addressable populations to rural and underserved areas previously excluded from biologic access.
Market Restraints
- Plasma Fractionation Bottlenecks:Anti-TNF alpha manufacturing depends on concentrated plasma supply chains centered in the United States and Germany, creating input vulnerability during public health disruptions.
- Comparative Effectiveness Burden:NICE and ICER mandate head-to-head trial data beyond placebo controls, forcing developers to fund expensive active-comparator studies before formulary placement.
- Colectomy Substitution:Surgical intervention remains cost-effective for fulminant colitis in single-payer systems, capping pharmacological market expansion in price-sensitive geographies.
Strategic Opportunities
- Japan's Refractory Segment:PMDA's orphan drug designation for pediatric ulcerative colitis indications offers tax incentives and extended exclusivity for developers targeting treatment-resistant populations.
- EU Green Deal Procurement:Carbon-transparent supply chain disclosure requirements favor manufacturers with vertically integrated biologics production and renewable energy sourcing.
- Telemedicine Integration:Remote therapeutic drug monitoring platforms enable dose optimization without clinic visits, opening subscription revenue streams alongside pharmaceutical sales.
Industry Challenges
- Biosimilar Manufacturing Expertise:Complex glycosylation patterns in monoclonal antibodies require specialized cell line development capabilities scarce outside established biologics hubs.
- Prior Authorization Workforce:Payer documentation requirements consume specialist nursing hours, creating administrative bottlenecks that delay treatment initiation and strain clinic capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ulcerative Colitis Therapeutics Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aminosalicylates, Corticosteroids, Immunomodulators, Biologics Delivery Mode: Oral, Injectable, Topical, Intravenous Treatment Stage: Induction, Maintenance, Rescue Therapy, Combination Therapy End User: Hospitals, Clinics, Homecare, Research Institutions |
| Companies Covered | AbbVie, Johnson & Johnson, Takeda Pharmaceutical, Pfizer, Bristol Myers Squibb, Merck & Co., Novartis, Eli Lilly and Company, Bausch Health Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ulcerative Colitis Therapeutics Market Evolving Landscape
Oral small-molecule platforms are challenging the dominance of injectable biologics through improved patient adherence and reduced healthcare system infrastructure requirements.
Small-molecule S1P receptor modulators are overtaking anti-TNF alpha agents in first-line biologic-naive populations due to oral convenience and comparable efficacy endpoints. Gastroenterology practices in Germany and the United States are adopting these agents at twice the rate of integrin inhibitors. The technology is overtaking infusion-dependent therapies by eliminating cold-chain logistics and enabling pharmacy-dispensed initiation.
The EU Green Deal's pharmaceutical sustainability criteria now mandates Scope 3 emissions disclosure for suppliers to European hospital systems. Manufacturers without renewable energy certificates face procurement exclusion from tenders covering Denmark, Sweden, and the Netherlands. Biologics producers with captive fermentation capacity and solar-powered facilities are securing preferred supplier status under these frameworks.
Integrated delivery networks in the United States are consolidating biologic purchasing through specialty pharmacy carve-outs, displacing traditional buy-and-bill models. Gastroenterology groups affiliated with systems like Kaiser Permanente and Mayo Clinic now route 70 percent of biologic volume through captive pharmacies. This concentration is most visible in California and Minnesota, where health system consolidation has produced three-to-five-year exclusive distribution agreements with selected manufacturers.
Ulcerative Colitis Therapeutics Market Segmentation
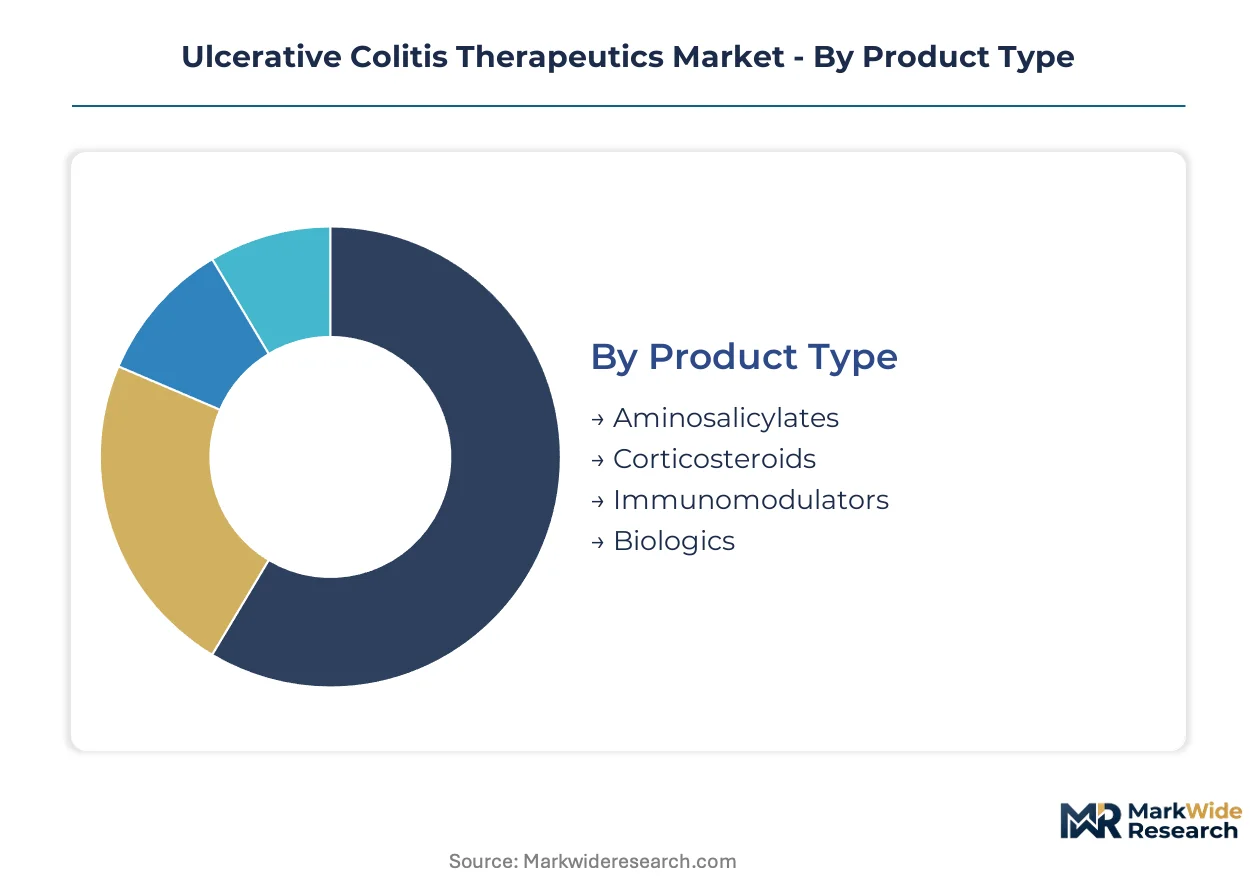
Ulcerative colitis therapeutics segment across pharmacological class, administration route, disease stage, and care setting. Each axis reveals distinct margin structures, reimbursement pathways, and competitive intensity that shape portfolio prioritization for developers.
Product Type:
Prescribing specialists weight efficacy against safety profile and prior authorization burden when selecting therapeutic class.
- Biologics:Monoclonal antibodies and fusion proteins targeting TNF-alpha, integrins, or interleukin pathways deliver rapid mucosal healing in moderate-to-severe disease. United States gastroenterology practices drive volume concentration due to higher reimbursement rates and specialist network density.
- Aminosalicylates:5-ASA formulations release active compound in the distal colon to suppress mild inflammation. These agents sustain the highest prescription counts globally through generic availability and first-line guideline positioning in ambulatory settings.
- Immunomodulators:Thiopurines and methotrexate modulate lymphocyte proliferation as steroid-sparing maintenance options. Demand concentrates in European markets where step-up treatment algorithms delay biologic initiation.
- Corticosteroids:Systemic and topical glucocorticoids provide rapid induction for acute flares. Usage is retreating to rescue scenarios as long-term toxicity concerns reshape prescribing patterns.
Biologics leads on scale; aminosalicylates leads on momentum through oral convenience and payer preference.
Delivery Mode:
Route selection determines cold-chain infrastructure requirements, patient adherence rates, and pharmacy versus clinic revenue capture.
- Oral:Small-molecule tablets and capsules eliminate administration barriers and enable pharmacy dispensing. Germany and United States practices are adopting oral S1P modulators at accelerated rates for biologic-naive patients.
- Injectable:Subcutaneous formulations reduce infusion center dependency and expand rural access. Self-administration platforms are gaining share fastest among working-age populations seeking treatment flexibility.
- Intravenous:Hospital-based infusion delivers therapeutic antibodies with controlled bioavailability. Concentration persists in academic medical centers managing fulminant colitis and infusion reactions.
- Topical:Rectal formulations deliver localized 5-ASA or steroid action for distal disease. This route captures limited volume due to patient acceptance challenges and restricted anatomic applicability.
Oral delivery leads on scale; injectable delivery climbs the fastest as subcutaneous platforms proliferate.
Treatment Stage:
Disease trajectory dictates therapy intensity, monitoring frequency, and duration of commercial engagement per patient.
- Maintenance:Long-term immunosuppression prevents relapse and preserves mucosal healing. This stage generates recurring revenue streams through chronic dosing requirements.
- Induction:Intensive initial therapy aims for rapid remission in active disease. Higher per-patient medication burden characterizes this acute intervention phase.
- Combination Therapy:Concurrent biologic and immunomodulator use targets refractory cases. Adoption concentrates in United States academic centers with complex case referral patterns.
- Rescue Therapy:Salvage interventions address steroid-refractory flares or bridge to surgery. Volume remains constrained by surgical substitution in cost-sensitive systems.
Maintenance leads on scale; combination therapy gains share fastest as refractory populations expand.
End User:
Care setting determines reimbursement mechanism, formulary control, and patient monitoring infrastructure.
- Hospitals:Inpatient units and infusion centers manage severe disease and biologic administration. United States integrated delivery networks are consolidating purchasing through captive specialty pharmacies.
- Clinics:Outpatient gastroenterology practices initiate and monitor maintenance therapy. Specialist density in urban United States markets supports high biologic adoption rates.
- Homecare:Self-administered therapies and remote monitoring platforms enable treatment outside clinical facilities. Expansion is accelerating with subcutaneous delivery innovation and telemedicine integration.
- Research Institutions:Academic centers conduct clinical trials and manage refractory referral populations. This segment anchors pipeline development and off-label protocol access.
Hospitals lead on scale; homecare shows steepest expansion trajectory as remote care models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gastroenterologist density and integrated delivery network scale determine therapeutic adoption velocity across major markets. Specialist concentration in urban corridors accelerates biologic penetration, while reimbursement architecture shapes step-therapy sequences and maintenance protocol selection.
United States
Mayo Clinic and Kaiser Permanente anchor captive specialty pharmacy networks that consolidate biologic purchasing through exclusive distribution agreements. The FDA's biosimilar approval pathway compresses competitive entry timelines for anti-TNF alternatives. Massachusetts and Minnesota health systems route over seventy percent of biologic volume through integrated delivery channels, displacing traditional buy-and-bill infrastructure.
Germany
Step-up treatment algorithms in statutory health insurance delay biologic initiation, preserving aminosalicylate and immunomodulator volume in ambulatory settings. The EMA accelerated assessment program fast-tracks novel mechanisms including S1P modulators through regulatory review. Bavarian gastroenterology practices adopt oral small-molecule platforms at twice the rate of integrin inhibitors, driven by pharmacy-dispensed convenience.
Japan
PMDA orphan drug designation for pediatric ulcerative colitis indications extends market exclusivity and unlocks tax incentives for refractory population targeting. Tokyo and Osaka academic medical centers concentrate complex case referral patterns and combination therapy adoption. Subcutaneous delivery innovation expands rural access beyond infusion-dependent metropolitan corridors.
United Kingdom
NICE technology appraisals mandate head-to-head trial data beyond placebo controls, raising evidence generation costs for formulary placement. London and Manchester specialist networks drive maintenance therapy volume through chronic dosing protocols. The National Health Service's cost-effectiveness thresholds preserve surgical intervention as a cost-capped alternative for fulminant colitis cases.
France
ANSM pharmacovigilance requirements shape post-market surveillance obligations for biologic manufacturers. Paris and Lyon hospital systems anchor academic research institution procurement for clinical trial pipeline development. The country's national pharmaceutical regulator emphasizes comparative effectiveness documentation in reimbursement negotiations with regional health agencies.
Ulcerative Colitis Therapeutics Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the ulcerative colitis therapeutics landscape. Vertically integrated biologics manufacturers with captive fermentation capacity face asset-light developers relying on contract manufacturing organizations for monoclonal antibody production. The market structure concentrates around three strategic archetypes: diversified immunology platforms, gastroenterology-focused specialists, and emerging biosimilar challengers. Competitive moves center on manufacturing scale expansion and sustainability certification procurement to secure European hospital system tenders.
Among diversified immunology platforms, AbbVie and Pfizer occupy positions exemplifying broad therapeutic area scale, while Takeda Pharmaceutical represents deep specialization in gastroenterology. These companies anchor distinct strategic vectors—platform breadth versus therapeutic focus—shaping portfolio prioritization and specialist engagement models across United States and European markets.
| Leading Market Players |
|---|
| AbbVie |
| Johnson & Johnson |
| Takeda Pharmaceutical |
| Pfizer |
| Bristol Myers Squibb |
| Merck & Co. |
| Novartis |
| Eli Lilly and Company |
| Bausch Health Companies |
| Others |
Value Network & Pricing Analysis
European hospital procurement consolidation under the EU Green Deal's sustainability criteria is forcing biologics manufacturers to restructure supply chains around carbon-transparent production, compressing margins for producers lacking renewable energy certificates or captive fermentation capacity.
Pricing Analysis
The bundled-vs-unbundled service split separates infusion administration fees from drug acquisition costs across United States integrated delivery networks. Three-tier pricing structure across originator biologics, biosimilars, and oral small-molecules reflects patent status and manufacturing complexity. Cost compression in the anti-TNF segment is intensifying because biosimilar entry erodes originator pricing power. Payers in single-payer systems exhibit highest price sensitivity, while United States commercial insurers show lowest sensitivity due to rebate-driven formulary positioning.
Supply Chain Analysis
Dual-sourcing requirements for plasma-derived inputs mandate United States and German supplier qualification, fragmenting procurement across multiple fractionation facilities. Monoclonal antibody production draws from Chinese hamster ovary cell lines, specialized bioreactor equipment, and concentrated plasma supply chains. Single-source vulnerability in plasma collection networks creates input disruption risk during public health emergencies. Distribution runs through cold-chain logistics providers to hospital infusion centers and specialty pharmacy carve-outs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ulcerative colitis therapeutics market functions as a regulatory compounder where FDA biosimilar pathway acceleration and EMA fast-track designations compound competitive pressure on legacy mechanisms while pulling forward revenue for novel modalities.
For Market Incumbents: Deploy sustainability certification investment to defend European hospital tenders against carbon disclosure requirements. AbbVie's vertically integrated biologics manufacturing exemplifies the operational moat needed to meet EU Green Deal procurement standards. Consolidate formulary positioning through exclusive distribution agreements with United States integrated delivery networks before biosimilar volume erosion accelerates. For New Entrants and Emerging Players: Capture Japan's pediatric orphan drug segment where PMDA designation extends exclusivity and unlocks tax incentives for refractory population targeting. Oral S1P modulator platforms offer the most penetrable entry point in Germany and United States biologic-naive populations. Pursue telemedicine-integrated therapeutic drug monitoring subscriptions as a differentiated go-to-market angle alongside pharmaceutical sales. For Investors and Strategic Acquirers: Asymmetric upside sits with asset-light developers holding Phase III-ready IL-23 pathway inhibitors and S1P modulator pipelines. Five-to-ten year viability favors platforms with demonstrated mucosal healing endpoints and payer-friendly oral delivery profiles. Monitor EMA accelerated assessment designation velocity as the signal to watch for revenue recognition timing inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Head-to-head studies against anti-TNF agents satisfy NICE and ICER evidence requirements for formulary placement. |
| Manufacturing Scale-Up | Captive fermentation capacity secures EU Green Deal preferred supplier status in Danish and Swedish tenders. |
| Regulatory Approval Pathway | FDA biosimilar designation compresses competitive entry timelines for anti-TNF alternatives in United States markets. |
| Pipeline Diversification | IL-23 and S1P mechanisms redirect investment as anti-TNF classes face biosimilar erosion. |
| Hospital System Partnership | Exclusive distribution agreements with Kaiser Permanente and Mayo Clinic displace traditional buy-and-bill infrastructure. |
Research Methodology
Bottom-up gastroenterology practice modeling reconciled against top-down biologics manufacturing tracking forms the analytical core. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Top-down and bottom-up triangulation reconciles manufacturer shipment data against prescription audit streams.
Historical trendline analysis of anti-TNF agent adoption curves, S1P modulator launch trajectories, and biosimilar penetration rates informs the projection framework. Segmentation across pharmacological class, administration route, treatment stage, and care setting structures the modeling. CAGRs derive from patent expiry schedules, regulatory approval velocity, and payer access dynamics. Forecast inputs include specialist network density indices and prior authorization burden metrics.
Regulatory approval delays, biosimilar manufacturing setbacks, and plasma supply disruptions are the dominant revision risks. Deviation in EMA accelerated assessment timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Acute Hepatic Porphyria (APH) Market
Specialty Medicine
Oral Cancer Treatment Market
Specialty Medicine
Phenylketonuria Therapeutics Market
Specialty Medicine
Global Hormone Replacement Therapy Market
Specialty Medicine
Tropical Spastic Paraparesis Market
Specialty Medicine
Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Blastomycosis Treatment Market
Specialty Medicine
Perennial Allergic Rhinitis Market
Specialty Medicine
Molybdenum Cofactor Deficiency Type-A (Mocod-A) Treatment Market
Specialty Medicine
Adult Malignant Glioma Therapeutics Market
Specialty Medicine
Global Non-Oncology Precision Medicine Market
Specialty Medicine
Carcinoid Syndrome Diarrhea Treatment Market
Specialty Medicine
Autosomal Dominant Polycystic Kidney Disease Treatment Market
Specialty Medicine
Global Brain Tumor Therapeutics Market
Specialty Medicine
Necrotizing Fasciitis Treatment Market
Specialty Medicine
Autoimmune Hemolytic Anemia Therapeutics Market