
 Nuclear Medicine Therapeutics Market | 2026-2036
Nuclear Medicine Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Medicine Therapeutics Market Analytics
Hospital procurement channels for radiopharmaceuticals is reconfiguring around centralized nuclear pharmacy networks and direct manufacturer partnerships. Novartis AG leverages its integrated theranostic platform to control supply chain endpoints from isotope production to patient dosing. Lantheus Holdings anchors the commercial radiopharmaceutical segment through its specialized manufacturing infrastructure and distribution scale. Bayer AG competes by extending its oncology portfolio into precision radioligand therapies with complementary diagnostic imaging agents.
Nuclear medicine therapeutics employ radioactive isotopes bound to tumor-targeting vectors, delivering cytotoxic radiation at cellular scale with dose ranges typically between 100 and 250 mCi per therapeutic cycle. These agents treat malignancies by DNA strand breakage and apoptosis induction while sparing adjacent healthy tissue through short path-length alpha or beta emissions. The therapy area dimension shows cancer applications dominating current revenue pools, while neurology applications represent an emerging growth frontier as tau and amyloid-targeting radiopharmaceuticals advance through clinical pipelines. Intravenous administration routes sustain the majority of therapeutic protocols, though intra-arterial delivery differentiates specialized liver and neuroendocrine tumor programs.
The FDA governs radiopharmaceutical manufacturing under current Good Manufacturing Practice and specific radioactive drug guidelines, while the Nuclear Regulatory Commission oversees clinical handling, disposal, and personnel certification requirements. EMA's centralized marketing authorization process for radiopharmaceuticals shapes European market access timelines and cross-border distribution feasibility. Stakeholders must monitor evolving reimbursement frameworks for radioligand therapy as health technology assessments increasingly determine patient access and commercial viability across major markets.
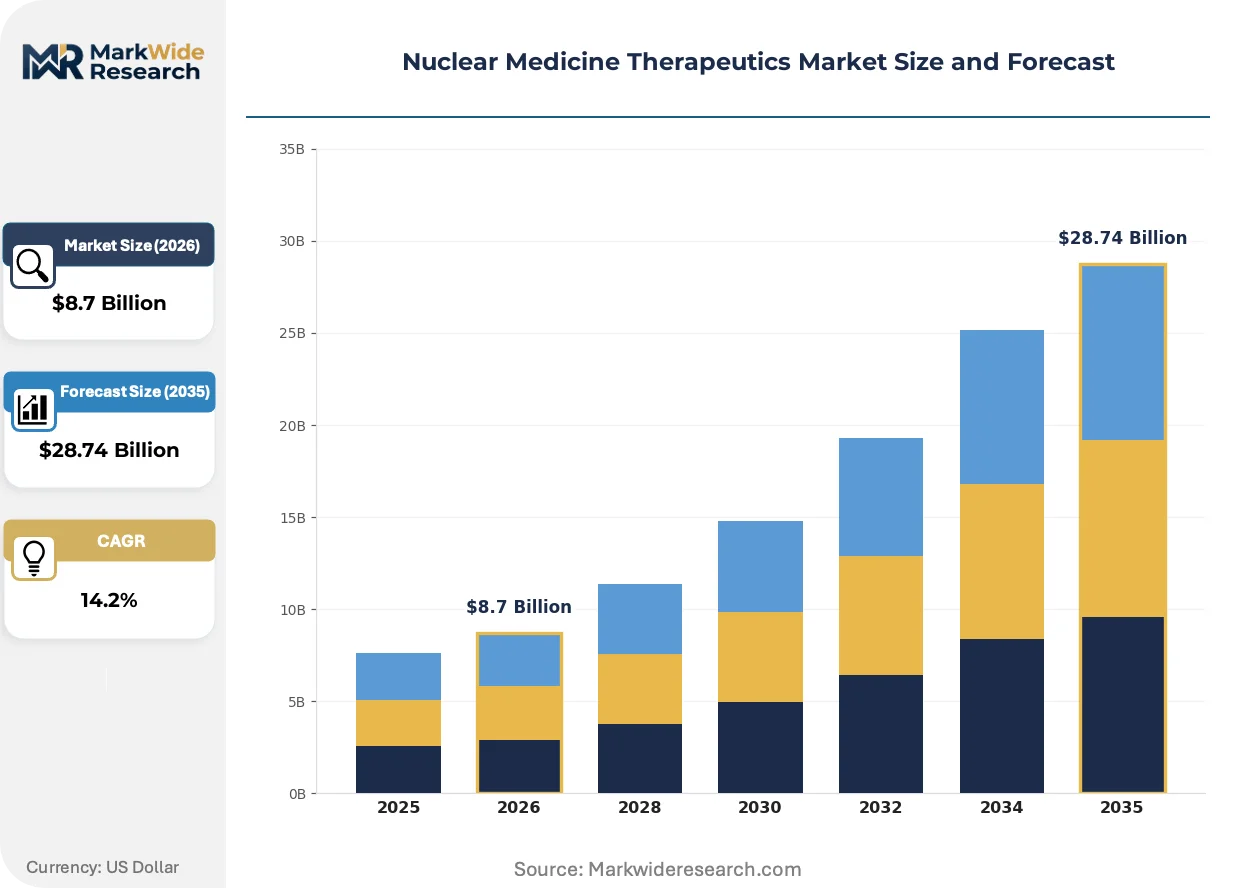
Market Dynamics
The nuclear medicine therapeutics sector is restructuring around isotope supply concentration, with reactor-dependent production creating chokepoints that favor manufacturers securing proprietary irradiation partnerships and cold-chain distribution networks.
Growth Catalysts
- Targeted Alpha Therapy Expansion:Clinical validation of actinium-225 and lead-212 conjugates is opening solid tumor indications beyond hematologic malignancies, drawing investment into radiochemistry infrastructure.
- Medicare Reimbursement Alignment:The United States has established favorable payment pathways for radioligand therapy, reducing financial barriers for hospital adoption and patient access.
- Theranostic Pairing Protocols:Diagnostic imaging agents matched to therapeutic isotopes are streamlining patient selection and treatment monitoring, improving clinical workflow efficiency.
Market Restraints
- Molybdenum-99 Supply Fragility:Ageing research reactors in Canada and Europe create single-point failure risks for technetium-99m generators, cascading into downstream therapeutic isotope availability.
- Radioactive Waste Liability:Long-lived isotope disposal imposes escalating cost burdens on treatment centers, particularly in jurisdictions with strict EPA or EMA environmental compliance mandates.
- Specialized Manufacturing Concentration:Contract manufacturing organizations with cGMP radiopharmaceutical capabilities cluster in the United States and Germany, limiting geographic diversification.
Strategic Opportunities
- Neurology Pipeline Advancement:Tau and amyloid-targeting radiopharmaceuticals for neurodegenerative disease represent an untapped therapeutic frontier with limited current competition.
- Distributed Production Models:Cyclotron-based isotope generation and on-site radiolabeling systems could reduce dependency on centralized reactor infrastructure.
- EMA Accelerated Assessment Pathway:European regulatory streamlining for orphan radiopharmaceuticals offers faster market entry for novel alpha-emitter therapies addressing rare cancers.
Industry Challenges
- Radiopharmaceutical Chemist Scarcity:The intersection of nuclear physics, organic chemistry, and regulatory science creates a shallow talent pool for manufacturing and quality control roles.
- Cold-Chain Integrity Complexity:Short half-life isotopes demand precise logistics coordination, with temperature excursions or transit delays rendering batches clinically unusable.
- Multi-Agency Compliance Burden:Manufacturers must simultaneously satisfy FDA cGMP, NRC handling protocols, and DOT transportation regulations, multiplying audit exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Medicine Therapeutics Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radioisotope, Radiopharmaceuticals, Brachytherapy Sources, Diagnostic Agents Therapy Area: Cancer, Cardiology, Neurology, Thyroid Disorders Administration Route: Intravenous, Oral, Intra-arterial, Subcutaneous End User: Hospitals, Diagnostic Centers, Research Laboratories, Oncology Clinics |
| Companies Covered | Novartis AG, Lantheus Holdings, Bayer AG, Telix Pharmaceuticals, Curium Pharma, Cardinal Health, GE HealthCare, Siemens Healthineers, Eckert & Ziegler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Medicine Therapeutics Market Evolving Landscape
Radioisotope production and clinical deployment are undergoing parallel transformation, with supply-side decentralization and demand-side precision dosing converging to reshape competitive economics.
Alpha-emitting radionuclides are migrating from experimental protocols into standard-of-care frameworks for metastatic castration-resistant prostate cancer and neuroendocrine tumors. Academic medical centers in the United States and Switzerland are establishing dedicated alpha therapy suites, compressing the timeline between clinical trial readouts and institutional adoption. This technology is migrating from boutique applications toward volume-scale treatment, forcing manufacturers to recalibrate production batch sizing and staffing models.
The FDA's streamlined radiopharmaceutical approval pathway is compressing development timelines for novel theranostic agents, reducing the historical gap between diagnostic and therapeutic authorization. This regulatory acceleration is enabling parallel commercialization of imaging and treatment isotopes from single manufacturing platforms. Oncology clinics are responding by consolidating radiopharmaceutical procurement under centralized nuclear pharmacy networks rather than maintaining in-house compounding capabilities.
Hospital procurement for radioligand therapy is consolidating around direct manufacturer partnerships and specialty distributor agreements, displacing traditional wholesale pharmaceutical channels. Academic medical centers and integrated delivery networks are negotiating multi-year supply contracts that bundle isotope allocation with technical training and waste management services. This channel restructuring is most pronounced in the United States, where Medicare reimbursement stability has enabled capital commitment to dedicated radiopharmaceutical infrastructure.
Nuclear Medicine Therapeutics Market Segmentation
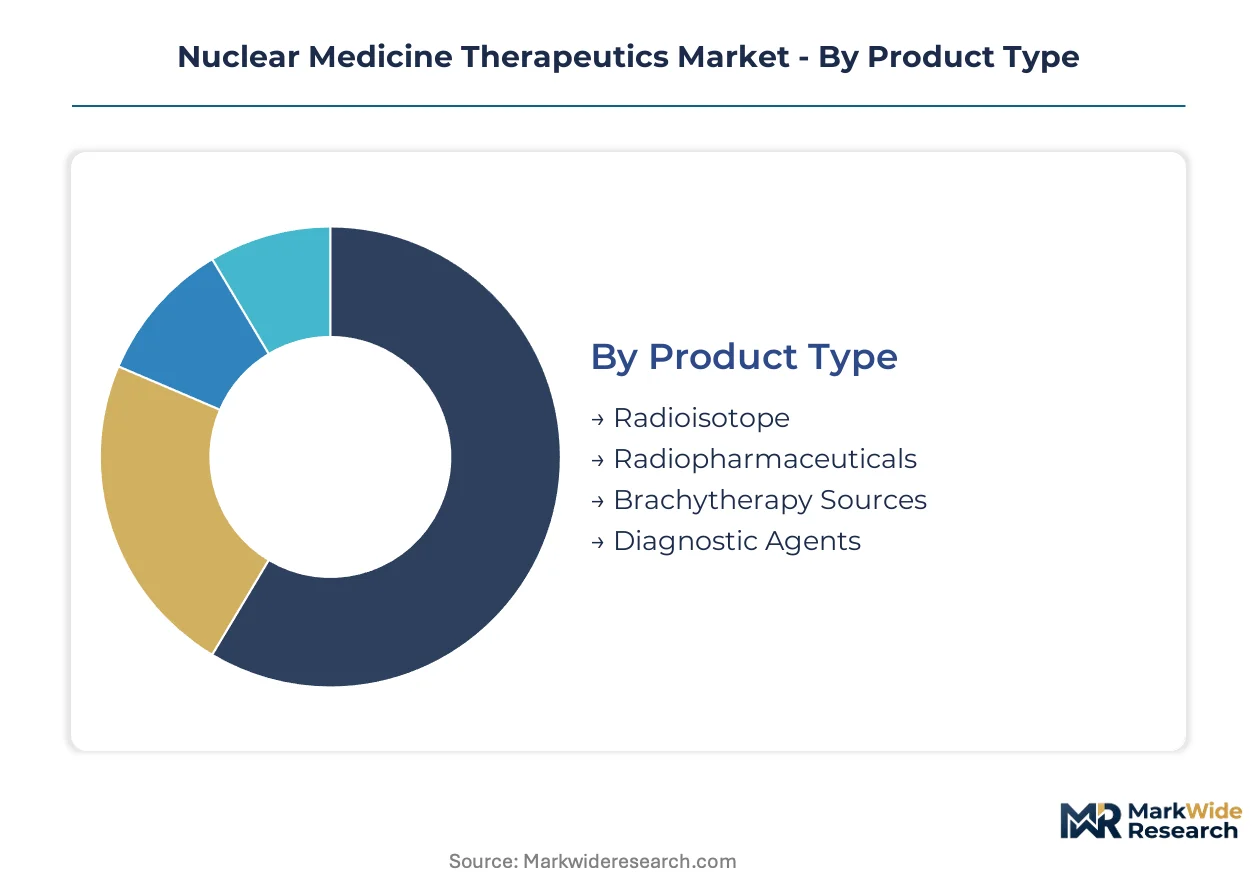
Segmentation in nuclear medicine therapeutics reveals how clinical workflows, isotope half-lives, and regulatory pathways fragment demand across incompatible supply chains. Each dimension—product chemistry, disease target, delivery method, and care setting—imposes distinct manufacturing, handling, and reimbursement requirements that reshape competitive boundaries.
Product Type:
Mature reactor-produced isotopes anchor current revenue pools while emerging accelerator-generated radionuclides redraw supply economics.
- Radiopharmaceuticals:Tumor-targeting vectors conjugated to therapeutic isotopes deliver cytotoxic radiation at cellular scale. Demand concentrates in United States oncology clinics where Medicare reimbursement pathways for radioligand therapy have reduced financial barriers to adoption.
- Radioisotope:Unbound radioactive materials serve as raw inputs for radiolabeling and industrial applications. Supply concentrates around reactor-dependent production in Canada and Europe, creating chokepoints that favor manufacturers securing proprietary irradiation partnerships.
- Brachytherapy Sources:Sealed radioactive implants deliver localized radiation for prostate and cervical malignancies.
- Diagnostic Agents:Imaging isotopes paired with therapeutic counterparts enable theranostic patient selection protocols.
Radiopharmaceuticals retain volume leadership; radioisotope supply innovations hold the steepest expansion curve.
Therapy Area:
Application breadth spans well-established oncologic protocols to neurology frontiers with divergent clinical evidence requirements.
- Cancer:Targeted alpha and beta emitters treat metastatic castration-resistant prostate cancer and neuroendocrine tumors through DNA strand breakage. United States academic medical centers are establishing dedicated alpha therapy suites, compressing timelines between trial readouts and institutional adoption.
- Neurology:Tau and amyloid-targeting radiopharmaceuticals for neurodegenerative disease represent an emerging therapeutic frontier. Switzerland and United States research centers lead clinical pipeline advancement for Alzheimer's and Parkinson's applications.
- Cardiology:Myocardial perfusion imaging dominates current use, with therapeutic applications limited to refractory angina.
- Thyroid Disorders:Iodine-131 remains the standard for hyperthyroidism and differentiated thyroid carcinoma ablation.
Cancer applications retain volume leadership; neurology holds the steepest expansion curve.
Administration Route:
Delivery method selection hinges on isotope pharmacokinetics, tumor vascularity, and radiation safety containment requirements.
- Intravenous:Systemic circulation enables broad biodistribution for hematologic and metastatic solid tumors. This route sustains the majority of therapeutic protocols across United States and European hospital networks, with standardized infusion protocols reducing training overhead.
- Intra-arterial:Regional delivery differentiates specialized liver and neuroendocrine tumor programs through first-pass extraction. Japan and Germany have pioneered catheter-based radiopharmaceutical administration for hepatocellular carcinoma with curative intent.
- Oral:Iodine-131 capsules for thyroid conditions represent the simplest delivery mechanism with minimal infrastructure requirements.
- Subcutaneous:Limited applications include lymphoscintigraphy and select peptide receptor radionuclide therapy protocols.
Intravenous delivery retains volume leadership; intra-arterial methods hold the steepest expansion curve.
End User:
Customer type determines procurement scale, technical sophistication, and waste management liability exposure.
- Hospitals:Integrated delivery networks negotiate multi-year supply contracts bundling isotope allocation with technical training and waste management. United States hospital procurement is consolidating around direct manufacturer partnerships, displacing traditional wholesale pharmaceutical channels.
- Oncology Clinics:Specialized cancer centers are expanding radiopharmaceutical therapy capacity as targeted alpha and beta emitters gain clinical traction. These facilities require dedicated hot labs and radiation safety officers, creating capital barriers that favor network consolidation.
- Diagnostic Centers:Imaging-focused facilities handle diagnostic agents with lighter regulatory burdens than therapeutic isotopes.
- Research Laboratories:Academic and commercial R&D sites drive pipeline innovation with small-batch cyclotron production.
Hospitals retain volume leadership; oncology clinics hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reimbursement premiums command pricing leverage over European markets where EMA centralized authorization compresses margin structures. German and Swiss manufacturers offset this gap through theranostic bundling and proprietary isotope partnerships.
United States
Medicare reimbursement stability for radioligand therapy has enabled capital commitment to dedicated alpha therapy suites at academic medical centers. FDA streamlined approval pathways compress development timelines for novel theranostic agents. Boston and Houston anchor concentrated procurement networks negotiating multi-year supply contracts with bundled waste management services.
Germany
Contract manufacturing organizations with cGMP radiopharmaceutical capabilities cluster in Baden-Württemberg and Bavaria, serving cross-border European demand. EMA centralized marketing authorization shapes market access timelines and distribution feasibility across member states. Heidelberg and Munich host specialized nuclear pharmacy networks supplying oncology clinics throughout Central Europe.
Switzerland
Swissmedic oversight of radioactive drug handling protocols aligns with stringent environmental compliance mandates for long-lived isotope disposal. Academic medical centers in Zurich and Geneva pioneered dedicated alpha therapy suites, compressing adoption timelines between clinical trial readouts and institutional implementation. Basel anchors integrated theranostic platform development bridging diagnostic imaging and therapeutic isotope production.
Japan
PMDA regulatory frameworks govern radiopharmaceutical manufacturing alongside METI coordination of reactor-dependent isotope supply chains. Intra-arterial delivery protocols for hepatocellular carcinoma have achieved curative-intent status through catheter-based administration programs. Tokyo and Osaka metropolitan areas concentrate specialized hot lab infrastructure for peptide receptor radionuclide therapy.
Canada
Ageing research reactor infrastructure at Chalk River creates supply vulnerability cascading into downstream therapeutic isotope availability for North American markets. Health Canada and CNSC joint oversight of radioactive drug manufacturing and clinical handling imposes multi-agency compliance burdens on treatment centers. Toronto and Montreal host centralized nuclear pharmacy networks reconfiguring hospital procurement channels around direct manufacturer partnerships.
Nuclear Medicine Therapeutics Market Competitive Landscape
Integrated theranostic platforms and specialized radiopharmaceutical manufacturers split the market between end-to-end supply chain control and focused production scale. The vendor base concentrates around isotope supply partnerships and cold-chain distribution capabilities rather than broad pharmaceutical portfolios. Three archetypes dominate: diversified healthcare conglomerates with captive isotope infrastructure, pure-play radiopharmaceutical specialists, and diagnostic imaging equipment manufacturers extending into therapeutic agents. Competitive moves center on proprietary irradiation partnerships securing reactor access and multi-year hospital supply contracts bundling technical training with waste management liability transfer.
Within the integrated platform tier, Novartis AG and Bayer AG exemplify archetypes controlling supply chain endpoints from isotope production through patient dosing. Lantheus Holdings occupies a position among specialized manufacturers leveraging dedicated radiopharmaceutical infrastructure and distribution scale. These three entities represent contrasting strategic postures: conglomerate-backed vertical integration versus focused commercial radiopharmaceutical execution.
| Leading Market Players |
|---|
| Novartis AG |
| Lantheus Holdings |
| Bayer AG |
| Telix Pharmaceuticals |
| Curium Pharma |
| Cardinal Health |
| GE HealthCare |
| Siemens Healthineers |
| Eckert & Ziegler |
| Others |
Value Network & Pricing Analysis
Reactor utilization rates at Canadian and European facilities sit below optimal thresholds, forcing isotope suppliers to ration allocation through priority contracts while inflating spot-market premiums for uncontracted buyers. This capacity squeeze tightens manufacturer margins and accelerates hospital procurement consolidation around multi-year supply agreements.
Pricing Analysis
The customization-premium spread between patient-specific radiopharmaceutical dosing and standard isotope vials runs wide, with configured-to-order alpha-emitter conjugates commanding substantial premiums over bulk lutetium-177. Pricing stratifies across premium, standard, and economy tiers based on isotope half-life precision and cGMP certification grade. Cost compression in the standard tier is intensifying because reactor-dependent molybdenum-99 supply fragility pushes buyers toward guaranteed allocation contracts. Oncology clinics exhibit highest price sensitivity due to Medicare reimbursement caps, while academic medical centers with research funding show lowest sensitivity for experimental protocols.
Supply Chain Analysis
Contract manufacturing concentration rests with specialized radiopharmaceutical CMOs clustered in the United States and Germany, with Eckert & Ziegler and Curium Pharma anchoring European capacity. Geographic supply concentration centers on Canada for reactor-produced molybdenum-99, the United States for cyclotron-generated isotopes, and Germany for radiolabeling infrastructure. Raw material dependencies draw from enriched uranium targets, specialized chelating agents, and tumor-targeting peptide vectors. Single-source vulnerability pervades the reactor network, where ageing Chalk River infrastructure creates cascading failure risks. Distribution runs through centralized nuclear pharmacy networks that coordinate cold-chain logistics directly to hospital hot labs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market faces substitution pressure from external beam radiation therapy and CAR-T cell therapies that compete for metastatic cancer treatment share. Incumbents must defend radioligand therapy's precision-dosing advantage against these alternatives while securing isotope supply continuity.
For Market Incumbents: Insulate market position through captive supply of actinium-225 and lead-212 via proprietary irradiation partnerships at research reactors. Deepen backward integration into isotope production to offset molybdenum-99 supply fragility. Lock hospital networks into multi-year contracts bundling technical training, waste management liability transfer, and guaranteed allocation during supply crunches. For New Entrants and Emerging Players: Pursue neurology applications as the most penetrable frontier, where tau and amyloid-targeting radiopharmaceuticals face limited incumbent competition. Target Switzerland and United States academic medical centers for pilot commercialization of neurodegenerative disease therapies. Lead with theranostic pairing protocols that streamline patient selection and demonstrate clinical workflow efficiency to hospital procurement committees. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across alpha-emitter manufacturing infrastructure due to specialized hot lab requirements and radiation safety compliance burdens. Long-term viability favors platforms combining diagnostic imaging and therapeutic isotope production under unified regulatory pathways. Acquisition target archetype: pure-play radiopharmaceutical specialists with cyclotron-based isotope generation capabilities. The signal to watch is FDA approval velocity for novel theranostic agents as an indicator of platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Irradiation Partnership | Secures reactor access for actinium-225 production, locking out competitors from critical isotope supply. |
| Theranostic Platform Integration | Matches diagnostic imaging agents to therapeutic isotopes, streamlining FDA approval pathways for paired agents. |
| Multi-Year Hospital Supply Contract | Bundles isotope allocation with waste management services, transferring liability and cementing procurement relationships. |
| Alpha Therapy Suite Deployment | Establishes dedicated treatment infrastructure at academic medical centers, compressing adoption timelines. |
| Cyclotron-Based Isotope Generation | Reduces dependency on centralized reactor infrastructure through distributed production models. |
Research Methodology
A standing panel of nuclear medicine department heads, radiopharmaceutical manufacturing executives, and hospital procurement managers provided ongoing calibration across the study period. This primary fieldwork combined with secondary validation from FDA filings, EMA centralized marketing authorization records, ClinicalTrials.gov radiopharmaceutical protocols, and CMS Medicare reimbursement databases. Bottom-up and top-down triangulation reconciled manufacturer shipment data with hospital adoption surveys.
Scenario-bracketing framed the analytical approach across the analysis window, with base, optimistic, and conservative cases reflecting isotope supply stability assumptions. Segmentation dimensions modeled included therapy area, isotope type, administration route, and regional regulatory cluster. CAGRs derived from weighted average of historical growth patterns and forward-looking reimbursement trajectory assessments. Industry-specific forecast inputs incorporated reactor decommissioning schedules and FDA approval pipeline velocity.
Sensitivities concentrate around molybdenum-99 supply disruptions, Medicare reimbursement rate revisions, and EMA accelerated assessment pathway adoption rates. Forecasts reflect documented assumptions regarding isotope production capacity expansion and theranostic protocol standardization. Quarterly review of FDA radiopharmaceutical approval decisions and reactor maintenance outage announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Barlow's Syndrome Market
Specialty Medicine
Ischemic Hepatitis Treatment Market
Specialty Medicine
Anophthalmia and Microphthalmia Market
Specialty Medicine
Overt Hepatic Encephalopathy Market
Specialty Medicine
Toxoplasmosis Treatment Market
Specialty Medicine
Prostate Cancer Therapeutics Market
Specialty Medicine
Malignant Pleural Effusion Market
Specialty Medicine
Paediatric Sports Medicine Market
Specialty Medicine
Cerebral Folate Deficiency Market
Specialty Medicine
Liver Cirrhosis Treatment Market
Specialty Medicine
Global Constipation Treatment Market
Specialty Medicine
Ulcerative Colitis Market
Specialty Medicine
Dry Eye Disease Market
Specialty Medicine
Scleritis Market
Specialty Medicine
Acute Myeloid Leukemia Therapeutics Market