
 Dry Eye Syndrome Market | 2026-2036
Dry Eye Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Eye Syndrome Market Intelligence
The direct-to-consumer channel for over-the-counter artificial tears is narrowing as prescription-based therapies gain prominence. Novartis AG leverages its extensive R&D pipeline to develop novel treatments for Meibomian Gland Dysfunction. Alcon Inc. sustains a strong market presence through its broad portfolio of lubricating ointments and contact lens solutions. Santen Pharmaceutical Co., Ltd. specializes in ophthalmic pharmaceuticals, focusing heavily on markets in Japan and China.
Dry eye syndrome is a multifactorial disease of the ocular surface characterized by a loss of homeostasis of the tear film. It is often accompanied by ocular symptoms, in which tear film instability and hyperosmolarity are key etiological factors. Anti-inflammatory drugs constitute a high-margin product category, contrasting with the high-volume, mature market for artificial tears. Within therapy areas, treatments for Evaporative Dry Eye, often linked to Meibomian Gland Dysfunction, command the largest share of clinical focus.
Market access for novel therapies is governed by stringent clinical trial and approval protocols set by the US FDA and the European Medicines Agency (EMA). In Japan, the Pharmaceuticals and Medical Devices Agency (PMDA) establishes specific guidelines for ophthalmic drug development. Stakeholders must navigate evolving reimbursement landscapes and the shift towards outcome-based evidence to secure formulary placement.
Market Dynamics
The market's central tension arises from the bifurcation between the high-volume, mature segment of artificial tears and the high-margin, R&D-intensive category of prescription anti-inflammatory therapies. This dynamic shapes investment, clinical development priorities, and market access strategies globally.
Growth Catalysts
- Aging Demographics:The rising prevalence of dry eye syndrome in aging populations, particularly in developed nations like Japan, provides a sustained, demographically driven expansion of the patient base requiring chronic management.
- Digital Device Proliferation:Increased screen time among office workers and consumers globally is accelerating the incidence of digital eye strain and associated evaporative dry eye symptoms, broadening the addressable market beyond traditional patient profiles.
- Diagnostic Advancements:The development and adoption of more precise diagnostic tools for assessing tear film osmolarity and meibomian gland function are improving the accuracy of diagnosis, leading to earlier and more targeted therapeutic intervention.
Market Restraints
- Stringent Regulatory Pathways:The rigorous clinical trial and approval protocols mandated by the US FDA, European Medicines Agency (EMA), and Japan's PMDA create high barriers to entry and extend development timelines for novel therapies.
- Generic and OTC Competition:The widespread availability of low-cost over-the-counter artificial tears creates significant pricing pressure and can act as a substitute, limiting the initial uptake of premium-priced prescription drugs for mild-to-moderate cases.
- Reimbursement Hurdles:Securing favorable formulary placement and reimbursement from public and private payers requires extensive evidence of clinical and economic value, a significant challenge for new therapies with high acquisition costs.
Strategic Opportunities
- Meibomian Gland Dysfunction (MGD) Therapies:A substantial opportunity exists in developing and commercializing novel treatments specifically targeting MGD, the leading cause of evaporative dry eye, which remains an area of significant unmet clinical need.
- Telehealth Integration:Integrating diagnostic and prescription management into telehealth platforms offers a new channel to reach patients, improve adherence, and streamline care pathways, particularly in geographically dispersed or underserved areas.
- Novel Drug Delivery Systems:Development of sustained-release formulations, drug-eluting contact lenses, and less-frequent dosing regimens represents a key opportunity to improve patient compliance and differentiate products in a crowded therapeutic landscape.
Industry Challenges
- Complex Clinical Trial Endpoints:The multifactorial nature of the disease makes it difficult to design clinical trials with endpoints that consistently satisfy regulators, leading to high failure rates and increased development costs for drug candidates.
- Patient Adherence and Education:Ensuring long-term patient compliance with prescribed treatment regimens is a persistent operational challenge, hindering therapeutic effectiveness and impacting real-world outcomes for chronic forms of the disease.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Eye Syndrome Market |
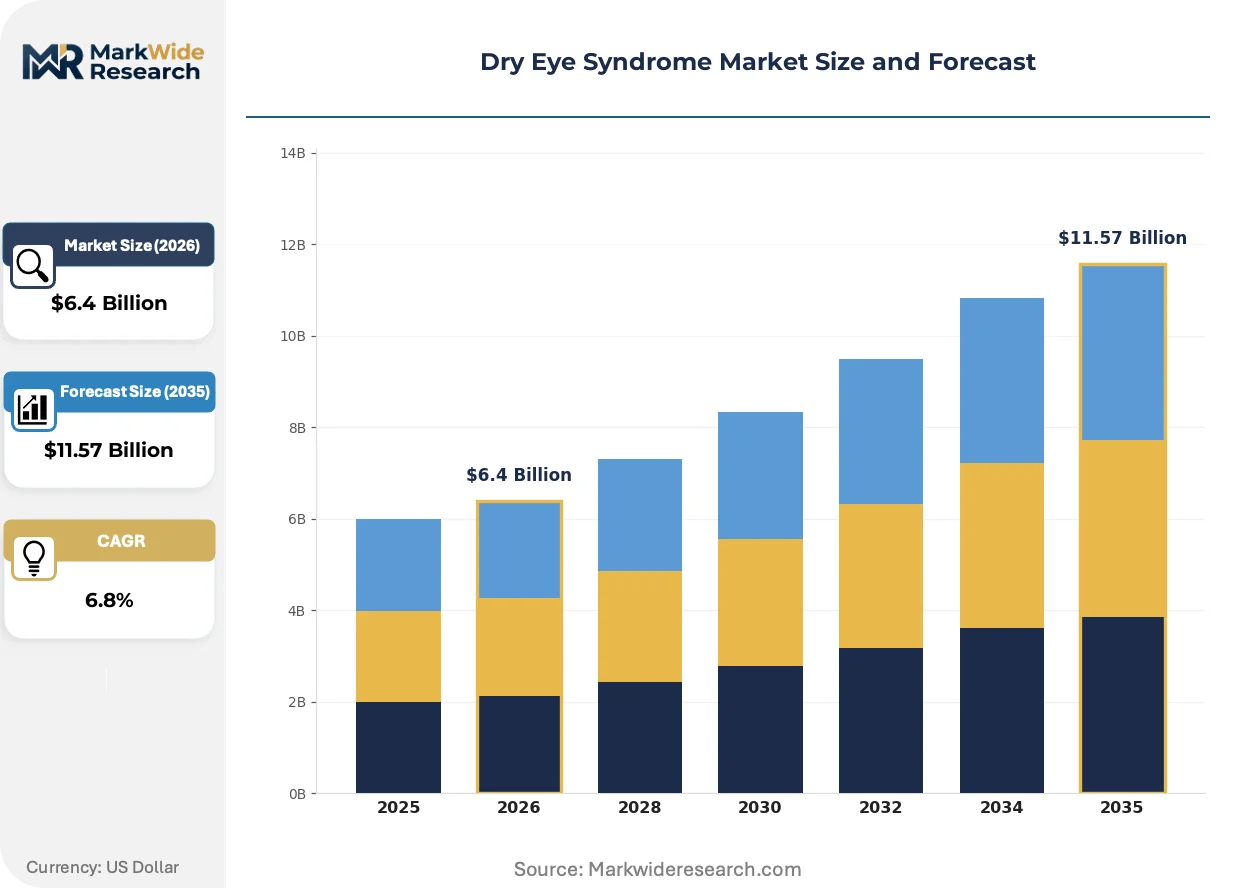
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $11.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artificial Tears, Anti-inflammatory Drugs, Lubricating Ointments, Tear Stimulants, Contact Lens Solutions Therapy Area: Evaporative Dry Eye, Aqueous Deficient Dry Eye, Mixed Type, Meibomian Gland Dysfunction End User: Ophthalmology Clinics, Specialty Eye Hospitals, Ambulatory Surgery Centers, Optometry Practices Application: Post-surgical Care, Chronic Condition Management, Contact Lens Wearers, Digital Eye Strain Relief, Environmental Protection |
| Companies Covered | AbbVie Inc., Alcon Inc., Santen Pharmaceutical Co., Ltd., Novartis AG, Bausch Health Companies Inc., Johnson & Johnson Vision Care, Inc., Sun Pharmaceutical Industries Ltd., Otsuka Pharmaceutical Co., Ltd., OASIS Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Eye Syndrome Market Strategic Shifts & Innovations
The convergence of advanced biologics, digital health platforms, and a deeper understanding of the disease's underlying inflammatory pathways is transforming treatment paradigms. This evolution moves the market away from palliative symptom relief toward targeted, disease-modifying interventions.
Novel drug delivery systems provide sustained therapeutic effects with reduced dosing frequency. These technologies, including punctal plugs that release medication over time, are gaining traction among patients with chronic dry eye who struggle with the adherence required for multiple daily eye drop applications. This technology is hybridizing pharmaceutical treatment with medical device functionality, creating combination products that offer both convenience and improved clinical efficacy.
Regulatory agencies are adapting their requirements to accommodate the complexity of dry eye disease. The FDA and EMA are increasingly encouraging the use of patient-reported outcomes (PROs) as co-primary or key secondary endpoints in clinical trials. This policy shift compels manufacturers to demonstrate not just improvements in clinical signs but also meaningful relief of symptoms, directly affecting trial design for anti-inflammatory and MGD-focused therapies.
Patient behavior is shifting toward a more proactive and digitally engaged approach to managing their condition. The use of smartphone apps for tracking symptoms, setting reminders for eye drop application, and accessing educational content is becoming more common. This trend is most visible in North America and Europe, where it empowers patients and provides pharmaceutical companies with valuable real-world data on treatment adherence and effectiveness.
Dry Eye Syndrome Market Segmentation
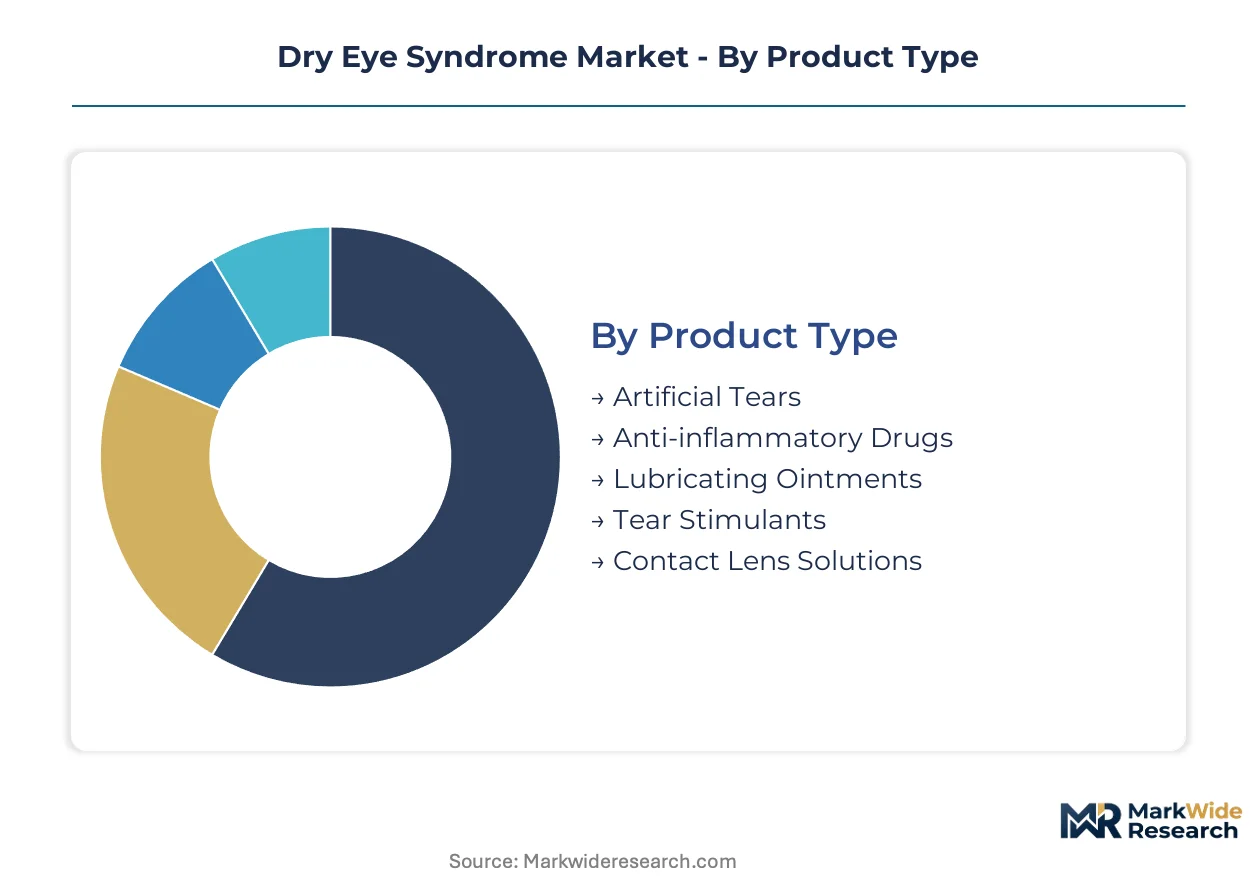
The Dry Eye Syndrome market is segmented across various dimensions, reflecting the diverse etiologies, treatment modalities, and patient needs associated with this multifactorial ocular surface disease. Understanding these segments helps stakeholders tailor product development, market access strategies, and clinical interventions for optimal patient outcomes.
Product Type:
The market for dry eye syndrome therapies spans a broad use-case spectrum, from palliative relief to targeted disease modification, influencing product development and patient management strategies.
- Artificial Tears:These over-the-counter lubricating drops replenish the tear film, providing temporary relief from dryness and irritation. Demand for these high-volume products is concentrating among digital eye strain sufferers in North America.
- Anti-inflammatory Drugs:Prescription medications like cyclosporine and lifitegrast reduce ocular surface inflammation, addressing a core pathological mechanism of dry eye. This high-margin category sees significant demand in chronic condition management, particularly within Japan's aging demographic.
- Lubricating Ointments:Thicker, petrolatum-based formulations offer extended ocular lubrication, often used at night for severe dry eye symptoms.
- Tear Stimulants:These prescription drugs, such as diquafosol and rebamipide, promote natural tear production and mucin secretion from the ocular surface.
- Contact Lens Solutions:Specialized solutions are formulated to enhance comfort and hydration for individuals wearing contact lenses, reducing lens-induced dryness.
Established volume favors Artificial Tears; emerging adoption favors Anti-inflammatory Drugs.
Therapy Area:
Clinical approaches to dry eye syndrome are differentiated by the underlying pathophysiology, guiding targeted therapeutic interventions and diagnostic priorities.
- Evaporative Dry Eye:This type results from excessive tear evaporation, often linked to meibomian gland dysfunction and environmental factors. Treatments for this category command the largest share of clinical focus, particularly for MGD.
- Aqueous Deficient Dry Eye:Characterized by insufficient tear production from the lacrimal glands, this form is frequently associated with autoimmune conditions like Sjögren's syndrome. Management often involves tear stimulants and anti-inflammatory agents.
- Mixed Type:Many patients present with characteristics of both evaporative and aqueous deficient dry eye, requiring a combined therapeutic approach.
- Meibomian Gland Dysfunction:This specific condition, a primary cause of evaporative dry eye, involves blockages or abnormalities of the meibomian glands along the eyelid margin.
Treatments for Evaporative Dry Eye command the largest clinical focus, while interventions for Aqueous Deficient Dry Eye are gaining specialized attention.
End User:
The delivery of dry eye care involves a diverse ecosystem of healthcare providers, each serving distinct patient needs and clinical complexities.
- Ophthalmology Clinics:These specialized facilities provide comprehensive eye care, including advanced diagnostics and prescription-based treatments for dry eye syndrome. They manage a significant portion of moderate to severe cases.
- Specialty Eye Hospitals:Offering tertiary care, these hospitals handle complex dry eye cases, often involving surgical interventions or co-morbid ocular conditions. They are crucial for advanced disease management.
- Ambulatory Surgery Centers:These outpatient facilities perform minor ophthalmic procedures, including some interventions for meibomian gland dysfunction.
- Optometry Practices:Primary eye care providers diagnose and manage mild to moderate dry eye, often recommending over-the-counter solutions and initial prescription therapies.
Ophthalmology Clinics manage the highest acuity cases, with Specialty Eye Hospitals handling more complex surgical requirements.
Application:
Patient needs drive the diverse applications of dry eye treatments, addressing specific triggers and long-term management requirements.
- Post-surgical Care:Managing ocular surface health following various eye surgeries, such as LASIK or cataract removal, often involves dry eye treatments. This application sees demand from refractive surgery patients.
- Chronic Condition Management:This application focuses on long-term treatment regimens for persistent dry eye symptoms, crucial for patient populations with ongoing disease. Aging populations in Europe represent a significant patient base.
- Contact Lens Wearers:Products and therapies are specifically designed to alleviate dryness and discomfort experienced by individuals using contact lenses.
- Digital Eye Strain Relief:Addressing symptoms like dryness and irritation caused by prolonged exposure to digital screens, this application targets office workers and heavy screen users.
- Environmental Protection:Treatments and protective measures are utilized to shield eyes from environmental irritants such as wind, dust, and low humidity.
Chronic Condition Management represents the largest patient base, while Digital Eye Strain Relief shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dry Eye Syndrome market demonstrates a pricing-power asymmetry, with premium prescription therapies commanding higher value in developed markets like Japan, while high-volume artificial tears dominate in emerging economies. This dynamic influences investment in novel drug development and market access strategies across diverse healthcare systems. Local regulatory frameworks significantly impact product availability and reimbursement across different regions.
United States
Demand for advanced anti-inflammatory therapies is strong in the United States, driven by a high prevalence of chronic dry eye and significant healthcare expenditure. The US FDA's stringent approval processes shape the clinical development pipeline for novel treatments. Major ophthalmic research clusters in Boston and Research Triangle Park actively drive innovation in ocular surface disease management.
Japan
Japan exhibits a high and growing demand for dry eye treatments, fueled by its rapidly aging demographic and high rates of the condition. The Pharmaceuticals and Medical Devices Agency (PMDA) establishes specific guidelines for ophthalmic drug development and market entry. Pharmaceutical companies in Tokyo and Osaka focus heavily on specialized ophthalmic formulations and MGD therapies.
Germany
Germany's dry eye market benefits from a robust healthcare system and a strong emphasis on evidence-based medicine for chronic conditions. The European Medicines Agency (EMA) oversees drug approvals, influencing market access for new therapeutic agents. Research institutions in Berlin and Munich contribute to advancements in diagnostic tools and personalized treatment approaches.
China
China's market for dry eye therapies is expanding rapidly, driven by increased digital device usage and a large, aging population. The National Medical Products Administration (NMPA) regulates the approval and marketing of both over-the-counter and prescription ophthalmic drugs. Major pharmaceutical hubs in Shanghai and Beijing are seeing increased investment in local R&D and manufacturing capabilities.
India
India presents a substantial volume market for artificial tears and generic ophthalmic products, with rising awareness of ocular health issues. The Central Drugs Standard Control Organization (CDSCO) regulates drug approvals, focusing on affordability and accessibility. Pharmaceutical manufacturing clusters in Hyderabad and Ahmedabad are key centers for producing a wide range of dry eye medications.
Dry Eye Syndrome Market Key Industry Players
Specialized ophthalmic pharmaceutical companies and diversified healthcare conglomerates split the Dry Eye Syndrome market. The market structure exhibits a tiered approach, with a few large players dominating the prescription segment and numerous smaller entities competing in the over-the-counter space. Strategic partnerships for R&D and geographic expansion are common competitive moves among market participants.
Diversified healthcare companies like Novartis AG and Alcon Inc. exemplify the broad-portfolio archetype, leveraging extensive R&D pipelines and established distribution networks across multiple ophthalmic segments. Santen Pharmaceutical Co., Ltd., a Japan-based company, represents a specialist archetype, focusing heavily on ophthalmic pharmaceuticals and commanding a strong presence in specific Asian markets. These entities anchor different segments of the market, from high-margin prescription drugs to widely available lubricating solutions.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Alcon Inc. |
| Santen Pharmaceutical Co., Ltd. |
| Novartis AG |
| Bausch Health Companies Inc. |
| Johnson & Johnson Vision Care, Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Otsuka Pharmaceutical Co., Ltd. |
| OASIS Medical |
| Others |
Cost & Logistics Intelligence
Specialized cold chain logistics corridors, essential for transporting advanced biologics, directly influence supply concentration and downstream price differentiation across the Dry Eye Syndrome market. These specialized routes add significant cost, impacting the final pricing of premium prescription therapies compared to high-volume over-the-counter products. The intricate global pharmaceutical supply chain for ophthalmic products shapes regional market access and cost structures.
Pricing Analysis
Value-based premium pricing for novel anti-inflammatory therapies contrasts sharply with the high-volume, transactional pricing of artificial tears. Clinical efficacy and regulatory approval in key markets like the United States and Japan drive significant price differentiation for prescription drugs. Pricing pressure stems from the widespread availability of generic cyclosporine and low-cost artificial tears in emerging economies. Patients with chronic conditions demonstrate lower price sensitivity for effective prescription treatments, while digital eye strain sufferers prioritize affordability in artificial tears.
Supply Chain Analysis
Specialized pharmaceutical contract manufacturers in regions like Europe and the United States hold significant capacity for complex ophthalmic drug production. The supply chain sources active pharmaceutical ingredients (APIs) primarily from India and China, alongside specialized sterile packaging components. Single-source API vulnerability represents a structural supply chain risk for several key therapies. Distribution runs through established pharmaceutical wholesalers and direct-to-pharmacy channels in developed markets, while local distributors dominate in India and China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Dry Eye Syndrome market presents a significant opportunity for innovation, particularly given the persistent skill gap in developing targeted therapies for complex conditions like Meibomian Gland Dysfunction. Bridging this gap requires focused R&D investment and specialized expertise in ocular surface biology.
For Market Incumbents:Insulate core prescription franchises by diversifying R&D pipelines into novel biologics and gene therapies for MGD, countering the threat of generic erosion. Pursue strategic acquisitions of specialized biotech firms with promising Phase II/III assets to consolidate market share. Leverage existing distribution networks and ophthalmology clinic relationships to reinforce market access for new product launches. Invest in patient adherence programs to maximize the real-world effectiveness of chronic treatments.
For New Entrants and Emerging Players:Build out telehealth platforms for remote diagnosis and prescription management, particularly targeting underserved rural populations or busy urban professionals experiencing digital eye strain. Target the evaporative dry eye segment with novel drug delivery systems that improve patient compliance and reduce dosing frequency. A patient-centric digital engagement strategy, offering educational content and symptom tracking, can differentiate offerings in a crowded market. Focus on niche therapeutic areas with high unmet needs, such as autoimmune-related dry eye.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors specialized biotech firms with validated platforms for ocular surface inflammation or meibomian gland regeneration. The market demonstrates long-term viability over the next 5-10 years, driven by aging demographics and increased screen time. Acquisition targets should possess strong intellectual property and a clear regulatory pathway for novel anti-inflammatory or MGD therapies. Successful Phase III trial readouts for disease-modifying agents represent a critical signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates the development of novel anti-inflammatory biologics for chronic dry eye conditions. |
| Regulatory Approval Pathway Optimization | Streamlines market entry for new therapies, particularly with US FDA and European Medicines Agency. |
| Licensing Agreements for MGD Therapies | Expands product portfolios by accessing innovative treatments for Meibomian Gland Dysfunction. |
| Manufacturing Scale-Up for Biologics | Ensures sufficient supply of complex, high-value ophthalmic drugs for global demand. |
| Digital Health Platform Integration | Improves patient adherence and provides real-world data on treatment effectiveness for pharmaceutical companies. |
Research Approach
A standing panel of ophthalmologists, optometrists, pharmaceutical R&D leads, and regulatory affairs specialists provided ongoing calibration for market sizing and forecast assumptions. This primary research, conducted through in-depth interviews, was rigorously validated against extensive secondary data sources. Secondary data included FDA filings, EMA submissions, clinical trial registries, and company annual reports, ensuring comprehensive market understanding through bottom-up and top-down triangulation.
Scenario-bracketing around plausible market conditions informed the forecast framework across the analysis window, integrating various growth trajectories. The analytical framework modeled market dynamics across product type, therapy area, end user, application, and regional regulatory clusters. Compound annual growth rates were derived from historical data analysis and projected future trends, with demographic shifts and digital device adoption rates serving as key industry-specific forecast inputs.
Sensitivities concentrate around unforeseen regulatory changes and disruptive therapeutic innovations that could alter market trajectories. Forecasts reflect assumptions documented through extensive primary and secondary research. Quarterly review of clinical trial progress and reimbursement policy changes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
ACTH Deficiency Treatment Market
Specialty Medicine
Cholangitis Market
Specialty Medicine
Neurometabolic Disorder Market
Specialty Medicine
Global Addison's Disease Treatment Market
Specialty Medicine
Global Multiple Sclerosis Therapeutics Market
Specialty Medicine
Myasthenia Gravis Market
Specialty Medicine
Gallbladder Cancer Therapeutics Market
Specialty Medicine
Central Nervous System (CNS) Biomarkers Market
Specialty Medicine
Intraductal Papilloma Market
Specialty Medicine
Anophthalmia and Microphthalmia Market
Specialty Medicine
Europe Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Glucagon Therapy Market
Specialty Medicine
Global Allergic Rhinitis Market
Specialty Medicine
Premenstrual Dysphoric Disorder Market
Specialty Medicine
Bartter Syndrome Treatment Market
Specialty Medicine
Gingivostomatitis Market