
 Pediatric Perfusion Products Market | 2026-2036
Pediatric Perfusion Products Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Perfusion Products Market Outlook
Software-defined monitoring and predictive maintenance overlays are restructuring how perfusion capital equipment generates recurring revenue. Medtronic leverages integrated service contracts to sustain installed-base loyalty across high-volume pediatric cardiac centers. Getinge AB anchors European aftermarket presence through regional technical service hubs. Edwards Lifesciences differentiates via algorithm-driven perfusion analytics that extend hardware utility.
Pediatric perfusion products encompass extracorporeal circuits, oxygenation modules, and blood management systems engineered for patients under eighteen kilograms with priming volumes below 500 milliliters. These systems maintain cardiopulmonary function during open-heart procedures, transplant operations, and critical circulatory support. Cardiopulmonary bypass equipment occupies the largest value pool given capital intensity and replacement cycles, while extracorporeal membrane oxygenation technology leads expansion due to rising neonatal respiratory failure admissions. Pediatric hospitals command the dominant end-user share through centralized surgical volume and bundled procurement frameworks.
FDA 510(k) pathways and EU MDR conformity assessments shape product development timelines and clinical evidence requirements for oxygenators and cannulas. ISO 10993 biocompatibility standards and IEC 60601 electrical safety protocols govern material selection and device interoperability across regulatory jurisdictions. Stakeholders must monitor evolving premarket submission thresholds for novel blood-contacting surfaces as agencies tighten pediatric-specific safety benchmarks.
Market Dynamics
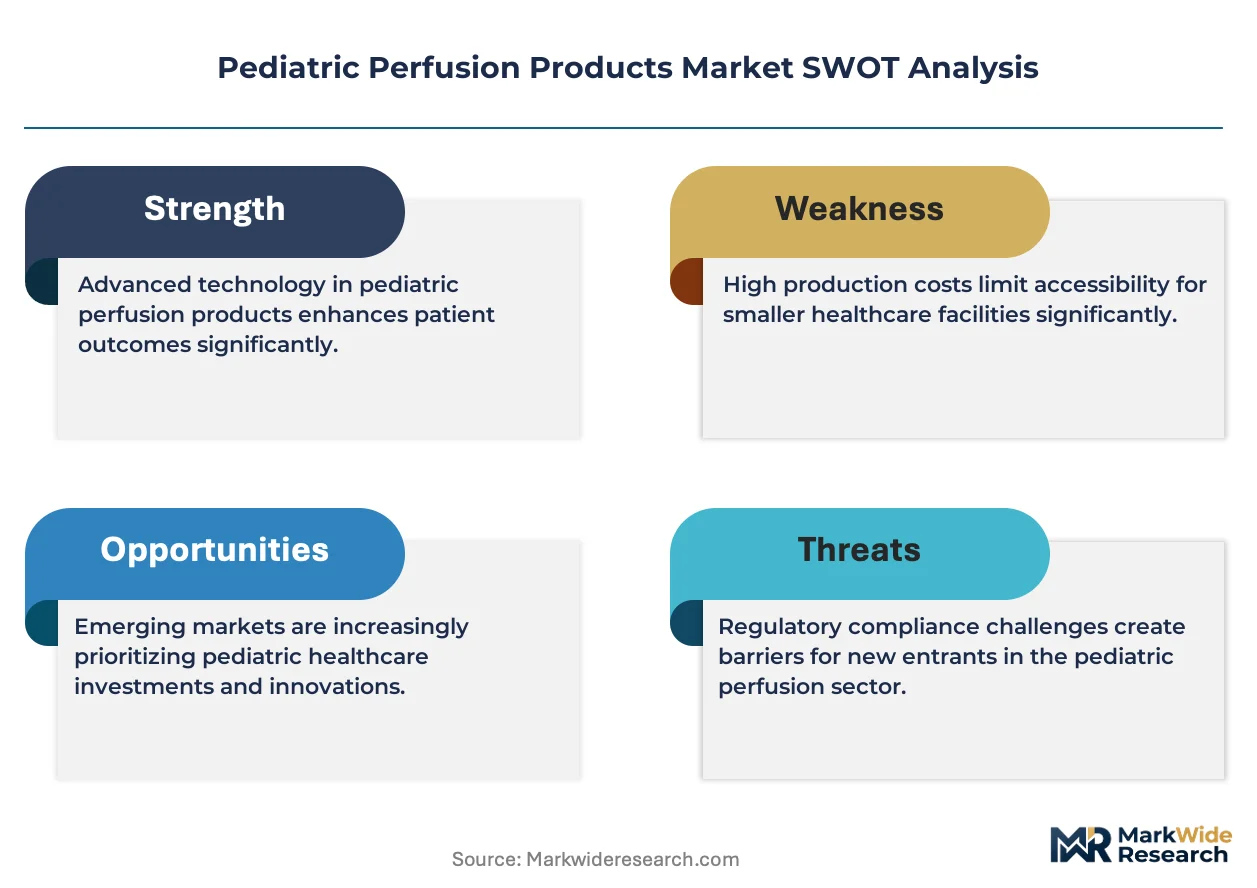
FDA premarket submission thresholds for pediatric-specific blood-contacting surfaces are tightening clinical evidence requirements and lengthening development timelines across oxygenator and cannula portfolios.
Growth Catalysts
- Neonatal ECMO protocols:Rising respiratory failure admissions in pediatric intensive care units are expanding addressable procedure volumes for membrane oxygenation circuits.
- EU MDR pediatric annexes:Updated conformity assessment pathways for devices under eighteen kilograms are creating certified product differentiation that rewards early compliance investment.
- German manufacturing clusters:Concentrated extracorporeal device production around Eurosets and Xenios AG technical centers is generating specialized supplier ecosystems and faster prototyping cycles.
Market Restraints
- Silicone membrane input volatility:Specialized polymer supply concentration in Asian chemical processing creates pricing unpredictability for oxygenator hollow-fiber production.
- Single-supplier cannula sourcing:Pediatric-specific arterial cannula manufacturing concentrates among three European contract manufacturers, creating vulnerability to capacity constraints.
- Priming volume floor:Hematocrit maintenance requirements for patients under five kilograms impose hard technical limits on circuit miniaturization below 150 milliliters.
Strategic Opportunities
- Indian pediatric cardiac centers:Underpenetrated tertiary care infrastructure in Delhi and Mumbai corridors offers volume expansion as congenital surgery programs scale.
- Software-defined monitoring overlays:Predictive perfusion analytics convergence with cloud-based hemodynamic platforms creates recurring revenue attachment to capital equipment.
- Integrated service contracting:Unbundled technical service and consumable bundling is displacing traditional capital purchase models in high-volume North American centers.
Industry Challenges
- Pediatric perfusionist training pipelines:Specialized certification requirements for sub-twenty-kilogram procedures create talent scarcity that limits center expansion.
- Legacy equipment interoperability:IEC 60601 electrical safety protocol variations across installed-base generations complicate monitoring system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Perfusion Products Market |
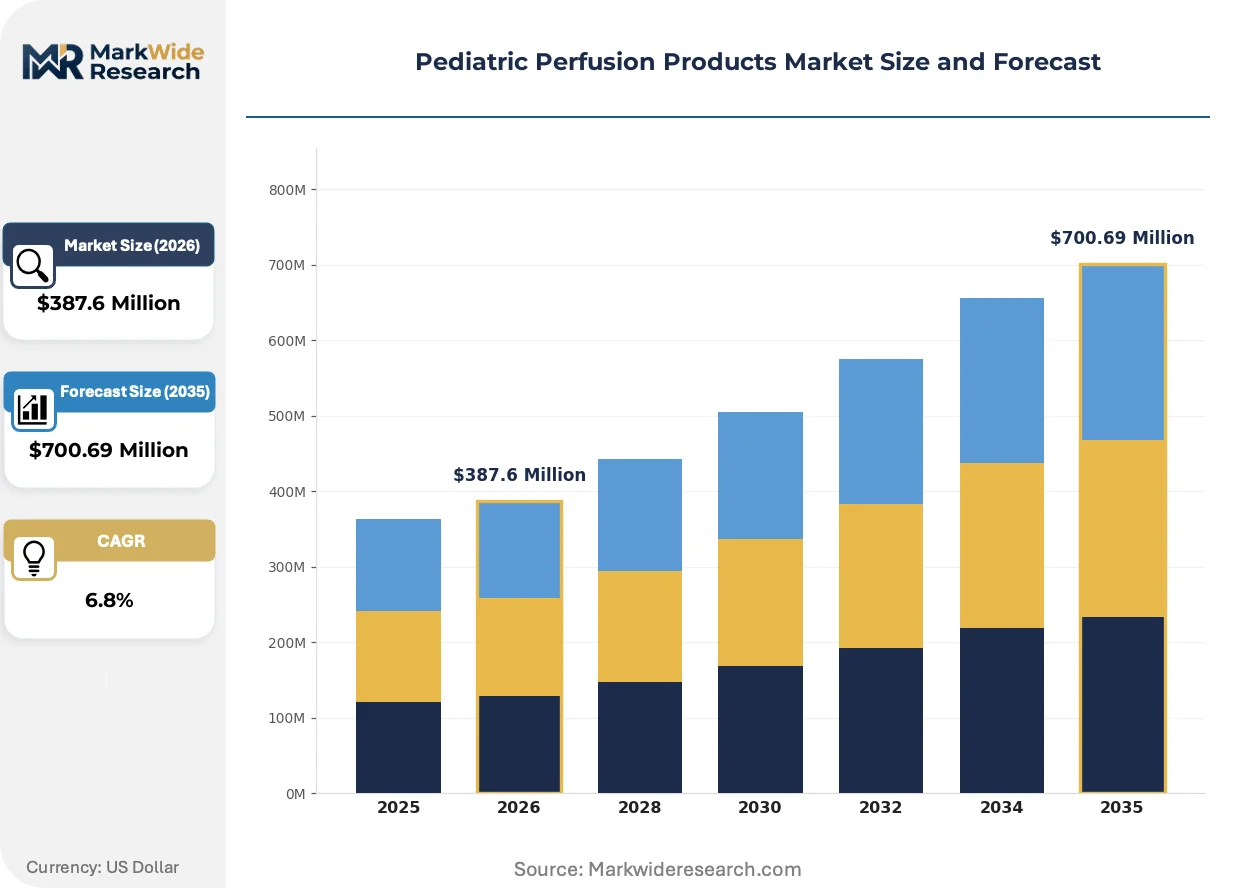
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiopulmonary Bypass Equipment, Oxygenators, Cannulas, Modular Pumps Application: Cardiac Surgery, Organ Transplantation, Hematology, Research End User: Pediatric Hospitals, Surgical Centers, Cardiovascular Clinics, Academic Research Institutions Technology: Extracorporeal Membrane Oxygenation, Artificial Heart-Lung Machines, Blood Management Systems, Advanced Monitoring Solutions |
| Companies Covered | Getinge AB, Edwards Lifesciences Corporation, Medtronic plc, Braile Biomédica, Nipro Corporation, Terumo Cardiovascular Systems Corporation, Eurosets, Xenios AG, LivaNova PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Perfusion Products Market Strategic Shifts
Digital overlay technologies and regulatory pediatric-specificity are restructuring how perfusion capital equipment generates lifetime value and competitive differentiation.
Disposable circuit components are modularizing around standardized connector geometries that separate oxygenation, pumping, and monitoring functions into interoperable sub-assemblies. Pediatric cardiac centers in Germany and the United States are piloting these configurations to reduce inventory complexity and enable intraoperative customization. This architecture is modularizing supplier relationships and compressing switching costs between hardware vendors.
EU MDR Annex XVI expansion for active implantable devices is extending clinical evidence requirements to temporary circulatory support systems previously governed by lighter frameworks. Manufacturers must now submit pediatric-specific biocompatibility data under ISO 10993-1 extended testing protocols. Oxygenator portfolios with legacy CE marks face the steepest compliance burden, with German notified bodies processing the highest submission volumes.
After-sales service unbundling is fragmenting traditional capital equipment relationships as buyers separate hardware procurement from technical support and consumable supply. Pediatric hospitals in North America are negotiating direct oxygenator contracts with specialty manufacturers while retaining independent service agreements. This pattern is most pronounced in centers performing over two hundred annual procedures where volume justifies disaggregated sourcing.
Pediatric Perfusion Products Market Segmentation
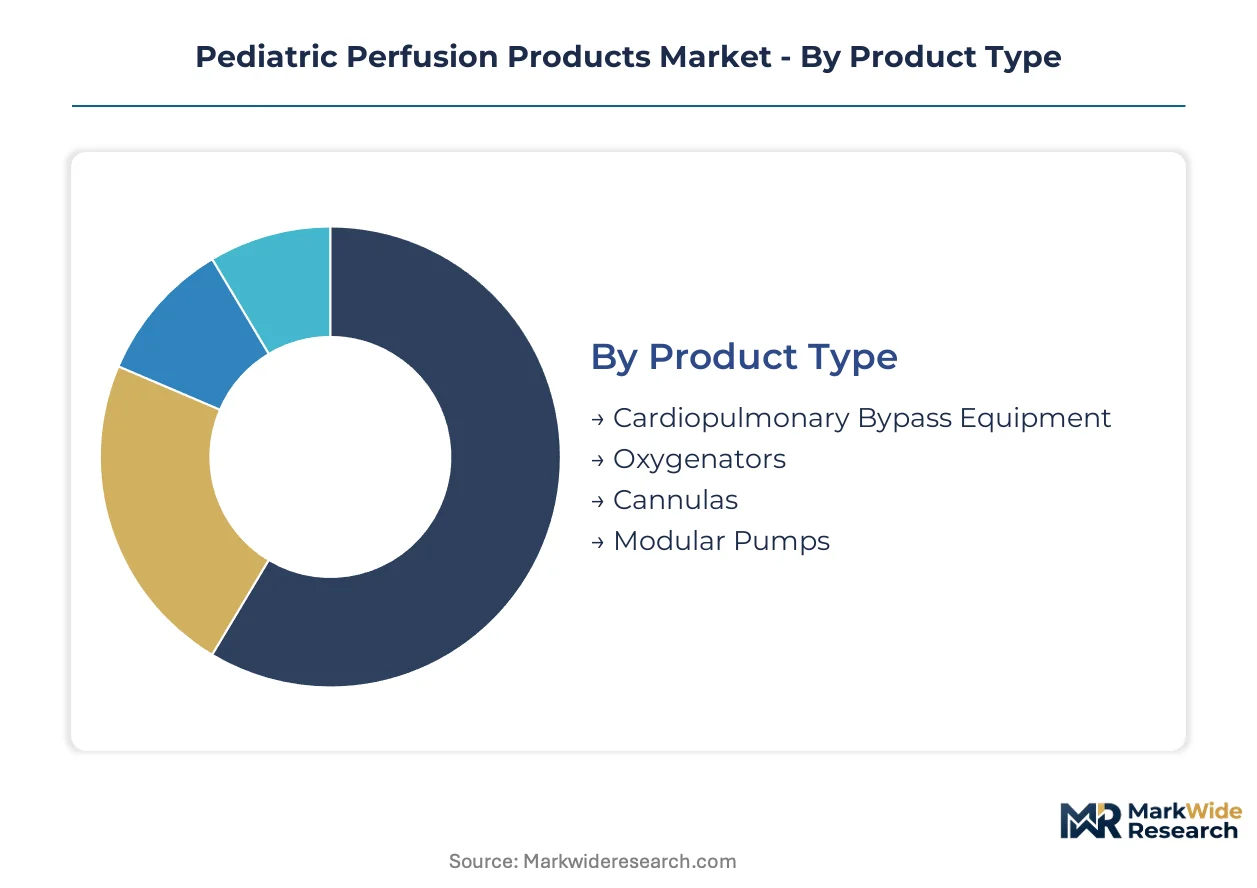
Pediatric perfusion markets fragment across equipment intensity, procedure acuity, and institutional purchasing power. Segmentation reveals where capital budgets concentrate versus where consumable attach rates sustain recurring revenue.
Product Type:
Cost tier separates integrated capital platforms from disposable circuit components that generate recurring revenue streams.
- Cardiopulmonary Bypass Equipment:Integrated pump-oxygenator consoles with centrifugal or roller pump architectures dominate capital expenditure allocation. North American pediatric cardiac centers prioritize FDA 510(k) cleared platforms with sub-500 milliliter priming volumes for neonatal procedures.
- Oxygenators:Hollow-fiber membrane devices with silicone or polymethylpentene diffusion layers constitute the highest-velocity consumable category. German manufacturing clusters around Eurosets and Xenios AG supply the majority of EU MDR certified pediatric-specific oxygenators.
- Cannulas:Arterial and venous access devices sized for patients under eighteen kilograms feature specialized biocompatible coatings and tapered flow geometries.
- Modular Pumps:Interchangeable centrifugal pump heads that integrate with third-party monitoring systems enable intraoperative configuration flexibility.
Cardiopulmonary bypass equipment leads volumes today; oxygenators are gaining share fastest.
Application:
Procedure volume and reimbursement intensity determine hardware utilization rates and consumable throughput.
- Cardiac Surgery:Congenital heart defect corrections, valve reconstructions, and septal defect closures generate the highest annual procedure counts. Pediatric hospitals in the United States perform the majority of complex neonatal bypass cases requiring specialized low-prime circuits.
- Organ Transplantation:Heart and lung transplant operations demand extended perfusion support with advanced organ preservation protocols. ECMO bridging prior to pediatric transplant has expanded membrane oxygenation circuit utilization in specialized centers.
- Hematology:Therapeutic apheresis and stem cell collection procedures employ modified perfusion circuits for cellular processing applications.
- Research:Preclinical device testing and hemodynamic simulation studies utilize scaled pediatric circuit models for regulatory submission support.
Cardiac surgery commands installed base concentration; organ transplantation shows the steepest expansion trajectory.
End User:
Annual procedure volume and procurement sophistication separate centralized purchasing from distributed acquisition patterns.
- Pediatric Hospitals:Tertiary care institutions with dedicated congenital cardiac surgery programs aggregate the highest equipment utilization and negotiate bundled capital-consumable contracts.
- Surgical Centers:Ambulatory facilities performing lower-acuity pediatric cardiac interventions require compact, transportable bypass platforms with rapid setup protocols.
- Cardiovascular Clinics:Diagnostic and interventional cardiology practices utilize perfusion support for hybrid operating room procedures and catheterization laboratory emergencies.
- Academic Research Institutions:University-affiliated medical centers with active perfusionist training programs maintain diverse equipment portfolios for educational and investigational use.
Pediatric hospitals dominate capital deployment; surgical centers are expanding their addressable share most rapidly.
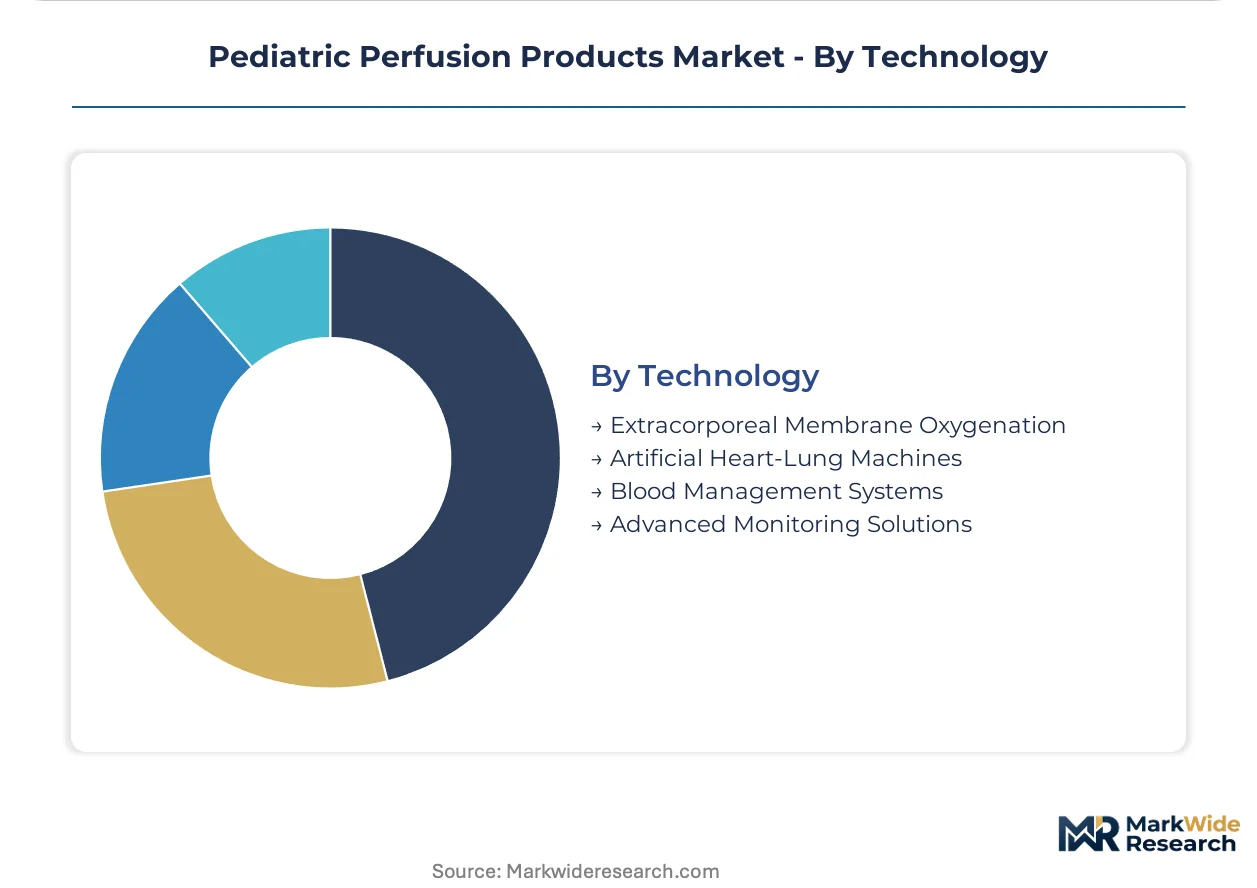
Technology:
Maturity curve positioning separates established mechanical support from emerging digital integration platforms.
- Extracorporeal Membrane Oxygenation:Veno-arterial and veno-venous configurations for neonatal respiratory failure provide prolonged cardiopulmonary support beyond standard bypass durations. Rising pediatric ICU admissions for congenital diaphragmatic hernia and meconium aspiration syndrome are expanding circuit demand.
- Artificial Heart-Lung Machines:Conventional cardiopulmonary bypass platforms with roller pump or centrifugal pump architectures remain the foundational technology for open-heart procedures.
- Blood Management Systems:Cell salvage, hemofiltration, and ultrafiltration modules that integrate with primary bypass circuits reduce allogeneic transfusion requirements.
- Advanced Monitoring Solutions:Real-time hemodynamic analytics, near-infrared spectroscopy, and predictive perfusion algorithms overlay digital capabilities onto hardware platforms.
Artificial heart-lung machines anchor installed base value; extracorporeal membrane oxygenation is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as EU MDR compliance costs push production toward jurisdictions with streamlined pediatric device pathways. German notified bodies process the highest submission volumes, while FDA 510(k) clearances concentrate value capture in United States tertiary centers.
United States
Pediatric cardiac centers in Boston and Philadelphia drive installed-base renewal for sub-500 milliliter priming circuits. FDA 510(k) premarket submissions for oxygenators face lengthening review timelines amid tightened pediatric-specific safety benchmarks. Medtronic leverages integrated service contracts across high-volume centers to sustain hardware loyalty.
Germany
Concentrated extracorporeal device production around Eurosets and Xenios AG technical centers generates specialized supplier ecosystems. EU MDR Annex XVI expansion extends clinical evidence requirements to temporary circulatory support systems previously under lighter frameworks. Notified bodies in Munich and Stuttgart process the highest pediatric oxygenator certification volumes.
Japan
PMDA regulatory harmonization with ISO 10993 biocompatibility standards accelerates market entry for hollow-fiber membrane devices. Tokyo and Osaka pediatric hospitals prioritize compact bypass platforms with rapid setup protocols for hybrid operating room procedures. Domestic manufacturers face pressure from EU MDR-certified imports.
India
Underpenetrated tertiary care infrastructure in Delhi and Mumbai corridors offers volume expansion as congenital surgery programs scale. CDSCO import licensing requirements for blood-contacting devices create compliance barriers that favor local assembly partnerships. Apollo and Fortis hospital chains are consolidating procurement across cardiac centers.
Brazil
ANVISA pediatric device registration pathways remain fragmented compared to FDA or EU MDR frameworks. São Paulo and Rio de Janeiro cardiac institutes rely on imported oxygenators and cannulas from German manufacturing clusters. Currency volatility complicates long-term service contracting for capital equipment.
Pediatric Perfusion Products Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated pump-oxygenator consoles commanding concentrated vendor relationships while disposable circuits fragment across specialty suppliers. The market structure tiers across three archetypes: diversified cardiovascular conglomerates with full perfusion portfolios, focused extracorporeal device specialists, and regional contract manufacturers serving private-label demand. Competitive moves center on M&A for regulatory certification assets and capacity expansion in German manufacturing clusters.
Among diversified cardiovascular conglomerates, Getinge AB and Medtronic exemplify archetypes pursuing integrated service contracting to displace traditional capital purchase models. Edwards Lifesciences occupies a position emphasizing algorithm-driven perfusion analytics that extend hardware utility. Eurosets and Xenios AG represent the specialist tier concentrated in German manufacturing clusters with EU MDR-certified pediatric-specific oxygenators.
| Leading Market Players |
|---|
| Getinge AB |
| Edwards Lifesciences Corporation |
| Medtronic plc |
| Braile Biomédica |
| Nipro Corporation |
| Terumo Cardiovascular Systems Corporation |
| Eurosets |
| Xenios AG |
| LivaNova PLC |
| Others |
Value Chain & Pricing Dynamics
EU MDR Annex XVI pediatric-specific biocompatibility mandates now gate qualified supply access and premium-tier pricing eligibility for hollow-fiber membrane oxygenators. Manufacturers lacking ISO 10993-1 extended testing protocols face exclusion from German procurement frameworks that anchor European pricing benchmarks.
Pricing Analysis
Capacity additions in German manufacturing clusters are reshaping price floors for EU MDR-certified pediatric oxygenators. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales bundling intensity. Cost compression in economy-tier cannulas is intensifying because Asian polymer feedstock volatility feeds through to hollow-fiber production. Pediatric hospitals in the United States show least price sensitivity given bundled capital-consumable contracting, while Indian tertiary centers remain most exposed to landed cost fluctuations.
Supply Chain Analysis
ISO 10993-1 extended testing protocols and EU MDR notified body certification now filter supplier eligibility for pediatric blood-contacting surfaces. German, Italian, and Japanese manufacturing clusters anchor hollow-fiber membrane and specialized cannula production. Raw material dependencies center on silicone polymers, polymethylpentene resins, and biocompatible coating chemistries drawn from Asian chemical processing. Single-source vulnerability concentrates in pediatric-specific arterial cannula manufacturing among European contract foundries. Distribution runs through hospital system GPO contracts in North America and direct manufacturer agreements in European pediatric centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pediatric perfusion products offer margin-expansion pathways through software-defined monitoring overlays that transform capital equipment into recurring revenue platforms. Premium-tier shift toward predictive analytics contracts displaces traditional hardware purchase economics in high-volume centers.
For Market Incumbents: Anticipate regulatory fragmentation as FDA pediatric-specific safety benchmarks diverge from EU MDR Annex XVI requirements. Deepen backward integration into hollow-fiber membrane production to offset silicone polymer input volatility. Secure notified body pre-certification for legacy oxygenator portfolios before submission backlogs lengthen in German technical centers. For New Entrants and Emerging Players: The premium-to-economy tier price-point gap in Indian pediatric cardiac centers offers white-space capture as congenital surgery programs scale in Delhi and Mumbai corridors. Target modular pump configurations that interoperate with third-party monitoring systems to bypass installed-base loyalty at incumbent-dominated North American hospitals. Pursue CDSCO local assembly partnerships to circumvent import licensing barriers for blood-contacting devices. For Investors and Strategic Acquirers: Valuations sit cheapest among regional contract manufacturers lacking EU MDR certification assets but possessing pediatric-specific cannula production capacity. Long-term viability hinges on regulatory certification moats rather than manufacturing scale alone. Watch FDA premarket submission timeline extensions for novel blood-contacting surfaces as the inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Notified body approval in Germany unlocks premium-tier pricing access across European pediatric hospitals. |
| Software Companion Development | Predictive perfusion analytics from Edwards Lifesciences extend hardware utility and consumable attach rates. |
| Hospital System Partnership | Integrated service contracts at Medtronic sustain installed-base loyalty in high-volume North American centers. |
| Backward Integration | In-house silicone membrane production at Eurosets reduces exposure to Asian polymer supply volatility. |
| Geographic Manufacturing Footprint | Local assembly partnerships in India circumvent CDSCO import barriers for blood-contacting cannulas. |
Study Parameters
Multiple input streams — perfusionist interviews, hospital procurement database analysis, regulatory filing review, and GPO contract extraction — were reconciled through bottom-up and top-down triangulation. Primary fieldwork encompassed pediatric cardiac surgeons, biomedical engineers, hospital purchasing committee members, and GPO contracts managers across tertiary care institutions in the United States, Germany, and India. Secondary validation drew from FDA 510(k) filings, EU MDR notified body submission logs, CMS Medicare procedure data, and hospital capital expenditure disclosures.
Historical utilization patterns were cross-referenced against expert panel inputs to anchor growth assumptions across the analysis window. Segmentation modeling captured product type, application acuity, end-user procurement sophistication, and technology maturity curve positioning. CAGRs were derived from procedure volume trajectories, replacement cycle analysis, and consumable attach rate evolution in pediatric cardiac surgery and organ transplantation settings.
Caveats apply where FDA premarket submission timeline extensions or EU MDR notified body capacity constraints could materially shift the outlook for oxygenator portfolio renewals. Forecasts reflect assumptions regarding neonatal ECMO protocol expansion and software-defined monitoring adoption curves. A model refresh is warranted upon material change in pediatric perfusionist training pipeline output or silicone membrane supply concentration patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Pediatric HIV Infection Treatment Market
Pediatrics
Paediatric Wheelchairs Market
Pediatrics
Pediatrics Medicine Market
Pediatrics
Paediatric Spasticity Treatment Market
Pediatrics
Global Pediatric Clinical Trials Market
Pediatrics
Pediatric Nasal Cannula Market
Pediatrics
Autism Service Platform Market
Pediatrics
Pediatric Home Healthcare Market
Pediatrics
Pediatric Healthcare Market
Pediatrics
Pediatric Growth Hormone Deficiency Market
Pediatrics
Paediatric Neuropsychiatric Disorders Treatment Market
Pediatrics
Global Pediatric Neuroblastoma Treatment Market
Pediatrics
Pediatric Obesity Management Market
Pediatrics
Pediatric Mattress Market
Pediatrics
Pediatric Brain Tumor Market
Pediatrics
Pediatric MRI Market