
 Gingivostomatitis Market | 2026-2036
Gingivostomatitis Market Size, Share, and Industry Trends Forecast 2026-2036
Gingivostomatitis Market Analysis
Pediatric dentistry is restructuring the demand profile for gingivostomatitis therapeutics as early-intervention protocols displace reactive hospital referrals. Merck & Co. leverages its antiviral manufacturing scale to supply hospital systems with acyclovir-based formulations. Pfizer competes through pain management portfolios that anchor pharmacy channel relationships. GlaxoSmithKline differentiates via topical delivery R&D programs targeting dental clinic networks.
Gingivostomatitis denotes a painful mucosal inflammation of the gums and oral cavity, typically triggered by primary herpes simplex virus infection in children under six years, presenting with vesicular lesions, fever, and dysphagia that disrupt nutritional intake. The condition demands antiviral suppression combined with topical anesthetic and antiseptic adjuncts to prevent dehydration and secondary bacterial colonization. Antiviral ointment leads product type revenue due to payer preference for prescription-grade HSV intervention, while dental clinics represent the fastest-growing end user channel as chairside diagnosis protocols expand. Oral delivery mode dominates volume, though topical gel commands premium positioning in home care settings where caregiver-administered pain management reduces emergency utilization.
FDA oversight of pediatric antiviral labeling shapes formulation development timelines and clinical trial enrollment criteria for manufacturers seeking pediatric indications. The EPA regulates residual solvent thresholds in topical gel excipients, constraining contract manufacturing options for mouth rinse and oral spray products. Stakeholders must monitor evolving FDA guidance on antiviral pediatric dosing and EPA excipient safety reassessments to align pipeline investments with compliance-ready formulation strategies.
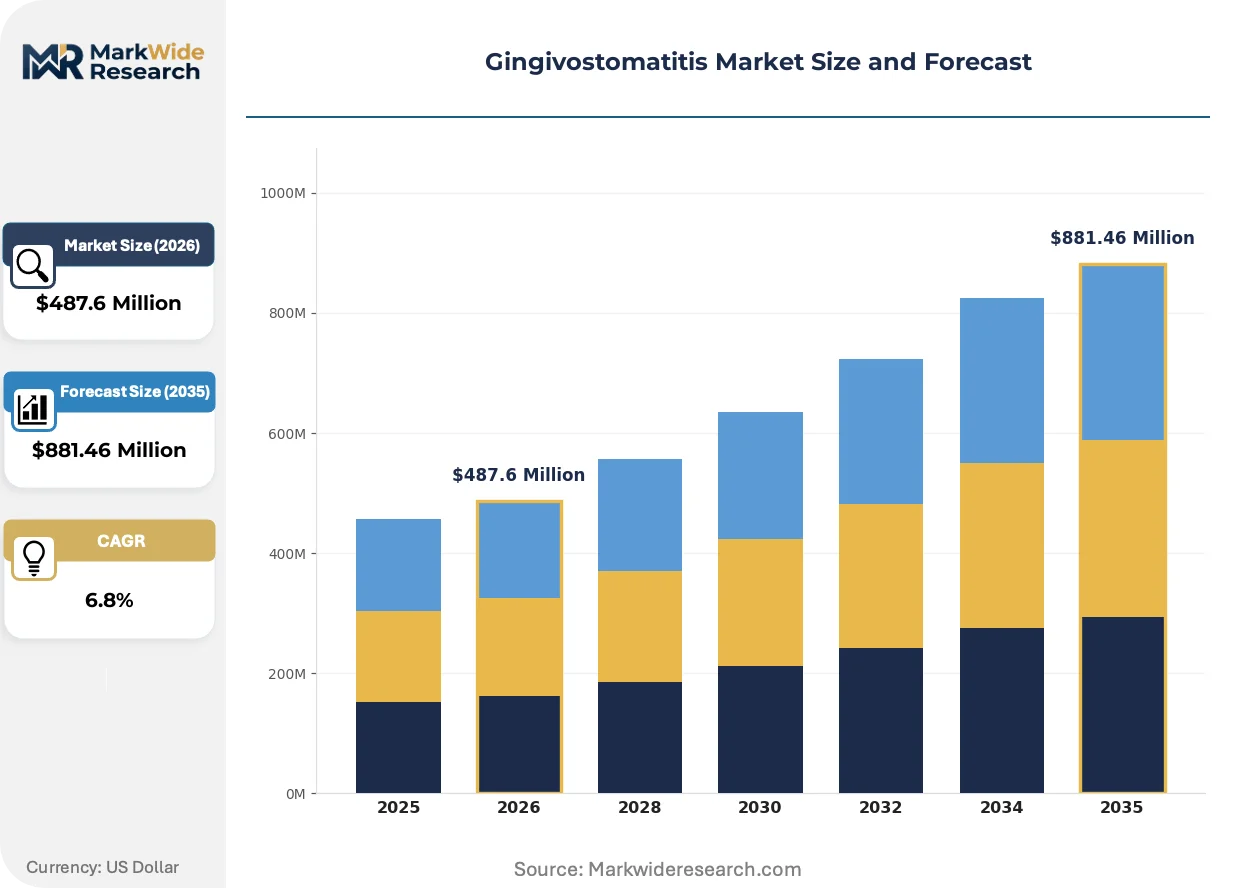
Market Dynamics
Pediatric dental clinics are consolidating antiviral procurement around chairside diagnostic protocols, compressing traditional hospital referral pathways while FDA pediatric labeling requirements extend formulation development timelines for topical therapeutics.
Growth Catalysts
- HSV Screening Mandates:FDA guidance tightening herpes simplex virus detection protocols in pediatric settings is expanding prescription antiviral ointment utilization rates.
- Dental Clinic Networks:Chairside diagnosis capabilities in specialized pediatric dentistry practices are displacing emergency department referrals for mucosal inflammation cases.
- Topical Anesthetic Coverage:Commercial payer formulary expansions for lidocaine-based oral gels are reducing out-of-pocket barriers to home-based pain management.
Market Restraints
- Acyclovir API Concentration:Active pharmaceutical ingredient manufacturing clusters in India and China create supply vulnerability for antiviral formulation producers.
- Pediatric Trial Complexity:FDA requirements for age-stratified dosing studies extend clinical development timelines and inflate regulatory submission costs.
- Generic Substitution Pressure:Patent-expired antiviral compounds face commoditization as pharmacy benefit managers prioritize cost-minimization over branded formulations.
Strategic Opportunities
- Telehealth-Integrated Prescribing:Remote pediatric consultation platforms are creating direct-to-home antiviral delivery channels bypassing traditional pharmacy intermediaries.
- Mucoadhesive Gel Innovation:Bioadhesive polymer technologies are enabling extended-release topical formulations that reduce dosing frequency for caregiver-administered therapy.
- Rural Clinic Penetration:Underserved geographic clusters in the Mountain West and Deep South present white-space expansion potential for mobile dental diagnostic units.
Industry Challenges
- Pediatric Formulation Expertise Scarcity:Specialized compounding pharmacists capable of age-appropriate dosing conversions remain concentrated in academic medical centers.
- EPA Excipient Compliance:Residual solvent threshold revisions for topical gel carriers are forcing contract manufacturer qualification cycles and inventory write-downs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gingivostomatitis Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Gel, Mouth Rinse, Antiviral Ointment, Oral Spray End User: Hospitals, Dental Clinics, Home Care, Pharmacy Delivery Mode: Oral, Injectable, Transdermal, Inhalation Therapy Area: Anti-Inflammatory, Pain Management, Antiseptic, Antifungal |
| Companies Covered | Merck & Co., AstraZeneca, GlaxoSmithKline, Sanofi, Bristol-Myers Squibb, Pfizer, Johnson & Johnson, AbbVie, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gingivostomatitis Market Emerging Trajectories
Diagnostic automation and regulatory recalibration are compressing treatment initiation windows while reshaping how antiviral therapeutics reach pediatric patients outside traditional hospital settings.
Point-of-care PCR platforms are automating herpes simplex virus confirmation at the dental chairside, eliminating the 24-48 hour laboratory turnaround that previously delayed antiviral initiation. Pediatric dental networks in Texas and Florida are deploying these instruments at the fastest clip, with equipment financing bundled into group purchasing agreements. This automation is compressing the diagnostic-to-treatment interval from days to minutes, redirecting patient volume away from emergency departments and into outpatient clinic revenue capture.
EPA is reassessing residual solvent thresholds for propylene glycol and polyethylene glycol excipients used in mucoadhesive oral gels, triggering reformulation mandates for products manufactured before 2022. Contract manufacturers serving the topical anesthetic segment are absorbing retesting costs and extending lead times while awaiting final rule publication. Mouth rinse and oral spray categories face the steepest compliance burden given their higher water-content formulations and corresponding solvent volatility profiles.
Caregiver-administered pain management protocols are displacing emergency department utilization for nutritional intake disruption cases, with pharmacy benefit managers expanding prior authorization exemptions for topical anesthetic combinations. Home care settings now represent the fastest-expanding consumption node, with mail-order pharmacy channels capturing prescription volume previously routed through hospital discharge. This behavioral pivot concentrates in suburban markets where pediatric dental clinic density exceeds hospital saturation.
Gingivostomatitis Market Segmentation
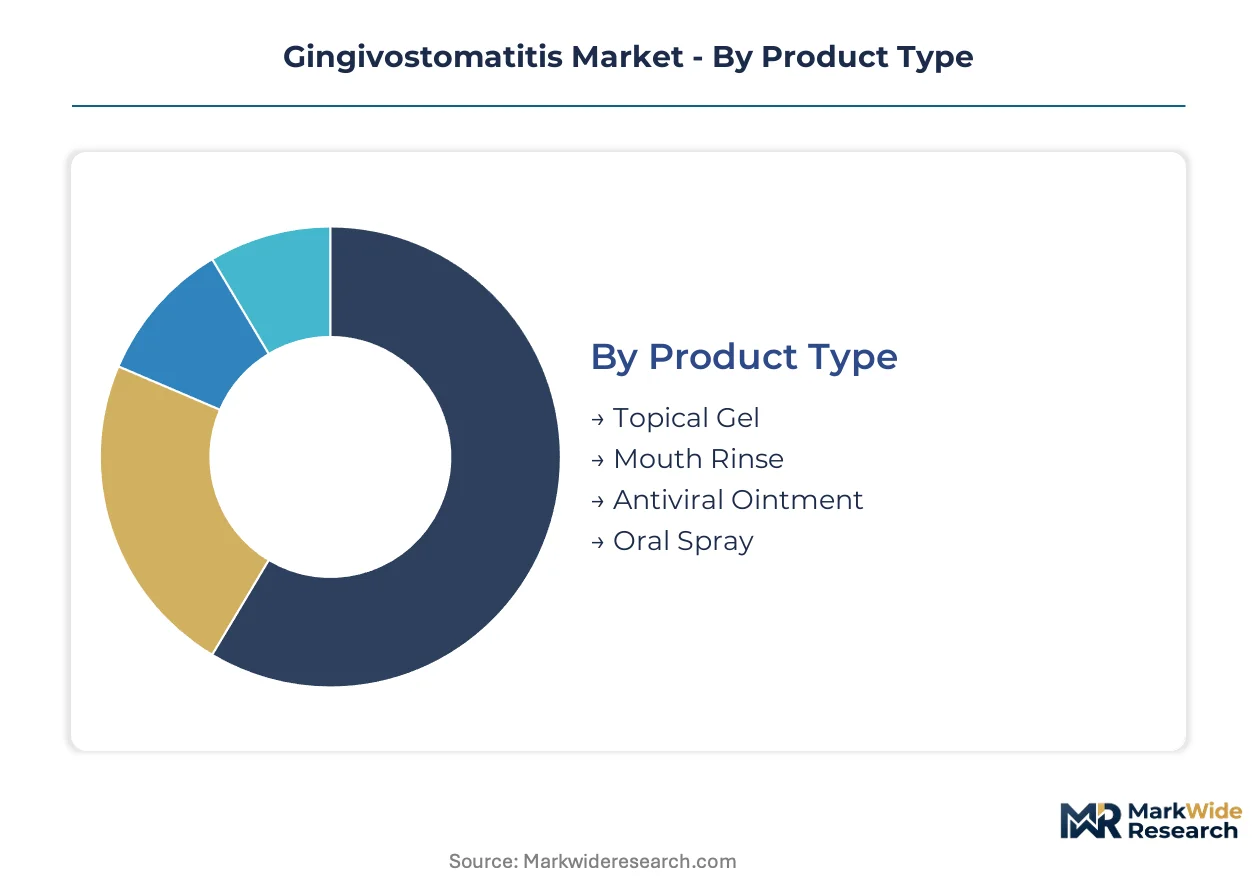
Gingivostomatitis therapeutics fragment across formulation physics, care setting workflows, and administration routes that reshape procurement priorities. Pediatric dental clinics and home caregivers now drive category-specific demand patterns distinct from legacy hospital purchasing.
Product Type:
Formulation viscosity and residence time on mucosal surfaces determine reimbursement tiers and caregiver compliance rates.
- Antiviral Ointment:Acyclovir-based semisolid preparations adhere to vesicular lesions for sustained drug release. FDA pediatric labeling for HSV suppression concentrates prescription volume in dental clinic networks with chairside diagnostic capabilities.
- Topical Gel:Lidocaine-hydrogel matrices provide rapid-onset anesthesia for dysphagia-related nutritional disruption. Commercial payer formulary expansions in suburban United States markets reduce out-of-pocket barriers for home-based administration.
- Mouth Rinse:Aqueous antiseptic solutions target secondary bacterial colonization prevention. EPA residual solvent thresholds constrain contract manufacturer qualification for propylene glycol excipient formulations.
- Oral Spray:Metered-dose aerosolized delivery enables caregiver-administered pain management without tactile lesion contact. Pharmacy benefit manager prior authorization exemptions are expanding for this modality.
Volume sits with antiviral ointment; growth tilts toward topical gel.
End User:
Care setting capabilities for point-of-care diagnosis and caregiver training intensity segment demand by procurement sophistication.
- Dental Clinics:Specialized pediatric dentistry practices deploy PCR-based HSV confirmation at chairside. Texas and Florida network expansions are compressing diagnostic-to-treatment intervals from days to minutes.
- Home Care:Mail-order pharmacy channels now capture prescription volume previously routed through hospital discharge. Suburban markets with high pediatric dental clinic density show the steepest consumption climb.
- Hospitals:Emergency departments retain severe dehydration cases requiring IV fluid replacement. Volume is compressing as dental clinic networks intercept moderate presentations earlier.
- Pharmacy:Retail and mail-order channels mediate between prescriber and caregiver for topical anesthetic fulfillment. Generic substitution pressure concentrates acyclovir procurement toward cost-minimization protocols.
Procurement gravity centers on dental clinics; expansion concentrates in home care.
Delivery Mode:
Patient age and lesion accessibility determine route feasibility, with oral administration dominating pediatric compliance.
- Oral:Solutions, suspensions, and orodispersible tablets accommodate children under six with limited cooperation capacity. This route captures the predominant prescription volume for antiviral and analgesic agents.
- Injectable:IV acyclovir reserves for hospitalized patients with severe immunocompromise or dehydration. Administration requires clinical monitoring infrastructure unavailable in outpatient settings.
- Transdermal:Limited applicability given mucosal lesion location; experimental patches for perioral HSV extension remain developmental.
- Inhalation:Nebulized delivery investigational for pharyngeal extension cases; no commercial formulations currently approved.
Prescription volume clusters with oral delivery; innovation investment targets mucoadhesive extensions.
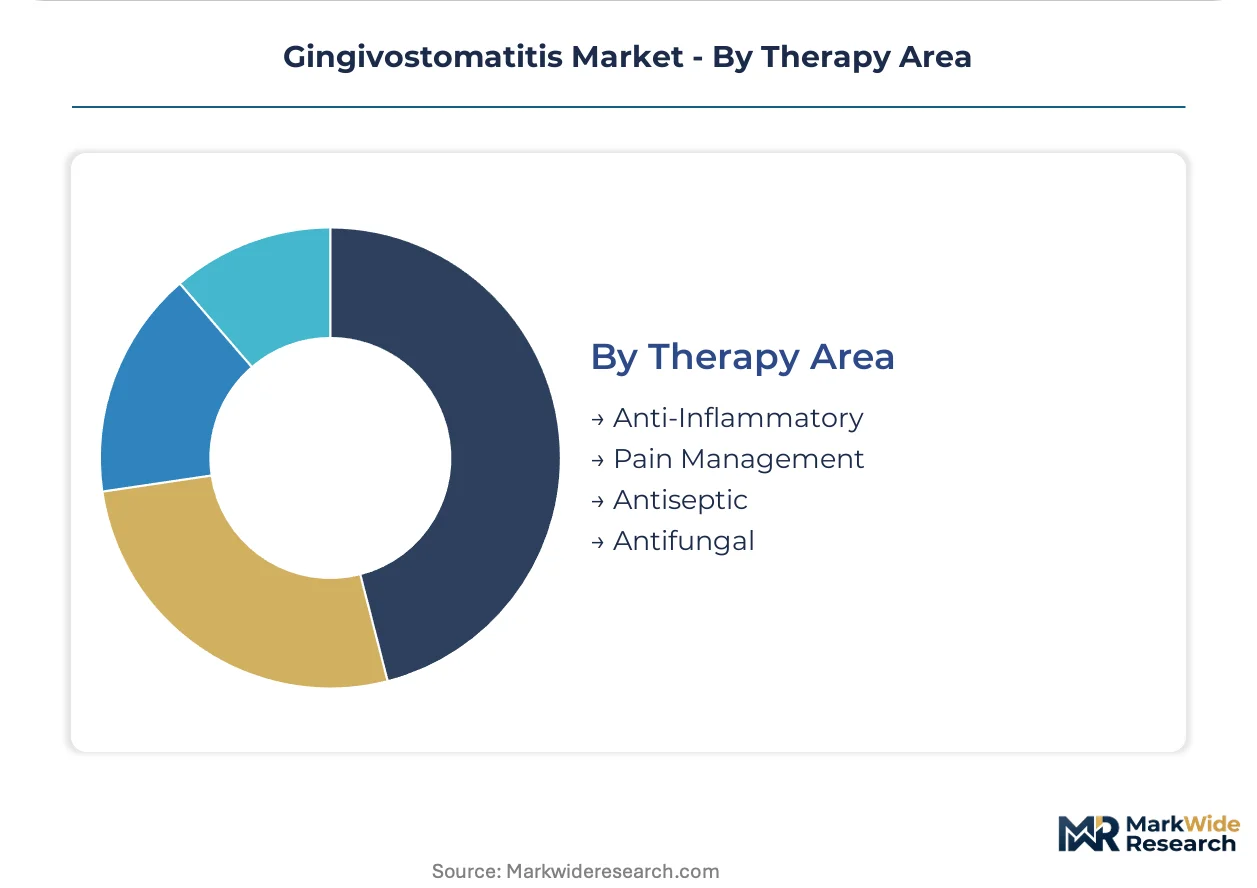
Therapy Area:
Clinical objective—viral suppression versus symptom palliation versus complication prevention—segments procurement by prescriber specialty.
- Pain Management:Topical anesthetic combinations address dysphagia-driven nutritional intake disruption. Lidocaine-benzocaine gels anchor pharmacy channel relationships through repeat prescription patterns.
- Antiviral Suppression:Systemic and topical acyclovir formulations target HSV replication reduction. FDA pediatric dosing guidance shapes clinical trial enrollment and label expansion timelines.
- Antiseptic:Chlorhexidine and povidone-iodine rinses prevent bacterial superinfection of ulcerated mucosa. Mouth rinse formulations face EPA excipient compliance burdens.
- Anti-Inflammatory:Corticosteroid preparations limited by immunosuppression risk in active HSV infection; niche use in post-viral inflammatory persistence.
Revenue concentration favors pain management; protocol evolution elevates antiviral suppression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in the United Arab Emirates attract pharmaceutical distributors serving Gulf pediatric dental networks. Tax-advantaged logistics hubs concentrate antiviral formulation imports for re-export across Middle Eastern markets.
United States
Pediatric dental clinic networks in Texas and Florida deploy point-of-care PCR instruments for chairside HSV confirmation. FDA pediatric labeling requirements for acyclovir formulations extend clinical trial timelines for manufacturers seeking age-specific indications. Suburban markets around Houston and Miami show the steepest consumption climb for mail-order topical anesthetic fulfillment.
Germany
EMA centralized approval pathways accelerate antiviral ointment market access across EU member states. The country's national pharmaceutical regulator enforces pediatric formulation stability standards that exceed baseline EU requirements. Bavarian dental technology clusters supply diagnostic automation equipment to pediatric practices throughout Central Europe.
India
CDSCO pediatric indication fast-track programs compress regulatory review timelines for generic acyclovir manufacturers. Active pharmaceutical ingredient production concentrates in Gujarat and Telangana, supplying formulation facilities across Asia-Pacific markets. Hyderabad-based contract research organizations manage age-stratified dosing studies for multinational sponsors.
Japan
PMDA pediatric extrapolation guidelines reduce clinical data requirements for antiviral formulations with established adult profiles. METI subsidizes point-of-care diagnostic deployment in rural prefectures with aging dentist populations. Osaka pharmaceutical manufacturing corridors specialize in mucoadhesive gel excipient production for regional formulation houses.
Brazil
ANVISA pediatric bioequivalence protocols shape generic antiviral substitution patterns in pharmacy channels. São Paulo state health programs distribute topical anesthetic kits through public dental clinics serving low-income pediatric populations. Minas Gerais manufacturing parks host regional formulation facilities for Portuguese-speaking African export markets.
Gingivostomatitis Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with prescription antiviral ointment revenue concentrating around firms with FDA pediatric labeling capabilities while topical gel procurement fragments across regional compounding networks. Three archetypes dominate: multinational pharmaceutical houses with antiviral manufacturing scale, pain management portfolio specialists anchoring pharmacy relationships, and topical delivery R&D firms targeting dental clinic networks. Competitive moves center on mucoadhesive polymer licensing agreements and telehealth-integrated prescribing platform partnerships.
Within the multinational pharmaceutical tier, Merck & Co., Pfizer, and GlaxoSmithKline occupy positions that exemplify divergent strategic anchoring. Merck & Co. represents the antiviral manufacturing scale archetype, supplying hospital systems with formulation capabilities shaped by decades of HSV therapeutic development. Pfizer exemplifies the pain management portfolio specialist, with pharmacy channel relationships built around repeat prescription patterns for lidocaine-based oral gels. GlaxoSmithKline sits within the topical delivery innovation tier, with R&D programs targeting dental clinic network procurement criteria for extended-release mucosal formulations.
| Leading Market Players |
|---|
| Merck & Co. |
| AstraZeneca |
| GlaxoSmithKline |
| Sanofi |
| Bristol-Myers Squibb |
| Pfizer |
| Johnson & Johnson |
| AbbVie |
| Novartis |
| Others |
Supply Flow & Price Mechanics
Acyclovir API procurement costs cascade through three pricing tiers before reaching pediatric dental clinics and home care settings. Indian and Chinese active pharmaceutical ingredient manufacturing clusters feed contract formulation facilities, where EPA residual solvent compliance burdens and FDA pediatric labeling requirements stratify final product positioning.
Pricing Analysis
Short lead-time premiums attach to acyclovir ointment batches qualified under FDA pediatric labeling protocols, while spot inventory of generic antiviral compounds trades at compressed margins. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Price erosion runs through economy-tier generic substitution as pharmacy benefit managers tighten cost-minimization protocols. Dental clinic networks show the least price sensitivity due to bundled diagnostic equipment financing, while retail pharmacy channels face the steepest caregiver pushback on out-of-pocket topical anesthetic costs.
Supply Chain Analysis
Single-source vulnerability sits with Gujarat and Telangana API manufacturing corridors, where acyclovir precursor synthesis concentrates among contract manufacturers serving multinational formulation houses. Formulation production draws from propylene glycol excipient suppliers in Japan and polyethylene glycol specialists in Germany, with EPA residual solvent threshold revisions creating regulatory chokepoints for pre-2022 inventory. Tariff exposure on Indian API imports into the United States threatens margin compression for domestic compounding networks. Distribution runs through group purchasing organizations consolidating dental clinic procurement and mail-order pharmacy channels capturing home care volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized pediatric formulation capacity scarcity props pricing power for manufacturers with FDA age-stratified dosing approvals, as clinical trial complexity blocks rapid competitor entry.
For Market Incumbents: Extend mucoadhesive polymer R&D partnerships to lock dental clinic network loyalty before generic gel formulations achieve bioequivalence. Defend against telehealth-integrated prescribing platforms by embedding diagnostic equipment financing into exclusive supply agreements. Prioritize backward integration into acyclovir API production to offset Indian supply vulnerability. For New Entrants and Emerging Players: Telehealth platform operators represent the most penetrable channel partner type for bypassing entrenched pharmacy intermediaries. Target rural Mountain West and Deep South dental clinic clusters where mobile diagnostic unit deployment lags metropolitan density. White-space expansion in caregiver-administered oral spray formulations offers the clearest go-to-market angle given expanding prior authorization exemptions. For Investors and Strategic Acquirers: EPA final rule publication on propylene glycol residual solvents is the leading indicator that contract manufacturer consolidation will accelerate. Five-to-ten year viability favors acquisition of mucoadhesive gel excipient specialists with reformulation-ready compliance infrastructure. Monitor CDSCO pediatric fast-track approval announcements for signals of generic antiviral substitution timing.| Strategic Initiative | Industry Significance |
|---|---|
| Mucoadhesive Polymer Licensing | Extended-release gel formulations reduce dosing frequency for caregiver compliance in home care settings. |
| Telehealth Platform Partnership | Direct-to-home antiviral delivery channels bypass traditional pharmacy intermediaries and capture prescription volume. |
| FDA Pediatric Labeling Investment | Age-stratified dosing approvals create regulatory moats against generic substitution in dental clinic procurement. |
| Mobile Diagnostic Unit Deployment | Underserved rural clusters in Texas and Florida present white-space expansion for chairside HSV confirmation. |
| API Backward Integration | In-house acyclovir production mitigates supply vulnerability from Indian and Chinese manufacturing concentration. |
Methodological Framework
Multi-period observation of FDA pediatric labeling timelines, EPA excipient rulemaking progress, and dental clinic network expansion rates anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from FDA filings, ClinicalTrials.gov enrollment data, CMS Medicare Part D utilization patterns, and pharmacy benefit manager formulary databases. Bottom-up prescription volume modeling triangulated against top-down market sizing from antiviral API trade flows and topical gel excipient production statistics.
Input-output matrices mapped acyclovir ointment, topical gel, mouth rinse, and oral spray demand across dental clinic, home care, hospital, and pharmacy end users, with oral delivery mode and antiviral suppression therapy area as cross-cutting segmentation dimensions. CAGRs were derived from patient incidence modeling, treatment rate assumptions, and pricing trajectory analysis. Forecast inputs incorporated HSV screening mandate implementation pace and point-of-care PCR platform deployment curves.
Caveats apply where EPA residual solvent final rule revisions or FDA pediatric dosing guidance updates could materially shift the outlook for formulation development timelines and contract manufacturer qualification cycles. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Multiple Sclerosis Therapeutics Market
Specialty Medicine
Eosinophilic Granulomatosis Market
Specialty Medicine
Chronic Obstructive Pulmonary Disease Therapeutics Market
Specialty Medicine
Herpangina Treatment Market
Specialty Medicine
Global Alcoholic Hepatitis Therapeutics Market
Specialty Medicine
Vertebral Radiculopathy Market
Specialty Medicine
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Severe Hypertriglyceridemia (SHTG) Treatment Market
Specialty Medicine
Global Cryptococcosis Treatment Market
Specialty Medicine
Cubital Tunnel Syndrome Market
Specialty Medicine
Global Non-Oncology Precision Medicine Market
Specialty Medicine
Global Pemphigus Vulgaris Market
Specialty Medicine
Global Herpes Market
Specialty Medicine
Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market
Specialty Medicine
Meningitis Treatment Market
Specialty Medicine
Malabsorption Syndrome Market