
 Acute Hepatic Porphyria (APH) Market | 2026-2036
Acute Hepatic Porphyria (APH) Market Size, Share, and Industry Trends Forecast 2026-2036
Acute Hepatic Porphyria (APH) Market Analytics
Modular therapy bundling is pivoting how hospital procurement teams evaluate APH treatment protocols. Alnylam Pharmaceuticals sustains technology leadership through RNA interference platforms purpose-built for hepatic enzyme regulation. Recordati Rare Diseases anchors European market access through established orphan disease distribution channels. Pfizer leverages manufacturing scale to compete across intravenous and emerging oral formulation categories.
Acute Hepatic Porphyria comprises a family of rare metabolic disorders characterized by enzymatic defects in heme biosynthesis, specifically porphobilinogen deaminase deficiency in acute intermittent porphyria, the most prevalent subtype. These conditions trigger neurovisceral attacks requiring urgent hematin replenishment to restore heme homeostasis and prevent irreversible neuronal damage. Gene therapy segments attract concentrated R&D investment as programmable nucleases target liver-directed correction of underlying enzymopathies. Subcutaneous delivery modes represent the fastest-growing configuration, displacing prolonged hospital-based intravenous administration with patient-administered alternatives that reduce specialty clinic burden.
FDA orphan drug exclusivity provisions shape commercial timelines by granting seven-year market protection upon approval, while EMA's PRIME designation streamlines European centralized assessment for therapies addressing unmet rare disease needs. The EU Green Deal's pharmaceutical sustainability requirements increasingly influence manufacturing site selection and active pharmaceutical ingredient sourcing decisions. Stakeholders must monitor evolving HTA body evidentiary standards for single-arm trials and real-world data acceptance across major reimbursement markets.
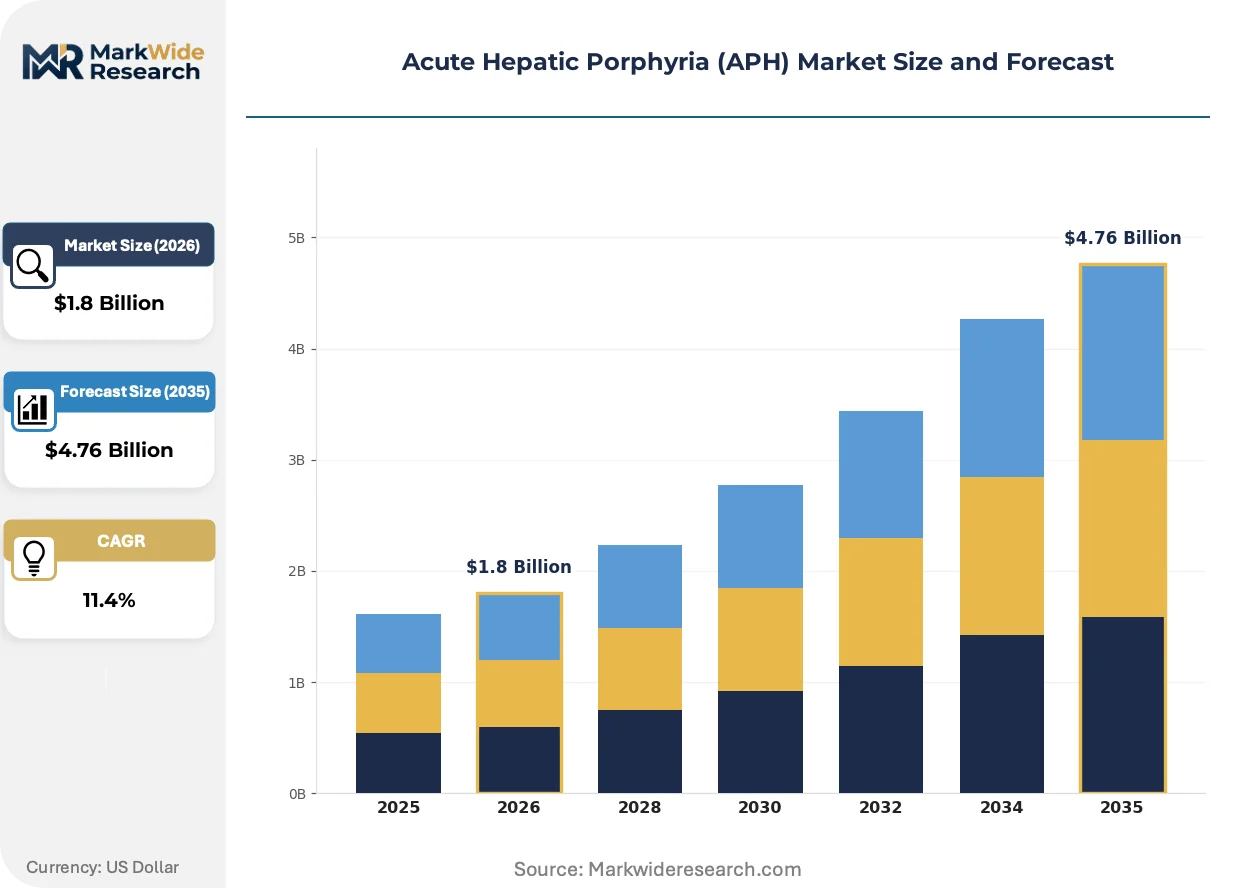
Market Dynamics
RNA interference platforms are compressing development timelines for hepatic enzyme regulation while FDA orphan drug incentives reshape competitive entry barriers across the APH therapeutic landscape.
Growth Catalysts
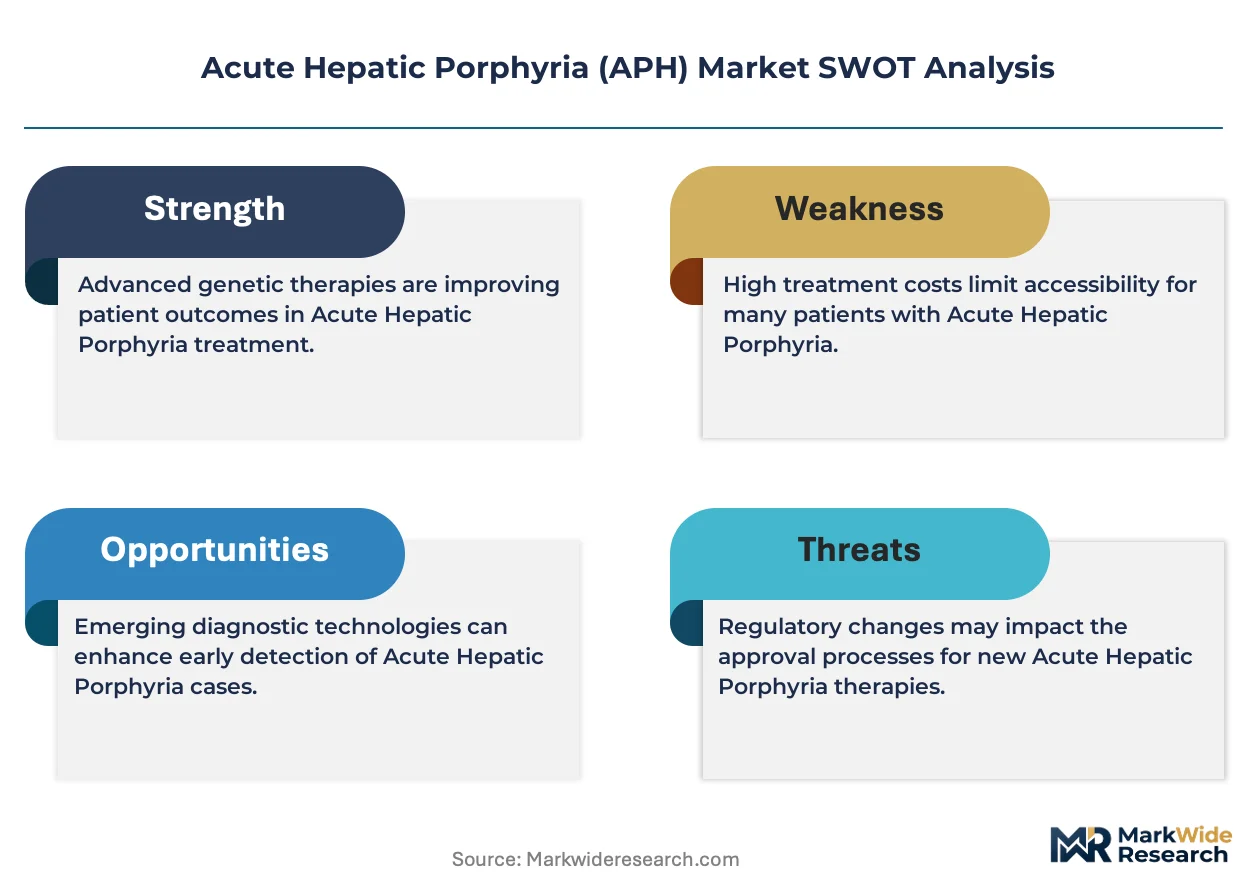
- Breakthrough Therapy Designation:FDA's expedited review pathway accelerates clinical development for novel RNAi therapeutics targeting porphobilinogen deaminase deficiency, compressing time-to-market by 2-4 years versus standard approval tracks.
- Subcutaneous Delivery Innovation:Patient-administered injection formats reduce hospitalization burden and expand addressable patient populations beyond tertiary care centers into community specialty clinics.
- Gene Therapy Investment:Programmable nuclease platforms attract concentrated R&D funding for liver-directed correction of underlying enzymopathies, with CRISPR-based approaches advancing through preclinical validation.
Market Restraints
- Plasma-Derived Hematin Supply Concentration:Reliance on fractionated human plasma creates input vulnerability, with manufacturing concentrated among limited biologics suppliers subject to viral safety screening constraints.
- Diagnostic Latency:Mean diagnostic delay of 15 years for acute intermittent porphyria fragments addressable market, as nonspecific neurovisceral symptoms misroute patients through gastroenterology and neurology pathways.
- Reimbursement Complexity:Orphan drug pricing frameworks encounter pushback from pharmacy benefit managers, with prior authorization requirements extending therapy initiation timelines.
Strategic Opportunities
- Real-World Evidence Pathways:FDA's expanded acceptance of patient registry data and natural history studies enables streamlined post-market efficacy confirmation, reducing confirmatory trial costs.
- Home Infusion Services:Specialty pharmacy networks are building capacity for subcutaneous administration support, creating channel expansion beyond hospital outpatient departments.
- Biomarker-Guided Prevention:ALA and PBG quantification protocols enable attack prediction algorithms, opening preventive therapy segments before symptomatic presentation.
Industry Challenges
- Genetic Counselor Workforce Scarcity:Interpretation of HMBS, CPOX, and PPOX variant significance requires specialized expertise, with accredited counselor supply lagging testing volume growth.
- Cold Chain Integrity:Temperature-sensitive RNAi formulations demand validated distribution infrastructure, with last-mile delivery to patient homes requiring continuous monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acute Hepatic Porphyria (APH) Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hematin, Panhematin, Givosiran, Others Therapy Area: Gene Therapy, Enzyme Replacement Therapy, Supportive Care, Others Delivery Mode: Intravenous, Subcutaneous, Oral, Others End User: Hospitals, Specialty Clinics, Homecare, Others |
| Companies Covered | Alnylam Pharmaceuticals, Inc., Recordati Rare Diseases, Pfizer Inc., Takeda Pharmaceutical Company Limited, Sanofi, Mitsubishi Tanabe Pharma Corporation, Teva Pharmaceutical Industries Ltd., Ipsen Pharma, Lundbeck Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acute Hepatic Porphyria (APH) Market Evolving Landscape
RNA interference mechanisms are rewriting therapeutic possibilities for hepatic metabolic disorders while regulatory frameworks adapt to accelerated approval paradigms for ultra-rare conditions.
Subcutaneous siRNA formulations are consolidating treatment administration away from infusion centers toward patient-managed settings. Specialty clinics in the United States and Germany are adopting these platforms within 18-24 months of launch, reducing per-patient healthcare system burden by eliminating prolonged intravenous observation periods. This shift is compressing hospital pharmacy revenue capture while expanding manufacturer addressable market through improved adherence profiles.
EMA's PRIME designation streamlines European centralized assessment for therapies addressing unmet rare disease needs, with rolling review mechanisms allowing data package submission before complete dossier finalization. Manufacturers gain scientific advice continuity and accelerated rapporteur assignment, compressing regulatory preparation timelines. France, Germany, and Italy demonstrate highest PRIME utilization for hepatic porphyria candidates, reflecting established orphan disease infrastructure.
Patient advocacy organizations are reshaping trial design through direct engagement in endpoint selection and site selection criteria. The American Porphyria Foundation and European Porphyria Network influence protocol feasibility assessments, prioritizing home-based monitoring over clinic visits. This behavioral shift is most pronounced in the United States and United Kingdom, where foundation-sponsored registries provide natural history comparators enabling single-arm trial designs.
Acute Hepatic Porphyria (APH) Market Segmentation
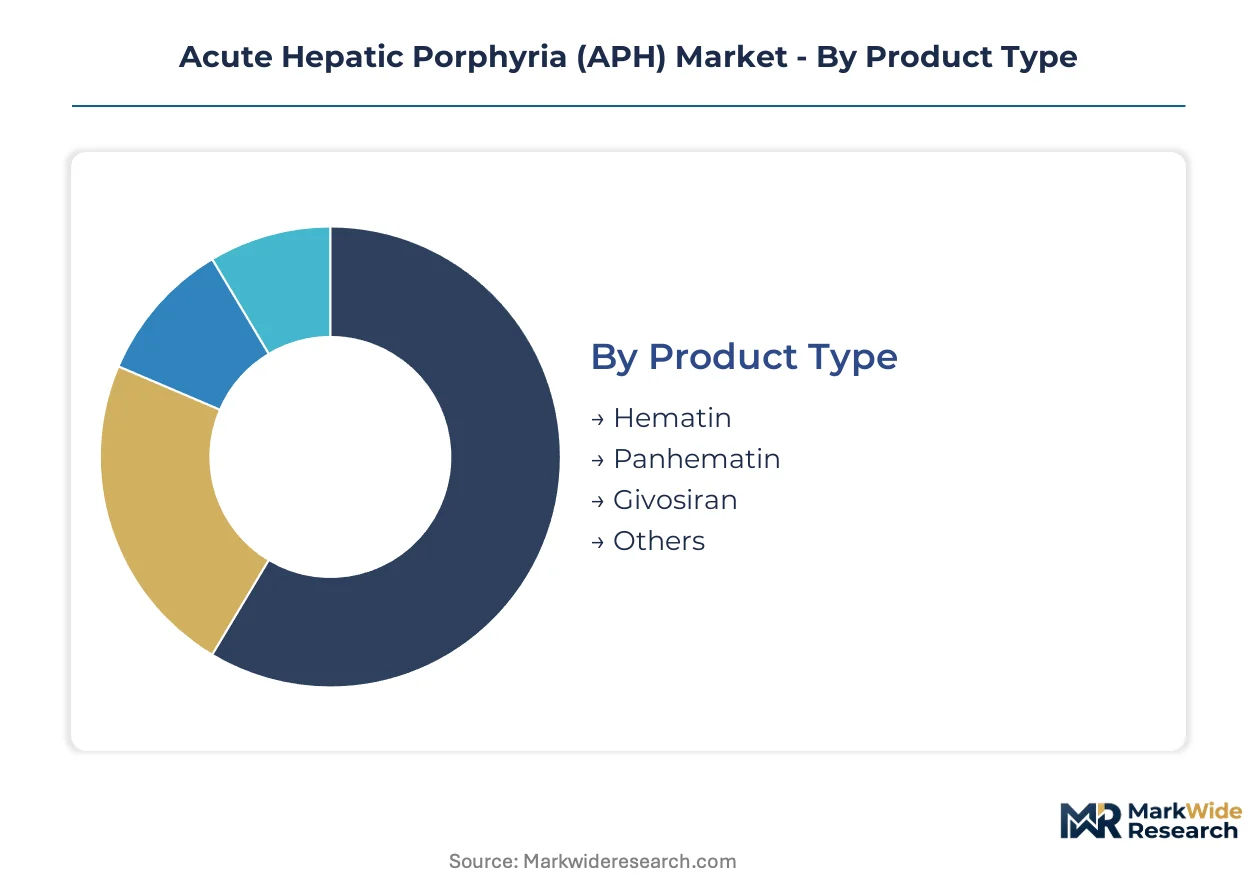
APH treatment segmentation reflects a market pivoting from acute rescue interventions toward preventive and patient-managed modalities. Procurement teams now evaluate categories through total cost-of-care lenses rather than per-dose acquisition metrics.
Product Type:
Standardized plasma-derived formulations dominate hospital formularies, while precision-engineered RNAi therapeutics command premium positioning through differentiated mechanism-of-action claims.
- Hematin:Lyophilized hematin hydroxide derived from pooled human plasma serves as the reference standard for acute attack termination. United States tertiary centers maintain this as first-line rescue therapy despite supply vulnerability from fractionation concentration.
- Givosiran:Subcutaneously administered small interfering RNA reduces hepatic ALAS1 expression, cutting attack frequency in prophylactic protocols. Specialty clinics in Germany and the United States are consolidating this into maintenance regimens as manufacturing scale stabilizes.
- Panhematin:Stabilized hematin formulation with albumin carrier improves solubility profiles for rapid intravenous reconstitution.
- Others:Investigational porphobilinogen deaminase replacement biologics and liver-targeted gene correction vectors.
Most installed capacity flows through Hematin. Expansion is steepest in Givosiran.
Therapy Area:
Reimbursement pathways diverge sharply between curative intent and chronic management philosophies across major markets.
- Gene Therapy:Programmable nuclease platforms target liver-directed HMBS gene correction for definitive disease modification. Preclinical programs concentrate in Boston and Basel biotech clusters with FDA breakthrough therapy designations accelerating IND timelines.
- Enzyme Replacement Therapy:Recombinant porphobilinogen deaminase formulations address underlying enzymopathy through protein supplementation. Manufacturing complexity limits current supply to investigator-initiated protocols.
- Supportive Care:Intravenous glucose loading, analgesic protocols, and seizure management for acute neurovisceral presentations.
- Others:Hemin prophylaxis and experimental liver transplantation for refractory cases.
Commercial revenue concentrates in Enzyme Replacement Therapy. Pipeline investment is densest in Gene Therapy.
Delivery Mode:
Administration setting requirements create distinct margin profiles and patient access barriers across configuration categories.
- Subcutaneous:Patient-administered injection formats eliminate infusion center dependency and enable community-based specialty clinic expansion. Home nursing networks in the United States are building administration support capacity for these platforms.
- Intravenous:Hospital-confined administration demands hematology-oncology nursing oversight and prolonged observation periods. European centers maintain this as standard-of-care for acute presentations due to established pharmacy infrastructure.
- Oral:Small-molecule prophylactic candidates in Phase II development target hepatic ALAS modulation without injection burden.
- Others:Implantable depot formulations and inhaled delivery systems in preclinical evaluation.
Volume share remains anchored in Intravenous. Patient preference is shifting fastest toward Subcutaneous.
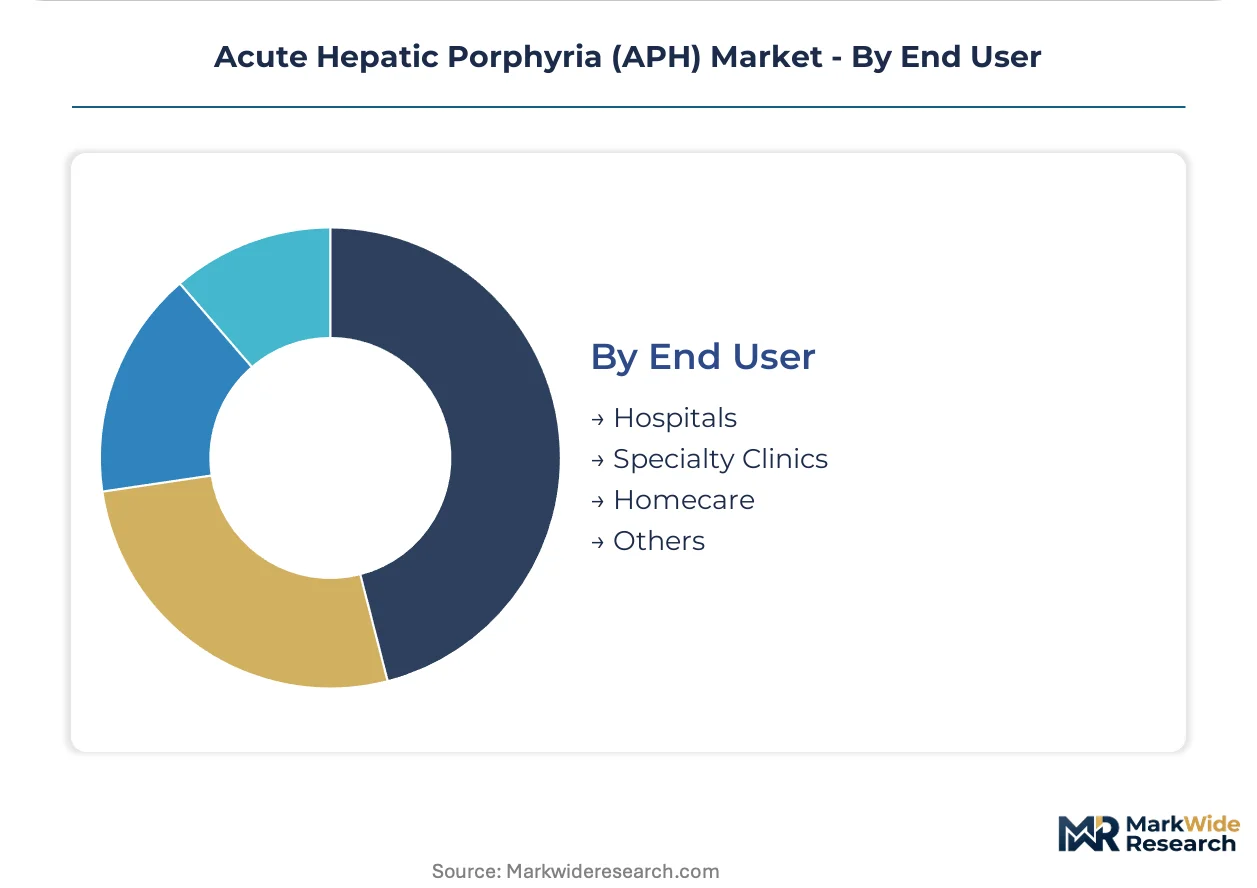
End User:
Site-of-care economics and prior authorization complexity fragment addressable populations across institutional settings.
- Specialty Clinics:Dedicated porphyria centers coordinate genetic counseling, attack prevention, and acute management through multidisciplinary protocols. United States academic medical centers anchor regional referral networks with established natural history registries.
- Hospitals:Emergency departments and inpatient services manage undifferentiated neurovisceral presentations before diagnostic confirmation. Diagnostic latency funnels patients through gastroenterology and neurology services before porphyria identification.
- Homecare:Specialty pharmacy networks administer subcutaneous formulations with remote monitoring support.
- Others:Telemedicine platforms and mobile infusion services.
Diagnostic encounters originate in Hospitals. Prophylactic therapy administration is consolidating in Specialty Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acute Hepatic Porphyria therapeutic development traces its commercial roots to hematin formulations pioneered in United States academic medical centers during the 1970s, with subsequent RNAi innovation concentrated in Boston and Basel biotech clusters.
United States
FDA breakthrough therapy designations accelerate clinical timelines for RNAi candidates targeting hepatic ALAS1 modulation. The American Porphyria Foundation maintains patient registries that enable single-arm trial designs through natural history comparators. Massachusetts hosts the densest concentration of gene therapy preclinical programs, with CRISPR-based HMBS correction advancing through IND-enabling studies.
Germany
EMA PRIME designation utilization for hepatic porphyria candidates concentrates in France, Germany, and Italy, with German centers leading subcutaneous adoption curves. The country's statutory health insurance funds negotiate outcome-based reimbursement for orphan drugs through AMNOG assessments. Heidelberg and Munich anchor European natural history registry coordination, feeding centralized HTA evidentiary requirements.
United Kingdom
NICE technology appraisals for ultra-rare conditions increasingly accept real-world evidence from foundation-sponsored registries. The British Porphyria Association influences trial design feasibility assessments, prioritizing home-based monitoring protocols. London's tertiary centers maintain referral networks spanning the Commonwealth, capturing diagnostic encounters that fragment across gastroenterology and neurology services.
Japan
PMDA orphan drug designation provides tax incentives and priority review vouchers for hepatic enzyme regulation therapies. Mitsubishi Tanabe Pharma Corporation anchors domestic manufacturing capacity for plasma-derived formulations. Tokyo and Osaka academic medical centers coordinate regional attack management protocols, with diagnostic latency remaining pronounced due to nonspecific neurovisceral symptom presentation.
Switzerland
Swissmedic's accelerated assessment pathway for rare diseases compresses regulatory timelines for liver-directed gene correction vectors. Basel's biotech cluster hosts concentrated RNAi platform development, with manufacturing scale-up subject to EU Green Deal pharmaceutical sustainability requirements. Geneva's HTA body evaluates single-arm trial packages with heightened evidentiary scrutiny for preventive therapy segments.
Acute Hepatic Porphyria (APH) Market Competitive Landscape
The competitive structure tilts toward platform technology specialists commanding premium positioning through differentiated mechanism-of-action claims. RNAi developers and plasma fractionation incumbents occupy distinct strategic tiers, with gene therapy entrants emerging through preclinical validation. Three archetypes dominate: RNA interference platform holders, established orphan disease distributors, and diversified pharmaceutical manufacturers leveraging manufacturing scale. Competitive moves concentrate on subcutaneous formulation development and real-world evidence generation for HTA submissions.
Within the platform technology tier, Alnylam Pharmaceuticals, Inc. exemplifies RNAi specialization through hepatic enzyme regulation focus, while Recordati Rare Diseases occupies a position anchored in European orphan disease distribution infrastructure. Pfizer Inc. represents diversified manufacturing scale across delivery modalities. These three entities collectively illustrate the competitive tension between precision mechanism innovation and established channel access.
| Leading Market Players |
|---|
| Alnylam Pharmaceuticals, Inc. |
| Recordati Rare Diseases |
| Pfizer Inc. |
| Takeda Pharmaceutical Company Limited |
| Sanofi |
| Mitsubishi Tanabe Pharma Corporation |
| Teva Pharmaceutical Industries Ltd. |
| Ipsen Pharma |
| Lundbeck Inc. |
| Others |
Value Network & Pricing Analysis
Plasma fractionation capacity in the United States and Germany feeds directly into hematin pricing tiers, with pooled human plasma input costs cascading through stabilized formulation premiums to hospital procurement teams evaluating total cost-of-care protocols.
Pricing Analysis
Subscription-based prophylactic pricing for RNAi therapeutics commands premium positioning against acute rescue per-dose models, with differentiation anchored in mechanism-of-action novelty and administration setting convenience. Certification through FDA breakthrough therapy designation and EMA PRIME status separates premium-tier entrants from standard plasma-derived alternatives. Pricing pressure stems from pharmacy benefit manager prior authorization requirements extending therapy initiation timelines. Community specialty clinics exhibit highest price sensitivity due to constrained formulary budgets, while academic medical centers demonstrate lowest sensitivity given established orphan disease infrastructure and natural history registry participation.
Supply Chain Analysis
Direct-to-hospital channels handle acute hematin demand through centralized pharmacy procurement, while specialty pharmacy networks manage subcutaneous RNAi distribution to homecare settings. Plasma fractionation concentrates in the United States, Germany, and Japan, with manufacturing anchored in fractionated human plasma, albumin carriers, and lyophilization excipients. Single-source vulnerability pervades the plasma supply base, subject to viral safety screening constraints and donor pool fluctuations. Distribution runs through hospital outpatient departments for intravenous formulations and home nursing networks for patient-administered alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in subcutaneous delivery transitions that compress hospitalization burden while enabling premium pricing capture, with gene therapy manufacturing scale-up representing the dominant cost-down trajectory over the analysis window.
For Market Incumbents: Extend RNAi platform leadership through liver-directed formulation optimization and real-world evidence generation for HTA submissions, defending against CRISPR-based gene therapy entrants by accelerating pediatric indication expansion and securing outcome-based reimbursement contracts with German statutory health insurance funds. For New Entrants and Emerging Players: Enter via biomarker-guided prevention segments targeting ALA and PBG quantification protocols, exploiting diagnostic latency white space in Japan and the United Kingdom where mean diagnostic delay fragments addressable market, with go-to-market positioning anchored in attack prediction algorithms and remote monitoring partnerships. For Investors and Strategic Acquirers: Consolidation pressure builds where plasma-derived manufacturing scale intersects with RNAi platform technology scarcity, positioning vertically integrated mid-cap specialists with European orphan disease distribution infrastructure as acquisition targets over the five-to-ten year viability window, with FDA gene therapy IND approval velocity serving as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Patient-administered RNAi platforms displace hospital-based intravenous administration in United States specialty clinics. |
| Real-World Evidence Generation | Foundation-sponsored registries enable single-arm trial designs through natural history comparators for FDA submissions. |
| Gene Therapy Manufacturing Scale-Up | CRISPR-based HMBS correction programs in Boston and Basel clusters advance through IND-enabling studies. |
| Outcome-Based Reimbursement Contracts | German AMNOG assessments negotiate value-based pricing for orphan drugs through attack frequency reduction metrics. |
| Diagnostic Latency Reduction Programs | Multidisciplinary protocols in emergency departments shorten mean diagnostic delay from gastroenterology misrouting. |
Research Methodology
Coverage spans the United States, Germany, the United Kingdom, Japan, and Switzerland, with primary inputs from each market combining interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases, employing bottom-up patient population sizing and top-down revenue triangulation.
Granularity-level modeling addresses treatment line, delivery mode, therapy area, and regional regulatory cluster dimensions across the projection horizon, with CAGRs derived from segment-level growth rate synthesis and convergence testing against macroeconomic healthcare expenditure trends, incorporating attack frequency epidemiology, diagnostic latency assumptions, and subcutaneous adoption curves as industry-specific forecast inputs.
Inputs from foundation-sponsored registries and HTA body evidentiary guidelines were available through the study window; gaps in long-term gene therapy durability data introduce uncertainty bands around curative intent therapy forecasts, with periodic stress-testing of base assumptions recommended given evolving FDA real-world evidence acceptance criteria and EMA PRIME designation utilization patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Liver Cancer Therapeutics Market
Specialty Medicine
Nuclear Medicine Therapeutics Market
Specialty Medicine
Middle East and Africa Primary Angle-Closure Glaucoma Market
Specialty Medicine
Advance Renal Cell Carcinoma Therapeutics Market
Specialty Medicine
Generalized Anxiety Disorder (GAD) Market
Specialty Medicine
Perennial Allergic Rhinitis Market
Specialty Medicine
Global Pemphigus Vulgaris Market
Specialty Medicine
Sex Cord-Gonadal Stromal Tumor Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
North America Alopecia Market
Specialty Medicine
Acute Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Eosinophilic Granulomatosis Market
Specialty Medicine
Premenstrual Dysphoric Disorder Market
Specialty Medicine
Americas Gerd and Nerd Treatment Market
Specialty Medicine
Piriformis Syndrome Treatment Market
Specialty Medicine
Atopic Dermatitis Market