
 Global Dry Eye Syndrome Treatment Market | 2026-2036
Global Dry Eye Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dry Eye Syndrome Treatment Market Foresight
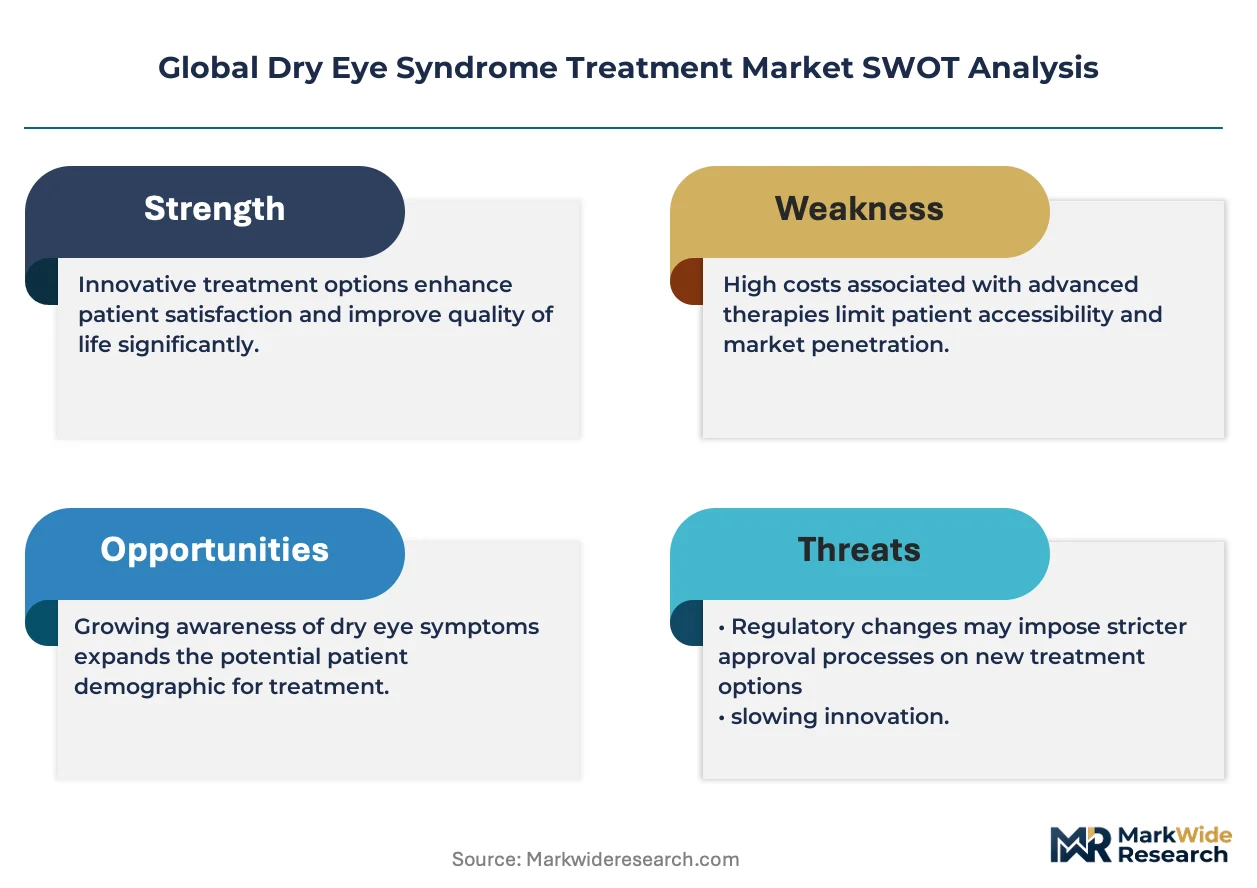
The EU Green Deal's pharmaceutical sustainability criteria is rebalancing procurement priorities across European hospital networks. Novartis AG leverages its integrated ophthalmology pipeline to sustain leadership in immunomodulator development. Alcon Inc. anchors its competitive position through manufacturing scale across multiple delivery modes. Santen Pharmaceutical Co. Ltd. specializes in advanced aqueous formulations for the Japanese market.
Dry eye syndrome treatment encompasses pharmaceutical and device-based interventions formulated to restore tear film stability, reduce ocular surface inflammation, and preserve corneal epithelial integrity through mechanisms including aqueous supplementation, lipid layer stabilization, and mucin secretagogue activity. Artificial tears and anti-inflammatory agents occupy the largest current revenue share, though immunomodulators represent the fastest-expanding margin pool due to chronic disease management protocols. Ophthalmology clinics and specialty eye hospitals dominate the end-user channel, while telemedicine providers are capturing follow-up prescription volumes through remote monitoring integrations.
FDA, EMA, and Japan's PMDA enforce divergent efficacy endpoints and labeling requirements that fragment development timelines and commercialization strategies across major markets. The EU MDR and updated FDA guidance on preservative-free formulations are reshaping manufacturing standards and packaging specifications. Stakeholders must monitor regulatory divergence on sustained-release delivery technologies to align R&D investments with market access timelines.
Market Dynamics
EU MDR and FDA device classification convergence is forcing manufacturers to consolidate clinical evidence portfolios across ophthalmology markets. Prescription protocols for chronic immunomodulator therapies are tightening documentation requirements for tear film biomarker endpoints.
Growth Catalysts
- Aging Demographics:Ophthalmology clinics in Japan, Germany, and the United States are expanding chronic disease management protocols for evaporative dry eye subtypes. Patient volumes in specialty eye hospitals are accelerating prescription renewals for aqueous-deficient cases.
- Preservative-Free Mandates:FDA guidance on benzalkonium chloride elimination is driving reformulation investments across multi-dose packaging lines. Manufacturers are redesigning delivery systems to meet stability requirements without traditional antimicrobial agents.
- Telemedicine Integration:Remote monitoring platforms are capturing follow-up prescription volumes through digital slit-lamp imaging and automated symptom scoring algorithms.
Market Restraints
- API Supply Concentration:Cyclosporine and lifitegrast active pharmaceutical ingredients concentrate among contract manufacturers in India and China, creating single-source vulnerability for immunomodulator production.
- Clinical Trial Cost Escalation:EMA and PMDA divergence on corneal staining endpoints fragments Phase III design, extending development timelines for sustained-release formulations.
- Generic Artificial Tear Substitution:Unpreserved single-use vials from regional manufacturers are compressing margin pools in the largest volume segment of the treatment hierarchy.
Strategic Opportunities
- Underpenetrated Markets:Brazil and Mexico present expansion pathways where ophthalmology infrastructure is maturing and private insurance coverage for immunomodulators is expanding.
- Nanoparticle Delivery Convergence:Lipid-based carriers combined with mucoadhesive polymers are enabling extended residence time on the ocular surface for corticosteroid-sparing protocols.
- EU Green Deal Procurement:Hospital networks in France and the Netherlands are prioritizing suppliers with validated carbon footprint reductions across packaging and logistics chains.
Industry Challenges
- Ocular Surface Specialist Shortage:Fellowship-trained cornea specialists capable of interpreting interferometry and meibography outputs remain concentrated in urban academic centers.
- Legacy Device Integration:New diagnostic platforms must interface with existing electronic health record systems in ophthalmology clinics, creating implementation friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dry Eye Syndrome Treatment Market |
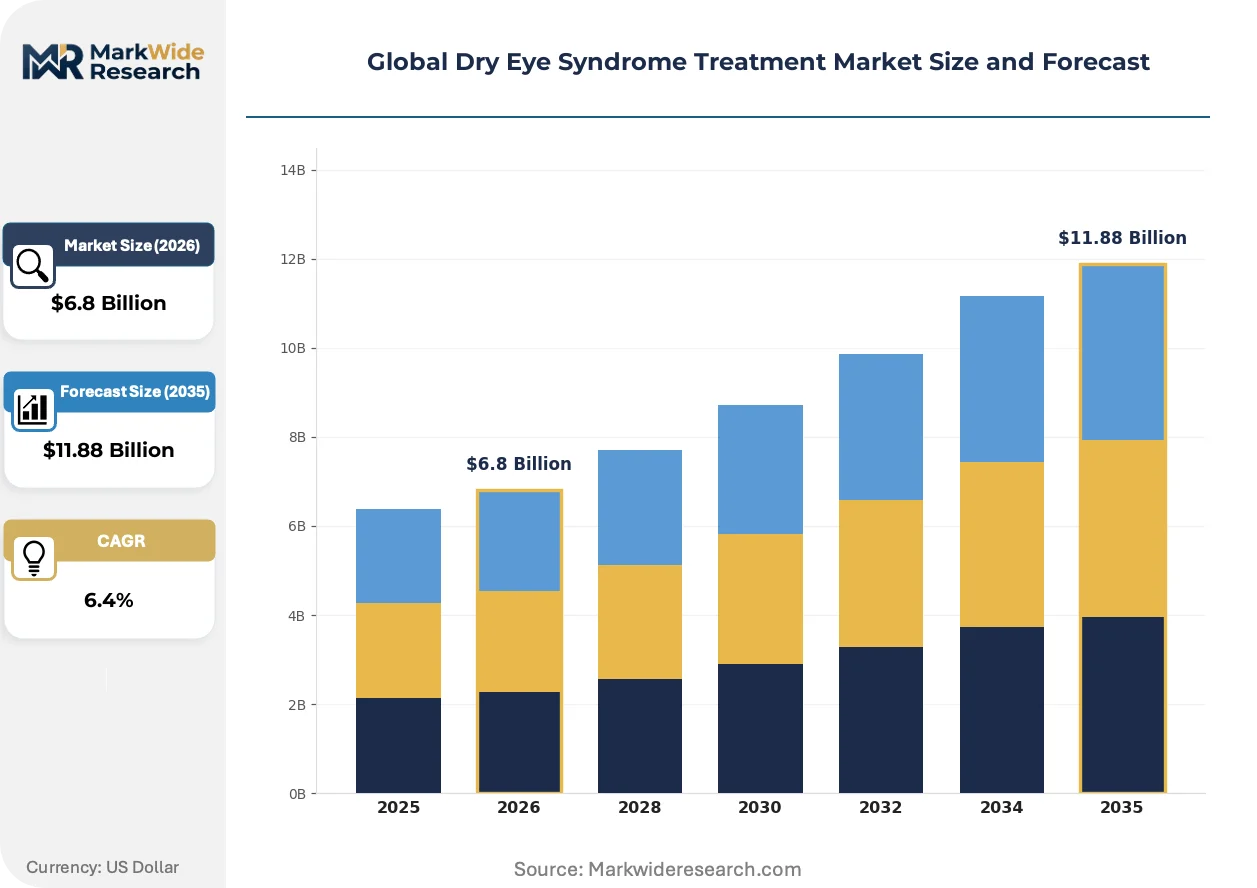
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artificial Tears, Anti-inflammatory Agents, Immunomodulators, Punctal Plugs, Nutritional Supplements Therapy Area: Aqueous Deficient Dry Eye, Evaporative Dry Eye, Mixed Dry Eye, Cicatricial Dry Eye End User: Ophthalmology Clinics, Specialty Eye Hospitals, Ambulatory Surgery Centers, Telemedicine Providers Delivery Mode: Eye Drops, Ointments, Gels, Oral Medications, Injections |
| Companies Covered | AbbVie Inc., Novartis AG, Alcon Inc., Santen Pharmaceutical Co. Ltd., Sun Pharmaceutical Industries Ltd., Johnson & Johnson Services Inc., Bausch Health Companies Inc., Otsuka Pharmaceutical Co. Ltd., Novaliq GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dry Eye Syndrome Treatment Market Shifts & Advancements
Sustained-release delivery technologies are compressing dosing frequencies from four times daily to monthly or quarterly intervals. Manufacturing scale-up for these platforms is reshaping competitive positioning across the value chain.
Intracanalicular inserts and punctal plug reservoirs are overtaking conventional drop therapy in moderate-to-severe disease segments. Specialty eye hospitals in the United States are adopting these platforms for patients with compliance barriers. The shift is enabling premium pricing for chronic management while reducing pharmacy benefit manager friction.
Japan's PMDA has implemented post-market surveillance requirements for novel ocular surface devices that exceed FDA predicate validation standards. Manufacturers targeting simultaneous East Asian and North American launches must design parallel clinical programs. The regulation is compressing first-mover advantages for companies with legacy 510(k) clearance pathways.
Patient self-triage through smartphone-based tear film osmolarity estimators is disrupting traditional referral channels. Telemedicine providers are capturing initial diagnosis volumes that previously flowed to general ophthalmology practices. The pattern is most visible in metropolitan United States markets where direct-to-consumer advertising for prescription immunomodulators is permitted.
Global Dry Eye Syndrome Treatment Market Segmentation
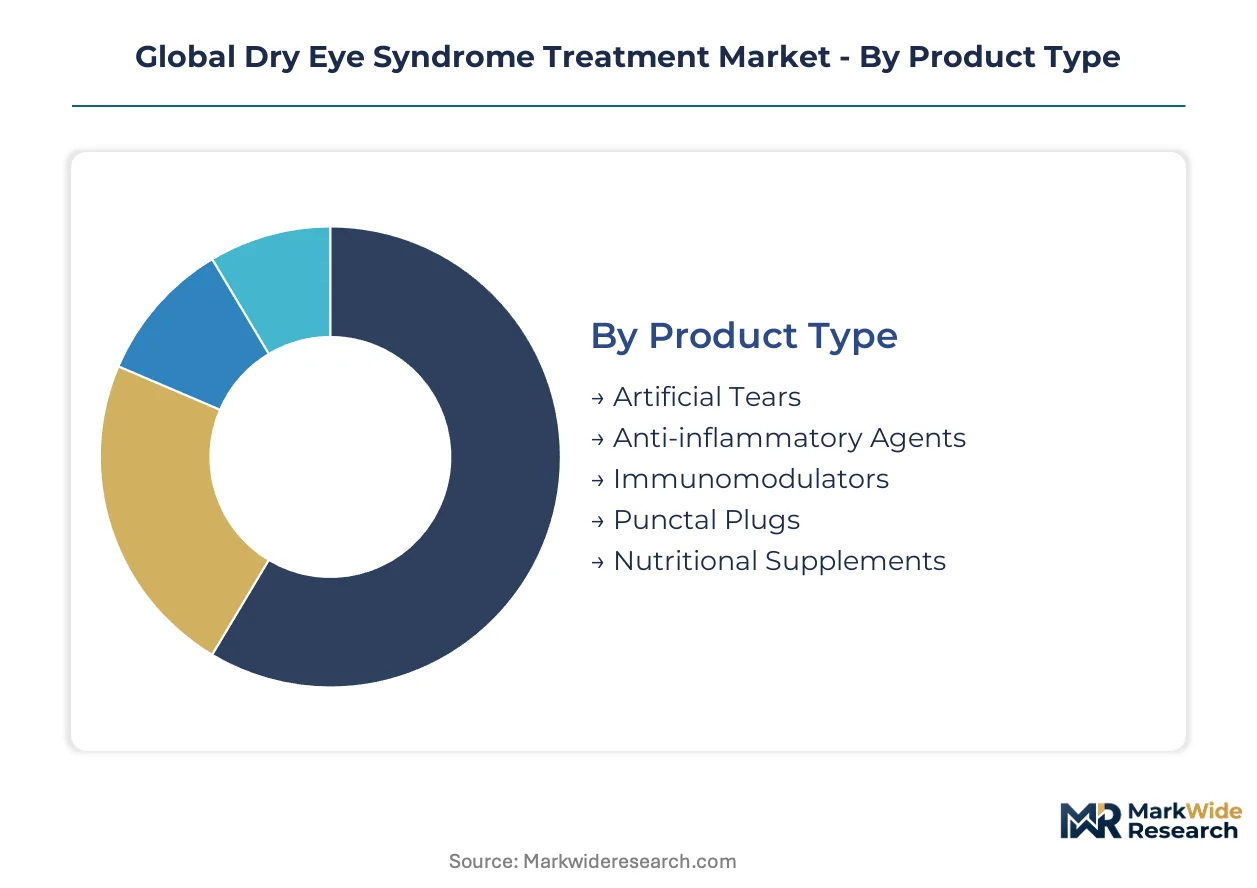
Dry eye syndrome treatment segments fragment across therapeutic mechanism, disease etiology, and care setting. Procurement patterns diverge sharply between chronic immunomodulator prescriptions and acute symptomatic relief, while reimbursement pathways reshape volume distribution across delivery technologies.
Product Type:
Standalone pharmaceutical formulations dominate prescription volumes, while embedded device-drug combinations command premium positioning in specialty settings.
- Artificial Tears:Polymer-based aqueous solutions and lipid emulsions provide immediate tear film stabilization without pharmacological activity. Demand clusters in Germany and the United States where over-the-counter availability supports high-frequency replenishment cycles.
- Anti-inflammatory Agents:Corticosteroid and non-steroidal formulations target ocular surface inflammation in moderate disease stages. Japanese ophthalmology clinics favor short-pulse protocols that minimize intraocular pressure elevation risks.
- Immunomodulators:Cyclosporine and lifitegrast formulations interrupt T-cell mediated inflammation in chronic cases.
- Punctal Plugs:Silicone and collagen-based inserts block tear drainage to preserve natural lubrication.
- Nutritional Supplements:Omega-3 fatty acid formulations support meibomian gland function from systemic administration.
Volume placements concentrate in artificial tears; the faster expansion belongs to immunomodulators.
Therapy Area:
Cost-tier stratification separates acute symptomatic management from chronic disease modification protocols.
- Aqueous Deficient Dry Eye:Lacrimal gland dysfunction drives prescription immunomodulator uptake in United States specialty eye hospitals. Sjögren's syndrome patients generate the highest lifetime value per treated individual.
- Evaporative Dry Eye:Meibomian gland dysfunction predominates in aging populations across Japan and Germany. Thermal pulsation devices and lipid-based artificial tears capture procedure-based revenue streams.
- Mixed Dry Eye:Combined aqueous and lipid deficiency requires multimodal therapy sequencing.
- Cicatricial Dry Eye:Ocular surface scarring from autoimmune or chemical injury demands surgical intervention alongside pharmaceutical management.
Procedure volumes favor evaporative presentations; the steepest expansion trajectory sits with mixed etiology diagnoses as diagnostic precision improves.
End User:
Customer-type concentration shifts prescription authority from institutional settings to distributed care models.
- Ophthalmology Clinics:Private practice settings in the United States and Germany generate the majority of immunomodulator initiations. Cornea specialists control formulary decisions through direct patient relationships.
- Specialty Eye Hospitals:Academic medical centers in Japan and the United States manage severe refractory cases with punctal plug and sustained-release device implantation.
- Ambulatory Surgery Centers:Procedure-based revenue from thermal pulsation and intense pulsed light therapies.
- Telemedicine Providers:Digital platforms capture artificial tear renewals and follow-up prescriptions through remote monitoring.
Prescription authority concentrates in ophthalmology clinics; telemedicine providers are gaining share fastest in metropolitan United States markets.
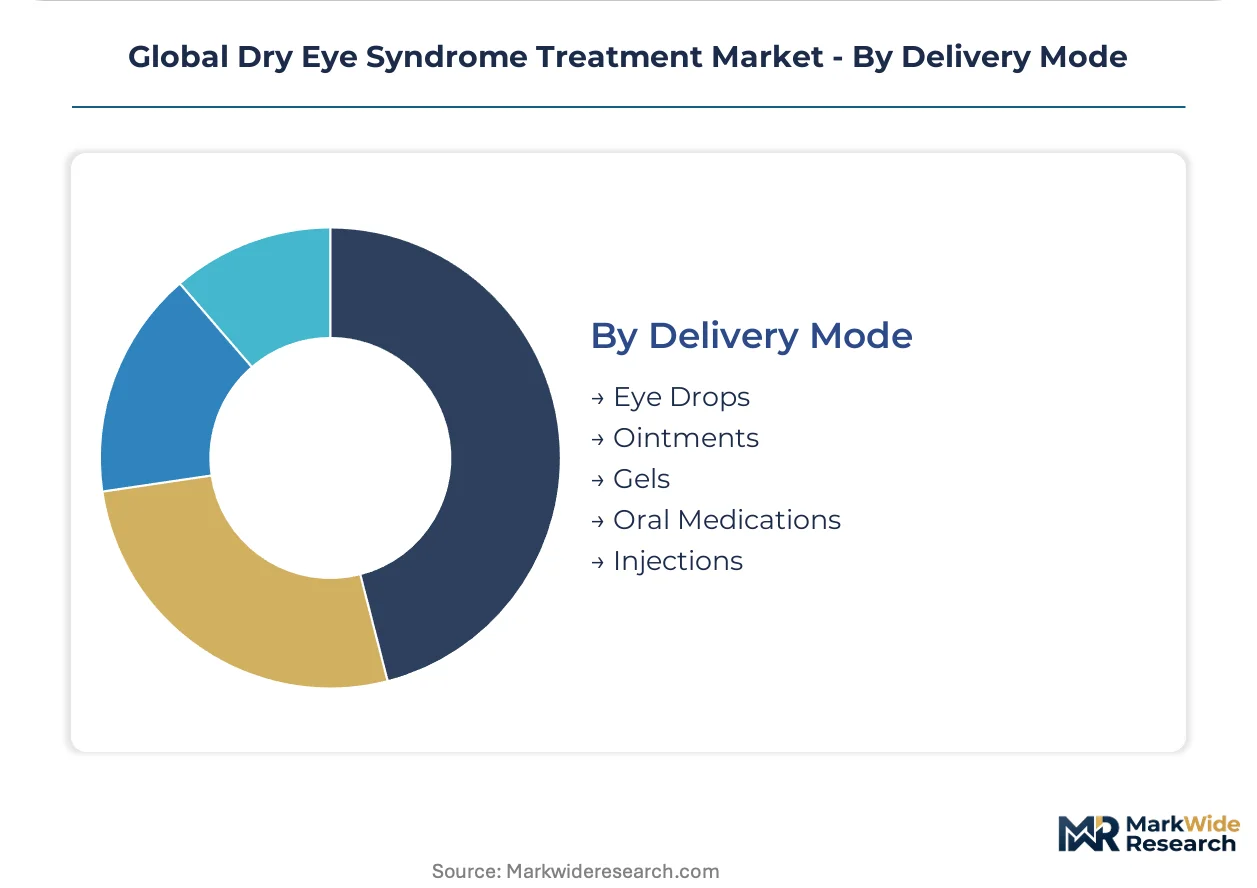
Delivery Mode:
Application-method maturity separates established topical administration from emerging sustained-release platforms.
- Eye Drops:Multi-dose and single-use vials remain the default administration route across all geographies. Preservative-free formulations command 40-60% price premiums in European markets.
- Ointments:Petrolatum-based nighttime lubricants address severe exposure keratopathy in post-surgical patients.
- Gels:Carbomer and cellulose-based viscous preparations extend residence time for moderate disease.
- Oral Medications:Systemic tetracyclines and omega-3 supplements target meibomian gland dysfunction.
- Injections:Periocular corticosteroid depot formulations manage severe inflammatory flares.
Unit volumes cluster in eye drops; intracanalicular inserts and sustained-release platforms are climbing the fastest toward quarterly dosing intervals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the largest share of prescription immunomodulators while API manufacturing concentrates in India and China. Germany and Japan anchor European and Asian demand for preservative-free formulations. Brazil represents the fastest-expanding access frontier as private insurance coverage broadens.
United States
Specialty eye hospitals in Boston and New York Metro drive sustained-release device adoption for refractory cases. FDA guidance on benzalkonium chloride elimination forces reformulation investments across multi-dose packaging lines. Cornea specialists in urban academic centers control immunomodulator formulary decisions through direct patient relationships.
Germany
Ophthalmology clinics in Bavaria and North Rhine-Westphalia generate high-frequency artificial tear replenishment cycles through over-the-counter availability. EU MDR tightening of clinical evidence requirements extends approval timelines for novel sustained-release platforms. The EU Green Deal's pharmaceutical sustainability criteria rebalances procurement priorities across hospital networks in the Netherlands-bordering regions.
Japan
Aging demographics in Tokyo and Osaka accelerate prescription renewals for evaporative dry eye subtypes. PMDA post-market surveillance requirements for ocular surface devices exceed FDA predicate validation standards. Santen Pharmaceutical anchors advanced aqueous formulation development from its Kansai operational base.
India
Contract manufacturers in Gujarat and Maharashtra concentrate cyclosporine and lifitegrast active pharmaceutical ingredient supply. CDSCO alignment with ICH guidelines streamlines domestic clinical trial approvals for multinational sponsors. Hyderabad and Bangalore clusters support API production scale-up for immunomodulator export markets.
Brazil
Private insurance expansion in São Paulo and Rio de Janeiro opens reimbursement pathways for immunomodulator therapies previously restricted to out-of-pocket payment. ANVISA regulatory convergence with FDA standards accelerates market access timelines for multinational entrants. Specialty eye hospital infrastructure is maturing in southeastern metropolitan corridors.
Global Dry Eye Syndrome Treatment Market Competitive Landscape
The competitive structure tilts toward integrated pharmaceutical conglomerates with ophthalmology-specific divisions. Consolidation among immunomodulator developers contrasts with fragmentation in artificial tear manufacturing. Three archetypes dominate: diversified pharma majors with integrated pipelines, specialized ophthalmology-focused firms, and regional generic manufacturers. Capacity expansion in preservative-free formulation lines and strategic partnerships for sustained-release technology licensing represent the dominant competitive moves.
Among Swiss-based pharmaceutical conglomerates, Novartis AG exemplifies the integrated pipeline archetype through its immunomodulator development focus. Alcon Inc. anchors the device-drug combination tier with manufacturing scale across multiple delivery modes. German specialty pharmaceutical developer Novaliq GmbH occupies a position within the novel formulation archetype, representing sustained-release technology innovation. Japanese ophthalmology specialist Santen Pharmaceutical Co. Ltd. sits within the geographic-focused tier, concentrating advanced aqueous formulations for its domestic market.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Novartis AG |
| Alcon Inc. |
| Santen Pharmaceutical Co. Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Johnson & Johnson Services Inc. |
| Bausch Health Companies Inc. |
| Otsuka Pharmaceutical Co. Ltd. |
| Novaliq GmbH |
| Others |
Supply & Pricing Matrix
The EU Green Deal's pharmaceutical sustainability criteria gates qualified supply and premium-tier pricing access, as manufacturers lacking validated carbon footprint reductions across packaging and logistics chains face exclusion from hospital network procurement in France and the Netherlands. This environmental mandate compresses margin pools for non-compliant suppliers while enabling 40-60% price premiums for preservative-free formulations that meet stability requirements without traditional antimicrobial agents.
Pricing Analysis
Outcome-based pricing anchors immunomodulator contracts to tear film biomarker endpoint achievement, with cyclosporine and lifitegrast formulations commanding premium positioning through chronic disease management protocols. Price differentiation separates preservative-free multi-dose lines from benzalkonium chloride-containing alternatives, with certification tier and geographic delivery cost as secondary drivers. Cost compression in artificial tears intensifies as unpreserved single-use vials from regional manufacturers displace branded equivalents. Pharmacy benefit managers exhibit highest price sensitivity for chronic prescription renewals, while specialty eye hospitals demonstrate lowest sensitivity for sustained-release device implantation.
Supply Chain Analysis
India's PLI scheme for active pharmaceutical ingredients and China's dominance in contract manufacturing reshape sourcing patterns for cyclosporine and lifitegrast production. API supply concentrates in Gujarat and Maharashtra clusters, with lipid-based carriers and mucoadhesive polymers as critical formulation inputs. Single-source vulnerability for immunomodulator production creates structural risk given concentration among contract manufacturers in Hyderabad and Bangalore. Distribution runs through ophthalmology clinic direct purchasing and specialty hospital formulary committees, with telemedicine platforms capturing artificial tear renewals through digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dry eye syndrome treatment market sits in a technology-transition phase as sustained-release delivery platforms displace conventional four-times-daily drop regimens with monthly or quarterly dosing intervals.
For Market Incumbents: Acquire sustained-release technology licensing portfolios to defend against intracanalicular insert and punctal plug reservoir substitution threatening conventional drop therapy revenue streams. Backward integration into preservative-free formulation manufacturing secures supply chain control against API concentration risk in Indian contract manufacturers. Capacity expansion in EU MDR-compliant packaging lines addresses tightening clinical evidence requirements fragmenting commercialization timelines. For New Entrants and Emerging Players: Telemedicine platform partnerships offer the most penetrable channel for artificial tear renewals and follow-up prescription capture in metropolitan United States markets where direct-to-consumer advertising is permitted. Brazil's private insurance expansion in São Paulo and Rio de Janeiro presents white-space access for immunomodulator therapies previously restricted to out-of-pocket payment. Nanoparticle delivery convergence combining lipid-based carriers with mucoadhesive polymers enables differentiated positioning for corticosteroid-sparing protocols. For Investors and Strategic Acquirers: FDA guidance on benzalkonium chloride elimination is the leading indicator that reformulation investment cycles will accelerate across multi-dose packaging lines. The five-to-ten year viability window favors acquisition targets with validated preservative-free stability platforms and EU Green Deal carbon footprint credentials. PMDA post-market surveillance requirement divergence from FDA standards signals regulatory arbitrage opportunities for parallel clinical program design capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Preservative-Free Reformulation | FDA guidance on benzalkonium chloride elimination forces manufacturing line redesigns across multi-dose portfolios. |
| Sustained-Release Technology Licensing | Quarterly dosing interval platforms command premium positioning in specialty eye hospital procurement. |
| EU MDR Clinical Evidence Consolidation | Converged trial designs reduce fragmentation between European and North American approval pathways. |
| Telemedicine Platform Integration | Remote monitoring captures prescription renewals previously flowing to general ophthalmology practices. |
| Carbon Footprint Validation | EU Green Deal procurement criteria in France and the Netherlands rebalances hospital network supplier selection. |
Research Methodology
Multi-period observation of prescription immunomodulator uptake rates, tear film biomarker endpoint adoption, and preservative-free formulation penetration anchored the trend analysis, supplemented by interviews with ophthalmology clinic formulary directors, specialty eye hospital procurement managers, cornea specialists, and regulatory affairs leads at pharmaceutical developers. Secondary validation drew from FDA 510(k) filings, EMA MDR submission databases, PMDA approval records, and ClinicalTrials.gov protocol registrations. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Segment-weighting across therapeutic mechanism, disease etiology, care setting, and delivery mode informed the analytical framework across the projection horizon. Product type splits separated artificial tears, anti-inflammatory agents, immunomodulators, punctal plugs, and nutritional supplements. Therapy area stratification captured aqueous-deficient, evaporative, mixed, and cicatricial presentations. End-user weighting reflected ophthalmology clinic, specialty eye hospital, ambulatory surgery center, and telemedicine provider prescription authority. CAGRs derived from longitudinal prescription volume trajectories and pricing trend analysis, with regulatory approval timeline divergence and reimbursement pathway maturity as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced regulatory guidance revisions, raw material supply disruptions from geopolitical events, and novel diagnostic technology obsolescence effects. Forecasts reflect documented assumptions regarding immunomodulator pipeline advancement rates and sustained-release device adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Myasthenia Gravis Market
Specialty Medicine
Stress Urinary Incontinence Market
Specialty Medicine
Musculoskeletal System Disorders Market
Specialty Medicine
Bipolar Disorder (BPD) Market
Specialty Medicine
Diamond-Blackfan Anemia Syndrome Therapeutics Market
Specialty Medicine
Seasonal Allergy Market
Specialty Medicine
Idiopathic Thrombocytopenic Purpura Therapeutics Market
Specialty Medicine
Medical Foods for Orphan Diseases Market
Specialty Medicine
Global Herpes Market
Specialty Medicine
Overt Hepatic Encephalopathy Market
Specialty Medicine
Adenomyosis Market
Specialty Medicine
Hairy Cell Leukemia Therapeutics Market
Specialty Medicine
APAC Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
North America Dry Eye Syndrome Market
Specialty Medicine
Whipple's Disease Market
Specialty Medicine
Pharyngitis Treatment Market