
 Tinnitus Management Market | 2026-2036
Tinnitus Management Market Size, Share, and Industry Trends Forecast 2026-2036
Tinnitus Management Market Outlook
Audiology center distribution is narrowing as direct-to-consumer channels and teleaudiology platforms gain regulatory traction. Starkey Hearing Technologies leverages its vertically integrated manufacturing footprint across the Midwest to sustain cost advantages in custom-molded sound therapy hardware. GN Hearing A/S competes through its ReSound brand strength in programmable tinnitus masker firmware, while Neuromod Devices Ltd. specializes in bimodal neuromodulation systems that pair tongue stimulation with audio tones.
Tinnitus management encompasses clinical and consumer interventions designed to reduce the perceived severity of phantom auditory sensations through sound masking, neural plasticity modulation, or psychological coping frameworks. Hearing aids with integrated tinnitus masker functionality dominate current volume, as these dual-purpose devices qualify for insurance reimbursement under audiological benefit codes in multiple markets. Cognitive Behavioral Therapy represents the fastest-growing treatment approach segment, driven by digital health platform scalability and mental health parity legislation expanding covered behavioral services. Sound Therapy Devices command premium positioning in home care settings where patients seek non-pharmaceutical nighttime relief without clinical visits.
FDA 510(k) premarket notification requirements govern neuromodulation and sound therapy device commercialization in the United States, while the EU Medical Device Regulation mandates clinical evidence thresholds for tinnitus treatment hardware entering European markets. Japan's PMDA enforces QMS ministerial ordinances that extend approval timelines for novel acoustic stimulation devices, creating compliance cost barriers for smaller manufacturers. Stakeholders must monitor evolving reimbursement coding decisions by CMS and national health technology assessment bodies, as coverage determinations for emerging bimodal therapies will reshape competitive allocation of R&D capital across device and pharmaceutical pipelines.
Market Dynamics
FDA 510(k) clearance pathways for neuromodulation devices are compressing product development timelines while simultaneously elevating clinical evidence requirements, forcing manufacturers to front-load regulatory investment before commercialization.
Growth Catalysts
- Aging demographics:Population cohorts over 65 in the United States, Germany, and Japan are expanding the addressable patient base for hearing health services and reimbursable audiological interventions.
- Mental health parity legislation:Expanded coverage mandates for behavioral health services are accelerating reimbursement access for Cognitive Behavioral Therapy protocols delivered through digital platforms.
- Bimodal neuromodulation:Tongue stimulation paired with audio tone delivery is demonstrating efficacy signals that attract venture capital toward next-generation device development.
Market Restraints
- Regulatory friction:Japan's PMDA QMS ministerial ordinances extend approval timelines for novel acoustic stimulation devices, creating compliance cost barriers for smaller manufacturers seeking market entry.
- Supply concentration:Custom-molded sound therapy hardware production clusters in the Midwest United States, exposing distribution networks to regional logistics disruptions.
- Technical limitation:Tinnitus heterogeneity—varying pitch, loudness, and etiology—constrains standardized treatment protocols and complicates clinical trial endpoint design.
Strategic Opportunities
- Teleaudiology platforms:Direct-to-consumer channels are gaining regulatory traction, enabling remote fitting and programming of tinnitus masker firmware without clinic-based encounters.
- EU Medical Device Regulation:MDR clinical evidence thresholds, while stringent, create competitive moats for manufacturers with robust quality management systems and post-market surveillance infrastructure.
- Home care sound therapy:Non-pharmaceutical nighttime relief devices represent underpenetrated white space where patients seek clinical-grade outcomes without recurring appointment burdens.
Industry Challenges
- Audiologist workforce constraints:Specialized fitting expertise for integrated hearing aid and tinnitus masker systems faces supply bottlenecks in rural and underserved metropolitan areas.
- Reimbursement coding volatility:CMS coverage determinations for emerging bimodal therapies remain unsettled, forcing manufacturers to maintain dual commercialization strategies for cash-pay and insurance channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tinnitus Management Market |
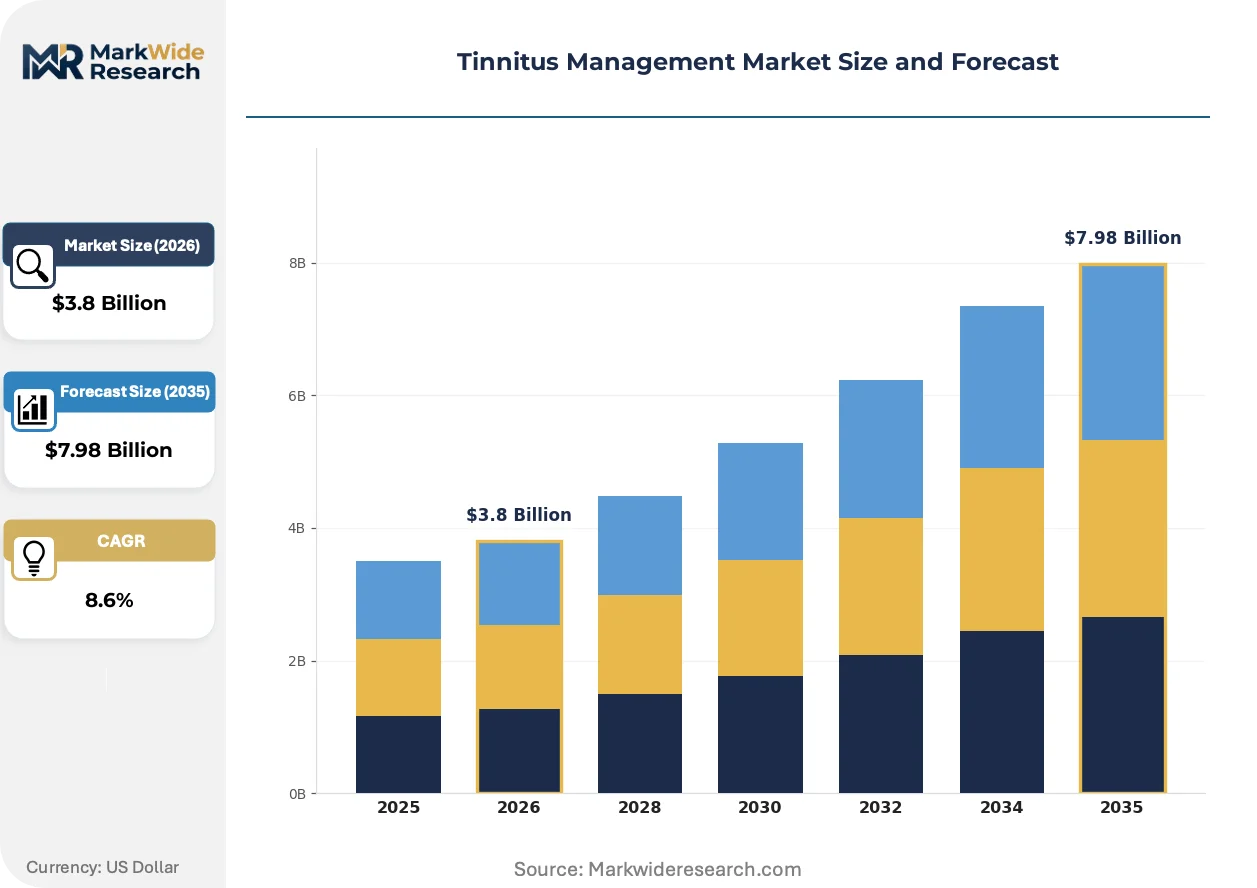
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sound Therapy Devices, Hearing Aids, Acoustic Coordinators, Maskers Treatment Approach: Cognitive Behavioral Therapy, Mindfulness Techniques, Tinnitus Retraining Therapy, Medication End User: Hospitals, Clinics, Audiology Centers, Home Care Distribution Channel: Online Retail, Direct Sales, Pharmacies, Medical Supply Stores |
| Companies Covered | Starkey Hearing Technologies, GN Hearing A/S, Neuromod Devices Ltd., Widex A/S, Oticon Inc., Neuromonics Inc., Puretone Ltd., Signia, Sivantos Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tinnitus Management Market Strategic Shifts
Neuromodulation hardware is converging with software-defined audio processing, enabling personalized stimulation protocols that adapt to patient-reported outcome data in real time.
Bimodal stimulation systems are hybridizing conventional acoustic delivery with somatosensory tongue electrodes to modulate neural plasticity through coordinated sensory pathways. ENT clinics and academic medical centers are piloting these configurations for treatment-resistant chronic tinnitus patients. This convergence is compressing the traditional boundary between implantable neurostimulation and external sound therapy hardware categories.
Europe's MDR framework is mandating clinical performance studies for tinnitus treatment devices that previously qualified under self-certification routes, extending time-to-market for novel hardware introductions. Manufacturers with legacy CE-marked portfolios face retrospective compliance obligations that divert R&D resources toward regulatory remediation. German notified bodies are experiencing backlogs that disproportionately affect small-cap developers lacking dedicated regulatory affairs functions.
Patients are migrating toward subscription-based digital health platforms that bundle tinnitus coping tools with remote audiologist consultations, displacing traditional device-centric purchase models. This behavioral shift concentrates lifetime value capture in software and service layers rather than hardware margins. The United States exhibits the most pronounced channel migration, where mental health parity coverage reduces out-of-pocket friction for platform-based behavioral interventions.
Tinnitus Management Market Segmentation
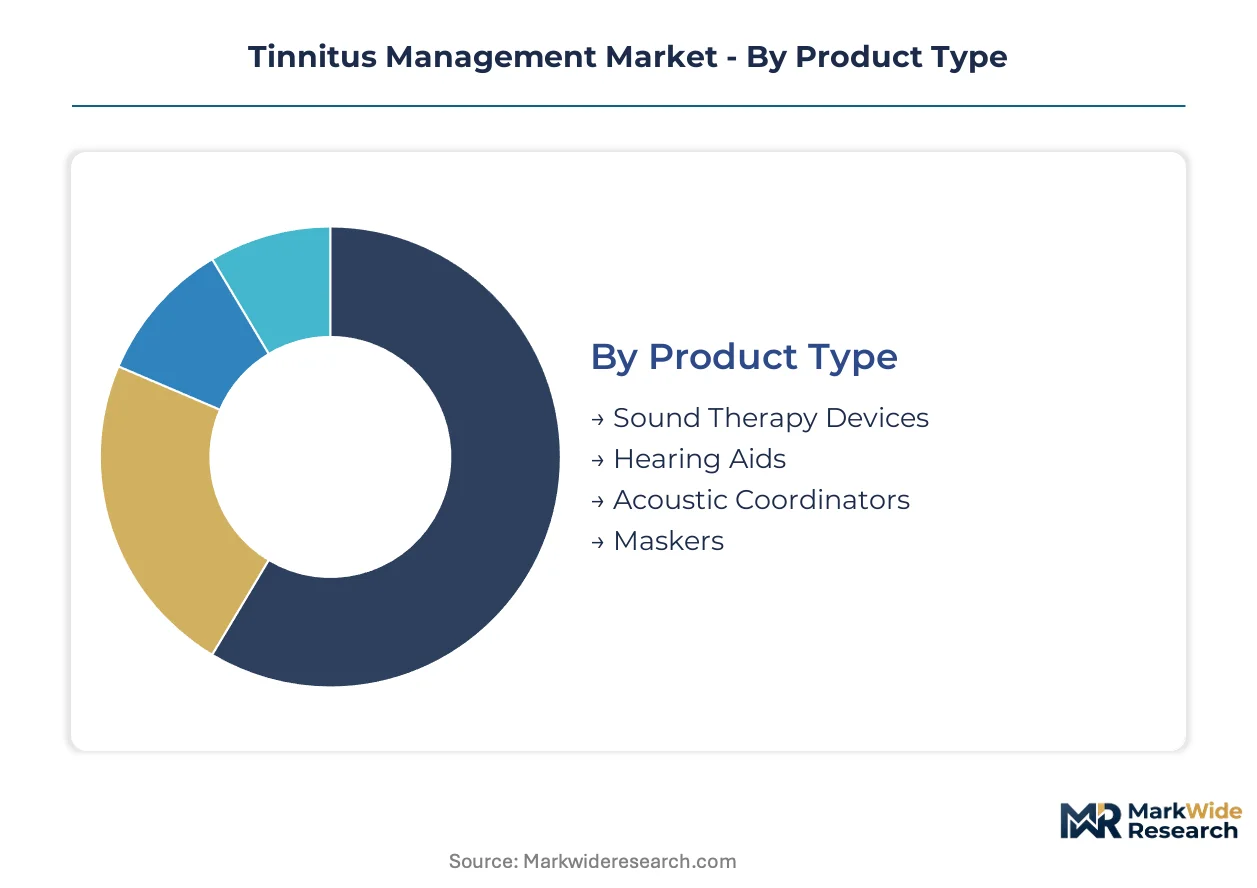
Segmentation in tinnitus management reveals distinct service intensity profiles across hardware and therapeutic modalities. Product categories demand varying levels of audiologist support for fitting and calibration, while treatment approaches diverge sharply in their reliance on clinical infrastructure versus self-directed patient engagement.
Product Type:
After-sales service intensity varies dramatically across hardware categories, with programmable devices requiring recurring firmware updates and acoustic calibration that reshape vendor-customer relationships.
- Hearing Aids:Dual-purpose instruments integrate tinnitus masker functionality with amplification, qualifying for audiological benefit codes in the United States and Germany. Demand concentrates in ENT clinics and audiology centers where reimbursement coverage reduces patient out-of-pocket burden for programmable hardware.
- Sound Therapy Devices:Standalone acoustic delivery systems generate premium positioning in home care settings through non-pharmaceutical nighttime relief protocols. Patient preference for clinical-grade outcomes without recurring appointments drives adoption in Japan and the United States where aging demographics expand the addressable base.
- Acoustic Coordinators:Multi-channel audio processing hardware synchronizes environmental sound masking with personalized frequency modulation.
- Maskers:Simplified tone generators provide baseline sound enrichment for cost-sensitive patient segments.
Hearing Aids holds the largest share; momentum sits with Sound Therapy Devices.
Treatment Approach:
Cost tier stratification separates reimbursed clinical protocols from cash-pay digital platforms, creating divergent margin structures across therapeutic categories.
- Cognitive Behavioral Therapy:Digital health platforms deliver scalable coping frameworks through subscription models, displacing traditional device-centric purchase structures. Mental health parity legislation in the United States accelerates reimbursement access for platform-based behavioral interventions.
- Tinnitus Retraining Therapy:Structured habituation protocols combine directive counseling with low-level sound enrichment, requiring specialized audiologist certification that limits workforce scalability in rural United States markets.
- Mindfulness Techniques:App-guided meditation and stress reduction tools target patient self-efficacy without clinical infrastructure.
- Medication:Off-label pharmaceutical interventions address comorbid anxiety and depression rather than tinnitus perception directly.
Cognitive Behavioral Therapy commands expanding reimbursement access; Tinnitus Retraining Therapy retains entrenched clinical loyalty.
End User:
Volume concentration favors institutional settings where bundled reimbursement and device fitting expertise coexist, though home care channels are gaining regulatory traction for remote programming.
- Audiology Centers:Specialized fitting infrastructure for integrated hearing aid and masker systems generates recurring revenue through follow-up calibration and firmware updates. Workforce constraints in underserved United States metropolitan areas create supply bottlenecks that limit patient throughput.
- Home Care:Direct-to-consumer channels enable remote programming of tinnitus masker firmware without clinic-based encounters, concentrating lifetime value in software and service layers. Teleaudiology platform adoption is climbing fastest in the United States where regulatory frameworks accommodate remote care delivery.
- Hospitals:Academic medical centers pilot bimodal neuromodulation systems for treatment-resistant chronic patients.
- Clinics:ENT practices expand adoption of integrated sound therapy protocols for co-located hearing health services.
Audiology Centers holds the largest share; Home Care is gaining share fastest.
Distribution Channel:
Customer type segmentation separates institutional procurement through direct sales from patient-directed purchasing via retail and digital channels.
- Direct Sales:Manufacturer-employed audiology specialists support high-consideration hearing aid purchases with in-home fitting and ongoing calibration services. Institutional contracts with United States hospital systems and German ENT clinic networks sustain volume concentration.
- Online Retail:Direct-to-consumer platforms bypass traditional audiologist gatekeepers for sound therapy hardware and subscription-based digital interventions. Regulatory traction for remote fitting protocols in the United States enables channel expansion without clinical encounter requirements.
- Medical Supply Stores:Brick-and-mortar retailers serve patients seeking hands-on product demonstration before purchase.
- Pharmacies:Limited role confined to over-the-counter sound masking accessories and supplement adjacencies.
Direct Sales holds the largest share; Online Retail shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 35 corridor through Minnesota and Iowa underwrites North American distribution efficiency for custom-molded sound therapy hardware, connecting Midwest manufacturing clusters to coastal ENT clinic networks.
United States
Aging demographics expand the Medicare-eligible patient base for audiological services across Florida and Arizona retirement corridors. FDA 510(k) premarket notification requirements compress development timelines for neuromodulation devices while elevating clinical evidence thresholds. Starkey Hearing Technologies anchors production in Eden Prairie, Minnesota, leveraging vertically integrated manufacturing to sustain cost advantages in programmable masker hardware.
Germany
Reimbursement coverage for hearing health services under statutory health insurance funds drives ENT clinic adoption of integrated sound therapy protocols. EU Medical Device Regulation mandates clinical performance studies that extend time-to-market for novel acoustic stimulation devices. Berlin and Munich academic medical centers pilot bimodal neuromodulation systems for treatment-resistant chronic tinnitus patients.
Japan
Super-aged society status concentrates demand for home care sound therapy devices among patients seeking nighttime relief without clinical visits. PMDA QMS ministerial ordinances enforce extended approval timelines that create compliance cost barriers for smaller manufacturers. Tokyo and Osaka metropolitan areas concentrate audiology center infrastructure where workforce constraints limit patient throughput.
United Kingdom
NHS England commissioning frameworks for hearing services shape procurement patterns for dual-purpose hearing aid and masker systems. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR clinical evidence thresholds while streamlining UK-specific market access. London and Manchester audiology networks drive adoption of teleaudiology platforms for remote firmware programming.
South Korea
MFDS medical device approval pathways accommodate digital health platform commercialization for subscription-based tinnitus coping tools. National Health Insurance Service coverage decisions for behavioral health services accelerate platform-based Cognitive Behavioral Therapy access. Seoul Capital Area concentrates ENT clinic infrastructure where integrated sound therapy protocols displace standalone device dispensing.
Tinnitus Management Market Competitive Environment
On the supply side, the industry is consolidating around three strategic archetypes: vertically integrated hearing aid manufacturers with masker firmware capabilities, specialized neuromodulation device developers, and digital health platform operators. Hearing instrument conglomerates leverage audiological benefit code reimbursement to defend installed base relationships. Neuromodulation specialists pursue venture capital to advance bimodal stimulation hardware through regulatory clearance. Platform operators capture recurring revenue through subscription models that displace traditional device-centric purchase structures.
Among vertically integrated manufacturers, Starkey Hearing Technologies and GN Hearing A/S occupy positions that exemplify the hardware-dominant archetype, while Neuromod Devices Ltd. represents the specialized neuromodulation developer tier. Starkey anchors Midwest production geography through captive manufacturing infrastructure. GN Hearing A/S sits within the Nordic hearing instrument cluster with ReSound brand positioning. Neuromod Devices Ltd. exemplifies venture-backed specialization in bimodal tongue-audio stimulation systems.
| Leading Market Players |
|---|
| Starkey Hearing Technologies |
| GN Hearing A/S |
| Neuromod Devices Ltd. |
| Widex A/S |
| Oticon Inc. |
| Neuromonics Inc. |
| Puretone Ltd. |
| Signia |
| Sivantos Inc. |
| Others |
Value Chain & Pricing Dynamics
Midwest United States manufacturing clusters for custom-molded sound therapy hardware concentrate upstream supply, anchoring margin pools with vertically integrated hearing instrument conglomerates while compressing pricing power for component-dependent assemblers.
Pricing Analysis
Volume-discount tiering structures separate enterprise procurement contracts for hospital systems from individual cash-pay transactions at audiology centers. Three-tier pricing structure across premium, standard, and economy levels reflects firmware customization depth and after-sales calibration bundling. Pricing pressure stems from direct-to-consumer platform expansion that disintermediates traditional audiologist gatekeepers. Cash-pay patients in home care channels exhibit highest price sensitivity, whereas institutional purchasers with bundled reimbursement show lowest elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk profiles for acoustic processing chipsets and miniature speaker components. Manufacturing concentrates in the United States, Germany, and China, with final assembly drawing from Taiwanese semiconductor foundries and Japanese precision acoustic transducers. Single-source vulnerability persists for bimodal neuromodulation tongue electrodes. Distribution runs through manufacturer-employed audiology specialists for high-consideration hearing aid purchases, supplemented by direct-to-consumer platforms for sound therapy hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 510(k) clearance compression for neuromodulation devices signals high-growth disruption, as accelerated regulatory pathways attract venture capital toward bimodal stimulation hardware while elevating clinical evidence thresholds that favor capitalized incumbents.
For Market Incumbents: Entrench installed base relationships through firmware subscription models that capture recurring revenue from programmable masker updates. Deepen backward integration into custom-molded hardware production to defend cost advantages against direct-to-consumer entrants. Prioritize certification investment for EU MDR clinical performance studies to erect competitive moats. For New Entrants and Emerging Players: Home care sound therapy devices for aging demographics in Japan represent the most penetrable entry point, given PMDA approval timeline barriers that deter smaller competitors. Teleaudiology platform partnerships with United States audiology networks offer regulatory-compliant channel access without captive clinic infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed neuromodulation specialists possessing FDA-cleared bimodal systems but limited commercial scale. Long-term viability hinges on CMS reimbursement coding decisions for tongue-audio stimulation protocols. Watch FDA breakthrough device designations as inflection indicators for platform valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerated clearance pathways compress development timelines for neuromodulation hardware entrants. |
| CE Marking Pathway | EU MDR clinical evidence thresholds favor manufacturers with robust post-market surveillance infrastructure. |
| Hospital System Partnership | Academic medical center pilots for bimodal systems generate treatment-resistant patient data assets. |
| Software Companion Development | Real-time adaptive stimulation protocols differentiate hardware through personalized patient outcome integration. |
| Reimbursement Strategy | CMS coverage determinations for emerging bimodal therapies reshape competitive R&D capital allocation. |
Study Parameters
A spread of perspectives from ENT clinicians, biomedical engineers, audiology center operators, and hospital purchasing committees converged on the working assumptions. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR notified body guidance documents, CMS reimbursement coding decisions, and audiological benefit code databases. Bottom-up patient volume estimates triangulated against top-down manufacturer shipment data across the analysis window.
Demand-supply-balance framing anchored the analytical framework, modeling patient cohort expansion against manufacturing capacity and workforce constraints throughout the forecast period. Segmentation dimensions included product type, treatment approach, end user, and distribution channel, with regional regulatory clusters as an overlay. CAGRs derived from fitted growth curves applied to baseline prevalence data and adoption rate assumptions. Forecast inputs incorporated aging demographic trajectories and mental health parity legislative expansion.
Macroeconomic conditions sit as an overlay; deviation in reimbursement policy, regulatory clearance timelines, or venture capital availability for device development would shift the trajectory. Forecasts reflect documented assumptions about patient access and technology adoption. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Endometrial Cancer Market
Specialty Medicine
Complex Regional Pain Syndrome (CRPS) Market
Specialty Medicine
Global Prurigo Nodularis Treatment Market
Specialty Medicine
Moderate-To-Severe Acne Therapeutics Market
Specialty Medicine
Hemifacial Spasm Market
Specialty Medicine
Head and Neck Cancer Therapeutics Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Leukocytoclastic Vasculitis Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Market
Specialty Medicine
Pseudobulbar Treatment Market
Specialty Medicine
Veno-Occlusive Hepatic Disease Therapeutics Market
Specialty Medicine
Lipoprotein Metabolism Disorders Treatment Market
Specialty Medicine
Eosinophilia Therapeutics Market
Specialty Medicine
Peptide-Based Metabolic Disorders Therapeutics Market
Specialty Medicine
Global Gastrointestinal Therapeutics Market
Specialty Medicine
Dyschromia Therapeutics Market