
 US Opioid Use Disorder (OUD) Market | 2026-2036
US Opioid Use Disorder (OUD) Market Size, Share, and Industry Trends Forecast 2026-2036
US Opioid Use Disorder (OUD) Market Insights
Market Context
The divergence between branded long-acting injectables and generic oral formulations is hardening into a two-tier competitive structure. Indivior PLC leverages its patent-protected depot formulations to sustain premium positioning in medication-assisted therapy, while Alkermes anchors the Vivitrol franchise through specialized addiction psychiatry networks. Teva Pharmaceutical Industries competes aggressively on price in commoditized buprenorphine-naloxone tablets, controlling significant outpatient pharmacy volume.
Technical Definition and Segment Structure
Opioid Use Disorder constitutes a chronic, relapsing condition of compulsive opioid use despite adverse consequences, diagnosed under DSM-5 criteria with severity graded by functional impairment and withdrawal symptomatology. The disorder demands pharmacological intervention through mu-opioid receptor modulation—agonist, partial agonist, or antagonist mechanisms—paired with behavioral therapy to restore neurochemical homeostasis and reduce mortality risk. Buprenorphine formulations dominate value generation due to ceiling-effect safety profiles and expanding office-based prescribing privileges, while injectable depot therapies capture the fastest expansion as adherence engineering overtakes daily dosing convenience in payer value assessments. Naloxone distribution through outpatient facilities represents a mature, policy-subsidized volume pool with thinning margins, whereas implantable devices occupy a narrow but defensible niche for high-recidivism patient cohorts.
Regulatory Framework and Outlook
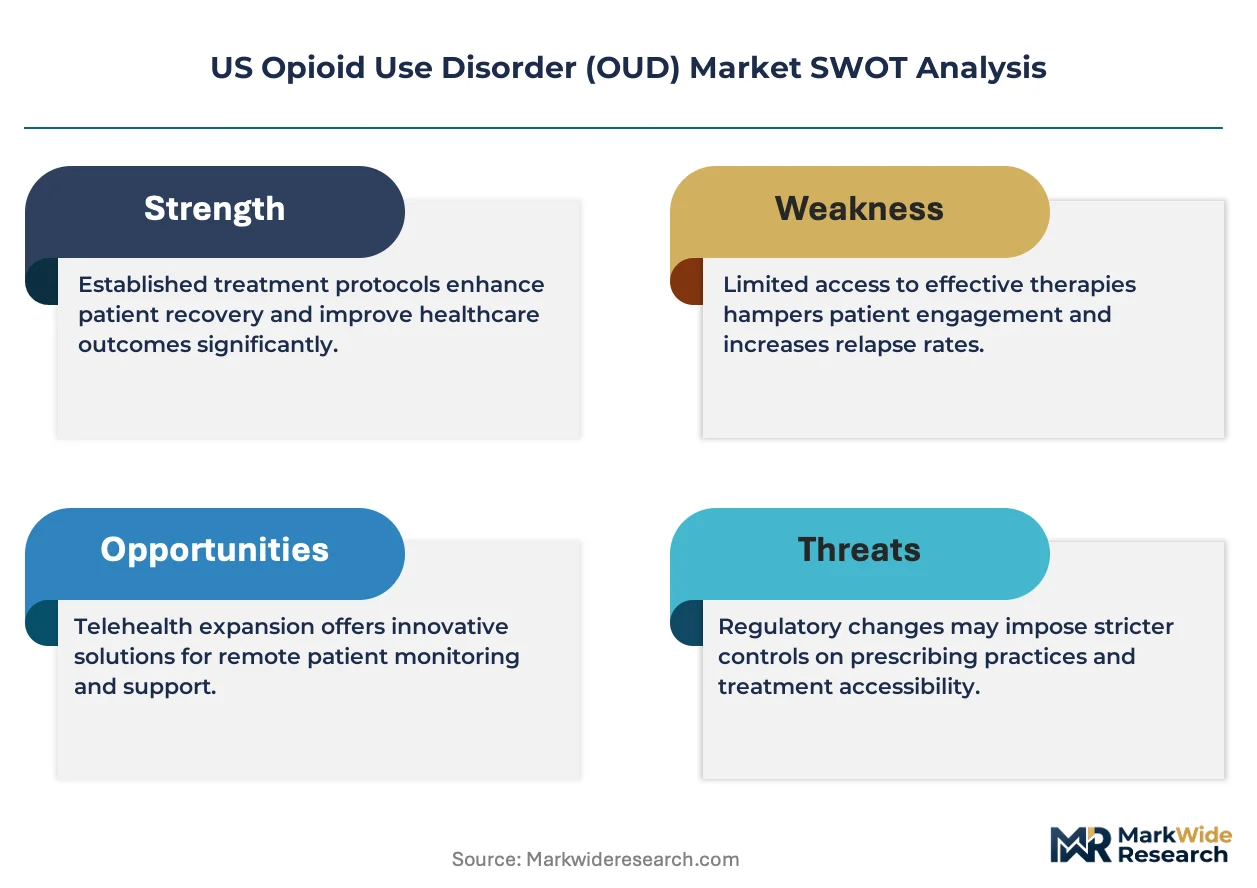
FDA, DEA, and SAMHSA collectively govern market access through controlled-substance scheduling, Risk Evaluation and Mitigation Strategy mandates, and practitioner waiver requirements that dictate prescriber capacity. The 2023 MAT Act elimination of the X-waiver reduced bureaucratic friction for buprenorphine prescribing, directly expanding the addressable prescriber base. Stakeholders must monitor whether CMS reimbursement parity rules for telehealth-delivered OUD treatment survive policy review cycles, as virtual care infrastructure has become integral to rural access models.
Market Dynamics
The US OUD market pivots on Medicaid-driven demand concentration, where state-level coverage mandates for medication-assisted therapy have compressed prescribing autonomy into standardized formularies and preferred drug lists.
Growth Catalysts
- MAT Act deregulation:The 2023 elimination of DEA X-waiver requirements removed prescriber capacity constraints, expanding office-based buprenorphine prescribing privileges to thousands of previously restricted clinicians.
- Long-acting injectable engineering:Depot formulations with monthly or quarterly dosing intervals are displacing daily oral regimens in state Medicaid programs seeking adherence guarantees over patient convenience.
- Ohio-Pennsylvania-West Virginia corridor:Appalachian states with the highest overdose mortality rates have implemented mandatory MAT coverage and hub-and-spoke treatment networks, creating concentrated demand pools.
Market Restraints
- DEA production quotas:Annual aggregate limits on buprenorphine API manufacturing create supply rigidity that constrains formulation diversification and generic entry timing.
- Specialty pharmacy concentration:Cold-chain distribution requirements for long-acting injectables limit dispensing to a narrow network of certified facilities, creating geographic access deserts.
- Antagonist therapy ceiling:Vivitrol's opioid-blockade mechanism requires full detoxification prior to initiation, excluding acute withdrawal patients and compressing addressable share.
Strategic Opportunities
- Rural telehealth infrastructure:CMS reimbursement parity for virtual OUD treatment delivery creates channel expansion into federally qualified health centers serving frontier counties.
- Co-formulation innovation:Buprenorphine-naloxone combinations with abuse-deterrent properties align with FDA Risk Evaluation and Mitigation Strategy requirements for diversion control.
- Justice-involved populations:State corrections systems and drug courts represent underpenetrated channels where medication-assisted therapy reduces recidivism costs.
Industry Challenges
- Addiction psychiatry workforce scarcity:Board-certified specialists capable of managing complex comorbidities remain concentrated in academic medical centers, limiting rural program scale.
- Behavioral therapy integration:SAMHSA-mandated counseling requirements create operational friction as telehealth platforms struggle to coordinate synchronous psychotherapy with pharmacological dosing.
- Stigma-driven formulary exclusion:Employer-sponsored commercial plans continue to impose prior authorization burdens that delay treatment initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Opioid Use Disorder (OUD) Market |
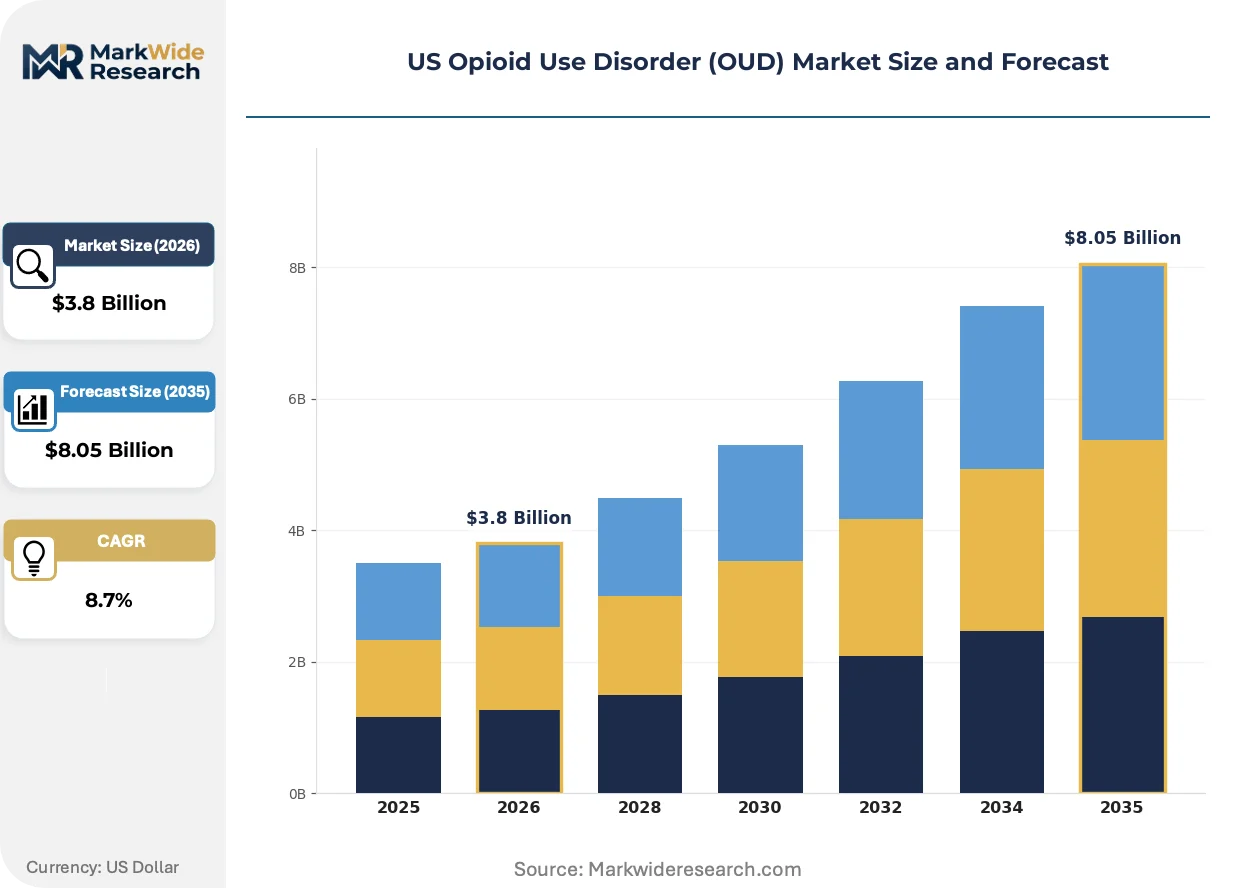
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Methadone, Buprenorphine, Naltrexone, Naloxone Therapy Area: Detoxification, Maintenance Therapy, Relapse Prevention, Overdose Treatment End User: Treatment Centers, Rehabilitation Clinics, Psychiatric Facilities, Outpatient Facilities Delivery Mode: Oral Tablets, Injectable, Sublingual Films, Implantable Devices |
| Companies Covered | Indivior PLC, Alkermes, Orexo AB, Teva Pharmaceutical Industries, Pfizer, Camurus AB, Titan Pharmaceuticals, Collegium Pharmaceutical, Hikma Pharmaceuticals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Opioid Use Disorder (OUD) Market Trends and Innovations
Prescribing infrastructure is bifurcating between high-touch specialty networks and commoditized primary care channels, with technology and reimbursement policy determining which model captures patient volume.
Long-acting buprenorphine depot formulations are absorbing patient populations previously managed on daily sublingual tablets. Addiction psychiatry networks in Massachusetts and California have adopted monthly Sublocade injections as first-line maintenance therapy. This shift is absorbing outpatient pharmacy volume into physician-administered settings, compressing retail dispensing margins while elevating adherence metrics in Medicaid value-based contracts.
SAMHSA's updated Opioid Treatment Program standards now mandate electronic health record interoperability and outcomes reporting for certified providers. The regulation forces capital expenditure on data infrastructure for smaller methadone clinics. Rural OTPs in Kentucky and Tennessee are responding through regional consortium arrangements that share compliance costs across multiple sites.
Correctional facilities are emerging as a distinct procurement channel with separate contracting dynamics. State departments of correction in Pennsylvania and Illinois have issued bundled RFPs combining in-custody initiation with post-release continuity through Medicaid managed care handoffs. This channel disintermediation bypasses traditional outpatient referral pathways and demands specialized carceral health vendors capable of coordinating justice and community systems.
US Opioid Use Disorder (OUD) Market Segmentation
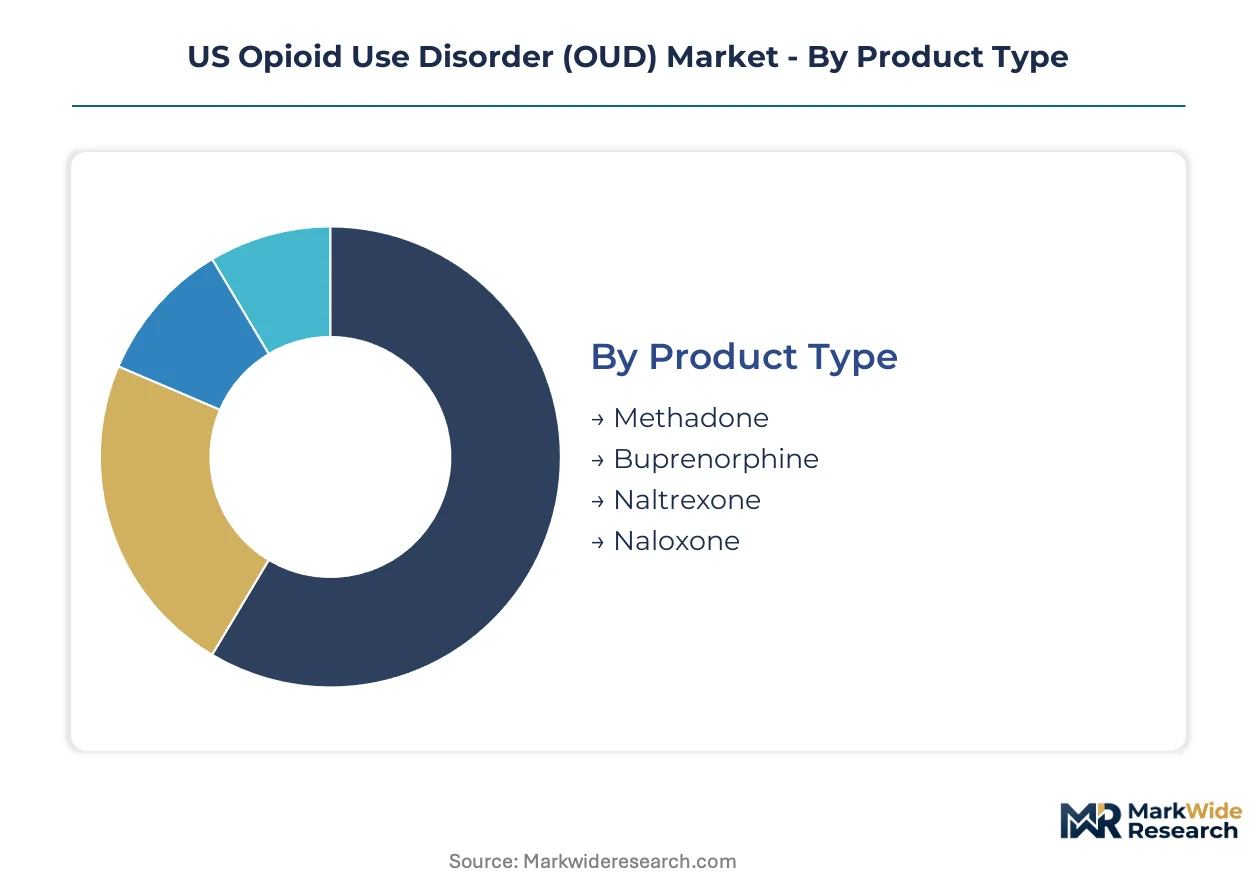
Segmentation in the US OUD market reveals how reimbursement policy and prescriber infrastructure allocate patient volume across competing pharmacological modalities. Each dimension—product chemistry, clinical intent, care setting, and formulation engineering—creates distinct competitive battlegrounds with divergent margin profiles and regulatory exposure.
Product Type:
Integration depth varies sharply: methadone and buprenorphine embed into daily clinical workflows with mandatory counseling, while naltrexone and naloxone function as standalone interventions with lighter infrastructure requirements.
- Buprenorphine:Partial mu-opioid agonist with ceiling-effect respiratory depression safety. Demand concentrates in Ohio, Pennsylvania, and West Virginia Medicaid programs where office-based prescribing expansion has displaced methadone clinic dependency. The 2023 MAT Act elimination of X-waivers accelerated primary care adoption.
- Methadone:Full agonist restricted to SAMHSA-certified Opioid Treatment Programs requiring daily supervised dosing. Patient volume clusters in urban corridors with established OTP infrastructure; rural access deserts persist due to regulatory concentration requirements.
- Naltrexone:Mu-opioid antagonist formulated as monthly depot injection for maintenance therapy. Vivitrol's opioid-blockade mechanism demands full detoxification prior to initiation, limiting addressable share to stabilized patients.
- Naloxone:Emergency overdose reversal agent distributed through policy-subsidized channels. State mandates for co-prescription with opioid analgesics have saturated outpatient pharmacy volume with thinning margins.
Buprenorphine leads volumes today; naltrexone depot formulations are gaining share fastest in commercial and Medicaid managed care contracts prioritizing adherence guarantees.
Therapy Area:
Cost tier stratification separates acute intervention from chronic disease management, with detoxification commanding premium reimbursement and relapse prevention facing utilization review compression.
- Maintenance Therapy:Long-term pharmacological stabilization using buprenorphine or methadone with indefinite duration. Medicaid programs in Appalachian states have mandated coverage as a condition of managed care contracting, creating concentrated demand pools with volume guarantees.
- Detoxification:Medically supervised withdrawal management bridging to maintenance or abstinence-based recovery. Academic medical centers and residential facilities capture premium reimbursement for inpatient initiation protocols.
- Relapse Prevention:Extended naltrexone depot therapy and behavioral reinforcement for high-recidivism cohorts. Drug courts and corrections systems represent emerging procurement channels with bundled contracting.
- Overdose Treatment:Naloxone administration in emergency and bystander settings. Community distribution programs and first-responder bulk purchasing dominate volume with federal subsidy dependency.
Maintenance therapy absorbs the majority of pharmaceutical spend; relapse prevention is expanding most quickly through justice-involved population contracts.
End User:
Customer type determines procurement sophistication, with psychiatric facilities and outpatient sites diverging on formulary autonomy versus standardized preferred drug list compliance.
- Outpatient Facilities:Office-based buprenorphine prescribing in primary care and federally qualified health centers. The MAT Act prescriber base expansion has shifted volume toward this channel, though behavioral therapy integration remains operationally challenging.
- Treatment Centers:SAMHSA-certified Opioid Treatment Programs providing methadone with comprehensive services. Concentrated in metropolitan statistical areas with established regulatory infrastructure; rural expansion limited by certification costs.
- Rehabilitation Clinics:Residential and intensive outpatient programs combining pharmacological and psychosocial intervention. Commercial insurance reimbursement parity varies by state mandate.
- Psychiatric Facilities:Addiction psychiatry specialists managing complex comorbidities. Board-certified workforce scarcity limits scale, concentrating expertise in academic medical centers.
Outpatient facilities capture the steepest volume trajectory; treatment centers retain the deepest methadone patient concentration.
Delivery Mode:
Maturity curves separate established oral formulations from engineered depot systems, with supply concentration in cold-chain distribution creating geographic access disparities.
- Injectable:Long-acting depot formulations including monthly buprenorphine and naltrexone suspensions. Specialty pharmacy certification requirements limit dispensing to narrow networks, creating access deserts in frontier counties.
- Sublingual Films:Buprenorphine-naloxone combination strips with abuse-deterrent properties. Retail pharmacy volume leader with generic price compression and Medicaid preferred status.
- Oral Tablets:Commoditized buprenorphine-naloxone and methadone formulations. Teva Pharmaceutical Industries and generic manufacturers compete on price in outpatient pharmacy channels.
- Implantable Devices:Probuphine and emerging six-month buprenorphine implants for high-recidivism cohorts. Narrow niche due to surgical insertion requirements and limited prescriber training.
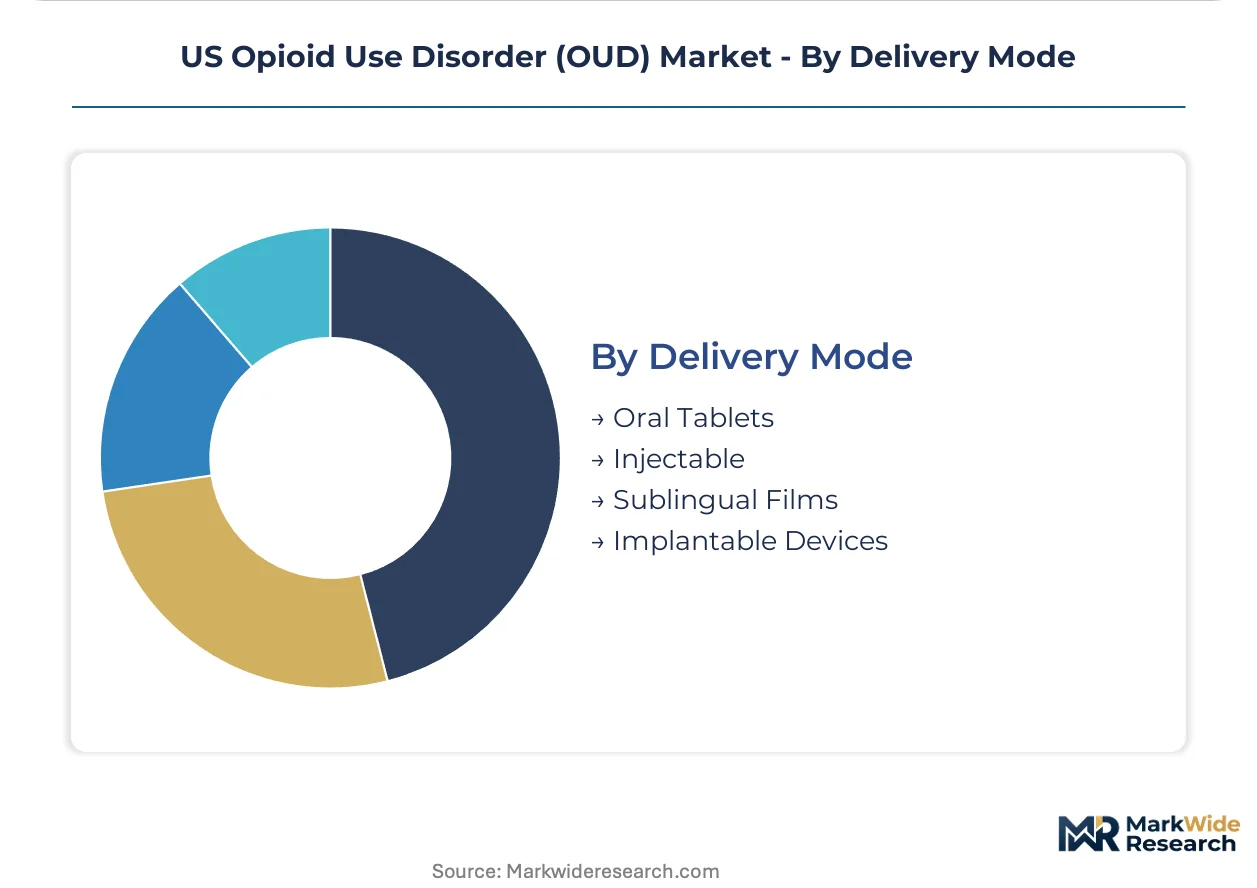
Sublingual films dominate current dispensing volume; injectable depots are climbing the fastest as adherence engineering overtakes convenience in payer value assessments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Addiction psychiatry specialists cluster in academic medical centers across the Ohio-Pennsylvania-West Virginia corridor, creating concentrated treatment capacity in the nation's highest overdose mortality zones. State Medicaid programs in this region have implemented mandatory medication-assisted therapy coverage mandates that reshape prescriber infrastructure and patient access patterns.
Ohio
Hub-and-spoke treatment networks concentrate patient volume in federally qualified health centers serving Appalachian counties. The Ohio Department of Medicaid mandates buprenorphine coverage in managed care contracts, eliminating prior authorization barriers for office-based prescribing. Cleveland Clinic and Ohio State University anchor specialized addiction psychiatry capacity that trains regional prescribers.
Pennsylvania
State corrections systems issue bundled procurement contracts combining in-custody initiation with post-release continuity through Medicaid handoffs. The Pennsylvania Department of Drug and Alcohol Programs certifies regional opioid treatment programs with strict electronic health record interoperability requirements. Philadelphia and Pittsburgh academic medical centers dominate complex comorbidity management for justice-involved populations.
West Virginia
Rural access deserts persist despite federal treatment expansion grants targeting outpatient facilities in frontier counties. The West Virginia Bureau for Medical Services reimburses telehealth-delivered OUD treatment at parity with in-person visits, expanding prescriber reach into underserved mountain communities. Charleston and Huntington cluster existing opioid treatment program infrastructure while Morgantown anchors university-affiliated research capacity.
Massachusetts
Addiction psychiatry networks have adopted monthly long-acting buprenorphine injections as first-line maintenance therapy, displacing retail pharmacy volume into physician-administered settings. The Massachusetts Department of Public Health mandates outcomes reporting for certified providers, forcing capital expenditure on data infrastructure. Boston's academic medical corridor leads adherence-engineering adoption in Medicaid value-based contracts.
California
Medi-Cal managed care plans prioritize long-acting depot formulations in preferred drug lists, compressing margins for generic oral competitors. The California Department of Health Care Services integrates behavioral therapy requirements into telehealth platform regulations, creating operational friction for asynchronous care models. Los Angeles County and the San Francisco Bay Area concentrate specialized treatment capacity for high-recidivism patient cohorts.
US Opioid Use Disorder (OUD) Market Competitive Landscape
Top-tier vendors anchor patent-protected depot formulations, while generic manufacturers compete on price in commoditized oral tablet channels. The market structure hardens around a two-tier competitive dynamic: premium-positioned long-acting injectables command adherence-based value contracts, while sublingual films and tablets face Medicaid preferred drug list compression. Three strategic archetypes dominate: specialty pharmaceutical firms engineering depot delivery systems, diversified generics houses controlling outpatient pharmacy volume, and niche device developers targeting implantable maintenance therapy. Competitive moves concentrate on formulary positioning through state Medicaid preferred drug list negotiations and hub-and-spoke network certification partnerships.
Within the specialty pharmaceutical tier, Indivior PLC and Alkermes occupy positions defined by proprietary delivery mechanisms and specialized addiction psychiatry network relationships. Indivior PLC represents the depot formulation archetype with monthly buprenorphine suspensions that displace daily dosing regimens in payer value assessments. Alkermes anchors the antagonist therapy segment through Vivitrol's opioid-blockade positioning, though its detoxification prerequisite limits addressable patient share. Teva Pharmaceutical Industries exemplifies the generic scale archetype, competing aggressively on price in buprenorphine-naloxone tablets across outpatient pharmacy channels.
| Leading Market Players |
|---|
| Indivior PLC |
| Alkermes |
| Orexo AB |
| Teva Pharmaceutical Industries |
| Pfizer |
| Camurus AB |
| Titan Pharmaceuticals |
| Collegium Pharmaceutical |
| Hikma Pharmaceuticals |
| Others |
Pricing and Supply Chain Analysis
Medicaid preferred drug list standardization across Ohio, Pennsylvania, and West Virginia has compressed formulary autonomy into narrow reimbursement bands, forcing manufacturers to absorb distribution complexity while competing on adherence guarantees rather than convenience premiums.
Pricing Analysis
Bundled service contracts for justice-involved populations diverge sharply from unbundled retail pharmacy dispensing. Three-tier pricing structure across depot injectables, sublingual films, and generic tablets reflects FDA Risk Evaluation and Mitigation Strategy certification levels and cold-chain handling requirements. Cost compression in oral generics intensifies as Teva Pharmaceutical Industries and Hikma Pharmaceuticals compete on Medicaid tender volume, while specialty pharmacy networks command premium positioning for long-acting formulations. State corrections systems exhibit lowest price sensitivity due to recidivism cost-avoidance framing; retail outpatient channels face highest sensitivity from prior authorization burdens.
Supply Chain Analysis
Specialized addiction psychiatry workforce scarcity in Appalachian manufacturing corridors constrains hub-and-spoke network expansion regardless of API availability. Active pharmaceutical ingredient production draws from India and China for buprenorphine base material, with domestic formulation concentration in New Jersey and North Carolina facilities. Single-source vulnerability persists for naloxone auto-injector devices. Distribution runs through specialty pharmacy networks requiring DEA-certified cold-chain handling, limiting patient access in frontier counties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Opioid Use Disorder market functions as a stable compounder anchored by federal Medicaid expansion and the irreversible shift toward medication-assisted therapy as standard of care.
For Market Incumbents: Anchor formulary positioning through state Medicaid preferred drug list negotiations in the Ohio-Pennsylvania-West Virginia corridor, where mandatory coverage mandates create volume guarantees. Deepen hub-and-spoke network certification partnerships to lock out generic competitors from long-acting injectable channels. Vertical integration into telehealth platform infrastructure addresses behavioral therapy integration friction that threatens patient retention. For New Entrants and Emerging Players: The price-point gap between premium depot formulations and economy oral tablets creates entry space for mid-tier sublingual film competitors with abuse-deterrent properties. Rural telehealth infrastructure in West Virginia and Kentucky represents the most penetrable geography, with federally qualified health centers seeking formulary diversity beyond incumbent offerings. Justice-involved population contracts offer bundled procurement angles that bypass saturated outpatient pharmacy channels. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty pharmaceutical firms holding proprietary depot delivery mechanisms and established addiction psychiatry network relationships. Long-term viability favors platforms capable of spanning carceral and community care continuity. Monitor CMS reimbursement parity rule survival as the critical inflection signal for rural telehealth-delivered treatment models.| Strategic Initiative | Industry Significance |
|---|---|
| Formulary Positioning Investment | State Medicaid preferred drug list placement in Ohio and Pennsylvania secures volume guarantees. |
| Hub-and-Spoke Network Certification | SAMHSA-certified regional partnerships lock patient flow into controlled distribution channels. |
| Telehealth Platform Integration | CMS reimbursement parity enables virtual care reach into Appalachian frontier counties. |
| Justice-Involved Population Contracting | State corrections bundled RFPs combine in-custody initiation with post-release Medicaid handoffs. |
| Abuse-Deterrent Co-Formulation Development | FDA Risk Evaluation and Mitigation Strategy alignment supports diversion control claims. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with addiction psychiatry specialists, state Medicaid formulary directors, specialty pharmacy procurement managers, and SAMHSA-certified treatment program administrators with secondary validation against FDA filings, CMS Medicare and Medicaid data, state Opioid Treatment Program certification records, and DEA controlled substance production quota disclosures. Bottom-up patient volume modeling and top-down pharmaceutical spend triangulation anchored segment-level outputs.
Comparable-period anchoring tied projection trajectories to historical Medicaid enrollment expansion patterns and MAT Act implementation timing across the analysis window. Segmentation dimensions spanned product chemistry, therapy area intent, care setting infrastructure, and formulation engineering maturity. CAGRs were derived from fitted growth curves calibrated to state-level coverage mandate adoption curves and prescriber waiver elimination effects. Forecast inputs incorporated DEA production quota rigidity and specialty pharmacy network concentration metrics.
Caveats apply where DEA scheduling reclassification, CMS telehealth reimbursement rollback, or state Medicaid formulary restriction reversals could materially shift the outlook. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Herpes Zoster (Shingles) Market
Specialty Medicine
Vertigo Market
Specialty Medicine
Disruptive Behavior Disorders Market
Specialty Medicine
Global Parkinsons Disease Treatment Market
Specialty Medicine
Paronychia Treatment Market
Specialty Medicine
Global Fungal Keratitis Treatment Market
Specialty Medicine
Cholangiocarcinoma (CCA) Therapeutics Market
Specialty Medicine
Latin America Liver Cancer Treatment Market
Specialty Medicine
Respiratory Syncytial Virus (RSV) Therapeutics Market
Specialty Medicine
Chronic Obstructive Pulmonary Disease Therapeutics Market
Specialty Medicine
Listeriosis Treatment Market
Specialty Medicine
Epilepsy Treatment Market
Specialty Medicine
Acromegaly Market
Specialty Medicine
Strep Throat Treatment Market
Specialty Medicine
Global Hormone Replacement Therapy Market
Specialty Medicine
Frontotemporal Dementia Management Market