
 North America Collagen Market | 2026-2036
North America Collagen Market Size, Share, and Industry Trends Forecast 2026-2036
North America Collagen Market Outlook
FDA's New Dietary Ingredient notification pathway is repositioning the cost-of-entry calculus for collagen peptide suppliers entering the nutritional supplements channel. Nitta Gelatin NA Inc. leverages its North American manufacturing footprint to navigate these compliance requirements with minimal supply disruption. Gelita AG anchors its position through deep specialization in hydrolyzed collagen grades tailored to sports nutrition formulations. Darling Ingredients Inc. competes by controlling integrated rendering-to-collagen supply chains that reduce raw material cost volatility.
Collagen comprises a family of triple-helical structural proteins rich in glycine, proline, and hydroxyproline, extracted through acid or enzymatic hydrolysis of bovine hides, porcine skins, or fish scales for applications spanning gelling, film-forming, and cell scaffolding. Hydrolyzed collagen dominates value capture due to its cold-water solubility and neutral sensory profile, while marine-sourced variants command premium positioning in clean-label cosmetic applications. Gelatin retains mature volume share in food stabilization though growth tilts toward collagen peptides in functional foods where bioactive claims drive formulation decisions.
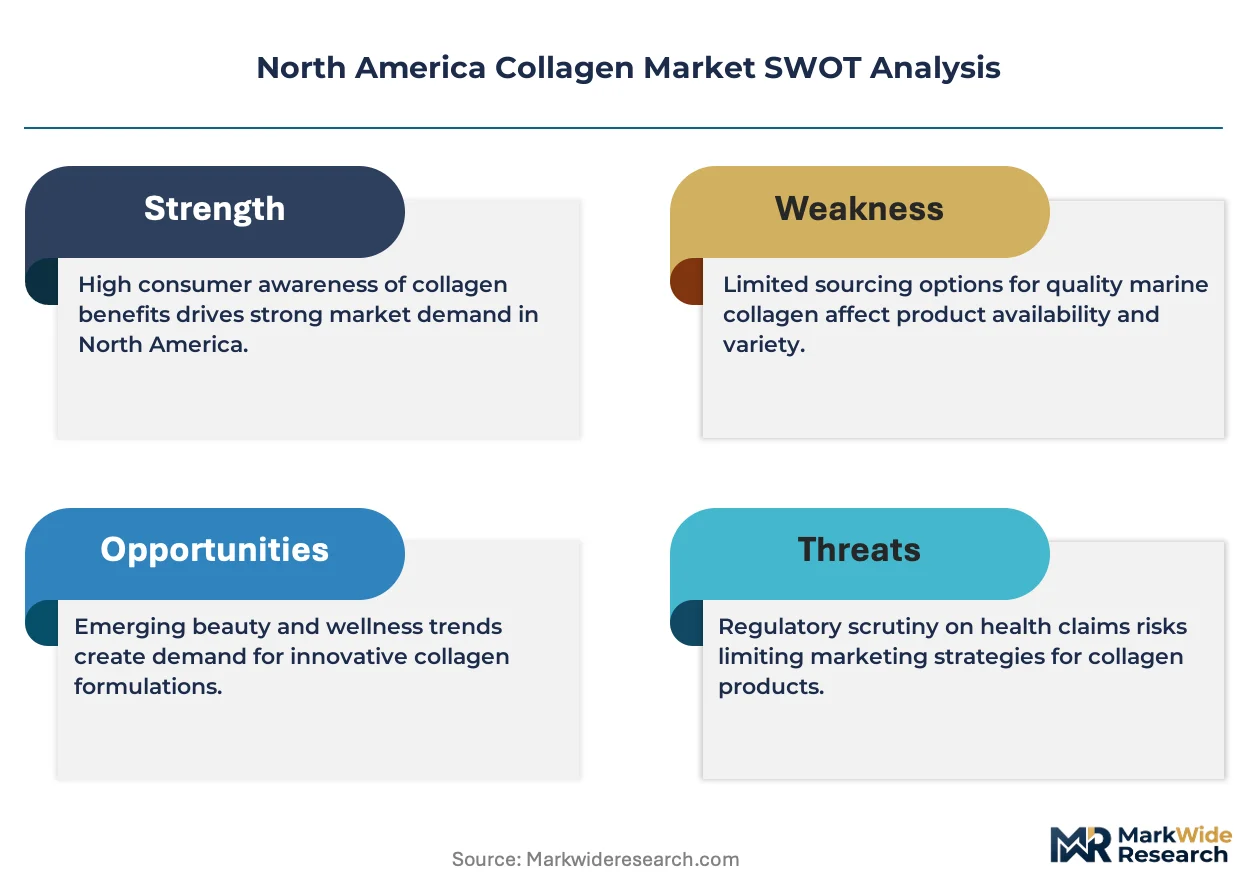
USDA oversight of animal-derived raw materials intersects with FDA food additive and dietary supplement regulations to create a dual-track compliance environment that favors suppliers with documented traceability systems. Health Canada's Natural Health Product regulations for cross-border suppliers add a secondary certification layer that shapes market access dynamics for peptide exporters. Stakeholders must monitor evolving allergen labeling requirements and alternative protein competition as these forces reshape procurement criteria across beauty and nutrition end markets.
Market Dynamics
FDA's New Dietary Ingredient notification framework is compressing supplier timelines and elevating documentation burdens for collagen peptide entrants targeting nutritional supplements. This regulatory pressure concentrates advantage among established North American manufacturers with in-house compliance infrastructure and documented supply chain traceability.
Growth Catalysts
- Clean-label cosmetic formulation:Marine-sourced collagen peptides command premium positioning as beauty brands eliminate synthetic additives. California and New York formulation labs drive procurement volume for cold-water soluble grades.
- Protein-forward wellness routines:Sports nutrition formulators integrate hydrolyzed collagen into recovery products. Bioactive claims differentiate functional food launches targeting athletic consumers.
- USDA-FDA dual-track compliance:Documented traceability systems for bovine and porcine raw materials unlock preferential market access. Suppliers with integrated rendering-to-peptide operations capture margin stability.
Market Restraints
- Bovine hide supply volatility:Rendering industry consolidation in the Midwest creates input cost pressure. Tightness in cattle processing volumes transmits directly to collagen raw material pricing.
- Fish scale sourcing constraints:Marine collagen dependence on aquaculture byproduct streams limits scale-up potential. Asian-origin marine raw materials face extended certification timelines for US entry.
- Alternative protein substitution:Pea and rice protein isolates displace collagen in mass-market nutrition bars. Plant-based positioning erodes addressable volume in price-sensitive segments.
Strategic Opportunities
- Health Canada Natural Health Product pathway:Cross-border peptide exporters can capture Canadian functional food and supplement demand. Secondary certification investment opens adjacent revenue streams.
- Cell scaffolding medical applications:Regenerative medicine research programs integrate collagen matrices for tissue engineering. Hospital procurement channels offer long-term contract potential.
- Enzymatic hydrolysis technology convergence:Precision enzyme blends reduce processing time and improve peptide molecular weight consistency. Biotech partnerships accelerate process optimization.
Industry Challenges
- Allergen labeling complexity:FDA evolving requirements for fish-derived collagen disclosure demand reformulation vigilance. Label compliance errors trigger recall exposure and retailer penalties.
- Specialized technical talent scarcity:Protein biochemists with collagen-specific hydrolysis expertise command premium compensation. Recruitment friction delays process scale-up timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Collagen Market |
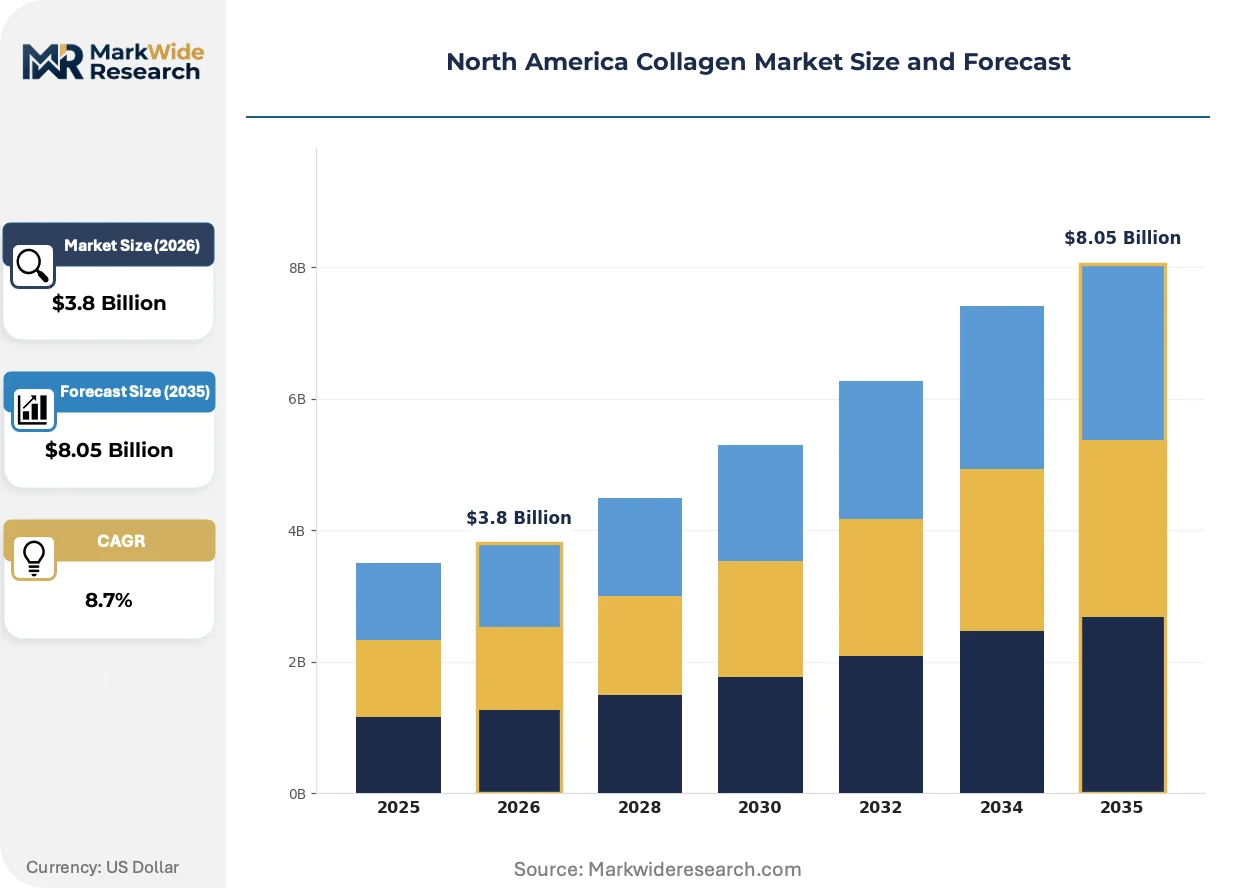
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Gelatin, Collagen Peptides, Native Collagen Application: Cosmetic Products, Nutritional Supplements, Functional Foods, Pharmaceuticals End User: Beauty Industry, Sports Nutrition, Healthcare Sector, Food & Beverage Source: Bovine, Porcine, Marine, Poultry |
| Companies Covered | Nitta Gelatin NA Inc., Gelita AG, Darling Ingredients Inc., Weishardt, Tessenderlo Group, Rousselot, Regenity, Collagen Solutions, PB Gelatins, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Collagen Market Strategic Shifts
Collagen peptide production is converging with precision fermentation and enzymatic engineering to reshape cost structures and functional performance. These intersecting advances compress traditional extraction economics while opening novel application categories.
Precision enzymatic hydrolysis is unifying control over peptide molecular weight distribution with reduced thermal processing requirements. Sports nutrition formulators adopt these engineered grades for faster dissolution and neutral sensory profiles. The technology is unifying quality consistency across batches previously achievable only through extensive manual oversight.
FDA's evolving New Dietary Ingredient notification pathway is elevating documentation standards for peptide suppliers entering supplements. Pre-market safety substantiation requirements extend lead times for novel sourcing configurations. Early-stage companies without regulatory affairs infrastructure face exclusion from nutritional channels.
Direct-to-consumer subscription models are displacing traditional wholesale distribution for premium collagen supplements. California and New York urban consumers prioritize personalized regimen delivery over retail shelf selection. This channel rotation compresses brand marketing spend efficiency and elevates customer acquisition cost sensitivity.
North America Collagen Market Segmentation
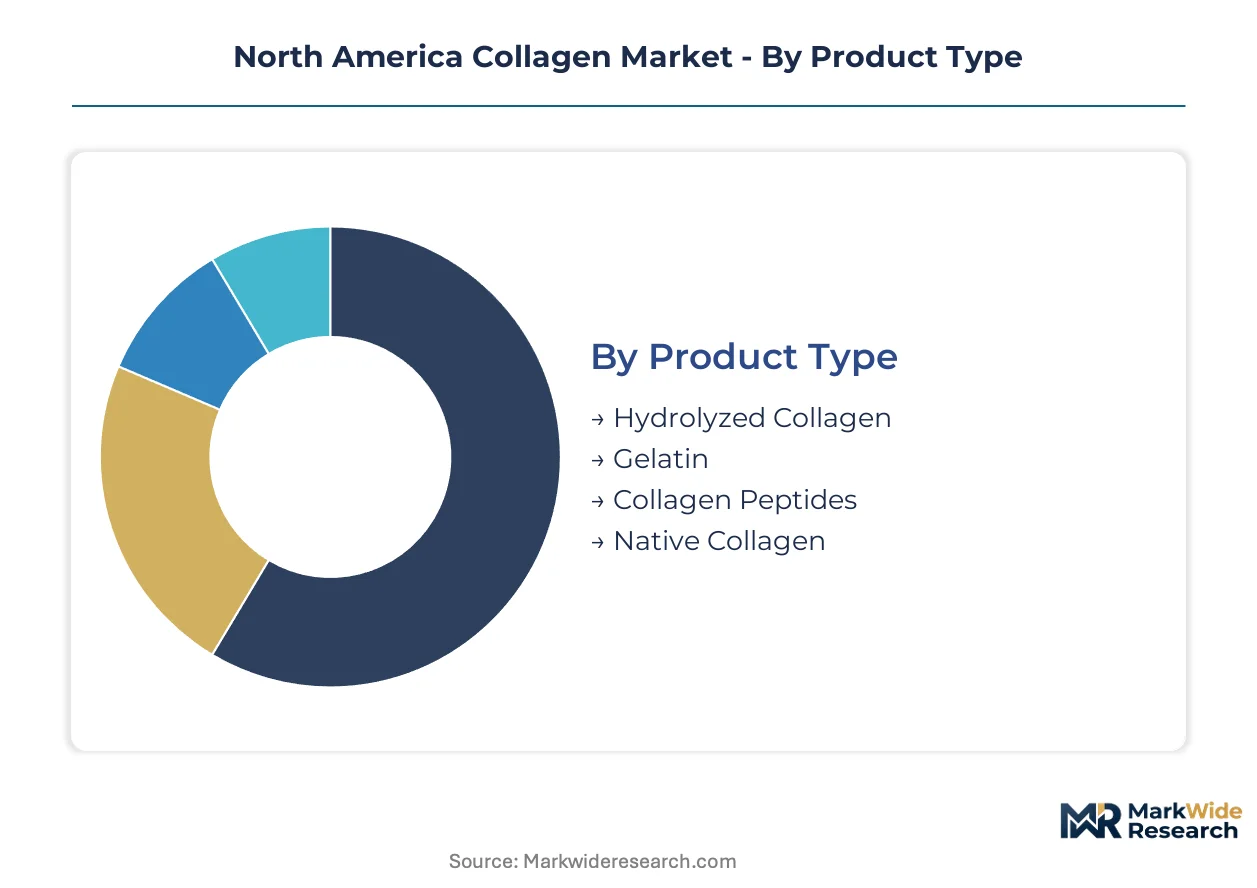
Collagen procurement patterns diverge sharply across molecular form, end-use application, and raw material provenance. Each segmentation axis reveals distinct margin structures, compliance burdens, and customer concentration profiles that shape supplier strategy.
Product Type:
Customization intensity varies from standardized commodity grades to precision-engineered peptide specifications.
- Hydrolyzed Collagen:Enzymatically cleaved to achieve cold-water solubility and neutral sensory profiles. Sports nutrition formulators in California and New York specify these grades for rapid-dissolution recovery beverages where bioactive claims drive purchasing decisions.
- Collagen Peptides:Fractionated to specific molecular weight distributions for targeted absorption kinetics. Nutritional supplement brands prioritize these engineered grades for subscription-based direct-to-consumer regimens where dissolution speed determines repeat purchase rates.
- Gelatin:Partially hydrolyzed collagen retaining gelling functionality for food stabilization. Mature volume share in confectionery and dairy applications faces gradual displacement by peptide alternatives in functional food launches.
- Native Collagen:Triple-helical structure preserved for medical scaffolding and regenerative medicine applications. Hospital procurement channels and tissue engineering research programs specify these undenatured grades for cell culture matrices.
Most installed capacity flows through Hydrolyzed Collagen. Expansion is steepest in Collagen Peptides.
Application:
Cost tier stratification separates premium-positioned beauty formulations from mass-market nutrition bars.
- Nutritional Supplements:Powder and capsule formats targeting protein-forward wellness routines. FDA New Dietary Ingredient notification requirements concentrate advantage among established North American manufacturers with documented safety substantiation.
- Cosmetic Products:Topical serums and ingestible beauty shots commanding premium positioning. Clean-label elimination of synthetic additives drives marine-sourced peptide procurement in California formulation labs.
- Functional Foods:Protein-fortified beverages and snack formats integrating collagen into daily consumption occasions. Bioactive differentiation claims separate premium launches from commodity nutrition bars facing pea protein substitution pressure.
- Pharmaceuticals:Wound healing matrices and drug delivery excipients requiring documented purity and endotoxin control. Regenerative medicine research programs in academic medical centers specify pharmaceutical-grade native collagen.
Volume concentrates in Nutritional Supplements. Margin expansion is strongest in Cosmetic Products.
End User:
Customer type determines technical service intensity and contract structure preferences.
- Sports Nutrition:Recovery-focused formulators specifying rapid-dissolution hydrolyzed grades for pre- and post-workout applications. Athletic consumer segments prioritize bioavailability claims over price sensitivity.
- Beauty Industry:Clean-label cosmetic brands eliminating synthetic additives through marine collagen integration. Direct-to-consumer subscription models displace traditional wholesale procurement for premium positioning.
- Healthcare Sector:Hospital systems and research institutions sourcing native collagen for wound care and tissue engineering. Long-term supply agreements with documented traceability satisfy procurement compliance requirements.
- Food & Beverage:Mainstream manufacturers incorporating gelatin for stabilization or peptides for protein fortification. Cost pressure from alternative proteins limits collagen penetration in price-sensitive mass-market segments.
Contract value concentrates in Healthcare Sector. Customer acquisition velocity is highest in Beauty Industry.
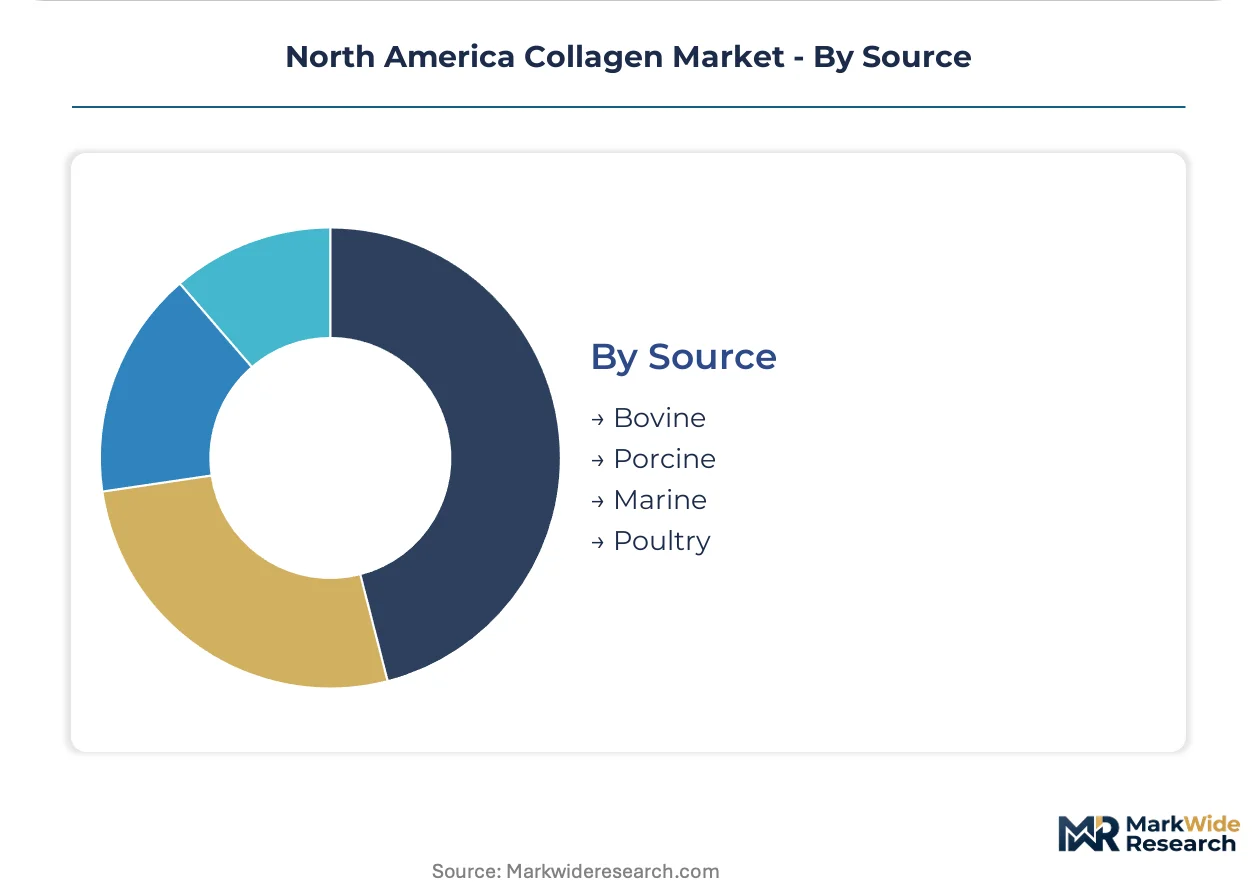
Source:
Supply concentration and certification burden vary dramatically across animal provenance.
- Bovine:Hides from cattle processing supply the majority of North American collagen volume. USDA oversight of rendering operations intersects with FDA regulations to create dual-track compliance favoring integrated suppliers.
- Marine:Fish scales and skins from aquaculture byproduct streams command premium positioning in clean-label applications. Asian-origin raw materials face extended certification timelines for US market entry.
- Porcine:Skins from pork processing offer alternative mammalian collagen with distinct allergen profiles. Religious dietary restrictions limit addressable market in certain consumer segments.
- Poultry:Emerging source from chicken processing waste streams with developing supply infrastructure. Scale limitations constrain commercial penetration relative to established bovine and marine alternatives.
Raw material throughput concentrates in Bovine. Premium positioning is strongest in Marine.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Collagen extraction and peptide processing first achieved industrial scale in the United States during the mid-twentieth century, establishing North America as the foundational geography for modern hydrolyzed collagen production. This historical lineage continues to shape procurement patterns and regulatory frameworks across the continent.
United States
California and New York formulation labs drive procurement volume for marine-sourced collagen peptides targeting clean-label cosmetic applications. FDA's evolving New Dietary Ingredient notification framework elevates documentation burdens for peptide suppliers entering nutritional supplements. Midwest rendering operations supply bovine hides to integrated collagen manufacturers, though cattle processing consolidation creates periodic raw material tightness.
Canada
Cross-border peptide exporters capture Canadian functional food and supplement demand through Health Canada's Natural Health Product regulatory pathway. The certification investment opens adjacent revenue streams for US-based manufacturers with documented traceability systems. Ontario and Quebec house distribution infrastructure serving beauty industry procurement channels.
Mexico
Emerging demand from sports nutrition formulators in Mexico City and Guadalajara integrates hydrolyzed collagen into recovery product launches. Domestic regulatory alignment with US FDA frameworks facilitates ingredient importation from established North American suppliers. Northern border states concentrate warehousing capacity for just-in-time delivery to US manufacturing facilities.
North America Collagen Market Competitive Environment
The competitive structure tilts toward integrated suppliers with captive rendering operations and documented compliance infrastructure. Established North American manufacturers with in-house regulatory affairs capabilities capture preferential positioning as FDA documentation requirements intensify. Three archetypes dominate: vertically integrated rendering-to-peptide operators, specialized hydrolyzed collagen engineers, and diversified ingredient conglomerates with collagen divisions. Capacity expansion and enzymatic hydrolysis technology licensing represent the dominant competitive moves reshaping cost structures.
Among North American integrated operators, Nitta Gelatin NA Inc. and Darling Ingredients Inc. exemplify the rendering-to-peptide archetype with upstream control over bovine hide supply chains. Gelita AG occupies a position representing specialized hydrolyzed collagen engineering for sports nutrition applications. These three anchors illustrate how regulatory compliance infrastructure and raw material integration separate sustainable competitors from entrants facing extended New Dietary Ingredient notification timelines.
| Leading Market Players |
|---|
| Nitta Gelatin NA Inc. |
| Gelita AG |
| Darling Ingredients Inc. |
| Weishardt |
| Tessenderlo Group |
| Rousselot |
| Regenity |
| Collagen Solutions |
| PB Gelatins |
| Others |
Value Chain & Pricing Dynamics
California and New York formulation labs demanding marine-sourced collagen peptides for clean-label cosmetic applications are forcing suppliers to absorb extended certification timelines and premium freight costs, compressing margins on high-grade peptide specifications while concentrating pricing power among integrated operators with captive raw material access.
Pricing Analysis
Service bundling separates peptide suppliers offering regulatory documentation packages from transactional commodity sellers. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade specifications reflects certification burden and molecular weight precision. Cost compression in mass-market nutrition bars intensifies as pea protein isolates displace collagen in price-sensitive segments. Sports nutrition formulators exhibit lowest price sensitivity, prioritizing bioavailability claims and rapid-dissolution performance over unit economics.
Supply Chain Analysis
Freight cost volatility from Asian-origin marine raw materials elevates landed costs for US coastal formulation labs. Bovine hide supply concentrates in Midwest rendering operations, while fish scale sourcing draws from aquaculture byproduct streams in Southeast Asia and South America. Single-source vulnerability in cattle processing consolidation creates periodic input tightness. Distribution runs through integrated rendering-to-peptide manufacturers serving direct-to-consumer subscription channels and wholesale ingredient markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on enzymatic hydrolysis technology convergence reducing processing costs and regenerative medicine applications commanding premium native collagen pricing.
For Market Incumbents: Extend compliance infrastructure investments to capture FDA New Dietary Ingredient notification advantages as documentation burdens exclude undercapitalized entrants. Deepen captive rendering operations in Midwest cattle processing corridors to defend against bovine hide supply volatility. Anchor position in pharmaceutical-grade native collagen for tissue engineering contracts with academic medical centers. For New Entrants and Emerging Players: Health Canada's Natural Health Product regulations in Canada opens a window for cross-border peptide exporters with documented traceability systems to capture adjacent functional food demand. Target direct-to-consumer subscription regimens in urban coastal markets where customer acquisition costs favor niche positioning over mass retail. Pursue enzymatic hydrolysis technology licensing partnerships to bypass capital-intensive process development. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized hydrolyzed collagen engineers possessing sports nutrition formulation relationships and in-house peptide molecular weight control capabilities. Long-term viability hinges on regenerative medicine pipeline maturation and clean-label cosmetic premiumization. Watch FDA enforcement patterns on New Dietary Ingredient notifications as inflection indicator for competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Technology Licensing | Precision enzyme blends reduce processing time and improve peptide consistency for sports nutrition formulators. |
| Backward Integration into Rendering Operations | Captive bovine hide supply insulates margin stability against Midwest cattle processing consolidation. |
| Health Canada Natural Health Product Certification | Cross-border regulatory investment unlocks Canadian functional food and supplement revenue streams. |
| Direct-to-Consumer Subscription Launch | California and New York urban consumers prioritize personalized regimen delivery over retail shelf selection. |
| Regenerative Medicine Partnership | Hospital procurement channels offer long-term contract potential for pharmaceutical-grade native collagen matrices. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with protein biochemists, sports nutrition formulators, cosmetic brand R&D directors, and hospital procurement managers with secondary validation against FDA New Dietary Ingredient notification databases, USDA rendering facility records, Health Canada Natural Health Product registrations, and SEC filings from publicly traded ingredient suppliers. Bottom-up volume estimates from peptide production capacity and top-down demand triangulation from end-use application sizing anchored the analysis.
Comparable historical periods spanning pre-pandemic baseline, supply disruption intervals, and regulatory framework transitions informed projection anchoring across the analysis window. Segmentation dimensions modeled include molecular form tier, end-use application, raw material provenance, and geographic demand cluster. CAGRs derived from fitted growth curves incorporating enzymatic hydrolysis technology adoption rates and clean-label cosmetic formulation penetration assumptions.
Revisions become necessary when FDA enforcement intensity on New Dietary Ingredient notifications shifts, alternative protein substitution accelerates beyond modeled thresholds, or marine raw material certification timelines extend substantially. Forecasts reflect documented assumptions about peptide absorption science validation and regenerative medicine regulatory pathway clarity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Cordyceps Sinensis and Militaris Market
Nutraceuticals
Chondroitin Sulfate Market
Nutraceuticals
US Pet Nutraceuticals Market
Nutraceuticals
Multifunctional Health Pot Market
Nutraceuticals
Eggshell Membrane Market
Nutraceuticals
Phosphatidylserine Market
Nutraceuticals
Micro-Ecological Regulators Market
Nutraceuticals
Immunostimulants Market
Nutraceuticals
Pycnogenol Market
Nutraceuticals
UK Pet Nutraceuticals Market
Nutraceuticals
Cordyceps Militaris Extract Market
Nutraceuticals
Fish-Oil Based Drugs Market
Nutraceuticals
Global Eye Health Supplement Market
Nutraceuticals
Middle East and Africa Effervescent Tablet Market
Nutraceuticals
Europe Collagen Peptide Products Market
Nutraceuticals
Tetrahydropalmatine Market