
 TIL Therapy Market | 2026-2036
TIL Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
TIL Therapy Market Insights
Synthetic IL-2 cytokine support is rebalancing manufacturing economics for TIL expansion protocols, reducing dependence on recombinant human IL-2 that historically constrained batch scale-up. Iovance Biotherapeutics anchors commercial infrastructure with centralized GMP facilities in Florida and Pennsylvania. Bristol Myers Squibb leverages its immuno-oncology portfolio to compete in combination regimens pairing TIL with checkpoint blockade. Obsidian Therapeutics differentiates through cytokine engineering platforms that enhance TIL persistence without systemic toxicity.
Tumor-infiltrating lymphocyte therapy involves extracting patient-derived T cells from resected tumor tissue, expanding them ex vivo with IL-2 stimulation over 22-36 days, and reinfusing the activated cell product following lymphodepletion. The process requires strict viability thresholds above 70 percent and clonality assessments to ensure polyclonal T-cell repertoire breadth. Among product type segments, TIL cells occupy the dominant revenue position given their status as the foundational therapeutic modality, while immune checkpoint inhibitors represent the fastest-growing adjuvant category as combination protocols mature. Hospitals capture the largest end-user share due to inpatient lymphodepletion requirements, though oncology clinics are building ambulatory capacity for post-infusion monitoring.
FDA's Center for Biologics Evaluation and Research governs TIL manufacturing through IND and BLA pathways, with recent draft guidance on potency assays tightening release specifications. EMA's Committee for Advanced Therapies coordinates centralized assessments across EU member states, creating divergent timelines versus US approval. The analysis indicates stakeholders must monitor how CMS reimbursement decisions for inpatient cell therapy administration reshape site-of-care economics and manufacturing location strategy.
Market Dynamics
Synthetic cytokine engineering is compressing manufacturing costs while FDA's accelerated approval pathway for cell therapies shortens development timelines, fundamentally restructuring how TIL products reach patients.
Growth Catalysts
- FDA Accelerated Approval:The Center for Biologics Evaluation and Research compresses IND-to-BLA timelines for autologous cell therapies, enabling faster patient access and reduced capital lock-up periods for developers.
- Academic Medical Center Expansion:Solid tumor oncology programs at major US teaching hospitals are building dedicated TIL infusion units, creating pull-through demand for commercial manufacturing partnerships.
- GMP Infrastructure Maturation:Centralized cell therapy manufacturing facilities in Florida and Pennsylvania achieve economies of scale through automated closed-system bioreactors, reducing per-batch labor intensity.
Market Restraints
- Recombinant IL-2 Supply Concentration:Historic dependence on a narrow supplier base for growth factor inputs creates batch-to-batch variability risks and price volatility in expansion media.
- Lymphodepletion Inpatient Requirements:High-dose chemotherapy conditioning mandates hospital admission, limiting site-of-care flexibility and compressing reimbursement margins under DRG-based payment.
- Polyclonality Assessment Complexity:Current clonality testing protocols lack standardization across laboratories, creating release specification friction and inventory hold risks.
Strategic Opportunities
- Outpatient Monitoring Infrastructure:Oncology clinics are building ambulatory capacity for post-infusion cytokine release syndrome management, enabling site-of-care migration from hospitals.
- Immune Checkpoint Inhibitor Pairing:Combination protocols with anti-PD-1 agents represent white space for label expansion beyond monotherapy indications.
- EMA Centralized Assessment Alignment:The Committee for Advanced Therapies pathway offers parallel EU market entry, though timeline divergence requires dual-track regulatory strategy investment.
Industry Challenges
- Cell Therapy Manufacturing Talent Scarcity:GMP aseptic processing and vector quality control functions face acute workforce shortages, extending facility qualification timelines.
- Potency Assay Validation Burden:FDA draft guidance on release specifications demands extensive analytical method development, stretching quality control capex cycles.
- Autologous Supply Chain Coordination:Patient-specific logistics require cryogenic chain integrity across tumor harvest, transport, expansion, and reinfusion nodes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | TIL Therapy Market |
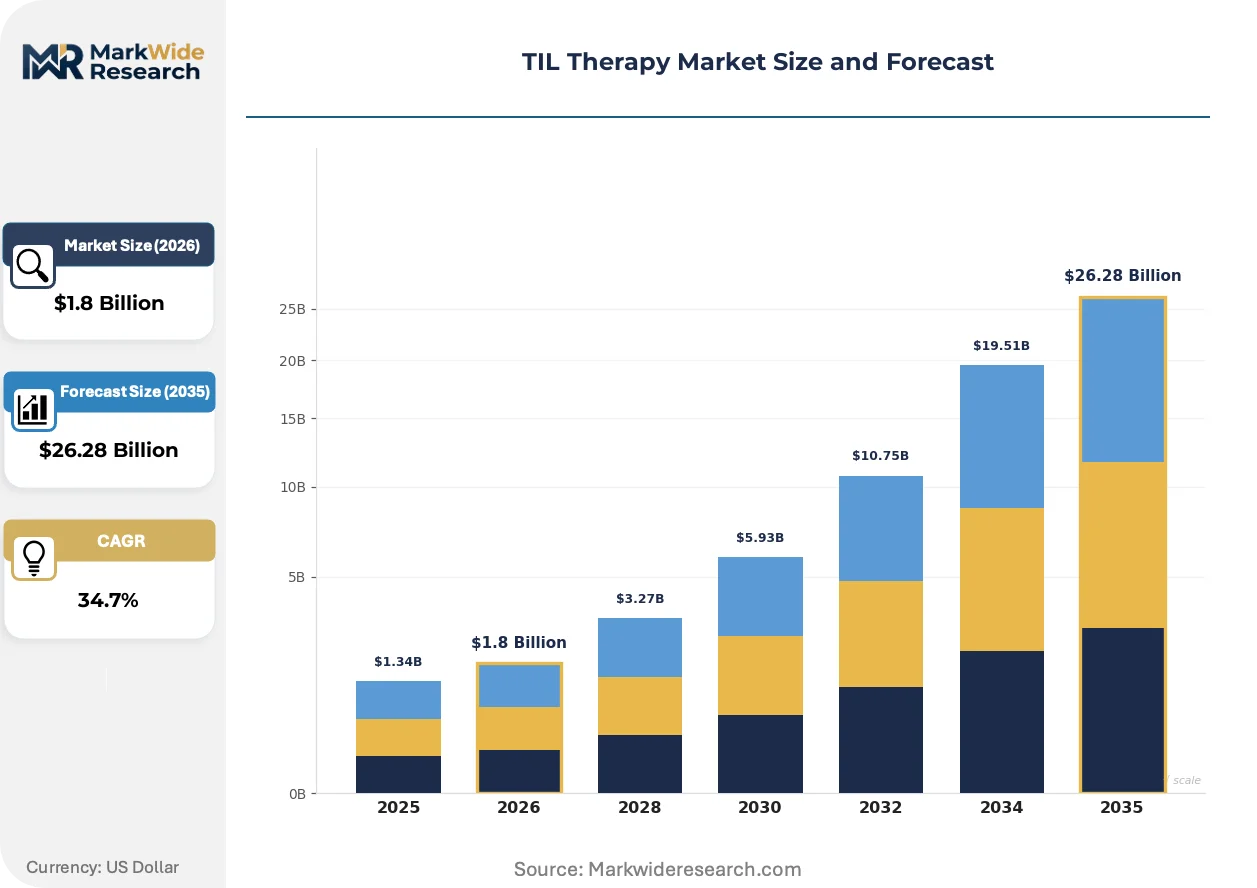
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $26.28 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: TIL Cells, Immune Checkpoint Inhibitors, Monoclonal Antibodies, CAR T-Cell Therapies End User: Hospitals, Oncology Clinics, Research Laboratories, Academic Institutions Administration Route: Intravenous, Subcutaneous, Intraarterial, Local Injection Treatment Stage: Adjuvant Therapy, Neoadjuvant Therapy, Palliative Care, Experimental Therapy |
| Companies Covered | Iovance Biotherapeutics, Bristol Myers Squibb, Obsidian Therapeutics, KSQ Therapeutics, Instil Bio, Cellectis, Incyte Corporation, REPROCELL, Intima Bioscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
TIL Therapy Market Trends and Innovations
Bioprocess automation and cytokine engineering are converging to reshape TIL manufacturing economics, while regulatory frameworks and care delivery models adapt to cell therapy complexity.
Synthetic IL-2 cytokine support is absorbing the cost structure historically tied to recombinant human IL-2 procurement. Contract development and manufacturing organizations are adopting engineered cytokine platforms to reduce per-dose input costs. This absorption is enabling batch scale-up that was previously constrained by growth factor economics.
EMA's Committee for Advanced Therapies coordinates centralized marketing authorization assessments across EU member states, creating procedural divergence from FDA timelines. European developers face extended review cycles for novel cell therapy manufacturing changes. TIL sponsors are responding with parallel-track filing strategies that front-load CMC package preparation.
Site-of-care economics are driving hospital systems to unbundle inpatient lymphodepletion from post-infusion monitoring. Freestanding oncology clinics are certifying for cytokine release syndrome management to capture ambulatory reimbursement. This shift is most visible in United States markets where CMS reimbursement decisions for cell therapy administration create margin pressure on traditional inpatient models.
TIL Therapy Market Segmentation
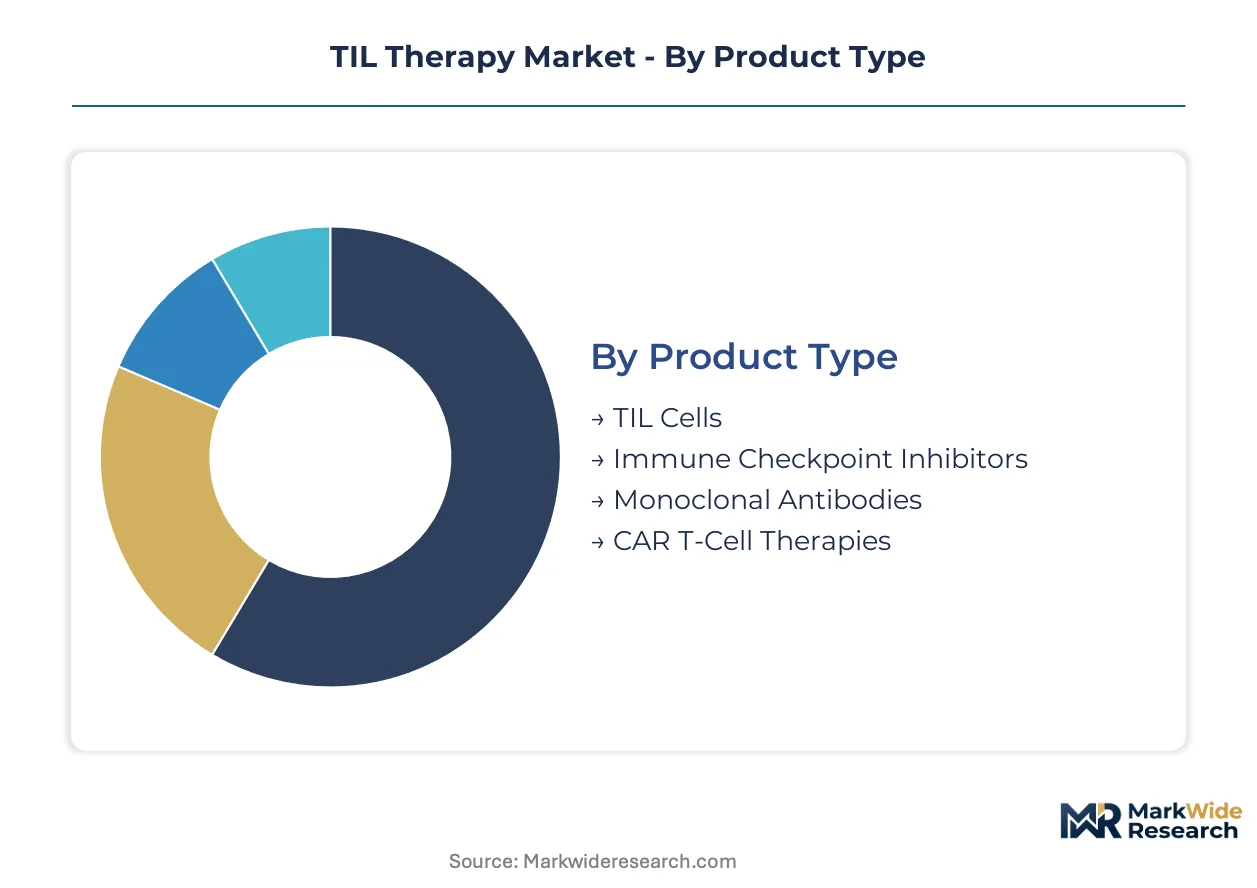
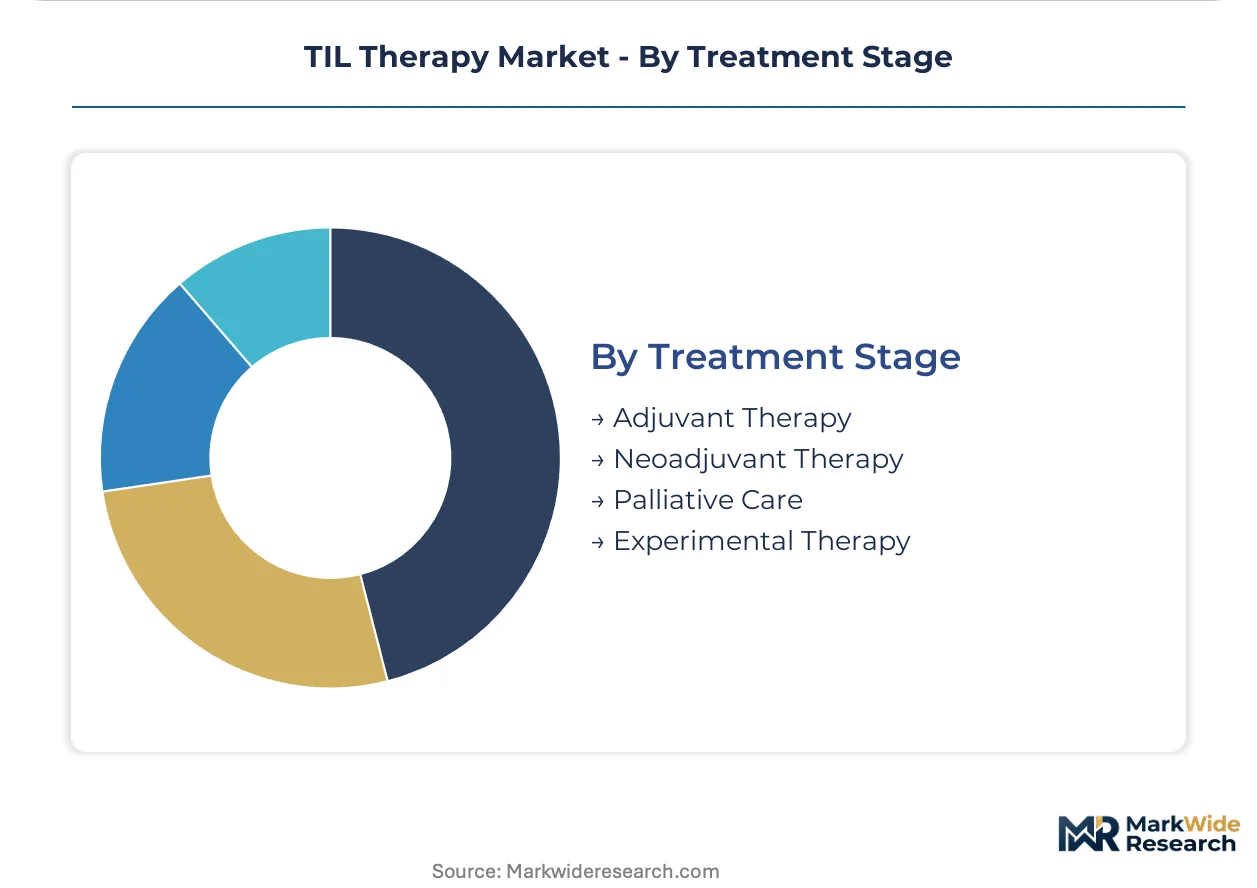
TIL therapy segmentation reveals how product architecture, care delivery settings, and clinical protocols intersect to determine commercial viability. Each dimension carries distinct regulatory, reimbursement, and operational implications for manufacturers and providers.
Product Type:
Cost tier differentiation separates autologous cell products from engineered biologics, with manufacturing complexity driving margin structure.
- TIL Cells:Patient-derived lymphocytes expanded ex vivo from resected tumor tissue under IL-2 stimulation. Demand concentrates at academic medical centers with dedicated GMP manufacturing partnerships, driven by solid tumor efficacy data in melanoma and cervical cancer.
- Immune Checkpoint Inhibitors:Systemic antibodies blocking PD-1/PD-L1 or CTLA-4 pathways to potentiate TIL persistence. Oncology clinics in the United States are expanding combination protocol adoption, constrained by CMS reimbursement timelines for novel regimen billing codes.
- Monoclonal Antibodies:Targeted biologics addressing tumor microenvironment modulation.
- CAR T-Cell Therapies:Genetically modified autologous T cells with synthetic receptors.
TIL Cells lead volumes today; Immune Checkpoint Inhibitors are gaining share fastest.
End User:
Site-of-care economics reshape where lymphodepletion and infusion occur, with reimbursement pressure driving ambulatory migration.
- Hospitals:Inpatient facilities managing high-dose chemotherapy conditioning and cytokine release syndrome. Major US teaching hospitals anchor demand through dedicated cell therapy units, though DRG-based payment compresses margins for extended stays.
- Oncology Clinics:Freestanding ambulatory centers certifying for post-infusion monitoring. Florida and Pennsylvania clusters are expanding fastest, enabled by streamlined CMS reimbursement for same-day cell therapy administration.
- Research Laboratories:Academic and commercial sites conducting protocol development.
- Academic Institutions:University-affiliated centers bridging clinical trial access and commercial translation.
Hospitals retain the largest patient volume; Oncology Clinics are expanding most quickly.
Administration Route:
Delivery mechanism selection depends on tumor location, vascular accessibility, and systemic toxicity risk tolerance.
- Intravenous:Systemic infusion following lymphodepletion, the standard for disseminated disease. US infusion centers favor this route for standardized nursing protocols and established reimbursement pathways.
- Local Injection:Direct intratumoral or regional delivery to concentrate effector cells. Specialized interventional radiology programs at MD Anderson and Memorial Sloan Kettering are building capacity, constrained by operator training requirements.
- Subcutaneous:Depot administration for sustained cytokine exposure.
- Intraarterial:Regional perfusion for organ-confined malignancies.
Intravenous dominates current protocols; Local Injection is climbing the fastest as interventional oncology matures.
Treatment Stage:
Clinical positioning relative to surgery and systemic therapy determines regulatory pathway and evidence requirements.
- Adjuvant Therapy:Post-surgical TIL administration to eliminate residual micrometastatic disease. US solid tumor programs are prioritizing this indication, supported by FDA's accelerated approval framework for recurrence-free survival endpoints.
- Neoadjuvant Therapy:Pre-operative TIL to downstage tumors and improve resectability. Early-phase trials at Sarah Cannon Research Institute and Moffitt Cancer Center are generating demand, limited by surgical scheduling coordination complexity.
- Palliative Care:Symptom-focused therapy in advanced refractory disease.
- Experimental Therapy:Investigational protocols outside approved indications.
Adjuvant Therapy leads current commercial focus; Neoadjuvant Therapy shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florida and Pennsylvania anchor the TIL therapy manufacturing footprint through centralized GMP facilities serving academic medical centers across the United States. The regulatory environment and reimbursement frameworks in select countries are determining where cell therapy infrastructure concentrates and how quickly patients gain access.
United States
Academic medical centers in Houston, New York, and Philadelphia are expanding dedicated TIL infusion units to serve solid tumor oncology programs. FDA's Center for Biologics Evaluation and Research governs IND and BLA pathways with accelerated approval timelines compressing development cycles. Iovance Biotherapeutics operates centralized manufacturing in Florida and Pennsylvania, achieving batch scale-up through automated closed-system bioreactors.
Germany
University hospitals in Munich and Heidelberg are building GMP partnerships for autologous cell therapy manufacturing. EMA's Committee for Advanced Therapies coordinates centralized assessments, creating procedural divergence from FDA timelines that extends review cycles. The BioRN cluster in Heidelberg is attracting TIL sponsors with parallel-track filing strategies for EU market entry.
United Kingdom
London and Manchester teaching hospitals are certifying for lymphodepletion and post-infusion monitoring under NHS specialized commissioning frameworks. The Medicines and Healthcare products Regulatory Agency aligns with EMA guidance while maintaining national flexibility for early access schemes. The Cell and Gene Therapy Catapult in London is supporting manufacturing technology transfer for domestic production.
Japan
PMDA's regenerative medicine framework is enabling conditional approval pathways for cell therapies in melanoma and cervical cancer indications. Tokyo and Osaka medical centers are adopting TIL protocols through the Sakigake designation system, which prioritizes review for innovative products. The Japan Agency for Medical Research and Development is funding academic-industry partnerships for cytokine engineering platforms.
Australia
TGA's provisional approval pathway is attracting sponsors seeking early market access with reduced evidence requirements. Melbourne and Sydney oncology networks are building ambulatory capacity for post-infusion cytokine release syndrome management. The Victorian Comprehensive Cancer Centre is coordinating multi-site trials for neoadjuvant TIL applications in solid tumors.
TIL Therapy Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and combination regimen development. The vendor base clusters around three strategic tiers: integrated biopharmaceuticals with immuno-oncology portfolios, pure-play cell therapy specialists with centralized GMP infrastructure, and cytokine engineering platforms addressing persistence limitations. Dominant competitive moves include strategic partnerships for combination protocol development and geographic expansion of manufacturing footprints to reduce autologous supply chain risk.
Within the integrated biopharmaceutical tier, Bristol Myers Squibb occupies a position leveraging checkpoint inhibitor assets for combination regimens. Among pure-play cell therapy specialists, Iovance Biotherapeutics anchors commercial infrastructure through Florida and Pennsylvania manufacturing facilities. Obsidian Therapeutics exemplifies the cytokine engineering archetype, differentiating through platforms that enhance TIL persistence. These three companies represent distinct strategic positions without direct product overlap.
| Leading Market Players |
|---|
| Iovance Biotherapeutics |
| Bristol Myers Squibb |
| Obsidian Therapeutics |
| KSQ Therapeutics |
| Instil Bio |
| Cellectis |
| Incyte Corporation |
| REPROCELL |
| Intima Bioscience |
| Others |
Pricing and Supply Chain Analysis
Recombinant human IL-2 procurement costs cascade through TIL therapy manufacturing economics, compressing margins at centralized GMP facilities in Florida and Pennsylvania before passing through to hospital reimbursement rates under DRG-based payment systems. Synthetic cytokine engineering platforms are absorbing these upstream input costs, enabling pricing tier differentiation between academic medical centers with captive manufacturing partnerships and oncology clinics reliant on third-party cell therapy supply.
Pricing Analysis
Input-cost pass-through from growth factor procurement dominates pricing structure, with synthetic IL-2 platforms enabling three-tier pricing structure across premium, standard, and economy levels. Premium tiers attach to academic medical centers with integrated GMP facilities and FDA Master File documentation, while standard tiers serve hospital systems under group purchasing organization contracts. Cost compression in economy tiers is intensifying because contract development and manufacturing organizations are competing on per-dose cytokine input costs. Academic medical centers with captive supply chains exhibit lowest price sensitivity; freestanding oncology clinics negotiating CMS reimbursement codes face highest price sensitivity.
Supply Chain Analysis
Direct-to-hospital channels handle autologous cell therapy demand from major US teaching hospitals, with centralized manufacturing nodes in Florida and Pennsylvania feeding regional infusion networks. Geographic supply concentrates in the United States, Germany, and Japan, where GMP facility qualification timelines and regulatory inspection protocols create entry barriers. Raw material dependencies center on recombinant cytokines, cryopreservation media, and closed-system bioreactor consumables. Single-source vulnerability in IL-2 growth factor supply creates batch release risk. Distribution runs through temperature-controlled logistics networks maintaining cryogenic chain integrity from tumor harvest through reinfusion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TIL therapy represents a late-cycle quality story as solid tumor oncology programs shift demand toward premium manufacturing specifications with validated potency assays and polyclonality documentation. This demand migration favors sponsors with integrated GMP infrastructure over contract-dependent competitors.
For Market Incumbents: Cement manufacturing scale advantages through backward integration into cytokine engineering platforms, reducing dependence on external growth factor suppliers. Expand capacity in Pennsylvania and Florida to capture ambulatory site-of-care migration as oncology clinics build post-infusion monitoring capacity. Priority lever rests on FDA Master File accumulation to accelerate partner facility qualification timelines against emerging CDMO competitors.
For New Entrants and Emerging Players: Launch via specialized cytokine engineering partnerships targeting checkpoint inhibitor combination protocols, the fastest-expanding adjuvant category. White space concentrates in neoadjuvant therapy indications at Sarah Cannon Research Institute and Moffitt Cancer Center networks, where surgical scheduling coordination complexity deters incumbent sponsors. Go-to-market angle centers on streamlined clonality assessment protocols reducing release specification friction.
For Investors and Strategic Acquirers: Consolidation pressure builds where GMP manufacturing talent scarcity extends facility qualification timelines beyond competitive windows. Long-term viability favors pure-play cell therapy specialists with centralized infrastructure over platform biotechs lacking commercial manufacturing experience. Acquisition target archetype: cytokine engineering platforms with demonstrated TIL persistence enhancement. Signal to watch is CMS reimbursement decision timing for outpatient cell therapy administration codes.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Automated closed-system bioreactors at Iovance facilities reduce per-batch labor intensity. |
| Regulatory Approval Pathway | FDA accelerated approval compresses IND-to-BLA timelines for autologous cell therapies. |
| Strategic Partnership | Checkpoint inhibitor pairing with Bristol Myers Squibb assets expands combination protocol addressable market. |
| Pipeline Diversification | Neoadjuvant therapy applications at Moffitt Cancer Center extend indication breadth beyond melanoma. |
| Reimbursement Strategy | CMS inpatient cell therapy administration decisions reshape site-of-care economics for hospital partners. |
Research Methodology
Direct dialogue with cell therapy manufacturing executives, regulatory affairs leads at FDA and EMA, hospital procurement managers, and payer access specialists grounded qualitative insights. Secondary validation drew from FDA BLA filings, EMA Committee for Advanced Therapies assessments, ClinicalTrials.gov protocol registrations, and CMS reimbursement coding databases. Bottom-up patient-flow modeling triangulated against top-down market size estimates from academic medical center expansion announcements and GMP facility capacity disclosures.
Market size and growth trajectory outputs reflect integrated modeling across product type, end user, administration route, and treatment stage segmentation dimensions. CAGRs were derived from patient volume forecasts weighted by manufacturing capacity expansion timelines and regulatory approval probability assessments. Industry-specific inputs included lymphodepletion inpatient day requirements, cytokine release syndrome incidence rates, and potency assay development cost curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA potency assay guidance finalization delays or EMA centralized assessment timeline extensions. Periodic stress-testing of base assumptions is recommended, particularly regarding CMS reimbursement decisions for autologous cell therapy administration and synthetic cytokine platform clinical validation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Irritable Bowel Syndrome (IBS) Treatment Market
Specialty Medicine
North America Cancer Therapy Market
Specialty Medicine
Biliary Atresia Treatment Market
Specialty Medicine
Optic Atrophy Management Market
Specialty Medicine
Chemotherapy Induced Peripheral Neuropathy Treatment Market
Specialty Medicine
Strep Throat Treatment Market
Specialty Medicine
Kinase Inhibitor in Autoimmune Diseases Market
Specialty Medicine
Liver Metastases Treatment Market
Specialty Medicine
Ankylosing Spondylitis Market
Specialty Medicine
North America Dry Eye Syndrome Market
Specialty Medicine
Borderline Personality Disorder Market
Specialty Medicine
Frontotemporal Dementia Management Market
Specialty Medicine
Hemophilia Market
Specialty Medicine
Global Hereditary Angioedema Therapeutics Market
Specialty Medicine
Diverticulitis Disease Market
Specialty Medicine
Ischemic Hepatitis Treatment Market