
 North America Digital Pathology Market | 2026-2036
North America Digital Pathology Market Size, Share, and Industry Trends Forecast 2026-2036
North America Digital Pathology Market Intelligence
The gap between enterprise-grade whole slide imaging systems and entry-level digital scanners is repositioning how vendors allocate R&D budgets across the North America Digital Pathology Market. Leica Biosystems Nussloch GmbH leverages its installed base of histology equipment to bundle scanner sales with consumables contracts. PathAI, Inc. specializes in AI-native image analysis workflows that command premium pricing from pharmaceutical partners. F. Hoffmann-La Roche Ltd. anchors its position through integrated diagnostics platforms that link digital pathology with companion testing.
Digital pathology encompasses the acquisition, management, interpretation, and sharing of digitized tissue specimen images at resolutions exceeding 20x optical magnification, enabling remote diagnosis and computational analysis. Whole slide imaging dominates hardware revenue while image analysis software captures expanding margin pools as laboratories seek automated quantification of biomarker expression. Cloud-based deployment is gaining traction among mid-sized diagnostic laboratories that lack capital for on-premise server infrastructure. Academic research institutes represent a concentrated demand node for telepathology solutions supporting multi-site collaboration.
FDA regulates whole slide imaging devices as Class II or Class III medical devices requiring premarket notification or approval, while HIPAA governs the storage and transmission of patient data across cloud-based pathology networks. The Digital Imaging and Communications in Medicine standard shapes interoperability requirements that influence purchasing decisions. Stakeholders must monitor evolving reimbursement policies for remote pathology interpretation, as coverage determinations by the Centers for Medicare & Medicaid Services will dictate adoption velocity among cost-constrained health systems.
Market Dynamics
Cloud-native image analysis platforms are compressing capital barriers for mid-sized diagnostic laboratories across the United States and Canada, forcing incumbent scanner vendors to restructure pricing architectures and accelerate software monetization timelines.
Growth Catalysts
- FDA 510(k) pathway for whole slide imaging:The FDA's premarket notification framework for digital pathology devices is clarifying validation requirements and reducing regulatory uncertainty for scanner manufacturers seeking primary diagnosis indications.
- Academic medical center procurement clusters:Northeastern United States academic hospitals are consolidating purchasing power through shared service organizations, creating volume anchors that justify vendor R&D investments in integrated workflows.
- AI-native computational pathology:Machine learning algorithms for biomarker quantification are expanding reimbursable service lines beyond traditional histopathology interpretation.
Market Restraints
- High-resolution data storage costs:Whole slide images exceeding 1 gigabyte per scan require specialized storage infrastructure that strains IT budgets at community hospital laboratories.
- Scanner hardware supply concentration:Precision optical components and sensor modules originate from concentrated Asian manufacturing bases, exposing North American vendors to logistics volatility.
- HIPAA cloud compliance complexity:Business associate agreement negotiations with cloud infrastructure providers extend deployment timelines for multi-site pathology networks.
Strategic Opportunities
- Canadian provincial health system digitization:Ontario and Quebec are allocating capital budgets for regional pathology networks that lack incumbent vendor relationships.
- Companion diagnostic-pharma partnerships:Contract research organizations are outsourcing image analysis for clinical trial endpoints, creating recurring revenue streams detached from hospital capital cycles.
- Remote pathology interpretation reimbursement:CMS coverage determinations for telepathology services are expanding addressable market beyond physical laboratory footprints.
Industry Challenges
- Computational pathology specialist shortage:Dual-trained pathologists with informatics competencies command compensation premiums that constrain laboratory hiring.
- Legacy LIS-PACS integration complexity:Proprietary data formats from existing scanner installations resist seamless interoperability with cloud-based analysis platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Digital Pathology Market |
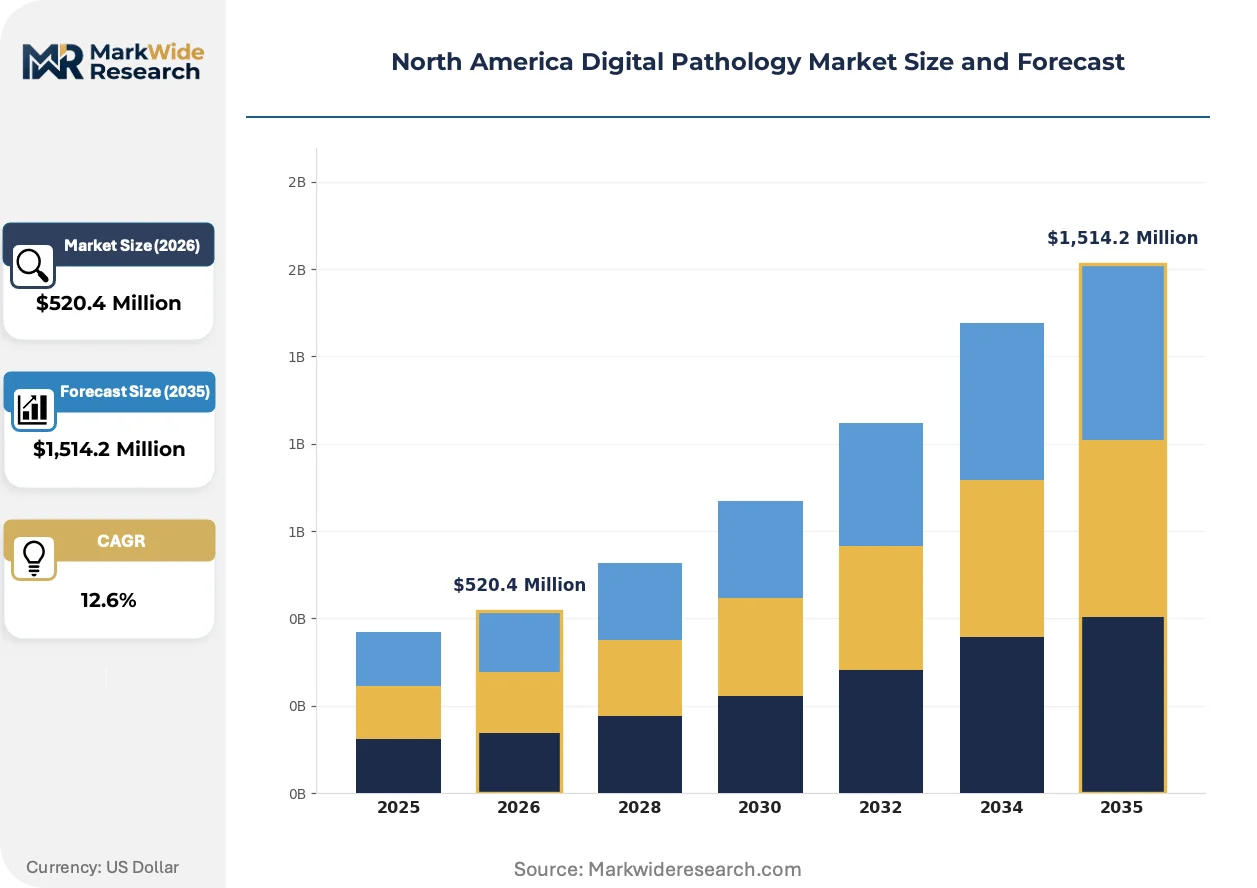
| Market Size in 2026 | $520.4 Million |
| Market Size in 2035 | $1,514.2 Million |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Slide Imaging, Digital Slide Scanners, Image Analysis Software, Telepathology Solutions End User: Hospitals, Academic Research Institutes, Pharmaceutical Companies, Diagnostic Laboratories Deployment: On-premise, Cloud-based, Hybrid, Server-based Solution: Workflow Solutions, Reporting Solutions, Image Management Solutions, Collaboration Tools |
| Companies Covered | Leica Biosystems Nussloch GmbH, F. Hoffmann-La Roche Ltd., Koninklijke Philips N.V., Hamamatsu Photonics, Inc., Akoya Biosciences, Inc., Proscia, Inc., Olympus Corporation, PathAI, Inc., Huron Digital Pathology, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Digital Pathology Market Strategic Shifts & Innovations
Artificial intelligence is migrating from research novelty to production-grade diagnostic utility, compressing development timelines for algorithm validation and forcing regulatory frameworks to adapt to continuous learning systems.
Multiplex immunofluorescence imaging is overtaking chromogenic immunohistochemistry in pharmaceutical research settings. Contract research organizations are adopting 7-9 color panel workflows for immuno-oncology biomarker studies. This technology shift is compressing tissue consumption per assay while expanding data dimensionality, forcing scanner manufacturers to prioritize spectral unmixing capabilities in next-generation hardware roadmaps.
FDA guidance on predetermined change control plans for machine learning-enabled devices is clarifying post-market modification pathways for algorithm developers. The framework permits locked algorithm updates without supplemental 510(k) submissions when validation protocols are pre-specified. Digital pathology vendors with companion diagnostic portfolios are restructuring quality management systems to accommodate iterative model improvements.
Subscription-based software licensing is displacing perpetual license sales among mid-sized independent laboratories. Vendors are unbundling image analysis modules from scanner hardware transactions, creating recurring revenue visibility. This purchasing pattern shift is most pronounced in Texas and Florida metropolitan markets where private equity-backed laboratory rollups prioritize operational expenditure flexibility over capital ownership.
North America Digital Pathology Market Segmentation
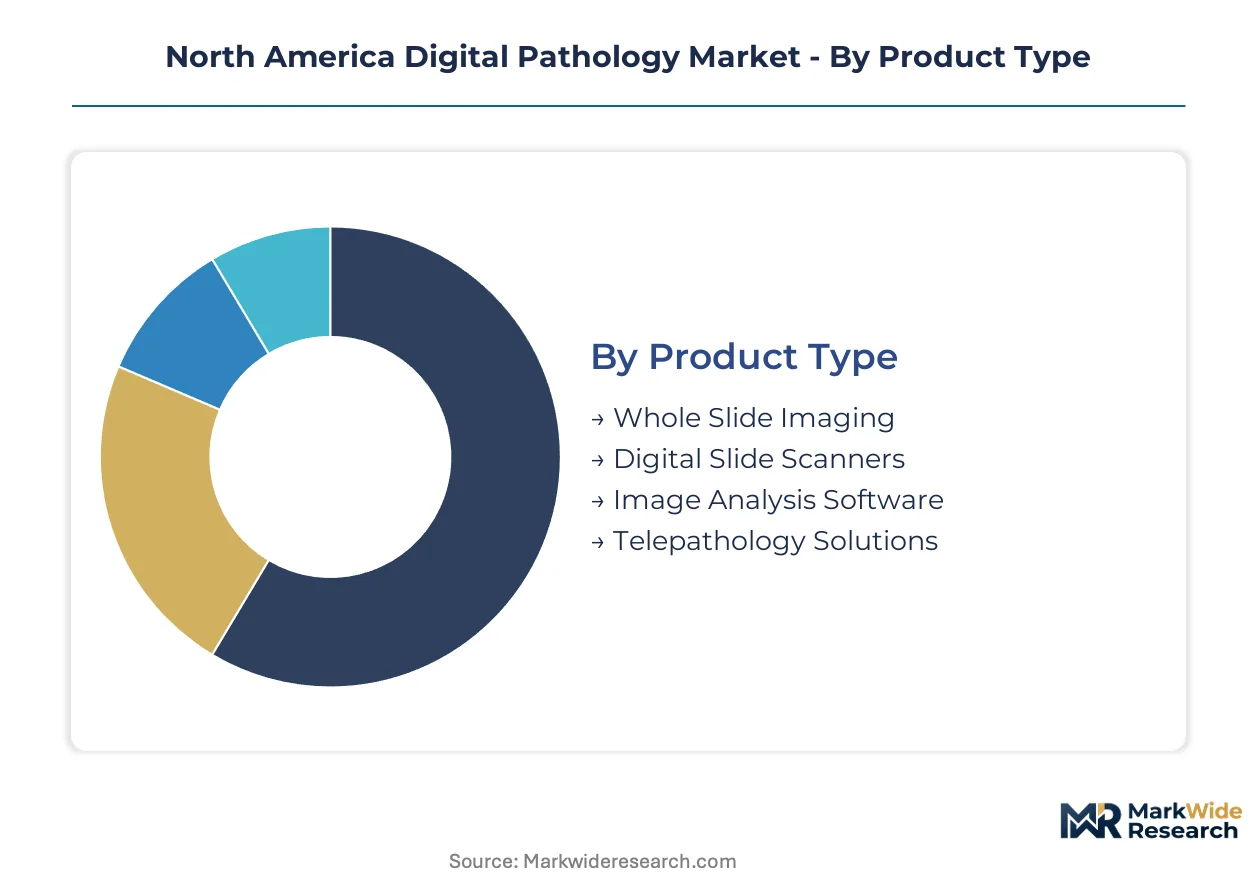
Digital pathology procurement decisions split across hardware performance tiers, software deployment models, and institutional workflow requirements. Understanding these segment boundaries clarifies where vendor R&D investments concentrate and which customer types drive margin expansion.
Product Type:
Capital allocation intensity varies sharply between scanner hardware and software-only purchases, with laboratories weighing optical resolution specifications against recurring license economics.
- Whole Slide Imaging:Enterprise-grade systems capture tissue specimens at 20x-40x optical magnification with automated slide handling. Northeastern United States academic medical centers anchor procurement volume for FDA-cleared primary diagnosis platforms.
- Image Analysis Software:AI-native algorithms for biomarker quantification and pattern recognition command premium pricing from pharmaceutical partners seeking computational pathology capabilities. Cloud-native licensing is displacing perpetual sales in mid-sized laboratories.
- Digital Slide Scanners:Entry-level and mid-range hardware targets independent pathology practices with lower throughput requirements.
- Telepathology Solutions:Real-time streaming and store-and-forward systems enable remote consultation across multi-site networks.
Volume sits with Whole Slide Imaging; growth tilts toward Image Analysis Software.
End User:
Institutional purchasing authority determines contract structure, with consolidated health systems negotiating enterprise licenses that independent laboratories cannot replicate.
- Diagnostic Laboratories:High-throughput reference laboratories process thousands of cases daily, driving scanner utilization rates that justify premium hardware investments. Cloud deployment preferences are most pronounced here due to IT infrastructure constraints.
- Academic Research Institutes:Multi-site collaboration requirements and grant-funded procurement cycles shape demand for telepathology and image sharing platforms. Spectral imaging capabilities for multiplex immunofluorescence research command priority in pharmaceutical partnership settings.
- Hospitals:Integrated delivery networks seek seamless LIS-PACS interoperability for surgical pathology workflows.
- Pharmaceutical Companies:Outsourced image analysis for clinical trial endpoints creates recurring revenue detached from hospital capital cycles.
Diagnostic Laboratories capture the heaviest equipment volume; Academic Research Institutes are expanding most quickly for AI-native analysis tools.
Deployment:
Data sovereignty requirements and HIPAA business associate agreement complexity create friction that shapes infrastructure decisions across institutional types.
- Cloud-based:Subscription models eliminate upfront server capital for mid-sized laboratories in Texas and Florida metropolitan markets where private equity rollups prioritize operational expenditure flexibility. FDA cybersecurity guidance for connected devices adds validation overhead.
- Hybrid:Split architectures keep identifiable patient data on-premise while pushing computational analysis to cloud infrastructure. This configuration is gaining traction among regional health systems navigating state-level privacy variations.
- On-premise:Fully captive infrastructure persists at flagship academic centers with dedicated informatics teams.
- Server-based:Legacy architectures remain in installed base but face replacement pressure from cloud-native alternatives.
On-premise retains installed base dominance; Hybrid deployment is climbing the fastest as compliance frameworks mature.
Solution:
Workflow integration depth determines switching costs, with vendors competing on LIS connectivity rather than standalone feature sets.
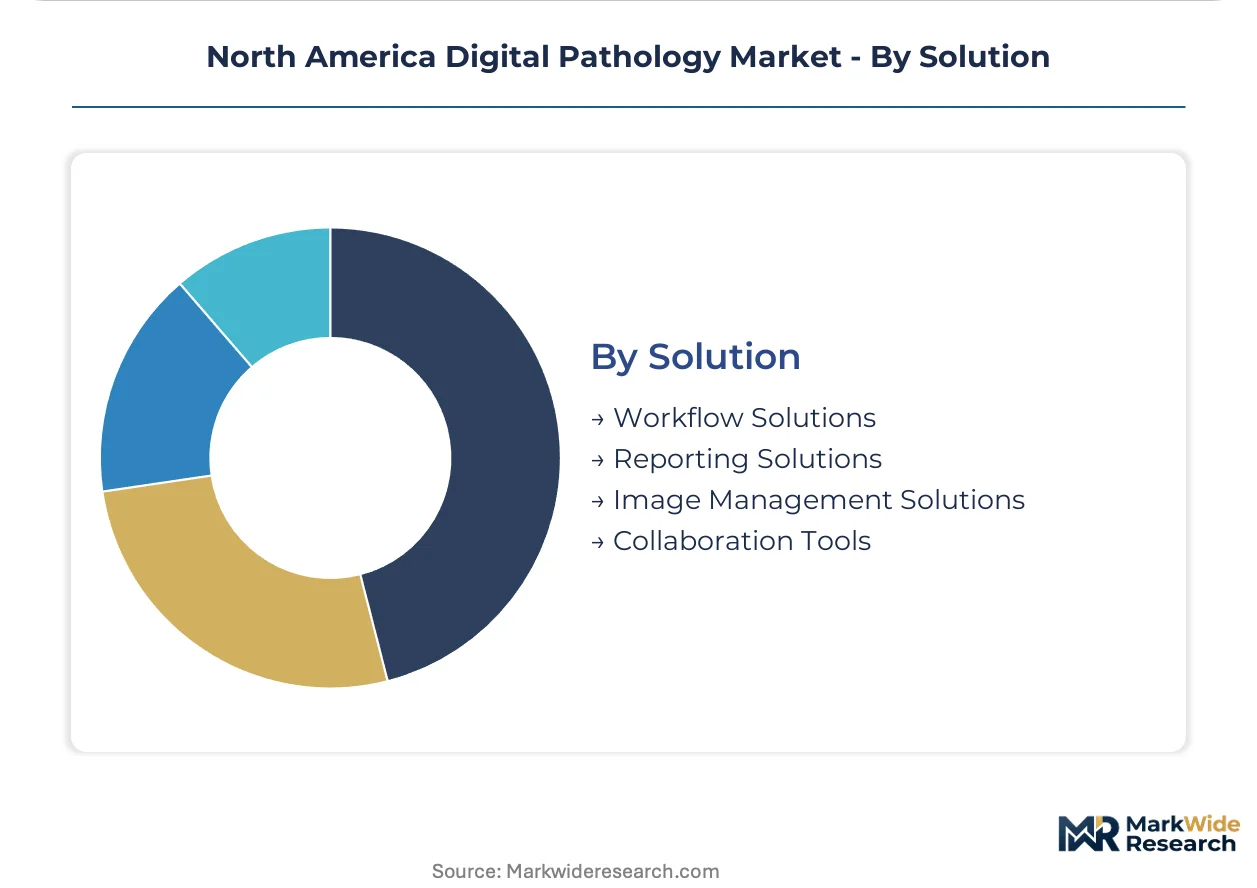
- Workflow Solutions:End-to-end specimen tracking from accessioning to sign-out reduces turnaround time variability. Integration with existing histology equipment creates vendor stickiness through bundled consumables contracts.
- Image Management Solutions:Vendor-neutral archives supporting DICOM standard interoperability enable multi-scanner environments. Storage cost per gigabyte for whole slide images strains IT budgets at community hospital laboratories.
- Reporting Solutions:Structured synoptic reporting aligns with CAP cancer protocol requirements.
- Collaboration Tools:Multi-pathologist review platforms support quality assurance and education workflows.
Workflow Solutions command the deepest integration spend; Image Management Solutions show the steepest expansion trajectory as data volumes compound.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Boston anchors digital pathology procurement intensity, where Massachusetts General Hospital and Dana-Farber Cancer Institute drive scanner validation protocols for primary diagnosis applications.
Northeastern United States
New York-Pennsylvania corridor health systems consolidate purchasing through shared service organizations, creating volume commitments that justify vendor R&D investments. FDA 510(k) clearance timelines for whole slide imaging devices compress as manufacturers pre-submit validation protocols. Philadelphia's academic medical cluster hosts multi-site telepathology networks linking suburban community hospitals with university pathology departments.
Southwestern United States
Texas metropolitan laboratories prioritize cloud-native deployment models to accommodate private equity-backed rollup expansion strategies. HIPAA business associate agreements with cloud infrastructure providers extend implementation timelines for multi-site networks. Houston's Texas Medical Center concentrates demand for AI-native image analysis tools supporting immuno-oncology biomarker quantification.
Southeastern United States
Florida diagnostic laboratories favor subscription-based software licensing to preserve operational expenditure flexibility under corporate ownership structures. State-level privacy variations complicate hybrid deployment architectures for regional health systems. Miami's international patient referral networks drive demand for telepathology consultation platforms linking Latin American specimens with US-based pathologists.
Canada
Ontario and Quebec provincial health systems allocate capital budgets for regional pathology network digitization lacking incumbent vendor relationships. Health Canada medical device licensing requirements parallel FDA frameworks while adding bilingual labeling obligations. Toronto's University Health Network validates whole slide imaging workflows for primary diagnosis ahead of provincial rollout decisions.
North America Digital Pathology Market Key Industry Players
Premium-margin players sit above commodity-margin players across software-hardware bundling strategies, with integrated diagnostics platforms commanding pricing power that standalone scanner vendors cannot replicate. Market structure consolidates around three tiers: multinational conglomerates with companion diagnostic portfolios, specialized scanner manufacturers with precision optical expertise, and AI-native software vendors with pharmaceutical partnerships. Dominant competitive moves include strategic partnerships linking hardware vendors with cloud infrastructure providers, and portfolio diversification into consumables bundling to capture recurring revenue streams.
Within the integrated diagnostics tier, F. Hoffmann-La Roche Ltd. and Koninklijke Philips N.V. occupy positions that exemplify platform consolidation strategies, anchoring end-to-end workflow solutions that link digital pathology with broader laboratory informatics ecosystems. Among specialized hardware manufacturers, Leica Biosystems Nussloch GmbH and Hamamatsu Photonics, Inc. represent archetypes of optical engineering heritage applied to whole slide imaging precision, while PathAI, Inc. sits within the AI-native tier exemplifying pharmaceutical partnership models for computational pathology development.
| Leading Market Players |
|---|
| Leica Biosystems Nussloch GmbH |
| F. Hoffmann-La Roche Ltd. |
| Koninklijke Philips N.V. |
| Hamamatsu Photonics, Inc. |
| Akoya Biosciences, Inc. |
| Proscia, Inc. |
| Olympus Corporation |
| PathAI, Inc. |
| Huron Digital Pathology |
| Others |
Cost & Logistics Intelligence
Backward integration into precision optical component manufacturing anchors pricing power for incumbent scanner vendors while exposing new entrants to supply bottlenecks and margin compression. FDA 510(k) validation requirements for whole slide imaging devices create certification barriers that favor established players with captive quality management systems and pre-cleared hardware platforms.
Pricing Analysis
Throughput-based pricing anchors enterprise scanner contracts, with laboratories paying per-slide fees or annual throughput tiers rather than capital purchase prices. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared primary diagnosis systems from research-grade hardware and entry-level devices. Cost compression in the mid-range tier is intensifying because cloud-native software vendors are unbundling analysis modules from hardware transactions. Independent pathology practices in Florida and Texas metropolitan markets exhibit highest price sensitivity, while northeastern academic medical centers prioritize optical resolution specifications over unit economics.
Supply Chain Analysis
FDA quality system regulation certification gates access to precision sensor modules and automated slide handling mechanisms sourced from Japan, Germany, and Taiwan. CMOS image sensors, precision motion control systems, and high-numerical-aperture objective lenses draw from concentrated Asian and European manufacturing bases. Single-source vulnerability persists for 40x optical magnification components used in enterprise-grade systems. Distribution runs through authorized dealer networks serving hospital procurement committees and laboratory capital planning cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is compressing margins for standalone hardware vendors as integrated diagnostics platforms capture recurring revenue through consumables bundling and companion diagnostic linkages. Incumbents must secure upstream control over optical component supply or downstream software monetization to defend position.
For Market Incumbents: Extend consumables bundling contracts to lock in scanner replacement cycles and capture recurring revenue streams detached from capital procurement freezes. Deepen software integration with laboratory information systems to raise switching costs against cloud-native entrants. FDA 510(k) validation protocols for AI-enabled devices represent a critical certification investment lever. Threat substitution from pharmaceutical partners building in-house computational pathology capabilities demands preemptive platform consolidation. For New Entrants and Emerging Players: Mid-sized Canadian provincial laboratories lack incumbent vendor relationships and present accessible procurement entry points for cloud-native workflow solutions. AI-native image analysis modules for multiplex immunofluorescence research command premium pricing from contract research organizations in the pharmaceutical segment. A subscription-first go-to-market model eliminates upfront capital barriers and aligns with private equity-backed laboratory rollup strategies in Texas and Florida. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated diagnostics conglomerates seeking computational pathology capabilities. Long-term viability favors AI-native software vendors with validated pharmaceutical partnerships over hardware manufacturers facing optical component supply concentration. The signal to watch is CMS coverage determinations for remote pathology interpretation, which would expand addressable market beyond physical laboratory footprints and trigger valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Premarket notification for whole slide imaging devices clarifies validation requirements for primary diagnosis indications. |
| Cloud Infrastructure Partnership | Business associate agreements with HIPAA-compliant providers accelerate deployment timelines for multi-site pathology networks. |
| Companion Diagnostic Integration | Linking digital pathology with biomarker testing captures premium pricing from pharmaceutical development partners. |
| AI Algorithm Validation | Predetermined change control plans under FDA guidance enable iterative model improvements without supplemental submissions. |
| Reimbursement Strategy Development | CMS coverage determinations for telepathology services expand addressable market beyond traditional laboratory footprints. |
Research Approach
Document review covered FDA 510(k) filings, CMS reimbursement determinations, and Health Canada medical device licensing records, complemented by interviews with hospital pathology department directors, diagnostic laboratory operations managers, biomedical engineers, and GPO contract specialists. Secondary validation drew from DICOM standard documentation, CAP cancer protocol guidelines, and SEC filings of publicly traded diagnostics companies. Bottom-up scanner shipment estimates and top-down healthcare IT spending allocations were triangulated against provincial health system capital budget disclosures.
Cross-referencing historical procurement patterns against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include hardware performance tier, software deployment model, end-user institution type, and regional regulatory cluster. CAGRs were derived from curve-fitting approaches applied to validated installation base data and subscription revenue recognition patterns. Forecast inputs incorporated FDA clearance timeline assumptions and cloud infrastructure adoption elasticity estimates.
Revisions become necessary when HIPAA business associate agreement negotiations materially extend deployment timelines or when optical component supply disruptions alter hardware availability assumptions. Forecasts reflect documented assumptions about reimbursement policy evolution and academic medical center procurement consolidation trajectories. A model refresh is warranted upon material change in CMS telepathology coverage determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
France Computed Tomography Market
Medical Imaging
3D Medical and Surgical Imaging Market
Medical Imaging
Global Computed Tomography (CT) Market
Medical Imaging
Coronary Heart Disease Diagnostic Imaging Market
Medical Imaging
Spain Digital Radiology Market
Medical Imaging
Africa Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Ultrasound Systems Market
Medical Imaging
France Magnetic Resonance Imaging Market
Medical Imaging
United Kingdom Nuclear Imaging Market
Medical Imaging
Global Single-Photon Emission Computed Tomography (SPECT) Market
Medical Imaging
Latin America Medical Imaging Software Market
Medical Imaging
Chile Diagnostic Imaging Equipment Market
Medical Imaging
China Medical Imaging Market
Medical Imaging
US and Europe Digital Pathology Market
Medical Imaging
Canada Computed Tomography Market
Medical Imaging
Contrast Media/Contrast Agents Market