
 Latin America Medical Imaging Software Market | 2026-2036
Latin America Medical Imaging Software Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Medical Imaging Software Market Foresight
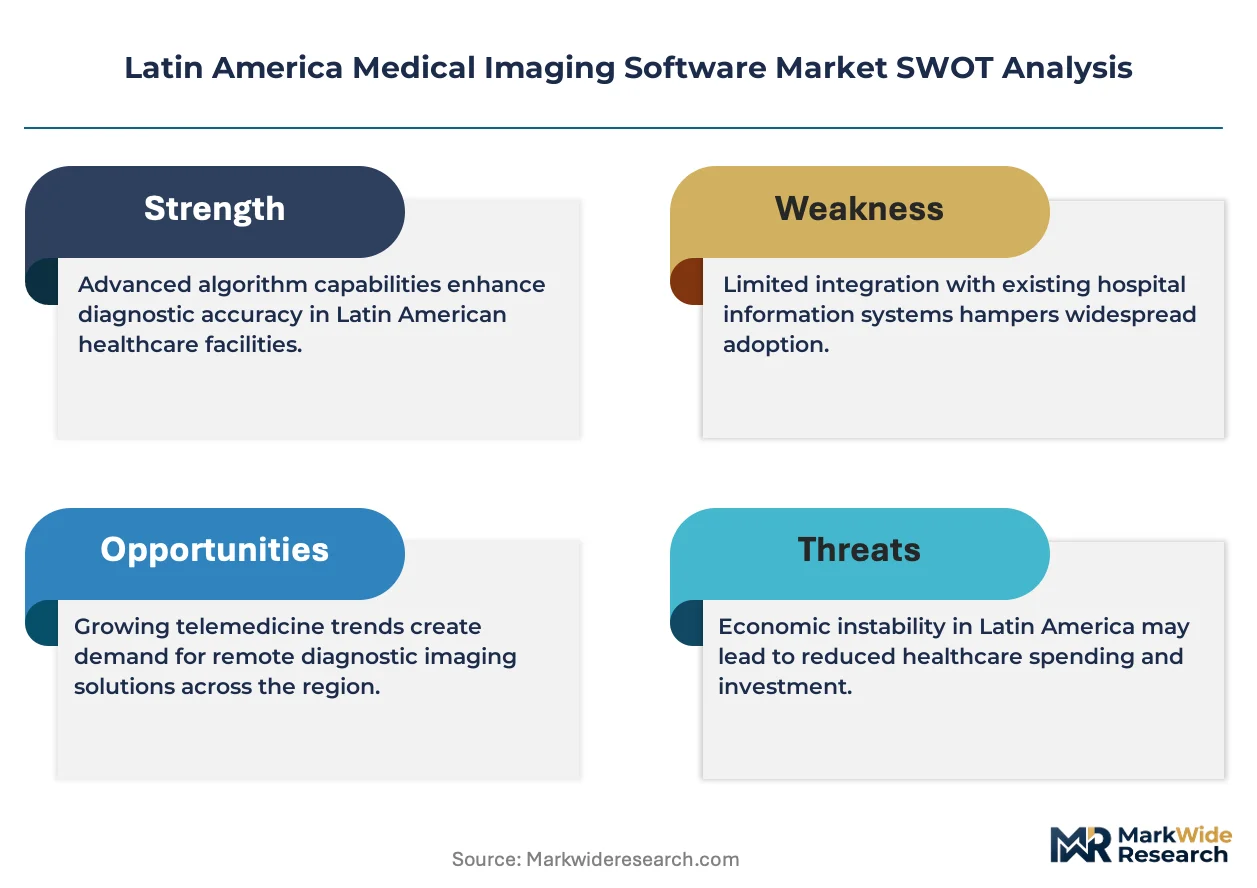
CE marking alignment requirements for imported medical devices is recalibrating the cost-of-entry calculus for software vendors entering Latin America. GE Healthcare leverages extensive service infrastructure to sustain installed-base loyalty across Brazilian tertiary hospitals. Siemens Healthcare anchors regional R&D partnerships that deepen localization of AI-powered diagnostic modules.
Latin America medical imaging software encompasses platforms that acquire, process, store, and transmit diagnostic images using DICOM interoperability standards and HL7 FHIR protocols to enable clinical decision support. These systems integrate picture archiving and communication capabilities with vendor-neutral archives to unify radiology, cardiology, and mammography workflows across distributed care networks. Diagnostic imaging currently dominates product-type revenue as hospitals modernize legacy CT and MRI interfaces, while AI-powered tools within the technology dimension represent the fastest-expanding segment as neural-network-based lesion detection gains regulatory traction. Cloud-based deployment is displacing on-premises installations among mid-sized clinics seeking scalable subscription models without capital-intensive server commitments.
ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia enforce software-as-medical-device classifications that mandate clinical validation documentation and post-market surveillance protocols, elevating compliance burdens for new entrants. The EU MDR and FDA predicate rules indirectly shape Latin American standards as multinational manufacturers harmonize quality systems across jurisdictions. Stakeholders must monitor how national regulators incorporate IMDRF machine-learning guidance into domestic software approval pathways.
Market Dynamics
Cloud migration is restructuring competitive positioning across Latin America medical imaging software as mid-sized clinics abandon capital-intensive server infrastructure for subscription-based platforms. ANVISA's streamlined digital health framework accelerates this shift by reducing registration timelines for software-as-medical-device classifications.
Growth Catalysts
- Diagnostic center consolidation:Brazil's tertiary hospital networks are centralizing radiology operations into shared service models that demand interoperable PACS-VNA platforms. This concentration forces software vendors to prioritize DICOM-native cloud architectures.
- ANVISA's 2023 digital health resolution:The Brazilian regulator's clarified software-as-medical-device pathway eliminates redundant clinical validation steps for AI-powered diagnostic modules. Manufacturers now route algorithm updates through streamlined post-market surveillance protocols.
- HL7 FHIR protocol adoption:Mexico's metropolitan hospital systems are mandating FHIR-compliant interfaces for electronic health record integration. This technical requirement pulls imaging software vendors into mandatory interoperability investments.
Market Restraints
- Input cost volatility in GPU compute:Cloud-based AI inference workloads depend on NVIDIA data center hardware subject to export control fluctuations. Latin American clinics face unpredictable subscription pricing as providers pass through silicon scarcity premiums.
- Supply concentration in PACS core engines:Three North American vendors control the underlying archive technologies licensed across Brazilian diagnostic centers. This dependency creates vulnerability to licensing term renegotiation and feature deprecation.
- CE marking alignment burdens:European Union MDR conformity requirements for imported medical devices force Latin American software vendors into parallel quality system documentation. Smaller developers lack resources for dual-track regulatory maintenance.
Strategic Opportunities
- Colombian secondary city penetration:Medellín and Cali hospital networks remain underpenetrated by enterprise imaging platforms. Vendors can establish reference sites before competitors consolidate these metropolitan markets.
- AI-IoT convergence in point-of-care ultrasound:Handheld probe manufacturers are embedding neural-network-based lesion detection at the edge. Software vendors can capture recurring revenue through per-scan algorithm licensing models.
- COFEPRIS fast-track pilot for SaMD:Mexico's regulator is testing expedited review pathways for software with predicate approvals from FDA or Health Canada. Early entrants gain 6-12 month first-mover advantages in metropolitan hospital procurement cycles.
Industry Challenges
- Radiology informatics specialist scarcity:Brazilian diagnostic centers cannot source sufficient PACS administrators and DICOM integration engineers. Vendors must absorb training costs or risk implementation delays that trigger contract cancellations.
- Legacy modality interface fragmentation:Decade-old CT and MRI machines across Latin American public hospitals use proprietary communication protocols. Cloud-native platforms require expensive middleware development to maintain connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Medical Imaging Software Market |
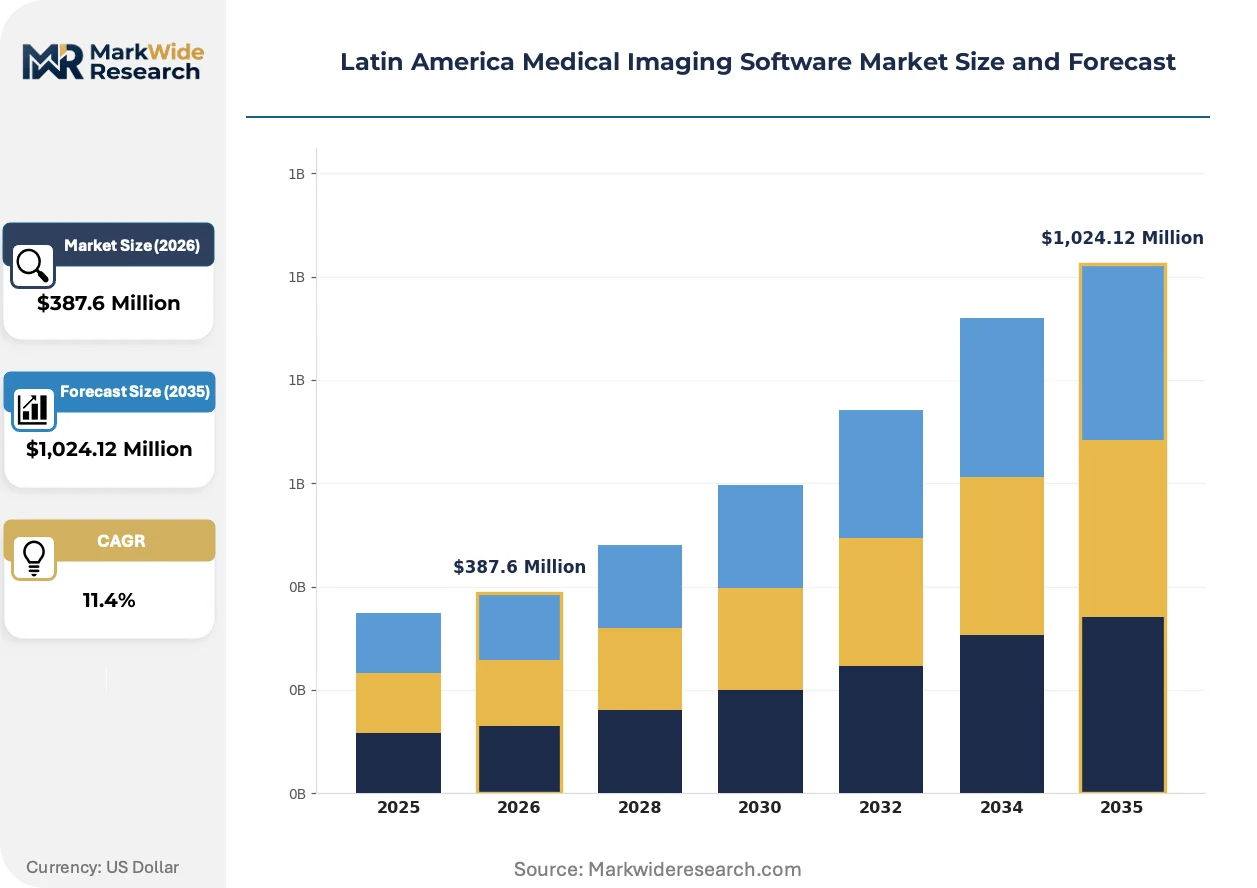
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Imaging, Radiology Software, Cardiology Systems, Mammography Solutions End User: Hospitals, Clinics, Diagnostic Centers, Research Institutes Deployment: Cloud-Based, On-Premises, Hybrid Solutions, Web-Based Technology: 3D Imaging, AI-Powered Tools, Visualization Software, Reporting Tools |
| Companies Covered | Canon Medical Systems Corporation, Carestream Health, GE Healthcare, Sectra AB, Esaote SpA, Siemens Healthcare, Agfa Gevaert HealthCare, MIM Software Inc., Philips Healthcare, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Medical Imaging Software Market Shifts & Advancements
Neural-network-based diagnostic assistance is compressing radiologist review cycles while forcing regulatory frameworks to adapt validation requirements for continuously learning algorithms. Three interconnected developments are reshaping how imaging software creates and captures value.
Vendor-neutral archive technology is integrating AI-powered metadata extraction to automate study routing and protocol selection. Colombian hospital networks are deploying these platforms to unify cardiology and mammography workflows without replacing existing modalities. The structural consequence is collapsing the traditional separation between image storage and clinical decision support functions.
ANVISA's incorporation of IMDRF machine-learning guidance into domestic software approval pathways is mandating predetermined change control plans for algorithm updates. Manufacturers must now document performance drift monitoring before receiving commercial authorization. Brazilian diagnostic centers purchasing AI-enabled platforms are demanding these compliance packages as standard contract terms.
Radiology departments are unbundling after-sales service from perpetual license agreements and negotiating outcome-based performance guarantees for AI diagnostic accuracy. Mexico's largest private hospital chains are leading this procurement evolution, replacing traditional maintenance contracts with subscription tiers tied to false-negative rate thresholds. The shift is most visible in Mexico City and Guadalajara metropolitan networks where consolidated purchasing power enables aggressive vendor negotiation.
Latin America Medical Imaging Software Market Segmentation
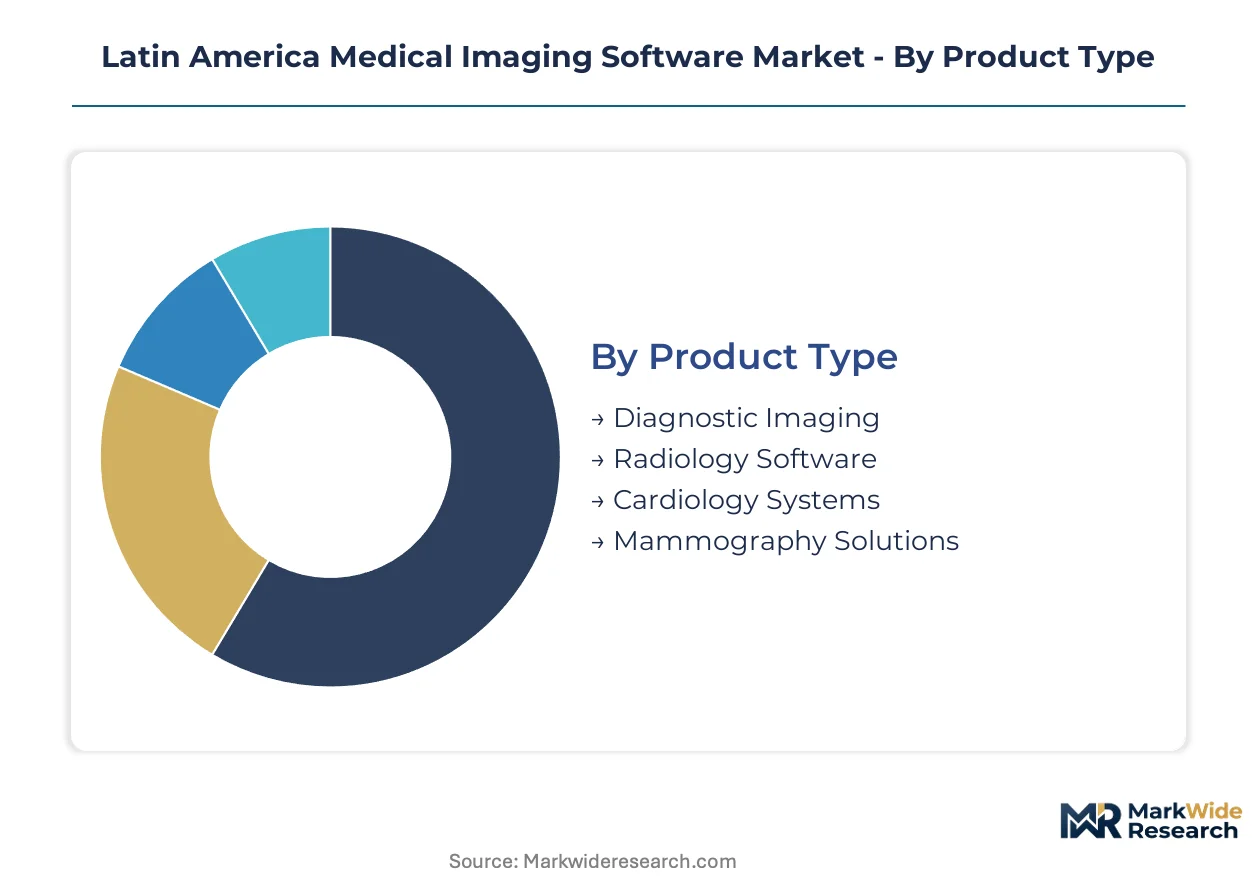
Segmentation reveals how software architectures map to distinct infrastructure maturity levels across Latin American healthcare networks. Each dimension exposes different integration constraints and procurement priorities that vendors must navigate.
Product Type:
Standalone imaging modules demand deeper workflow integration than embedded systems, creating divergent implementation timelines for hospital IT departments.
- Diagnostic Imaging:Core PACS platforms acquire, store, and distribute CT, MRI, and X-ray studies using DICOM 3.0 standards. Brazilian tertiary hospitals concentrate procurement here as they modernize legacy archive infrastructure to support multi-site radiology networks. The segment commands the largest installed base but faces margin compression from cloud-native competitors.
- Radiology Software:Workflow orchestration tools manage study prioritization, radiologist assignment, and turnaround-time analytics. Mexico's metropolitan hospital systems prioritize these platforms to reduce report backlogs in high-volume emergency departments. Integration with existing EHR systems drives vendor selection criteria.
- Cardiology Systems:Specialized modules handle echocardiogram and catheterization lab image analysis with dedicated measurement protocols.
- Mammography Solutions:Breast imaging platforms incorporate CAD algorithms and density assessment tools for screening programs.
Diagnostic Imaging leads volumes today; AI-Powered Tools within broader product portfolios are gaining share fastest.
End User:
Procurement sophistication varies sharply across facility types, with cost-tier differentiation determining accessible feature sets.
- Hospitals:Enterprise imaging platforms serving radiology, cardiology, and surgical departments demand vendor-neutral archive architectures and HL7 FHIR connectivity. Brazil's hospital networks in São Paulo and Rio de Janeiro anchor regional demand for integrated suites. Capital budgets constrain public sector adoption timelines.
- Diagnostic Centers:Specialized imaging facilities prioritize high-throughput PACS with automated study routing and sub-specialist teleradiology connectivity. Colombian independent diagnostic chains are consolidating procurement to negotiate volume-based SaaS pricing. Cloud migration accelerates fastest in this segment.
- Clinics:Mid-sized outpatient facilities favor lightweight web-based viewers with basic measurement tools.
- Research Institutes:Academic medical centers require advanced visualization and quantitative imaging biomarker capabilities.
Hospitals dominate current revenue; Diagnostic Centers are expanding most quickly as consolidation creates purchasing leverage.
Deployment:
Infrastructure ownership models determine capital commitment levels and data sovereignty compliance burdens for Latin American providers.
- Cloud-Based:Subscription platforms eliminate server hardware procurement and shift IT staffing burdens to vendors. Mexican clinics in Guadalajara and Monterrey are migrating fastest to escape capital expenditure constraints. ANVISA's streamlined SaMD registration accelerates vendor onboarding for these deployments.
- Hybrid Solutions:Mixed architectures keep sensitive studies on local storage while leveraging cloud compute for AI inference. Brazilian diagnostic centers adopt this model to satisfy data residency requirements while accessing neural-network diagnostic tools. Complexity elevates integration costs.
- On-Premises:Traditional server-based installations persist in public hospitals with limited connectivity infrastructure.
- Web-Based:Browser-accessible viewers serve remote radiologist reading workflows without thick-client installation.
On-Premises retains the largest installed footprint; Cloud-Based deployment shows the steepest expansion trajectory.
Technology:
Algorithmic sophistication tiers separate premium positioning from commoditized visualization capabilities.
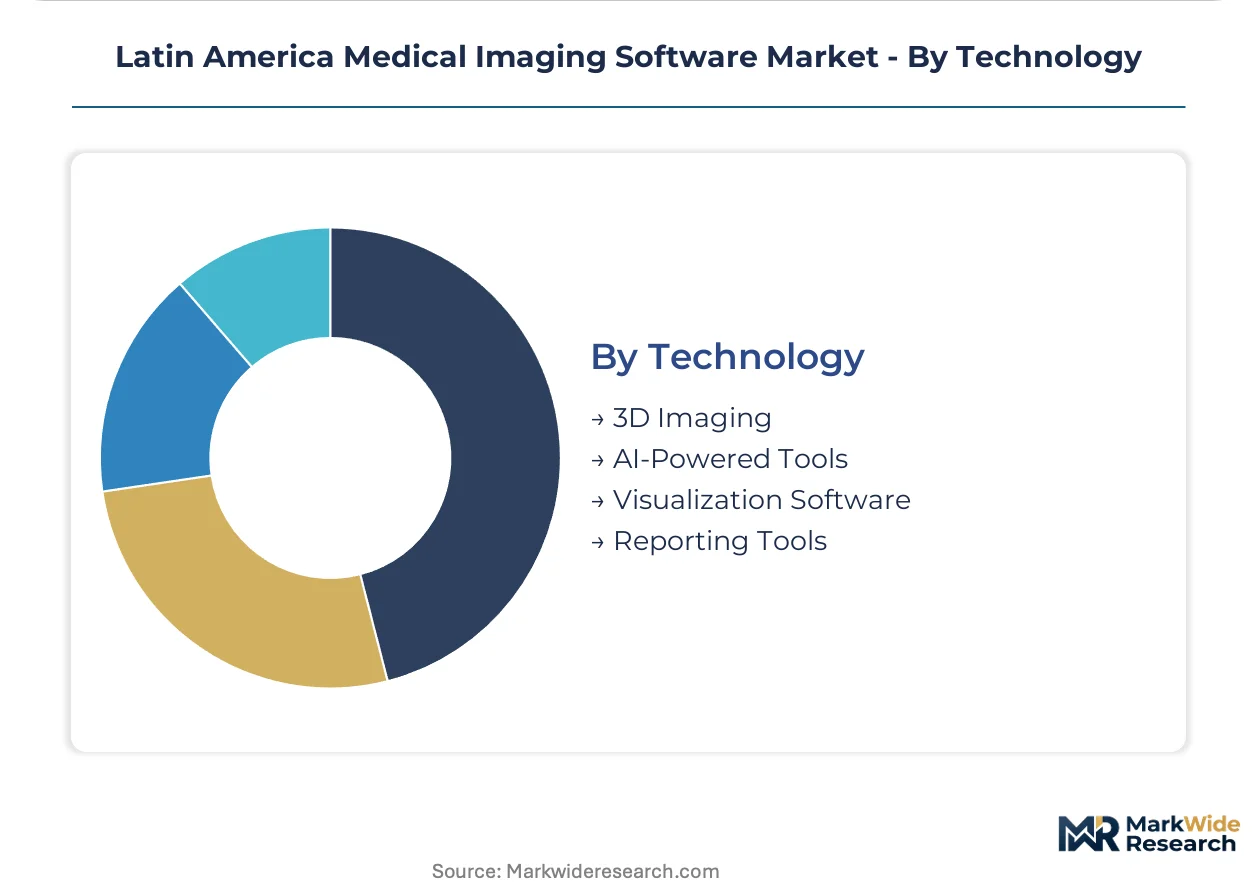
- AI-Powered Tools:Neural-network modules for lesion detection, quantification, and prioritization embed within PACS workflows. Brazilian radiology groups are piloting FDA-cleared algorithms for lung nodule and intracranial hemorrhage screening. ANVISA's predetermined change control requirements add compliance documentation burdens.
- 3D Imaging:Volume rendering and multi-planar reconstruction tools support surgical planning and interventional guidance. Colombian cardiovascular centers deploy these for structural heart procedure planning. Hardware acceleration dependencies limit deployment flexibility.
- Visualization Software:Core image display and manipulation tools form the baseline capability layer.
- Reporting Tools:Structured reporting templates and voice recognition integration streamline documentation workflows.
Visualization Software anchors current implementations; AI-Powered Tools are climbing the fastest as regulatory pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiology informatics specialists concentrate in São Paulo and Mexico City, anchoring deployment capacity for enterprise imaging platforms across the region's largest metropolitan hospital networks.
Brazil
Diagnostic center consolidation in São Paulo and Rio de Janeiro drives demand for interoperable PACS-VNA platforms. ANVISA's 2023 digital health resolution streamlines software-as-medical-device registration, reducing approval timelines for AI-powered modules. The São Paulo metropolitan corridor hosts the region's densest concentration of tertiary hospital networks modernizing legacy CT and MRI infrastructure.
Mexico
Metropolitan hospital systems in Mexico City and Guadalajara mandate HL7 FHIR-compliant interfaces for electronic health record integration. COFEPRIS pilots expedited review pathways for software with FDA or Health Canada predicate approvals, compressing procurement cycles by 6-12 months. Guadalajara's diagnostic chains are migrating fastest to cloud-based subscription models to escape capital expenditure constraints.
Colombia
Independent diagnostic chains in Medellín and Cali are consolidating procurement to negotiate volume-based SaaS pricing for enterprise imaging platforms. INVIMA enforces software-as-medical-device classifications requiring clinical validation documentation and post-market surveillance protocols. Medellín hospital networks deploy vendor-neutral archive technology with AI-powered metadata extraction to unify cardiology and mammography workflows.
Argentina
Public hospital modernization programs in Buenos Aires prioritize diagnostic imaging infrastructure upgrades amid fiscal constraints on capital budgets. The national pharmaceutical and medical device regulator maintains alignment with international standards for software validation. Buenos Aires anchors demand for lightweight web-based viewers serving remote radiologist reading workflows without thick-client installation.
Chile
Santiago's private hospital networks invest in AI-powered lesion detection tools for lung nodule and intracranial hemorrhage screening programs. The national health regulator incorporates IMDRF machine-learning guidance into domestic software approval pathways, mandating predetermined change control plans. Santiago's cardiovascular centers deploy 3D imaging volume rendering tools for structural heart procedure planning.
Latin America Medical Imaging Software Market Competitive Landscape
The competitive structure tilts toward diversified healthcare technology conglomerates with established service infrastructure. North American and European conglomerates with imaging hardware legacies dominate installed-base retention through bundled software-service contracts. Three strategic archetypes populate the landscape: full-stack diagnostic platform providers, specialized PACS pure-plays, and AI-native diagnostic software developers. M&A activity concentrates on algorithm licensing capabilities, while geographic expansion targets Colombian and Mexican secondary cities ahead of competitor consolidation.
Among diversified healthcare technology conglomerates, GE Healthcare and Siemens Healthcare exemplify the full-stack archetype, anchoring regional competition through extensive service infrastructure and R&D partnerships that deepen localization of diagnostic modules. Philips Healthcare occupies a position within this tier, representing the European-origin conglomerate vector competing for tertiary hospital loyalty across Brazilian and Mexican metropolitan networks.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Carestream Health |
| GE Healthcare |
| Sectra AB |
| Esaote SpA |
| Siemens Healthcare |
| Agfa Gevaert HealthCare |
| MIM Software Inc. |
| Philips Healthcare |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between ANVISA-validated AI modules and basic visualization tools creates parallel pricing tracks that mirror supply chain stratification across Brazilian and Mexican procurement channels. Premium tiers command bundled implementation support while commodity offerings compete on subscription elasticity alone.
Pricing Analysis
Bundled perpetual licenses with multi-year service contracts dominate Brazilian tertiary hospitals, while unbundled SaaS tiers penetrate Mexican diagnostic centers seeking monthly payment flexibility. Price differentiation rests on ANVISA registration status and cloud-native architecture maturity. Pricing pressure intensifies in the mid-market as North American vendors discount legacy PACS conversions to defend installed bases. Public hospital networks exhibit highest price sensitivity; consolidated private diagnostic chains leverage volume scale for steeper SaaS discounts.
Supply Chain Analysis
Regional distribution centers in São Paulo and Mexico City anchor hub-and-spoke fulfillment for software deployment kits and GPU compute hardware. Core PACS engines concentrate in the United States, Germany, and Japan, while AI inference chips draw from Taiwan and South Korea fabrication. Single-source vulnerability in NVIDIA data center GPU supply creates procurement bottlenecks for cloud-based AI workloads. Distribution runs through authorized service partners with biomedical engineering certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's 2023 digital health resolution compounds regulatory-driven demand by validating AI-powered diagnostic modules as reimbursable medical devices, creating procurement urgency across Brazilian hospital networks.
For Market Incumbents: To counter cloud-native challengers eroding mid-market share, GE Healthcare and Siemens Healthcare should deepen backward integration into edge-computing hardware partnerships while expanding captive training academies for PACS administrators in São Paulo. Certification investment in predetermined change control documentation will anchor enterprise contract renewals. For New Entrants and Emerging Players: Direct-to-clinic SaaS channels offer the lowest friction entry path for AI-native developers targeting Colombia's secondary cities. White-space concentration in Medellín and Cali independent diagnostic chains permits reference-site establishment before incumbent consolidation. COFEPRIS fast-track pilot participation accelerates Mexican metropolitan procurement cycles. For Investors and Strategic Acquirers: Consolidation pressure builds where radiology informatics specialist scarcity constrains implementation velocity for pure-play AI vendors. Five-to-ten year viability favors platforms with ANVISA-registered algorithm portfolios and established Brazilian service infrastructure. Watch FDA-cleared lesion detection algorithms gaining Brazilian regulatory equivalence as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA SaMD Registration Pathway | Streamlined validation accelerates AI module commercialization across Brazilian diagnostic networks. |
| Hospital System Partnership | Reference site agreements in São Paulo tertiary networks anchor regional expansion credibility. |
| Software Companion Development | FHIR-compliant EHR integration modules satisfy Mexico City metropolitan procurement mandates. |
| Geographic Expansion | Secondary city penetration in Medellín and Cali precedes competitor consolidation in Colombia. |
| Strategic Partnership | GPU cloud compute alliances mitigate silicon scarcity exposure for AI inference workloads. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down vendor shipment tracking forms the analytical core of this study. Primary interviews with radiology department heads, biomedical engineers, GPO contracts managers, and ANVISA regulatory consultants combined with secondary validation from hospital procurement databases, ANVISA registration filings, and COFEPRIS expedited pathway disclosures. Triangulation across DICOM adoption surveys and HL7 FHIR implementation reports verified segment-level demand estimates.
Input-output matrices mapped software deployment volumes against infrastructure maturity indices across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user facility type, technology sophistication tier, and regional regulatory cluster. CAGRs derived from curve-fitting historical adoption patterns against ANVISA registration velocity and cloud subscription growth trajectories. Forecast inputs incorporated GPU compute cost elasticity and radiologist workforce expansion rates.
The model assumes a particular technology adoption path; alternative pathways for edge-computing AI inference would alter the outlook if handheld probe manufacturers accelerate embedded neural-network deployment. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and data sovereignty enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
South Korea Mammography Market
Medical Imaging
Argentina Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Portable Ultrasound Market
Medical Imaging
Global Elastography Imaging Market
Medical Imaging
Molecular Imaging Market
Medical Imaging
Global Computed Tomography (CT) Market
Medical Imaging
Japan Diagnostic Imaging Market
Medical Imaging
South Korea Digital X-Ray Market
Medical Imaging
Industrial Radiography Market
Medical Imaging
Digital Radiography Detectors Market
Medical Imaging
Structural Heart Imaging Market
Medical Imaging
Neurophotonics Market
Medical Imaging
Small Animal Imaging (in-Vivo) Market
Medical Imaging
MRI Ferromagnetic Detection Systems Market
Medical Imaging
Mammography Market
Medical Imaging
Global Medical Imaging Workstation Market