
 France Magnetic Resonance Imaging Market | 2026-2036
France Magnetic Resonance Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
France Magnetic Resonance Imaging Market Foresight
Academic medical centers are bifurcating from general hospitals as the dominant buyer archetype for high-field MRI installations in France. Siemens Healthineers leverages its installed base across Parisian teaching hospitals to sustain service contract renewals. GE Healthcare anchors its position through direct channel control over replacement cycles in regional hospital groups. Philips differentiates via diagnostic imaging suites that integrate MRI with interventional platforms.
Magnetic resonance imaging deploys superconducting magnets generating field strengths from 1.5 to 7 Tesla, using radiofrequency coils and gradient systems to produce tomographic images of soft tissue without ionizing radiation; its primary purpose is non-invasive diagnostic visualization for neurological, oncological, and musculoskeletal pathologies. Closed MRI systems dominate the installed base in France due to superior signal-to-noise ratios, while functional MRI technology captures the fastest growth trajectory as neurosurgical planning expands. The application dimension shows neurology commanding the largest volume share, though cardiovascular MRI represents the most concentrated margin pool given specialized coil requirements and protocol complexity.
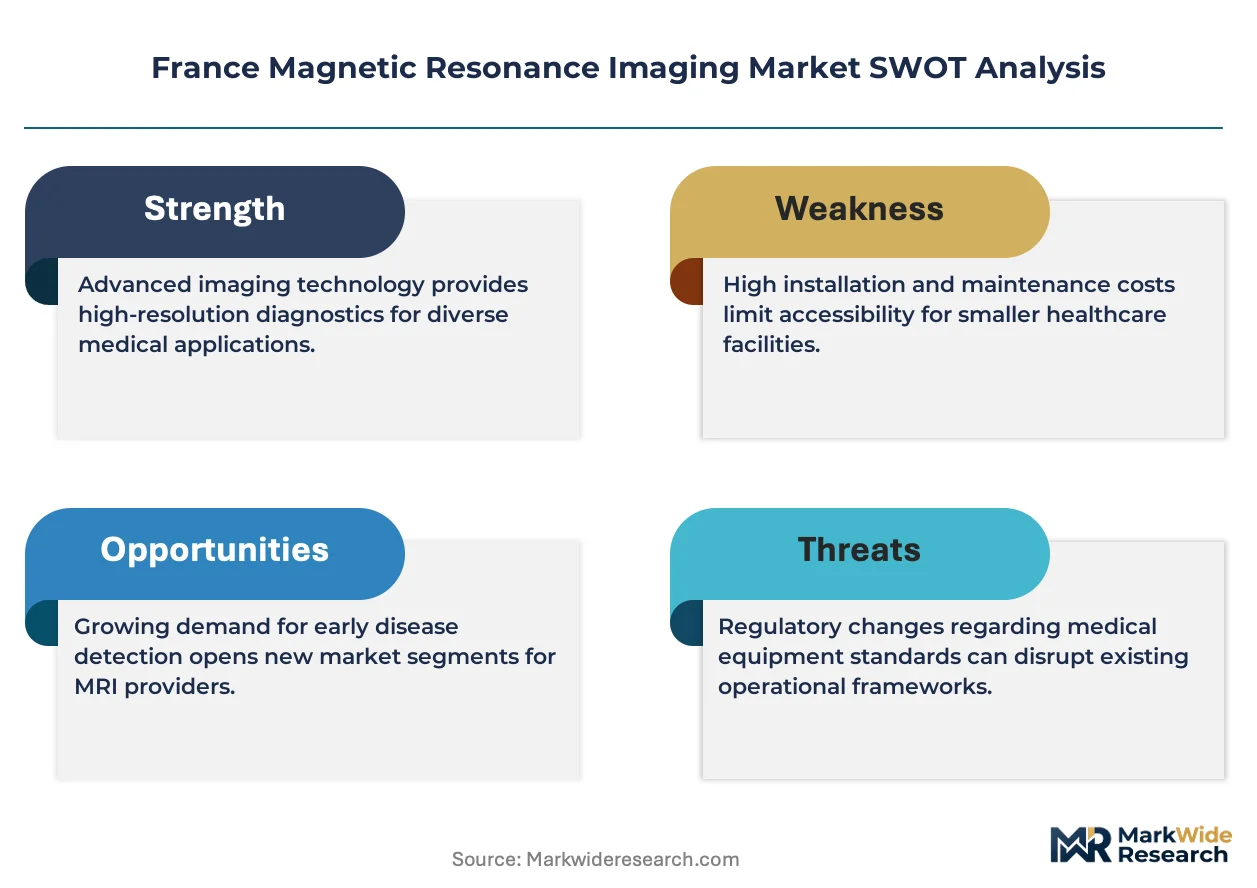
France's Haute Autorité de Santé (HAS) evaluates clinical benefit and cost-effectiveness before national reimbursement approval, directly shaping manufacturer pricing negotiations and hospital procurement timelines. The national radiology information system (PACS-RIS interoperability mandate) and European Medical Device Regulation (MDR) certification requirements filter market access for new entrants. Stakeholders must monitor how France's regional health agencies (ARS) allocate capital budgets between MRI replacement and first-time installations across underserved departments.
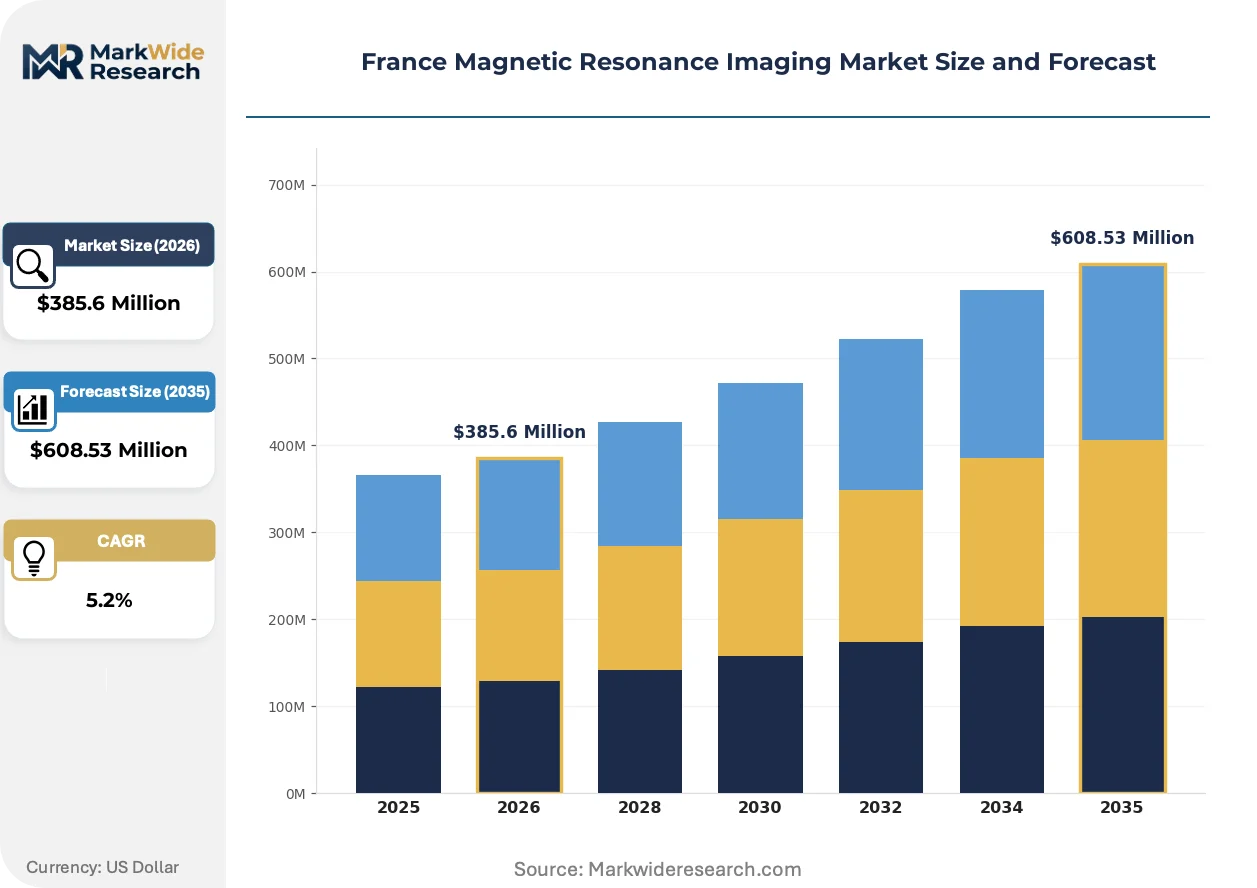
Market Dynamics
France's MRI market pivots on the tension between HAS reimbursement gatekeeping and university hospital clusters demanding 7 Tesla research-grade systems for neurosurgical planning protocols.
Growth Catalysts
- HAS Accelerated Assessment Pathway:The Haute Autorité de Santé fast-track for breakthrough devices compresses reimbursement timelines for high-field systems in oncological staging.
- Neurosurgical Planning Demand:Functional MRI protocols for preoperative brain mapping are expanding installed base requirements across Parisian teaching hospital networks.
- Île-de-France Capital Concentration:Regional health agencies in the Paris basin channel replacement budgets toward 3 Tesla upgrades ahead of national equipment aging targets.
Market Restraints
- Helium Supply Bottleneck:Superconducting magnet cooling depends on constrained global helium refining capacity, exposing French hospitals to price volatility and delivery delays.
- European MDR Certification Drag:Extended conformity assessment timelines for software-enabled diagnostic features delay new system launches by 18-24 months.
- CT Substitution in Emergency Settings:Computed tomography retains preference for trauma and acute stroke protocols where MRI scan duration creates clinical workflow friction.
Strategic Opportunities
- Auvergne-Rhône-Alpes Underserved Departments:Regional hospital groups in Clermont-Ferrand and Grenoble present first-installation opportunities as ARS budgets shift from replacement to expansion.
- AI-Assisted Reconstruction Convergence:Deep learning image enhancement enables diagnostic-quality scans at reduced acquisition times, differentiating vendor offerings in throughput-constrained sites.
- ARS Performance-Based Procurement:Regional agencies pilot outcome-linked equipment financing models that align manufacturer incentives with utilization targets.
Industry Challenges
- Radiographer Specialization Gap:Advanced cardiac and functional neuroimaging protocols require certified technologists that training programs in Lyon and Toulouse cannot supply at replacement rates.
- PACS-RIS Interoperability Burden:The national mandate for seamless radiology information system integration forces hospitals to synchronize MRI vendor selection with legacy infrastructure upgrade cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Magnetic Resonance Imaging Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $608.53 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Wide Bore MRI, Upright MRI Application: Neurology, Musculoskeletal, Cardiovascular, Oncology, Gastroenterology End User: Hospitals, Diagnostic Centers, Ambulatory Surgical Centers, Research Institutes Technology: High-Field MRI, Low-Field MRI, Functional MRI, Diffusion MRI |
| Companies Covered | Canon Medical Systems Corporation, Hitachi Medical Corporation, Siemens Healthineers, Agfa-Gevaert Group, Fujifilm Holdings Corporation, GE Healthcare, Esaote SpA, Bracco Imaging, Koninklijke Philips N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Magnetic Resonance Imaging Market Shifts & Advancements
Artificial intelligence reconstruction algorithms and compressed sensing protocols are compressing scan durations while preserving diagnostic fidelity, reshaping throughput economics for French hospital operators.
Compressed sensing acquisition is displacing conventional Cartesian k-space sampling in neurovascular protocols. Academic medical centers in Paris and Marseille deploy these sequences to double daily examination volumes without magnet replacement. The technology is displacing capital-intensive capacity expansion as the primary response to referral backlogs.
The European Medical Device Regulation (MDR) recertification requirements for software-as-medical-device features are forcing manufacturers to revalidate AI-enabled reconstruction tools under notified body supervision. This regulatory friction most impacts systems with iterative denoising algorithms, compelling vendors to segregate European and non-European software builds.
Hospital purchasing consortia in France are consolidating vendor negotiations through regional group purchasing organizations that unbundle service contracts from equipment procurement. The Grand Est and Hauts-de-France ARS regions now mandate separate bidding for maintenance and replacement cycles, compressing manufacturer margin pools in multi-year agreements.
France Magnetic Resonance Imaging Market Segmentation
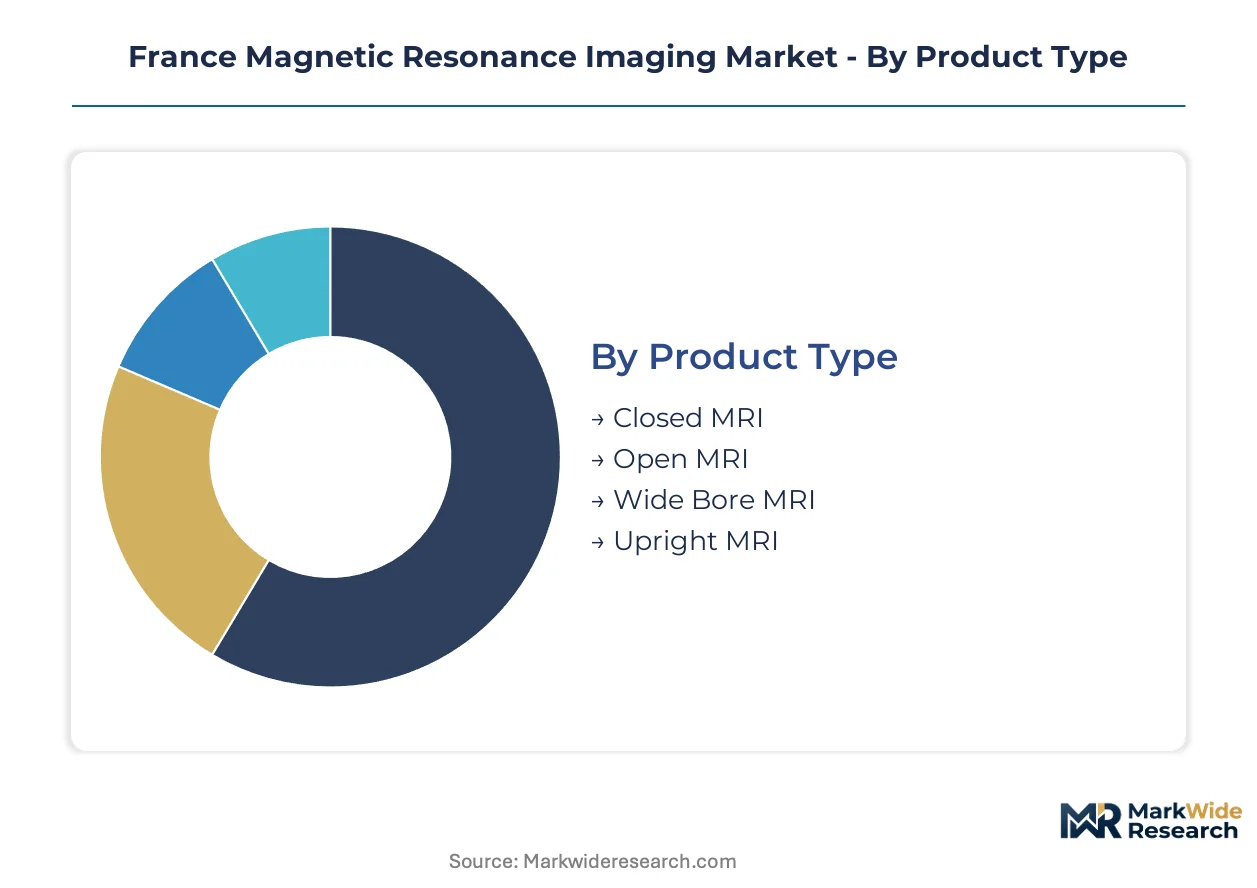
Segmentation in the France MRI market reveals how procurement priorities diverge between high-margin research applications and volume-driven diagnostic services. Understanding these splits enables vendors to align field strength configurations with specific buyer archetypes across hospital networks and independent imaging centers.
Product Type:
Margin pools concentrate in closed-bore systems where superconducting magnet technology commands premium pricing and long-term service contracts.
- Closed MRI:Superconducting magnets operating at 1.5 to 3 Tesla generate superior signal-to-noise ratios for neurovascular and oncological protocols. Demand clusters in Parisian university hospital clusters where HAS reimbursement approval for high-field neurological staging drives replacement cycles toward 3 Tesla upgrades.
- Wide Bore MRI:Expanded 70-centimeter bore diameters accommodate claustrophobic patients and bariatric cases without sacrificing field strength. Regional hospital groups in Lyon and Marseille prioritize these systems for mixed outpatient populations where patient throughput directly impacts ARS funding allocations.
- Open MRI:Permanent magnet designs eliminate helium dependency but trade field strength for accessibility. Pediatric departments and orthopedic clinics in Clermont-Ferrand specify these for extremity imaging where positioning flexibility outweighs resolution requirements.
- Upright MRI:Vertical field configurations permit weight-bearing spinal and joint studies under physiological load. Specialized musculoskeletal institutes in Grenoble deploy these for preoperative surgical planning in complex degenerative cases.
The dominant share belongs to Closed MRI, while Wide Bore MRI is closing the gap fastest as regional agencies balance diagnostic performance with patient access metrics.
Application:
Volume distribution tracks referral patterns from general practitioners and specialists, with procedural reimbursement rates determining equipment utilization intensity.
- Neurology:Brain and spinal cord imaging for stroke, tumor, and demyelinating disease protocols consumes the largest examination slot allocation. Functional MRI sequences for preoperative brain mapping command premium scheduling priority at Pitié-Salpêtrière and Hôpital Européen Georges-Pompidou.
- Cardiovascular:Cardiac MRI with specialized phased-array coils enables non-invasive assessment of myocardial viability and congenital defects. HAS accelerated assessment pathways for stress perfusion protocols concentrate demand in tertiary centers with certified cardiac imaging technologists.
- Oncology:Whole-body staging and treatment response monitoring drives repeat examination volumes. Radiation therapy planning integration at Gustave Roussy and Institut Curie links MRI procurement to linear accelerator replacement cycles.
- Musculoskeletal:Sports medicine and arthroplasty assessment protocols serve high-volume outpatient streams. Private imaging centers in Bordeaux and Nantes differentiate through rapid-access knee and shoulder protocols.
- Gastroenterology:MR enterography and hepatobiliary imaging for inflammatory bowel disease and liver lesion characterization. Academic centers deploy these for non-invasive alternatives to endoscopic procedures in Crohn's disease monitoring.
Neurology commands the largest installed base allocation, yet Cardiovascular MRI is expanding most quickly as specialized coil technology and technologist certification programs mature.
End User:
Capital access and procurement autonomy separate institutional buyers, with public budget cycles and private investment timelines creating distinct sales motion requirements.
- Hospitals:Public hospital networks under ARS oversight manage replacement cycles through multi-year capital equipment plans. CHU de Toulouse and AP-HP central purchasing consortia negotiate framework agreements that lock in service pricing across regional scanner fleets.
- Diagnostic Centers:Independent imaging facilities compete on appointment availability and report turnaround times. Operators in the Grand Est region consolidate through group purchasing organizations to match hospital-scale procurement leverage.
- Ambulatory Surgical Centers:Limited MRI deployment for preoperative screening and postoperative complication assessment. Orthopedic day surgery units in the Hauts-de-France region specify compact 1.5 Tesla systems for same-joint imaging workflows.
- Research Institutes:7 Tesla and above systems for neuroimaging research occupy dedicated facilities with separate funding streams. CEA NeuroSpin at Saclay and ICM in Paris operate outside clinical reimbursement frameworks through national research agency grants.
Hospitals retain the dominant procurement volume, though Diagnostic Centers are gaining share fastest as liberalized medical imaging regulations permit independent facility expansion.
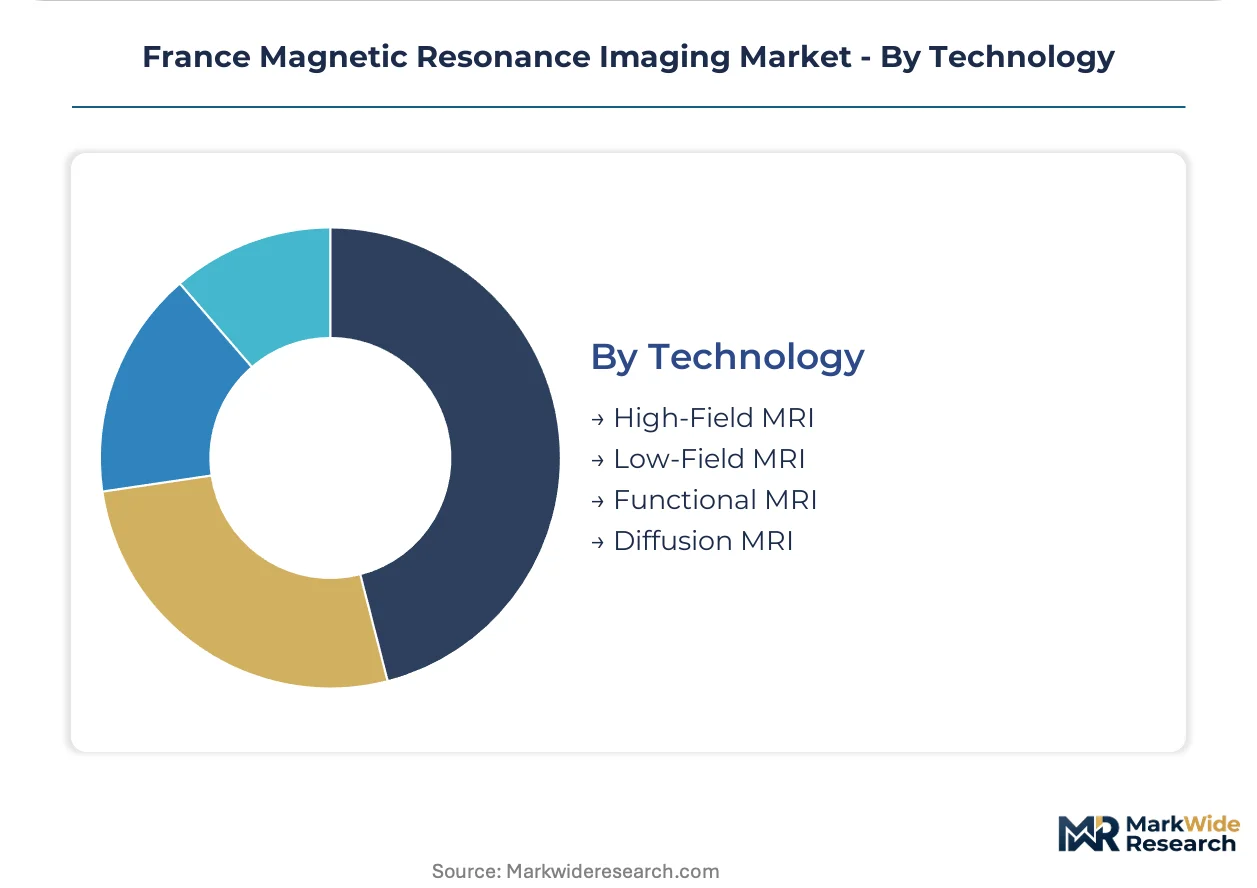
Technology:
Field strength classification determines magnet complexity, siting requirements, and operational cost structures that filter addressable market segments.
- High-Field MRI:Systems at 3 Tesla and above deliver the spatial resolution and spectroscopic capability required for functional neuroimaging and small-lesion oncology protocols. HAS reimbursement codes for high-field-specific sequences concentrate these in Île-de-France teaching hospitals.
- Functional MRI:Blood-oxygen-level-dependent imaging for brain activation mapping and neurosurgical planning. Preoperative language and motor cortex localization at Hôpital de la Pitié-Salpêtrière drives 7 Tesla research system procurement.
- Diffusion MRI:Tensor imaging for white matter tractography in stroke and tumor infiltration assessment. Integration with neuronavigation systems at neurosurgical centers in Marseille and Lyon creates specialized demand.
- Low-Field MRI:Permanent magnet and resistive designs below 0.5 Tesla for extremity and open-configured imaging. Rural hospital groups in Auvergne-Rhône-Alpes specify these for cost-constrained first installations where siting infrastructure limits superconducting system deployment.
High-Field MRI holds the dominant technology position, while Functional MRI is climbing the fastest as neurosurgical planning protocols expand beyond Parisian academic centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export high-field MRI systems through distribution partnerships into French hospital networks. The trade corridor channels magnet technology from Stuttgart and Erlangen toward Parisian teaching hospitals and regional procurement consortia.
Île-de-France
AP-HP central purchasing consolidates scanner procurement across thirteen Parisian university hospitals. HAS reimbursement codes for functional neuroimaging sequences concentrate 3 Tesla upgrades at Pitié-Salpêtrière and Hôpital Européen Georges-Pompidou. The Saclay research plateau hosts CEA NeuroSpin's 7 Tesla facility outside clinical reimbursement frameworks.
Auvergne-Rhône-Alpes
CHU de Clermont-Ferrand and Grenoble Alpes University Hospital manage replacement cycles for aging 1.5 Tesla systems. The regional health agency channels capital budgets toward first-time installations in underserved Cantal and Haute-Loire departments. Lyon-based training programs supply certified cardiac MRI technologists to tertiary centers across the region.
Provence-Alpes-Côte d'Azur
Aix-Marseille University Hospital deploys diffusion tensor imaging for neurosurgical planning at Timone Hospital. The ARS Provence-Alpes-Côte d'Azur mandates PACS-RIS interoperability compliance in framework agreements with diagnostic imaging networks. Private imaging centers in Nice compete on rapid-access musculoskeletal protocols.
Hauts-de-France
CHU de Lille negotiates service contract unbundling through the regional group purchasing organization. The ARS prioritizes wide-bore MRI for bariatric and claustrophobic patient populations across Valenciennes and Amiens hospital groups. Orthopedic day surgery units specify compact 1.5 Tesla systems for same-joint imaging workflows.
Nouvelle-Aquitaine
CHU de Bordeaux tests AI-assisted reconstruction algorithms under the national radiology information system interoperability mandate. The regional agency allocates replacement budgets toward 3 Tesla upgrades ahead of equipment aging targets in Pau and Bayonne. Private diagnostic operators in Nantes consolidate procurement leverage through multi-site group purchasing arrangements.
France Magnetic Resonance Imaging Market Competitive Landscape
Listed leaders compete with private specialists across service contract bundling and research system deployment. The vendor base organizes around three archetypes: diversified imaging conglomerates with full modality portfolios, pure-play MRI specialists with targeted field strength configurations, and regional service organizations capturing maintenance revenue. Consolidation pressures concentrate among mid-scale European players lacking 7 Tesla research capabilities. Competitive moves center on unbundling service contracts from equipment sales and securing exclusive replacement cycle access through multi-year framework agreements.
Among diversified imaging conglomerates, Siemens Healthineers, GE Healthcare, and Koninklijke Philips N.V. occupy positions defined by installed base scale and service network density. Siemens Healthineers exemplifies the research-system archetype through its penetration of Parisian teaching hospital networks. GE Healthcare anchors the replacement-cycle control model via direct channel relationships with regional hospital groups. Philips represents the diagnostic imaging suite strategy, positioning MRI within integrated interventional platforms. These three conglomerates sit within a tier where HAS reimbursement timelines and ARS procurement frameworks determine competitive positioning rather than product differentiation alone.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Hitachi Medical Corporation |
| Siemens Healthineers |
| Agfa-Gevaert Group |
| Fujifilm Holdings Corporation |
| GE Healthcare |
| Esaote SpA |
| Bracco Imaging |
| Koninklijke Philips N.V. |
| Others |
Supply & Pricing Matrix
Compressed sensing acquisition protocols displacing conventional Cartesian k-space sampling simultaneously redraw procurement geography toward academic medical centers and compress per-scan pricing economics for regional hospital groups.
Pricing Analysis
Three-tier pricing structure across premium 3 Tesla systems, standard 1.5 Tesla configurations, and economy-grade low-field magnets dominates vendor quotations. Price differentiation hinges on HAS reimbursement tier alignment and field strength-specific coil bundles. Cost compression in the standard tier is intensifying because ARS procurement frameworks unbundle service contracts from equipment sales. Regional hospital groups in Auvergne-Rhône-Alpes exhibit highest price sensitivity, while Parisian teaching hospitals prioritize performance specifications over capital outlay.
Supply Chain Analysis
Germany and the Netherlands anchor superconducting magnet fabrication and gradient coil assembly for French hospital networks. Liquid helium sourcing draws from Qatar and the United States, with refining capacity concentrated in Algerian export terminals. Single-source vulnerability in helium logistics exposes French operators to delivery volatility and price spikes. Distribution runs through manufacturer-direct channels for high-field systems and regional service organizations for maintenance renewals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's MRI market approaches a platform-economics inflection as PACS-RIS interoperability mandates force vendor consolidation around integrated diagnostic suites rather than standalone magnet sales.
For Market Incumbents: Fortify replacement cycle control through multi-year framework agreements with AP-HP and CHU de Toulouse central purchasing consortia. Deepen backward integration into helium recycling infrastructure to offset supply volatility. Prioritize MDR certification investment for AI-enabled reconstruction features ahead of software-as-medical-device revalidation deadlines.
For New Entrants and Emerging Players: Anchor in diagnostic imaging networks across Grand Est and Hauts-de-France where GPO procurement unbundling creates service contract white space. Target ambulatory surgical centers in orthopedic day surgery units with compact 1.5 Tesla configurations. Pursue outcome-based financing pilots with ARS performance-linked procurement models.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-scale European MRI specialists lacking 7 Tesla research capabilities and MDR transition resources. Long-term viability favors vendors with installed base density in Île-de-France teaching hospitals and software differentiation under HAS accelerated assessment pathways. Monitor helium supply contract renegotiations as inflection indicator for operational cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Software Recertification | AI reconstruction algorithms require notified body validation under European Medical Device Regulation timelines. |
| Helium Recycling Infrastructure | Closed-loop cryogen systems reduce dependency on constrained global helium refining capacity. |
| PACS-RIS Interoperability Integration | Seamless radiology information system compliance filters vendor access to ARS framework agreements. |
| ARS Performance-Based Procurement | Outcome-linked equipment financing aligns manufacturer incentives with hospital utilization targets. |
| 7 Tesla Research System Deployment | Neurosurgical planning protocols at CEA NeuroSpin and ICM drive non-reimbursable grant-funded installations. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and HAS reimbursement specialists and refined through secondary validation. Primary fieldwork combined structured interviews with radiology department heads and procurement officers across CHU de Toulouse, AP-HP networks, and regional ARS agencies. Secondary sources encompassed HAS reimbursement code databases, European Medical Device Regulation notified body filings, and ARS capital equipment budget disclosures. Bottom-up scanner installation tracking and top-down healthcare expenditure modeling provided cross-verification.
Variance decomposition across field strength tiers, end-user categories, and regional procurement clusters shaped the analytical framework over the projection horizon. Segmentation dimensions modeled included product configuration, application protocol, technology generation, and ARS regional funding allocation patterns. CAGRs were derived from replacement cycle velocity and first-installation penetration rates in underserved departments. Forecast inputs incorporated HAS accelerated assessment pathway approval timelines and helium supply contract duration distributions.
Material uncertainties — MDR certification delays, helium logistics disruptions, and CT substitution in emergency protocols — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding ARS budget continuity and reimbursement code stability. Recalibration cycles align with material shifts in HAS technology assessment outcomes and regional health agency capital allocation priorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
PET Radiotracer Market
Medical Imaging
Global Veterinary Diagnostic Imaging Market
Medical Imaging
Ultrasound Image Processing Software Market
Medical Imaging
United Kingdom Computed Tomography Market
Medical Imaging
Magnetic Resonance Imaging Equipment Coils Market
Medical Imaging
Digital X Ray Market
Medical Imaging
Radiology As a Service Market
Medical Imaging
Mobile Computed Tomography Scanners Market
Medical Imaging
Refurbished Medical Imaging Devices Market
Medical Imaging
India Diagnostic Imaging Equipment Market
Medical Imaging
Radiation Dose Management Market
Medical Imaging
Africa Nuclear Imaging Market
Medical Imaging
Mobile Vascular Imaging Market
Medical Imaging
Positron Emission Tomography Devices (PET) Market
Medical Imaging
Dental Imaging Market
Medical Imaging
China Computed Tomography Market