
 Chile Diagnostic Imaging Equipment Market | 2026-2036
Chile Diagnostic Imaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Diagnostic Imaging Equipment Market Outlook
Decreto Supremo 825 is repositioning the cost-of-entry calculus for equipment suppliers entering Chile. Siemens Healthineers leverages its installed base of MRI and CT platforms to sustain service revenue streams across public hospital networks. GE Healthcare anchors its position through localized technical support and training infrastructure. Canon Medical Systems competes on digital radiography conversion programs targeting mid-sized diagnostic centers.
Diagnostic imaging equipment encompasses systems that generate visual representations of internal body structures for clinical diagnosis, utilizing electromagnetic radiation, magnetic fields, or acoustic energy with spatial resolution thresholds measured in millimeters. These systems serve primarily to detect disease, guide interventions, and monitor treatment progression across cardiology, oncology, and neurology applications. MRI and CT scanner segments command premium price positions due to higher technical complexity and specialized installation requirements. Digital radiography technology leads volume shipments as facilities retire analog film-based systems. Ultrasound occupies the most accessible tier, with portable systems expanding into outpatient clinics and emergency settings.
Chile's Ministry of Health enforces medical device registration through the Instituto de Salud Pública, while electrical safety and performance standards fall under the Superintendencia de Electricidad y Combustibles. These frameworks shape procurement timelines, mandating local calibration protocols and preventive maintenance documentation that filter out non-compliant vendors. Stakeholders must monitor upcoming revisions to technical standards and public hospital budget allocations to anticipate replacement cycles and tender opportunities.
Market Dynamics
Chile's diagnostic imaging equipment sector pivots on the Ministry of Health's Decreto Supremo 825, which mandates digital radiography conversion across public hospital networks and compresses procurement timelines for analog system replacements.
Growth Catalysts
- Metropolitan Hospital Expansion:Tertiary care facilities in Santiago and Valparaíso are accelerating capital expenditure on MRI and CT platforms to address patient backlogs.
- Decreto Supremo 825:The technical standards update creates mandatory replacement cycles for aging analog radiography equipment across Chile's public health infrastructure.
- Portable Ultrasound Diffusion:Battery-powered systems are penetrating outpatient clinics and emergency departments previously dependent on fixed installations.
Market Restraints
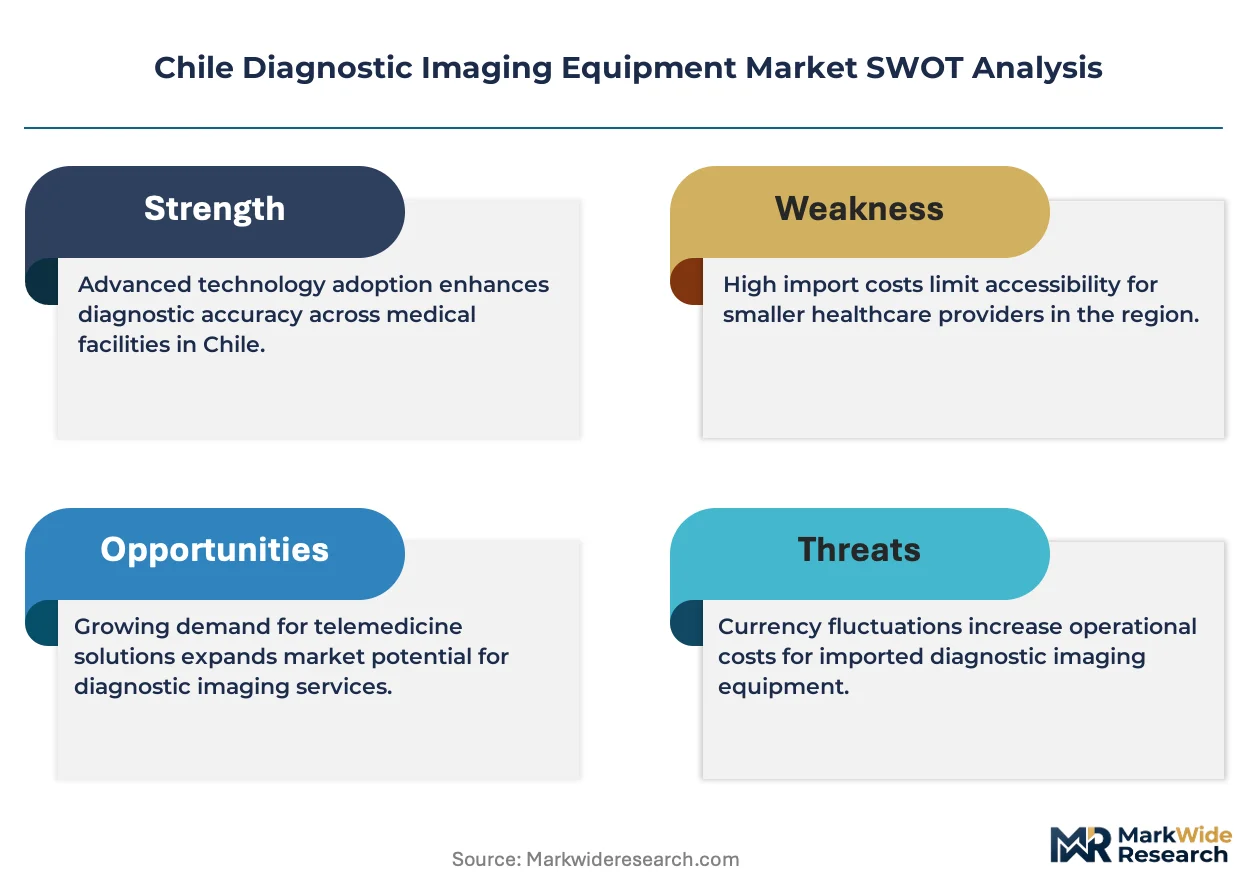
- Import Tariff Structure:Chile's customs framework imposes cost premiums on high-value imaging components sourced from non-mercosur suppliers.
- Technical Labor Scarcity:Biomedical engineering programs in Chile produce insufficient qualified personnel for preventive maintenance and calibration protocols.
- Currency Volatility:Peso-dollar exchange rate fluctuations inflate landed costs for European and Asian equipment manufacturers.
Strategic Opportunities
- Regional Hospital Digitization:Secondary care centers in Antofagasta and Concepción lag Santiago in digital radiography penetration.
- Artificial Intelligence Integration:Machine learning algorithms for image reconstruction are creating upgrade pathways for installed CT and MRI bases.
- Service Contract Unbundling:Independent technical service providers can capture preventive maintenance volumes from manufacturer-captive programs.
Industry Challenges
- ISP Registration Timelines:Instituto de Salud Pública medical device approval processes extend market entry lead times for novel imaging technologies.
- Legacy System Interoperability:PACS integration with analog-to-digital conversion platforms requires custom engineering for heterogeneous hospital IT environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Diagnostic Imaging Equipment Market |
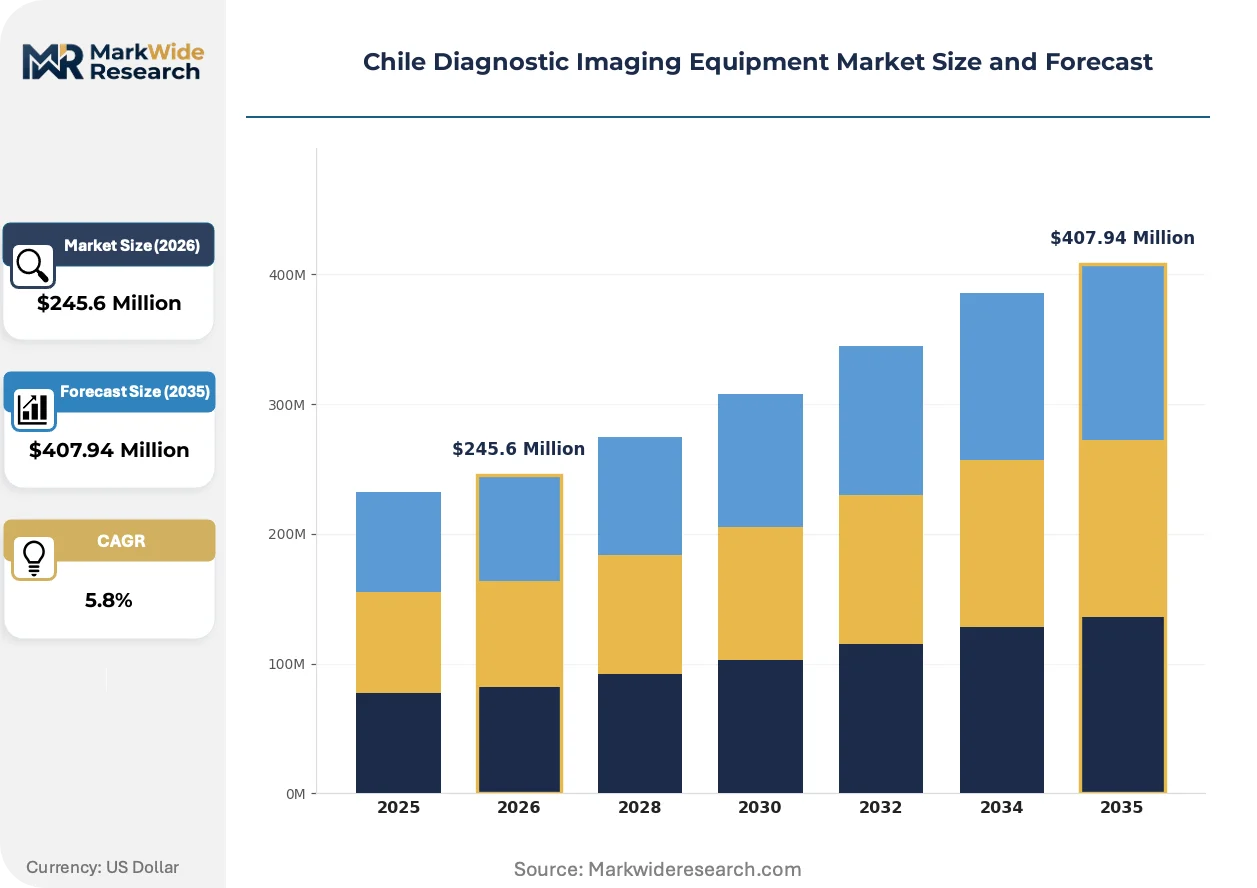
| Market Size in 2026 | $245.6 Million |
| Market Size in 2035 | $407.94 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray, MRI, CT Scanner, Ultrasound Technology: Digital Radiography, Analog Radiography, Computed Tomography, Magnetic Resonance End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Clinics Delivery Mode: Portable Systems, Stationary Systems, Teleradiology, Cloud-based Systems |
| Companies Covered | Canon Medical Systems, Carestream Health, Siemens Healthineers, Samsung Medison, Esaote SpA, GE Healthcare, Fujifilm Holdings, Hologic, Koninklijke Philips, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Diagnostic Imaging Equipment Market Strategic Shifts
Digital radiography platforms are displacing analog film systems at the core of Chile's imaging infrastructure, while regulatory pressure and procurement model evolution reshape how equipment reaches end-users.
Computed tomography systems equipped with photon-counting detectors are expanding into Chile's oncology and cardiology departments. Private hospital groups in Santiago are piloting these platforms for spectral imaging applications. The technology is expanding into premium service tiers previously dominated by conventional CT scanners.
Chile's Superintendencia de Electricidad y Combustibles has tightened electrical safety certification requirements for imported imaging equipment. Manufacturers must now submit preventive maintenance documentation as a condition of market authorization. CT and MRI segments face the steepest compliance adjustments due to high-voltage subsystem complexity.
Public hospital consortia are consolidating equipment procurement through centralized tender mechanisms administered by Chile Compra. Regional health services in Valparaíso and Biobío are aggregating demand to extract volume pricing from multinational suppliers. This concentration is visible most acutely in MRI acquisitions, where single tenders now cover multiple facility deployments.
Chile Diagnostic Imaging Equipment Market Segmentation
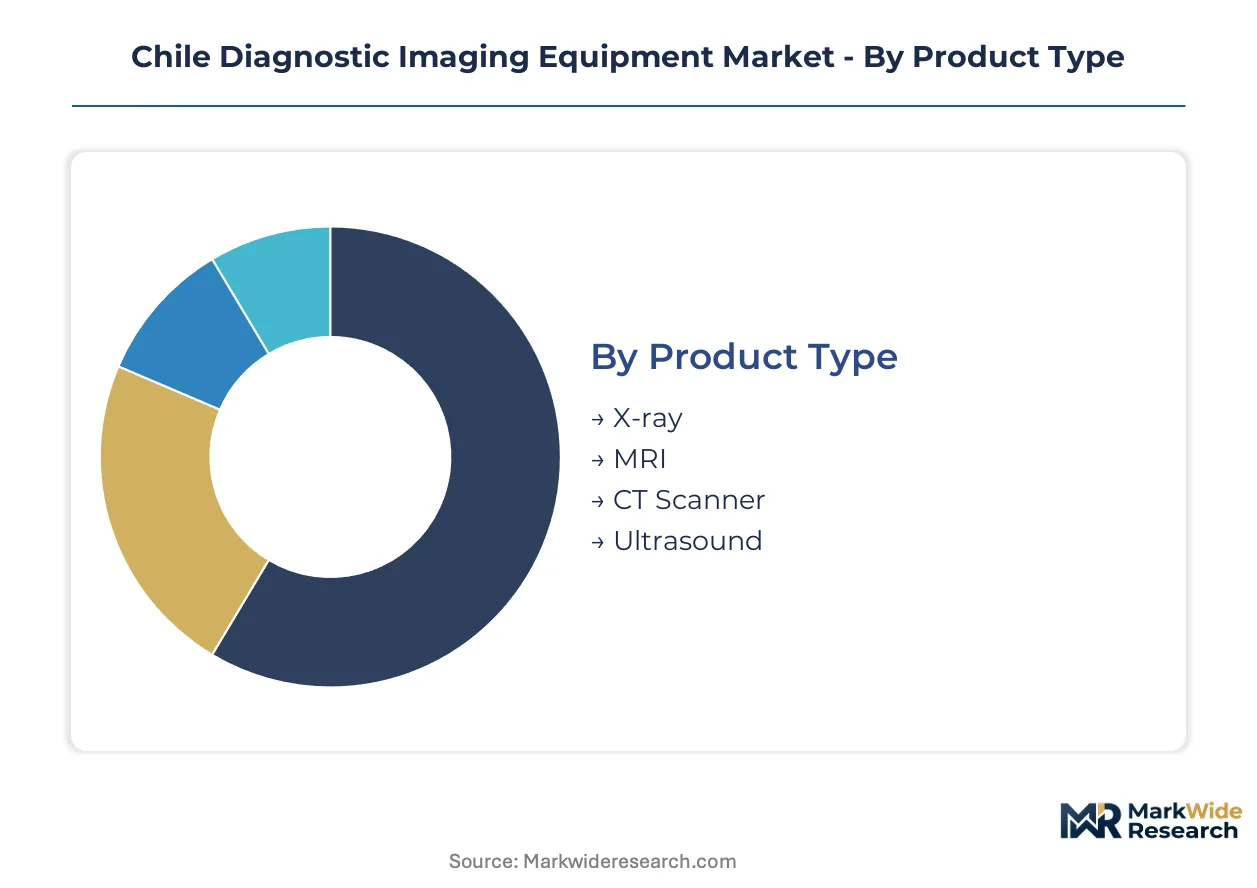
Segmentation in Chile's diagnostic imaging equipment market reveals how procurement priorities diverge across facility tiers and technology generations. Understanding these splits exposes where Decreto Supremo 825's replacement mandates intersect with capital availability and clinical specialization.
Product Type:
Capital intensity and installation complexity separate buyers in this category, with tertiary hospitals targeting multi-million dollar platforms while smaller facilities prioritize accessible modalities.
- X-ray:Digital radiography systems dominate replacement cycles under Decreto Supremo 825, with fixed installations in Santiago's public hospital networks retiring analog film processors. Procurement concentrates in metropolitan tertiary centers where patient throughput justifies premium detector technology.
- MRI:Superconducting systems with 1.5T and 3T field strengths command the highest capital allocations, serving neurology and oncology departments in Valparaíso's expanding public networks. Chile's customs tariff structure on non-MERCOSUR components inflates landed costs for these magnet-intensive platforms.
- CT Scanner:Multi-slice systems address emergency and trauma volumes across Chile's regional health services.
- Ultrasound:Portable battery-powered units penetrate outpatient clinics previously dependent on fixed installations.
X-ray leads volumes today; ultrasound is gaining share fastest.
Technology:
Regulatory deadlines and reimbursement alignment determine which technology generations facilities can justify, creating a bifurcation between compliance-driven replacements and capability-driven upgrades.
- Digital Radiography:Flat-panel detectors and computed radiography plates form the technical core of Chile's analog-to-digital conversion, with the Instituto de Salud Pública mandating electrical safety documentation for all new installations. Santiago's hospital consortia aggregate tender demand to extract volume pricing on these systems.
- Analog Radiography:Film-based systems persist in underfunded secondary centers outside metropolitan zones, though Decreto Supremo 825's technical standards update accelerates their phase-out. Replacement timelines compress where Chile Compra-administered tenders pool regional demand.
- Computed Tomography:Photon-counting detector variants pilot in Santiago's private oncology departments.
- Magnetic Resonance:Spectral imaging capabilities differentiate premium service tiers in cardiology applications.
Digital radiography leads volumes today; computed tomography is gaining share fastest.
End User:
Patient acuity and reimbursement structure shape procurement authority, with centralized public networks operating under different capital allocation logic than fragmented private operators.
- Hospitals:Tertiary facilities in Santiago and Valparaíso anchor MRI and CT procurement through Chile Compra consortia, aggregating multi-facility tenders to negotiate service contract terms. The Superintendencia de Electricidad y Combustibles mandates preventive maintenance documentation as a condition of market authorization for high-voltage installations.
- Diagnostic Centers:Mid-sized facilities in Concepción and Antofagasta lag metropolitan zones in digital radiography penetration, creating replacement backlogs where regional health service budgets permit.
- Research Institutions:Academic medical centers in Santiago pilot AI-integrated reconstruction algorithms for image analysis.
- Outpatient Clinics:Primary care expansion drives portable ultrasound diffusion into emergency settings.
Hospitals lead volumes today; outpatient clinics are gaining share fastest.
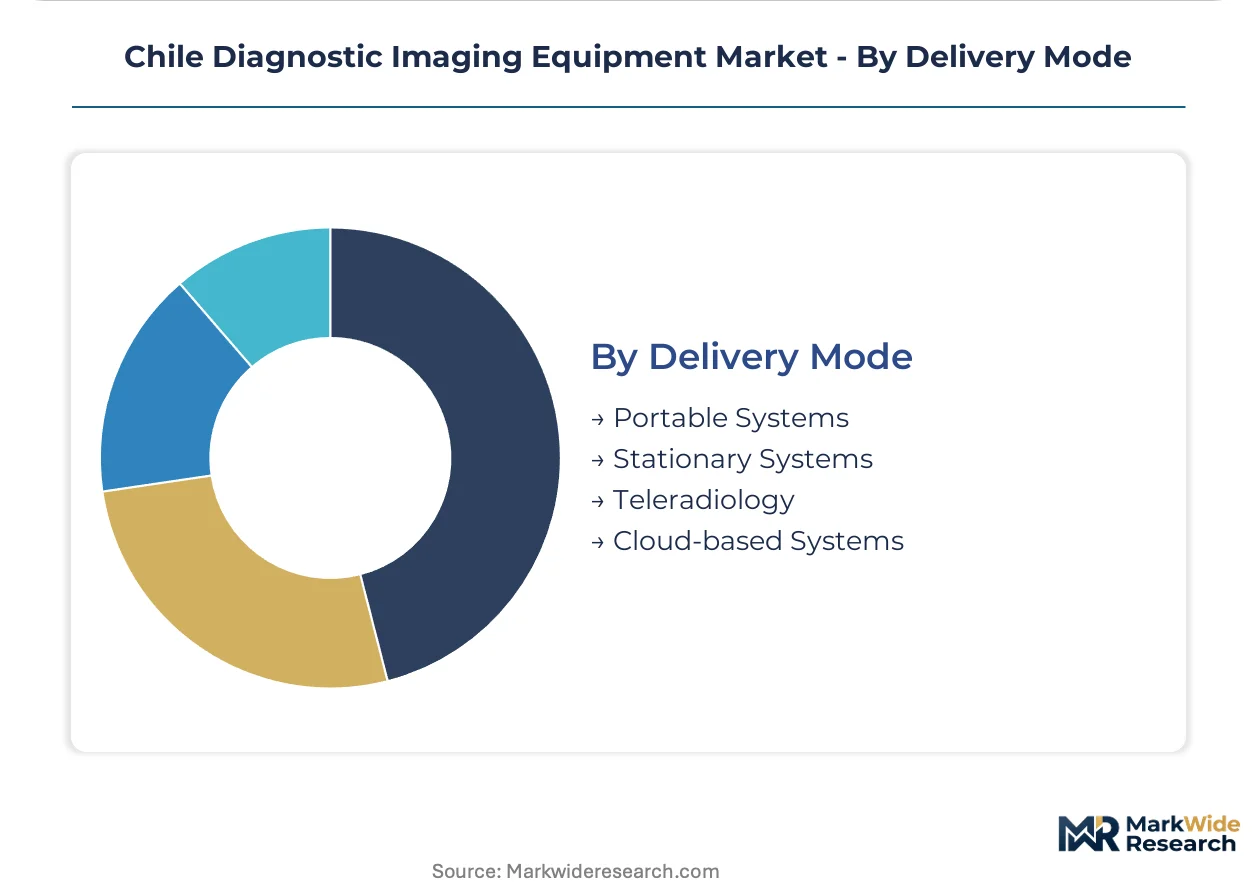
Delivery Mode:
Physical system mobility and data architecture flexibility represent distinct procurement dimensions, with facilities evaluating capital deployment against operational adaptability.
- Portable Systems:Battery-powered ultrasound and digital radiography units penetrate Chile's outpatient clinics and emergency departments, addressing patient backlogs without fixed infrastructure investment. Biomedical engineering scarcity constrains preventive maintenance coverage for distributed device fleets.
- Stationary Systems:Fixed MRI and CT platforms dominate tertiary care capital budgets in Santiago, where installation complexity and shielding requirements anchor equipment to purpose-built suites. Currency volatility inflates landed costs for European and Asian manufacturers supplying these high-value installations.
- Teleradiology:Image transmission infrastructure connects regional centers to metropolitan specialist interpretation.
- Cloud-based Systems:PACS integration faces interoperability challenges with heterogeneous hospital IT environments.
Stationary systems lead volumes today; portable systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent concentrates in Santiago's metropolitan universities, anchoring Chile's diagnostic imaging infrastructure while regional health services struggle with technical labor scarcity.
Metropolitan Santiago
Chile's capital hosts the densest cluster of tertiary care facilities driving MRI and CT procurement through Chile Compra consortia. Decreto Supremo 825 accelerates digital radiography replacement across Hospital Metropolitano and Clínica Alemana networks. The Superintendencia de Electricidad y Combustibles enforces preventive maintenance documentation for high-voltage installations concentrated in Las Condes and Providencia districts.
Valparaíso Region
Public hospital networks in Viña del Mar and Valparaíso port city are expanding CT and MRI capacity to address patient backlogs from metropolitan referral flows. The Instituto de Salud Pública processes medical device registrations for imported imaging platforms landing through the Pacific port. Regional health service budgets aggregate tender demand for multi-facility equipment deployments.
Biobío Region
Concepción's secondary care centers lag Santiago in digital radiography penetration, creating replacement backlogs where regional health service allocations permit. The Universidad de Concepción trains biomedical technicians supporting preventive maintenance protocols. Local diagnostic centers pilot portable ultrasound diffusion into emergency departments.
Antofagasta Region
Mining industry health services in this northern desert region drive demand for ruggedized portable imaging systems serving remote extraction sites. Customs tariff structures on non-MERCOSUR components inflate landed costs for European and Asian equipment. The regional health service pools procurement with Atacama neighbors to extract volume pricing.
Chile Diagnostic Imaging Equipment Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Chile's diagnostic imaging equipment sector, creating a tiered structure where full-line suppliers anchor premium hospital contracts while niche players capture specific modality segments. Siemens Healthineers leverages its installed base to sustain service revenue streams across public networks. Strategic moves concentrate on localized technical support infrastructure and unbundled service contract capture.
Among multinational health technology conglomerates, Siemens Healthineers, GE Healthcare, and Canon Medical Systems occupy positions reflecting distinct competitive archetypes. Siemens Healthineers exemplifies the full-line integrated supplier model with deep installed base penetration. GE Healthcare anchors the localized service infrastructure approach. Canon Medical Systems represents the targeted digital conversion specialist competing on mid-tier diagnostic center accessibility.
| Leading Market Players |
|---|
| Canon Medical Systems |
| Carestream Health |
| Siemens Healthineers |
| Samsung Medison |
| Esaote SpA |
| GE Healthcare |
| Fujifilm Holdings |
| Hologic |
| Koninklijke Philips |
| Others |
Value Chain & Pricing Dynamics
Superconducting magnet components sourced from Germany and Japan flow through Santiago-based distributors before reaching Chile's tertiary hospital networks, with landed costs inflating at each tariff and currency conversion node along the chain.
Pricing Analysis
Bundled full-service contracts dominate MRI and CT procurement through Chile Compra consortia, while unbundled equipment-only sales penetrate mid-tier diagnostic centers seeking third-party maintenance alternatives. Price differentiation hinges on field strength specifications for MRI platforms and detector array density for CT systems, with premium tiers commanding multiples over standard configurations. Pricing pressure stems from peso-dollar volatility compressing margins for European and Asian manufacturers. Public hospital networks exhibit acute price sensitivity due to fixed regional health service budgets, whereas private oncology groups in Las Condes prioritize capability over cost.
Supply Chain Analysis
Warehouse-distribution layers in Santiago's Quilicura industrial zone serve as consolidation points for imaging equipment arriving through Valparaíso port, with regional spokes extending to Concepción and Antofagasta. Manufacturing concentration centers on Germany, Japan, and the United States for high-field MRI magnets and photon-counting CT detectors. Supply chains draw from rare earth element processors in China for magnet fabrication and semiconductor foundries in Taiwan for detector electronics. Single-source vulnerability concentrates in liquid helium supply for superconducting systems. Distribution runs through manufacturer-authorized distributors holding ISP registration and SEC electrical certification documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Chile's diagnostic imaging equipment sector rests on service contract unbundling and AI-integrated upgrade pathways that capture premium pricing from installed base modernization.
For Market Incumbents: Anchor market position by deepening localized biomedical engineering training infrastructure to offset technical labor scarcity threatening service revenue retention. Capture preventive maintenance volumes from fragmented third-party providers through tiered service offerings. Defend against emerging portable ultrasound specialists by integrating battery-powered platforms into full-line portfolios. Prioritize certification investment with the Superintendencia de Electricidad y Combustibles to accelerate approval timelines for photon-counting CT variants. For New Entrants and Emerging Players: The premium-to-economy price gap in digital radiography systems creates entry space for mid-tier detector manufacturers willing to bundle installation with simplified PACS integration. Target secondary care centers in Concepción and Antofagasta where regional health service budgets lag Santiago's procurement velocity. Penetrate through Chile Compra subcontractor relationships rather than direct tender participation. Emphasize rapid ISP registration completion as competitive differentiator against established players with backlogged approval pipelines. For Investors and Strategic Acquirers: Consolidation pressure builds where biomedical engineering talent scarcity constrains independent service provider scalability across Chile's dispersed regional hospital networks. Long-term viability favors vertically integrated platforms combining equipment supply with captive maintenance capabilities. Acquisition target archetype: mid-sized distributors holding established SEC certification relationships and underutilized technical labor pools. Monitor Decreto Supremo 825 revision timelines as inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISP Registration Fast-Track Program | Accelerates market entry for photon-counting CT platforms ahead of competitor approval timelines. |
| Biomedical Engineering Training Partnership | Addresses technical labor scarcity constraining preventive maintenance coverage in regional networks. |
| Chile Compra Consortium Participation | Unlocks volume pricing leverage through aggregated public hospital tender demand across Valparaíso and Biobío. |
| AI Reconstruction Algorithm Integration | Creates upgrade revenue streams from installed CT and MRI bases in Santiago's oncology departments. |
| Portable Ultrasound Distribution Expansion | Captures outpatient clinic penetration driven by primary care expansion in emergency settings. |
Study Parameters
Multiple input streams — structured interviews with hospital purchasing committees, biomedical engineering directors, and GPO contracts managers, alongside secondary validation through ISP registration databases, SEC electrical certification records, and Chile Compra tender documentation — were reconciled through bottom-up equipment shipment tracking and top-down health expenditure analysis. Primary fieldwork captured procurement decision criteria across public hospital networks in Santiago, Valparaíso, and Biobío. Secondary sources included customs import records for imaging equipment components, regional health service budget allocations, and technical standards documentation from the Ministry of Health.
Historical shipment patterns were cross-referenced against panel input from equipment distributors and service providers to establish baseline penetration rates across the projection horizon. Segmentation modeling incorporated product type, technology generation, end-user facility tier, and delivery mode dimensions. CAGRs were derived from replacement cycle analysis under Decreto Supremo 825 mandates and capacity expansion plans in metropolitan hospital networks. Forecast inputs included currency volatility scenarios for peso-dollar exchange rates and tariff structure assumptions for non-MERCOSUR component sourcing.
Caveats apply where ISP registration timeline delays, Superintendencia de Electricidad y Combustibles certification revisions, or regional health service budget reallocations could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Veterinary Imaging Systems Market
Medical Imaging
Italy Digital X-Ray Market
Medical Imaging
Artificial Intelligence in Medical Imaging Market
Medical Imaging
Global Dental Panoramic Radiography Market
Medical Imaging
Japan Computed Tomography Market
Medical Imaging
Asia-Pacific CT Market
Medical Imaging
Breast Imaging Equipment Market
Medical Imaging
Hand-Held X-Rays Market
Medical Imaging
North America Medical Imaging Software Market
Medical Imaging
Global 3D Ultrasound Market
Medical Imaging
Perfusion Imaging Market
Medical Imaging
South Korea Computed Tomography Market
Medical Imaging
Mammography Workstation Market
Medical Imaging
US Digital Radiology Market
Medical Imaging
United Kingdom Digital X-Ray Devices Market
Medical Imaging
South America Mammography Market