
 Global Single-Photon Emission Computed Tomography (SPECT) Market | 2026-2036
Global Single-Photon Emission Computed Tomography (SPECT) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Single-Photon Emission Computed Tomography (SPECT) Market Foresight
Preventive maintenance and software upgrade subscriptions are consolidating around equipment vendors rather than independent service organizations. Siemens Healthineers leverages its digital service platform to lock in multi-year contracts across installed base accounts. GE HealthCare anchors its aftermarket revenue through predictive analytics bundled with detector replacement programs. Canon Medical Systems competes on regional service density, particularly across East Asian hospital networks.
Single-photon emission computed tomography captures gamma ray emissions from radiopharmaceutical tracers to reconstruct three-dimensional functional images, typically employing sodium iodide [NaI(Tl)] or cadmium zinc telluride detectors with energy resolution between 9-12% at 140 keV. The technology serves primarily to assess blood flow, organ function, and metabolic activity in clinical diagnostics and treatment monitoring. Hybrid SPECT systems command premium positioning by fusing functional data with CT anatomical reference, while CZT detector technology displaces conventional NaI scintillator configurations in cardiology-focused installations due to superior energy resolution and reduced scan times. Application demand clusters in cardiology and oncology, where reimbursement certainty and protocol standardization protect margin pools.
The FDA governs radiopharmaceutical approval and device clearance under 21 CFR requirements, while the EMA oversees centralized marketing authorization across European member states through the MDR framework. Japan's PMDA maintains distinct technical standards for detector performance validation that shape product configurations for that market. Stakeholders must monitor evolving CMS reimbursement codes for myocardial perfusion imaging and prepare for potential site-of-service payment differentials between hospital outpatient departments and freestanding diagnostic centers.
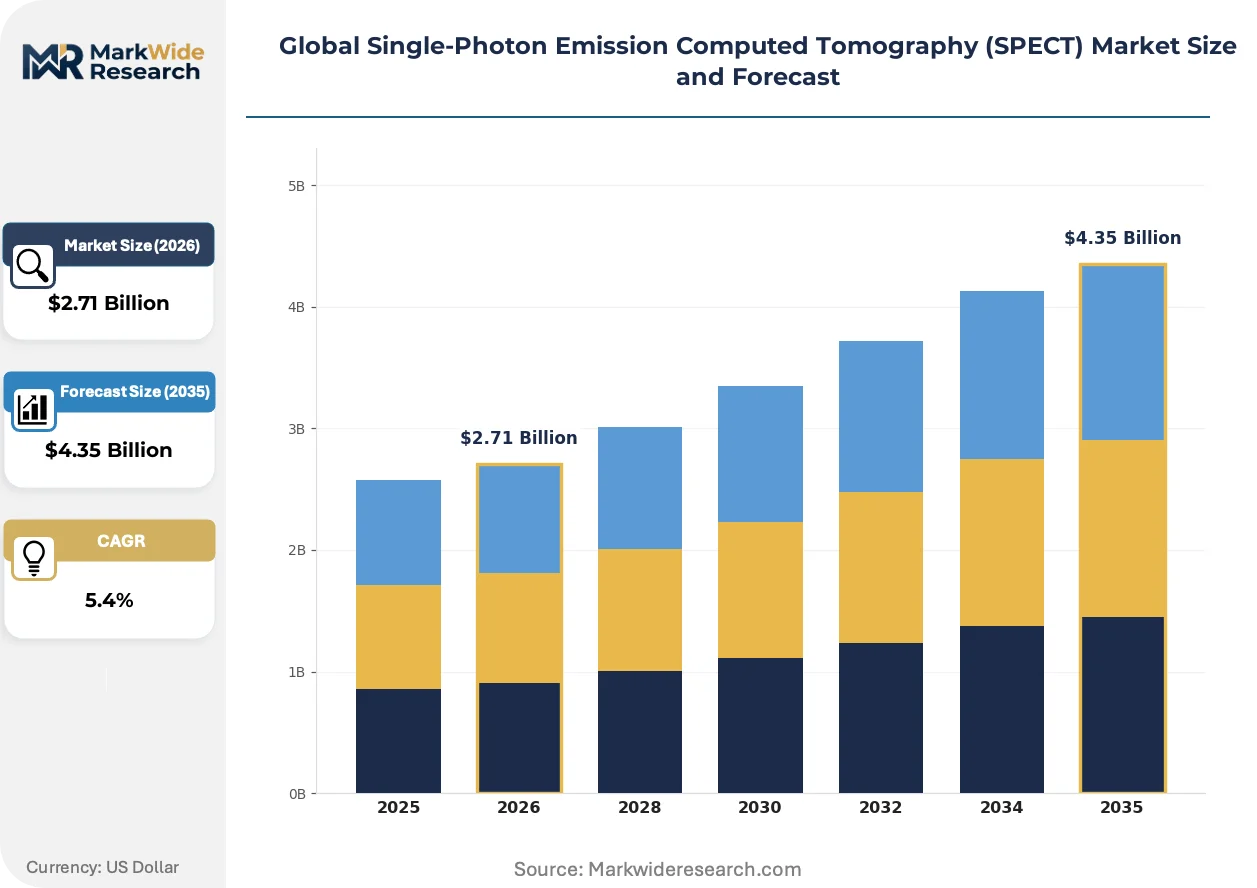
Market Dynamics
Cadmium zinc telluride detector technology is restructuring competitive positioning across the SPECT installed base, compressing scan times and forcing incumbent vendors to accelerate hardware refresh cycles.
Growth Catalysts
- Cardiology protocol expansion:Hospital systems are standardizing myocardial perfusion imaging protocols, creating pull-through demand for hybrid SPECT-CT configurations in tertiary care centers.
- FDA diagnostic radiopharmaceutical guidance updates:Streamlined approval pathways for novel tracers are shortening development timelines and expanding the addressable tracer portfolio.
- Medicare reimbursement stability:CMS site-of-service payment differentials favor established nuclear medicine procedures in hospital outpatient departments.
Market Restraints
- Isotope supply concentration:Molybdenum-99 production clusters at aging research reactors in Canada and the Netherlands, exposing users to unplanned outage risk.
- CZT detector cost structure:Semiconductor-grade crystal growth requires specialized foundry capacity that limits manufacturing scale and sustains premium pricing.
- Positron emission tomography substitution:PET-CT systems with superior spatial resolution capture oncology referrals previously routed to SPECT protocols.
Strategic Opportunities
- India diagnostic infrastructure buildout:Government PLI scheme incentives for medical device manufacturing are drawing vendor investment toward localized assembly and service networks.
- Theranostic convergence:Radioligand therapy expansion is creating demand for SPECT-based dosimetry verification alongside diagnostic staging workflows.
- Artificial intelligence reconstruction:Deep learning algorithms are reducing acquisition times and enabling throughput gains without hardware replacement.
Industry Challenges
- Nuclear medicine technologist shortage:Radiation safety certification requirements and aging workforce demographics constrain scanner utilization rates.
- Legacy NaI detector integration:Hospital capital planning cycles struggle to justify full fleet replacement when existing scintillator systems remain clinically functional.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Single-Photon Emission Computed Tomography (SPECT) Market |
| Market Size in 2026 | $2.71 Billion |
| Market Size in 2035 | $4.35 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid SPECT, Portable SPECT, Dedicated Cardiovascular SPECT, Dedicated Brain SPECT, Mobile SPECT Application: Neurology, Cardiology, Oncology, Infection Detection, Endocrinology End User: Hospitals, Diagnostic Centers, Research Institutes, Clinics, Pharmaceutical Companies Technology: Multidetector SPECT, CZT Detector Technology, NaI Scintillator, High-Resolution Detectors, Solid-State Detectors |
| Companies Covered | Canon Medical Systems, Bracco Imaging, GE HealthCare, Lantheus Medical Imaging, Curium, Siemens Healthineers, Cardinal Health, United Imaging, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Single-Photon Emission Computed Tomography (SPECT) Market Shifts & Advancements
Workflow automation and software-defined imaging architectures are compressing examination durations while regulatory pressure on radiation exposure is accelerating detector material transitions.
Cadmium zinc telluride semiconductor detectors are automating energy discrimination and event positioning that previously required manual calibration protocols. Cardiology departments in United States health systems are adopting CZT-based systems at replacement cycle points to capture throughput gains. This shift is automating technologist workload allocation and reducing per-scan labor minutes by eliminating iterative quality checks.
Europe's MDR framework is extending conformity assessment timelines for SPECT device registrations, forcing manufacturers to front-load clinical evidence packages. Technical documentation requirements now mandate post-market surveillance systems that track detector performance degradation. Vendors are responding by restructuring European product launches to prioritize hybrid configurations with established CT module clearances.
Service contract unbundling is fragmenting buyer-vendor relationships as hospital procurement departments separate hardware maintenance from software subscription tiers. Independent service organizations are capturing detector replacement and preventive maintenance volumes previously held by original equipment manufacturers. This pattern is most pronounced in German and Japanese hospital networks with mature clinical engineering capabilities.
Global Single-Photon Emission Computed Tomography (SPECT) Market Segmentation
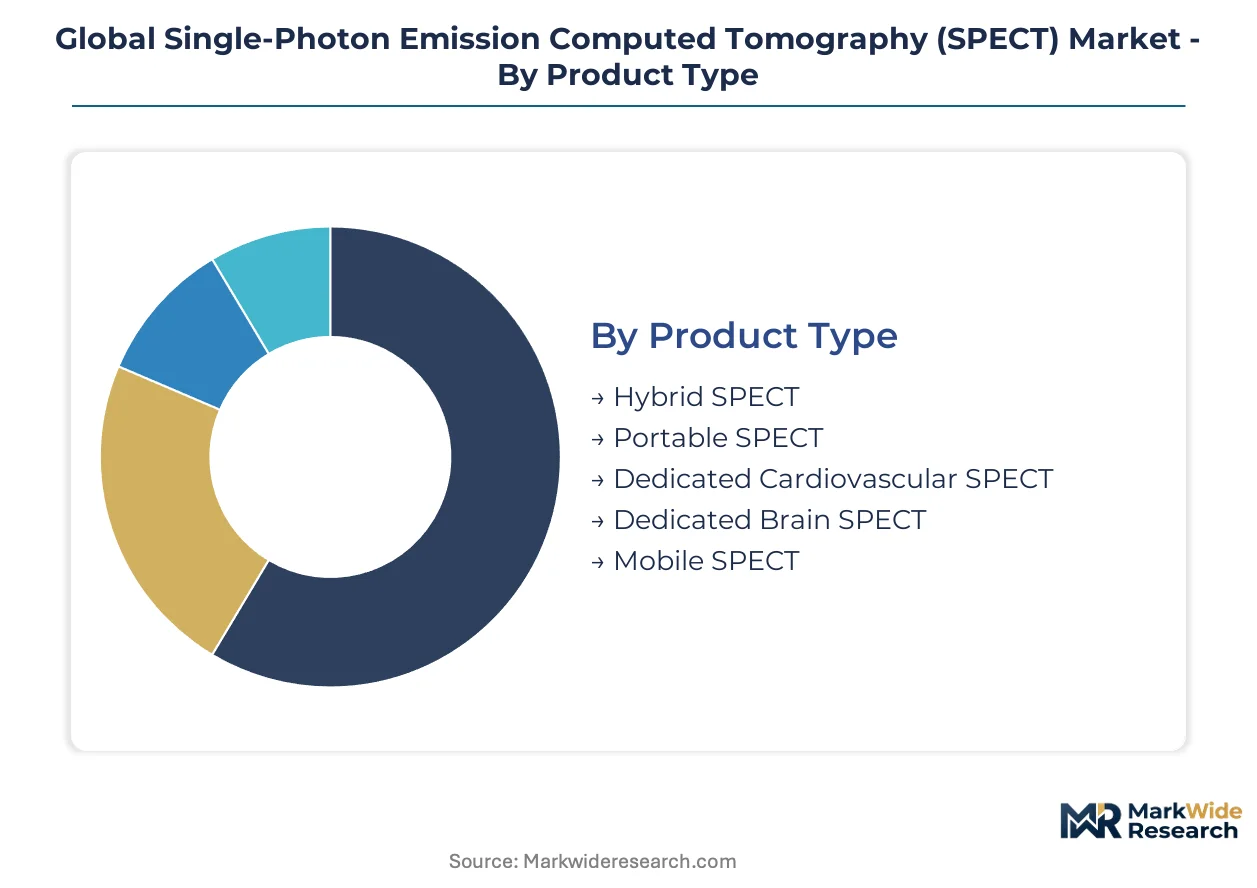
SPECT market segmentation reflects divergent clinical workflows across stationary hospital installations and distributed point-of-care networks. Equipment configurations vary sharply between high-throughput tertiary centers requiring hybrid anatomical fusion and mobile units serving rural access gaps.
Product Type:
Customization spans from fixed-room hybrid systems with integrated CT modules to self-contained mobile trailers, with standardization concentrated in portable units for emergency department triage.
- Hybrid SPECT:Combines functional gamma emission mapping with CT anatomical reference in single gantry architecture. Demand clusters in United States academic medical centers where CMS reimbursement favors hospital outpatient department site-of-service for myocardial perfusion imaging.
- Dedicated Cardiovascular SPECT:Optimized detector geometry and acquisition protocols for cardiac stress-rest perfusion studies. Adoption accelerates in German hospital networks seeking throughput gains through CZT detector replacement cycles.
- Portable SPECT:Compact gantry designs for intraoperative or emergency department deployment.
- Dedicated Brain SPECT:Specialized head-dedicated detector arrays for cerebrovascular and neurodegenerative assessment.
- Mobile SPECT:Trailer-mounted systems for rural service area coverage and temporary capacity expansion.
Leading the category by volume: Hybrid SPECT. Expanding most quickly: Dedicated Cardiovascular SPECT.
Application:
Clinical utility concentrates where reimbursement codes provide procedural certainty, with cardiology commanding capital allocation priority over emerging neurology protocols.
- Cardiology:Myocardial perfusion imaging dominates procedure volume through established CAD assessment protocols. Japanese health systems drive replacement demand as PMDA detector performance standards accelerate CZT adoption for stress testing workflows.
- Oncology:Tumor staging and therapy response monitoring using bone-seeking and receptor-targeted tracers. Referral patterns shift toward PET-CT substitution in United States oncology networks where superior spatial resolution commands premium positioning.
- Neurology:Cerebral blood flow quantification for dementia and epilepsy evaluation.
- Infection Detection:Radiolabeled white blood cell imaging for occult sepsis localization.
- Endocrinology:Thyroid and parathyroid functional assessment using iodine-123 and technetium-99m protocols.
Cardiology generates the highest procedure volume. Oncology faces the steepest competitive pressure from PET-CT substitution.
End User:
Procurement authority differs sharply between integrated health system capital committees and independent diagnostic center owner-operators.
- Hospitals:Tertiary care centers with nuclear medicine departments and captive radiopharmacy infrastructure. India's PLI scheme incentives are drawing vendor investment toward localized service networks for hospital-installed base expansion.
- Diagnostic Centers:Freestanding imaging facilities competing on appointment availability and payer contract breadth. Site-of-service payment differentials disadvantage these operators under current CMS hospital outpatient department reimbursement rules.
- Research Institutes:Academic medical centers with investigational new drug protocols and tracer development programs.
- Clinics:Limited deployment for thyroid and sentinel lymph node procedures.
- Pharmaceutical Companies:Contract research organization partnerships for radioligand therapy clinical trials.
Hospitals anchor installed base value. Diagnostic centers represent the most price-sensitive procurement segment.
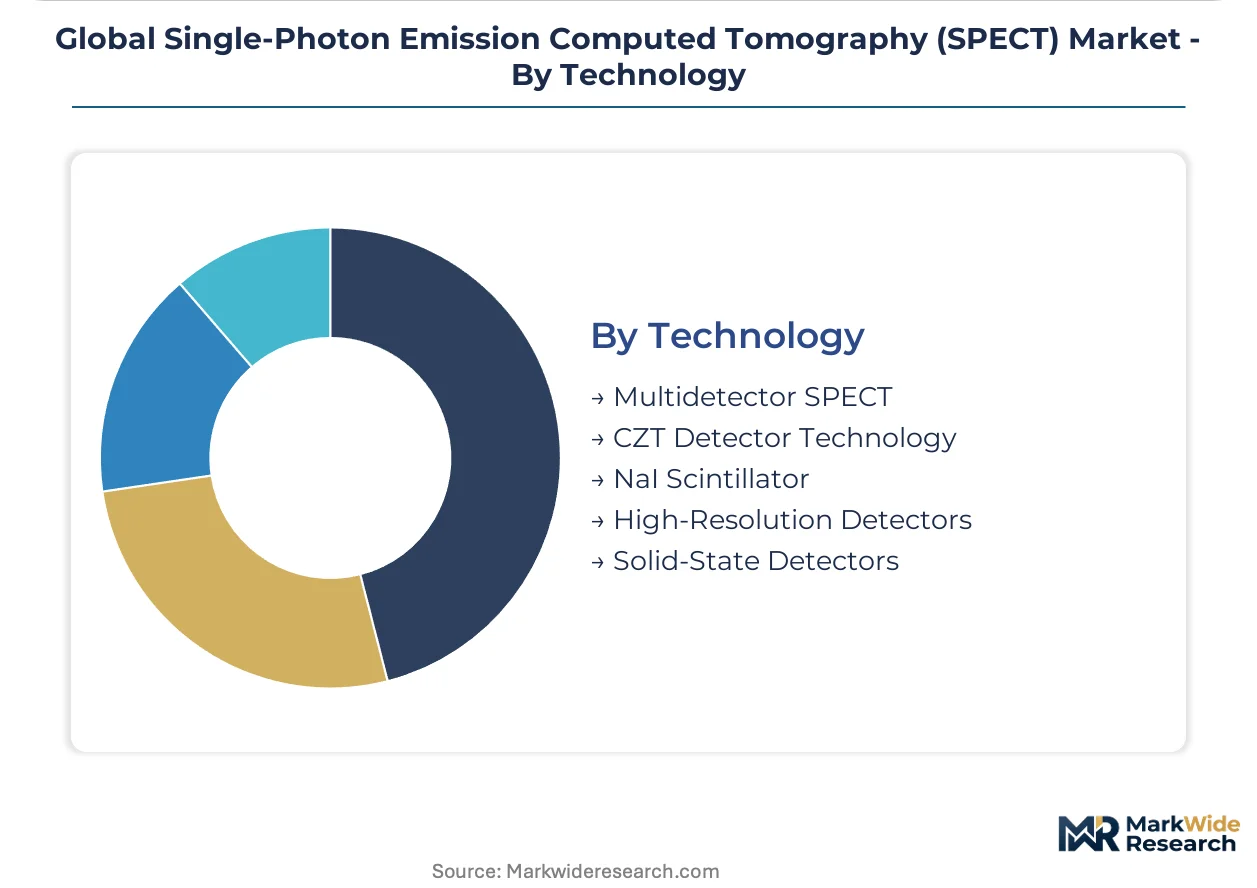
Technology:
Detector material selection determines energy resolution, scan duration, and capital depreciation schedules across the installed base.
- CZT Detector Technology:Cadmium zinc telluride semiconductors deliver 9-12% energy resolution at 140 keV with direct gamma conversion. German hospital procurement departments separate hardware maintenance from software subscriptions, fragmenting vendor relationships for CZT-equipped systems.
- NaI Scintillator:Thallium-doped sodium iodide crystals with established supply chains and lower unit economics. Legacy installations in Japanese networks face extended replacement cycles as capital planning struggles to justify fleet refresh against functional remaining life.
- Multidetector SPECT:Multiple gamma camera heads for simultaneous angular sampling.
- High-Resolution Detectors:Specialized collimator geometries for small-animal or pediatric applications.
- Solid-State Detectors:Emerging semiconductor alternatives to CZT for cost-sensitive configurations.
CZT Detector Technology commands the premium tier. NaI Scintillator retains the largest installed base population.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of molybdenum-99 isotopes concentrates at aging research reactors in Canada and the Netherlands, while consumption gravitates toward hospital systems in the United States, Germany, and Japan where reimbursement stability supports capital deployment.
United States
Hospital outpatient departments drive replacement demand for CZT-equipped systems as CMS site-of-service payment differentials favor established nuclear medicine protocols. The FDA governs radiopharmaceutical approval under 21 CFR requirements, streamlining pathways for novel tracers. Academic medical centers in Boston and Houston anchor hybrid SPECT-CT installations for myocardial perfusion imaging.
Germany
Hospital procurement departments separate hardware maintenance from software subscriptions, fragmenting vendor relationships across the installed base. The EMA oversees centralized marketing authorization through the MDR framework, extending conformity assessment timelines for device registrations. The Rhine-Ruhr metropolitan region concentrates service contract unbundling activity as mature clinical engineering capabilities enable independent service organization penetration.
Japan
PMDA detector performance standards accelerate CZT adoption for stress testing workflows in cardiology departments. METI maintains distinct technical standards for detector validation that shape product configurations for domestic installations. The Kanto region surrounding Tokyo hosts the highest density of replacement cycle activity as health systems modernize nuclear medicine infrastructure.
India
Government PLI scheme incentives for medical device manufacturing are drawing vendor investment toward localized assembly and service networks. The CDSCO regulates diagnostic device import and distribution, creating compliance thresholds for multinational entrants. Maharashtra and Karnataka are emerging as hubs for hospital-installed base expansion as tertiary care centers build captive radiopharmacy infrastructure.
China
Domestic equipment vendors are capturing share in provincial hospital networks through cost-competitive detector configurations. The NMPA governs device clearance and radiopharmaceutical licensing under centralized review processes. The Yangtze River Delta region concentrates demand for hybrid systems as municipal health bureaus upgrade diagnostic capabilities in Shanghai and surrounding prefectures.
Global Single-Photon Emission Computed Tomography (SPECT) Market Competitive Landscape
Top-tier vendors anchor the premium hybrid SPECT-CT segment, while mid-tier specialists compete on regional service density and detector replacement programs. Siemens Healthineers leverages digital service platforms to lock in multi-year contracts, while GE HealthCare anchors aftermarket revenue through predictive analytics bundles. The competitive landscape features three strategic archetypes: integrated imaging conglomerates with full modality portfolios, radiopharmaceutical suppliers with vertical tracer capabilities, and regional equipment specialists with localized service networks. Dominant competitive moves include detector technology transitions from NaI to CZT and service contract restructuring to separate hardware maintenance from software tiers.
Among integrated imaging conglomerates, Siemens Healthineers and GE HealthCare exemplify the full-modality archetype with established installed base positions across major hospital systems. Canon Medical Systems occupies a position within the regional service density tier, competing on proximity maintenance networks particularly across East Asian installations. These three entities represent the competitive core around which pricing, technology roadmaps, and service model innovation are currently organizing.
| Leading Market Players |
|---|
| Canon Medical Systems |
| Bracco Imaging |
| GE HealthCare |
| Lantheus Medical Imaging |
| Curium |
| Siemens Healthineers |
| Cardinal Health |
| United Imaging |
| Koninklijke Philips N.V. |
| Others |
Supply & Pricing Matrix
Equipment vendor consolidation through private-equity-rolled-up service organizations concentrates pricing power in aftermarket contracts, while semiconductor-grade crystal foundry scarcity sustains premium positioning for cadmium zinc telluride detectors across hospital procurement cycles.
Pricing Analysis
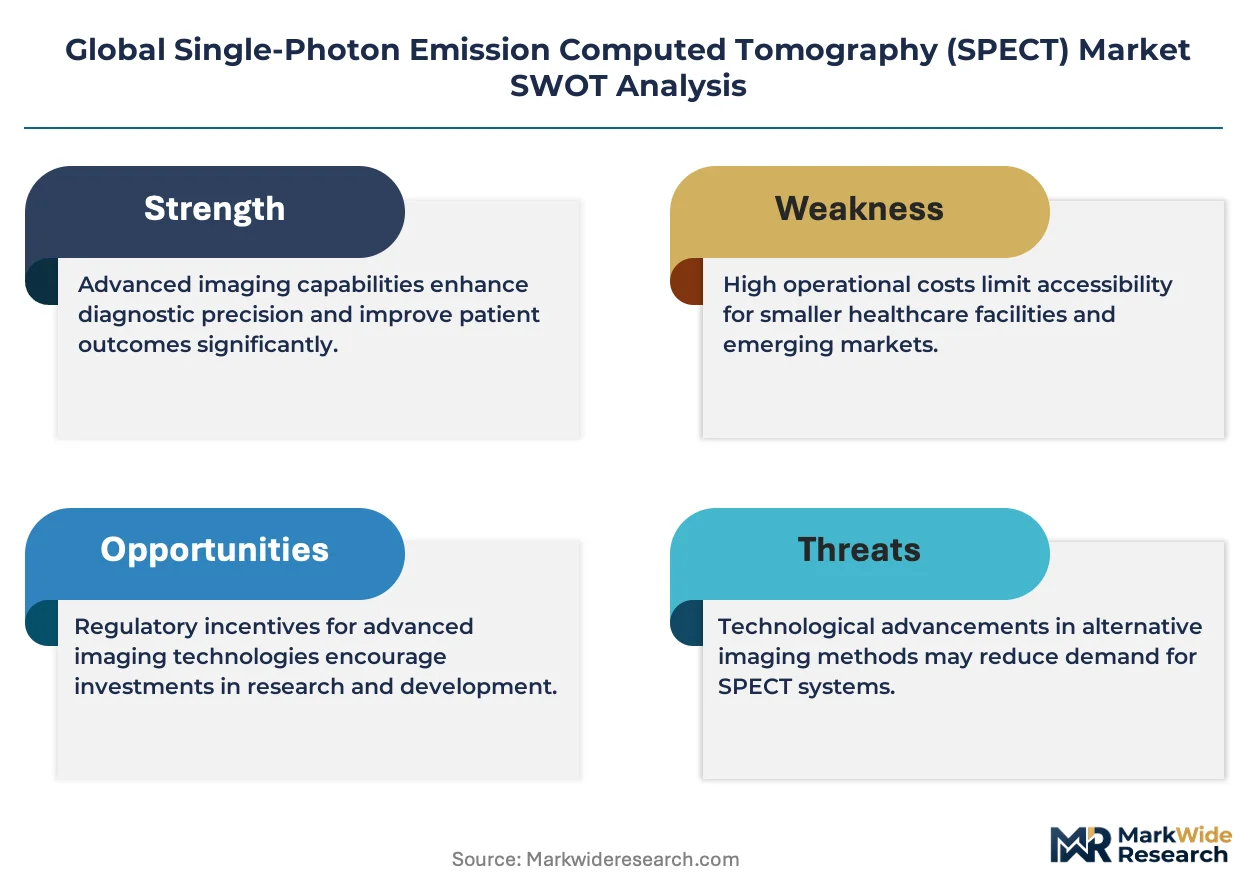
Margin tightening in detector replacement programs reflects CZT semiconductor foundry bottlenecks and specialized crystal growth requirements. Three-tier pricing structure across premium hybrid configurations, standard dedicated cardiology systems, and economy mobile units stratifies by detector material and software bundling intensity. Cost compression accelerates in the NaI scintillator tier as independent service organizations unbundle maintenance from original equipment manufacturer contracts. Freestanding diagnostic centers exhibit the highest price sensitivity, while academic medical centers anchored by NIH-funded research programs absorb premium hybrid system positioning.
Supply Chain Analysis
Single-source vulnerability sits with molybdenum-99 production at aging research reactors in Canada and the Netherlands. CZT crystal ingots draw from specialized foundries in the United States and Japan, while thallium-doped sodium iodide scintillator supply rests on established chemical processing corridors in China and Germany. Tariff exposure concentrates in detector electronics subassemblies sourced through East Asian contract manufacturers. Distribution runs through hospital capital equipment committees with multi-year procurement cycles, radiopharmaceutical distributor networks with cold-chain logistics, and direct vendor relationships for high-value hybrid installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SPECT market is becoming a vertical-integration race, with radiopharmaceutical suppliers acquiring dosimetry software capabilities and equipment vendors capturing captive isotope sourcing arrangements to secure procedure throughput.
For Market Incumbents: Cement installed base loyalty through predictive analytics subscriptions that preempt independent service organization penetration, while accelerating CZT detector refresh cycles ahead of PET-CT substitution in oncology referral patterns. Lock in multi-year radiopharmaceutical supply agreements with Curium and Lantheus to insulate hospital customers from molybdenum-99 outage risk. Prioritize backward integration into semiconductor-grade crystal foundry capacity to reduce CZT cost structure vulnerability. For New Entrants and Emerging Players: Begin with portable SPECT configurations for emergency department triage and rural mobile imaging, where capital planning cycles favor lower acquisition thresholds and service contract unbundling has already fragmented vendor relationships. Target India's PLI scheme subsidized manufacturing corridors in Maharashtra and Karnataka for localized assembly cost advantages. Lead with AI reconstruction software that reduces scan times without hardware replacement, bypassing detector material supply constraints. For Investors and Strategic Acquirers: Distressed-cycle entries favor independent service organizations with established clinical engineering capabilities in German and Japanese hospital networks, where procurement departments have already separated hardware maintenance from software tiers. Long-term viability hinges on theranostic convergence positioning, with SPECT-based dosimetry verification capturing radioligand therapy workflow integration. Monitor FDA diagnostic radiopharmaceutical guidance implementation as the signal for tracer portfolio expansion and addressable market inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CZT Detector Technology Transition | Superior energy resolution at 140 keV compresses scan times and forces hardware refresh cycles across the installed base. |
| AI Reconstruction Algorithm Development | Deep learning reduces acquisition durations and enables throughput gains without capital-intensive detector replacement. |
| Theranostic Workflow Integration | Radioligand therapy expansion creates demand for SPECT-based dosimetry verification alongside diagnostic staging protocols. |
| Regional Service Density Expansion | Proximity maintenance networks in East Asia and India capture unbundled service contracts from original equipment manufacturers. |
| Radiopharmaceutical Supply Security | Long-term offtake agreements with molybdenum-99 producers insulate hospital customers from research reactor outage risk. |
Research Methodology
Multi-period observation of hospital capital expenditure patterns, radiopharmaceutical procedure volumes, and detector replacement cycle timing anchored the trend analysis, supplemented by interviews with nuclear medicine department heads, biomedical engineering directors, GPO contracts managers, and radiopharmaceutical supply specialists. Secondary validation drew from FDA 510(k) clearance databases, EMA MDR technical documentation filings, CMS Medicare reimbursement code updates, and hospital procurement database aggregators. Bottom-up equipment shipment tracking triangulated against top-down health system capital budget surveys to establish market sizing boundaries.
The input-output matrix framed demand drivers across cardiology protocol expansion, oncology referral substitution risk, and technologist workforce constraints against supply-side variables including isotope production capacity and semiconductor foundry utilization. Segmentation dimensions spanned detector technology tier, system configuration type, clinical application, and end-user procurement authority. CAGRs were derived from logistic diffusion modeling of technology replacement curves and reimbursement stability indices. Industry-specific forecast inputs incorporated PMDA detector performance standard adoption timelines and PLI scheme incentive disbursement trajectories.
Underlying measurement precision varies by segment; hybrid SPECT-CT installations carry tighter precision than portable unit deployments due to concentrated vendor reporting. Forecasts reflect assumptions regarding CMS site-of-service payment stability and molybdenum-99 reactor operational continuity that could revise substantially upon regulatory or infrastructure disruption. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Ga 68 DOTATOC Market
Medical Imaging
Global Medical Imaging Phantoms Market
Medical Imaging
North America MRI (Magnetic Resonance Imaging) Market
Medical Imaging
Medical Radiation Detection Market
Medical Imaging
3D Medical and Surgical Imaging Market
Medical Imaging
Coronary Heart Disease Diagnostic Imaging Market
Medical Imaging
Europe Diagnostic Imaging Equipment Market
Medical Imaging
Malaysia Digital Radiography Market
Medical Imaging
United Kingdom Computed Tomography Market
Medical Imaging
India Computed Tomography Market
Medical Imaging
Industrial Computed Radiography Market
Medical Imaging
Asia-Pacific Digital X-Ray Devices Market
Medical Imaging
Spain Digital X-Ray Market
Medical Imaging
Canada Nuclear Imaging Market
Medical Imaging
Global Medical Imaging Workstation Market
Medical Imaging
Cone Beam Computed Tomography (CBCT) System Market