
 Telepathology Market | 2026-2036
Telepathology Market Size, Share, and Industry Trends Forecast 2026-2036
Telepathology Market Analysis
Subscription-based leasing for whole slide imaging scanners is fragmenting capital barriers for mid-sized diagnostic laboratories. Philips Healthcare leverages its enterprise imaging ecosystem to anchor hospital network contracts across North America. Leica Biosystems specializes in hardware-software integration for histopathology workflows, while Hamamatsu Photonics competes through sensor technology leadership in high-resolution image capture.
Telepathology encompasses the electronic transmission of pathology images and associated clinical data for diagnostic, educational, or research purposes, typically employing whole slide imaging systems that digitize glass slides at resolutions exceeding 20x optical magnification to enable remote interpretation. The technology serves primarily to extend specialist pathologist access to underserved regions and accelerate turnaround times for critical diagnoses. Whole slide imaging currently dominates installed base metrics among technology segments, while cloud-based tools represent the fastest-expanding margin pool as laboratories shift from on-premise storage to scalable subscription architectures. Diagnostic laboratories constitute the most concentrated end-user segment by transaction volume, though academic institutions sustain higher per-site software and training service expenditures.
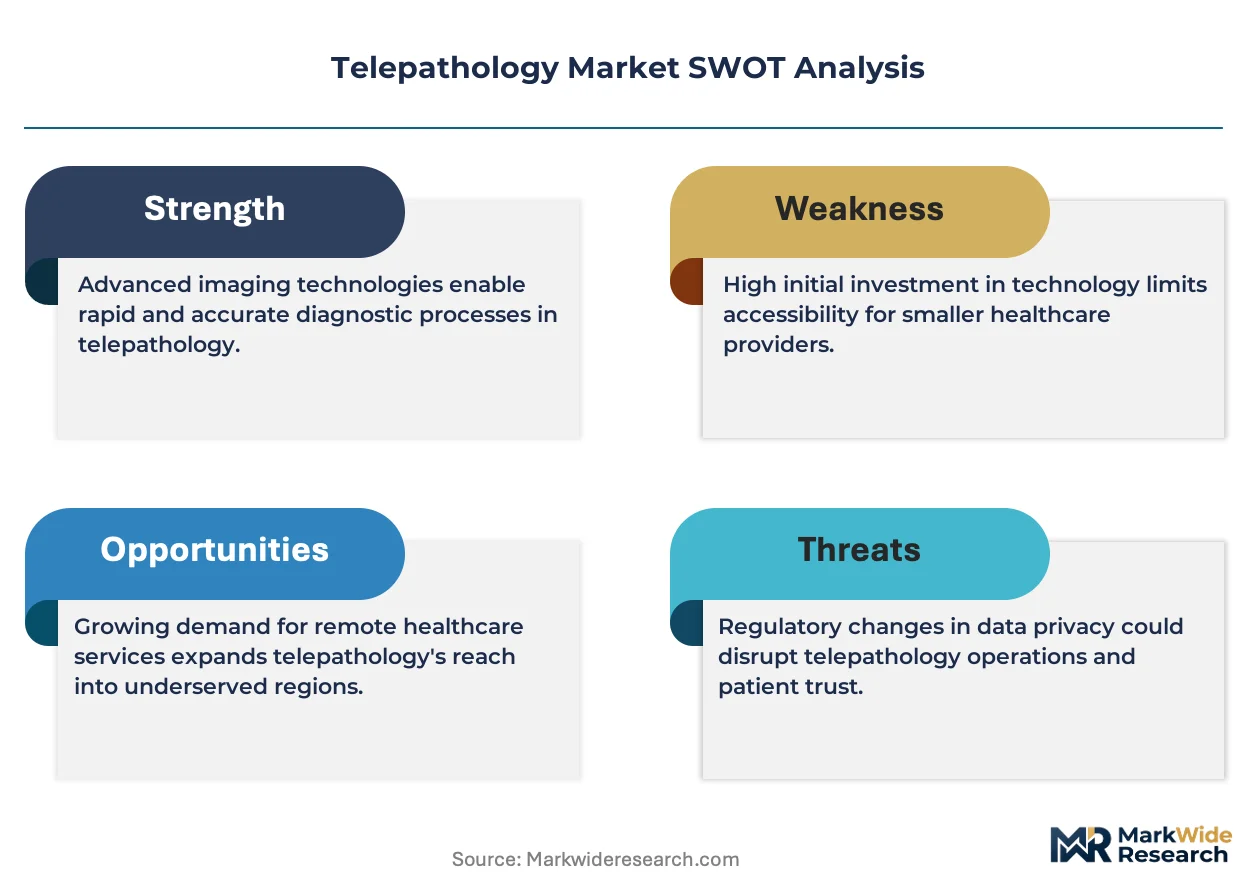
FDA premarket notification requirements for whole slide imaging devices shape product development timelines and commercial launch sequencing in the United States, while the EU Medical Device Regulation imposes conformity assessment obligations that filter market access across European member states. HIPAA security provisions in the United States and GDPR data localization standards in Europe constrain cross-border image transmission architectures, forcing vendors to engineer jurisdiction-specific data residency protocols. Stakeholders must monitor evolving reimbursement determinations for remote pathology services, as coverage parity with conventional in-person diagnostics will determine deployment velocity across health systems.
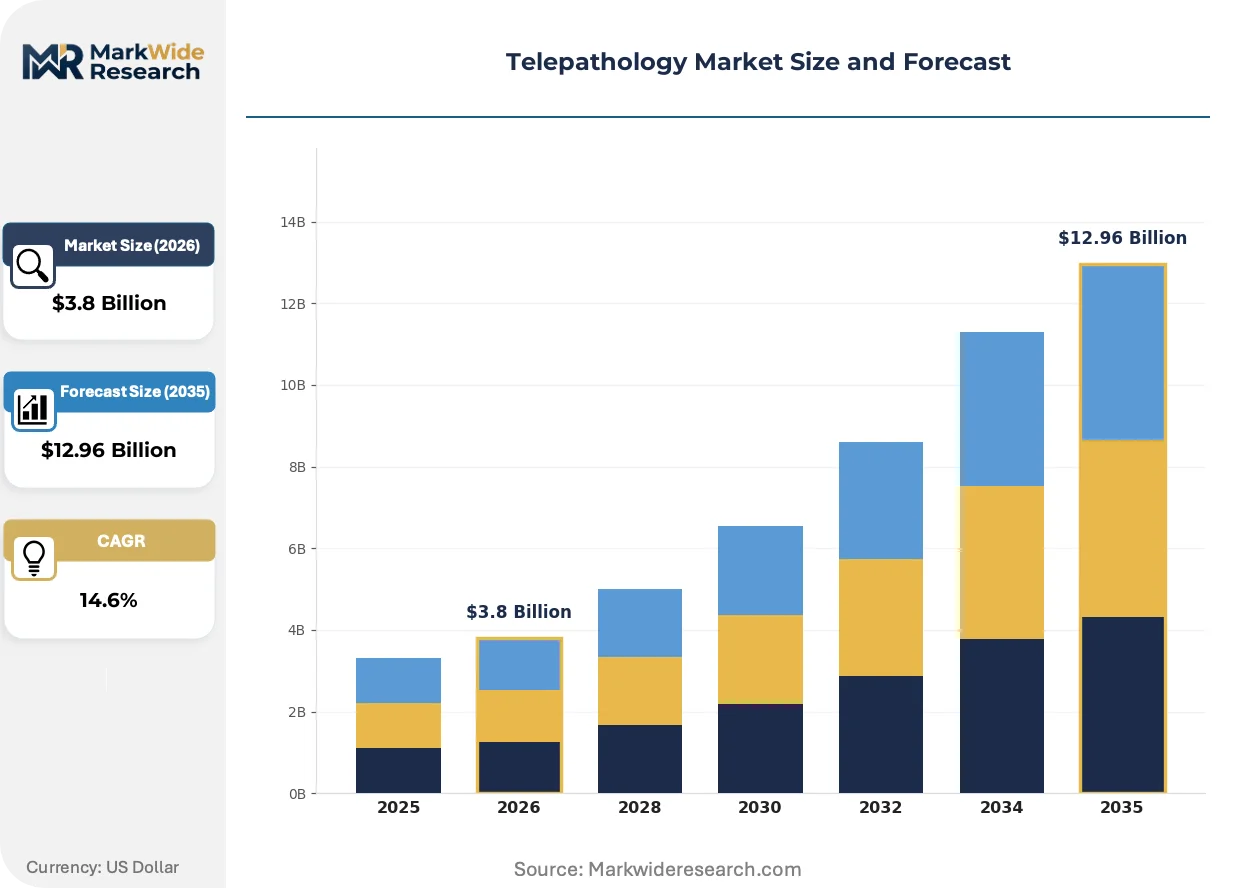
Market Dynamics
Cloud-based whole slide imaging is compressing capital requirements for diagnostic laboratories while FDA clearance pathways accelerate commercial deployment timelines for digital pathology devices. This structural shift fragments barriers to entry and reconfigures vendor-customer contracting relationships.
Growth Catalysts
- Pathologist workforce shortages:Rural and underserved regions in the United States face critical gaps in specialist availability, forcing hospital networks to deploy remote diagnostic capabilities.
- HIPAA-compliant cloud architectures:Security provisions for protected health information have matured sufficiently to enable cross-state image transmission for clinical decision-making.
- Histopathology workflow automation:Integration of artificial intelligence-assisted screening tools reduces manual slide review burden and accelerates turnaround times for cancer diagnoses.
Market Restraints
- High-resolution sensor supply concentration:Advanced CMOS and CCD sensors for whole slide imaging depend on a limited supplier base concentrated in East Asian manufacturing clusters.
- EU Medical Device Regulation conformity costs:MDR assessment obligations impose documentation and clinical evidence burdens that extend product launch timelines by 12-24 months for European market access.
- Bandwidth infrastructure heterogeneity:Inconsistent fiber and 5G deployment across diagnostic laboratory networks constrains real-time image streaming at diagnostic-grade resolution.
Strategic Opportunities
- Underserved Latin American markets:Brazil and Mexico present white space for remote pathology services where specialist pathologist density remains critically low relative to disease burden.
- Subscription-based scanner leasing:Mid-sized laboratories are shifting from capital purchase to operational expenditure models for whole slide imaging hardware.
- AI Act regulatory clarity in Europe:The EU AI Act's risk classification framework for medical devices creates predictable compliance pathways for algorithmic diagnostic tools.
Industry Challenges
- Digital pathology informatics expertise gap:Laboratories struggle to recruit personnel with hybrid competencies in histopathology and enterprise imaging system administration.
- Legacy LIS-PACS integration complexity:Proprietary data formats from incumbent laboratory information systems resist seamless interoperability with cloud-native whole slide imaging platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telepathology Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Digital Pathology, Remote Diagnosis, Education, Research End User: Hospitals, Diagnostic Laboratories, Academic Institutions, Research Facilities Technology: Whole Slide Imaging, Imaging Software, Data Storage Solutions, Cloud-Based Tools Service Type: Consultation, Data Analysis, Software Support, Training Services |
| Companies Covered | Leica Biosystems, Philips Healthcare, Roche Diagnostics, Danaher Corporation, Hamamatsu Photonics, 3DHISTECH, Cerner Corporation, American Well, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telepathology Market Emerging Trajectories
Artificial intelligence integration is transforming diagnostic workflows from reactive interpretation to predictive risk stratification. This evolution compresses diagnostic cycles while elevating software margins above hardware commoditization pressures.
Computational pathology algorithms are digitizing pattern recognition tasks previously requiring specialist pathologist hours. Academic medical centers in the United States are deploying these tools for prostate cancer and lymphoma screening at scale. The technology is digitizing diagnostic labor allocation, shifting human expertise toward complex case arbitration while algorithms handle high-volume screening protocols.
FDA premarket notification requirements for whole slide imaging devices are tightening clinical validation standards for algorithm-assisted diagnostics. Manufacturers must now submit reader studies demonstrating non-inferiority to conventional microscopy. Diagnostic laboratories seeking 510(k)-cleared platforms are prioritizing vendors with established FDA submission track records over emerging entrants.
Hospital procurement committees are unbundling after-sales service contracts from scanner hardware purchases, seeking specialized third-party maintenance providers. This behavior fragments vendor lock-in and creates margin pressure on original equipment manufacturers. The United States exhibits the most pronounced unbundling, where health system consolidation has centralized purchasing authority and standardized service-level expectations.
Telepathology Market Segmentation
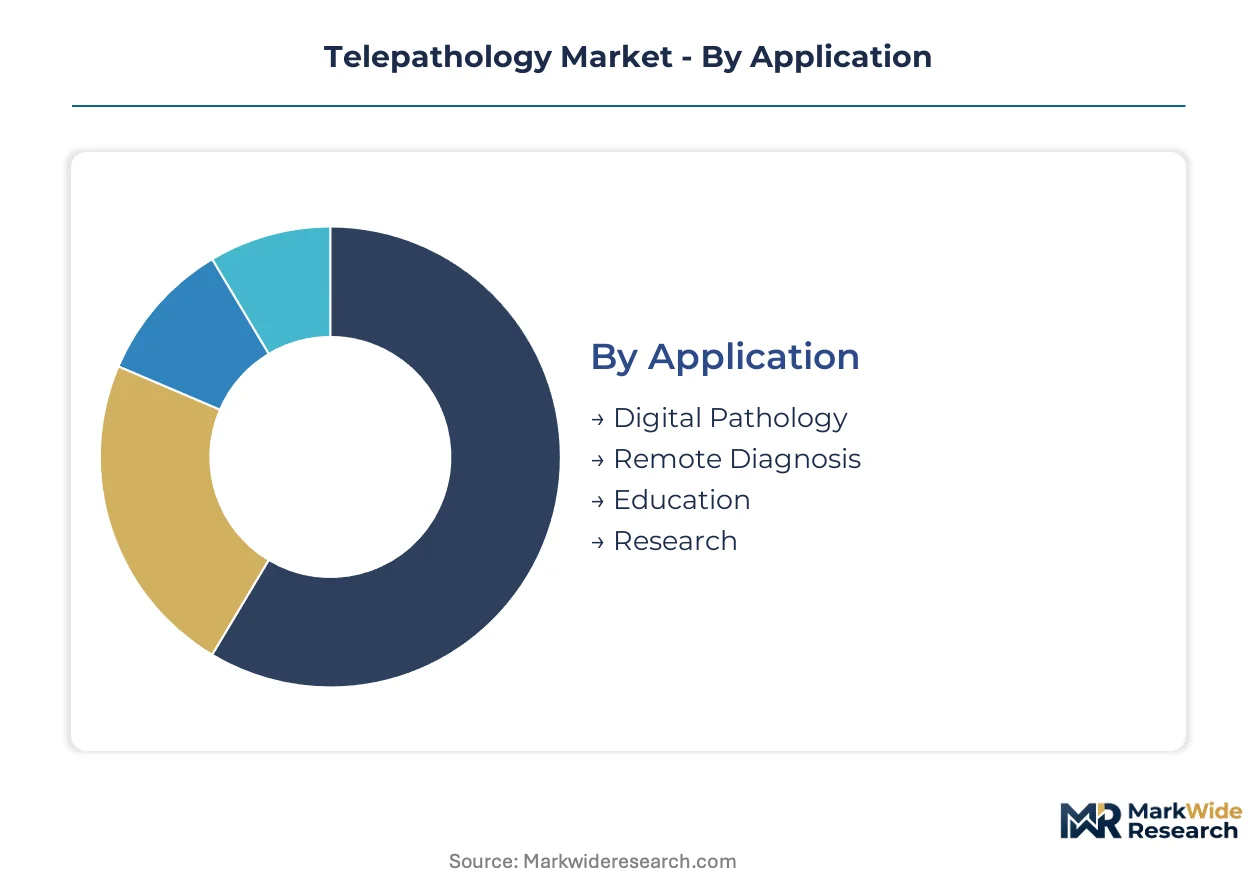
Telepathology segmentation reveals how value pools distribute across hardware, software, and service layers. Each dimension carries distinct margin profiles and regulatory exposure that shape vendor positioning strategies.
Application:
Application scope determines reimbursement eligibility and regulatory pathway complexity for telepathology deployments.
- Digital Pathology:Encompasses digitization of histopathology workflows through whole slide imaging systems integrated with laboratory information systems. Hospital networks in the United States concentrate procurement here as FDA-cleared platforms enable diagnostic reimbursement parity with conventional microscopy.
- Remote Diagnosis:Real-time specialist consultation across geographic distances using high-resolution image transmission. Rural health systems deploy this application to address pathologist workforce gaps, with HIPAA-compliant cloud architectures enabling cross-state clinical decision-making.
- Education:Training platforms for pathology residents and continuing medical education using annotated slide libraries. Academic medical centers sustain higher per-site software expenditures here than diagnostic laboratories.
- Research:Tissue biobanking and multi-institutional studies requiring standardized image formats and metadata protocols. Pharmaceutical companies fund this segment for biomarker discovery and clinical trial endpoint validation.
Digital Pathology holds installed capacity. Remote Diagnosis is rotating up the share rankings.
End User:
Customer type dictates contract structure, with consolidated health systems demanding enterprise pricing and academic institutions negotiating research licensing terms.
- Hospitals:Integrated delivery networks purchasing enterprise-wide digital pathology platforms with multi-site deployment rights. United States hospital consolidation has centralized procurement authority and standardized service-level expectations.
- Diagnostic Laboratories:Independent and hospital-affiliated labs forming the most concentrated transaction volume segment. Mid-sized laboratories are shifting from capital purchase to subscription-based scanner leasing models.
- Academic Institutions:Medical schools and university hospitals driving AI algorithm development and clinical validation studies. These sites sustain elevated training service expenditures relative to hardware procurement.
- Research Facilities:Pharmaceutical and biotechnology company laboratories utilizing telepathology for drug development and companion diagnostic programs. Contract structures emphasize data sovereignty and intellectual property provisions.
Diagnostic Laboratories anchor current volume. Cloud-native platforms are expanding fastest among Hospitals.
Technology:
Technology layers stratify between hardware commoditization pressures and software margin expansion opportunities.
- Whole Slide Imaging:Scanner hardware digitizing glass slides at resolutions exceeding 20x optical magnification. FDA premarket notification requirements shape product development timelines and commercial launch sequencing in the United States.
- Imaging Software:Visualization and analysis platforms enabling pathologist interpretation of digitized slides. Vendors compete through AI-assisted screening integration that reduces manual review burden for cancer diagnoses.
- Data Storage Solutions:On-premise server infrastructure for high-volume image archiving. Bandwidth infrastructure heterogeneity constrains migration from these legacy systems in certain geographic markets.
- Cloud-Based Tools:Scalable subscription architectures enabling real-time remote diagnostics without capital-intensive hardware procurement. This segment climbs the fastest as laboratories shift from on-premise storage to operational expenditure models.
Whole Slide Imaging retains hardware dominance. Cloud-Based Tools is rotating up the share rankings.
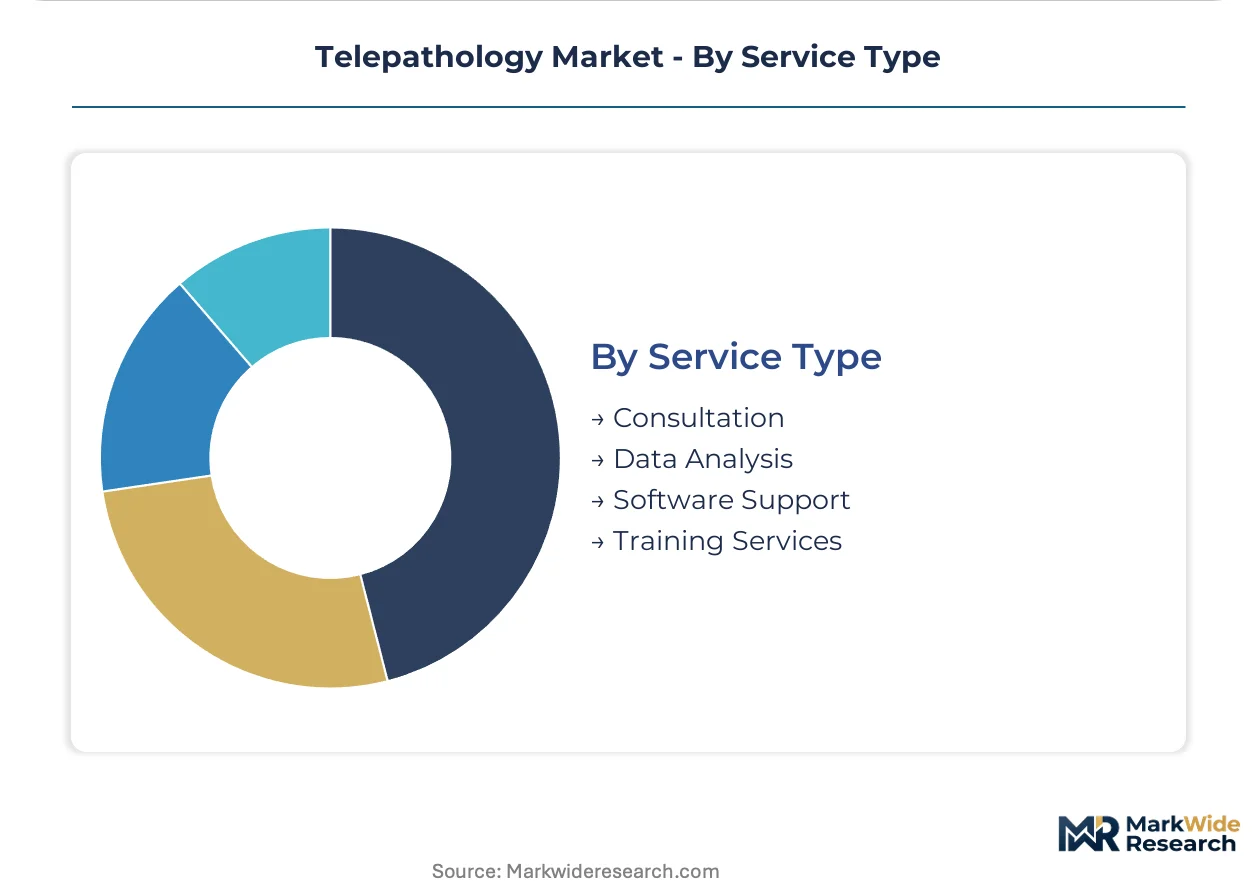
Service Type:
Service delivery models determine recurring revenue stability and customer switching costs for telepathology vendors.
- Consultation:Specialist pathologist interpretation services delivered remotely for complex or rare case diagnoses. Rural and underserved regions in the United States depend on this service type to address critical workforce gaps.
- Data Analysis:Computational pathology algorithms performing pattern recognition and quantitative biomarker assessment. Academic medical centers deploy these services for prostate cancer and lymphoma screening at scale.
- Software Support:Technical maintenance and system integration services for digital pathology platforms. Hospital procurement committees are unbundling these contracts from hardware purchases, fragmenting vendor lock-in.
- Training Services:Pathologist and laboratory technician education on digital workflow adoption. Academic institutions sustain higher per-site expenditures here than diagnostic laboratories.
Consultation holds installed capacity. Data Analysis is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways for digital pathology devices have accelerated commercial deployment in the United States, while the EU AI Act creates predictable compliance frameworks for algorithmic diagnostic tools across Europe. National reimbursement policies and data localization requirements are fragmenting vendor go-to-market strategies.
United States
Hospital networks deploy cloud-based whole slide imaging to address pathologist workforce shortages in rural regions. HIPAA security provisions constrain cross-border image transmission, forcing vendors to engineer jurisdiction-specific data residency protocols. The Mayo Clinic and Cleveland Clinic anchor enterprise imaging ecosystem adoption in the Midwest.
Germany
EU Medical Device Regulation conformity assessment obligations extend product launch timelines by 12-24 months for European market access. The country's national pharmaceutical regulator enforces clinical evidence documentation burdens that filter market entry. Berlin and Munich concentrate diagnostic laboratory consolidation activity among mid-sized operators.
Japan
Sensor technology leadership in high-resolution CMOS and CCD manufacturing supports domestic scanner hardware production. METI standards guide medical device software validation requirements for AI-assisted screening tools. Osaka and Nagoya host precision optics clusters supplying imaging componentry to regional vendors.
United Kingdom
NHS Long Term Plan targets for pathology digitization drive procurement of remote diagnostic capabilities across integrated care systems. GDPR data localization standards constrain cloud architecture choices for cross-border image transmission. London's academic medical centers sustain elevated training service expenditures for digital workflow adoption.
India
Specialist pathologist density remains critically low relative to disease burden, creating white space for remote consultation services. CDSCO medical device regulations govern import and registration requirements for whole slide imaging hardware. Bengaluru and Hyderabad anchor health technology startup activity targeting diagnostic workflow automation.
Telepathology Market Vendor Landscape
On the supply side, the industry is consolidating around enterprise imaging ecosystems and hardware-software integration specialists. Three archetypes dominate: diversified healthcare conglomerates leveraging cross-divisional contracts, precision optics manufacturers with captive sensor technology, and cloud-native platform vendors compressing capital barriers for mid-sized laboratories. Competitive moves concentrate on strategic partnerships with academic medical centers and unbundling of after-sales service contracts from hardware purchases.
Within the diversified healthcare tier, Philips Healthcare and Roche Diagnostics represent integrated system vendors anchoring hospital network contracts through enterprise imaging ecosystems. Leica Biosystems exemplifies the hardware-software integration archetype, while Hamamatsu Photonics occupies a position among precision optics specialists competing through sensor technology leadership.
| Leading Market Players |
|---|
| Leica Biosystems |
| Philips Healthcare |
| Roche Diagnostics |
| Danaher Corporation |
| Hamamatsu Photonics |
| 3DHISTECH |
| Cerner Corporation |
| American Well |
| Medtronic |
| Others |
Supply Flow & Price Mechanics
Osaka's precision optics cluster feeds high-resolution CMOS sensor production that determines pricing power for whole slide imaging hardware manufacturers serving North American diagnostic laboratories. Capacity constraints in Japanese sensor fabrication compress margins for scanner vendors unable to secure long-term component allocations.
Pricing Analysis
Certification level (FDA 510(k)-cleared versus CE-marked versus non-certified) creates the primary spread between premium and standard scanner tiers. Three-tier pricing structure across FDA-cleared, CE-marked, and research-grade levels reflects validation investment differentials. Cost compression in the mid-tier segment is intensifying because hospital procurement committees unbundle after-sales service contracts from hardware purchases. Diagnostic laboratories exhibit highest price sensitivity, while academic medical centers prioritize AI integration capabilities over unit cost.
Supply Chain Analysis
Tariff exposure between Japan and the United States dominates supply chain risk planning for scanner hardware manufacturers. Manufacturing concentrates in Japan, Germany, and the United States for precision optics and sensor assembly. Component dependencies include high-resolution CMOS sensors, precision motion control systems, and specialized LED illumination modules. Single-source vulnerability persists for sub-2-micron resolution sensors from Hamamatsu and Sony fabrication facilities. Distribution runs through authorized medical device distributors with FDA establishment registration requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telepathology represents a high-growth disruption anchored by FDA clearance pathway maturation for whole slide imaging devices and HIPAA-compliant cloud architecture proliferation.
For Market Incumbents: Harden enterprise imaging ecosystem lock-in by embedding AI-assisted screening tools that increase switching costs for hospital network customers. Deepen backward integration into high-resolution sensor supply through strategic partnerships with Japanese precision optics manufacturers. Defend against cloud-native platform entrants by accelerating subscription-based scanner leasing programs for mid-sized diagnostic laboratories. For New Entrants and Emerging Players: Latin American specialist pathologist shortages present the most penetrable geographic entry point, particularly Brazil and Mexico where disease burden far exceeds diagnostic capacity. Target remote consultation service models that bypass capital-intensive hardware manufacturing. Pursue CDSCO registration pathways for Indian market access where diagnostic laboratory digitization lags North American adoption curves by several years. For Investors and Strategic Acquirers: Long-term, this sits as a healthcare infrastructure play because reimbursement parity determinations for remote pathology services will determine deployment velocity across consolidated health systems. Acquisition targets should prioritize cloud-native platform vendors with established FDA submission track records and hospital network pilot contracts. Monitor CMS reimbursement policy signals as the critical inflection indicator for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Premarket notification clearance enables diagnostic reimbursement parity with conventional microscopy in United States hospital networks. |
| Hospital System Partnership | Enterprise imaging ecosystem contracts with Mayo Clinic or Cleveland Clinic anchor multi-site deployment rights across integrated delivery networks. |
| Cloud-Native Platform Integration | Scalable subscription architectures compress capital barriers for mid-sized diagnostic laboratories shifting from on-premise storage. |
| AI Algorithm Companion Development | Computational pathology tools for prostate cancer and lymphoma screening reduce manual slide review burden and accelerate turnaround times. |
| Reimbursement Strategy Alignment | Coverage parity negotiations with CMS determine commercial deployment velocity across United States health systems. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with digital pathology platform executives, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, CMS reimbursement determinations, hospital procurement databases, and academic medical center pilot study disclosures. Bottom-up scanner shipment estimates triangulated against top-down health system IT expenditure surveys.
Forecast inputs include technology deployment models, laboratory size tiers, geographic regulatory clusters, and AI integration maturity levels across the projection horizon. CAGRs derive from segment-level growth rate reconciliation with macro healthcare IT expenditure trends. Modeled variables incorporate pathologist workforce shortage severity indices and cloud infrastructure penetration rates by state.
The forecast holds incumbent behavior within observed patterns; aggressive pricing moves by cloud-native entrants or accelerated FDA clearance timelines for AI-assisted diagnostics would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Middle East and Africa Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Global Complete Blood Count Device Market
Medical Diagnostics
Fluid Biopsy Market
Medical Diagnostics
Global HLA Typing for Transplant Market
Medical Diagnostics
Protein Sequencing Market
Medical Diagnostics
Global Circulating Tumor Cells Market
Medical Diagnostics
Blood Platelet Market
Medical Diagnostics
Real-Time PCR, Digital PCR, and End-Point PCR Market
Medical Diagnostics
Artificial Intelligence (AI) in Medical Diagnostics Market
Medical Diagnostics
Dosimetry Market
Medical Diagnostics
Medical Marker Bands Market
Medical Diagnostics
Asia-Pacific Flow Cytometry Market
Medical Diagnostics
Flow Cytometry Market
Medical Diagnostics
Global Hydrophobic Interaction Chromatography Market
Medical Diagnostics
North America Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Carrier Screening Market