
 US and Europe Digital Pathology Market | 2026-2036
US and Europe Digital Pathology Market Size, Share, and Industry Trends Forecast 2026-2036
US and Europe Digital Pathology Market Insights
Multi-source procurement of whole slide imaging hardware and image analysis software is recalibrating vendor relationships across hospital networks. Danaher Corporation through Leica Biosystems leverages its histology instrument installed base to bundle digital pathology subscriptions. Koninklijke Philips N.V. competes on integrated enterprise imaging architectures that extend from radiology into pathology workflows. Hamamatsu Photonics anchors its position through proprietary scanner sensor manufacturing that controls core component supply.
Digital pathology encompasses the acquisition, management, and interpretation of pathology information in digital format, with whole slide imaging systems typically scanning glass slides at 20x or 40x magnification to produce multi-gigapixel files for remote review and computational analysis. Its primary commercial purpose is to enable telepathology consultation, AI-assisted diagnostic workflows, and centralized quality assurance across distributed laboratory networks. Whole slide imaging currently leads technology adoption in academic and large commercial laboratories where case volumes justify capital investment, while cloud-based solutions represent the fastest-expanding delivery model as laboratories seek to defer infrastructure expenditure. Among end users, diagnostic laboratories concentrate margin pools through high-throughput scanning contracts, whereas pharmaceutical companies represent an emerging demand segment for clinical trial endpoint adjudication.
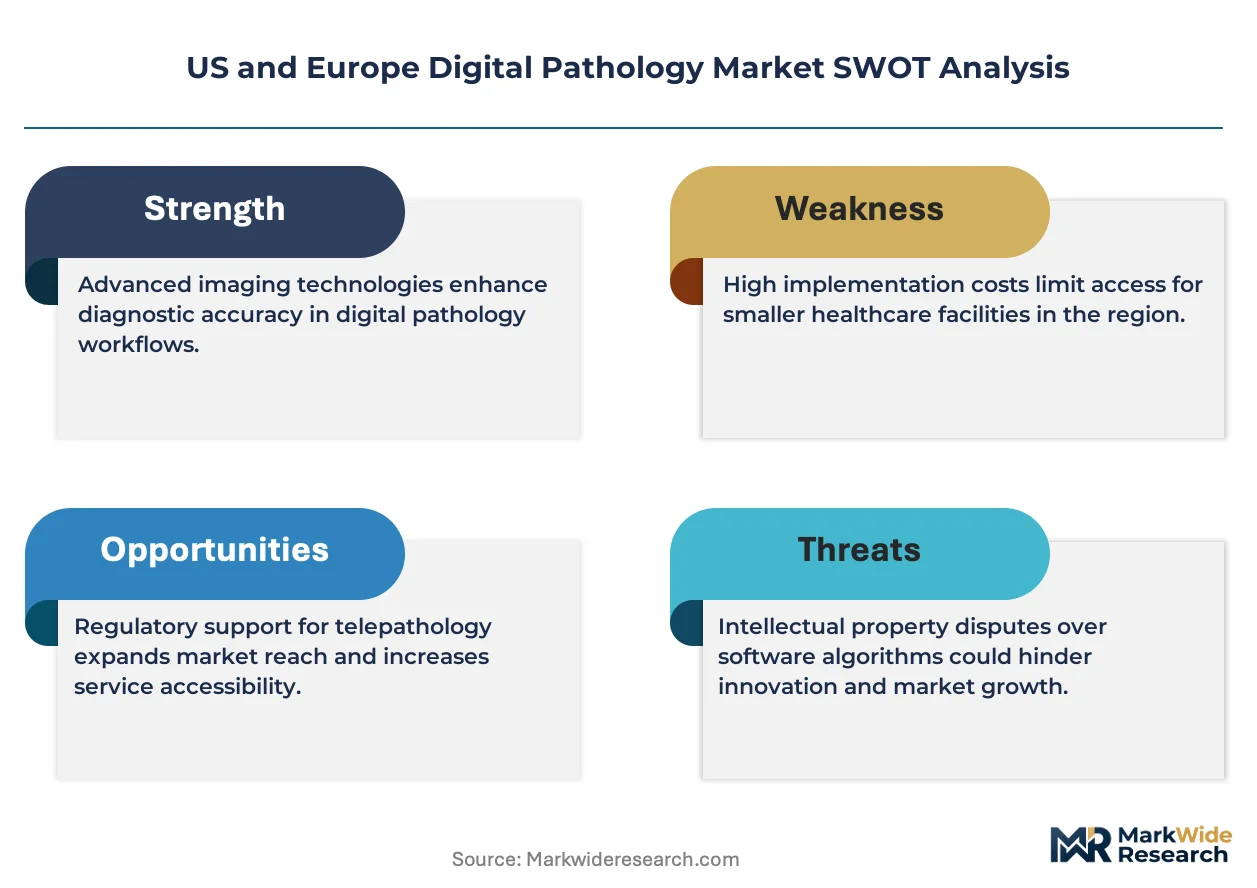
FDA 510(k) clearance requirements and the EU MDR's Class IIa classification for diagnostic software shape product development timelines and market access costs on both sides of the Atlantic. HIPAA in the United States and GDPR in Europe impose distinct data governance obligations on cloud-hosted pathology platforms, influencing vendor architecture decisions and customer procurement criteria. Stakeholders must monitor evolving FDA guidance on artificial learning-enabled diagnostic devices and the European Commission's AI Act risk classification for medical image analysis software.
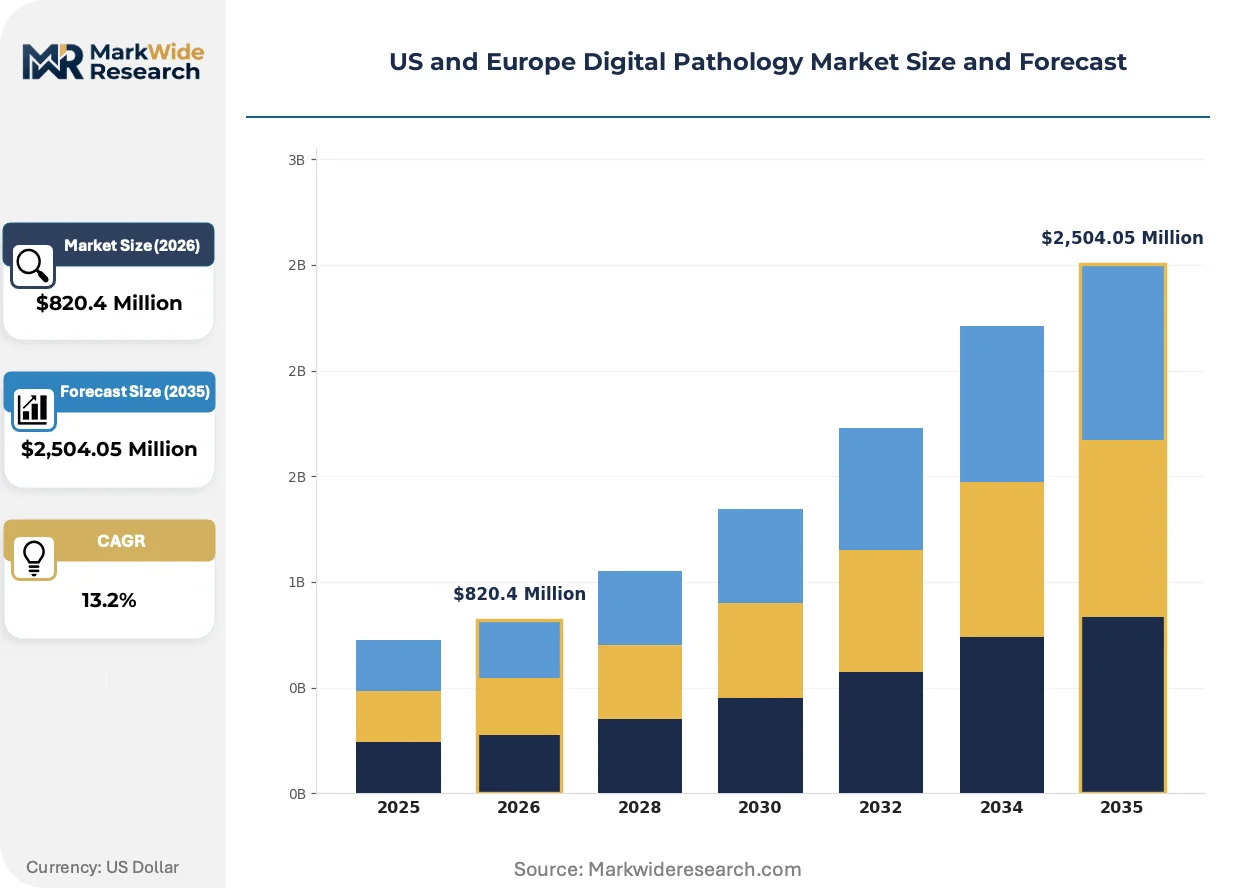
Market Dynamics
Consolidation of laboratory networks across the United States and Germany is compressing vendor negotiation cycles and forcing platform standardization decisions that lock in procurement patterns for multi-year horizons.
Growth Catalysts
- FDA 510(k) clearance streamlining:The FDA's evolving guidance on whole slide imaging devices accelerates market entry timelines for diagnostic software developers seeking US commercialization.
- Academic medical center expansion:Teaching hospitals in the United States are deploying remote pathology consultation infrastructure to extend specialist coverage across satellite campuses.
- EU MDR Class IIa harmonization:CE marking convergence under the Medical Device Regulation reduces duplicate certification burdens for vendors accessing European diagnostic laboratories.
Market Restraints
- Scanner sensor supply concentration:Proprietary CMOS sensor manufacturing remains concentrated among Japanese optical component suppliers, creating input bottlenecks for hardware vendors.
- GDPR compliance architecture costs:European data localization requirements impose redundant infrastructure expenditure on cloud-hosted pathology platforms serving multiple member states.
- Glass slide digitization throughput limits:Current whole slide imaging speeds create processing backlogs in high-volume anatomic pathology laboratories exceeding five hundred cases daily.
Strategic Opportunities
- Pharmaceutical clinical trial adjudication:Central pathology review for oncology endpoint validation represents an emerging demand segment with premium pricing tolerance.
- Cloud-native deployment models:Subscription-based image management is displacing capital-intensive on-premise storage in mid-sized European hospital networks.
- HIPAA-aligned interstate telepathology:Cross-border diagnostic licensing reciprocity between select US states enables specialist pool expansion without physical relocation.
Industry Challenges
- Computational pathology expertise scarcity:Dual-trained pathologists capable of validating AI-assisted diagnostic algorithms command compensation premiums that strain laboratory staffing budgets.
- Legacy LIS integration complexity:Proprietary data formats from existing laboratory information systems resist seamless interoperability with modern whole slide imaging platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US and Europe Digital Pathology Market |
| Market Size in 2026 | $820.4 Million |
| Market Size in 2035 | $2,504.05 Million |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Whole Slide Imaging, Virtual Microscopy, Image Analysis Software, Cloud-Based Solutions End User: Hospitals, Diagnostic Laboratories, Research Institutes, Pharmaceutical Companies Application: Telepathology, Education, Diagnosis, Clinical Trials Delivery Model: On-Premise, Cloud-Based, Hybrid, Software as a Service |
| Companies Covered | Danaher Corporation (Leica Biosystems), Koninklijke Philips N.V., F. Hoffmann-La Roche Ltd., Hamamatsu Photonics, 3DHISTECH, Inspirata, Inc., Visiopharm A/S, Epredia, Olympus Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US and Europe Digital Pathology Market Trends and Innovations
Artificial intelligence integration is restructuring diagnostic workflows across both sides of the Atlantic, with regulatory frameworks racing to catch up to deployment velocity in clinical settings.
Edge computing architectures for whole slide image analysis are decentralizing computational workloads from centralized data centers to local laboratory servers. Regional hospital networks in Germany are piloting on-premise GPU clusters to reduce latency for real-time diagnostic assistance. This distributed processing model is decentralizing vendor control over algorithm update cycles and data governance protocols.
The EU AI Act's risk classification framework for medical image analysis software is recalibrating product development priorities for vendors seeking European market access. High-risk system designations trigger conformity assessment obligations that extend software validation timelines by twelve to eighteen months. Diagnostic laboratories in France and the Netherlands are prioritizing procurement of CE-marked devices with established algorithmic transparency documentation.
Subscription-based service contracts are displacing perpetual licensing for image analysis software in United States academic medical centers. Hospital procurement departments favor operational expenditure classification that preserves capital budget flexibility for hardware refresh cycles. This financing preference is most pronounced in consolidated laboratory networks across the Northeastern and Midwestern United States.
US and Europe Digital Pathology Market Segmentation
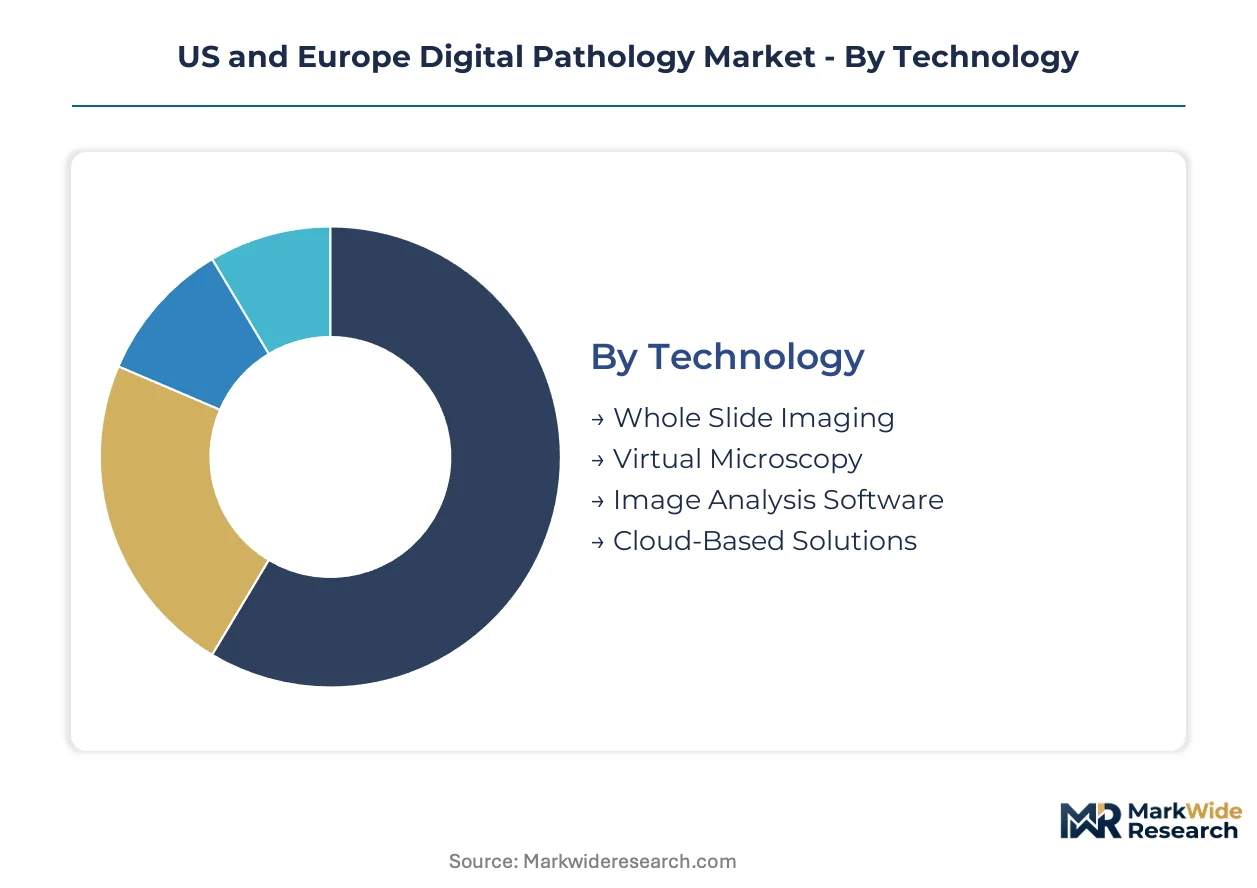
Segmentation in digital pathology reveals how procurement decisions split between capital-intensive hardware investments and recurring software subscriptions. Understanding these divides illuminates where vendor margins concentrate and where cloud-native challengers can displace incumbents.
Technology:
Integration depth varies sharply: whole slide imaging operates as standalone capital equipment, while image analysis software embeds into broader enterprise imaging architectures.
- Whole Slide Imaging:High-resolution scanners capture glass slides at 20x or 40x magnification, producing multi-gigapixel files. Demand clusters in academic medical centers across Germany and the United States where case volumes justify seven-figure capital deployments and dedicated IT infrastructure.
- Image Analysis Software:Computational algorithms for quantitative biomarker assessment and tissue classification run on local servers or cloud instances. Pharmaceutical companies in Switzerland and the Netherlands are driving adoption for oncology clinical trial endpoint adjudication, paying premium per-slide fees for validated algorithms.
- Virtual Microscopy:Lower-magnification remote viewing systems for education and consultation.
- Cloud-Based Solutions:Subscription image management and storage deferring on-premise infrastructure.
Whole slide imaging leads volumes today; cloud-based solutions are gaining share fastest.
End User:
Customer type determines pricing power and contract structure, with consolidated laboratory networks extracting multi-year commitments against fragmented hospital procurement.
- Diagnostic Laboratories:High-throughput anatomic pathology operations processing five hundred-plus daily cases. Integrated networks in the United States—particularly across the Northeast and Midwest—are standardizing on single-vendor platforms to lock in volume discounts and streamline quality assurance.
- Pharmaceutical Companies:Central pathology review for clinical trial endpoints demands algorithmic traceability and regulatory documentation. Sites in France and Germany under EMA jurisdiction prioritize CE-marked devices with established conformity assessment under EU MDR Class IIa.
- Hospitals:Mid-sized European hospital networks favor operational expenditure models.
- Research Institutes:Academic users driving open-source algorithm development and validation datasets.
Diagnostic laboratories dominate revenue concentration; pharmaceutical companies show the steepest expansion trajectory.
Application:
Use case maturity spans from established telepathology reimbursement to experimental AI-assisted diagnosis awaiting regulatory clarity.
- Telepathology:Remote specialist consultation for underserved regions. Cross-border licensing reciprocity between select US states enables specialist pool expansion without physical relocation, particularly benefiting satellite campuses in rural Texas and Arizona.
- Diagnosis:Primary diagnostic workflows incorporating AI-assisted screening. FDA 510(k) clearance pathways for algorithm-enabled devices are accelerating, though EU AI Act high-risk designations extend European validation timelines.
- Education:Digital slide repositories replacing physical teaching sets.
- Clinical Trials:Endpoint adjudication with audit trails for regulatory submission.
Telepathology anchors current deployment; diagnosis is climbing the fastest as regulatory frameworks mature.
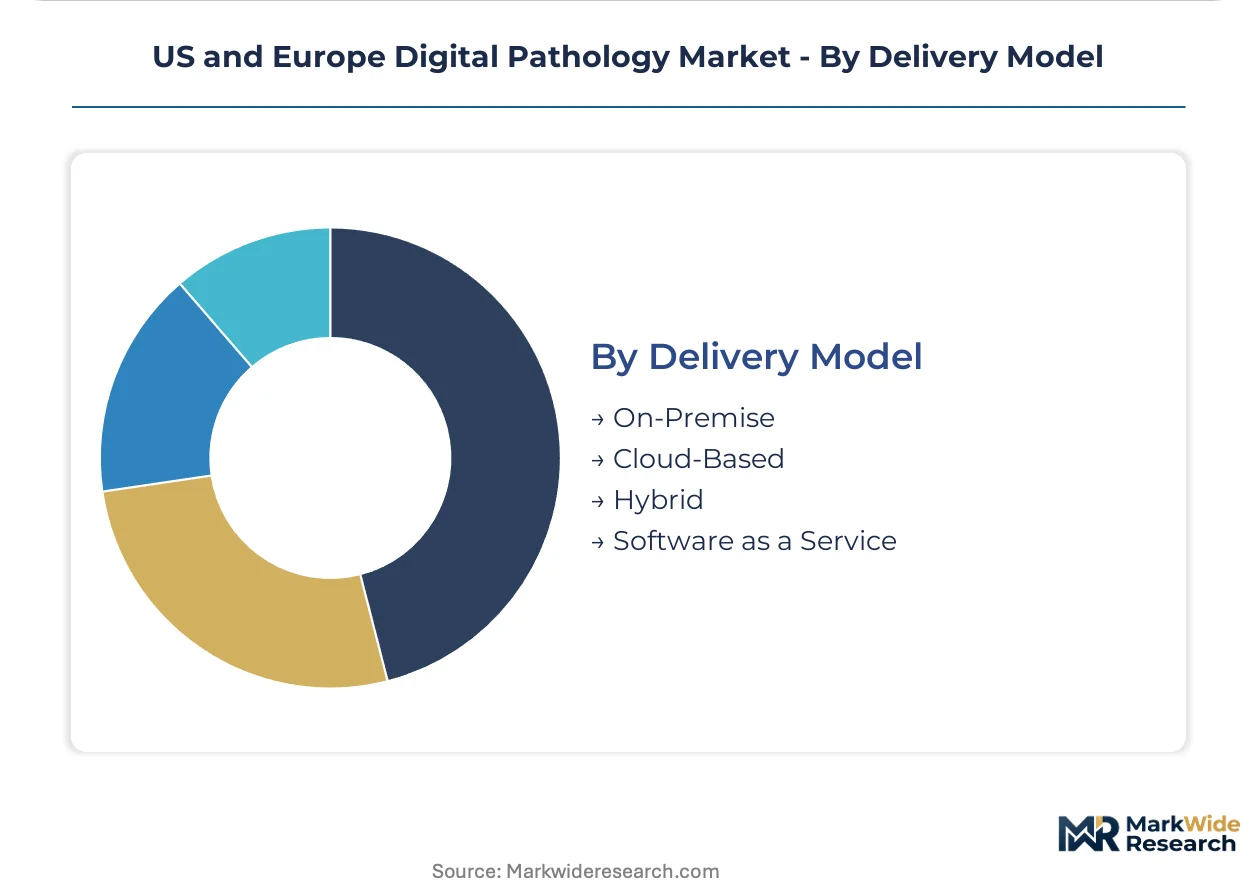
Delivery Model:
Financing preference is bifurcating procurement between capital budget preservation and infrastructure control.
- Software as a Service:Per-case or per-pathologist subscription pricing. United States academic medical centers favor this operational expenditure classification, preserving capital flexibility for hardware refresh cycles in consolidated networks.
- Cloud-Based:Hosted image management with vendor-managed infrastructure. GDPR data localization requirements impose redundant expenditure on platforms serving multiple European member states, favoring regional cloud instances.
- On-Premise:Full infrastructure ownership with maximum data governance control.
- Hybrid:Local scanning with cloud archival for long-term storage.
Software as a service leads new contract signings; hybrid deployments are expanding most quickly among risk-averse European laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge corridor anchors North American digital pathology innovation through dense academic medical center clustering and FDA-cleared device development pipelines.
United States
Integrated laboratory networks across the Northeast and Midwest standardize on single-vendor whole slide imaging platforms to extract volume discounts. FDA 510(k) clearance pathways for AI-enabled diagnostic devices accelerate commercial timelines for software developers. The Texas Medical Center in Houston deploys remote pathology consultation infrastructure to extend specialist coverage across rural satellite campuses in Arizona and New Mexico.
Germany
Baden-Württemberg's precision manufacturing base supplies optical scanner components to European hardware vendors. EU MDR Class IIa conformity assessment requirements under CE marking harmonize certification burdens across member states. The Rhine-Ruhr metropolitan region consolidates diagnostic laboratory procurement through network standardization decisions that lock in multi-year vendor commitments.
United Kingdom
NHS England's pathology modernization program drives centralized procurement of cloud-hosted image management systems. GDPR data localization requirements impose redundant infrastructure expenditure on platforms serving multiple European jurisdictions. The Cambridge-London corridor concentrates AI algorithm development through university-hospital partnerships and venture-backed spinouts.
France
Paris-region academic hospitals prioritize CE-marked devices with established algorithmic transparency documentation under EU AI Act risk classification. ANSM oversight of medical device software shapes validation timelines for diagnostic algorithm developers. The Lyon-Grenoble axis hosts pharmaceutical central pathology review facilities for oncology clinical trial endpoint adjudication.
Netherlands
Amsterdam-Rotterdam hospital networks favor operational expenditure models for image analysis software subscriptions. EMA proximity in Amsterdam influences regulatory documentation standards for clinical trial pathology services. The Eindhoven region's semiconductor equipment expertise feeds into edge computing architectures for on-premise GPU cluster deployment.
US and Europe Digital Pathology Market Competitive Landscape
Global majors compete with regional champions across integrated imaging architectures versus specialized scanner manufacturing. The vendor base stratifies into three tiers: diversified life science conglomerates bundling histology instruments with digital subscriptions, pure-play imaging specialists controlling proprietary sensor supply, and cloud-native software vendors displacing on-premise storage. Consolidation pressures intensify through multi-year laboratory network procurement lock-ins and cross-border telepathology licensing reciprocity.
Among diversified instrument manufacturers, Danaher Corporation through Leica Biosystems and Koninklijke Philips N.V. exemplify platform bundling strategies that leverage installed base relationships. Hamamatsu Photonics occupies a position within the optical component specialist tier through captive CMOS sensor manufacturing. These three anchors illustrate how supply-side concentration in core scanner components shapes competitive dynamics across both sides of the Atlantic.
| Leading Market Players |
|---|
| Danaher Corporation (Leica Biosystems) |
| Koninklijke Philips N.V. |
| F. Hoffmann-La Roche Ltd. |
| Hamamatsu Photonics |
| 3DHISTECH |
| Inspirata, Inc. |
| Visiopharm A/S |
| Epredia |
| Olympus Corporation |
| Others |
Pricing and Supply Chain Analysis
Proprietary CMOS sensor manufacturing costs in Japan cascade through hardware vendor pricing tiers, with scanner component scarcity elevating capital equipment premiums for academic medical centers while subscription-based software models absorb margin compression through operational expenditure reclassification.
Pricing Analysis
Input-cost pass-through from concentrated Japanese optical component suppliers elevates whole slide imaging hardware premiums, particularly for 40x magnification systems with specialized sensor arrays. Three-tier pricing structure separates FDA-cleared diagnostic platforms from CE-marked research-grade instruments and uncertified educational systems. Pricing pressure stems from consolidated laboratory networks extracting multi-year volume commitments against fragmented hospital procurement. Pharmaceutical companies show least price sensitivity for clinical trial adjudication services, while mid-sized European hospitals resist capital outlays.
Supply Chain Analysis
Reverse-logistics flows for scanner refurbishment and sensor replacement concentrate service operations in Germany and the Netherlands, extending hardware lifecycle value for consolidated laboratory networks. Manufacturing draws from Japanese CMOS sensor fabrication, German precision optics machining, and United States cloud infrastructure hosting. Single-source vulnerability in proprietary sensor supply creates bottleneck exposure for hardware vendors. Distribution runs through integrated laboratory network procurement committees and academic medical center IT governance boards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US and Europe Digital Pathology Market functions as a stable compounder, with regulatory clearance requirements creating durable competitive moats that sustain incumbent positioning across multi-year contract horizons.
For Market Incumbents: Lock in multi-year platform standardization decisions across consolidated laboratory networks before EU AI Act high-risk designations extend validation timelines for algorithm-enabled competitors. Deepen backward integration into cloud infrastructure hosting to capture recurring subscription margins from SaaS displacement of on-premise storage. Defend against cloud-native challengers through bundled histology instrument and digital pathology subscriptions that raise switching costs. For New Entrants and Emerging Players: Pharmaceutical central pathology review services represent the most penetrable white-space target, with premium pricing tolerance for validated algorithmic traceability and regulatory documentation. Target mid-sized European hospital networks seeking operational expenditure classification for image analysis software. Pursue partnership-based go-to-market models with academic medical center IT departments to bypass capital budget gatekeepers. For Investors and Strategic Acquirers: Consolidation pressure builds where laboratory network procurement standardization eliminates second-source vendor viability. The market sustains long-term compounding through AI-assisted diagnostic workflow penetration requiring continuous algorithm validation investment. Acquisition targets include cloud-native image analysis software vendors with established CE marking under EU MDR Class IIa. Monitor FDA guidance evolution on artificial learning-enabled devices as inflection signal for software valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class IIa conformity assessment accelerates European laboratory network access. |
| Hospital System Partnership | Integrated network procurement committees lock in multi-year platform standardization. |
| Software Companion Development | AI-assisted diagnostic algorithms command premium per-slide fees in clinical trials. |
| Backward Integration into Cloud | Vendor-managed infrastructure captures recurring subscription revenue from SaaS displacement. |
| Reimbursement Strategy | Telepathology consultation codes enable specialist coverage expansion across rural satellite campuses. |
Research Methodology
Direct dialogue with pathology laboratory directors, hospital procurement officers, biomedical engineers, and GPO contracts managers grounded qualitative findings in operational realities, cross-referenced with FDA 510(k) filings, EMA submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up scanner deployment counts triangulated against top-down market sizing from vendor revenue disclosures.
Segment-level projections across technology, end user, application, and delivery model dimensions fed into analytical framework outputs across the analysis window. CAGRs derived from regression against historical adoption curves for comparable diagnostic imaging modalities. Forecast inputs incorporated EU AI Act implementation timelines and FDA guidance evolution on algorithm-enabled devices.
Revisions become necessary when regulatory classification shifts, supply chain disruptions in Japanese sensor manufacturing, or laboratory network consolidation accelerations materialize. Practitioners should monitor FDA artificial learning-enabled device guidance and EU MDR notified body capacity constraints for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Single-Photon Emission Computed Tomography (SPECT) Market
Medical Imaging
Germany Digital Pathology Market
Medical Imaging
PACS and RIS Market
Medical Imaging
Dental X-Ray Market
Medical Imaging
Next Generation Ultrasound Systems Market
Medical Imaging
Medical Imaging Software Market
Medical Imaging
Spain Diagnostic Imaging Equipment Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Coils Market
Medical Imaging
Global Medical Imaging Reagents Market
Medical Imaging
AI-Assisted Radiology Market
Medical Imaging
Breast Imaging Market
Medical Imaging
X-Ray Flat Panel Detectors Market
Medical Imaging
Orthopedic Imaging Market
Medical Imaging
US Interventional Radiology Market
Medical Imaging
Surgical Imaging Robots Market
Medical Imaging
Pediatric Imaging Market