
 Biomarker Clinical Phase Outsourcing Services Market | 2026-2036
Biomarker Clinical Phase Outsourcing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Biomarker Clinical Phase Outsourcing Services Market Analytics
The biomarker outsourcing landscape is restructuring around a sharp split between premium integrated platforms and commodity assay shops. Laboratory Corporation of America Holdings leverages its central laboratory network to anchor complex biomarker programs across Phase II and III trials. Charles River Laboratories International differentiates through in vivo oncology models paired with biomarker readouts. Thermo Fisher Scientific dominates analytical instrument and consumable supply chains that underpin outsourced biomarker workflows.
Biomarker clinical phase outsourcing services encompass the transfer of biomarker discovery, analytical validation, and patient stratification activities to third-party providers during human drug trials, typically requiring CLIA-certified laboratories, GLP-compliant bioanalytical methods, and chain-of-custody protocols for biospecimen handling. Genomics and bioinformatics now capture expanding margin pools as next-generation sequencing costs decline and real-world evidence requirements intensify. Oncology applications sustain the largest revenue share within the application dimension, while proteomics competes for share in immuno-oncology combination trials requiring multiplexed protein profiling.
FDA biomarker qualification guidelines, EMA's ICH E16 implementation, and ISO 15189 medical laboratory standards collectively shape vendor selection criteria and contract scope for sponsors. HIPAA and GDPR data governance requirements constrain cross-border biomarker data flows, pushing regional laboratory buildouts. Sponsors must weigh captive analytical investments against outsourcing flexibility as regulatory scrutiny of biomarker-driven trial designs intensifies.
Market Dynamics
Biomarker outsourcing contracts are bifurcating between high-complexity integrated programs requiring CLIA/GLP dual certification and commoditized single-analyte testing, forcing vendors to choose margin structure over volume scale.
Growth Catalysts
- FDA Biomarker Qualification Program:The agency's structured qualification pathway accelerates sponsor willingness to embed biomarker endpoints in Phase II/III protocols, expanding validation outsourcing scope.
- Immuno-oncology pipeline expansion:Combination therapy trials require multiplexed protein and genomic profiling that exceeds in-house CRO capabilities, pulling work toward specialized biomarker shops.
- Next-generation sequencing cost curves:Plummeting NGS per-sample economics enable comprehensive genomic profiling in mid-sized trials previously limited to single-gene assays.
Market Restraints
- Biospecimen logistics concentration:Cold-chain integrity requirements and chain-of-custody protocols limit viable laboratory sites to established hubs in Massachusetts, Basel, and Singapore, creating capacity bottlenecks.
- GLP method validation timelines:FDA and EMA divergence on bioanalytical method acceptance criteria extends validation cycles by four to six months, compressing program margins.
- Data localization mandates:GDPR Article 44 restrictions and China's data security law fragment biomarker databases across jurisdictional silos, duplicating infrastructure investment.
Strategic Opportunities
- Real-world evidence integration:FDA's guidance on RWE-supported regulatory submissions creates demand for prospective biomarker collection in observational cohorts, opening adjacent service lines.
- Companion diagnostic co-development:EMA's parallel scientific advice pathway and FDA's CDx pilot program incentivize synchronized drug-diagnostic trial designs requiring integrated biomarker-CRO partnerships.
- AI-enabled biomarker discovery:Machine learning convergence with spatial transcriptomics is compressing target identification timelines, enabling service providers to offer discovery-through-validation bundled pricing.
Industry Challenges
- Bioinformatics talent scarcity:Computational biology PhDs with clinical trial experience command compensation premiums that erode project-level profitability at mid-tier vendors.
- ISO 15189 accreditation timelines:Medical laboratory certification processes stretch twelve to eighteen months in key European markets, delaying market entry for emerging competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biomarker Clinical Phase Outsourcing Services Market |
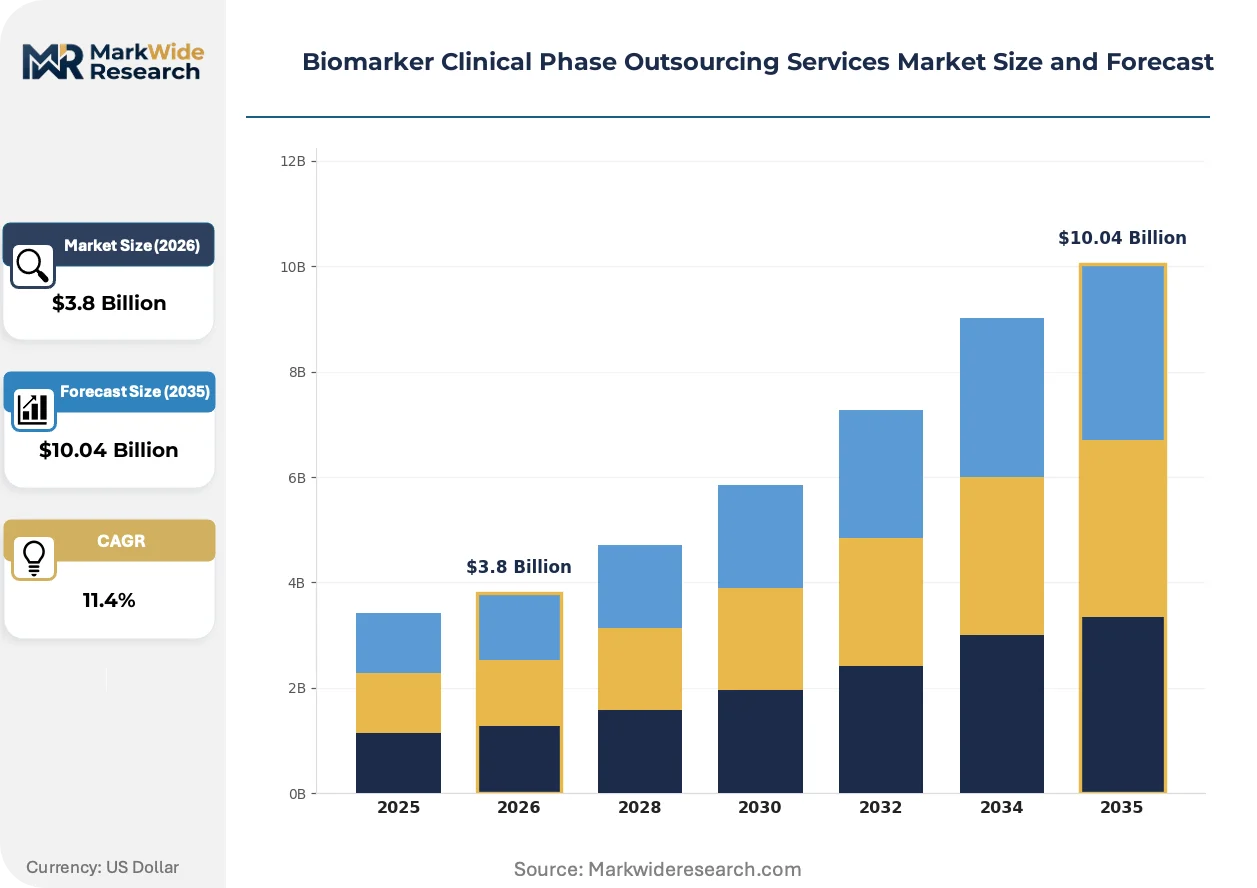
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Assay Development, Sample Collection, Data Analysis, Project Management Technology: Genomics, Proteomics, Metabolomics, Bioinformatics Application: Oncology, Neurology, Immunology, Cardiovascular End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Contract Research Organizations |
| Companies Covered | Laboratory Corporation of America Holdings, Charles River Laboratories International, Parexel International Corporation, Thermo Fisher Scientific, ICON plc, Eurofins Scientific, WuXi AppTec, Syneos Health, QIAGEN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biomarker Clinical Phase Outsourcing Services Market Evolving Landscape
Digital biomarker modalities and spatial omics platforms are restructuring competitive advantage around data integration depth rather than analytical throughput alone. Vendors now differentiate through proprietary algorithm development, not just instrument access.
Spatial transcriptomics is rewriting how sponsors map tumor microenvironment heterogeneity. Oncology CROs are adopting multiplexed imaging platforms at accelerating pace to support immuno-oncology combination trials. The technology is compressing traditional immunohistochemistry workflows into single-slide multi-analyte readouts that reduce both tissue consumption and analytical variability.
EMA's ICH E16 biomarker qualification implementation is harmonizing genomic context-of-use submissions across EU member states. This regulatory convergence reduces duplicate validation studies for pan-European trials. Sponsors are restructuring outsourcing contracts to front-load EMA scientific advice engagement rather than sequential national filings.
Pharmaceutical procurement teams are unbundling biomarker discovery from clinical testing services, creating separate vendor pools for exploratory versus validated assay work. This bifurcation is fragmenting incumbent full-service CRO relationships. The pattern is most pronounced among mid-cap biotech sponsors in the Boston-Cambridge cluster seeking specialized genomic platform access.
Biomarker Clinical Phase Outsourcing Services Market Segmentation
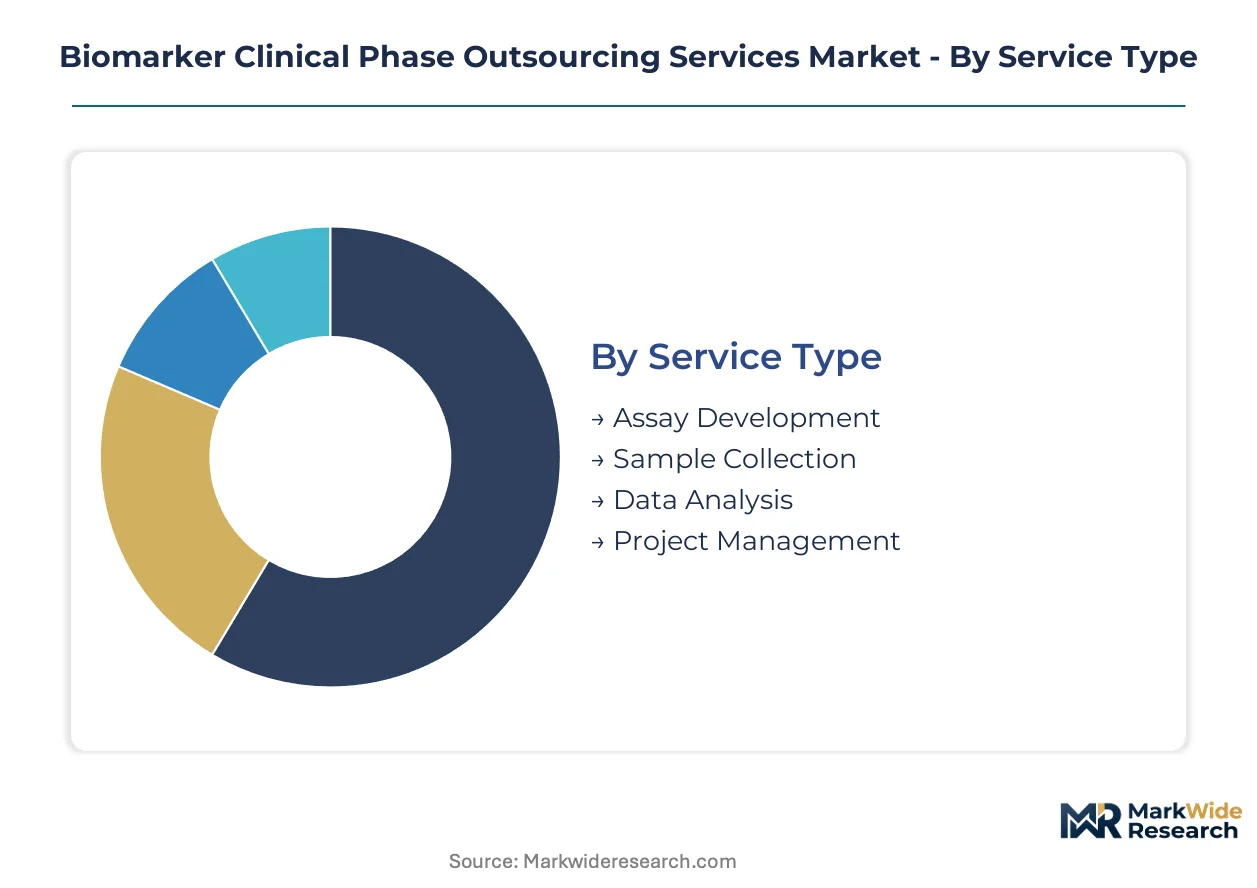
Biomarker outsourcing contracts vary sharply in regulatory burden, technical complexity, and margin structure across service dimensions. Sponsors map vendor selection criteria to specific trial phases, with CLIA/GLP dual certification requirements filtering eligible providers differently for each segment category.
Service Type:
CLIA certification governs clinical diagnostic testing while GLP compliance anchors non-clinical bioanalytical work, creating divergent vendor qualification pathways across service lines.
- Assay Development:Analytical method creation for novel biomarker endpoints demands GLP-compliant validation protocols and FDA bioanalytical method guidance adherence. Massachusetts and California laboratory clusters concentrate specialized immunoassay development capacity for Phase II/III oncology trials. Method transfer timelines stretch validation cycles by four to six months when FDA and EMA acceptance criteria diverge.
- Sample Collection:Biospecimen acquisition requires chain-of-custody protocols, cold-chain integrity maintenance, and HIPAA-compliant handling procedures. Capacity bottlenecks emerge at established hubs in Massachusetts, Basel, and Singapore where cryogenic logistics infrastructure concentrates. ISO 15189 medical laboratory standards constrain site selection for multi-regional trials.
- Data Analysis:Computational biology workflows integrate genomic, proteomic, and clinical datasets for patient stratification algorithms.
- Project Management:Cross-functional coordination spans regulatory submission timelines, vendor oversight, and sponsor communication protocols.
Assay Development sits at the top of the volume ranking, with Data Analysis climbing the fastest.
Technology:
Platform selection dictates capital intensity, consumable lock-in, and bioinformatics talent requirements for service providers.
- Genomics:Next-generation sequencing and PCR-based profiling enable comprehensive genomic characterization of tumor heterogeneity and pharmacogenomic variation. NGS per-sample economics have collapsed sufficiently to support mid-sized trial designs previously limited to single-gene assays. Real-world evidence requirements intensify demand for prospective genomic data collection in observational cohorts.
- Proteomics:Mass spectrometry and multiplexed immunoassay platforms quantify protein biomarker panels for immuno-oncology combination therapy monitoring. Spatial proteomics workflows compress traditional immunohistochemistry into single-slide multi-analyte readouts. Basel-region CROs anchor specialized protein quantification capacity for European trial networks.
- Metabolomics:Small-molecule profiling captures pharmacodynamic responses and toxicity biomarkers through mass spectrometry-based platforms.
- Bioinformatics:Computational pipelines for variant calling, pathway analysis, and machine learning model development require specialized PhD-level talent commanding compensation premiums.
Genomics captures the largest revenue share, with Bioinformatics expanding most quickly as spatial omics data volumes explode.
Application:
Therapeutic area specialization determines biomarker modality mix, regulatory precedent availability, and companion diagnostic co-development pathways.
- Oncology:Tumor profiling, circulating tumor DNA monitoring, and immune biomarker quantification dominate biomarker outsourcing volume. FDA's biomarker qualification program and EMA's parallel scientific advice pathway accelerate structured context-of-use submissions for genomic and protein-based endpoints. Immuno-oncology combination trials pull work toward specialized biomarker shops with multiplexed imaging platform access.
- Neurology:Cerebrospinal fluid biomarkers, neuroimaging correlates, and digital biomarker modalities address blood-brain barrier penetration and target engagement challenges. Biomarker-guided patient stratification remains less mature than oncology, with fewer qualified endpoints and longer validation timelines.
- Immunology:Cytokine profiling, immune cell phenotyping, and autoantibody quantification support inflammatory disease and autoimmune therapeutic development.
- Cardiovascular:Cardiac troponin, natriuretic peptide, and emerging proteomic risk signatures address residual cardiovascular risk and heart failure phenotyping.
Oncology sits at the top of the volume ranking, with Neurology climbing the fastest as amyloid and tau biomarker qualifications mature.
End User:
Customer scale and internal capability depth shape outsourcing scope, with large pharmas unbundling services while mid-cap biotechs seek integrated partnerships.
- Pharmaceutical Companies:Global sponsors drive adoption of biomarker-guided trial designs across Phase II and III pipelines, with procurement teams increasingly separating exploratory discovery from validated clinical testing vendor pools. Boston-Cambridge cluster biopharmas fragment incumbent full-service CRO relationships to access specialized genomic platforms. Internal analytical investments compete against outsourcing flexibility as regulatory scrutiny intensifies.
- Biotechnology Firms:Resource-constrained sponsors rely heavily on external biomarker expertise, bundling discovery-through-validation services under single-provider contracts. AI-enabled biomarker discovery offerings attract venture-backed companies seeking compressed target identification timelines.
- Academic Institutions:Translational research programs and investigator-initiated trials access CLIA-certified laboratory capacity through fee-for-service arrangements.
- Contract Research Organizations:Full-service CROs subcontract specialized biomarker work to niche analytical providers while building internal genomics and bioinformatics capabilities.
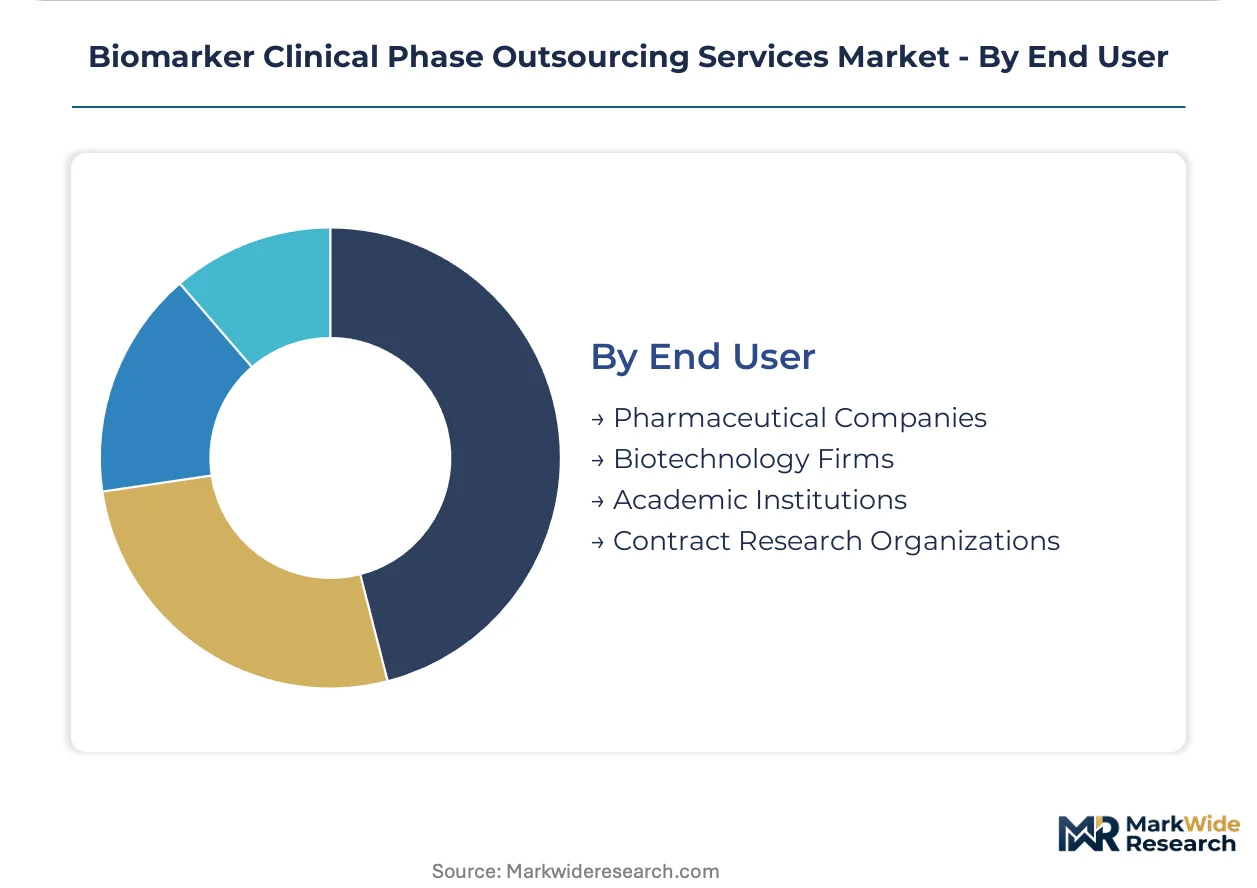
Pharmaceutical Companies sit at the top of the volume ranking, with Biotechnology Firms climbing the fastest as immuno-oncology pipeline expansion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bioinformatics PhDs with clinical trial experience cluster in Massachusetts, Basel, and Singapore, anchoring global biomarker outsourcing capacity. These talent concentrations shape where sponsors contract analytical validation work and build regional laboratory networks.
United States
FDA's biomarker qualification program accelerates sponsor embedding of biomarker endpoints in Phase II/III protocols. HIPAA data governance requirements constrain cross-border biomarker data flows, pushing regional laboratory buildouts. The Boston-Cambridge cluster concentrates specialized genomic platform access, with mid-cap biotechs fragmenting incumbent full-service CRO relationships to reach this capacity.
Switzerland
Swissmedic harmonizes with EMA's parallel scientific advice pathway for synchronized drug-diagnostic trial designs. Basel-region CROs anchor specialized protein quantification capacity for European trial networks. Cold-chain integrity requirements and chain-of-custody protocols reinforce this hub's role in pan-European biomarker logistics.
Germany
ISO 15189 medical laboratory standards stretch certification timelines to twelve to eighteen months, delaying market entry for emerging competitors. EMA's ICH E16 implementation reduces duplicate validation studies for pan-European trials. Munich and Heidelberg laboratories concentrate GLP-compliant bioanalytical method development for oncology applications.
China
Data security law fragments biomarker databases across jurisdictional silos, duplicating infrastructure investment for multinational sponsors. NMPA bioanalytical method acceptance criteria diverge from FDA standards, extending validation cycles. Shanghai and Suzhou clusters build CLIA-certified capacity to serve domestic biotech pipeline expansion.
Singapore
Cryogenic logistics infrastructure concentrates at this hub, creating capacity bottlenecks for Asia-Pacific trial networks. GDPR Article 44 restrictions and China's data security law push regional sponsors toward this jurisdiction for data localization compliance. The city-state's biomedical precinct anchors multiplexed imaging platform access for immuno-oncology combination trials.
Biomarker Clinical Phase Outsourcing Services Market Competitive Landscape
Top-tier vendors anchor integrated platform offerings, while commodity assay shops compete on volume scale. The market structures around a sharp split between premium dual-certified laboratories and single-analyte testing providers. Three archetypes dominate: central laboratory networks with biomarker program anchoring, in vivo oncology model specialists with paired readout capabilities, and analytical instrument supply chain controllers. Consolidation pressures favor M&A activity among mid-tier bioinformatics providers, while capacity expansion concentrates in Massachusetts and Basel hubs.
Within the integrated platform tier, Laboratory Corporation of America Holdings, Charles River Laboratories International, and Thermo Fisher Scientific exemplify divergent competitive positioning. Laboratory Corporation anchors complex biomarker programs across Phase II and III trials through central laboratory network density. Charles River occupies a position pairing in vivo oncology models with biomarker readout integration. Thermo Fisher sits within analytical instrument and consumable supply chains that underpin outsourced biomarker workflows globally.
| Leading Market Players |
|---|
| Laboratory Corporation of America Holdings |
| Charles River Laboratories International |
| Parexel International Corporation |
| Thermo Fisher Scientific |
| ICON plc |
| Eurofins Scientific |
| WuXi AppTec |
| Syneos Health |
| QIAGEN |
| Others |
Value Network & Pricing Analysis
Captive laboratory buildouts by pharmaceutical sponsors in Massachusetts and Switzerland anchor both supply positioning and pricing power, as internal analytical investments compete against outsourcing flexibility while regulatory scrutiny of biomarker-driven trial designs intensifies. This vertical integration choice compresses margins at mid-tier vendors while premium dual-certified providers defend pricing through CLIA/GLP certification scarcity.
Pricing Analysis
Bundled discovery-through-validation contracts command premium pricing against unbundled single-analyte testing, with project-based fee structures dominating complex biomarker programs. Price differentiation rests on dual certification status and bioinformatics talent depth, with Massachusetts and Basel laboratories capturing brand premiums. Cost compression in commoditized assay tiers is intensifying because NGS per-sample economics have collapsed, pulling mid-sized trials toward comprehensive genomic profiling. Mid-cap biotech sponsors exhibit highest price sensitivity, while large pharmas prioritize certification tier over unit cost.
Supply Chain Analysis
Regional distribution centers in Massachusetts, Basel, and Singapore anchor hub-and-spoke cryogenic logistics patterns for biospecimen integrity. Supply concentration in the United States, Switzerland, and Singapore draws from specialized cold-chain infrastructure and bioinformatics PhD clusters. The chain rests on consumable dependencies from analytical instrument manufacturers, biospecimen collection kits, and proprietary reagent supplies. Single-source vulnerability concentrates at multiplexed imaging platform vendors. Distribution runs through sponsor-directed site selection with chain-of-custody protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EMA's twelve-to-eighteen-month ISO 15189 accreditation timelines in Germany create cost and speed advantages for Swiss and US laboratory entrants.
For Market Incumbents: Hedge against sponsor captive buildouts by deepening CLIA/GLP dual certification moats and expanding bioinformatics talent pipelines in Basel and Singapore. Capacity addition in Singapore addresses Asia-Pacific data localization requirements while defending margin position against mid-tier price competition. For New Entrants and Emerging Players: Capture white-space in neurology biomarker services where amyloid and tau qualification timelines lag oncology maturity, and in real-world evidence integration where FDA guidance creates adjacent service demand. The most penetrable segment is AI-enabled biomarker discovery bundled with validation for venture-backed biotechs. For Investors and Strategic Acquirers: Roll-up economics work for bioinformatics specialists because computational biology PhD scarcity and spatial omics data volume explosions create fragmented capabilities ripe for consolidation. The viable acquisition window spans five to ten years. Target mid-tier vendors with ISO 15189 accreditation progress but incomplete dual certification. The signal to watch is EMA parallel scientific advice pathway utilization rates as inflection indicator for companion diagnostic co-development demand.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA/GLP Dual Certification Investment | FDA biomarker qualification program expands validation outsourcing scope for certified providers. |
| Spatial Omics Platform Acquisition | Multiplexed imaging capabilities compress immunohistochemistry workflows for immuno-oncology trials. |
| Singapore Laboratory Buildout | GDPR Article 44 and China's data security law push regional sponsors toward this jurisdiction. |
| Companion Diagnostic Co-development Partnership | EMA parallel scientific advice pathway incentivizes synchronized drug-diagnostic trial designs. |
| AI-Enabled Discovery Service Launch | Machine learning convergence with spatial transcriptomics enables bundled discovery-through-validation pricing. |
Research Methodology
Coverage spans the United States, Switzerland, Germany, China, and Singapore, with primary inputs from each market cluster combining structured interviews with drug development executives, regulatory affairs leads, CLIA laboratory directors, and biomarker procurement managers at pharmaceutical sponsors. Secondary validation draws from FDA biomarker qualification filings, EMA parallel scientific advice records, ClinicalTrials.gov protocol specifications, and ISO 15189 accreditation databases. Bottom-up service line sizing and top-down sponsor spending triangulation anchor volume estimates.
Rate-of-change decomposition separates volume drivers from price mix effects across the analysis window. The analytical framework models segmentation dimensions including service type, technology platform, therapeutic application, and end-user scale tier. CAGRs derive from sponsor pipeline biomarker adoption curves, NGS cost trajectory assumptions, and regulatory pathway velocity. Industry-specific inputs incorporate immuno-oncology combination trial expansion rates and spatial omics platform penetration assumptions.
Underlying measurement precision varies by segment; oncology applications carry tighter precision than neurology given mature endpoint qualification precedents. Forecasts reflect assumptions about FDA biomarker qualification program throughput, EMA ICH E16 harmonization progress, and bioinformatics talent availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Lab Mailers Market
Laboratory Services
US Clinical Laboratory Services Market
Laboratory Services
Serum Separation Gel Market
Laboratory Services
Clinical Laboratory Tests Market
Laboratory Services
Middle East and Africa Clinical Laboratory Services Market
Laboratory Services
Global Elispot and Fluorospot Assay Market
Laboratory Services
Central Lab Market
Laboratory Services
Veterinary Reference Laboratories Market
Laboratory Services
Autosampler Vials Market
Laboratory Services
Hematocrit Tests Market
Laboratory Services
Global Lab Consumables Market
Laboratory Services
Laboratory Developed Tests Market
Laboratory Services
Global Office Based Lab Market
Laboratory Services
Pathology Services Market
Laboratory Services
Laboratory Disposable Products Market
Laboratory Services
Global Medical Laboratories Market