
 Epigenetics Diagnostics Market | 2026-2036
Epigenetics Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Epigenetics Diagnostics Market Analytics
A shift from single-source instrument supply to multi-vendor reagent ecosystems is restructuring procurement across clinical and research settings. Thermo Fisher Scientific leverages its integrated instrument-reagent portfolio to anchor high-throughput methylation screening workflows. Illumina sustains platform dominance through consumable pull-through on its sequencing systems. QIAGEN competes with sample-to-insight automation that reduces bisulfite conversion variability.
Epigenetics diagnostics encompasses the detection and quantification of heritable DNA modifications—primarily cytosine methylation, histone acetylation, and non-coding RNA regulation—without alteration of the underlying nucleotide sequence, typically requiring bisulfite conversion sensitivity below 0.1% to distinguish 5-methylcytosine from unmodified cytosine. These tests serve to stratify cancer risk, monitor minimal residual disease, and identify imprinting disorders in clinical practice. Assays and kits capture the largest revenue share due to recurring consumable demand tied to instrument installed bases. Cancer diagnostics leads application-level growth, fueled by blood-based multi-cancer early detection panels. Next-Generation Sequencing displaces microarrays in translational settings where single-base resolution and novel biomarker discovery justify higher per-sample costs.
FDA oversight of laboratory-developed tests and EPA guidelines for nucleic acid reagent disposal shape product design and commercialization timelines in the United States. EMA's In Vitro Diagnostic Regulation in Europe imposes stricter clinical evidence requirements for epigenetic biomarker claims, filtering market entrants by validation depth. Stakeholders must monitor evolving payer coverage policies for methylation-based screening tests as laboratories seek reimbursement parity with established oncologic modalities.
Market Dynamics
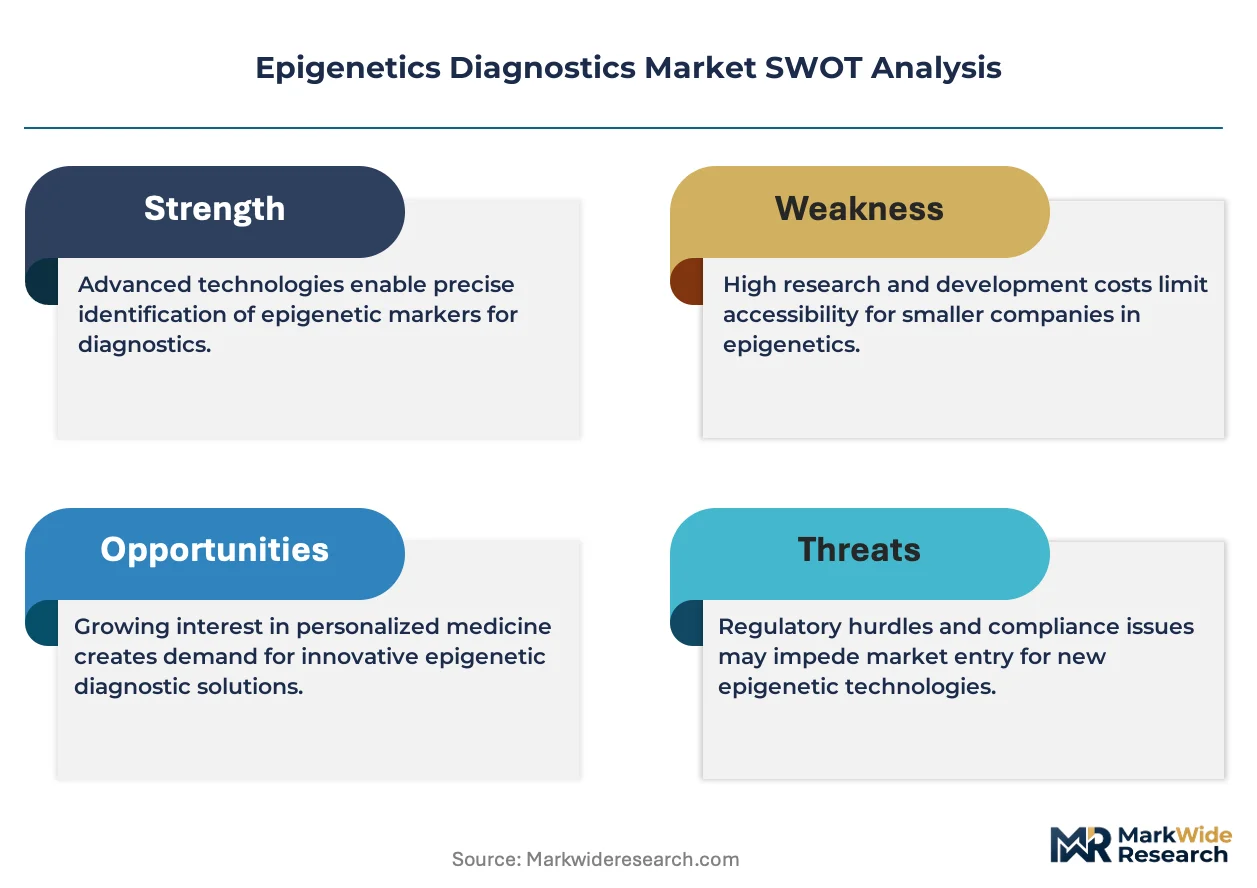
Multi-cancer early detection panels are compressing clinical validation timelines while fragmenting test reimbursement pathways across payer categories.
Growth Catalysts
- Blood-based screening expansion:Liquid biopsy workflows enable serial monitoring of minimal residual disease without tissue acquisition. Academic medical centers in the United States standardize pre-analytical protocols for cell-free DNA methylation extraction.
- FDA guidance acceleration:The agency's templated review pathways for next-generation sequencing oncology tests reduce regulatory uncertainty for assay developers. This compresses commercialization timelines for multi-gene methylation panels.
- Histone modification mapping:Chromatin immunoprecipitation sequencing advances reveal regulatory landscapes for imprinting disorders. Pediatric genetics programs integrate these assays into diagnostic workups for developmental delay.
Market Restraints
- Bisulfite conversion cost volatility:Reagent purity requirements below 0.1% false-positive rates concentrate supply among specialized chemical manufacturers. Price instability for molecular-grade sodium bisulfite squeezes mid-volume laboratory margins.
- EMA validation depth requirements:The In Vitro Diagnostic Regulation mandates prospective clinical evidence for epigenetic biomarker claims. Small assay developers face capital barriers to European market entry.
- Microarray substitution pressure:Reduced-cost sequencing alternatives erode array-based methylation screening in translational research. Legacy platform installed bases depreciate faster than anticipated replacement cycles.
Strategic Opportunities
- India's diagnostic infrastructure buildout:The country's PLI scheme for medical devices attracts reagent manufacturing investment. Regional reference laboratories in Maharashtra and Karnataka adopt automated nucleic acid extraction workflows.
- AI-assisted variant interpretation:Machine learning classifiers reduce manual review burden for methylation pattern analysis. This convergence accelerates report turnaround for high-complexity molecular pathology.
- Direct-to-consumer channel emergence:Wellness platforms integrate epigenetic age testing into subscription health monitoring. Regulatory arbitrage between jurisdictions shapes geographic launch sequencing.
Industry Challenges
- Bioinformatics pipeline standardization:Inconsistent alignment algorithms for bisulfite-converted sequences generate inter-laboratory discordance. Proficiency testing programs struggle to establish reference ranges for novel methylation biomarkers.
- Cross-border sample logistics:Temperature excursion risks for cell-free DNA specimens complicate centralized testing models. Courier networks with cryogenic capabilities remain concentrated in metropolitan corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epigenetics Diagnostics Market |
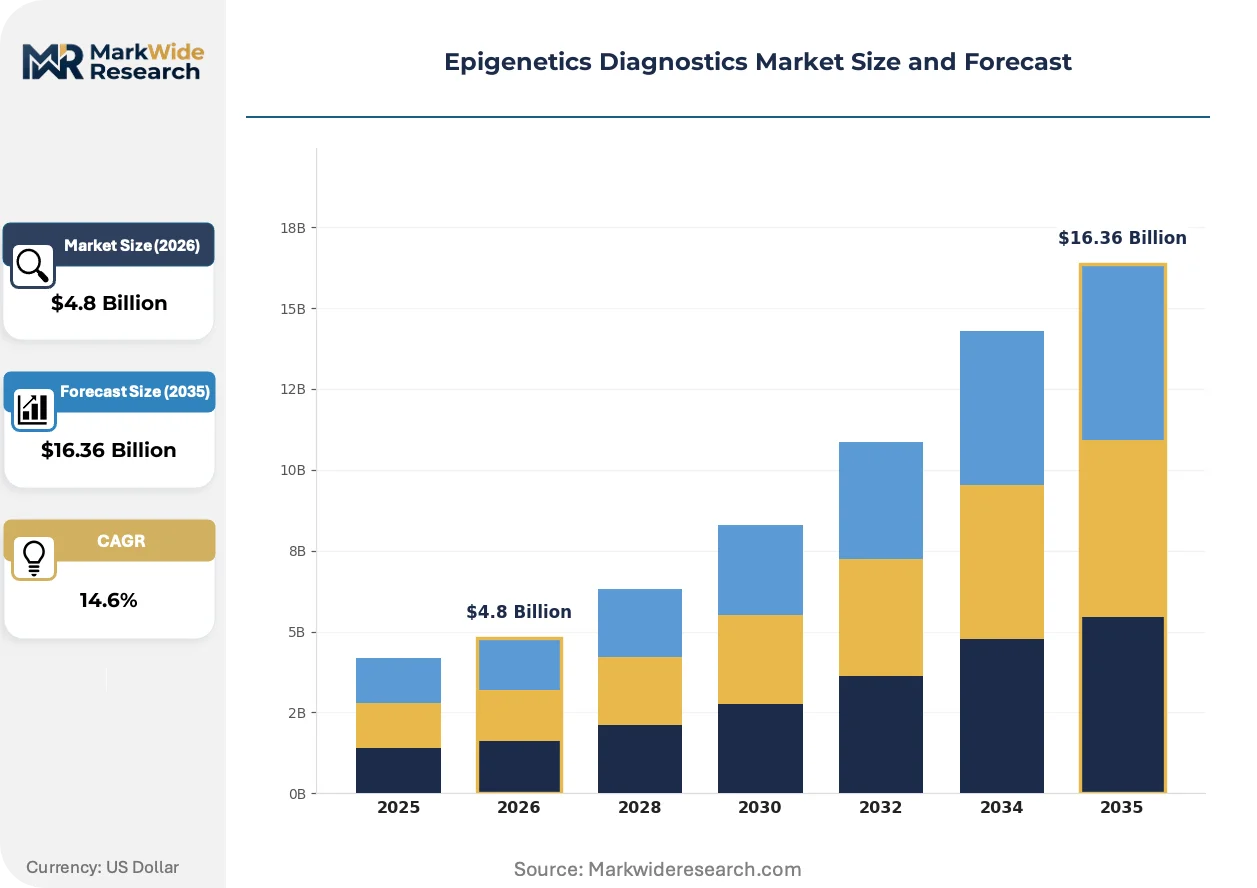
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assays, Kits, Instruments, Software End User: Research Institutions, Clinical Laboratories, Hospitals, Diagnostics Centers Technology: Next-Generation Sequencing, PCR, Microarrays, Bisulfite Sequencing Application: Cancer Diagnostics, Genetic Disorders, Prenatal Testing, Agriculture |
| Companies Covered | Thermo Fisher Scientific, Illumina, Roche Diagnostics, QIAGEN, Agilent Technologies, Merck KGaA, Promega Corporation, Pacific Biosciences, New England Biolabs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epigenetics Diagnostics Market Evolving Landscape
Platform economics are inverting as reagent-agnostic instruments displace closed-system workflows, while regulatory frameworks race to catch up with multiplexed biomarker complexity.
Third-generation sequencing chemistries are decentralizing methylation analysis from core facilities toward distributed clinical laboratories. Community hospital systems in the United States deploy benchtop instruments for same-day oncology panel turnaround. This compression of testing geography reduces specimen referral revenue for centralized academic centers.
REACH chemical safety registrations in Europe now capture nucleic acid modification reagents under extended producer responsibility frameworks. Reagent manufacturers reformulate bisulfite conversion kits to eliminate hazardous byproducts. German clinical laboratories face elevated disposal compliance costs that favor outsourced reference testing.
Consolidated procurement by integrated delivery networks is unbundling instrument placement from consumable contracts. Health system administrators negotiate reagent sourcing flexibility across multiple vendor platforms. This behavior shift concentrates purchasing leverage in the United States Midwest and Southeast hospital alliances.
Epigenetics Diagnostics Market Segmentation
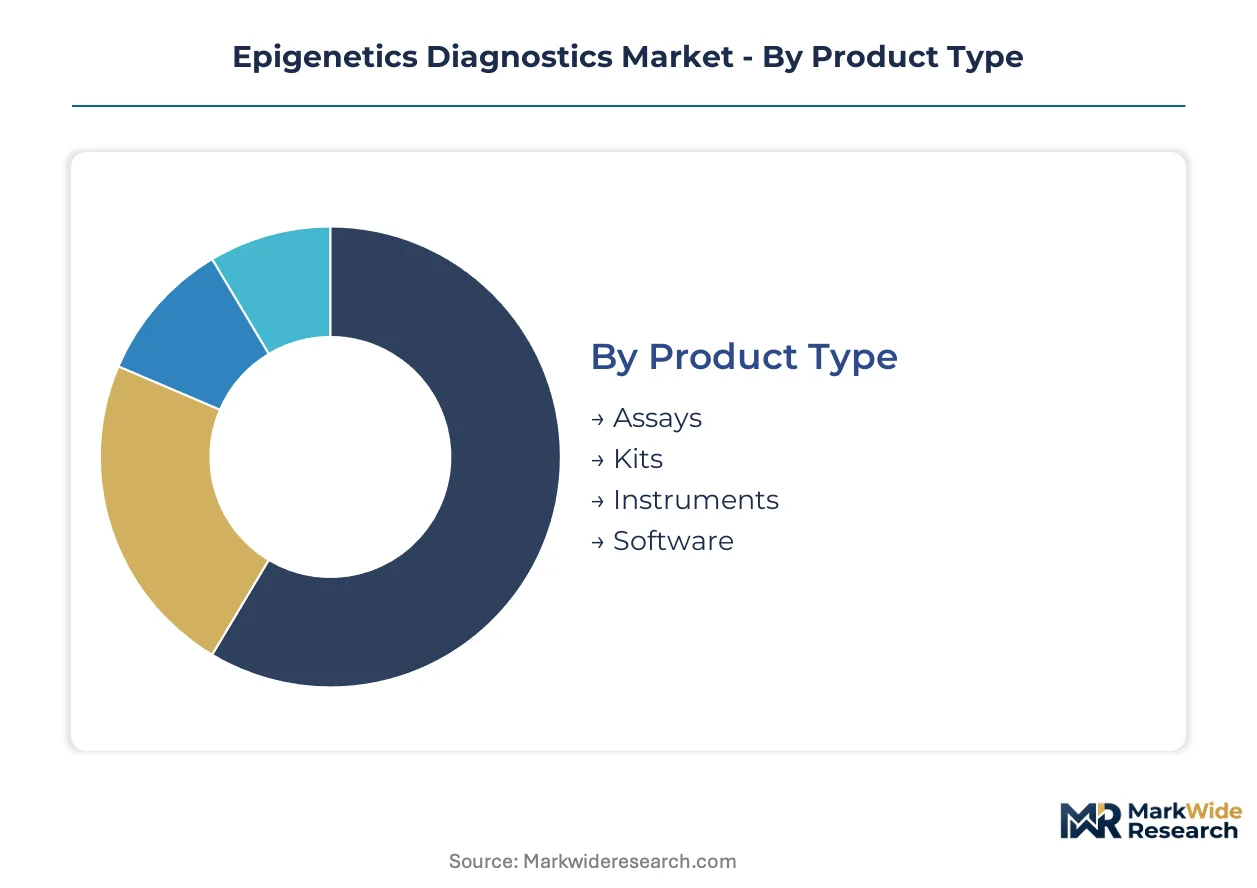
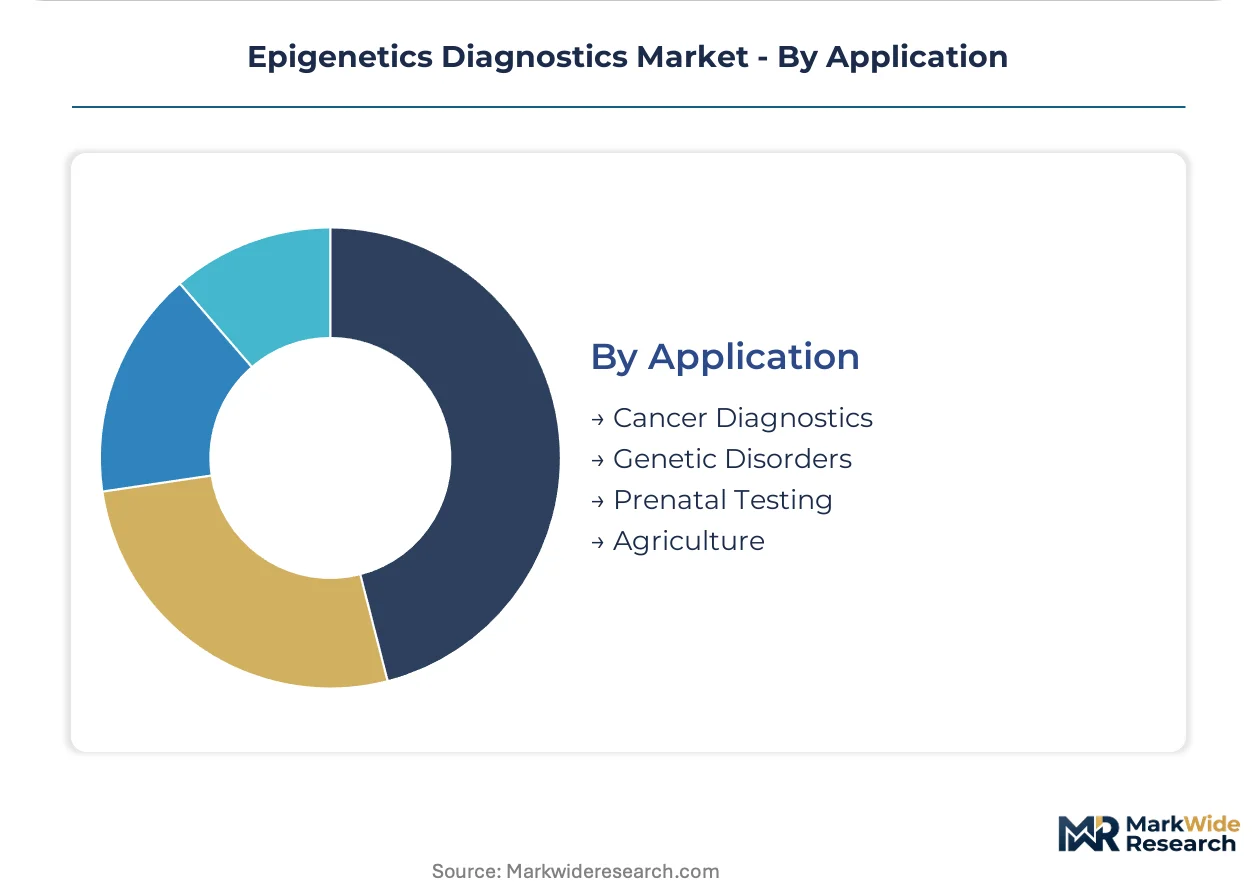
Epigenetics diagnostics segmentation reflects divergent buyer priorities across clinical throughput demands, research discovery workflows, and regulatory compliance burdens. Procurement patterns split between high-volume consumable replenishment and capital-intensive platform investments.
Product Type:
Buyers differentiate by recurring operational expense versus upfront capital deployment and depreciation schedules.
- Assays:Pre-formulated reagent sets for targeted methylation detection with validated analytical performance. Clinical laboratories in the United States anchor procurement volumes through multi-year service contracts tied to oncology panel menus.
- Kits:Modular workflow components enabling protocol customization for novel biomarker validation. Academic medical centers in Germany and France concentrate demand for bisulfite conversion and library preparation flexibility.
- Instruments:Capital equipment spanning benchtop sequencers to high-throughput screening platforms. Integrated delivery networks negotiate placement terms separately from consumable sourcing.
- Software:Bioinformatics pipelines for methylation pattern interpretation and regulatory reporting. Cloud-deployed solutions gain traction among mid-volume reference laboratories.
Assays lead volumes today; software is gaining share fastest.
End User:
Site-specific workflow complexity and reimbursement access determine technology selection and vendor loyalty.
- Clinical Laboratories:CAP-accredited facilities processing high-complexity molecular diagnostics under CLIA oversight. Reference laboratories in Texas and California standardize pre-analytical protocols for cell-free DNA methylation extraction.
- Hospitals:In-house pathology departments seeking same-day oncology panel turnaround. Community hospital systems in the United States Midwest deploy third-generation sequencing for decentralized testing.
- Research Institutions:Academic centers prioritizing novel biomarker discovery over regulatory clearance. EMA validation depth requirements filter European grant-funded procurement toward established assay formats.
- Diagnostics Centers:Outpatient facilities offering direct-to-consumer epigenetic age testing and wellness screening. Regulatory arbitrage between jurisdictions shapes geographic launch sequencing.
Clinical laboratories dominate current procurement; diagnostics centers show steepest expansion trajectory.
Technology:
Resolution requirements and per-sample economics drive substitution between established and emerging platforms.
- Next-Generation Sequencing:Single-base resolution for novel biomarker discovery and multi-gene panel deployment. Translational research settings justify higher per-sample costs through comprehensive epigenomic profiling.
- PCR:Quantitative methylation-specific assays for rapid turnaround in resource-constrained environments. India's PLI scheme for medical devices attracts reagent manufacturing investment for regional reference laboratories.
- Microarrays:Legacy screening platforms facing displacement pressure from reduced-cost sequencing alternatives. Legacy installed bases depreciate faster than anticipated replacement cycles.
- Bisulfite Sequencing:Gold-standard cytosine methylation detection requiring sensitivity below 0.1% false-positive rates. Reagent purity requirements concentrate supply among specialized chemical manufacturers.
PCR anchors current installed base; next-generation sequencing climbs the fastest.
Application:
Disease prevalence, reimbursement parity, and clinical utility evidence shape assay development prioritization.
- Cancer Diagnostics:Blood-based multi-cancer early detection panels and minimal residual disease monitoring. FDA's templated review pathways compress commercialization timelines for methylation-based oncology tests.
- Genetic Disorders:Imprinting disorder detection through chromatin immunoprecipitation sequencing advances. Pediatric genetics programs in Massachusetts and California integrate these assays into developmental delay workups.
- Prenatal Testing:Non-invasive fetal epigenetic screening from maternal circulation. Cell-free DNA specimen stability requirements complicate centralized testing models.
- Agriculture:Crop epigenetic trait selection and stress response profiling. Research applications lag clinical segments in regulatory standardization.
Cancer diagnostics commands current revenue concentration; genetic disorders expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Boston cluster anchors global epigenetics diagnostics demand through concentrated academic medical center procurement and venture-backed assay development. FDA regulatory pathways and CLIA laboratory accreditation standards shape commercialization velocity. Regional procurement concentrates in reference laboratories across Massachusetts, California, and Texas.
United States
Academic medical centers in Massachusetts and California drive assay standardization for cell-free DNA methylation extraction. FDA templated review pathways for next-generation sequencing oncology tests compress regulatory timelines. Reference laboratories in Texas anchor high-throughput screening volumes through multi-year service contracts.
Germany
Pediatric genetics programs in Bavaria and Baden-Württemberg integrate chromatin immunoprecipitation sequencing for imprinting disorder diagnostics. REACH chemical safety registrations impose extended producer responsibility on nucleic acid modification reagent disposal. Clinical laboratories in North Rhine-Westphalia face elevated compliance costs favoring outsourced reference testing.
China
Regional reference laboratories in Shanghai and Beijing adopt automated nucleic acid extraction workflows for oncology panel deployment. NMPA oversight of laboratory-developed tests shapes product design timelines. The Yangtze River Delta cluster concentrates reagent manufacturing investment under medical device localization policies.
India
PLI scheme incentives attract reagent manufacturing investment to Maharashtra and Karnataka. CDSCO regulatory frameworks for in vitro diagnostics filter market entrants by validation depth. Regional reference laboratories in Telangana deploy quantitative methylation-specific PCR for resource-constrained environments.
United Kingdom
Research institutions in London and Cambridge prioritize novel biomarker discovery over regulatory clearance pathways. MHRA post-Brexit regulatory autonomy adjusts IVD evidence requirements. Genomics England integration programs concentrate methylation screening procurement in the Southeast cluster.
Epigenetics Diagnostics Market Competitive Landscape
Global majors compete with regional champions across reagent supply and instrument platform ecosystems. The vendor base stratifies between integrated instrument-reagent portfolios and modular workflow specialists. Three archetypes dominate: diversified life science conglomerates with consumable pull-through models, sequencing platform specialists defending installed base economics, and sample-to-insight automation providers reducing protocol variability. Competitive moves concentrate on strategic partnerships for assay menu expansion and geographic licensing arrangements for regulatory market access.
Among diversified life science conglomerates, Thermo Fisher Scientific exemplifies the integrated portfolio archetype through instrument-reagent bundling. Illumina occupies a position anchoring sequencing platform dominance, while QIAGEN sits within the sample-to-insight automation tier. These three represent distinct competitive vectors: consumable pull-through economics, platform installed base defense, and protocol standardization services.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Illumina |
| Roche Diagnostics |
| QIAGEN |
| Agilent Technologies |
| Merck KGaA |
| Promega Corporation |
| Pacific Biosciences |
| New England Biolabs |
| Others |
Value Network & Pricing Analysis
Integrated delivery network procurement consolidation in the United States Midwest and Southeast forces reagent manufacturers toward flexible sourcing contracts, compressing margins for mid-volume laboratories while elevating price premiums for specialized bisulfite conversion chemistries.
Pricing Analysis
Input-cost pass-through from molecular-grade sodium bisulfite reagents shapes contract pricing for clinical methylation assays. Three-tier pricing structure across premium, standard, and economy levels differentiates by analytical sensitivity grade and CAP/CLIA certification tier. Pricing pressure stems from health system administrators unbundling instrument placement from consumable contracts. Mid-volume reference laboratories exhibit highest price sensitivity; academic medical centers with grant funding show lowest.
Supply Chain Analysis
Specialized bisulfite conversion chemistry supply rests on German and Japanese specialty chemical producers with molecular-grade purification capabilities. Raw material dependencies include sodium bisulfite precursors, high-purity solvents, and sequencing-grade enzymes. Single-source vulnerability concentrates in reagent formulations requiring sub-0.1% false-positive sensitivity. Distribution runs through regional distributors serving CAP-accredited facilities and direct contracts with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Epigenetics diagnostics has entered a late-cycle quality phase where FDA-cleared methylation panels command reimbursement premiums over laboratory-developed tests, rewarding manufacturers with validated clinical evidence packages.
For Market Incumbents: Anchor platform dominance through consumable pull-through economics on installed sequencing bases. Defend against third-generation sequencing decentralization by embedding workflow automation in community hospital systems. Prioritize CAP/CLIA certification investment to maintain reimbursement access against emerging reagent-agnostic instruments.
For New Entrants and Emerging Players: Regional reference laboratories in India's Maharashtra and Karnataka represent an underserved buyer archetype with PLI scheme procurement capacity. White-space targets include AI-assisted methylation interpretation software and automated bisulfite conversion workflows for resource-constrained settings. Pursue CDSCO regulatory pathway alignment as the go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with sample-to-insight automation providers reducing protocol variability in high-complexity molecular pathology. Five-to-ten-year viability favors modular workflow specialists over closed-system instrument vendors facing platform substitution. Watch FDA reimbursement decisions for blood-based multi-cancer early detection panels as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | Accelerates commercialization timelines for methylation-based oncology panels under templated review pathways. |
| CE Marking Pathway | Enables European market entry despite EMA In Vitro Diagnostic Regulation validation depth requirements. |
| Hospital System Partnership | Secures multi-year service contracts for high-throughput screening volumes in Texas and California. |
| Software Companion Development | Reduces manual review burden for methylation pattern analysis through machine learning classifiers. |
| Reimbursement Strategy | Establishes payer parity for cell-free DNA methylation extraction against established oncologic modalities. |
Research Methodology
Bottom-up clinical laboratory modeling reconciled against top-down reagent manufacturer tracking forms the analytical core. Primary interviews with molecular pathology directors, CLIA laboratory managers, GPO contracts managers, and FDA regulatory affairs specialists combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and CAP proficiency testing reports. Triangulation across stakeholder inputs and documentary sources ensures segment-level consistency.
Input-output matrices map assay volumes to instrument installed bases and consumable pull-through rates across the projection horizon. Segmentation dimensions include product type, end-user facility class, technology platform, and application area with regional regulatory cluster overlays. CAGRs derive from fitted growth curves anchored to documented commercialization timelines and payer coverage expansion patterns. Forecast inputs incorporate NMPA and CDSCO regulatory pathway velocities alongside FDA review template adoption rates.
Inputs from FDA filing databases and CMS reimbursement schedules were available through the study window; gaps in private payer coverage policy documentation introduce uncertainty bands around commercialization timing assumptions. Forecasts reflect documented regulatory and procurement assumptions; EMA validation requirement changes, bisulfite reagent supply disruptions, or AI-assisted interpretation standardization delays could revise trajectory. A small set of reimbursement decisions and regulatory guidance releases warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Complement C3 ELISA Kits Market
Diagnostics
Urinary Protein Reagents Market
Diagnostics
HDL Cholesterol Kits Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market
Diagnostics
Global Antinuclear Antibody Test Market
Diagnostics
Global Inflammatory Bowel Disease (IBD) Diagnostic Market
Diagnostics
Global Prostate Specific Antigen (PSA) Test Market
Diagnostics
Epilepsy Diagnosis and Treatment Market
Diagnostics
Spain in-Vitro Diagnostics Market
Diagnostics
Global Respiratory Syncytial Virus (RSV) Diagnostic Market
Diagnostics
Global Neurodiagnostics Market
Diagnostics
Poultry Diagnostics Market
Diagnostics
Saudi Arabia in-Vitro Diagnostics (IVD) Market
Diagnostics
Europe Autoimmune Disease Diagnostics Market
Diagnostics
Molecular Diagnostics Market
Diagnostics
US Prostate Cancer Nuclear Medicine Diagnostics Market