
 Community Acquired Pneumonia (CAP) Market | 2026-2036
Community Acquired Pneumonia (CAP) Market Size, Share, and Industry Trends Forecast 2026-2036
Community Acquired Pneumonia (CAP) Market Outlook
Hospital end user demand is shifting toward integrated acute and outpatient pathways as health systems prioritize reduced readmission penalties. Pfizer leverages its vaccine manufacturing scale to supply pneumococcal conjugate products across multiple continents. AstraZeneca sustains competitive positioning through respiratory therapy specialization and hospital formulary relationships. Merck anchors its presence in intravenous antibiotic segments where resistant organism coverage commands clinical preference.
Community Acquired Pneumonia constitutes an acute lower respiratory tract infection acquired outside healthcare facilities, typically involving bacterial pathogens such as Streptococcus pneumoniae, Haemophilus influenzae, or atypical organisms including Mycoplasma pneumoniae and Legionella species, with diagnosis requiring radiographic infiltrate confirmation plus compatible clinical symptoms. The condition demands prompt antimicrobial intervention, with empiric therapy selection guided by severity scoring, local resistance patterns, and patient comorbidity profiles. Antibiotics occupy the dominant revenue position within product type segmentation due to established generic availability and high treatment volume, while vaccines represent the fastest-expanding margin pool as national immunization programs broaden age-based indications. Oral delivery mode leads volume metrics for outpatient CAP management, though intravenous administration captures premium pricing in hospitalized patient segments where severity and comorbidity drive parenteral requirements.
The FDA antimicrobial stewardship framework and EMA pharmacovigilance requirements constrain empiric broad-spectrum prescribing, directing development toward pathogen-directed diagnostics and narrow-spectrum alternatives. CDSCO quality standards and China's NMPA accelerated review pathways for anti-infectives influence regional product registration strategies and local manufacturing partnerships. Stakeholders must monitor evolving resistance surveillance data and regulatory incentives for novel mechanism antibiotics to align portfolio investments with reimbursement-accessible therapeutic gaps.
Market Dynamics
FDA antimicrobial stewardship mandates and EMA pharmacovigilance tightening are compressing empiric broad-spectrum prescribing, redirecting R&D investment toward narrow-spectrum alternatives and rapid diagnostic pairing.
Growth Catalysts
- Aging Demographics:Expanding elderly populations in the United States, China, and Germany intensify hospitalization rates and therapeutic complexity. Chronic comorbidity burdens multiply treatment-resistant case volumes.
- Streptococcus pneumoniae Vaccination Expansion:National immunization programs in high-income markets broaden age-based indications. Payer reimbursement for adult pneumococcal coverage accelerates preventive uptake.
- CDSCO Accelerated Pathways:India's anti-infective fast-track review mechanisms attract manufacturing partnerships targeting emerging market access. Local production scale reduces import dependency.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing clusters heavily in China, creating geopolitical and quality audit vulnerabilities. Single-source dependencies amplify shortage risks.
- Generic Antibiotic Price Compression:Off-patent macrolides and fluoroquinolones dominate outpatient prescribing, eroding branded margin pools. Reimbursement tiers favor lowest-cost alternatives.
- Diagnostic Confirmation Delays:Radiographic infiltrate requirements and sputum culture turnaround times prolong empiric therapy windows. Overuse of broad-spectrum agents persists pending pathogen identification.
Strategic Opportunities
- Point-of-Care Molecular Diagnostics:Syndromic respiratory panels enabling same-day pathogen identification are integrating into emergency department workflows. Rapid Streptococcus pneumoniae and atypical organism detection supports narrow-spectrum selection.
- Sub-Saharan Africa Underpenetration:Vaccine cold chain infrastructure gaps and diagnostic radiography scarcity limit treatment access. Public-private partnerships for decentralized care models address rural coverage.
- US Hospital Readmission Penalty Avoidance:CMS quality metrics incentivize integrated acute-to-outpatient pathways. Risk-stratified discharge protocols with oral step-down therapies reduce 30-day return rates.
Industry Challenges
- Antimicrobial Resistance Surveillance Integration:Local antibiogram maintenance requires continuous laboratory investment and data standardization. Hospital formulary committees demand real-time resistance pattern updates.
- Clinical Trial Enrollment Complexity:Severe CAP patient recruitment competes with COVID-19 and influenza trial pipelines. Seasonal epidemiology concentrates eligible case windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Community Acquired Pneumonia (CAP) Market |
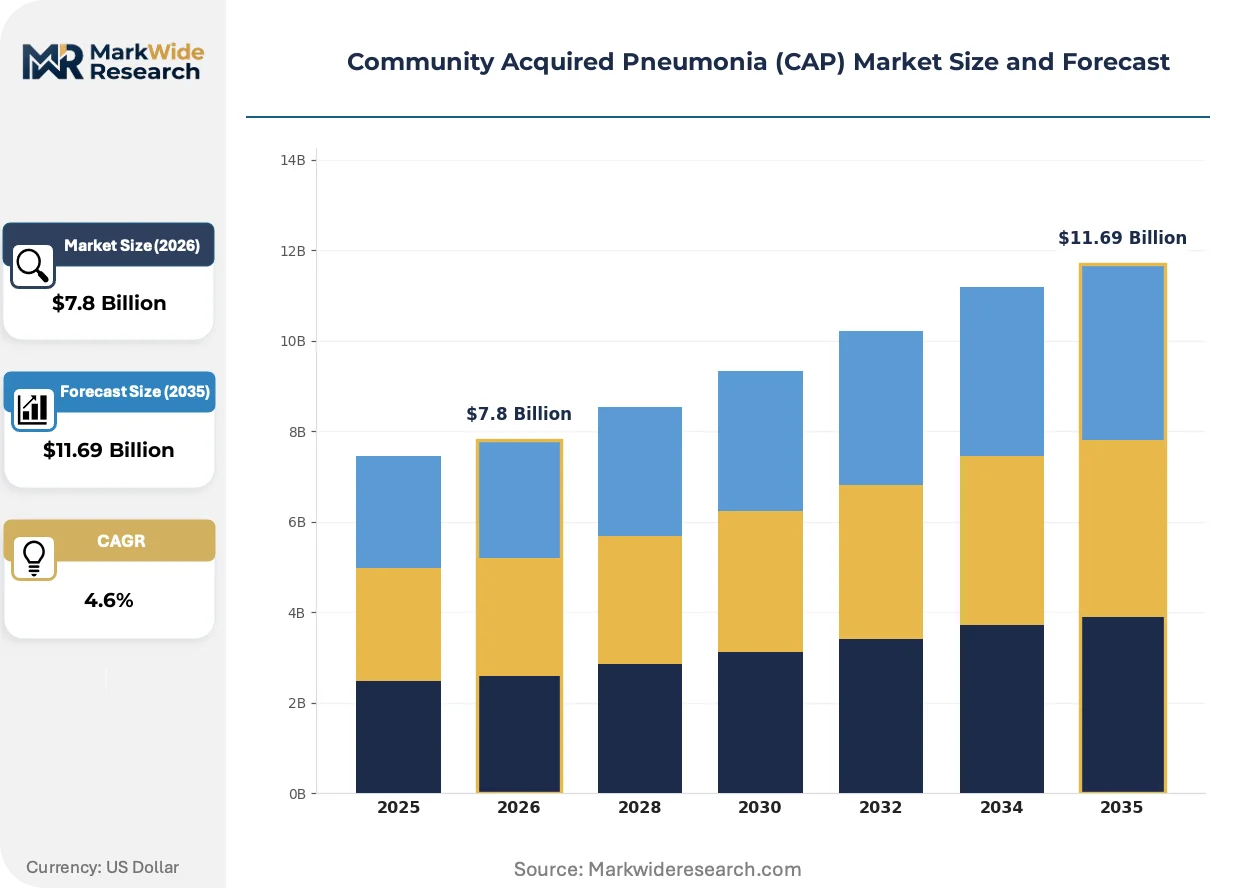
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $11.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Vaccines, Diagnostics, Supportive Care Therapy Area: Acute Care, Outpatient Care, Hospitalized Patients, Preventive Care Delivery Mode: Oral, Intravenous, Inhalation, Intramuscular End User: Clinics, Hospitals, Home Healthcare, Pharmacy |
| Companies Covered | Pfizer, AstraZeneca, Merck, GlaxoSmithKline, Biotest, BioAegis Therapeutics, Melinta Therapeutics, Kyorin Pharmaceutical, C10 Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Community Acquired Pneumonia (CAP) Market Strategic Shifts
Diagnostic-therapeutic pairing is displacing empiric protocols across acute care settings, with regulatory pressure and resistance economics converging to reward precision over coverage breadth.
Multiplex PCR respiratory panels are integrating into hospital laboratory workflows, enabling simultaneous detection of bacterial and viral pathogens from single specimens. Emergency departments in the United States and Germany are adopting these platforms to compress time-to-appropriate therapy decisions. The technology is integrating antibiotic stewardship compliance directly into triage protocols, reducing unnecessary broad-spectrum exposure.
EMA's evolving quality standards for generic antibiotic bioequivalence are tightening dissolution and impurity specifications. Manufacturers must reformulate legacy products or face market withdrawal, elevating production costs for European supply. Hospital procurement committees in Germany and France are responding by consolidating supplier lists toward vertically integrated producers with analytical capabilities.
Integrated acute-outpatient care pathways are fragmenting traditional hospital-centric revenue models. United States health systems facing CMS readmission penalties are unbundling intravenous administration from admission decisions, favoring observation units with rapid oral conversion protocols. This shift concentrates in Medicare Advantage–dominated markets where capitated risk transfers to provider groups.
Community Acquired Pneumonia (CAP) Market Segmentation
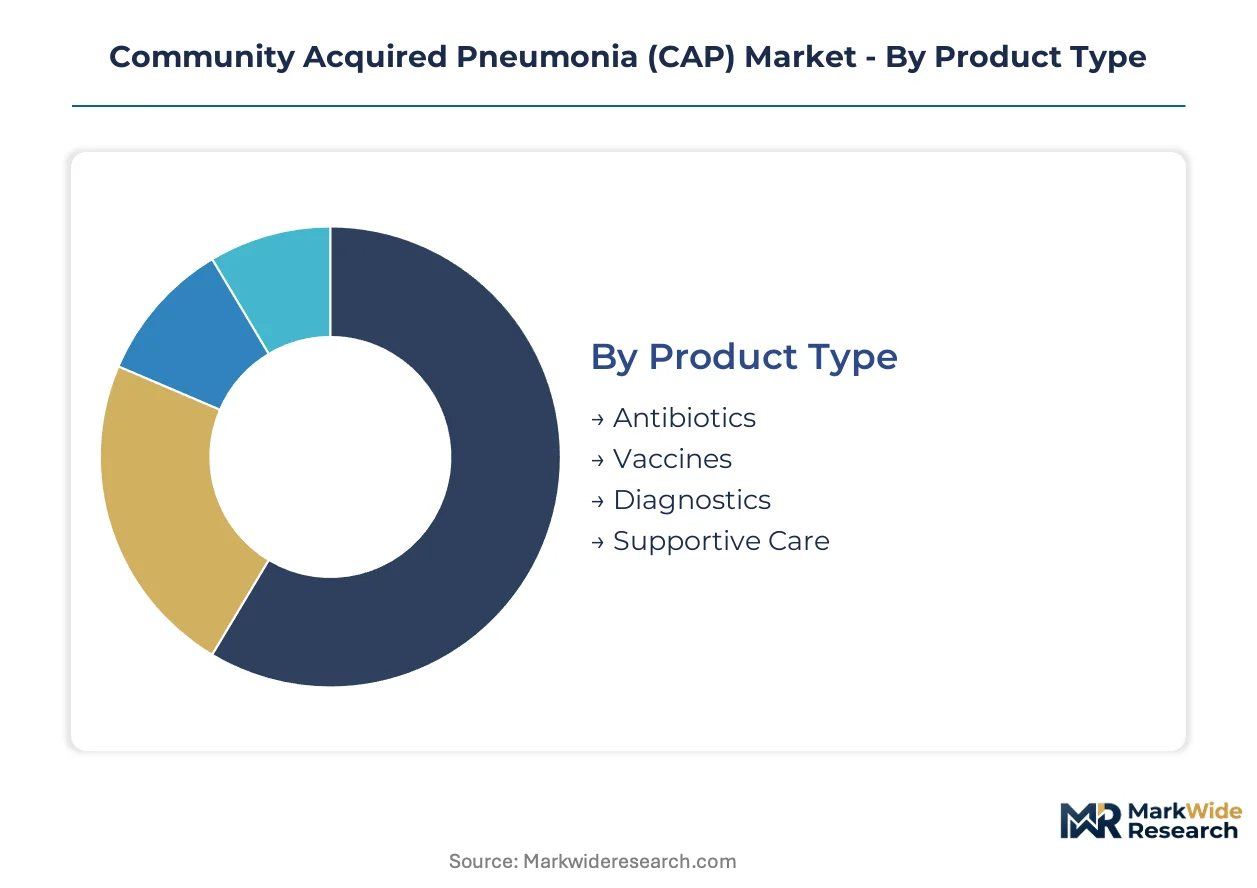
Community Acquired Pneumonia treatment pathways fragment across therapeutic modality, care setting, and administration route. Segmentation clarity enables stakeholders to align manufacturing capacity, regulatory submissions, and commercial deployment with distinct clinical workflows and reimbursement architectures.
Product Type:
Cost tier separates chronic preventive investments from acute intervention procurement cycles.
- Antibiotics:Beta-lactams, macrolides, fluoroquinolones, and respiratory fluoroquinolones constitute the empiric backbone of CAP management. Hospital formularies in the United States and Germany concentrate volume here, though generic price compression and antimicrobial stewardship mandates constrain branded expansion.
- Vaccines:Pneumococcal conjugate and polysaccharide formulations target Streptococcus pneumoniae serotype coverage. Medicare reimbursement expansion and China's NMPA adult indication approvals are accelerating preventive uptake fastest among all product categories.
- Diagnostics:Multiplex PCR panels, rapid antigen tests, and sputum culture systems enable pathogen-directed therapy selection. Emergency department adoption in Germany and the United States is compressing time-to-appropriate antibiotic decisions.
- Supportive Care:Oxygen therapy, bronchodilators, and fluid management address hypoxemia and symptom stabilization. Home healthcare channels in the United States are absorbing post-acute supportive care volume to reduce hospital readmission penalties.
Volume sits with antibiotics; growth tilts toward vaccines.
Therapy Area:
Patient acuity determines reimbursement tier, antimicrobial spectrum breadth, and site-of-care economics.
- Acute Care:Emergency department stabilization and intensive respiratory support for severe hypoxemia or septic presentation. United States hospitals facing CMS quality metrics prioritize rapid disposition to observation units.
- Outpatient Care:Oral antibiotic prescribing for low-risk CURB-65 scores with radiographic confirmation. Retail pharmacy chains in Germany and the United States capture prescription volume through integrated electronic health record connectivity.
- Hospitalized Patients:Parenteral antibiotic administration with severity-stratified protocols and step-down conversion criteria. Medicare Advantage capitation in the United States is shortening average length of stay.
- Preventive Care:Vaccination campaigns and chronic disease management to reduce incident CAP rates. China's national immunization program expansion and US Medicare Part D coverage are broadening adult pneumococcal access.
Hospitalized patients anchor revenue concentration; preventive care is climbing the fastest.
Delivery Mode:
Administration route governs site-of-care requirements, pricing premium, and generic substitution vulnerability.
- Oral:Tablet and suspension formulations for outpatient step-down and uncomplicated community presentation. Pharmacy benefit managers in the United States favor macrolide and doxycycline generics with minimal prior authorization friction.
- Intravenous:Hospital-administered beta-lactams and respiratory fluoroquinolones for severe CAP with comorbidity burden. German DRG reimbursement structures and US hospital procurement committees sustain premium pricing.
- Inhalation:Nebulized bronchodilators and adjunctive therapies for airway management. Home healthcare adoption in the United States supports early discharge protocols.
- Intramuscular:Vaccine administration and depot antibiotic formulations. Community pharmacy clinics in Germany are expanding vaccination access points outside hospital settings.
Oral delivery dominates prescription volume; intravenous commands per-dose value premiums.
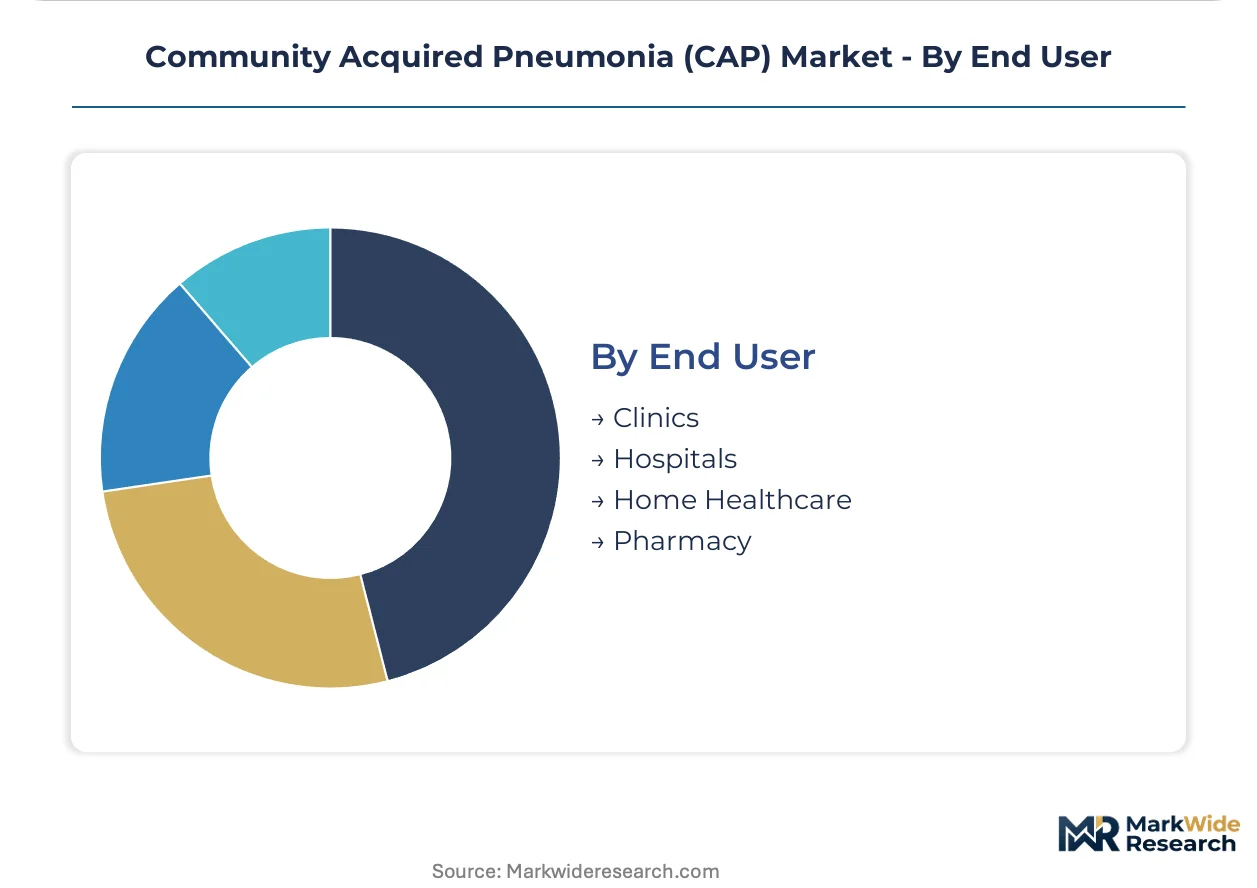
End User:
Customer type shapes procurement authority, formulary control, and patient relationship duration.
- Clinics:Primary care and urgent care settings managing uncomplicated CAP with rapid diagnostic triage. United States accountable care organizations are consolidating clinic networks to manage total cost of care.
- Hospitals:Acute care facilities with antimicrobial stewardship committees and integrated laboratory infrastructure. EMA pharmacovigilance requirements and FDA stewardship mandates drive formulary standardization.
- Home Healthcare:Post-acute oxygen therapy, nursing support, and oral medication adherence monitoring. US Medicare readmission penalty avoidance is transferring volume from inpatient to home-based settings.
- Pharmacy:Retail dispensing and vaccination administration with pharmacist prescriptive authority expansion. China's NMPA is piloting pharmacy-based diagnostic testing in select provinces.
Hospitals retain therapeutic complexity; home healthcare is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shanghai and Shenzhen concentrate API manufacturing for anti-infective supply chains serving domestic and export markets. India's pharmaceutical special economic zones in Hyderabad and Ahmedabad attract contract manufacturing organizations seeking cost-advantaged production bases. Germany's BioRN cluster and associated tax incentives anchor European vaccine development infrastructure.
United States
Medicare Advantage penetration and CMS readmission penalties drive integrated acute-outpatient pathway investments. FDA antimicrobial stewardship mandates compress empiric broad-spectrum prescribing in hospital emergency departments. Boston-Cambridge biotech corridor hosts rapid diagnostic developers pairing molecular platforms with narrow-spectrum antibiotic selection protocols.
China
Aging demographics and urban air quality burdens expand hospitalized CAP volumes in tier-one hospitals. NMPA accelerated review pathways for anti-infectives shorten novel antibiotic registration timelines. Yangtze River Delta manufacturing clusters dominate API production for macrolide and beta-lactam active ingredients serving global generic supply.
Germany
EMA pharmacovigilance tightening and DRG reimbursement structures favor pathogen-directed therapy protocols. Hospital formulary committees in Bavaria and North Rhine-Westphalia prioritize rapid diagnostic integration. Rhine-Main biopharma corridor concentrates vaccine development operations for pneumococcal conjugate formulations.
India
CDSCO fast-track mechanisms for anti-infectives attract multinational manufacturing partnerships targeting emerging market access. Hyderabad and Ahmedabad pharmaceutical zones scale generic antibiotic output for export to Africa and Southeast Asia. Government production-linked incentive schemes for active pharmaceutical ingredients reduce import dependency on Chinese supply.
Japan
PMDA streamlined review for anti-infectives addressing unmet resistance needs accelerates novel mechanism antibiotic approvals. Kanto region hospital networks adopt multiplex PCR respiratory panels for emergency department triage. Tokyo-Osaka pharmaceutical corridor maintains specialized respiratory therapy development capabilities.
Community Acquired Pneumonia (CAP) Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with vaccine developers commanding consolidated positions and generic antibiotic suppliers facing fragmented price competition. Large-cap pharmaceutical companies anchor pneumococcal conjugate supply through vertically integrated manufacturing networks. Mid-tier antibiotic developers occupy narrow-spectrum niches where resistance economics justify premium positioning. Competitive moves concentrate on diagnostic-therapeutic pairing partnerships and regional manufacturing joint ventures to secure API supply.
Among established respiratory and anti-infective developers, Pfizer, AstraZeneca, and Merck exemplify distinct strategic archetypes within the competitive structure. Pfizer represents scale-driven vaccine manufacturing with multi-continent distribution infrastructure. AstraZeneca occupies respiratory therapy specialization anchored by hospital formulary relationships. Merck anchors intravenous antibiotic segments where resistant organism coverage commands clinical preference in severe CAP management.
| Leading Market Players |
|---|
| Pfizer |
| AstraZeneca |
| Merck |
| GlaxoSmithKline |
| Biotest |
| BioAegis Therapeutics |
| Melinta Therapeutics |
| Kyorin Pharmaceutical |
| C10 Pharma |
| Others |
Value Chain & Pricing Dynamics
Captive API manufacturing in vertically integrated pharmaceutical networks anchors both supply security and pricing power for branded antibiotic developers, while generic manufacturers remain exposed to Chinese import volatility and spot-market fermentation feedstock costs. FDA antimicrobial stewardship mandates and EMA pharmacovigilance tightening reward narrow-spectrum developers with formulary premium access, compressing margins for undifferentiated broad-spectrum alternatives.
Pricing Analysis
Short lead-time premiums attach to intravenous beta-lactam supplies for hospital emergency departments facing CMS readmission penalties, while spot inventory of oral macrolides trades at discount in retail pharmacy channels. Contract-based long-term offtake dominates pneumococcal vaccine procurement through national immunization tenders, with price differentiation driven by serotype coverage breadth and cold chain reliability certification. Cost compression in generic oral segments intensifies as Indian API exporters scale macrolide fermentation capacity, though hospital procurement committees show lowest price sensitivity for resistant-coverage intravenous therapies where clinical outcomes override acquisition cost.
Supply Chain Analysis
Penicillin and cephalosporin API supply rests on Yangtze River Delta fermentation clusters in China, with secondary concentration in Hyderabad and Ahmedabad pharmaceutical zones for generic finished-dose formulation. Key input dependencies include corn steep liquor for fermentation media, specialized enzyme catalysts for beta-lactam ring synthesis, and sterile packaging components for parenteral administration. Single-source vulnerability concentrates in Chinese heparin and intermediate chemical supply, exposing European and North American formulators to geopolitical disruption and quality audit failures. Distribution runs through hospital procurement consortia in Germany and group purchasing organizations in the United States, with emerging direct-to-pharmacy channels expanding in India's urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multiplex PCR diagnostic platforms are displacing empiric prescribing protocols across acute care settings, with regulatory pressure and resistance economics converging to reward precision over coverage breadth. Stakeholders must align portfolio investments with this technology-transition phase or face formulary exclusion.
For Market Incumbents: Lock in hospital formulary relationships through rapid diagnostic co-development partnerships that embed narrow-spectrum antibiotics into stewardship-compliant order sets. Prioritize backward integration into fermentation capacity for critical beta-lactam APIs to reduce exposure to Chinese supply concentration. Defend against biosimilar pneumococcal vaccine entrants by securing national immunization program tender extensions through pediatric-to-adult indication expansion.
For New Entrants and Emerging Players: Capture white-space opportunity in point-of-care molecular diagnostics for atypical organism detection, where emergency department adoption curves remain steep and incumbent diagnostic majors lack respiratory specialization. Target Sub-Saharan Africa vaccine distribution through public-private partnerships addressing cold chain infrastructure gaps. Deploy community pharmacy-based vaccination administration as the go-to-market angle, leveraging China's NMPA pilot programs and Germany's pharmacist prescriptive authority expansion.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-tier antibiotic developers possessing narrow-spectrum assets with FDA qualified infectious disease product designation and hospital formulary traction. Long-term viability favors platforms pairing diagnostic-therapeutic workflows over standalone generic manufacturers facing perpetual price erosion. Watch for inflection signals in EMA pharmacovigilance enforcement intensity and CMS quality metric expansion to oral step-down protocols.
| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Therapeutic Partnership | Emergency department multiplex PCR adoption in Boston-Cambridge biotech corridor compresses time-to-appropriate antibiotic selection. |
| API Manufacturing Scale-Up | Indian pharmaceutical special economic zones reduce import dependency on Chinese fermentation supply through production-linked incentive schemes. |
| Narrow-Spectrum Regulatory Pathway | FDA qualified infectious disease product designation accelerates review timelines for resistance-targeted antibiotics addressing unmet need. |
| Adult Vaccination Indication Expansion | Medicare Part D reimbursement broadening and China's NMPA approvals accelerate preventive uptake fastest among product categories. |
| Integrated Acute-Outpatient Pathway | CMS readmission penalty avoidance transfers patient volume from inpatient to home healthcare settings with oral step-down protocols. |
Study Parameters
Document review covered FDA antimicrobial stewardship guidance documents, EMA pharmacovigilance assessment reports, and ClinicalTrials.gov CAP trial registries, complemented by interviews with hospital formulary directors, infectious disease specialists, antibiotic development executives, and payer access specialists. Secondary validation drew from CMS Medicare cost reports, hospital procurement database extracts, and national immunization program coverage statistics across the United States, Germany, China, and India. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Cross-referencing historical prescribing pattern analysis against expert panel input on diagnostic adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, therapy area, delivery mode, and end user, with patient acuity scoring and regional regulatory cluster as additional stratifiers. CAGRs derived from elasticity-adjusted volume projections and price trajectory assumptions, incorporating antimicrobial resistance surveillance data and vaccine schedule expansion timelines as industry-specific forecast inputs.
The model holds under stable FDA and EMA regulatory enforcement intensity and continued Medicare Advantage penetration; deviation in Chinese API export restrictions or novel resistance outbreak patterns would shift therapeutic mix and pricing power assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Botulism Market
Infection Control
Antimicrobial Hospital Curtains Market
Infection Control
Healthcare Protective Masks Market
Infection Control
Intra Abdominal Infection Market
Infection Control
Air Sanitizer Market
Infection Control
Global Dental Infection Control Products Market
Infection Control
Intra-Amniotic Infection Treatment Market
Infection Control
Virus Filtration Market
Infection Control
Surgical Site Infections Market
Infection Control
United States Hand Sanitizer Market
Infection Control
Sterility Indicators Market
Infection Control
Global Disease Control and Prevention Vaccine Market
Infection Control
Global Pseudomonas Aeruginosa Infection Treatment Market
Infection Control
Biological and Chemical Indicators Market
Infection Control
UV Sterilizer Pouch Market
Infection Control
Denture Disinfectants Market