
 United Kingdom Nuclear Imaging Market | 2026-2036
United Kingdom Nuclear Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Nuclear Imaging Market Analytics
The gap between premium hybrid PET-MRI installations and legacy gamma camera fleets is consolidating around capital availability rather than clinical indication. Siemens Healthineers leverages its MAGNETOM integration pipeline to dominate the high-end installed base. GE Healthcare anchors its position through cyclotron-linked radiopharmaceutical supply chains. Alliance Medical competes via mobile imaging units that extend nuclear diagnostics into underserved NHS trusts.
Nuclear imaging deploys radiolabeled tracers detected by gamma cameras, SPECT, or PET scanners to visualize physiological function at molecular resolution, with spatial precision reaching 4-6 mm for F-18 FDG PET studies. Hybrid systems lead capital expenditure as NHS trusts prioritize one-stop diagnostic pathways for cancer staging. Oncology commands the largest application share, though cardiology PET for myocardial perfusion is gaining faster traction where rubidium-82 generator networks exist. Radioisotopes concentrate margin pools due to cyclotron dependency and short half-life logistics.
The Medicines and Healthcare products Regulatory Agency enforces Good Manufacturing Practice for radiopharmaceutical production, while the Ionising Radiation (Medical Exposure) Regulations govern dose optimization and operator certification. Care Quality Commission inspections shape market access by linking imaging service approvals to tracer audit trails and equipment calibration records. Stakeholders must weigh cyclotron ownership against generator-based isotope sourcing as NHS England centralizes procurement frameworks.
Market Dynamics
NHS England's diagnostic capacity expansion is compressing procurement timelines while concentrating purchasing power around integrated PET-CT and PET-MRI systems. Trust-level capital constraints are fragmenting the installed base between teaching hospitals with cyclotron access and district general hospitals dependent on generator-based isotope supply.
Growth Catalysts
- IR(ME)R dose optimization mandates:The Ionising Radiation (Medical Exposure) Regulations are accelerating replacement of legacy gamma cameras with digital SPECT systems that reduce administered tracer volumes.
- Oncology referral networks:London and South East teaching hospitals are anchoring regional hubs that concentrate complex cancer staging demand and justify hybrid scanner capital investment.
- Radiopharmaceutical traceability standards:Updated Medicines and Healthcare products Regulatory Agency guidance on Good Manufacturing Practice compliance is standardizing procurement specifications across NHS trusts.
Market Restraints
- Cyclotron ownership concentration:Short half-life isotope logistics tether procurement decisions to a handful of radiopharmaceutical production sites, limiting trust-level sourcing flexibility.
- Capital intensity of hybrid systems:PET-MRI installations require dedicated shielded suites and helium infrastructure, compressing eligible trust pools to those with estate development capacity.
- Skill pipeline constraints:The Society of Radiographers reports persistent vacancies in nuclear medicine technologist roles, particularly outside London.
Strategic Opportunities
- Mobile imaging deployment:Unserved NHS trusts in the North East and Wales present white space for fleet-based SPECT services that circumvent fixed-site capital barriers.
- Cardiology PET expansion:Rubidium-82 generator networks are enabling myocardial perfusion imaging adoption where cyclotron proximity previously excluded cardiac applications.
- Care Quality Commission inspection alignment:Tracer audit trail requirements are creating first-mover advantage for suppliers with integrated pharmacy management systems.
Industry Challenges
- Technologist certification bottlenecks:Post-registration nuclear medicine training capacity lags scanner installation rates, stretching existing workforce across expanded operating hours.
- Legacy equipment integration:PACS connectivity standards vary across NHS trust IT estates, complicating hybrid scanner deployment in hospitals with fragmented imaging archives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Nuclear Imaging Market |
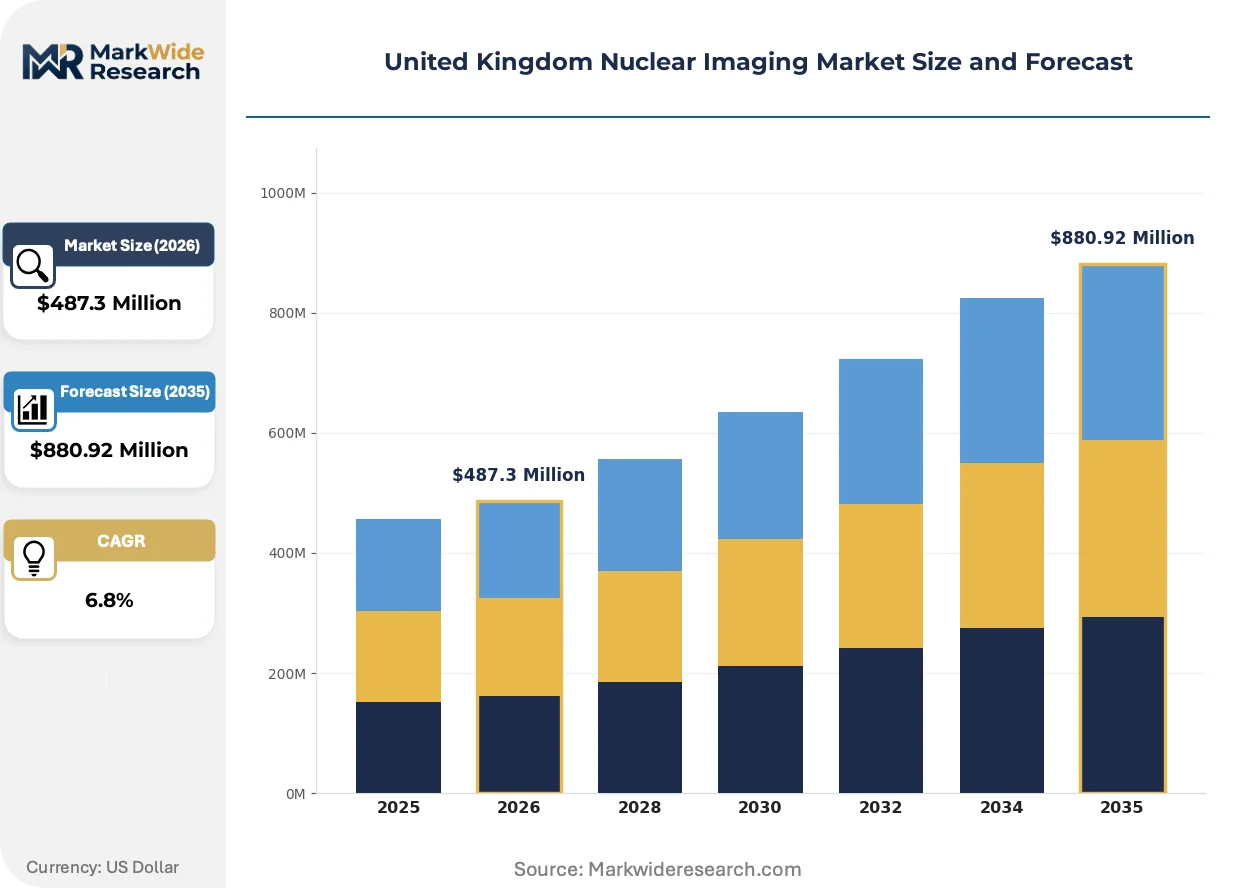
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Single Photon Emission Computed Tomography, Positron Emission Tomography, Hybrid Systems, Gamma Cameras End User: Hospitals, Diagnostic Imaging Centers, Research Institutions, Home Healthcare Application: Oncology, Cardiology, Neurology, Infectious Diseases Product Type: Radioisotopes, Contrast Agents, Imaging Software, Accessories |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips N.V., Canon Medical Systems Corporation, Curium Pharma, Bracco Imaging S.p.A., Alliance Medical, Fujifilm Holdings Corporation, Cardinal Health Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Nuclear Imaging Market Evolving Landscape
Digital detector technology and artificial intelligence reconstruction algorithms are compressing scan durations while expanding the addressable patient population beyond traditional BMI and mobility limits.
Digital SPECT systems with cadmium-zinc-telluride detectors are decentralizing nuclear imaging service delivery by enabling point-of-care tracer administration in ambulatory settings. Community diagnostic centres in England are adopting these systems to redirect non-urgent oncology referrals from acute hospital sites. The structural consequence is a fragmentation of the traditional hospital-centric imaging model toward distributed same-day diagnostic pathways.
The Medicines and Healthcare products Regulatory Agency's updated guidance on radiopharmaceutical batch release testing is tightening quality assurance timelines for cyclotron-based production facilities. Manufacturers must now submit enhanced stability data for novel tracers seeking clinical trial authorization. Early-phase PET radiopharmaceutical developers are responding by consolidating manufacturing partnerships with established GMP-certified sites rather than building captive production capacity.
Trust-level procurement is consolidating around framework agreements that bundle scanner hardware, maintenance, and isotope supply into single-source contracts. NHS Supply Chain's national imaging framework is displacing trust-level tendering for gamma camera and SPECT purchases. The shift is most pronounced in the Midlands and North West, where integrated care boards are harmonizing equipment specifications across constituent trusts to secure volume discounts and standardize training pathways.
United Kingdom Nuclear Imaging Market Segmentation
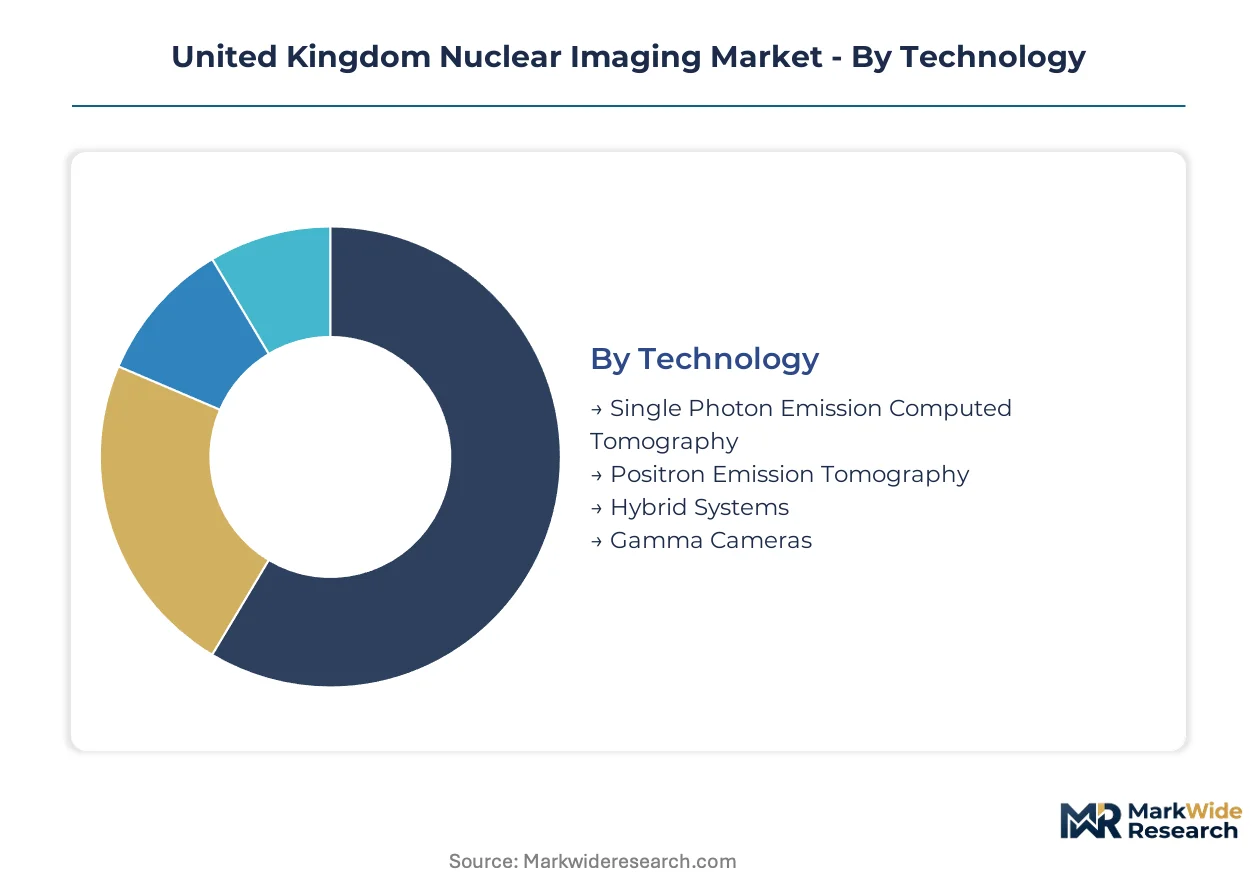
Technology choices in UK nuclear imaging lock in decade-long capital cycles and determine radiopharmaceutical sourcing flexibility. End-user concentration around NHS trusts shapes procurement scale and service delivery models across regions.
Technology:
The customization-vs-standardization spectrum spans from configurable hybrid PET-MRI platforms to commodity gamma camera configurations with limited upgrade paths.
- Hybrid Systems:PET-CT and PET-MRI platforms integrate anatomical and functional imaging into unified diagnostic pathways. Demand concentrates in London teaching hospitals and South East oncology hubs where complex cancer staging justifies shielded suite investments and cyclotron proximity.
- Positron Emission Tomography:Standalone PET scanners deploy F-18 FDG and novel tracers for metabolic imaging at 4-6 mm spatial resolution. NHS England diagnostic capacity expansion is accelerating digital detector replacements in Midlands and North West trusts seeking one-stop oncology pathways.
- Single Photon Emission Computed Tomography:Digital SPECT with cadmium-zinc-telluride detectors enables reduced tracer dosing under IR(ME)R optimization mandates.
- Gamma Cameras:Legacy Anger camera technology persists in district general hospitals with constrained capital budgets and generator-based isotope supply.
Most installed capacity flows through Gamma Cameras. Expansion is steepest in Hybrid Systems.
End User:
Customer concentration determines procurement leverage, with centralized NHS frameworks displacing trust-level tendering for hardware and isotope bundles.
- Hospitals:Acute NHS trusts with oncology departments anchor regional referral networks and concentrate PET-CT demand. London and South East teaching hospitals drive hybrid scanner procurement through specialized cancer staging pathways.
- Diagnostic Imaging Centers:Community diagnostic centres in England are redirecting non-urgent oncology referrals from acute sites. These facilities favor digital SPECT systems for same-day tracer administration in ambulatory settings.
- Research Institutions:Early-phase PET radiopharmaceutical developers partner with GMP-certified cyclotron sites for clinical trial authorization.
- Home Healthcare:Mobile imaging units extend nuclear diagnostics into underserved NHS trusts in North East and Wales.
Procurement volume concentrates in Hospitals. Service model innovation is expanding fastest in Diagnostic Imaging Centers.
Application:
Clinical indication shapes tracer selection, with oncology commanding capital priority and cardiology gaining ground where rubidium-82 generator networks reduce cyclotron dependency.
- Oncology:Cancer staging and treatment response monitoring consume the largest share of PET-CT capacity. F-18 FDG dominates tracer utilization across London and South East regional hubs.
- Cardiology:Myocardial perfusion imaging is climbing the fastest where rubidium-82 generator supply eliminates cyclotron proximity requirements.
- Neurology:Amyloid and tau tracers for dementia diagnosis face constrained adoption pending NICE reimbursement clarity.
- Infectious Diseases:WBC labeling and FDG-PET for device-related infections serves niche demand in tertiary referral centers.
Oncology absorbs the majority of installed scanner hours. Cardiology is gaining share fastest as generator-based isotopes expand addressable sites.
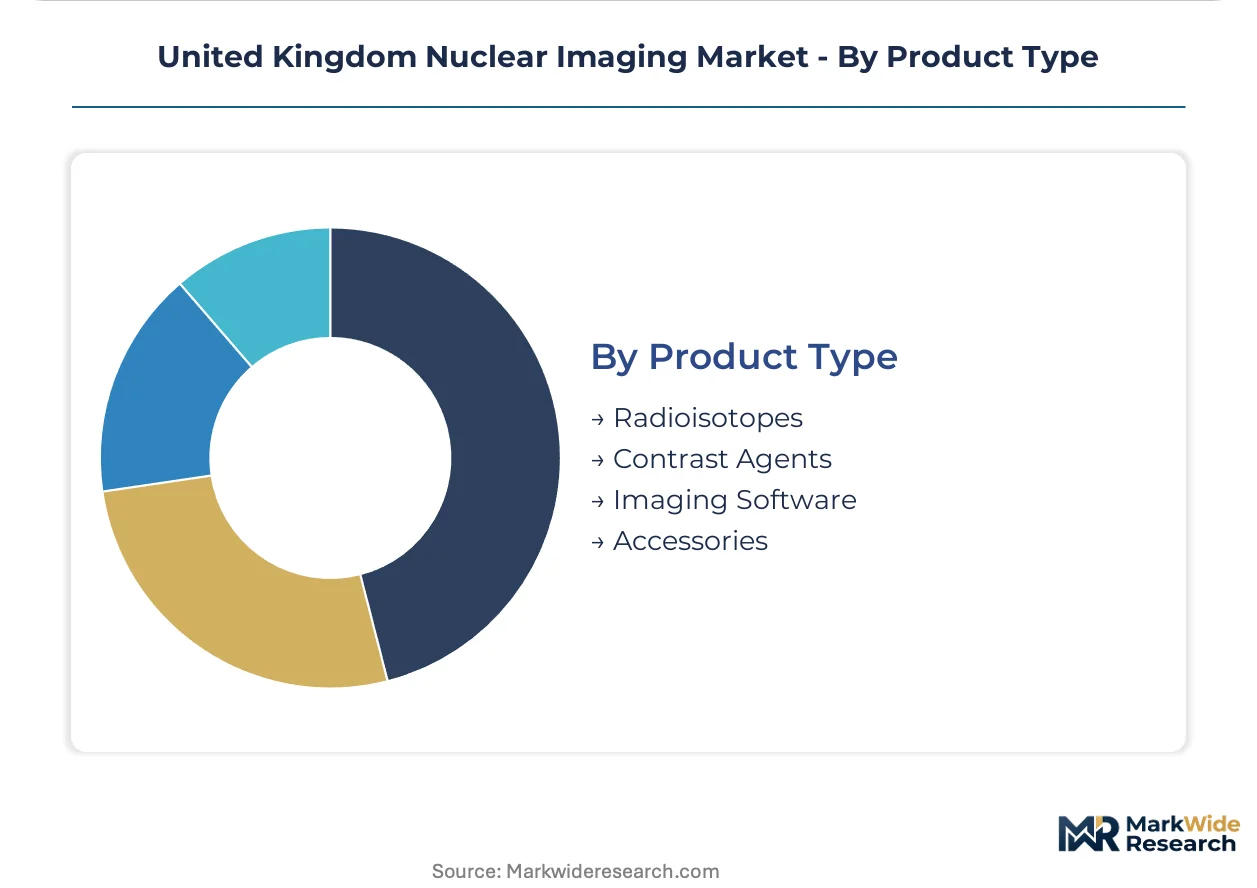
Product Type:
Margin concentration follows supply chain control, with cyclotron-dependent radioisotopes capturing value upstream of hardware and software.
- Radioisotopes:Short half-life logistics tether procurement to cyclotron ownership or generator supply contracts. F-18 FDG production concentrates at GMP-certified sites serving multiple NHS trusts.
- Imaging Software:AI reconstruction algorithms and PACS integration modules compress scan durations and expand patient eligibility beyond traditional BMI limits.
- Contrast Agents:Non-radioactive adjuncts for hybrid imaging protocols serve secondary demand in CT-correlated studies.
- Accessories:Shielded syringes, dose calibrators, and quality assurance phantoms complete procurement bundles under NHS Supply Chain frameworks.
Value capture concentrates in Radioisotopes. Software is expanding most quickly as digital detector deployment accelerates reconstruction algorithm adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's concentration of nuclear medicine technologists and radiopharmaceutical chemists anchors the United Kingdom's diagnostic imaging workforce, with regional disparities in specialist availability shaping procurement patterns across NHS trusts.
London and South East
Oncology referral networks concentrate PET-CT demand at teaching hospitals with cyclotron access. NHS England's diagnostic capacity expansion prioritizes hybrid scanner procurement in this corridor. The Royal Marsden and Guy's and St Thomas' anchor regional hubs that justify shielded suite investments.
Midlands
Integrated care boards harmonize equipment specifications across constituent trusts to secure volume discounts. The Care Quality Commission's inspection regime links imaging service approvals to tracer audit trails. Birmingham and Nottingham clusters drive standardization of digital SPECT deployment.
North West
Manchester's Christie Hospital anchors radiopharmaceutical production serving multiple NHS trusts. NHS Supply Chain's national imaging framework displaces trust-level tendering for gamma camera purchases. Liverpool and Leeds concentrate generator-based isotope distribution networks.
Scotland
NHS Scotland's centralized procurement concentrates PET capacity at Glasgow and Edinburgh teaching hospitals. The Ionising Radiation (Medical Exposure) Regulations drive replacement of legacy Anger cameras with digital detector systems. Aberdeen anchors north-of-England referral overflow.
Wales and North East
Underserved trusts present white space for mobile imaging units extending SPECT diagnostics beyond fixed-site infrastructure. Alliance Medical's fleet-based services circumvent capital barriers in Cardiff and Newcastle. Workforce vacancies in nuclear medicine technologist roles persist outside London.
United Kingdom Nuclear Imaging Market Competitive Landscape
Top-tier vendors anchor the high-end hybrid scanner segment, while mid-tier specialists and mobile service providers occupy distinct competitive strata. The vendor base stratifies across cyclotron-linked radiopharmaceutical suppliers, integrated hardware-software platforms, and fleet-based diagnostic services. Two strategic archetypes dominate: manufacturers controlling upstream isotope production and operators extending reach through asset-light deployment models. Consolidation pressures favor bundled procurement frameworks, while technology licensing agreements accelerate digital detector adoption.
Among Germany-based conglomerates with healthcare divisions, Siemens Healthineers occupies a position exemplifying integrated PET-MRI platform dominance. GE Healthcare and Koninklijke Philips N.V. represent the tier of vendors anchoring cyclotron-linked supply chain control. Alliance Medical sits within the mobile imaging archetype, extending nuclear diagnostics into capital-constrained NHS trusts through fleet deployment rather than fixed-site infrastructure ownership.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| Curium Pharma |
| Bracco Imaging S.p.A. |
| Alliance Medical |
| Fujifilm Holdings Corporation |
| Cardinal Health Inc. |
| Others |
Value Network & Pricing Analysis
Digital detector deployment in SPECT systems is compressing per-scan cost structures while simultaneously concentrating procurement leverage around NHS Supply Chain framework agreements that bundle hardware, maintenance, and isotope supply into single-source contracts. This technological shift rewards vendors with integrated pharmacy management systems and cyclotron-linked radiopharmaceutical networks, while fragmenting pricing power among standalone equipment suppliers lacking upstream isotope control.
Pricing Analysis
Bundle-unbundle service splits dominate UK nuclear imaging procurement, with NHS trusts increasingly favoring all-inclusive contracts covering scanner hardware, preventive maintenance, and guaranteed isotope availability over capital-only purchases. Price differentiation hinges on cyclotron proximity and GMP certification tier, with trusts in London and the South East commanding premium positioning through teaching hospital networks while district general hospitals in the North East and Wales face sharper cost compression due to generator dependency and mobile service reliance. Pricing pressure stems from NHS England's diagnostic capacity expansion centralizing purchasing power around integrated care boards. District general hospitals exhibit highest price sensitivity, constrained by estate development limitations and capital budget fragmentation.
Supply Chain Analysis
GMP certification gating from the Medicines and Healthcare products Regulatory Agency restricts radiopharmaceutical production to a handful of cyclotron-equipped facilities concentrated in England, with secondary sourcing from Belgium and the Netherlands for certain isotope types. Raw material dependencies center on enriched uranium targets for Mo-99 generators, F-18 precursor chemicals, and helium for MRI cooling infrastructure. Single-source vulnerability pervades the rubidium-82 generator segment, where one dominant supplier anchors cardiac PET expansion. Distribution runs through NHS Supply Chain's national imaging framework, displacing trust-level tendering and harmonizing specifications across integrated care boards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom nuclear imaging market functions as a regulatory compounder, where IR(ME)R dose optimization mandates and MHRA traceability standards continuously elevate compliance costs and consolidate procurement around certified suppliers.
For Market Incumbents: Hedge cyclotron ownership concentration by securing generator-based isotope partnerships that extend service reach beyond fixed-site infrastructure. Diversify into digital SPECT platforms with cadmium-zinc-telluride detectors to capture community diagnostic centre expansion. Threats from mobile imaging operators and AI reconstruction software vendors demand defensive certification investments in integrated pharmacy management systems. For New Entrants and Emerging Players: Underserved NHS trusts in Wales and the North East present immediate white-space opportunity for fleet-based SPECT deployment circumventing capital-intensive fixed-site requirements. Cardiology PET applications using rubidium-82 generators offer the most penetrable clinical segment, bypassing cyclotron proximity barriers that constrain oncology-focused competitors. A direct contracting model with integrated care boards, bypassing fragmented trust-level procurement, accelerates market access. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier radiopharmaceutical distributors lacking captive cyclotron capacity but possessing established GMP-certified site relationships. Long-term viability across the projection horizon hinges on backward integration into isotope production or forward integration into AI-enabled reconstruction software. Monitor NICE reimbursement decisions for amyloid and tau tracers in neurology as the critical inflection signal for dementia imaging market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Partnership Consolidation | GE Healthcare and Curium Pharma anchor radiopharmaceutical supply security through multi-trust production site networks. |
| Mobile Imaging Fleet Expansion | Alliance Medical extends diagnostic reach into capital-constrained regions without fixed-site infrastructure investment. |
| Digital Detector Platform Launch | Siemens Healthineers' cadmium-zinc-telluride SPECT systems reduce tracer dosing while expanding patient eligibility. |
| AI Reconstruction Software Development | Compressed scan durations from algorithmic image processing expand addressable patient volumes beyond traditional BMI limits. |
| Integrated Care Board Framework Alignment | NHS Supply Chain national imaging framework harmonization secures volume commitments across Midlands and North West trusts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with NHS trust procurement directors, nuclear medicine consultants, radiopharmaceutical production managers, and Society of Radiographers workforce analysts with secondary validation against MHRA guidance documents, NHS England diagnostic capacity reports, Care Quality Commission inspection records, and Ionising Radiation (Medical Exposure) Regulations compliance databases. Bottom-up equipment installation tracking and top-down healthcare expenditure analysis were triangulated against cyclotron production capacity estimates.
Segment-weighting approaches distributed value across technology tiers, end-user concentration levels, and clinical application intensity, with hybrid systems, standalone PET, digital SPECT, and legacy gamma cameras modeled separately across hospital, diagnostic imaging centre, research institution, and home healthcare delivery models. CAGRs were derived from equipment replacement cycles, radiopharmaceutical consumption trajectories, and workforce expansion constraints. Forecast inputs incorporated NHS capital budget allocations, IR(ME)R compliance timelines, and cyclotron construction pipelines.
Inputs from NHS trust finance directors and radiopharmaceutical suppliers were available through the study window; gaps in real-time workforce vacancy data and confidential framework pricing introduce uncertainty bands around medium-term penetration assumptions. Forecasts reflect documented assumptions regarding NHS estate development capacity and MHRA regulatory stability. A model refresh is warranted upon material change in NICE reimbursement determinations for novel neurology tracers or NHS England procurement centralization policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global 3D Laparoscopy Imaging Market
Medical Imaging
Dermatology Imaging Market
Medical Imaging
Asia-Pacific Fluoroscopy Market
Medical Imaging
Open Magnetic Resonance Imaging System Market
Medical Imaging
North America Digital Pathology Market
Medical Imaging
Australia Mammography Market
Medical Imaging
Asia Pacific Computed Tomography (CT) Market
Medical Imaging
Enterprise Medical Image Viewers Market
Medical Imaging
Global Digital Subtraction Angiography Market
Medical Imaging
China Diagnostic Imaging Equipment Market
Medical Imaging
Canada Computed Tomography Market
Medical Imaging
Global MRI Scanner Market
Medical Imaging
Australia Digital Radiology Market
Medical Imaging
Global Veterinary Diagnostic Imaging Market
Medical Imaging
Medical Videoscope Market
Medical Imaging
North America Nuclear Medicine Market