
 Africa Magnetic Resonance Imaging (MRI) Market | 2026-2036
Africa Magnetic Resonance Imaging (MRI) Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Magnetic Resonance Imaging (MRI) Market Outlook
Project finance and equipment leasing is fragmenting the competitive landscape for MRI deployment across Africa. GE Healthcare leverages its established service infrastructure to sustain long-term maintenance contracts in East African markets. Siemens Healthineers anchors its position through localized technical training programs that reduce dependence on expatriate engineers. Koninklijke Philips differentiates by offering refurbished systems that lower capital barriers for mid-tier hospitals.
Magnetic Resonance Imaging deploys superconducting magnets cooled by liquid helium to generate high-resolution anatomical images using radiofrequency pulses and magnetic field gradients, typically operating at 1.5 to 3.0 Tesla for clinical diagnostics. The technology serves primarily to detect soft-tissue pathologies including brain tumors, spinal disorders, and joint injuries without ionizing radiation exposure. Closed MRI systems dominate installed base volumes due to superior image quality and field strength, while open-architecture designs capture growing demand from claustrophobic patients and bariatric cases. Superconducting technology leads the technology segment by performance tier, though permanent magnet systems retain relevance in markets with unreliable helium supply chains.
South Africa's Health Products Regulatory Authority enforces medical device registration that shapes import timelines and compliance costs for equipment vendors. Egypt's drug authority and Nigeria's national agency for food and drug administration control apply parallel standards that fragment market access requirements across North and West Africa. The World Health Organization's essential diagnostics list influences national procurement priorities and public budget allocations. Stakeholders must monitor how divergent national regulatory timelines affect multi-country service scale and capital deployment sequencing.
Market Dynamics
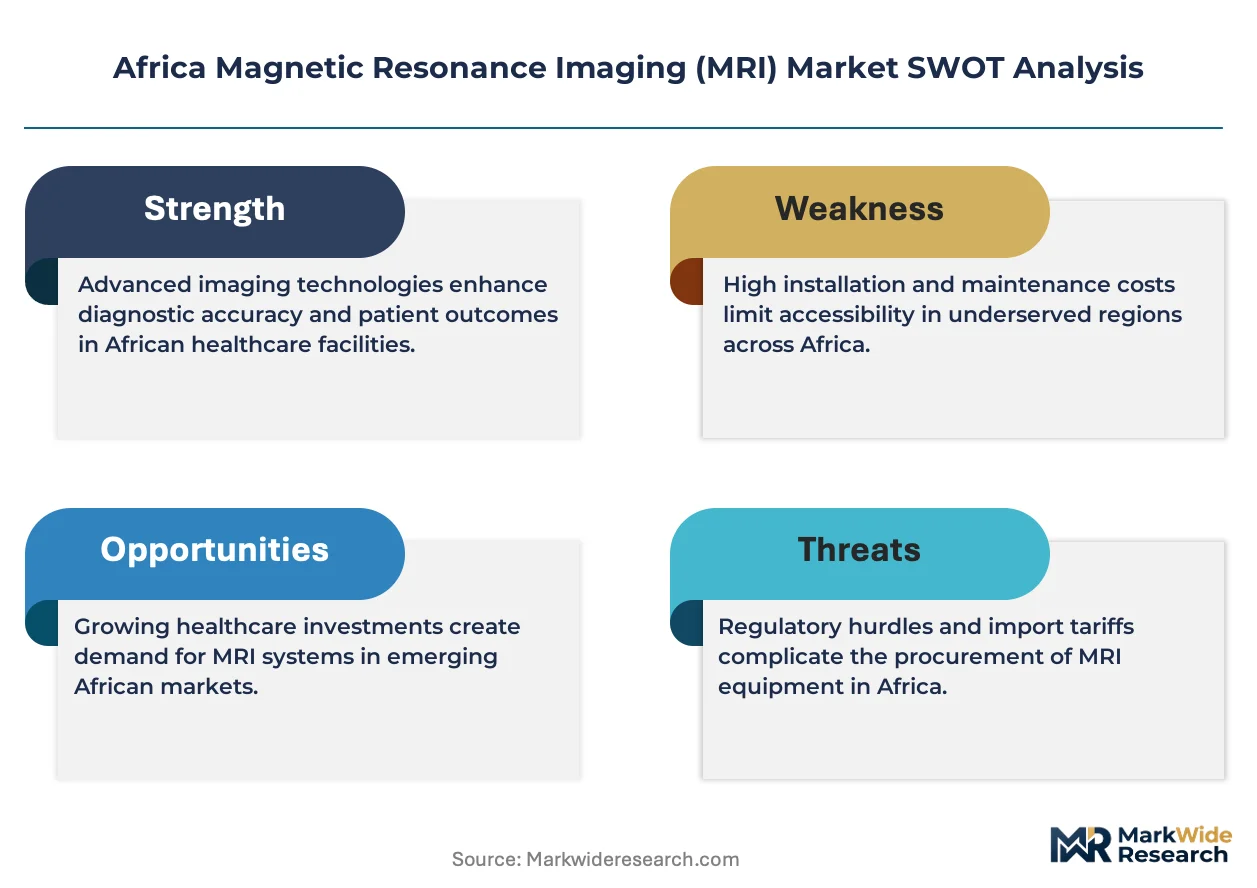
Helium supply fragility across Africa is forcing equipment vendors to reconfigure magnet cooling architectures and service logistics, compressing procurement timelines for public hospital networks while elevating total cost of ownership calculations.
Growth Catalysts
- WHO Essential Diagnostics List:National health ministries in Nigeria and Egypt prioritize MRI procurement within essential diagnostics frameworks, channeling public budget allocations toward magnetic resonance infrastructure.
- Project Finance Structures:Equipment leasing arrangements reduce upfront capital barriers for mid-tier hospitals across sub-Saharan Africa, accelerating deployment velocity beyond traditional purchase models.
- Tertiary Hospital Networks:Nigeria's federal teaching hospitals expand diagnostic imaging capacity to reduce outbound medical tourism, creating concentrated demand clusters in Lagos and Abuja.
Market Restraints
- Helium Supply Volatility:Liquid helium procurement depends on concentrated global suppliers with limited African distribution infrastructure, exposing operators to price shocks and maintenance interruptions.
- Regulatory Fragmentation:Divergent registration timelines between South Africa's Health Products Regulatory Authority and Nigeria's national food and drug administration multiply compliance costs for multi-country vendors.
- Permanent Magnet Performance Ceiling:Lower-field permanent magnet systems sacrifice diagnostic resolution compared to superconducting alternatives, limiting clinical applicability for neurological and oncological imaging.
Strategic Opportunities
- Refurbished System Channels:Pre-owned 1.5 Tesla installations from European and North American retirement pools address capital constraints for Egypt's private diagnostic center expansion.
- Helium-Free Magnet Architectures:Conduction-cooled superconducting and permanent magnet innovations eliminate cryogenic dependency, enabling reliable operation in markets with fragile cold chain logistics.
- Localized Technical Training:Vendor-operated engineering certification programs reduce reliance on expatriate service personnel, compressing mean time to repair and lowering lifecycle service costs.
Industry Challenges
- Biomedical Engineering Shortage:Sub-Saharan Africa lacks accredited training programs for MRI system maintenance, forcing operators to absorb premium costs for foreign technician deployment.
- Legacy Equipment Integration:Picture archiving and communication systems from disparate manufacturers create interoperability friction when hospitals upgrade from CT or ultrasound to magnetic resonance workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Magnetic Resonance Imaging (MRI) Market |
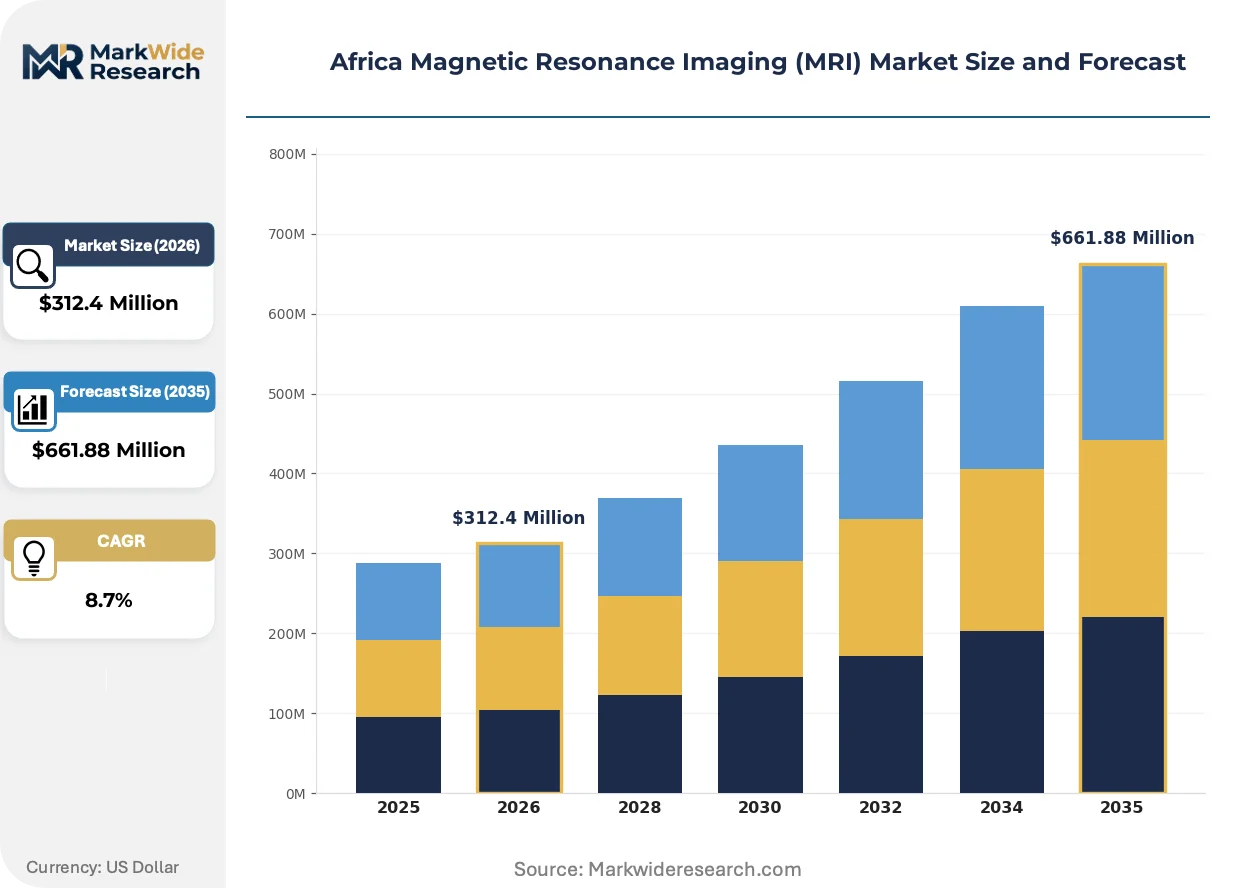
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Extremity MRI, Functional MRI Technology: Superconducting, Permanent Magnet, Open-architecture, High-field End User: Hospitals, Diagnostic Centers, Research Institutions, Clinics Application: Neurology, Oncology, Cardiology, Musculoskeletal |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips, Canon Medical Systems, FUJIFILM Healthcare, Hitachi, Neusoft Corporation, Stryker Corporation, Mindray Medical International, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Magnetic Resonance Imaging (MRI) Market Strategic Shifts
Magnetic resonance technology across Africa is converging toward operational resilience models that prioritize uptime assurance over peak performance specifications, reflecting infrastructure constraints that shape vendor product roadmaps.
Helium-recapture closed-loop cooling is hybridizing conventional superconducting magnet architectures with cryogenic conservation systems. Private diagnostic chains in Cairo and Johannesburg pilot these configurations to hedge against supply disruption. The technology is hybridizing service contract structures toward guaranteed-uptime pricing rather than time-and-materials billing.
South Africa's Health Products Regulatory Authority tightened medical device registration requirements, extending import approval timelines and mandating local adverse event reporting infrastructure. Equipment vendors now pre-position regulatory affairs personnel in Cape Town to navigate documentation complexity. High-field 3.0 Tesla systems face elongated approval cycles compared to 1.5 Tesla workhorse configurations.
Public hospital procurement committees increasingly unbundle equipment acquisition from multi-year service agreements, negotiating maintenance contracts separately through competitive tender. Egypt's Ministry of Health and Population piloted this separation for Cairo University Hospital's recent installation. Nigeria's federal medical centers are adopting the same unbundled approach, compressing vendor margin structures while expanding third-party service provider entry.
Africa Magnetic Resonance Imaging (MRI) Market Segmentation
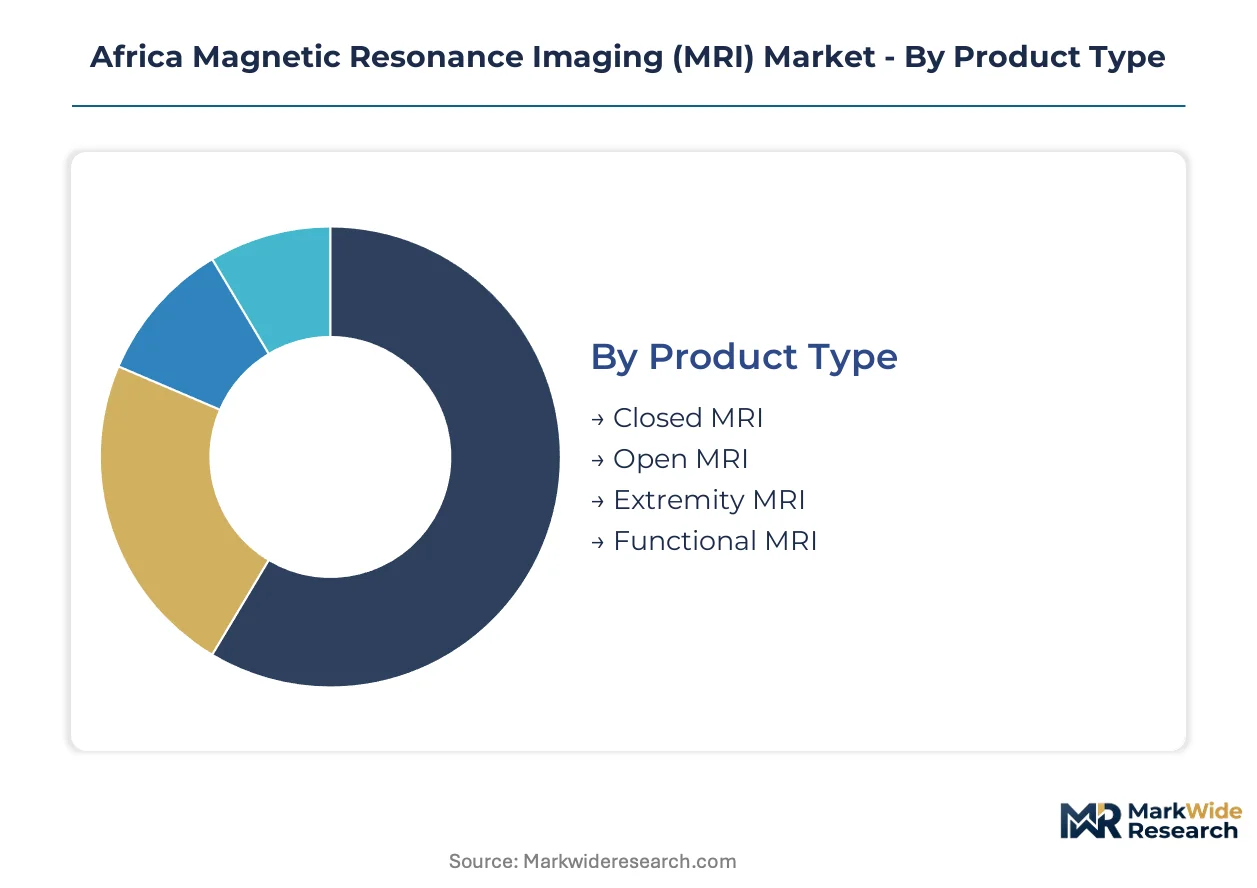
Segmentation across the Africa MRI market reveals how infrastructure constraints, clinical priorities, and capital availability fragment procurement patterns. Equipment specifications and end-user economics diverge sharply between South Africa's tertiary networks and Nigeria's emerging diagnostic chains.
Product Type:
Mature closed-bore configurations dominate installed capacity, while emerging open-architecture designs address accessibility gaps in claustrophobic and bariatric populations.
- Closed MRI:Cylindrical superconducting magnets operating at 1.5 to 3.0 Tesla deliver superior signal-to-noise ratios for neurological and oncological diagnostics. Demand concentrates in South Africa's academic medical centers and Egypt's private hospital chains where throughput volume justifies capital intensity.
- Open MRI:Vertical-field or C-arm architectures eliminate patient enclosure, expanding access for pediatric cases and patients with anxiety disorders. Nigeria's federal teaching hospitals in Lagos and Abuja prioritize these configurations to reduce referral leakage and capture diagnostic volume locally.
- Extremity MRI:Dedicated limb-only systems with lower field strength target orthopedic and rheumatology workflows in high-volume outpatient settings.
- Functional MRI:Blood-oxygen-level-dependent imaging sequences map neural activation patterns for pre-surgical planning in specialized neurosurgical units.
Closed MRI retains volume leadership; Open MRI holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium superconducting installations from mid-market permanent magnet alternatives suited to unreliable helium logistics.
- Superconducting:Niobium-titanium coils cooled by liquid helium enable stable high-field operation at 1.5 Tesla and above. Egypt's Ministry of Health and Population channels procurement toward these systems for Cairo University Hospital and affiliated tertiary centers.
- Permanent Magnet:Ferrite or rare-earth magnetic assemblies operate without cryogenic cooling, sacrificing field strength for operational resilience. Smaller diagnostic centers in sub-Saharan markets with fragile cold chains adopt these configurations to eliminate helium dependency.
- Open-architecture:Low-field vertical designs using resistive or permanent magnet cores prioritize patient comfort over resolution.
- High-field:3.0 Tesla and above configurations target research applications and complex neurovascular imaging in South Africa's academic health complexes.
Superconducting technology captures the premium tier; permanent magnet systems are gaining share fastest in capital-constrained markets.
End User:
Customer type determines procurement modality, with public hospitals favoring unbundled equipment acquisition and private chains negotiating integrated service contracts.
- Hospitals:Tertiary and secondary acute care facilities constitute the dominant installation base across North and West Africa. Nigeria's federal medical centers in Kaduna, Ibadan, and Enugu expand MRI capacity to stem outbound medical tourism to India and the Middle East.
- Diagnostic Centers:Standalone imaging chains concentrate equipment utilization across multiple referring physicians. Private operators in Cairo and Johannesburg deploy refurbished 1.5 Tesla systems to compress payback periods.
- Research Institutions:University-affiliated medical schools prioritize high-field systems for clinical trial enrollment and radiology resident training.
- Clinics:Small-format facilities with limited capital access deploy extremity-only or low-field systems for niche orthopedic applications.
Hospitals retain volume leadership; diagnostic centers hold the steepest expansion curve.
Application:
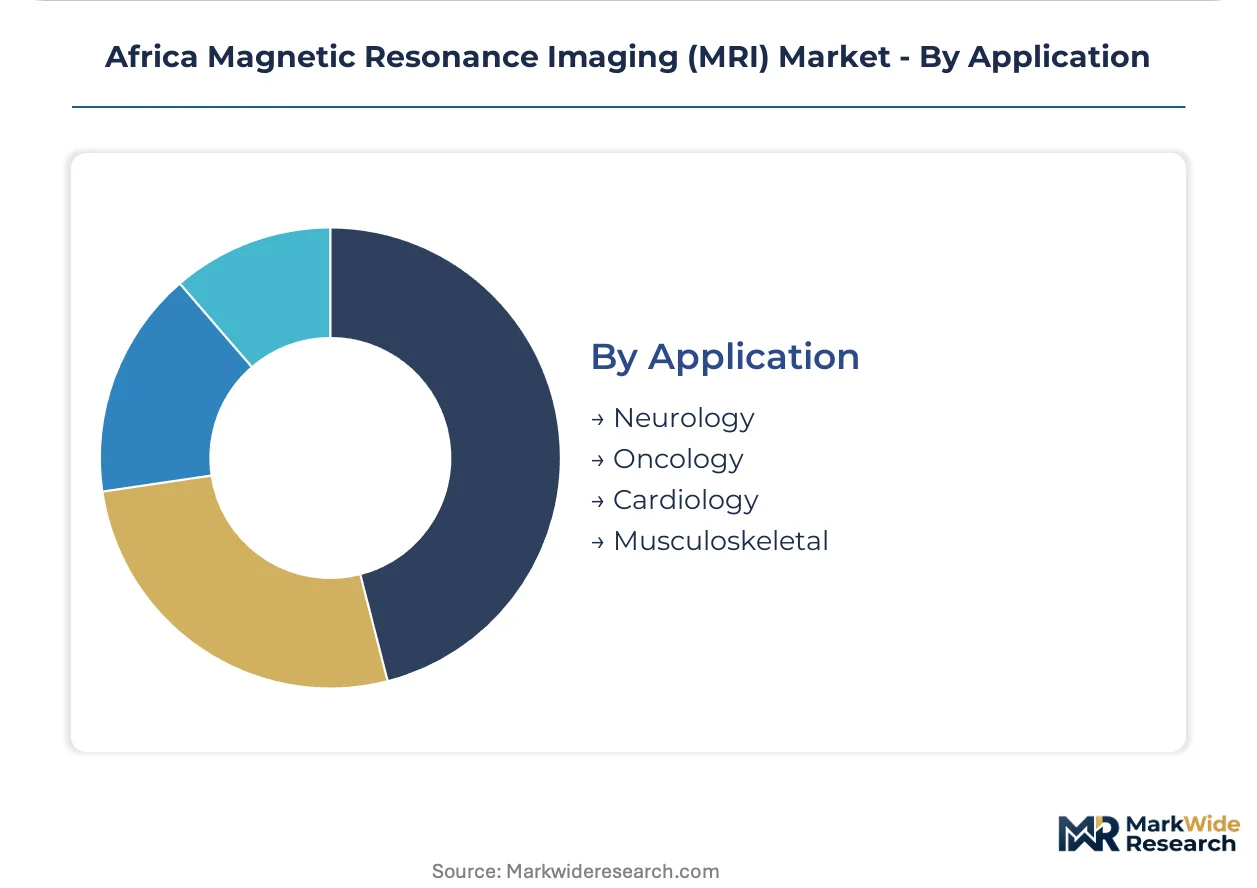
Clinical volume concentrates in neurology and oncology where MRI's soft-tissue contrast advantage displaces CT and ultrasound alternatives.
- Neurology:Brain parenchyma imaging for tumor characterization, stroke protocol, and demyelinating disease monitoring commands the largest procedure volume. South Africa's Groote Schuur Hospital and Red Cross Children's Hospital anchor demand for advanced neuroimaging sequences.
- Oncology:Staging and treatment response assessment for solid tumors drives 1.5 Tesla procurement in Egypt's National Cancer Institute network.
- Cardiology:Delayed-enhancement and stress-perfusion protocols for ischemic and non-ischemic cardiomyopathy evaluation.
- Musculoskeletal:Ligament, meniscal, and cartilage assessment for sports medicine and rheumatology referrals.
Neurology retains volume leadership; oncology holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National procurement frameworks and tertiary hospital expansion programs are redistributing MRI capacity across the continent's major healthcare systems. Public budget allocations increasingly prioritize diagnostic imaging infrastructure within universal health coverage schemes.
South Africa
Groote Schuur Hospital and Red Cross Children's Hospital anchor demand for advanced neuroimaging sequences in the Western Cape. The Health Products Regulatory Authority enforces extended import approval timelines for 3.0 Tesla configurations. Johannesburg's private diagnostic chains pilot helium-recapture cooling systems to hedge against supply disruption.
Egypt
The National Cancer Institute network drives 1.5 Tesla procurement for oncology staging and treatment response assessment. The country's drug authority applies parallel registration standards that shape vendor market access timelines. Cairo's private diagnostic center sector deploys refurbished European systems to compress capital payback periods.
Nigeria
Federal teaching hospitals in Lagos and Abuja expand capacity to reduce outbound medical tourism to India and the Middle East. The national agency for food and drug administration control fragments compliance requirements against regional counterparts. Kaduna, Ibadan, and Enugu medical centers adopt unbundled procurement separating equipment from service contracts.
Kenya
Moi Teaching and Referral Hospital and Kenyatta National Hospital anchor public diagnostic imaging demand in the East African Community hub. The national medical regulator aligns with WHO essential diagnostics list priorities for budget allocation. Nairobi's emerging private hospital chains negotiate integrated equipment-service contracts with established vendor service infrastructure.
Morocco
Royal University Hospital centers in Rabat and Casablanca concentrate high-field system demand for clinical trial enrollment. The national drug and health products safety agency harmonizes registration timelines with European Medicines Agency reference standards. Marrakech's medical tourism corridor attracts diagnostic center investment targeting sub-Saharan patient flows.
Africa Magnetic Resonance Imaging (MRI) Market Competitive Environment
On the supply side, the industry is consolidating around three strategic archetypes: integrated multinationals with captive service infrastructure, regional specialists leveraging refurbished equipment channels, and emerging Asian manufacturers competing on capital cost compression. Established players defend position through localized technical training programs and long-term maintenance contracts. Competitive moves center on unbundling service agreements from equipment sales and deploying helium-free magnet architectures to address operational fragility in target markets.
Within the integrated multinational tier, GE Healthcare, Siemens Healthineers, and Koninklijke Philips occupy positions defined by service infrastructure depth and regulatory navigation capabilities. GE Healthcare anchors its presence through established maintenance networks across East African markets. Siemens Healthineers exemplifies the training-centric archetype with localized engineering certification programs. Koninklijke Philips represents the capital-access strategy through refurbished system channels that lower barriers for mid-tier hospital procurement.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips |
| Canon Medical Systems |
| FUJIFILM Healthcare |
| Hitachi |
| Neusoft Corporation |
| Stryker Corporation |
| Mindray Medical International |
| Others |
Value Chain & Pricing Dynamics
Port of Durban container corridors absorb premium freight costs that compound helium logistics fragility, forcing Egyptian private diagnostic chains and Nigerian federal hospitals into divergent procurement strategies. South Africa's Health Products Regulatory Authority compliance overhead layers onto landed equipment costs, compressing margins for mid-tier installations while amplifying price spreads between refurbished European systems and new 3.0 Tesla configurations.
Pricing Analysis
Certification level (ISO/CE/FDA-grade) creates the primary spread between premium superconducting installations and mid-market permanent magnet alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects field strength differentiation, after-sales bundling, and local adverse event reporting infrastructure requirements. Pricing pressure stems from public hospital procurement committees unbundling equipment acquisition from multi-year service agreements. Nigeria's federal medical centers exhibit highest price sensitivity due to budget fragmentation across state and federal funding streams, while Egypt's private diagnostic chains absorb premium positioning for faster payback through volume utilization.
Supply Chain Analysis
Contract manufacturing for MRI subsystems concentrates in Germany, the Netherlands, and China, with superconducting wire production anchored in Japanese and American specialty metal foundries. Liquid helium sourcing draws from Algerian and Qatari industrial gas suppliers, creating single-source vulnerability for East African operators dependent on Johannesburg redistribution hubs. Distribution runs through vendor-direct sales organizations for premium installations, while refurbished European equipment channels feed Egyptian and Nigerian mid-tier demand through Dubai-based trading intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Helium-free magnet architectures and conduction-cooled superconducting innovations are disrupting procurement patterns across North and West Africa, compressing traditional vendor service contract structures. WHO Essential Diagnostics List adoption by Nigeria's and Egypt's health ministries accelerates public budget allocation toward magnetic resonance infrastructure.
For Market Incumbents: Build captive service infrastructure moats through localized biomedical engineering certification programs that reduce mean time to repair. Siemens Healthineers exemplifies this archetype with East African training centers. Anchor long-term maintenance contracts against emerging Asian manufacturers competing on capital cost compression. Defend against refurbished system channels by pre-positioning regulatory affairs personnel in Cape Town and Cairo to navigate documentation complexity. For New Entrants and Emerging Players: Mid-market permanent magnet configurations for sub-Saharan hospitals with unreliable cold chain logistics represent the most penetrable entry point. Nigeria's federal teaching hospitals in Kaduna and Enugu seek unbundled procurement separating equipment from service contracts. Target diagnostic center chains in Cairo and Johannesburg with helium-recapture cooling pilot programs. Go-to-market angle: guaranteed-uptime pricing rather than time-and-materials billing. For Investors and Strategic Acquirers: Carve-out targets emerge from European hospital system asset retirement pools supplying refurbished 1.5 Tesla systems to Egyptian private operators. Long-term viability hinges on regulatory navigation capabilities across fragmented national agency frameworks. Watch for South Africa's Health Products Regulatory Authority harmonization signals with WHO prequalification standards as inflection indicator for multi-country service scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Helium-Free Magnet Architecture Deployment | Eliminates cryogenic dependency for Nigerian and Kenyan operators facing supply disruption. |
| Localized Biomedical Engineering Certification | Reduces reliance on expatriate technicians across East African service territories. |
| Refurbished Equipment Channel Expansion | Addresses capital constraints for Egypt's private diagnostic center growth phase. |
| Unbundled Procurement Separation | Compresses vendor margins while expanding third-party service provider market entry. |
| Regulatory Affairs Pre-Positioning | Accelerates import approval timelines for 3.0 Tesla configurations in South Africa. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and vendor service heads across Cairo, Lagos, Johannesburg, and Nairobi. Secondary validation drew from hospital procurement databases, WHO essential diagnostics documentation, South Africa's Health Products Regulatory Authority filings, and Egyptian drug authority registration records. Bottom-up equipment installation tracking triangulated against top-down public health budget allocation analysis.
Calibration against historical procurement velocity and tertiary hospital expansion timelines shaped analytical framework development across the projection horizon. Segmentation dimensions modeled include field strength tier, magnet cooling technology, end-user category, and clinical application intensity. CAGRs were derived from equipment shipment trajectories and service contract inception rates. Forecast inputs incorporated helium supply volatility indices and regulatory approval timeline differentials between 1.5 Tesla and 3.0 Tesla configurations.
Practitioners should monitor WHO prequalification pathway acceleration and national essential diagnostics list revision cycles for early signals of budget reallocation. Forecasts reflect assumptions regarding cold chain logistics stabilization and biomedical engineering training program accreditation expansion. Quarterly review of helium spot pricing and South African Health Products Regulatory Authority registration queue depth is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Handheld Dental X-Ray Systems Market
Medical Imaging
United Kingdom Digital X-Ray Devices Market
Medical Imaging
Molecular Breast Imaging Market
Medical Imaging
South Korea Mammography Market
Medical Imaging
South Korea Digital X-Ray Market
Medical Imaging
Medical Digital Imaging Systems Market
Medical Imaging
Teleradiology Market
Medical Imaging
Molecular Imaging Market
Medical Imaging
Portable MRI Market
Medical Imaging
Global CT Scanners Market
Medical Imaging
Global Veterinary CT Scanner Market
Medical Imaging
Saudi Arabia Digital Radiology Market
Medical Imaging
Echocardiography Market
Medical Imaging
Interventional Radiology Market
Medical Imaging
South America MRI Market
Medical Imaging
Canada Nuclear Medicine Market