
 Canada Computed Tomography Market | 2026-2036
Canada Computed Tomography Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Computed Tomography Market Insights
Photon-counting detector architecture is rewriting how CT manufacturers balance dose reduction against spatial resolution in next-generation scanners. GE Healthcare leverages its deep installed base across Canadian teaching hospitals to sustain service contract renewal rates. Siemens Healthineers anchors its position through localized manufacturing partnerships that shorten delivery timelines for high-end CT configurations. Canon Medical Systems competes on spectral imaging pipelines that differentiate its dual-energy platforms in oncology workflows.
Computed tomography encompasses X-ray-based cross-sectional imaging systems that rotate a gantry-mounted tube and detector array around a patient, reconstructing volumetric datasets via filtered back-projection or iterative algorithms with spatial resolution typically below 0.5 mm. These systems serve as the primary non-invasive modality for detecting tumors, vascular anomalies, and traumatic injuries across acute and ambulatory settings. High-end CT and photon-counting technology command the dominant margin pool as Canadian procurement shifts toward premium platforms capable of spectral decomposition and cardiac gating. Mid-range CT occupies the volume-dominant tier where provincial health authorities standardize fleet replacements across community hospitals.
Health Canada's Medical Devices Bureau governs premarket licensing under the Medical Devices Regulations, while provincial health technology assessment bodies such as Ontario Health's Health Technology Assessment branch evaluate cost-effectiveness before public reimbursement. The Canadian Standards Association maintains electrical and radiation safety benchmarks that shape product certification timelines for imported CT systems. Stakeholders must monitor how Health Canada's evolving guidance on machine-learning diagnostic algorithms reshapes software upgrade pathways and vendor liability frameworks.
Market Dynamics
Photon-counting detector arrays are compressing the upgrade cycle across Ontario and Quebec hospital networks as provincial procurement committees prioritize dose-reduction specifications over legacy hardware longevity.
Growth Catalysts
- Health Canada software validation mandates:Tighter premarket licensing requirements for AI-enabled diagnostic algorithms are accelerating vendor certification timelines and filtering out non-compliant imports.
- Ontario hospital network consolidation:Centralized purchasing by provincial health authorities is standardizing fleet replacements and creating volume commitments for high-end CT configurations.
- Cardiac gating capabilities:Research-clinical hybrid installations at Quebec academic medical centers are anchoring replacement cycles for systems with advanced temporal resolution.
Market Restraints
- Import dependency for detector materials:Supply concentration for cadmium-zinc-telluride substrates in Asian manufacturing clusters creates input cost volatility and extended lead times.
- Health Canada licensing friction:Premarket licensing pathways under the Medical Devices Regulations impose multi-quarter certification timelines that delay revenue recognition for new platform launches.
- Magnetic resonance substitution:Soft-tissue imaging applications in neurology and musculoskeletal diagnostics are migrating to MRI where radiation dose concerns dominate patient selection criteria.
Strategic Opportunities
- Western Canada network penetration:Alberta and British Columbia community hospital fleets remain underpenetrated by photon-counting architectures relative to central Canadian academic centers.
- AI-integrated workflow convergence:Machine-learning reconstruction algorithms paired with spectral imaging pipelines are creating differentiated positioning in oncology staging protocols.
- Provincial technology assessment alignment:Ontario Health's Health Technology Assessment branch is streamlining cost-effectiveness evaluation pathways for systems demonstrating quantified dose reduction.
Industry Challenges
- Medical physicist specialization gap:Spectral imaging protocol optimization requires expertise in dual-energy decomposition that outpaces training program output.
- Legacy PACS integration complexity:Photon-counting data formats exceed storage and transmission specifications of decade-old hospital information systems.
- Service engineer certification bottlenecks:Manufacturer-specific training programs for solid-state detector maintenance create technician allocation constraints during peak replacement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Computed Tomography Market |
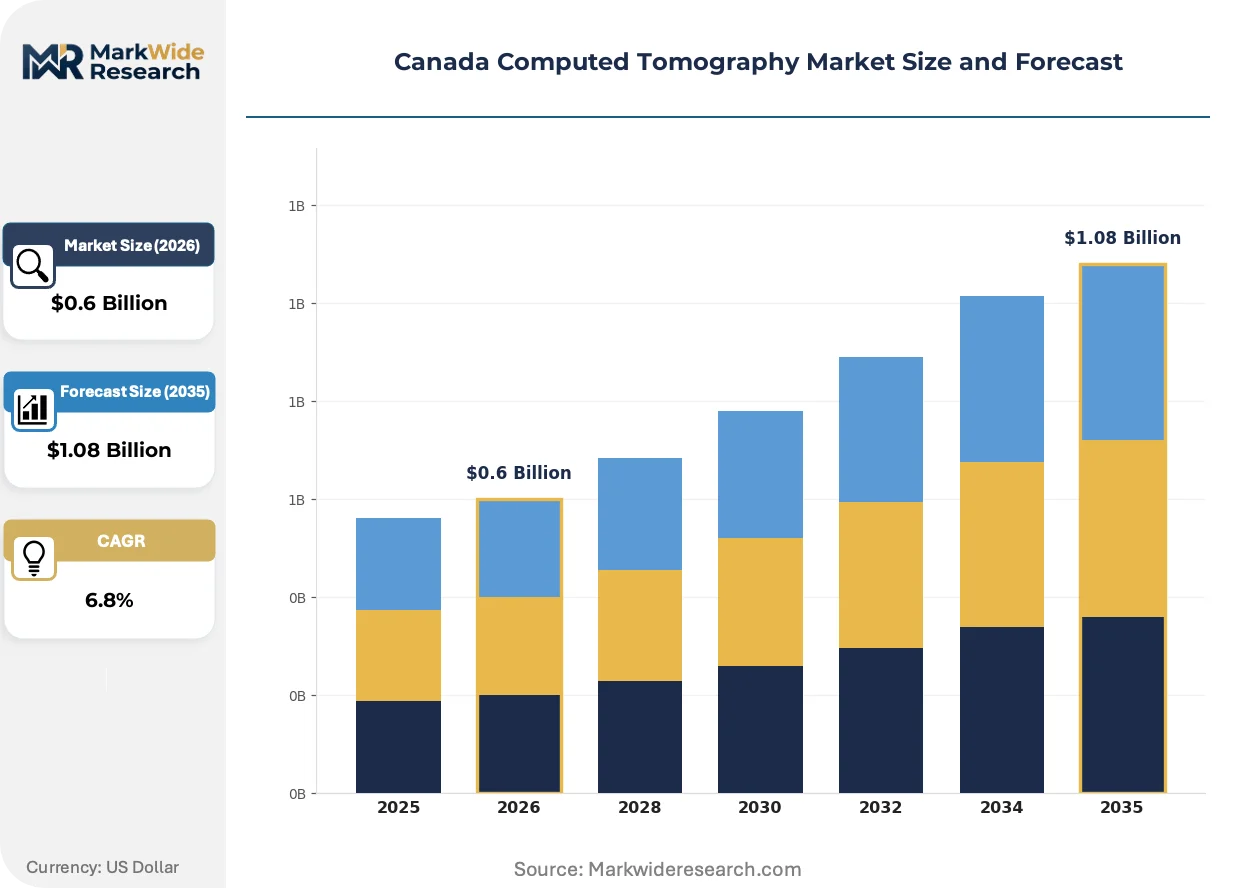
| Market Size in 2026 | $0.6 Billion |
| Market Size in 2035 | $1.08 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-end CT, Mid-range CT, High-end CT, Cone-beam CT End User: Hospitals, Diagnostic Centers, Academic Institutes, Research Laboratories Technology: Photon Counting, Dual-energy, Spiral CT, Mobile CT Application: Oncology, Neurology, Cardiology, Orthopedics |
| Companies Covered | GE Healthcare, Canon Medical Systems Corporation, Siemens Healthineers, Koninklijke Philips NV, Koning Corporation, Planmeca Group, Carestream Health, Neusoft Medical Systems Co Ltd, Samsung Electronics Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Computed Tomography Market Trends and Innovations
Detector architecture evolution and regulatory software mandates are compressing product lifecycles while reshaping how vendors structure service and upgrade revenue.
Photon-counting CT is hybridizing spectral decomposition capabilities with cardiac gating performance in single-platform configurations. Quebec academic medical centers are adopting these systems at accelerated replacement intervals. The technology is hybridizing what previously required separate scanner investments, compressing capital allocation across radiology and cardiology departments.
Health Canada's Medical Devices Bureau has tightened premarket licensing requirements for machine-learning diagnostic algorithms embedded in reconstruction software. This regulatory shift is extending vendor certification timelines and reshaping liability frameworks for software updates. High-end CT platforms with integrated AI reconstruction are experiencing the most pronounced compliance delays.
Ontario Health's centralized procurement committees are unbundling service contracts from hardware purchases and negotiating multi-hospital network agreements. Independent service organizations are capturing maintenance revenue previously retained by original equipment manufacturers. This purchasing behavior shift is most visible in community hospital replacements across the Greater Toronto Area.
Canada Computed Tomography Market Segmentation
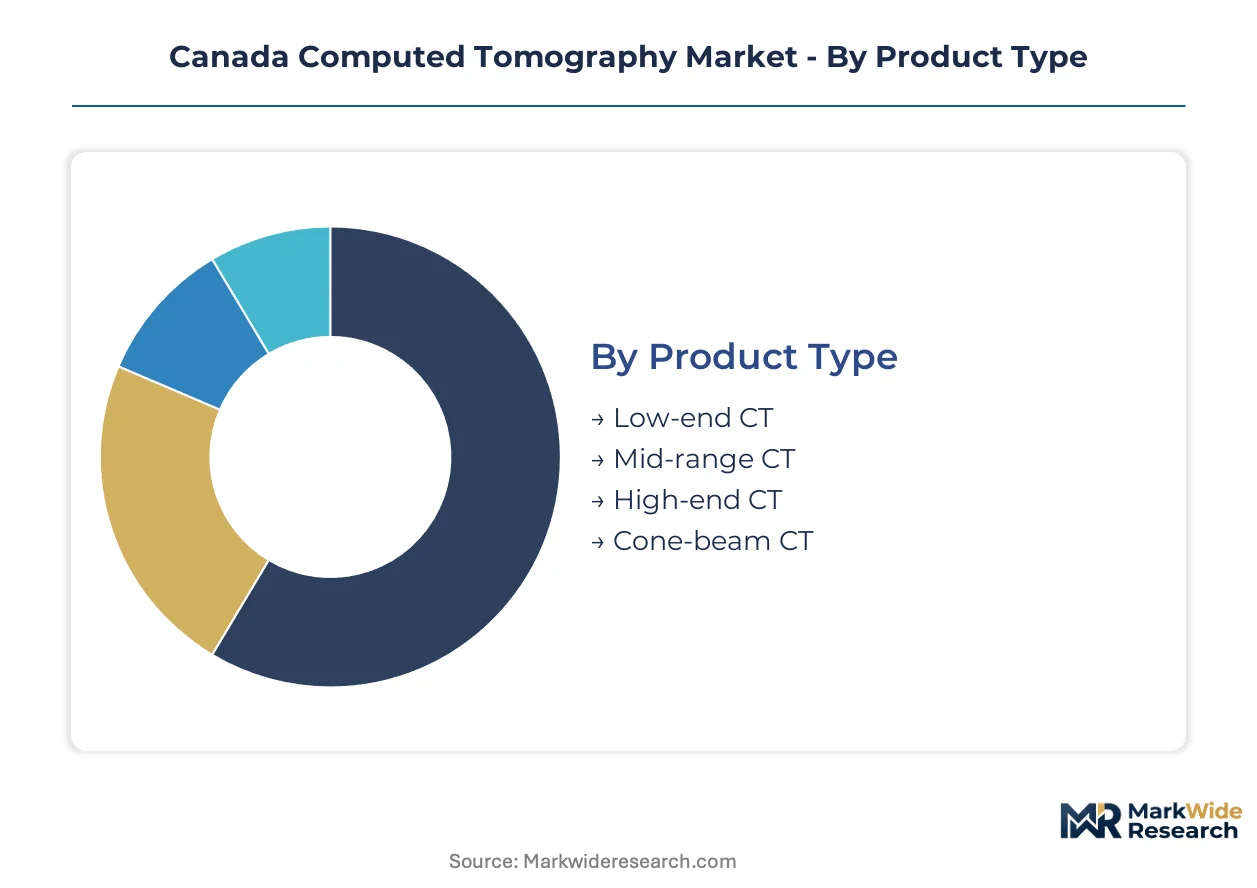
CT procurement patterns across Canadian provinces diverge sharply by clinical workload density and capital allocation priorities. Understanding how product tiers, end-user categories, and technology platforms fragment demand explains why vendor strategies must align with Ontario's centralized purchasing versus Quebec's academic-driven replacement cycles.
Product Type:
Clinical use-case spectrum spans trauma triage in community settings through research-grade spectral imaging at university hospitals.
- Low-end CT:Single-slice or limited multi-slice configurations serve urgent care centers and rural clinics where fracture detection and basic chest imaging dominate referral patterns. Demand concentrates in Saskatchewan and Manitoba community hospitals where provincial funding prioritizes access over advanced functionality.
- Mid-range CT:64-slice to 128-slice systems balance throughput against capital constraints, forming the procurement standard across Ontario Health's network consolidation initiatives. These configurations absorb the largest volume of provincial fleet replacement contracts.
- High-end CT:256-slice and photon-counting platforms command premium positioning through cardiac gating and spectral decomposition capabilities.
- Cone-beam CT:Specialized dental and ENT applications with compact footprints serve ambulatory surgical centers.
The dominant share belongs to Mid-range CT, while High-end CT is closing the gap fastest as Ontario and Quebec accelerate photon-counting procurement.
End User:
Customer-type concentration reveals how institutional purchasing power shapes vendor contract structures and service bundling.
- Hospitals:Acute care facilities generate the largest installed base, with Ontario's 141 hospital corporations driving centralized procurement through Health Shared Services Ontario. These institutions negotiate multi-year service agreements that unbundle maintenance from hardware acquisition.
- Diagnostic Centers:Independent imaging clinics operate on throughput economics where Medicare reimbursement schedules dictate equipment utilization targets. Alberta's privately operated community diagnostics represent the fastest-expanding customer segment.
- Academic Institutes:McGill University Health Centre and University Health Network anchor research-clinical hybrid demand.
- Research Laboratories:Preclinical imaging cores at Canadian Institutes of Health Research-funded facilities drive specialized micro-CT and spectral calibration system purchases.
Hospitals retain the dominant procurement volume, though Diagnostic Centers are expanding most quickly as Alberta and British Columbia license independent operators.
Technology:
Platform maturity and regulatory certification timelines create distinct competitive moats among detector architectures.
- Photon Counting:Cadmium-zinc-telluride direct-conversion detectors eliminate electronic noise and enable spectral decomposition at diagnostic dose levels. Quebec's academic medical centers have adopted these systems at compressed replacement intervals, anchoring vendor reference site strategies.
- Dual-energy:Rapid kV-switching and dual-source configurations deliver material differentiation for gout, kidney stone, and pulmonary embolism protocols. Community hospitals in the Greater Toronto Area prioritize these platforms for their versatility across service lines.
- Spiral CT:Continuous rotation helical acquisition remains the workhorse architecture for high-throughput emergency departments.
- Mobile CT:Truck-mounted and self-shielded units serve rural outreach and intraoperative neurosurgical applications.
Spiral CT maintains the largest installed base, while Photon Counting shows the steepest expansion trajectory as Health Canada clears premarket submissions.
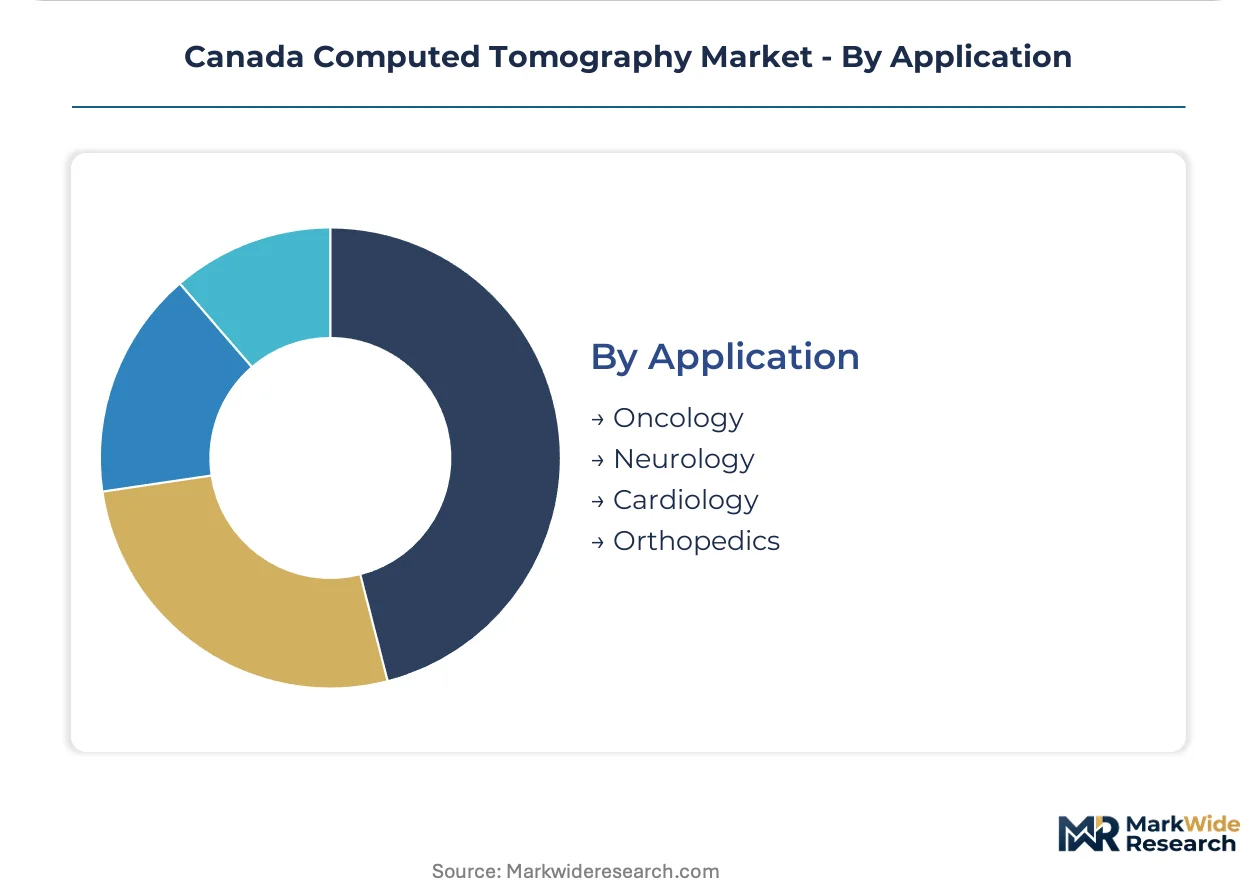
Application:
Clinical indication priority determines detector specification requirements and software reconstruction investment.
- Oncology:Staging and treatment response monitoring demands spectral imaging for iodine quantification and low-dose lung screening protocol compliance. Cross-Canada Cancer Control priorities are elevating CT against MRI for thoracic and abdominal tumor assessment.
- Neurology:Perfusion imaging and stroke protocol automation require sub-millimeter spatial resolution with rapid reconstruction pipelines. Ontario's stroke network consolidation is standardizing CT-first triage across 11 regional stroke centers.
- Cardiology:Coronary CT angiography with fractional flow reserve computation is displacing diagnostic catheterization in stable chest pain pathways.
- Orthopedics:Metal artifact reduction and weight-bearing extremity protocols serve arthroplasty and sports medicine practices.
Oncology commands the dominant application share, with Neurology climbing fastest as provincial stroke networks expand CT-first triage protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provincial health authorities concentrate purchasing power through centralized procurement committees, while academic medical centers anchor technology adoption cycles in Ontario and Quebec.
Ontario
Ontario Health's Health Shared Services Ontario consolidates fleet replacement across 141 hospital corporations, creating volume commitments for mid-range and high-end CT configurations. The Medical Devices Bureau's premarket licensing requirements filter vendor participation in centralized tenders. Toronto's University Health Network anchors research-clinical hybrid demand for photon-counting platforms with cardiac gating capabilities.
Quebec
McGill University Health Centre and Centre hospitalier de l'Université de Montréal drive accelerated replacement cycles for spectral imaging systems. Health Canada software validation mandates for AI-enabled reconstruction algorithms extend certification timelines for vendors targeting Quebec's academic centers. Montreal's radiology research clusters concentrate demand for dual-energy platforms in oncology staging protocols.
Alberta
Alberta Health Services standardizes community hospital procurement across the province's regional health authorities, prioritizing throughput economics for diagnostic centers. The province's privately operated community imaging clinics represent the fastest-expanding customer segment for mid-range CT configurations. Calgary's acute care networks concentrate demand for 64-slice to 128-slice systems in emergency department triage.
British Columbia
Provincial Health Services Authority procurement favors mobile CT units for rural outreach and intraoperative neurosurgical applications across Vancouver Coastal and Fraser Health regions. British Columbia's community hospital fleets remain underpenetrated by photon-counting architectures relative to central Canadian academic centers. Vancouver's academic medical centers anchor demand for advanced temporal resolution in stroke network consolidation.
Canada Computed Tomography Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement segments defined by provincial standardization versus academic customization. The vendor base organizes around three strategic archetypes: diversified imaging conglomerates with deep installed bases, regional specialists with localized manufacturing partnerships, and emerging entrants competing on AI-integrated workflow convergence. Consolidation pressure intensifies through multi-hospital network service contract unbundling and technology licensing arrangements for spectral imaging pipelines.
Within the diversified imaging conglomerate tier, GE Healthcare leverages its deep installed base across Canadian teaching hospitals to sustain service contract renewal rates. Siemens Healthineers anchors its position through localized manufacturing partnerships that shorten delivery timelines for high-end CT configurations. Canon Medical Systems occupies a position competing on spectral imaging pipelines that differentiate dual-energy platforms in oncology workflows.
| Leading Market Players |
|---|
| GE Healthcare |
| Canon Medical Systems Corporation |
| Siemens Healthineers |
| Koninklijke Philips NV |
| Koning Corporation |
| Planmeca Group |
| Carestream Health |
| Neusoft Medical Systems Co Ltd |
| Samsung Electronics Co Ltd |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on cadmium-zinc-telluride substrates from Asian manufacturing clusters compresses pricing tier spreads while forcing Canadian procurement committees toward long-term offtake contracts with built-in indexation clauses. Health Canada's Medical Devices Bureau premarket licensing timelines further amplify cost-plus contract prevalence as vendors seek margin protection against multi-quarter certification delays.
Pricing Analysis
Cost-plus contracts with metal-indexed escalation clauses dominate procurement between Ontario Health's centralized purchasing committees and high-end CT vendors. Price differentiation rests on Health Canada certification tier and bundled service contract duration, with academic medical centers showing lowest sensitivity due to research grant funding offsets. Cost compression in mid-range CT configurations is intensifying as provincial fleet standardization programs consolidate volume commitments. Diagnostic centers in Alberta exhibit highest price sensitivity where Medicare reimbursement schedules cap equipment utilization economics.
Supply Chain Analysis
Contract manufacturing for photon-counting detector arrays concentrates at Siemens Healthineers' German fabrication facilities and GE Healthcare's South Korean component partners. Raw material procurement draws from Chinese rare earth processors for scintillator crystals and Japanese precision optics suppliers for collimator assemblies. Single-source vulnerability in CZT substrate supply creates exposure to export control fluctuations. Distribution runs through manufacturer-direct sales organizations serving hospital corporations alongside independent service organizations capturing unbundled maintenance revenue in Ontario's Greater Toronto Area community hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat environment where Health Canada regulatory entrenchment creates structural switching costs that protect incumbent vendor positions against emerging competitors.
For Market Incumbents: Entrench installed base advantages by accelerating biomedical engineer certification programs for photon-counting detector maintenance, creating technician allocation constraints that delay competitor service response times. Deepen backward integration into CZT substrate supply through exclusive offtake agreements with Asian foundries, insulating against emerging entrant cost disruption while Ontario Health's unbundled procurement patterns threaten OEM service contract retention. For New Entrants and Emerging Players: Alberta and British Columbia community hospital fleets present the most penetrable white-space opportunity, with photon-counting architecture penetration lagging central Canadian academic centers by substantial replacement cycle intervals. Target independent diagnostic centers in Calgary and Edmonton where provincial licensing of private operators expands fastest. Lead with AI-integrated workflow convergence bundled at price points below Siemens and GE service-contract-inclusive offerings. For Investors and Strategic Acquirers: Regional service specialists with Health Canada Medical Devices Bureau certification infrastructure and established biomedical engineer training pipelines represent the highest-conviction acquisition archetype. Long-term viability hinges on vendor ability to convert photon-counting hardware sales into recurring software upgrade revenue as AI reconstruction algorithms face tightening validation mandates. Watch Health Canada guidance publication velocity on machine-learning diagnostic tools as the critical inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Premarket Licensing Investment | Accelerates vendor certification timelines for AI-enabled reconstruction algorithms. |
| Provincial GPO Partnership | Secures multi-hospital network volume commitments through Health Shared Services Ontario. |
| Biomedical Engineer Certification Program | Creates technician allocation moats during peak photon-counting replacement windows. |
| CZT Substrate Supply Agreement | Locks cadmium-zinc-telluride capacity against import cost volatility from Asian clusters. |
| AI Reconstruction Software Development | Differentiates positioning in oncology staging protocols at Quebec academic centers. |
Research Methodology
Operator-level perspectives from hospital purchasing committee directors, biomedical engineering managers, GPO contracts specialists, and provincial health technology assessment officers anchored the qualitative base. Primary interview insights combined with secondary validation from Health Canada Medical Devices Bureau licensing databases, Ontario Health procurement disclosure records, and hospital capital expenditure filings. Bottom-up installed base modeling triangulated against top-down provincial health authority budget allocations.
Scenario-bracketing around Health Canada software validation timeline variations and provincial procurement centralization pace shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product tier, end-user category, detector technology platform, and provincial regulatory cluster. CAGRs derived from replacement cycle compression rates and photon-counting adoption curves. Forecast inputs incorporated cadmium-zinc-telluride supply lead times and AI reconstruction algorithm certification velocity.
Practitioners should monitor Health Canada guidance publication schedules and provincial technology assessment streamlining announcements for early signals of vendor competitive position shifts. Forecasts reflect assumptions around detector material supply stability and reimbursement schedule continuity. Quarterly review of premarket licensing submission queues and GPO contract award disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Diagnostic Ultrasound Market
Medical Imaging
Perfusion Imaging Market
Medical Imaging
Asia Pacific Computed Tomography (CT) Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market
Medical Imaging
Digital Mammography Market
Medical Imaging
Cardiology PACS Market
Medical Imaging
Asia Pacific Open System MRI Market
Medical Imaging
Europe Medical Imaging Market
Medical Imaging
South Korea Mammography Market
Medical Imaging
India Mammography Market
Medical Imaging
United Kingdom Diagnostic Imaging Equipment Market
Medical Imaging
US Teleradiology Market
Medical Imaging
Global Medical Cameras Market
Medical Imaging
Industrial Radiography Equipment Market
Medical Imaging
Nuclear Medicine Software Market
Medical Imaging
South America Fluoroscopy Market