
 France Computed Tomography Market | 2026-2036
France Computed Tomography Market Size, Share, and Industry Trends Forecast 2026-2036
France Computed Tomography Market Foresight
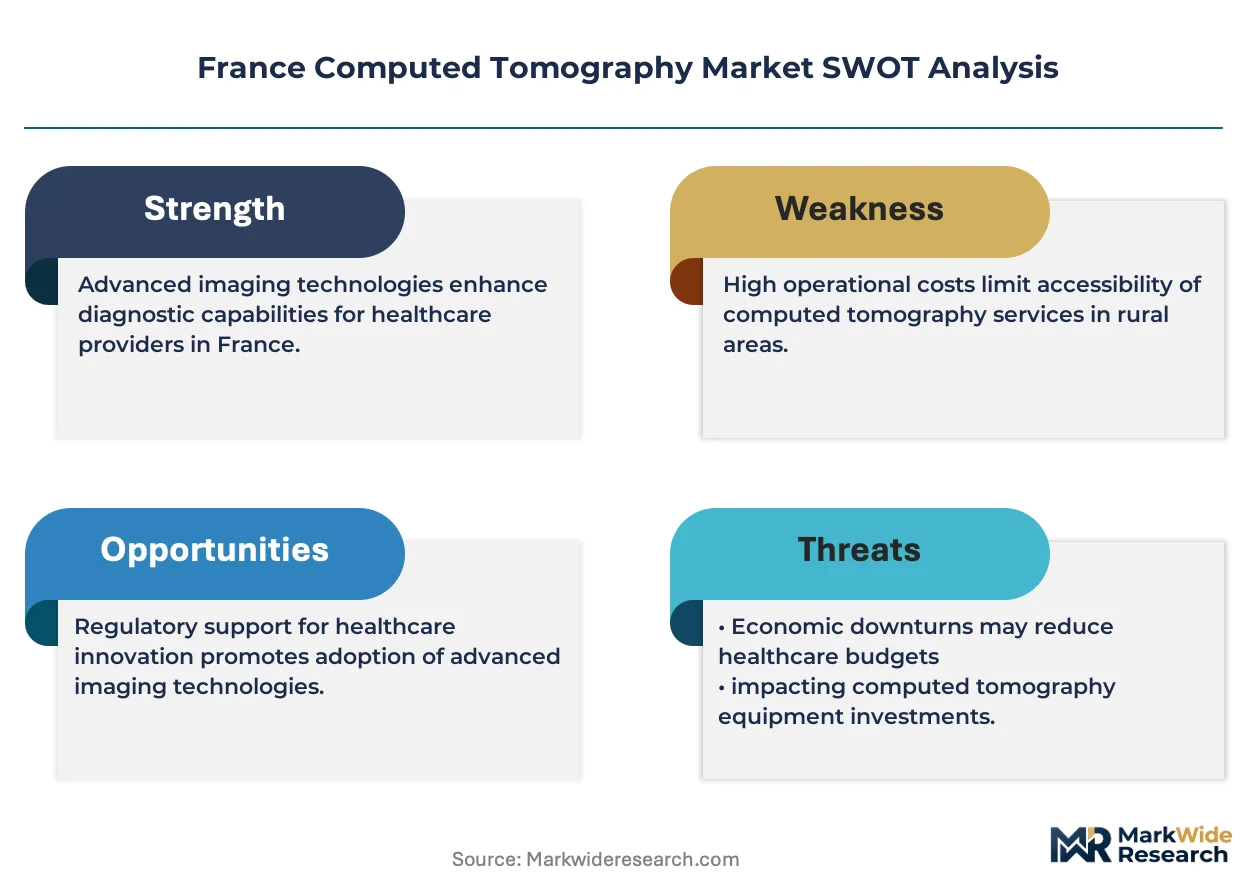
The EU Green Deal is expanding sustainability mandates across French healthcare procurement, pushing hospitals toward energy-efficient imaging platforms. GE Healthcare leverages its deep installed base in French public hospitals to sustain service contract renewals. Siemens Healthineers anchors its position through localized manufacturing and direct technical support networks. Canon Medical Systems Corporation differentiates via detector technology specialization in cardiovascular imaging suites.
Computed tomography systems generate cross-sectional anatomical images using rotating X-ray tubes and multi-row detector arrays, with slice counts ranging from 16 to 320 depending on clinical throughput requirements. Multi-slice CT dominates hospital capital budgets due to throughput demands in emergency and trauma settings, while portable CT units capture expanding demand in intensive care and intraoperative neurological assessment. Cone beam CT occupies a narrower margin pool concentrated in dental-maxillofacial and orthopedic outpatient clinics.
ANSM oversees medical device market authorization and post-market surveillance, while CE marking under the EU MDR establishes conformity requirements for CT system safety and clinical performance. The national hospital modernization program (Ségur de la Santé) channels public investment toward diagnostic infrastructure renewal. Stakeholders must monitor reimbursement rate adjustments for CT-guided interventions and the pace of cloud-integrated platform adoption across regional hospital groups.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing procurement cycles across French hospital networks, forcing accelerated replacement of aging single-slice CT systems with compliant multi-slice platforms before transitional deadlines expire.
Growth Catalysts
- Ségur de la Santé investment:The national hospital modernization program channels public capital toward diagnostic infrastructure renewal, expanding CT fleet capacity in regional hospital groups.
- EU Green Deal mandates:Sustainability procurement rules are pushing French healthcare buyers toward energy-efficient imaging platforms with reduced helium consumption and lower lifecycle carbon footprints.
- Trauma throughput requirements:Emergency departments in Parisian university hospitals are driving demand for 128-slice and above CT systems to handle peak patient volumes.
Market Restraints
- Helium supply volatility:Magnetic resonance cooling dependencies and superconducting CT component requirements expose French buyers to global helium market concentration risks.
- CE marking timeline friction:The EU MDR's expanded clinical evidence requirements are extending market authorization periods for novel CT detector technologies.
- Substitution by cone beam systems:Dental-maxillofacial and orthopedic outpatient clinics are diverting capital toward lower-cost cone beam CT alternatives for specialized anatomical imaging.
Strategic Opportunities
- Intensive care portable deployment:Mobile CT units for neurological assessment in ICUs represent underpenetrated demand within French regional hospital networks.
- Cloud-integrated platform adoption:Regional hospital groups are consolidating imaging data across multiple sites, creating demand for vendor-neutral archive and AI-assisted reconstruction platforms.
- AI Act compliance services:The EU AI Act's risk classification for medical imaging software is creating advisory and validation service revenue streams around CT-integrated diagnostic algorithms.
Industry Challenges
- Biomedical engineer scarcity:Specialized service talent for multi-slice CT maintenance is concentrating in Île-de-France, leaving peripheral regions with extended downtime risks.
- Legacy fleet interoperability:PACS integration complexity is delaying cloud migration timelines for hospital groups with heterogeneous installed bases spanning multiple vendor generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Computed Tomography Market |
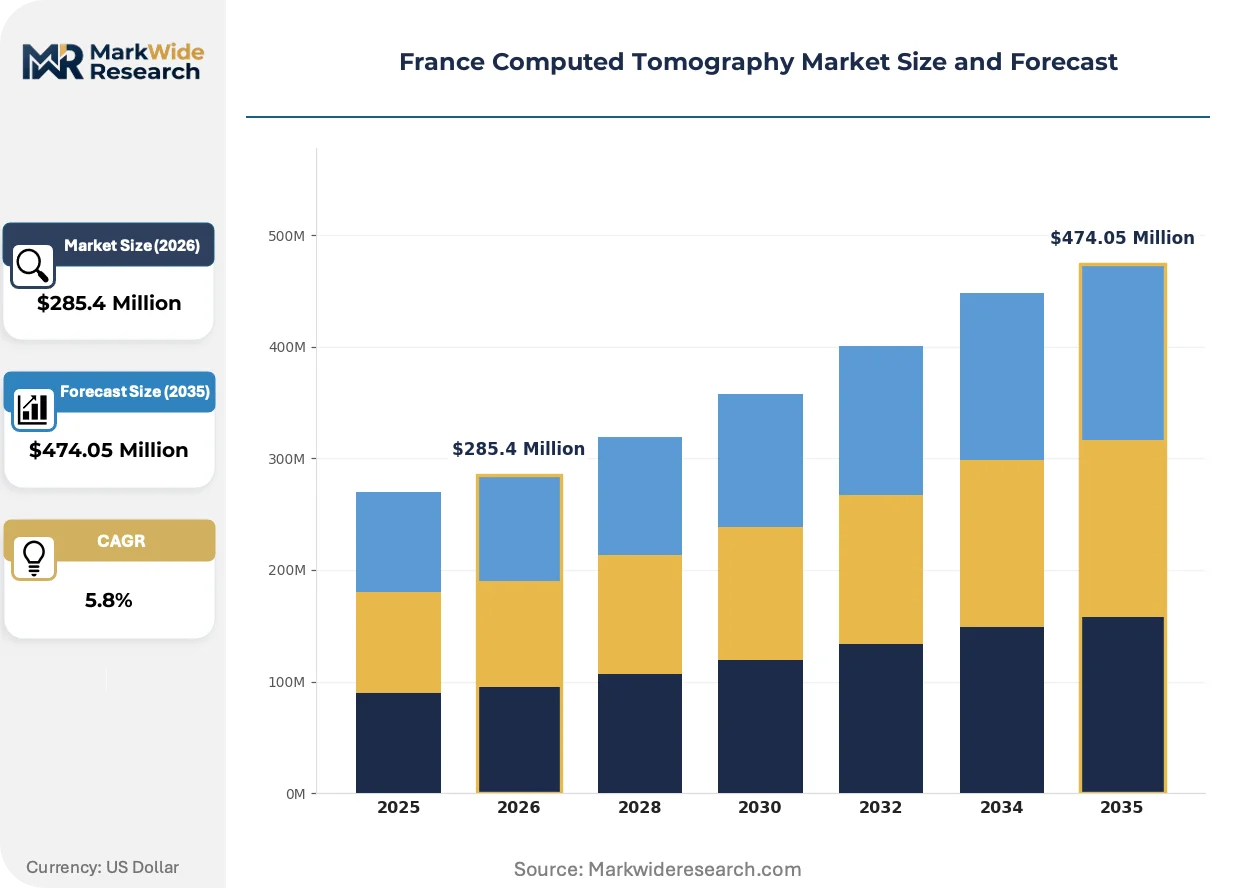
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multi-slice CT, Portable CT, Cone Beam CT, Dual-energy CT, Micro CT Application: Oncology Diagnostics, Cardiovascular Imaging, Neurological Assessment, Orthopedic Evaluation, Pulmonary Examination End User: Hospitals, Diagnostic Laboratories, Ambulatory Surgical Centers, Research Institutes Deployment: Stationary Systems, Mobile Units, Cloud-integrated Platforms, Hybrid Installations |
| Companies Covered | GE Healthcare, Canon Medical Systems Corporation, Koninklijke Philips NV, Siemens Healthineers AG, Koning Corporation, Planmeca Group, Carestream Health, Fujifilm Holdings Corporation, Neusoft Medical Systems Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Computed Tomography Market Shifts & Advancements
Photon-counting detector technology is electrifying the French CT landscape, compressing the competitive window for conventional energy-integrating systems while regulatory pressure and procurement consolidation reshape buyer-vendor relationships.
Photon-counting CT detectors are eliminating electronic noise through direct X-ray photon measurement rather than scintillator-based light conversion. Academic medical centers in Paris and Lyon are piloting these systems for cardiovascular and spectral imaging protocols. This architecture is electrifying the premium segment, forcing incumbent vendors to accelerate R&D timelines or cede high-margin university hospital contracts.
The EU MDR's post-market surveillance requirements are mandating systematic clinical follow-up data collection for CT systems with AI-integrated reconstruction. Manufacturers must now maintain active registries of device performance across French installations. High-throughput emergency departments are responding by demanding extended warranty and predictive maintenance packages that transfer compliance documentation burden to vendors.
Regional hospital groups are consolidating equipment purchasing through centralized Groupements Hospitaliers de Territoire structures, compressing vendor negotiation cycles from twelve to six months. Independent imaging centers in Provence-Alpes-Côte d'Azur are forming cooperative procurement alliances to match public hospital volume discounts. This concentration is most visible in the Grand Est region, where cross-border patient flows with Germany and Switzerland are driving standardization around dual-energy CT protocols.
France Computed Tomography Market Segmentation
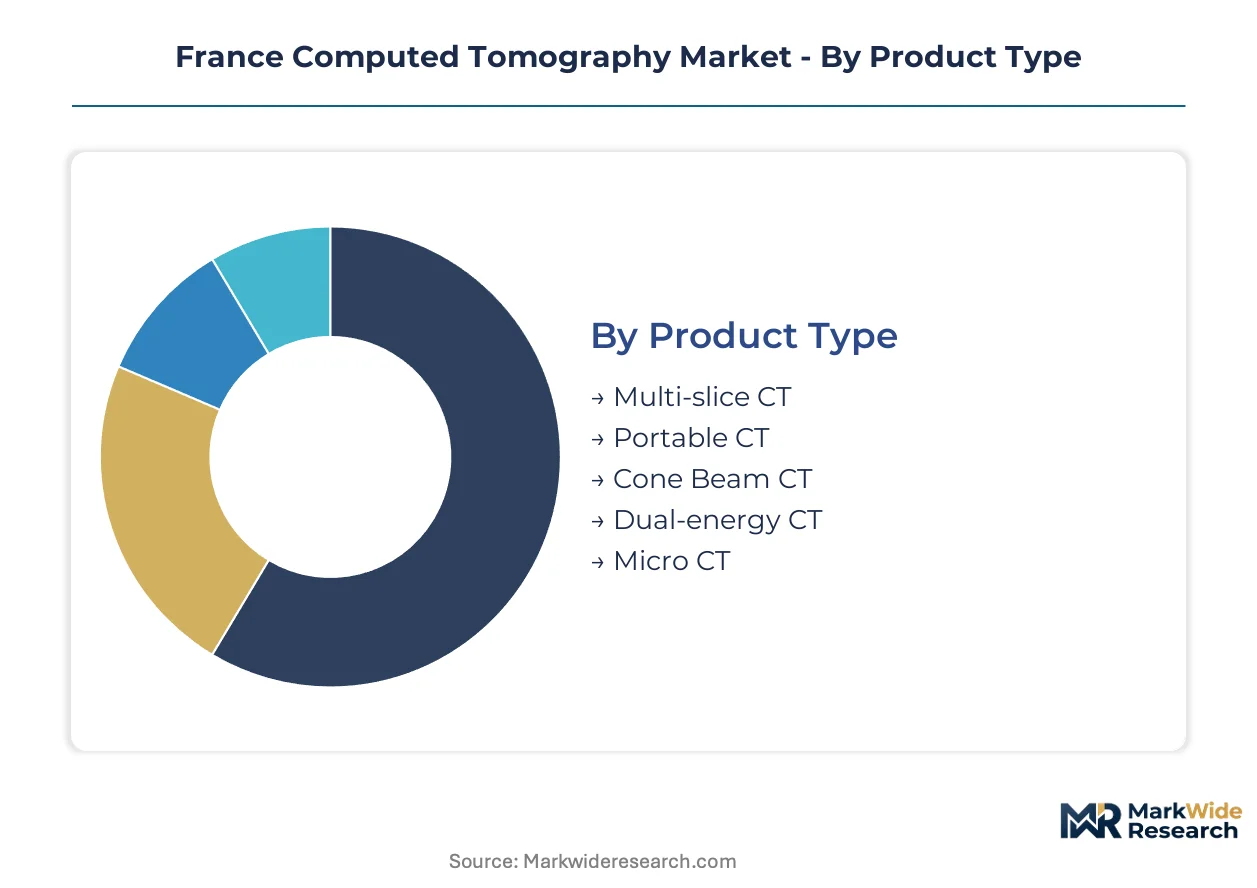
CT procurement in France splits across clinical throughput requirements, physical deployment constraints, and regulatory compliance tiers. Hospital buyers weight slice count against energy efficiency mandates, while outpatient networks prioritize footprint and reimbursement alignment.
Product Type:
French hospital capital committees prioritize throughput capacity and EU Green Deal compliance when evaluating scanner architecture.
- Multi-slice CT:Rotating X-ray tube systems with 16 to 320 detector rows generate cross-sectional anatomical images at high throughput. Parisian university hospitals anchor demand for 128-slice and above configurations to manage emergency department peak volumes under Ségur de la Santé modernization timelines.
- Portable CT:Self-contained mobile units with battery power and compact gantry designs enable bedside neurological assessment in intensive care settings. Regional hospital networks in peripheral zones deploy these to reduce patient transport risks and extend diagnostic coverage beyond fixed radiology suites.
- Cone Beam CT:Flat-panel detector systems optimized for dental-maxillofacial and orthopedic outpatient imaging with lower radiation dose profiles.
- Dual-energy CT:Spectral imaging platforms using two distinct X-ray energy levels for material decomposition and tissue characterization.
- Micro CT:Sub-micron resolution systems for preclinical research and ex vivo specimen analysis in academic medical centers.
Volume sits with multi-slice CT; growth tilts toward portable CT.
Application:
Reimbursement rate differentials and clinical outcome data shape specialty-specific procurement priorities across French healthcare networks.
- Oncology Diagnostics:Tumor staging and treatment response monitoring protocols drive demand for spectral imaging capabilities. Grand Est region hospitals standardize around dual-energy CT for cross-border patient referral compatibility with German and Swiss oncology networks.
- Cardiovascular Imaging:Coronary CT angiography and calcium scoring applications require sub-millimeter spatial resolution and motion correction algorithms. Lyon academic medical centers pilot photon-counting detector systems for plaque characterization studies.
- Neurological Assessment:Stroke protocol imaging and trauma evaluation in emergency settings.
- Orthopedic Evaluation:Preoperative planning and postoperative monitoring for joint replacement procedures.
- Pulmonary Examination:Emphysema quantification and interstitial lung disease assessment.
Emergency throughput concentrates demand in cardiovascular and neurological assessment; oncology diagnostics climb the fastest on precision medicine investment.
End User:
Public procurement consolidation through Groupements Hospitaliers de Territoire structures compresses vendor negotiation cycles and standardizes equipment specifications.
- Hospitals:Public and private acute care facilities with 24-hour emergency services and comprehensive radiology departments. Île-de-France hospital networks modernize aging single-slice fleets under EU MDR compliance deadlines and Ségur de la Santé infrastructure renewal programs.
- Diagnostic Laboratories:Independent imaging centers and outpatient diagnostic chains. Provence-Alpes-Côte d'Azur operators form cooperative procurement alliances to match public hospital volume discounts on multi-slice systems.
- Ambulatory Surgical Centers:Same-day procedure facilities with limited on-site imaging requirements.
- Research Institutes:Academic and preclinical research organizations with specialized spectral and micro-CT needs.
Installed base concentration favors hospitals; diagnostic laboratories gain share fastest on outpatient volume migration.
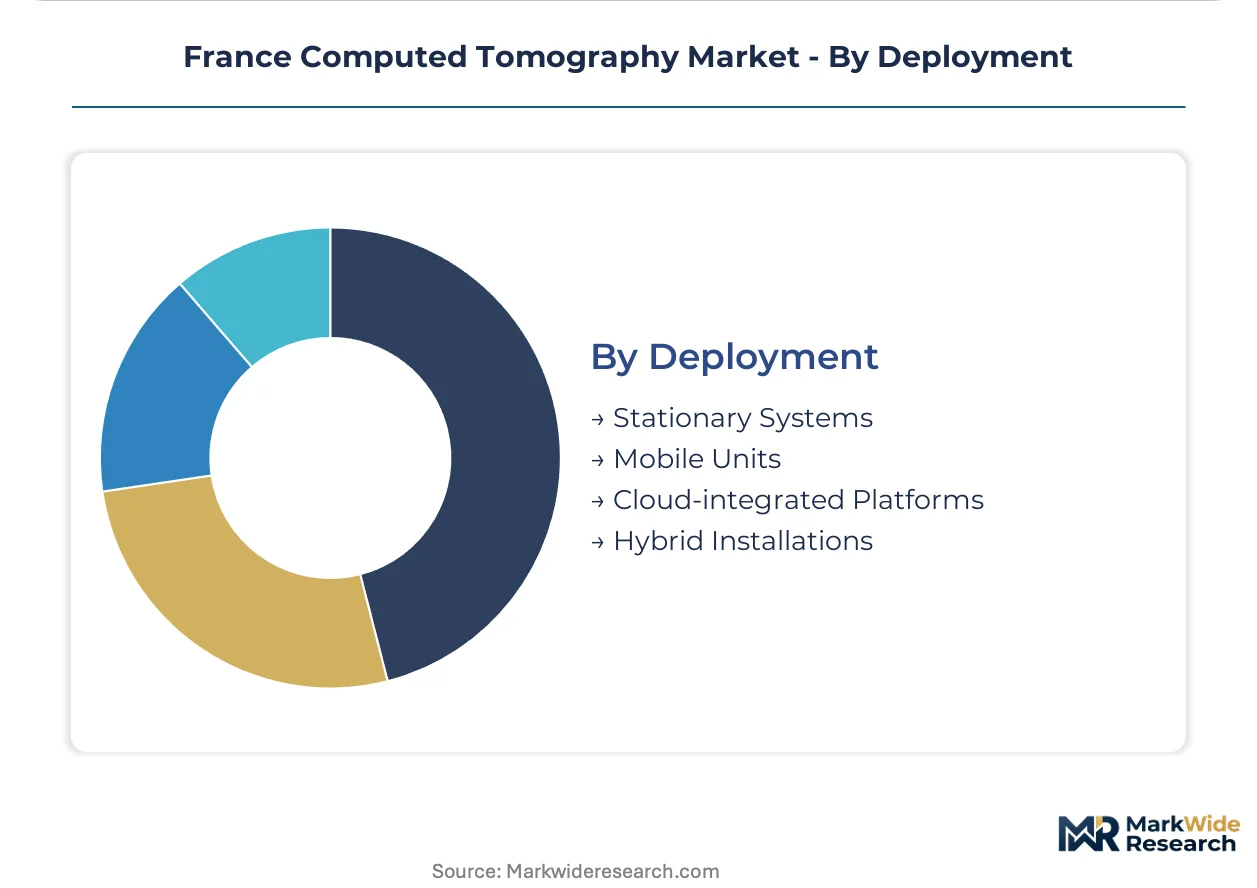
Deployment:
Physical installation constraints and data architecture requirements determine total cost of ownership calculations for French buyers.
- Stationary Systems:Fixed-room installations with dedicated power infrastructure and lead-shielded suites. ANSM market authorization and CE marking under EU MDR establish conformity requirements for these conventional hospital deployments.
- Mobile Units:Trailer-mounted or self-propelled systems for temporary deployment and rural coverage extension.
- Cloud-integrated Platforms:Vendor-neutral archive systems with AI-assisted reconstruction and multi-site data consolidation. Regional hospital groups adopt these to unify imaging data across dispersed sites and enable remote diagnostic collaboration.
- Hybrid Installations:Combined fixed and mobile configurations with shared detector technology.
Stationary systems dominate capital expenditure; cloud-integrated platforms show steepest expansion trajectory on GHT consolidation mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France produces minimal CT equipment domestically while consuming sophisticated imaging systems across its hospital networks. The Île-de-France region anchors national procurement volumes through Parisian academic medical centers. Regional hospital groups in peripheral zones rely on centralized purchasing structures to access equivalent technology tiers.
Île-de-France
Parisian university hospitals drive demand for 128-slice and photon-counting CT systems under Ségur de la Santé infrastructure renewal mandates. ANSM market authorization requirements compress procurement cycles for EU MDR-compliant platforms. The Greater Paris hospital network concentrates service engineering talent and anchors referral volumes for complex cardiovascular and oncological imaging protocols.
Auvergne-Rhône-Alpes
Lyon-based academic medical centers pilot photon-counting detector systems for plaque characterization and spectral imaging research. The EU Green Deal pushes procurement committees toward energy-efficient platforms with reduced helium dependency. Cross-border patient flows with Geneva and Swiss university hospitals standardize equipment specifications around dual-energy CT protocols in the Rhône corridor.
Provence-Alpes-Côte d'Azur
Independent diagnostic imaging centers in Marseille and Nice form cooperative procurement alliances to match public hospital volume discounts on multi-slice systems. CE marking under EU MDR establishes conformity requirements for outpatient clinic deployments. The region's aging population profile expands demand for portable CT units in intensive care settings across coastal hospital networks.
Grand Est
Strasbourg and Nancy hospital groups standardize around dual-energy CT to ensure compatibility with German and Swiss oncology referral networks. The EU AI Act's risk classification for diagnostic software creates validation service demand around CT-integrated algorithms. Cross-border healthcare integration with Baden-Württemberg and Basel drives equipment specification convergence in the Upper Rhine metropolitan zone.
Hauts-de-France
Lille university hospitals modernize aging single-slice fleets under compressed EU MDR transitional deadlines. Regional health agencies channel Ségur de la Santé investment toward diagnostic infrastructure in former industrial zones with elevated cardiovascular disease burdens. The Lille metropolitan cluster anchors procurement for northern France while maintaining interoperability with Belgian hospital networks in the Eurometropolis Lille-Kortrijk-Tournai zone.
France Computed Tomography Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with deep installed base relationships. French hospital procurement favors vendors offering localized technical support networks and long-term service contracts. Three archetypes dominate: integrated imaging system manufacturers with detector technology specialization, diversified healthcare conglomerates with broad modality portfolios, and regional Asian manufacturers competing on capital cost. Consolidation through Groupements Hospitaliers de Territoire purchasing is compressing vendor margins while extending contract durations.
Among the diversified healthcare conglomerates, GE Healthcare, Siemens Healthineers AG, and Canon Medical Systems Corporation occupy positions shaped by installed base legacy and service infrastructure depth. GE Healthcare leverages historical relationships with French public hospitals to sustain recurring revenue streams. Siemens Healthineers AG anchors its position through manufacturing proximity and direct field engineering networks. Canon Medical Systems Corporation exemplifies specialization strategy through detector technology focus in cardiovascular imaging suites. These three conglomerates represent distinct competitive postures—legacy service lock-in, localized production advantage, and component-level technical differentiation—rather than interchangeable market presence.
| Leading Market Players |
|---|
| GE Healthcare |
| Canon Medical Systems Corporation |
| Koninklijke Philips NV |
| Siemens Healthineers AG |
| Koning Corporation |
| Planmeca Group |
| Carestream Health |
| Fujifilm Holdings Corporation |
| Neusoft Medical Systems Co Ltd |
| Others |
Supply & Pricing Matrix
Captive helium sourcing from Qatar and Algeria anchors CT magnet cooling supply positions while simultaneously constraining French buyers' pricing leverage through long-term offtake dependencies. This upstream integration pattern forces hospital procurement committees to absorb volatility pass-through clauses in service contracts, compressing negotiation room on detector array replacements.
Pricing Analysis
Margin tightening in the mid-slice tier reflects Groupements Hospitaliers de Territoire consolidation mandating volume-discount thresholds across regional hospital networks. Three-tier pricing structure across premium photon-counting, standard multi-slice, and economy refurbished systems stratifies by detector generation and AI reconstruction bundling. Cost-down pressure on portable CT accelerates because independent imaging centers in Provence-Alpes-Côte d'Azur match public hospital procurement scale through cooperative alliances. Diagnostic laboratories exhibit highest price sensitivity due to reimbursement rate compression, while Parisian university hospitals prioritize spectral capability over capital cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth processing for scintillator crystals and German precision machining for rotating gantry bearings. Detector array manufacturing draws from Japan, South Korea, and the United States for photodiode substrates and ASIC fabrication. Helium extraction concentrates in Qatar, Algeria, and Russia, exposing French buyers to commodity price volatility and logistics chokepoint risks from Mediterranean shipping corridors. Distribution runs through authorized vendor field engineering networks with direct hospital technical support contracts, bypassing independent distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France CT market functions as a vertical-integration race where detector technology ownership and captive service talent determine margin retention. Incumbents and challengers alike must secure upstream component access or downstream installation lock-in to defend positioning.
For Market Incumbents: Lock in long-term helium supply agreements with Algerian extraction partners before Qatar expands Asian offtake commitments. Acquire regional biomedical engineering training programs in Auvergne-Rhône-Alpes to preempt talent scarcity risks from Île-de-France concentration. Defend against Asian capital-cost entrants by embedding predictive maintenance algorithms into existing installed bases, transferring EU MDR compliance documentation burdens to vendor-side registries. For New Entrants and Emerging Players: Capture portable CT white space in intensive care neurological assessment across Hauts-de-France and Grand Est peripheral hospital networks. Target cooperative procurement alliances in Provence-Alpes-Côte d'Azur as the most penetrable channel structure outside centralized GHT purchasing. Enter through cloud-integrated platform partnerships with regional hospital groups consolidating multi-site imaging data, sidestepping capital-intensive gantry manufacturing. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified imaging conglomerates seeking detector technology specialization or French service infrastructure depth. Five-to-ten year viability hinges on photon-counting detector commercialization timelines and EU AI Act validation service revenue maturation. Monitor CE marking authorization velocity under EU MDR as the critical inflection signal—extended timelines favor incumbents with regulatory affairs scale, compressed windows enable agile specialist acquisition.| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting Detector Commercialization | Spectral imaging capabilities secure premium positioning in Parisian university hospital tenders. |
| EU MDR Compliance Service Bundling | Post-market surveillance registries transfer documentation burden from ANSM to vendor accountability. |
| Helium Supply Diversification | Algerian extraction partnerships reduce dependency on Qatar-Russia logistics corridors. |
| Cloud-Integrated Platform Deployment | Vendor-neutral archives enable Groupements Hospitaliers de Territoire multi-site consolidation mandates. |
| Biomedical Engineer Training Programs | Auvergne-Rhône-Alpes talent pipelines address Île-de-France service concentration risks. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, GPO contract databases, and ANSM market authorization filings underwrites the qualitative findings in this study. Primary fieldwork engaged biomedical engineers, radiology department heads, and vendor account managers across Île-de-France, Auvergne-Rhône-Alpes, and Grand Est hospital networks. Secondary validation sourced EU MDR transition guidance documents, Ségur de la Santé infrastructure investment disclosures, and CE marking authorization timelines. Bottom-up equipment procurement tracking and top-down healthcare expenditure modeling triangulate volume estimates.
Comparable-period anchoring to pre-COVID baseline years and post-Ségur investment acceleration phases structures the forecast window across the analysis window. Segmentation modeling incorporates slice count tiers, deployment configurations, and end-user institutional types alongside EU Green Deal compliance scoring as a cross-cutting dimension. CAGRs derive from installed base replacement cycles, EU MDR transitional deadline compression, and spectral imaging adoption curves in academic medical centers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to helium market restructuring, photon-counting detector cost-down trajectories, and EU AI Act enforcement calibration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Preclinical MRI Equipment Market
Medical Imaging
South Korea Mammography Market
Medical Imaging
South Africa Mammography Market
Medical Imaging
Spain Nuclear Imaging Market
Medical Imaging
Middle East and Africa Mammography Market
Medical Imaging
Global Veterinary X-Ray Market
Medical Imaging
Ultrasound Image Processing Software Market
Medical Imaging
PSMA-PET Imaging Market
Medical Imaging
Mammography Workstation Market
Medical Imaging
South Africa Diagnostic Imaging Equipment Market
Medical Imaging
Portable Ultrasound Bladder Scanner Market
Medical Imaging
France Diagnostic Imaging Equipment Market
Medical Imaging
Global Portable Magnetic Resonance Imaging Market
Medical Imaging
Intravascular Imaging Market
Medical Imaging
Perfusion Imaging Market
Medical Imaging
Argentina Mammography Market