
 Spain Digital Radiology Market | 2026-2036
Spain Digital Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Digital Radiology Market Insights
Aftermarket service revenue is rewriting profit allocation across the Spain digital radiology landscape. Siemens Healthineers leverages its pan-European service infrastructure to capture long-term maintenance contracts. GE Healthcare anchors its position through localized refurbishment operations in Iberia. Philips competes on software upgrade cycles that extend hardware lifecycles.
Digital radiology encompasses ionizing and non-ionizing imaging modalities that convert anatomical data into digital matrices for diagnostic interpretation, with detector resolution, DICOM compliance, and radiation dose optimization serving as core performance parameters. Computed Tomography leads capital expenditure flows due to stroke and trauma protocol requirements, while AI-Driven Diagnostics represents the fastest-expanding technology segment as Spanish hospitals integrate algorithmic triage into emergency workflows. Digital X-Ray retains volume dominance across primary care clinics where throughput economics favor lower unit costs.
Spain's Ministry of Health interoperability mandates and CE marking under the EU Medical Device Regulation shape procurement criteria and software validation requirements for installed systems. The Spanish Agency for Medicines and Health Products enforces post-market surveillance protocols that elevate service documentation standards. Stakeholders must monitor how Madrid's regional health authority balances AI procurement against radiologist workforce constraints.
Market Dynamics
Spain's Ministry of Health interoperability mandates under the National Health System's digitalization framework are forcing radiology departments to replace legacy analog infrastructure with AI-integrated imaging suites. Public hospital networks in Madrid and Barcelona are accelerating procurement cycles to meet compliance deadlines.
Growth Catalysts
- EU Medical Device Regulation (MDR):CE marking requirements for software validation are upgrading installed base quality standards across Spanish healthcare facilities.
- Stroke protocol expansion:Emergency departments in tertiary hospitals are mandating sub-minute CT turnaround times that only digital radiology workflows can deliver.
- AI algorithmic triage:Integration of machine learning into emergency workflows is compressing diagnostic latency and reducing radiologist workload bottlenecks.
Market Restraints
- Detector component concentration:Supply of flat-panel detectors concentrates among Asian semiconductor fabricators, exposing Spanish OEMs to input volatility.
- Radiologist workforce scarcity:Spain's specialist training pipeline produces insufficient diagnostic radiologists to operate expanded imaging capacity.
- Capital intensity barriers:CT and MRI suites require multimillion-euro installations that strain budgets of autonomous community health services.
Strategic Opportunities
- Andalusian primary care network:Underpenetrated rural clinics in southern Spain present whitespace for portable digital X-ray deployment.
- Cloud-native PACS architectures:Convergence of edge computing with DICOM streaming is enabling centralized image management across dispersed hospital networks.
- EU Green Deal procurement criteria:Energy efficiency mandates in public tenders favor low-dose digital modalities over legacy equipment.
Industry Challenges
- AI validation timelines:Spain's Agency for Medicines and Health Products enforces extended post-market surveillance documentation that delays algorithm deployment.
- Legacy system integration:Interoperability between new AI-integrated suites and existing hospital information systems requires costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Digital Radiology Market |
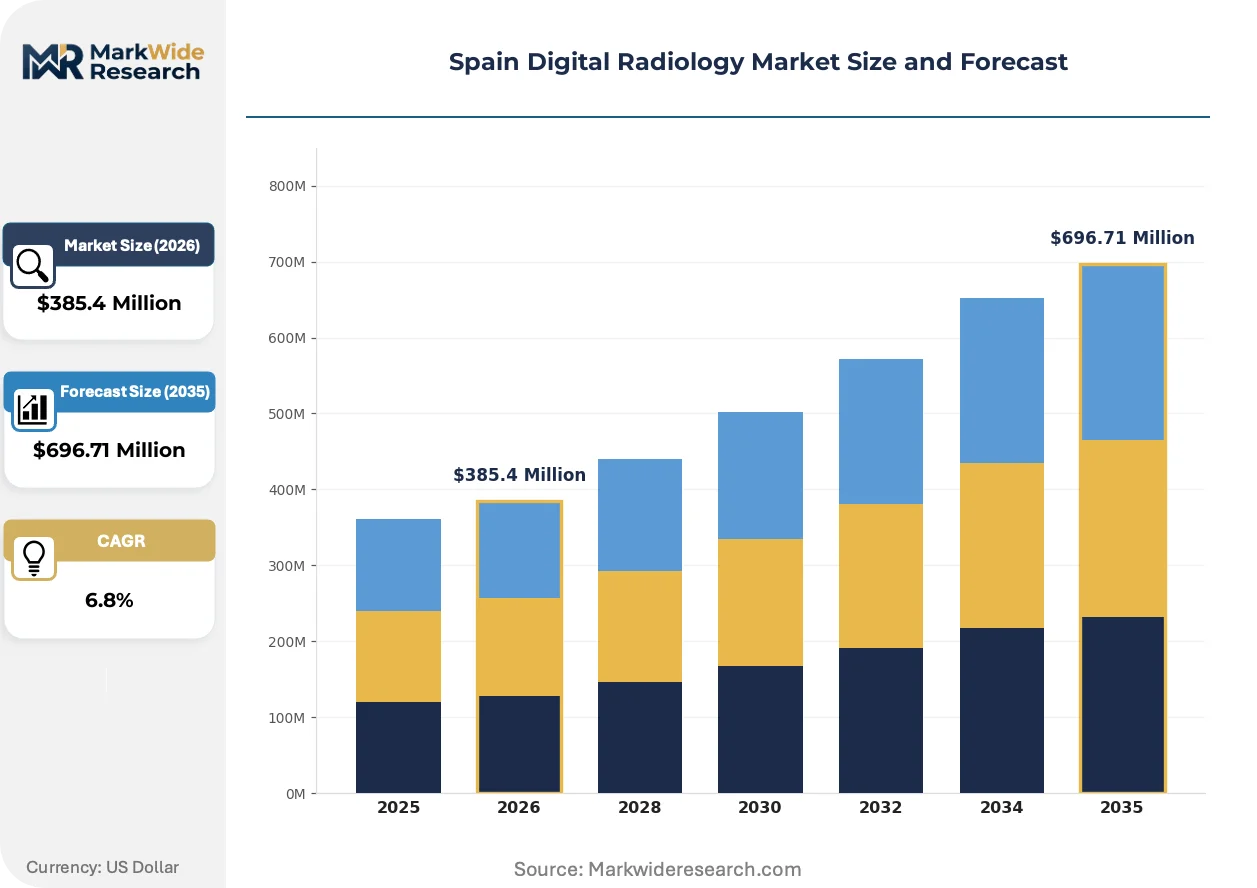
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Computed Tomography, Digital X-Ray, MRI Systems, Ultrasound End User: Hospitals, Imaging Centers, Clinics, Research Institutions Technology: Cloud-Based Solutions, On-Premise Systems, Hybrid Solutions, AI-Driven Diagnostics Application: Oncology, Orthopedics, Cardiology, Emergency Care |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips, Fujifilm Holdings Corporation, Canon Medical Systems Corporation, Hologic, Carestream Health, Sedecal, Shimadzu Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Digital Radiology Market Trends and Innovations
Spain's radiology sector is experiencing accelerated technology convergence as regulatory pressure and workforce constraints force simultaneous investment in automation and connectivity. Three distinct shifts are reshaping competitive positioning.
Photon-counting CT detector technology is hybridizing spectral imaging capabilities with conventional anatomical scanning. Madrid's tertiary hospital cluster is piloting installations that separate calcium from iodine contrast without dual-energy protocols. Siemens Healthineers and Philips are compressing upgrade cycles as Spanish buyers demand hardware that accommodates future software iterations.
Spain's transposition of the EU AI Act into national healthcare procurement rules is creating algorithmic accountability requirements for diagnostic software. The Spanish Agency for Medicines and Health Products now mandates explainability documentation for machine learning tools used in emergency triage. Barcelona's specialized oncology centers are responding by establishing internal validation protocols that exceed baseline regulatory thresholds.
Public hospital consortia are consolidating purchasing authority through autonomous community-level tendering platforms that bypass traditional distributor relationships. Valencia's regional health authority recently centralized radiology procurement for 23 hospitals, compressing vendor margins while demanding extended service bundling. This concentration is most visible in Catalonia, where the CatSalut agency negotiates system-wide maintenance contracts that unbundle hardware from software upgrade pricing.
Spain Digital Radiology Market Segmentation
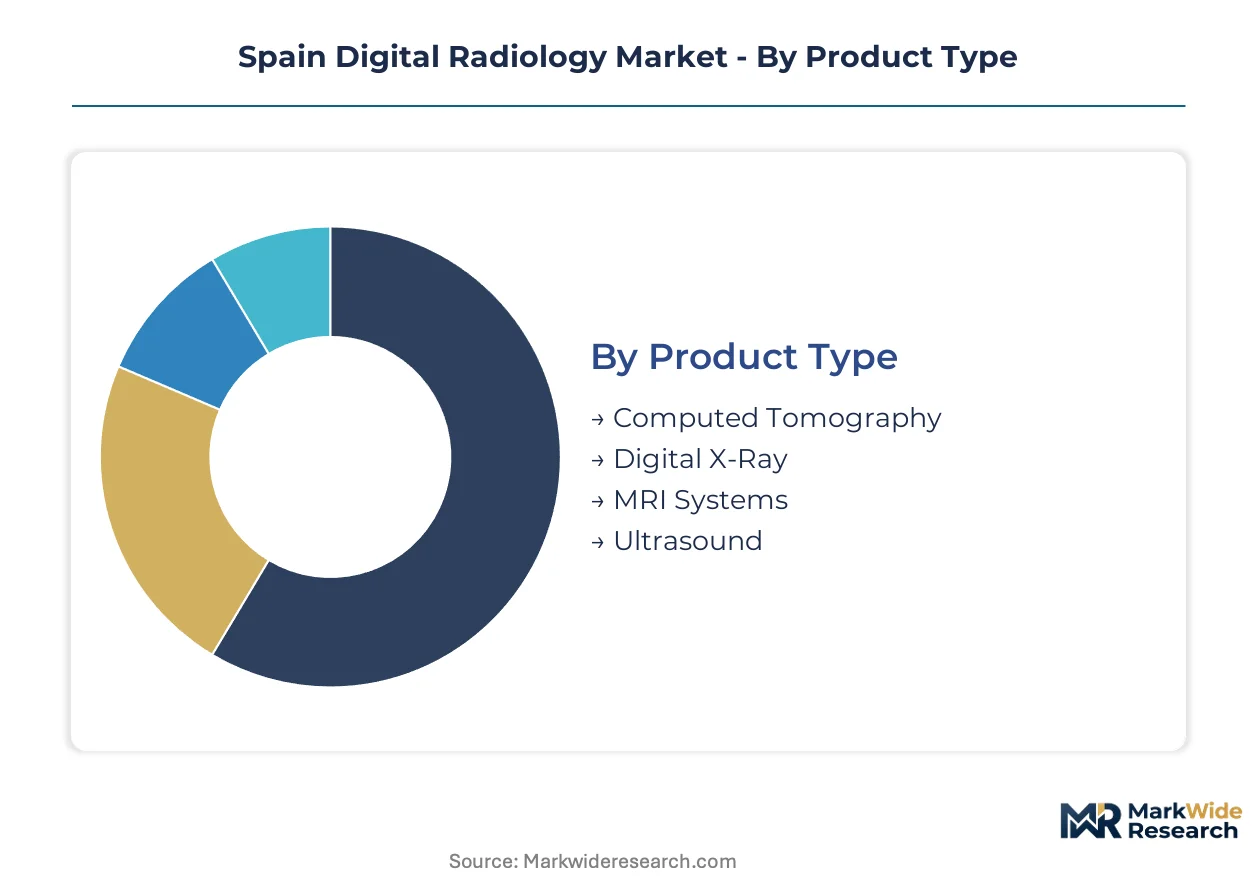
Spain's digital radiology market fragments across four critical dimensions that determine procurement patterns and technology deployment. Equipment specifications, care setting requirements, infrastructure architectures, and clinical use cases each create distinct competitive arenas with specialized vendor positioning.
Product Type:
Capital intensity and throughput economics divide equipment procurement across Spanish healthcare networks.
- Computed Tomography:Multi-detector systems with sub-millimeter slice resolution dominate tertiary hospital capital budgets. Stroke and trauma protocols in Madrid's emergency departments mandate sub-minute CT turnaround times that drive replacement cycles.
- Digital X-Ray:Flat-panel detector systems with wireless image transmission anchor primary care throughput. Andalusian rural clinics deploy portable units where infrastructure constraints exclude fixed-room installations.
- MRI Systems:3T superconducting magnets with parallel imaging capabilities serve neurological and musculoskeletal diagnostics. Barcelona's specialized oncology centers prioritize spectral capabilities for tumor characterization.
- Ultrasound:Point-of-care systems with elastography and contrast-enhanced modes expand interventional radiology workflows. Portable configurations address mobility requirements across decentralized clinic networks.
Digital X-Ray commands the established base. The steepest expansion runs through AI-Driven Diagnostics integration across CT modalities.
End User:
Procurement authority and patient volume concentration shape vendor engagement strategies across care settings.
- Hospitals:Tertiary centers with 24/7 emergency services drive premium system specifications. CatSalut's centralized purchasing for Catalonia's 23 hospitals compresses margins while demanding extended service bundling.
- Imaging Centers:Dedicated facilities optimize throughput economics with high-utilization equipment configurations. Private operators in Madrid prioritize rapid scan protocols that maximize daily patient volumes.
- Clinics:Primary care networks require compact systems with simplified operator interfaces. Valencia's regional health authority specifications emphasize DICOM interoperability with centralized PACS architectures.
- Research Institutions:Academic medical centers demand experimental imaging capabilities and algorithm development platforms. Barcelona's oncology research hubs validate AI tools that exceed baseline regulatory thresholds.
Hospitals anchor procurement volume. Imaging centers are gaining share fastest as private capital consolidates outpatient diagnostics.
Technology:
Infrastructure architecture decisions determine software validation requirements and long-term upgrade pathways.
- Cloud-Based Solutions:DICOM streaming architectures with edge computing nodes enable centralized image management. Spain's Ministry of Health interoperability mandates favor cloud-native deployments that simplify cross-facility data exchange.
- On-Premise Systems:Local server installations with air-gapped security configurations persist in facilities with stringent data sovereignty requirements. Legacy hardware dependencies slow migration timelines in budget-constrained autonomous communities.
- Hybrid Solutions:Mixed architectures partition sensitive diagnostics locally while streaming routine studies to cloud repositories. Madrid's tertiary hospital cluster pilots configurations that balance latency requirements with storage economics.
- AI-Driven Diagnostics:Algorithmic triage tools with explainability documentation compress diagnostic latency. Spain's Agency for Medicines and Health Products enforces extended post-market surveillance that delays deployment timelines.
On-Premise Systems command the installed base. Cloud-Based Solutions are climbing the fastest as regional health authorities consolidate purchasing platforms.
Application:
Clinical specialty requirements drive detector specifications, contrast protocols, and workflow automation priorities.
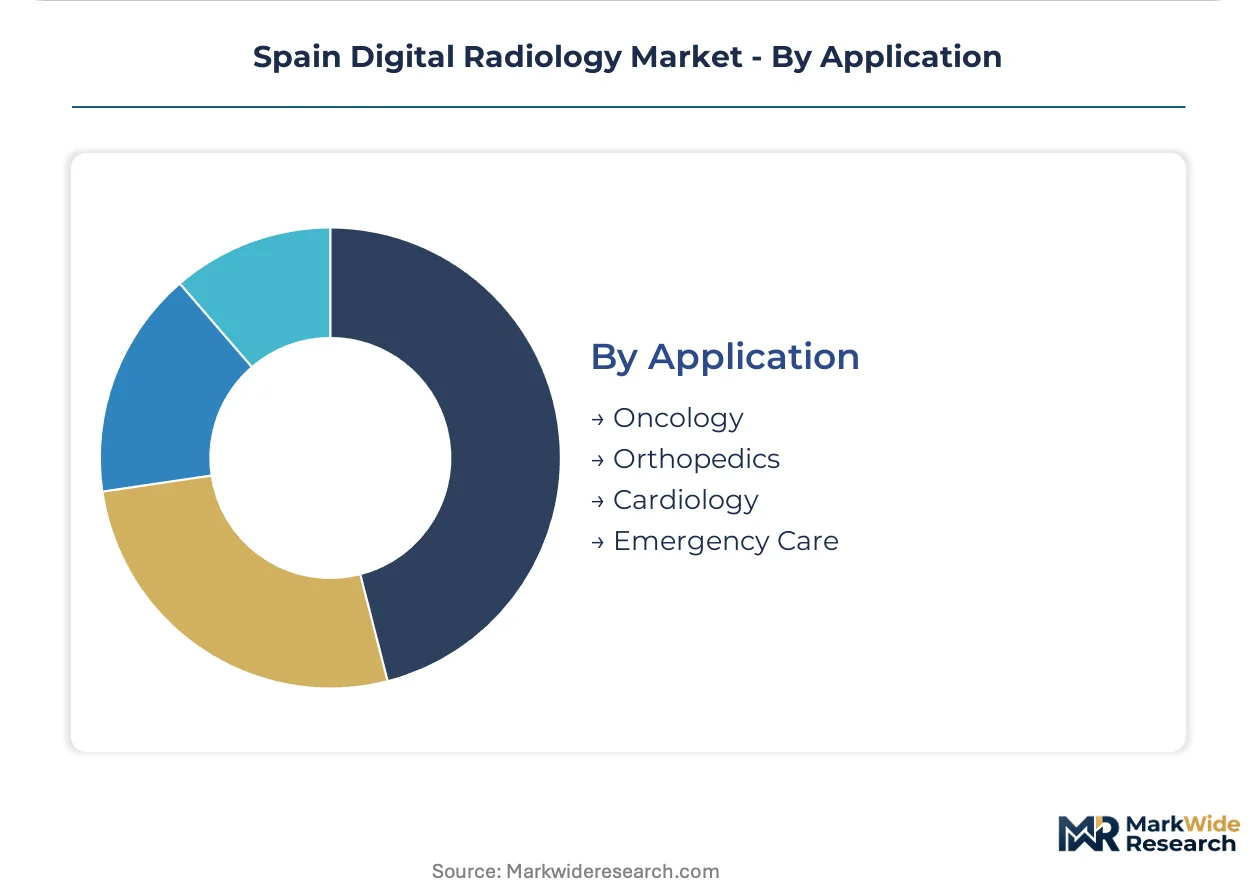
- Oncology:Quantitative imaging biomarkers with standardized response criteria guide therapeutic monitoring. Barcelona's specialized centers deploy spectral CT and multiparametric MRI for precision tumor characterization.
- Orthopedics:Weight-bearing digital X-ray and high-resolution MRI protocols support surgical planning. Sports medicine clinics in Madrid prioritize rapid musculoskeletal diagnostics for athlete populations.
- Cardiology:Coronary CT angiography with fractional flow reserve computation reduces invasive catheterization rates. Tertiary hospitals integrate cardiac imaging into comprehensive stroke center certifications.
- Emergency Care:Trauma protocols with whole-body CT scanning demand automated exposure control and rapid reconstruction. Sub-minute turnaround requirements drive AI-integrated workflow automation in Madrid's emergency departments.
Emergency Care anchors system utilization. Oncology is gaining share fastest as precision medicine protocols expand imaging intensity per patient.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Autonomous communities with concentrated tertiary capacity show limited price elasticity for AI-integrated suites, while rural networks in southern Spain exhibit acute sensitivity to unit economics and service bundling terms.
Madrid
The capital's emergency stroke protocols drive sub-minute CT turnaround requirements across Hospital Universitario La Paz and Gregorio Marañón complexes. Spain's Ministry of Health interoperability mandates accelerate replacement of legacy analog infrastructure. The Madrid tertiary hospital cluster anchors national procurement volume for photon-counting detector systems.
Catalonia
Barcelona's specialized oncology centers prioritize spectral imaging capabilities for precision tumor characterization under precision medicine protocols. CatSalut's centralized purchasing for 23 hospitals compresses vendor margins while demanding extended service bundling. The Vall d'Hebron and Hospital Clínic complexes validate AI tools exceeding baseline regulatory thresholds.
Andalusia
Rural primary care networks in Seville, Málaga, and Córdoba provinces present whitespace for portable digital X-ray deployment where fixed-room installations prove economically unviable. The Andalusian regional health authority specifications emphasize DICOM interoperability with centralized PACS architectures. Underpenetrated clinics drive volume economics favoring lower unit cost configurations.
Basque Country
Osakidetza's integrated health system consolidates procurement authority across Bilbao, San Sebastián, and Vitoria-Gasteiz facilities. EU Green Deal procurement criteria favor energy-efficient low-dose modalities in public tendering. The region's industrial automation heritage accelerates adoption of cloud-native imaging architectures.
Valencia
The regional health authority recently centralized radiology procurement for 23 hospitals, compressing vendor margins while demanding extended service bundling. Valencia's specifications emphasize hybrid cloud architectures partitioning sensitive diagnostics locally while streaming routine studies. The Hospital General Universitario network pilots edge computing configurations balancing latency requirements with storage economics.
Spain Digital Radiology Market Competitive Landscape
Capability concentration sits with multinational imaging conglomerates possessing pan-European service infrastructures; scale advantage sits with regional distributors leveraging localized refurbishment operations. The market structure exhibits tiered consolidation where premium hardware vendors, mid-tier refurbishment specialists, and software-centric challengers occupy distinct competitive bands. Three strategic archetypes dominate: integrated modality manufacturers, aftermarket service aggregators, and AI-native workflow disruptors. M&A activity concentrates on software upgrade capabilities and cloud-native PACS architectures, while strategic partnerships target interoperability middleware development.
Among the integrated modality tier, GE Healthcare, Siemens Healthineers, and Koninklijke Philips occupy positions exemplifying contrasting geographic and structural approaches. GE Healthcare represents the American diversified conglomerate model with extensive Iberian refurbishment footprints. Siemens Healthineers anchors the German engineering-centric archetype with pan-European service infrastructure leverage. Koninklijke Philips exemplifies the Dutch health technology convergence play prioritizing software upgrade cycles over hardware refresh velocity.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips |
| Fujifilm Holdings Corporation |
| Canon Medical Systems Corporation |
| Hologic |
| Carestream Health |
| Sedecal |
| Shimadzu Corporation |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in flat-panel detector fabrication across East Asian semiconductor hubs is compressing input costs while Madrid's tertiary hospital cluster exploits buyer concentration to extract extended service bundling from OEMs. Spain's Ministry of Health interoperability mandates accelerate replacement cycles, forcing vendors to absorb upfront certification costs that reshape contract economics across autonomous community procurement platforms.
Pricing Analysis
Long-term service bundling dominates contract structures as CatSalut and Valencia's regional health authority negotiate multi-year maintenance agreements that unbundle hardware from software upgrade pricing. Price differentiation hinges on CE marking tier under EU Medical Device Regulation and after-sales service depth, with premium AI-integrated suites commanding substantial margins over refurbished analog replacements. Cost compression in portable digital X-ray configurations is intensifying as Andalusian rural clinics prioritize unit economics over spectral capabilities. Public hospital networks show lowest price sensitivity due to compliance-driven procurement, while private imaging centers in Madrid negotiate aggressively on throughput guarantees.
Supply Chain Analysis
Export control regimes restricting semiconductor lithography equipment to China are rerouting flat-panel detector supply chains through South Korea and Japan, elevating input costs for Spanish OEMs. Manufacturing concentration in Taiwan, Germany, and the Netherlands governs photon-counting CT detector availability, with rare earth magnet sourcing from China and superconducting wire supply from Japan anchoring MRI system production. Single-source vulnerability in ASML-dependent lithography creates chokepoint exposure for next-generation detector fabrication. Distribution runs through autonomous community-level tendering platforms that consolidate purchasing authority and compress traditional distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's digital radiology sector represents high-growth disruption as EU AI Act transposition forces algorithmic accountability requirements that reshape competitive viability across software-centric challengers and integrated modality incumbents alike.
For Market Incumbents: Entrench service infrastructure dominance by extending pan-European maintenance contracts into AI upgrade cycles that lock hospital networks into proprietary software ecosystems. Siemens Healthineers and GE Healthcare should deepen backward integration into detector refurbishment operations within Iberia to defend against margin compression from centralized procurement. Certification investment in explainability documentation for emergency triage algorithms constitutes the critical defensive lever against AI-native workflow disruptors.
For New Entrants and Emerging Players: Build out cloud-native PACS architectures targeting Andalusian primary care networks where DICOM interoperability mandates create whitespace beyond incumbent legacy system dependencies. Portable digital X-ray deployment in underpenetrated rural clinics offers the most penetrable entry vector, with hybrid cloud configurations partitioning sensitive diagnostics locally while streaming routine studies. Go-to-market execution should leverage direct relationships with regional health authorities bypassing traditional equipment distributors.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across AI-driven diagnostics as software validation timelines compress hardware refresh velocity and extend useful equipment lifecycles. Acquisition targets should emphasize algorithm development platforms with established post-market surveillance documentation exceeding Spain's Agency for Medicines and Health Products baseline thresholds. Monitor CatSalut procurement patterns as the inflection signal for when centralized purchasing authority spreads to additional autonomous communities.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU Medical Device Regulation compliance unlocks procurement eligibility across Spain's public hospital networks. |
| Hospital System Partnership | CatSalut's centralized purchasing for 23 hospitals demands extended service bundling beyond hardware transactions. |
| Software Companion Development | AI algorithmic triage integration compresses diagnostic latency in Madrid's emergency stroke protocols. |
| Backward Integration | Localized detector refurbishment operations in Iberia defend margin position against centralized procurement pressure. |
| Reimbursement Strategy | Precision medicine protocol alignment in Barcelona's oncology centers drives spectral imaging capability prioritization. |
Research Methodology
The analysis maps AI-driven diagnostics, photon-counting CT, cloud-native PACS, and portable digital X-ray sub-sectors, each validated through hospital procurement managers, biomedical engineers, GPO contracts managers, and regional health authority technology officers. Primary interviews with Siemens Healthineers service executives, GE Healthcare refurbishment specialists, and Philips software upgrade strategists combined with secondary validation against EU Medical Device Regulation filings, Spain's Agency for Medicines and Health Products surveillance databases, and autonomous community tendering platform records. Bottom-up equipment shipment analysis and top-down healthcare expenditure triangulation anchored market sizing across the projection horizon.
Assumption sets held fixed Spain's Ministry of Health interoperability mandate compliance deadlines and EU AI Act transposition timelines while varying autonomous community budget allocation patterns and radiologist workforce pipeline output. Segmentation modeling spanned product type, end user, technology architecture, and clinical application dimensions, with CAGRs derived from replacement cycle analysis and AI integration penetration curves. Forecast inputs incorporated stroke protocol expansion intensity, photon-counting detector adoption rates in Madrid's tertiary cluster, and cloud-native PACS deployment velocity across regional health authority consolidation initiatives.
Practitioners should monitor EU export control regime evolution for semiconductor lithography equipment and Spain's radiologist training pipeline output for early signals of workforce constraint alleviation. Forecasts reflect assumptions regarding autonomous community budget stability and EU Medical Device Regulation enforcement consistency. Material shifts in detector component trade flows or AI validation timeline extensions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
South America MRI Market
Medical Imaging
Medical Imaging Outsourcing Market
Medical Imaging
Medical X-Ray Films Market
Medical Imaging
Contrast Media Market
Medical Imaging
Radio-Fluoroscopy Systems Market
Medical Imaging
CT Guided Intervention Market
Medical Imaging
Germany Nuclear Imaging Market
Medical Imaging
Cranial Doppler Market
Medical Imaging
Canada Digital Radiology Market
Medical Imaging
Open System MRI Market
Medical Imaging
Ultrasound Consoles and Transducers Market
Medical Imaging
South Africa Computed Tomography Market
Medical Imaging
Global 3D Laparoscopy Imaging Market
Medical Imaging
Veterinary CT Imaging Market
Medical Imaging
Positron Emission Tomography Devices (PET) Market
Medical Imaging
Japan Mammography Market