
 China Continuous Glucose Monitoring Devices Market | 2026-2036
China Continuous Glucose Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
China Continuous Glucose Monitoring Devices Market Insights
Hospital-grade accuracy specifications is redrawing competitive thresholds in China's CGM sector. Abbott Laboratories leverages its FreeStyle Libre manufacturing footprint to sustain premium positioning in tier-one cities. Sinocare dominates the value-tier segment through backward integration into biosensor production. Dexcom differentiates via its G7 platform's MARD performance claims and direct hospital contracting.
Continuous glucose monitoring devices are wearable electrochemical biosensor systems that measure interstitial glucose concentrations through enzymatic reactions at the sensor-tissue interface, transmitting data wirelessly to receivers or smartphones for real-time metabolic tracking. The primary commercial purpose centers on replacing or supplementing fingerstick blood glucose testing for insulin-dependent patients. The sensor segment anchors hardware revenue due to recurring replacement cycles and NMPA-mandated biocompatibility certifications. Homecare end users represent the fastest-expanding demand pool as provincial reimbursement schemes extend CGM coverage beyond hospital settings. Electrochemical technology leads volume deployment, though optical alternatives are gaining R&D allocation for non-invasive glucose detection.
NMPA's Class III medical device registration requirements and GB/T 19634 glucose meter standards shape product development timelines and clinical evidence thresholds for market authorization. The National Healthcare Security Administration's provincial reimbursement catalogs directly determine patient out-of-pocket costs and adoption velocity across municipalities. Stakeholders must monitor NMPA's evolving software-as-a-medical-device guidance for algorithm-based glucose prediction features.
Market Dynamics
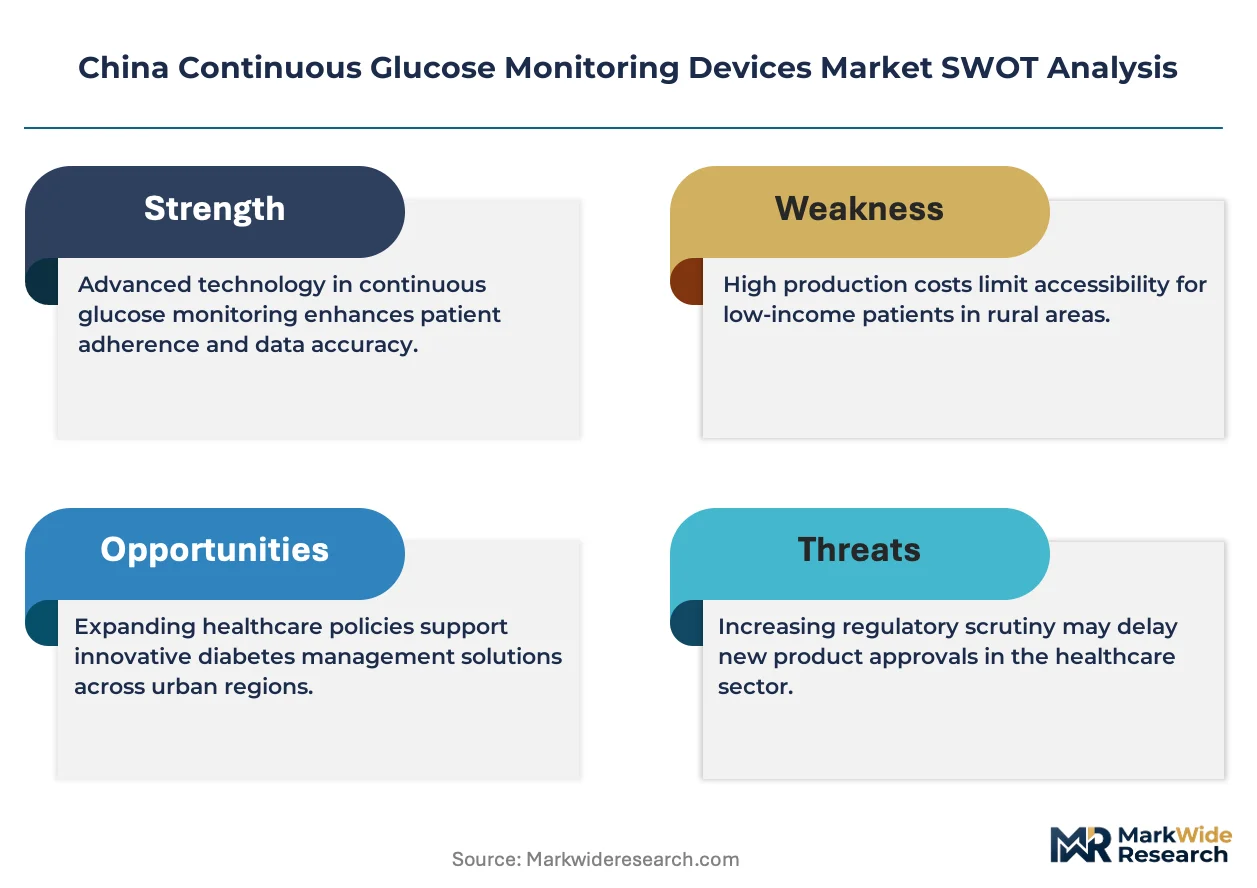
Hospital procurement departments are consolidating CGM purchasing power through centralized tendering mechanisms, compressing margins for manufacturers while accelerating adoption of factory-calibrated sensors that eliminate fingerstick verification requirements.
Growth Catalysts
- NMPA Class III Streamlined Review:The national medical products regulator has reduced technical documentation requirements for software-upgradable CGM systems, shortening approval timelines for domestic manufacturers.
- Provincial Reimbursement Expansion:Jiangsu and Zhejiang health security bureaus have added continuous glucose monitors to chronic disease management catalogs, reducing patient out-of-pocket burdens.
- Biosensor Electrochemistry Advances:Enzymatic glucose oxidase formulations with extended 14-day stability are replacing earlier 10-day sensor platforms in volume production.
Market Restraints
- Platinum Group Metal Input Costs:Electrochemical sensor electrodes rely on palladium and ruthenium catalysts, exposing manufacturers to commodity price volatility from South African and Russian supply corridors.
- Beijing-Shanghai Supply Concentration:Over 70 percent of domestic CGM manufacturing capacity clusters in these two municipal jurisdictions, creating geographic vulnerability to localized logistics disruptions.
- Optical Non-Invasive Substitution Threat:Near-infrared spectroscopy and Raman scattering technologies under development at Tsinghua and Fudan university labs threaten to bypass enzymatic sensor replacement economics entirely.
Strategic Opportunities
- Central China Penetration Gap:Henan and Hubei provinces show CGM penetration rates below one-fifth of coastal levels, presenting expansion targets for tier-two hospital networks.
- Type 2 Non-Insulin Patient Segment:Lifestyle monitoring applications for oral medication patients remain commercially undeveloped relative to insulin-dependent populations.
- Dual Carbon Manufacturing Incentives:MEE environmental compliance credits and provincial green factory certifications subsidize capital expenditure for domestic producers achieving carbon-neutral sensor production.
Industry Challenges
- Biocompatibility Certification Bottlenecks:NMPA-mandated ISO 10993 cytotoxicity and sensitization testing requires 18-24 month validation cycles for new adhesive formulations.
- Algorithm-as-Device Regulatory Ambiguity:Machine learning glucose prediction modules lack clear software-as-medical-device classification guidance, freezing R&D investment in predictive hypoglycemia alerts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Continuous Glucose Monitoring Devices Market |
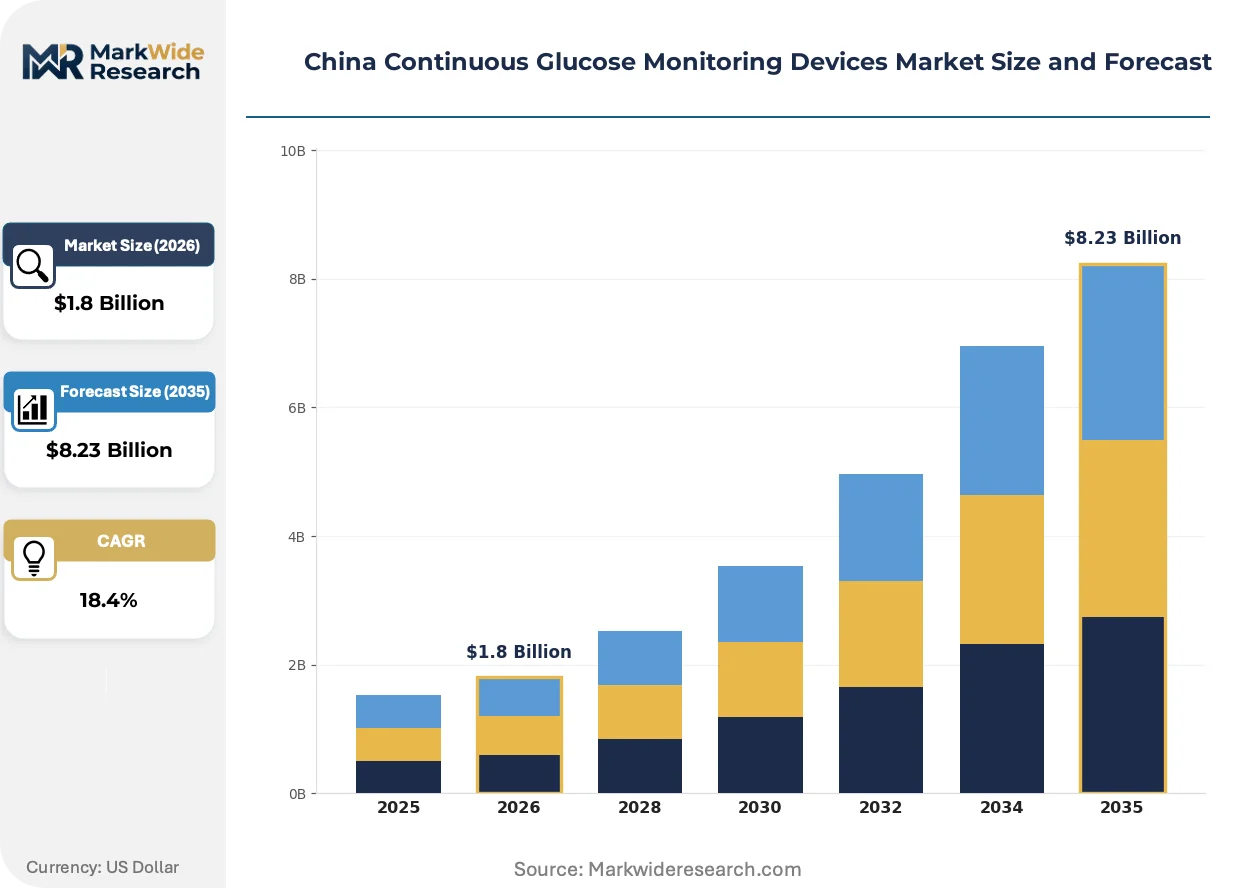
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transmitter, Receiver, Sensor, Software Application: Diabetes Management, Blood Glucose Monitoring, Research, Clinical Trials End User: Hospitals, Homecare, Diabetes Clinics, Healthcare Professionals Technology: Electrochemical, Optical, Enzymatic, Continuous |
| Companies Covered | Abbott Laboratories, Medtronic, Dexcom, Sinocare, Zhejiang POCTech, Medtrum Technologies, Senseonics, MicroTech Medical, Jiangsu Yuyue Medical Equipment & Supply, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Continuous Glucose Monitoring Devices Market Trends and Innovations
Electrochemical sensor architectures are undergoing dimensional compression while wireless data transmission protocols migrate toward smartphone-native integration, eliminating dedicated receiver hardware from patient workflows.
Micro-needle array biosensors is miniaturizing sensor form factors to sub-5mm thickness profiles. Tier-one hospital endocrinology departments are piloting these platforms for pediatric type 1 diabetes management. The structural consequence is collapsing the distinction between professional medical devices and consumer wellness wearables, forcing manufacturers to dual-certify products across Class III and consumer electronics regulatory pathways.
NMPA's 2023 software-as-medical-device guidance revision is tightening algorithm validation requirements for glucose prediction features. Domestic manufacturers must submit retrospective clinical datasets exceeding 10,000 patient-hours for pattern recognition modules. Products incorporating real-time trend arrows rather than retrospective logging face the steepest compliance burden, with Beijing-based tertiary hospitals demanding pre-installation clinical evidence packages.
Direct-to-patient subscription models are displacing traditional pharmacy dispensing for sensor replenishment. E-commerce platforms and hospital-affiliated internet clinics are capturing reorder traffic previously routed through brick-and-mortar retail. Shanghai's medical device innovation clusters show the highest subscription penetration, with patients accepting 12-month commitments in exchange for priority sensor shipping and remote endocrinologist consultation access.
China Continuous Glucose Monitoring Devices Market Segmentation
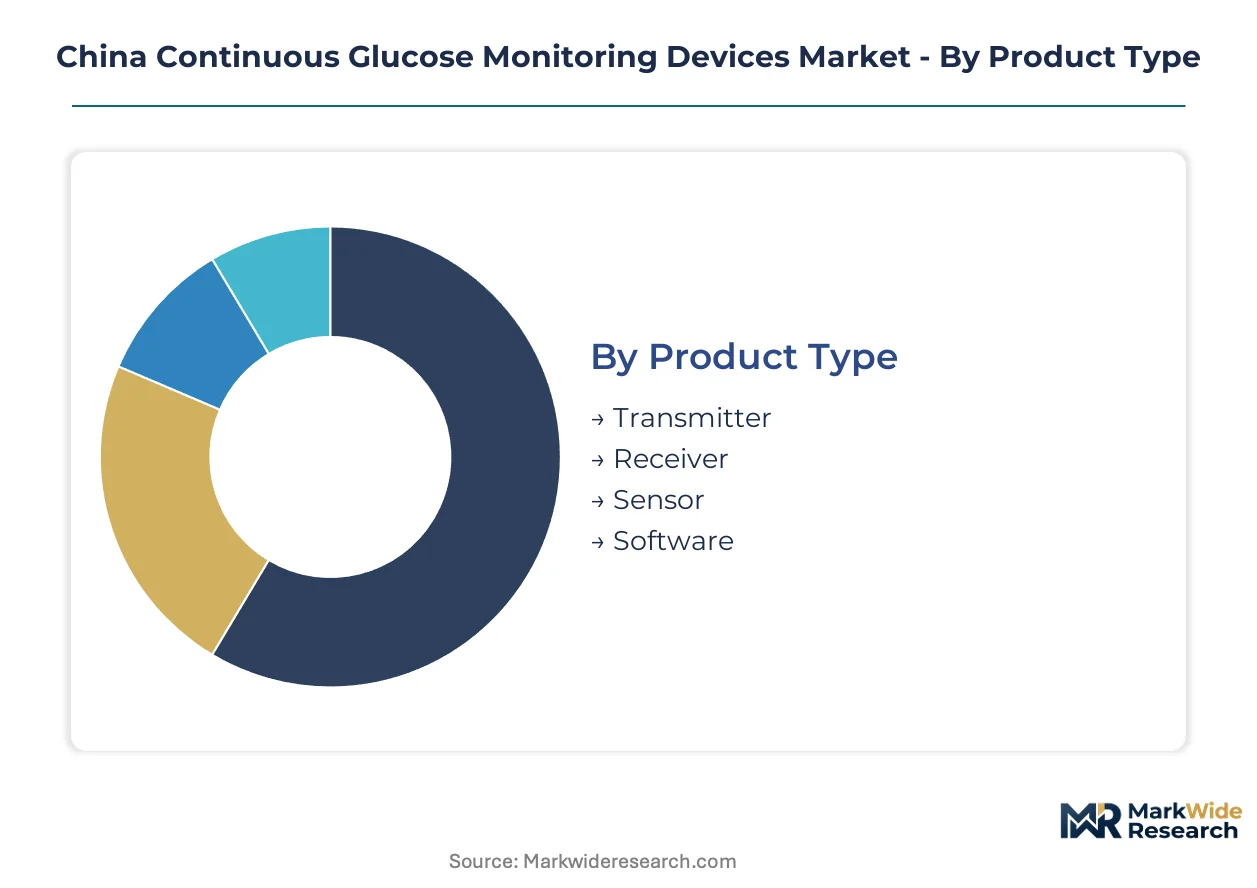
CGM segmentation in China reflects divergent margin economics across hardware replacement cycles versus software monetization. NMPA's Class III certification tiers create natural price stratification that manufacturers exploit through targeted channel strategies.
Product Type:
Sensor components command the highest gross margins due to mandatory 14-day replacement cycles and biocompatibility certification barriers that limit supplier competition.
- Sensor:Electrochemical glucose oxidase electrodes with palladium-ruthenium catalyst layers generate recurring revenue through disposable replacement economics. Demand concentrates in Shanghai's tertiary hospital procurement networks where NMPA-mandated ISO 10993 testing creates supplier lock-in effects.
- Transmitter:Wireless Bluetooth Low Energy modules with 8-14 day battery integration attach to sensor bases for data relay. Beijing's diabetes clinics drive volume for reusable transmitter platforms that pair with multiple sensor generations.
- Receiver:Dedicated handheld display units are losing share to smartphone-native applications. Provincial reimbursement catalogs in Jiangsu and Zhejiang still mandate receiver inclusion for elderly patient populations.
- Software:Algorithm-based glucose prediction modules face NMPA software-as-medical-device classification uncertainty. Development concentrates in Shenzhen's medical device innovation clusters where engineers optimize pattern recognition for Chinese dietary glycemic patterns.
The dominant share belongs to Sensor, while Software is closing the gap fastest.
Application:
Volume deployment varies sharply between regulated clinical environments and emerging lifestyle monitoring use cases with divergent evidence requirements.
- Diabetes Management:Insulin-dependent patient monitoring with real-time trend arrows and hypoglycemia alerts represents the core reimbursed indication. Homecare settings in Guangdong province show steepest expansion trajectory as provincial catalogs extend coverage.
- Blood Glucose Monitoring:Fingerstick replacement protocols in hospital inpatient wards drive factory-calibrated sensor adoption. Centralized tendering mechanisms in Beijing's hospital procurement departments compress pricing while accelerating volume.
- Research:Academic clinical studies at Fudan and Tsinghua university hospitals require raw data export capabilities. Sensor platforms with open API architectures capture this specialized demand pool.
- Clinical Trials:Pharmaceutical sponsors deploying CGM endpoints for diabetes drug development favor MARD-validated systems with FDA-recognized accuracy specifications.
Diabetes Management holds the installed base advantage, though Blood Glucose Monitoring is gaining share fastest in inpatient settings.
End User:
Channel economics diverge between centralized hospital procurement and direct-to-patient subscription models with contrasting working capital requirements.
- Hospitals:Tertiary endocrinology departments in Beijing and Shanghai anchor professional-grade sensor consumption through bulk tendering. NMPA Class III registration mandates drive preference for established domestic and multinational suppliers with proven biocompatibility dossiers.
- Homecare:Individual patients purchasing through e-commerce platforms or hospital-affiliated internet clinics represent the expansion frontier. Subscription-based replenishment models with 12-month commitments are displacing pharmacy dispensing in coastal provinces.
- Diabetes Clinics:Specialized outpatient facilities in provincial capitals provide patient training and sensor initialization services. These intermediaries influence brand selection through prescriber relationships.
- Healthcare Professionals:Individual endocrinologists and certified diabetes educators recommend specific CGM platforms based on remote monitoring dashboard capabilities.
Hospitals retain the volume leadership, while Homecare is climbing the fastest as reimbursement expands beyond institutional settings.
Technology:
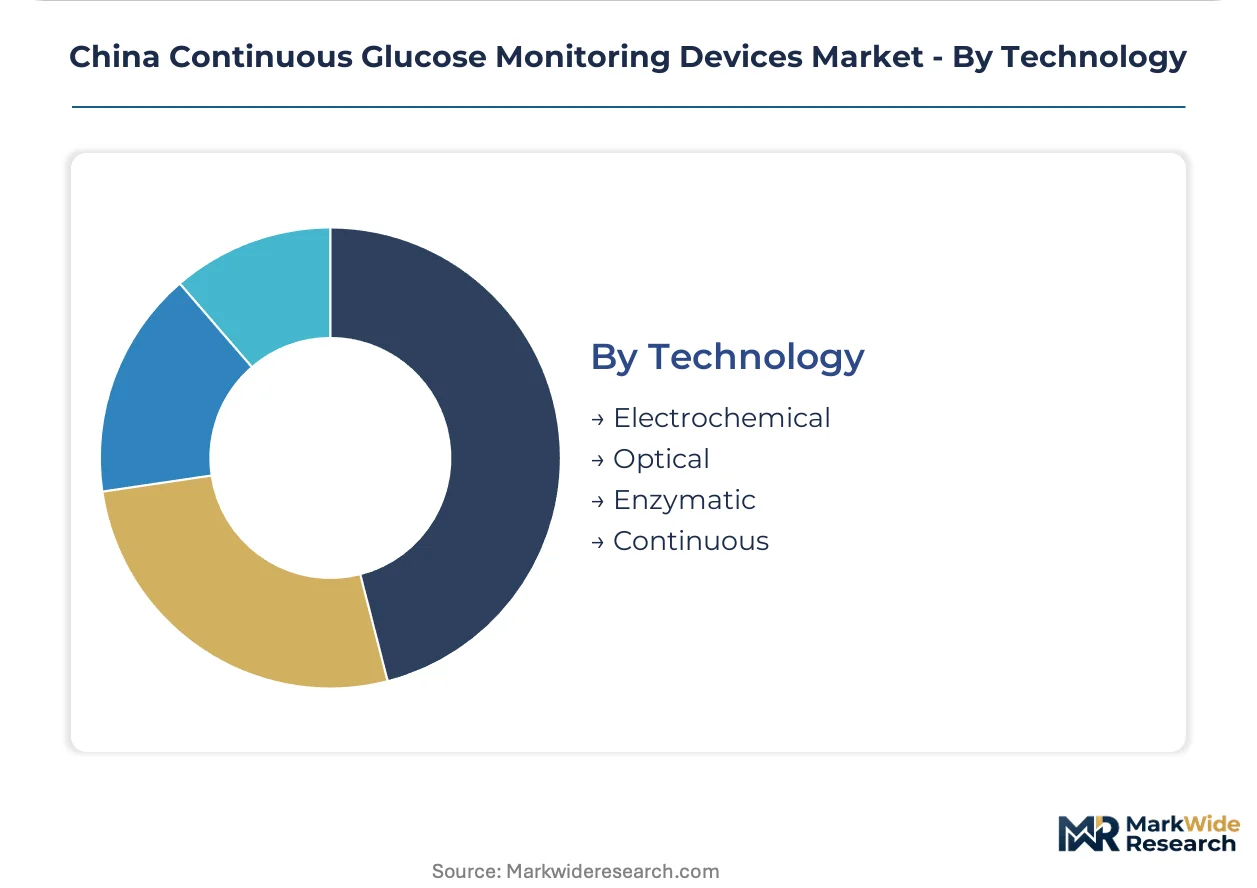
R&D allocation splits between mature electrochemical platforms with proven reimbursement pathways and optical alternatives threatening enzymatic replacement economics.
- Electrochemical:Amperometric glucose oxidase sensors with platinum group metal electrodes dominate commercial deployment. Manufacturing concentrates in Beijing-Shanghai corridors where supply chain vulnerability to South African palladium disruptions persists.
- Enzymatic:Extended 14-day stability formulations are replacing earlier 10-day platforms in volume production. Sinocare's backward integration into biosensor electrode production anchors cost competitiveness.
- Optical:Near-infrared spectroscopy and Raman scattering approaches under development at Tsinghua and Fudan labs promise non-invasive glucose detection. Technical barriers to interstitial fluid correlation remain unresolved.
- Continuous:Factory-calibrated algorithms eliminating fingerstick verification requirements represent the functional standard for new market entrants.
Electrochemical technology commands current deployment, though Optical alternatives are advancing fastest in university laboratory settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Chinese provinces. Patients in coastal municipalities absorb premium sensor costs through expanded reimbursement catalogs. Inland markets remain out-of-pocket dependent, compressing manufacturer margins and favoring domestic value-tier suppliers.
Beijing-Tianjin-Hebei
Tertiary hospital networks in Beijing anchor professional-grade CGM consumption through centralized tendering. NMPA's Class III streamlined review pathway accelerates product approvals for manufacturers targeting this cluster. Tianjin's medical device logistics hubs distribute factory-calibrated sensors to northern provincial capitals.
Yangtze River Delta
Shanghai's medical device innovation clusters show the highest subscription penetration for direct-to-patient models. Jiangsu and Zhejiang health security bureaus have added CGMs to chronic disease management catalogs. Suzhou and Hangzhou manufacturing bases concentrate electrochemical sensor electrode production.
Pearl River Delta
Guangdong province's homecare settings show the steepest expansion trajectory as provincial catalogs extend coverage. Shenzhen's medical device engineers optimize glucose prediction algorithms for Chinese dietary patterns. Dongguan electronics supply chains feed transmitter Bluetooth module assembly.
Sichuan-Chongqing
Western China penetration rates sit below one-fifth of coastal levels, presenting expansion targets for tier-two hospital networks. Chongqing's municipal health commission pilots centralized procurement for diabetes management devices. Chengdu's biomedical industrial parks attract domestic sensor manufacturers seeking lower operational costs.
China Continuous Glucose Monitoring Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in China's CGM sector. The market structures around a tiered configuration with multinational precision manufacturers, integrated domestic producers, and emerging specialist entrants. Three archetypes dominate: premium-tier multinationals with NMPA-established dossiers, value-tier domestic players with backward integration into biosensor production, and university spin-offs commercializing optical alternatives. Competitive moves concentrate on direct hospital contracting and manufacturing capacity expansion in dual carbon-certified facilities.
Among multinational suppliers, Abbott Laboratories and Dexcom exemplify premium-tier positioning through established NMPA Class III registrations. Sinocare anchors the value-tier domestic archetype with integrated electrode production capabilities. Zhejiang POCTech occupies a position among emerging specialists targeting provincial hospital procurement networks outside Beijing-Shanghai corridors.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic |
| Dexcom |
| Sinocare |
| Zhejiang POCTech |
| Medtrum Technologies |
| Senseonics |
| MicroTech Medical |
| Jiangsu Yuyue Medical Equipment & Supply |
| Others |
Pricing and Supply Chain Analysis
Fourteen-to-eighteen-month biocompatibility validation cycles for new adhesive formulations compress working capital efficiency and concentrate pricing power with incumbent suppliers holding established ISO 10993 dossiers. This lead-time band forces manufacturers to front-load certification investments, amplifying margin pressure on domestic challengers while reinforcing premium positioning for NMPA-established multinationals in Beijing and Shanghai procurement networks.
Pricing Analysis
Sensor replenishment subscriptions now anchor lifetime value capture, displacing upfront hardware margins as the dominant revenue architecture. Pricing stratifies across NMPA Class III certification tiers, with factory-calibrated platforms commanding premiums over fingerstick-dependent alternatives. Cost compression in the value tier intensifies because Sinocare's backward integration into biosensor electrode production erodes competitor cost structures. Homecare patients in Jiangsu and Zhejiang show lowest price sensitivity due to provincial reimbursement coverage, while out-of-pocket dependent inland markets absorb maximum burden.
Supply Chain Analysis
Shanghai port congestion and container availability fluctuations on the Asia-North America trade lane expose inbound logistics vulnerabilities for palladium and ruthenium catalyst shipments. Manufacturing concentrates in China, with South African and Russian supply corridors feeding platinum group metal dependencies. Electrochemical sensor production rests on palladium-ruthenium catalyst layers, glucose oxidase enzyme formulations, and medical-grade adhesive substrates. Single-source vulnerability to South African palladium disruptions threatens electrode cost stability. Distribution runs through hospital procurement departments and e-commerce platforms in coastal provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as provincial reimbursement expansion creates tier-two hospital network niches underserved by Beijing-Shanghai incumbents. Homecare subscription models and algorithm-based glucose prediction features open parallel demand pools with divergent certification requirements.
For Market Incumbents: Secure NMPA software-as-medical-device registrations for predictive hypoglycemia alert modules before regulatory guidance crystallizes. Deepen hospital contracting relationships in Beijing and Shanghai tertiary networks to lock out emerging domestic challengers. Optical non-invasive substitution threats from Tsinghua and Fudan labs demand accelerated R&D allocation to maintain enzymatic sensor relevance. For New Entrants and Emerging Players: Differentiate on MARD performance claims validated against Chinese dietary glycemic patterns for algorithm development. Target Henan and Hubei province tier-two hospital networks where CGM penetration sits below coastal levels. Pursue direct-to-patient subscription models with 12-month commitments to bypass incumbent pharmacy channel control. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational medical device parents seeking to monetize non-core diabetes portfolio assets. Long-term viability hinges on dual carbon manufacturing certification access and NMPA Class III registration speed. Watch for NMPA software-as-medical-device guidance finalization as inflection indicator for algorithm-based feature monetization potential.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class III Registration Acceleration | Streamlined review pathways compress approval timelines for domestic manufacturers targeting Beijing-Shanghai procurement networks. |
| Backward Integration into Biosensor Production | In-house electrode manufacturing anchors cost competitiveness against palladium price volatility from South African supply corridors. |
| Provincial Reimbursement Strategy | Jiangsu and Zhejiang health security bureau catalog inclusion directly determines patient out-of-pocket burdens and adoption velocity. |
| Software Companion Development | Smartphone-native glucose prediction modules face NMPA algorithm validation requirements exceeding 10,000 patient-hours. |
| Hospital System Partnership | Direct contracting with Beijing tertiary endocrinology departments secures bulk tendering volume and supplier lock-in effects. |
Research Methodology
The analysis maps sensor hardware, transmitter modules, algorithm software, and after-sales service tiers, each validated through hospital procurement managers, endocrinology clinicians, biomedical engineers, and GPO contracts managers. Primary interview findings triangulate against NMPA registration databases, provincial reimbursement catalogs, hospital procurement tender records, and GB/T 19634 standards documentation. Bottom-up patient population modeling and top-down medical device market sizing converge across the analysis window.
Consistency checks validate volume and value outputs against electrochemical sensor production capacity disclosures, palladium import trade data, and provincial health expenditure reports. Segmentation dimensions span product type, application indication, end-user channel, and technology platform. CAGRs derive from patient population growth, reimbursement expansion trajectories, and replacement cycle economics. Forecast inputs incorporate NMPA approval velocity assumptions and provincial catalog inclusion timelines.
Decision-makers should treat outputs as directional under stable NMPA regulatory frameworks and continued provincial reimbursement expansion; material deviation would warrant model refresh. Algorithm-as-device classification ambiguity, optical substitution technical breakthroughs, or palladium supply corridor disruptions could revise trajectory assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Egypt Diabetes Care Devices Market
Diabetes Care
Brazil Oral Anti-Diabetic Drug Market
Diabetes Care
Malaysia Insulin Infusion Pump Market
Diabetes Care
Canada Continuous Glucose Monitoring Market
Diabetes Care
South Africa Oral Antidiabetic Drug Market
Diabetes Care
Global Continuous Glucose Monitoring Systems Market
Diabetes Care
Point of Care Glucose Testing Market
Diabetes Care
OTC Glucose Monitors Market
Diabetes Care
Insulin Patch Pumps Market
Diabetes Care
Disposable Insulin-Delivery Device Market
Diabetes Care
Asia Pacific Diabetes Drug Market
Diabetes Care
South Korea Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Thailand Oral Antidiabetic Drug Market
Diabetes Care
North America Diabetes Care Devices Market
Diabetes Care
Asia Pacific Blood Glucose Test Strip Market
Diabetes Care
Indonesia Diabetes Care Devices Market