
 3D Medical and Surgical Imaging Market | 2026-2036
3D Medical and Surgical Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
3D Medical and Surgical Imaging Market Outlook
A shortage of radiologists trained in volumetric image interpretation is unwinding the deployment timelines for advanced surgical platforms across health systems. Siemens Healthineers leverages its installed base of MRI systems to cross-sell 3D visualization software, while GE Healthcare anchors its position through deep backward integration into detector manufacturing. Canon Medical Systems differentiates via high-resolution CT reconstruction algorithms that reduce radiation exposure during interventional procedures.
3D medical and surgical imaging encompasses volumetric acquisition systems that reconstruct cross-sectional anatomical datasets into navigable spatial models, typically achieving sub-millimeter resolution through multi-detector CT arrays or high-field MRI gradients. These systems serve primarily to enable preoperative planning, intraoperative guidance, and postoperative assessment across complex interventions. CT scanners occupy the largest revenue share among product types due to their ubiquity in emergency and oncology workflows, while machine learning within the technology dimension represents the fastest-expanding capability layer as vendors automate lesion detection and segmentation. Surgical navigation applications command premium pricing relative to diagnostics because they integrate real-time tracking hardware with preoperative 3D models.
FDA premarket clearance requirements for AI-enabled diagnostic devices shape product development roadmaps and prolong commercialization cycles for imaging software vendors. The EU Medical Device Regulation imposes stricter clinical evidence standards on 3D visualization platforms classified as Class IIa or higher, redirecting R&D investment toward predicate-device equivalence strategies. Stakeholders must monitor how CMS reimbursement decisions for AI-assisted surgical planning affect hospital capital allocation between imaging modalities.
Market Dynamics
AI-assisted surgical planning is compressing the gap between diagnostic imaging and operative intervention, forcing vendors to bundle real-time navigation with preoperative reconstruction software.
Growth Catalysts
- EU Medical Device Regulation Class IIa pathways:Streamlined equivalence routes for predicate 3D visualization platforms accelerate clearance timelines for software vendors targeting European surgical centers.
- Interventional oncology workflows:CT-guided ablation procedures for liver and lung lesions generate recurring demand for sub-millimeter spatial tracking integrated with volumetric datasets.
- Superconducting magnet supply concentration in Germany:Dense clustering of MRI gradient coil manufacturing near Erlangen and Munich reduces procurement lead times for high-field surgical navigation systems.
Market Restraints
- Helium supply volatility:Cryogen dependency for superconducting MRI systems exposes imaging departments to price shocks and allocation rationing from Qatar and Algeria.
- FDA premarket notification friction:De novo classification requirements for AI-enabled lesion detection algorithms extend commercialization cycles by 18-24 months for software-only vendors.
- Flat-panel detector duopoly:Concentration of amorphous silicon TFT substrate production in East Asia creates single-source vulnerability for C-arm manufacturers.
Strategic Opportunities
- US CMS reimbursement expansion:Category III CPT codes for AI-assisted surgical planning create billable pathways for hospital capital justification.
- Photon-counting CT convergence with surgical navigation:Direct conversion detector technology enables dual-energy tissue characterization intraoperatively.
- Outpatient ambulatory surgical centers:Underpenetrated site-of-care shift in the United States creates demand for compact, mobile 3D C-arms with reduced footprint.
Industry Challenges
- Volumetric interpretation skill scarcity:Fellowship-trained radiologists capable of navigating multiplanar reconstructions remain concentrated at academic medical centers, limiting community hospital deployment.
- Legacy PACS integration complexity:DICOM-RT and DICOM-SR metadata standards vary across vendor implementations, forcing costly middleware development for surgical navigation vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Medical and Surgical Imaging Market |
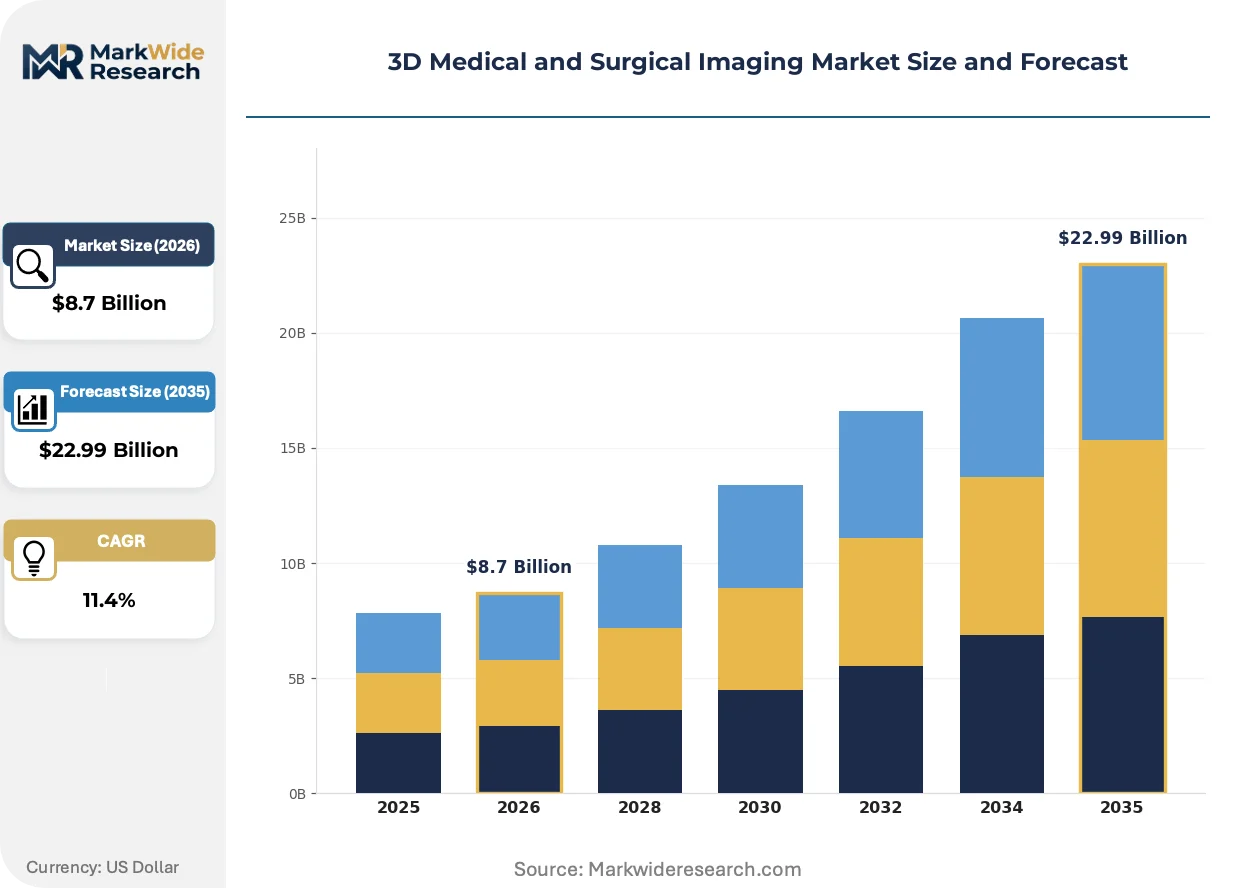
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Scanners, MRI Systems, Ultrasound Machines, Endoscopy Systems Technology: 3D Visualization, Image Processing, Augmented Reality, Machine Learning End User: Hospitals, Clinics, Research Laboratories, Surgical Centers Application: Diagnostics, Treatment Planning, Patient Monitoring, Surgical Navigation |
| Companies Covered | Canon Medical Systems, Brainlab AG, GE Healthcare, Fujifilm, Stryker Corp., Siemens Healthineers, Medtronic Inc., Olympus Corporation, Koninklijke Philips NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Medical and Surgical Imaging Market Strategic Shifts
Computational reconstruction algorithms are migrating from server-based architectures to edge-deployed inference engines, altering how surgical teams access real-time anatomical guidance.
Photon-counting detector technology is supplanting conventional energy-integrating CT sensors in interventional suites. Cardiac catheterization labs at Cleveland Clinic and Mayo Clinic are piloting these systems for transcatheter structural heart procedures. The shift is compressing radiation dose requirements while expanding soft-tissue contrast resolution for electrophysiology mapping.
EU AI Act risk classification for medical device software is redefining conformity assessment obligations for 3D visualization platforms. Class IIa devices with autonomous diagnostic features now require notified body review of training dataset governance. Siemens Healthineers and Brainlab AG are restructuring quality management systems to accommodate post-market performance monitoring mandates.
Hospital capital committees are unbundling hardware procurement from software maintenance contracts. Academic medical centers in the United States now negotiate separate SaaS agreements for AI segmentation tools rather than accepting bundled ten-year service plans. This pattern is most pronounced at integrated delivery networks in Texas and Florida, where CFOs demand usage-based pricing for cloud-hosted reconstruction pipelines.
3D Medical and Surgical Imaging Market Segmentation
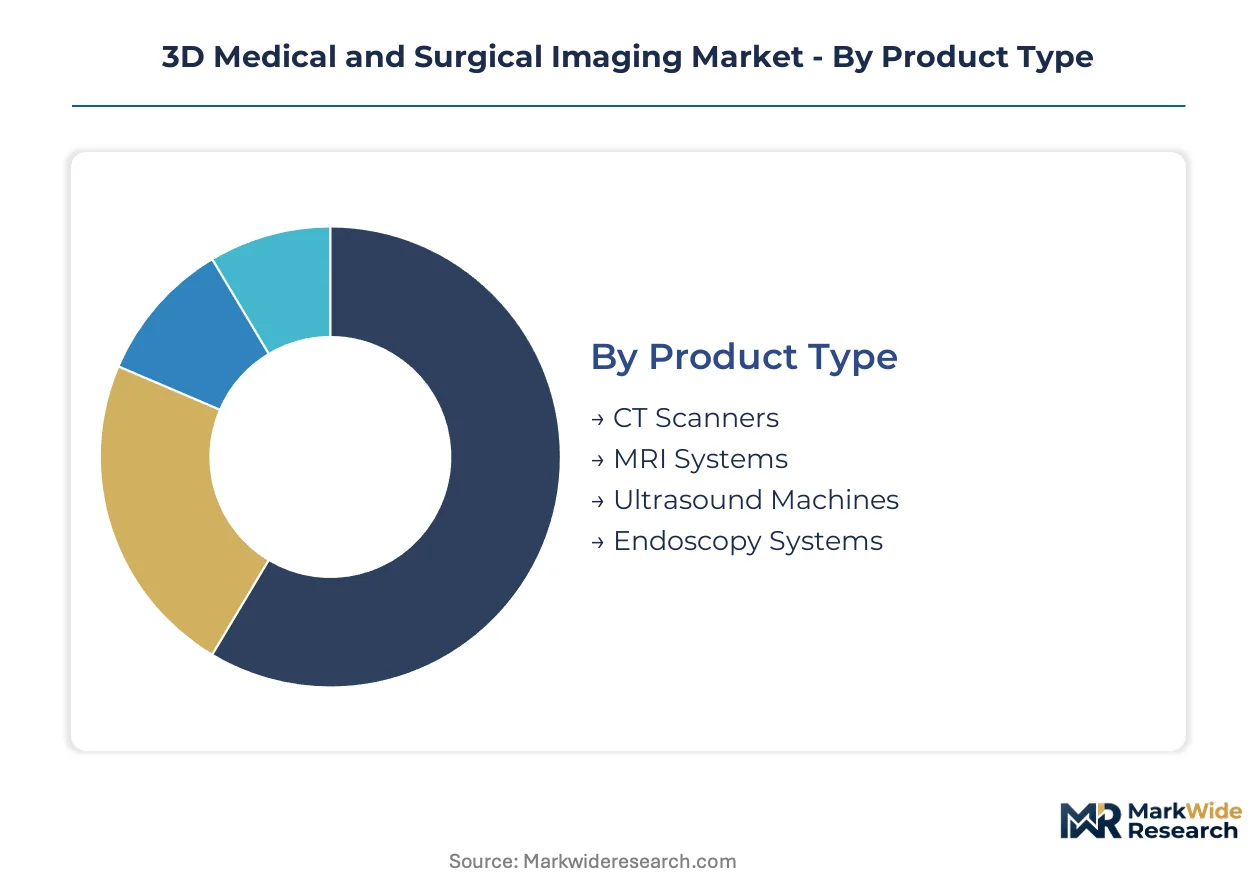
Segment boundaries in 3D medical imaging reflect divergent capital cycles, reimbursement pathways, and clinical workflow integration requirements. Understanding how product specifications, technology layers, and end-user economics intersect reveals where procurement budgets concentrate and where vendors must bundle capabilities to secure placement.
Product Type:
Domestic procurement dominates CT scanner and MRI system deployment in Germany and the United States, while ultrasound and endoscopy platforms show stronger export intensity into emerging health systems across Southeast Asia and Latin America.
- CT Scanners:Multi-detector arrays with 256+ slice configurations generate sub-millimeter isotropic resolution through helical acquisition protocols. Demand concentrates in United States emergency departments and German oncology networks, where throughput requirements and interventional oncology reimbursement codes justify premium capital expenditure.
- MRI Systems:Superconducting 1.5T and 3T platforms with high-performance gradient coils enable diffusion-weighted and functional neuroimaging. Procurement clusters around academic medical centers in Boston and Munich, constrained by helium supply rationing and siting requirements for fringe field management.
- Ultrasound Machines:Matrix array transducers with 3D/4D beamforming support obstetric and cardiac volumetric assessment.
- Endoscopy Systems:Video processors with 3D depth perception integrate with laparoscopic and bronchoscopic platforms for minimally invasive guidance.
CT scanners command the established base across hospital networks. The steepest expansion runs through MRI systems as intraoperative configurations penetrate neurosurgical suites.
Technology:
Cost tier stratification separates enterprise-grade reconstruction engines from point-of-care visualization tools, with machine learning capabilities commanding 40-60% software maintenance premiums over baseline 3D rendering licenses.
- 3D Visualization:Volume rendering and multiplanar reconstruction software transforms DICOM datasets into navigable anatomical models. Deployment concentrates in surgical planning workstations at Cleveland Clinic and Johns Hopkins, where FDA-cleared preoperative simulation reduces operative time.
- Machine Learning:Convolutional neural networks automate lesion segmentation, organ contouring, and anomaly flagging with training on curated institutional datasets. Demand accelerates in United States integrated delivery networks seeking Category III CPT code reimbursement for AI-assisted surgical planning.
- Image Processing:Noise reduction and motion correction algorithms enhance diagnostic confidence in suboptimal acquisition conditions.
- Augmented Reality:Head-mounted displays overlay preoperative 3D models onto live surgical fields for navigational guidance.
3D visualization commands the established base across installed PACS infrastructure. The steepest expansion runs through machine learning as regulatory pathways for autonomous diagnostic features mature under FDA and EU AI Act frameworks.
End User:
Customer type determines purchasing authority structure, with hospitals consolidating procurement through value analysis committees while surgical centers and clinics delegate to individual physician-owners or regional group purchasing organizations.
- Hospitals:Academic and community health systems with centralized capital budgets negotiate multi-modality enterprise agreements. Procurement concentrates in United States not-for-profit systems and German university hospitals, where ten-year total cost of ownership models dominate vendor selection.
- Surgical Centers:Ambulatory facilities with procedure-specific case mixes seek compact, mobile 3D C-arms and ultrasound platforms. Demand clusters in Texas and Florida outpatient settings, where site-of-care shift from inpatient reimbursement differentials creates capital availability.
- Clinics:Private practice imaging centers and specialty referral networks purchase leased or refurbished systems.
- Research Laboratories:Preclinical and translational imaging facilities acquire high-field preclinical MRI and micro-CT systems.
Hospitals command the established base through enterprise purchasing power. The steepest expansion runs through surgical centers as CMS reimbursement policy accelerates outpatient migration for arthroscopic and spine procedures.
Application:
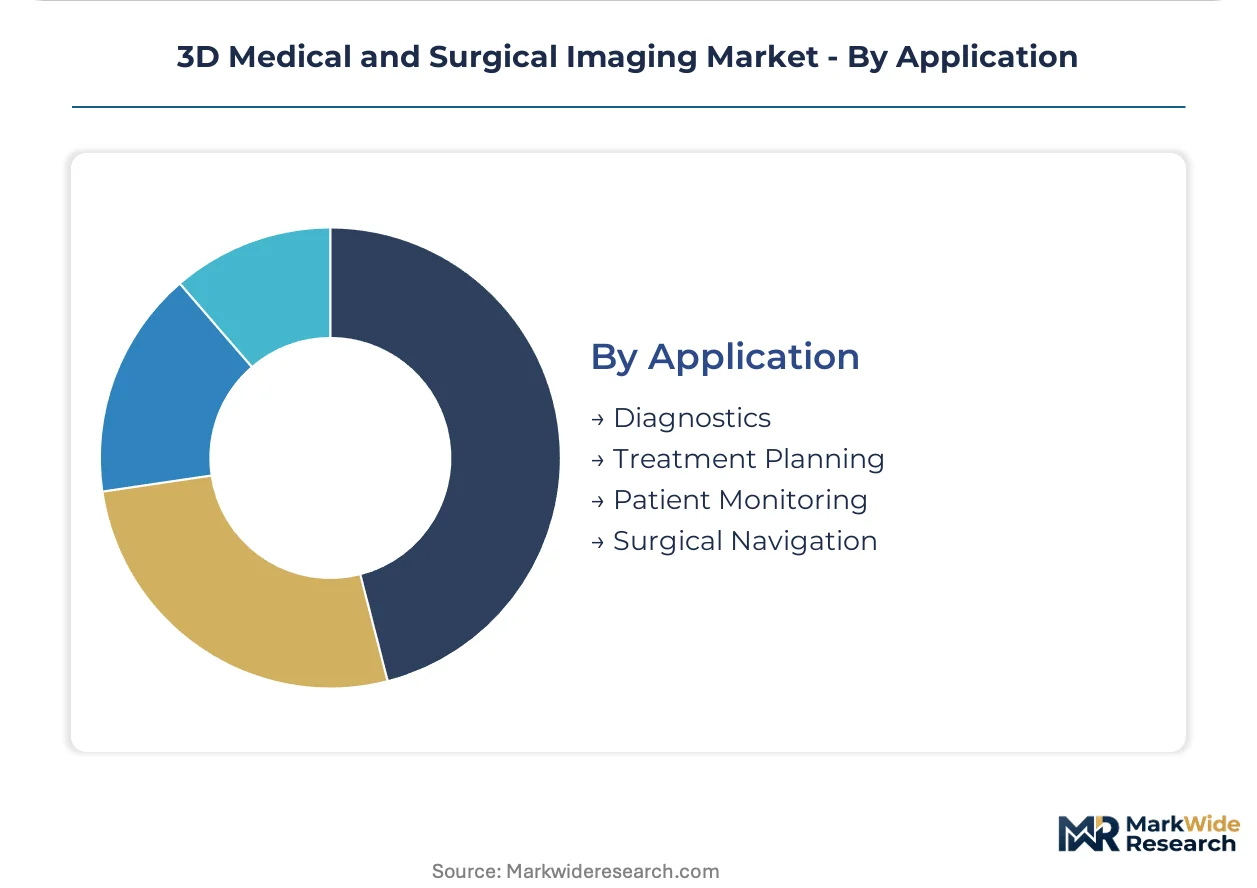
Application maturity curves diverge sharply, with diagnostics representing fully amortized installed bases while surgical navigation commands greenfield capital allocation and premium pricing multiples.
- Surgical Navigation:Integrated platforms combining preoperative 3D models with real-time optical or electromagnetic tracking enable instrument guidance during cranial, spinal, and orthopedic interventions. Deployment concentrates in German neurosurgical centers and United States spine institutes, where reimbursement for navigation-assisted procedures justifies capital outlay.
- Diagnostics:Standard-of-care imaging for oncology staging, trauma assessment, and cardiovascular evaluation represents the foundational revenue layer. Demand remains concentrated in emergency departments across United States health systems, constrained by flat Medicare reimbursement rates and utilization management protocols.
- Treatment Planning:Radiation oncology contouring and surgical simulation software supports multidisciplinary tumor boards.
- Patient Monitoring:Serial imaging for treatment response assessment and post-interventional surveillance.
Diagnostics command the established base across radiology department budgets. The steepest expansion runs through surgical navigation as vendors bundle real-time tracking hardware with preoperative reconstruction software to capture intraoperative spend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket clearance pathways for AI-assisted imaging anchor procurement momentum in the United States, while EU Medical Device Regulation frameworks reshape commercialization timelines across European surgical centers. National reimbursement policies and helium supply logistics create divergent deployment patterns across major health systems.
United States
Hospital networks in Texas and Florida accelerate outpatient migration for arthroscopic procedures, driving demand for compact mobile 3D C-arms. CMS Category III CPT codes for AI-assisted surgical planning create billable pathways that justify capital expenditure. Cleveland Clinic and Mayo Clinic anchor pilot programs for photon-counting CT systems in cardiac catheterization labs.
Germany
University hospitals in Munich and Erlangen concentrate procurement of high-field MRI systems for neurosurgical navigation. EU Medical Device Regulation Class IIa equivalence routes streamline software clearance for 3D visualization platforms. Siemens Healthineers and Brainlab AG maintain dense R&D clusters serving European surgical centers with precision imaging capabilities.
China
NMPA regulatory pathways for AI-enabled diagnostic devices accelerate domestic vendor commercialization cycles. Government hospital procurement programs prioritize localization of CT and MRI manufacturing capacity. Shanghai and Beijing anchor demonstration projects for intraoperative 3D navigation in tier-one medical centers.
Japan
PMDA review timelines for software-as-medical-device classifications extend market entry for foreign 3D visualization vendors. METI funding programs support photon-counting detector development for interventional oncology applications. Tokyo and Osaka metropolitan hospitals lead adoption of MRI-guided surgical navigation for cranial procedures.
United Kingdom
NHS England capital rationing constraints delay replacement cycles for legacy CT fleets in community hospitals. MHRA post-Brexit regulatory autonomy creates divergence from EU MDR conformity assessment timelines. London teaching hospitals concentrate deployment of AI-assisted surgical planning workstations for multidisciplinary tumor boards.
3D Medical and Surgical Imaging Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with consolidated imaging hardware manufacturers controlling detector supply chains and software-only vendors competing on algorithmic differentiation. Siemens Healthineers and GE Healthcare exemplify the integrated archetype through captive manufacturing of superconducting magnets and flat-panel detectors. Canon Medical Systems and Fujifilm occupy the mid-tier specialist position with focused CT reconstruction portfolios. Competitive moves concentrate on backward integration into critical components and strategic partnerships to bundle navigation hardware with preoperative planning software.
Among the integrated tier, Siemens Healthineers and GE Healthcare represent archetypal full-stack competitors with control over upstream magnet and detector production. Brainlab AG exemplifies the pure-play surgical navigation specialist, occupying a position defined by software-hardware integration without captive imaging system manufacturing. These three anchors illustrate the structural divide between capital-intensive hardware platforms and agile surgical planning software vendors competing for intraoperative spend.
| Leading Market Players |
|---|
| Canon Medical Systems |
| Brainlab AG |
| GE Healthcare |
| Fujifilm |
| Stryker Corp. |
| Siemens Healthineers |
| Medtronic Inc. |
| Olympus Corporation |
| Koninklijke Philips NV |
| Others |
Value Chain & Pricing Dynamics
Long-term helium supply contracts with Qatar and Algeria lock in cryogen access for superconducting MRI manufacturers while fixing a substantial portion of magnet production costs, creating price visibility that shields imaging vendors from spot-market volatility but limits flexibility when alternative cooling technologies mature.
Pricing Analysis
United States hospital procurement committees negotiate SaaS-based AI segmentation licenses at 40-60% premiums over baseline 3D rendering software, while German university hospitals favor bundled ten-year hardware-service agreements with total-cost-of-ownership guarantees. Price differentiation hinges on FDA clearance tier for autonomous diagnostic features and helium supply security for high-field MRI platforms. Cost compression in entry-level CT scanners intensifies as Chinese domestic vendors expand NMPA-cleared product lines for government hospital procurement programs. Community hospitals and ambulatory surgical centers exhibit highest price sensitivity, constrained by flat Medicare reimbursement and capital rationing, while academic medical centers prioritize clinical workflow integration over unit economics.
Supply Chain Analysis
Germany and Japan anchor superconducting magnet and gradient coil manufacturing, with Erlangen and Munich hosting dense clusters of MRI component production that feed assembly lines at Siemens Healthineers. China dominates amorphous silicon TFT substrate production for flat-panel detectors, creating single-source vulnerability for C-arm manufacturers sourcing X-ray sensors. Taiwan and South Korea supply specialized semiconductor components for detector readout electronics. Raw material dependencies center on niobium-titanium superconducting wire, high-purity helium for cryogenic cooling, and rare-earth elements for gradient coil fabrication. Supply chain risk concentrates in helium allocation rationing from Qatar and Algeria, with logistics chokepoints at liquefaction facilities and cryogenic transport vessel availability. Distribution runs through regional imaging equipment distributors with factory-trained service engineering capabilities, particularly for intraoperative navigation system installation and calibration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software maintenance and AI-assisted surgical planning subscriptions expand faster than hardware replacement cycles, transforming capital equipment vendors into recurring-revenue platforms where attach rates for cloud-hosted reconstruction pipelines determine lifetime customer value.
For Market Incumbents: Fortify backward integration into superconducting magnet manufacturing and flat-panel detector substrate production to defend against Chinese domestic vendor cost advantages in CT scanner segments. Prioritize captive helium supply agreements with Qatar and Algeria to secure production continuity for high-field MRI platforms. Invest in FDA 510(k) clearance pathways for autonomous lesion detection algorithms to maintain pricing premiums against software-only entrants targeting Category III CPT code reimbursement. For New Entrants and Emerging Players: Cloud-native AI segmentation tools for community hospitals represent the most penetrable service-layer gap, where legacy PACS integration complexity has slowed incumbent software deployment. Target Texas and Florida ambulatory surgical centers with usage-based pricing for mobile 3D C-arm reconstruction services, capitalizing on site-of-care shift reimbursement differentials. Pursue strategic partnerships with GPO contracts managers to bypass value analysis committee procurement friction at integrated delivery networks. For Investors and Strategic Acquirers: Surgical navigation software specialists with FDA-cleared optical tracking integration and established hospital system pilot programs offer the strongest acquisition target archetype for platform consolidation plays. Long-term viability hinges on convergence between photon-counting CT hardware and real-time intraoperative guidance software, with reimbursement expansion for AI-assisted procedures as the critical inflection signal to monitor across CMS policy cycles.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class IIa equivalence routes accelerate software clearance for 3D visualization platforms targeting German surgical centers. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic pilot programs validate photon-counting CT integration with cardiac catheterization workflows. |
| Software Companion Development | AI segmentation tools with DICOM-RT metadata compatibility reduce middleware costs for surgical navigation vendors. |
| Reimbursement Strategy | CMS Category III CPT codes for AI-assisted surgical planning create billable pathways at United States integrated delivery networks. |
| Backward Integration | In-house production of superconducting magnets and gradient coils secures supply continuity against helium rationing constraints. |
Study Parameters
Desk research of FDA 510(k) clearance databases, EU MDR notified body documentation, and hospital procurement contract filings preceded structured interviews with biomedical engineers, GPO contracts managers, and radiology department chairs. Primary fieldwork captured capital budget allocation priorities and vendor selection criteria across academic medical centers and community hospital networks. Secondary validation drew from CMS Medicare reimbursement data, NMPA registration filings, and SEC 10-K disclosures from listed imaging equipment manufacturers. Bottom-up unit shipment estimates triangulated against top-down healthcare capital expenditure forecasts across the analysis window.
Variance decomposition separates volume growth from pricing mix effects across product type, technology layer, and end-user segments. The analytical framework models CT scanner, MRI system, and surgical navigation platform adoption separately, with machine learning capability penetration as a cross-cutting dimension. CAGRs derive from logistic diffusion curves fitted to installed base replacement cycles and greenfield deployment patterns. Forecast inputs incorporate helium supply rationing scenarios, FDA premarket notification timelines for AI-enabled devices, and EU AI Act conformity assessment requirements for autonomous diagnostic features.
Underlying assumptions cover stable CMS reimbursement policy for AI-assisted surgical planning, with deviation risk concentrated in FDA de novo classification timelines for novel algorithm architectures and helium allocation disruptions from Qatar and Algeria. Forecasts reflect these assumptions with explicit sensitivity ranges around regulatory clearance durations and cryogen supply continuity. Recalibration cycles align with material shifts in NMPA localization mandates, EU MDR guidance document revisions, and photon-counting detector commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Italy Computed Tomography Market
Medical Imaging
Global Medical Imaging Phantoms Market
Medical Imaging
South Korea Digital X-Ray Market
Medical Imaging
Mammography Workstation Market
Medical Imaging
Global Veterinary CT Scanner Market
Medical Imaging
Global Vendor-Neutral Archive (VNA) and PACS Market
Medical Imaging
Orthopedic Radiology Equipment Market
Medical Imaging
Medical Hyperspectral Imaging Market
Medical Imaging
Italy Diagnostic Imaging Equipment Market
Medical Imaging
Non-Invasive Coronary Imaging Market
Medical Imaging
Japan Mammography Market
Medical Imaging
Digital Radiology Market
Medical Imaging
Europe Fluoroscopy Market
Medical Imaging
Global Ultrasound Imaging Devices Market
Medical Imaging
China Mammography Market
Medical Imaging
Italy Mammography Market