
 Global Computed Tomography (CT) Market | 2026-2036
Global Computed Tomography (CT) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Computed Tomography (CT) Market Foresight
Hospital procurement concentration is pivoting toward fragmented outpatient networks and mobile imaging providers across emerging economies. GE Healthcare leverages its installed base in North America to sustain service revenue streams, while Siemens Healthineers anchors European demand through photon counting CT development. Canon Medical Systems competes in Asia-Pacific through high-resolution CT specialization for cardiovascular diagnostics.
Computed tomography is a diagnostic imaging modality that uses rotating X-ray sources and detector arrays to reconstruct cross-sectional anatomical images with spatial resolution typically below one millimeter; its primary purpose is non-invasive visualization of soft tissue, bone, and vascular structures for clinical diagnosis and treatment planning. Multi-slice CT dominates installed base value owing to throughput advantages in emergency and cardiac settings, while photon counting CT captures fastest-growing technology interest due to dose reduction and spectral differentiation capabilities. Fixed CT scanners retain the largest revenue pool in hospitals, yet mobile CT scanners expand fastest as rural access programs and disaster response protocols multiply deployment sites.
FDA 510(k) and EU MDR frameworks govern CT device safety and clinical validation requirements, with Japan's PMDA adding layer-specific approval timelines that manufacturers must navigate for Asian market access. China's NMPA accelerates domestic innovation review tracks while enforcing GB standards for radiation exposure limits. Stakeholders must monitor photon counting CT reimbursement decisions and decentralized imaging regulatory clarity as these determine capital deployment priorities.
Market Dynamics
Photon counting detector technology is compressing dose-exposure thresholds while spectral imaging capabilities unlock tissue differentiation previously requiring multiple scans, fundamentally altering capital allocation priorities across hospital networks and outpatient chains.
Growth Catalysts
- Cardiovascular imaging protocols:Emergency departments in the United States and Germany now mandate coronary CT angiography for intermediate-risk chest pain triage, expanding scanner utilization rates.
- EU MDR pathway harmonization:Streamlined conformity assessment procedures for Class IIb medical devices accelerate photon counting CT commercialization across European markets.
- China's tier-one hospital expansion:Municipal health commissions in Shanghai, Beijing, and Guangzhou prioritize multi-slice CT procurement for stroke center accreditation.
Market Restraints
- Helium supply concentration:Cryogenic cooling systems for superconducting CT magnets depend on Qatar and Algeria for liquefied helium, exposing manufacturers to export quota volatility.
- PMDA layer-specific reviews:Japan's Pharmaceuticals and Medical Devices Agency imposes additional clinical trial requirements for iterative reconstruction algorithms, extending registration timelines.
- Point-of-care ultrasound substitution:Bedside echocardiography and lung ultrasound displace low-acuity CT scans in intensive care settings across France and Italy.
Strategic Opportunities
- India's Ayushman Bharat expansion:Government-funded health insurance creates reimbursement pathways for CT diagnostics in tier-two and tier-three cities previously served by radiology outsourcing.
- Mobile stroke unit integration:Ambulance-mounted CT scanners combined with telemedicine links enable thrombolysis initiation during patient transport in rural Australia.
- AI-enabled workflow prioritization:Automated triage algorithms for intracranial hemorrhage detection attract radiology group purchasing decisions in the United Kingdom.
Industry Challenges
- Medical physics specialist scarcity:Radiation safety officer certification requirements outpace university training program output in Brazil and Mexico.
- Legacy PACS interoperability:DICOM-RT and proprietary vendor formats obstruct seamless integration of photon counting CT datasets into existing hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Computed Tomography (CT) Market |
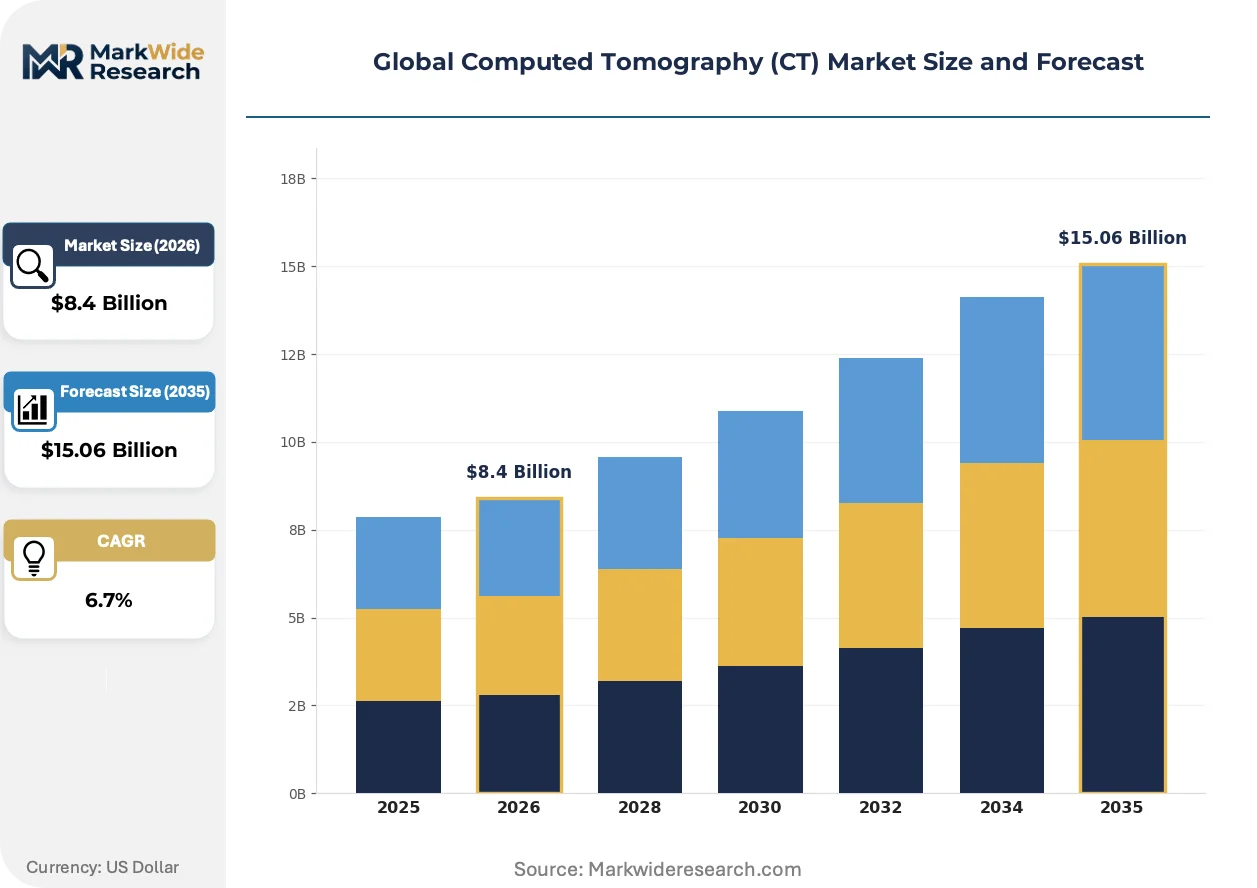
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed CT Scanners, Mobile CT Scanners, Portable CT Systems, High-Resolution CT, Cone Beam CT Technology: Single-Slice CT, Multi-Slice CT, Dual-Energy CT, Photon Counting CT, Spectral CT Application: Neurological Imaging, Cardiovascular Diagnostics, Oncology Imaging, Pulmonary Assessment, Musculoskeletal Examination End User: Hospitals, Diagnostic Imaging Centers, Ambulatory Surgical Centers, Research Institutes, Outpatient Clinics |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips, Canon Medical Systems Corporation, Neusoft Medical Systems, United Imaging Healthcare, FUJIFILM Holdings, Shimadzu Corporation, Carestream Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Computed Tomography (CT) Market Shifts & Advancements
Artificial intelligence inference at the scanner edge is compressing reconstruction times from minutes to seconds, while spectral data acquisition protocols expand contrast-free diagnostic applications across vascular and oncologic imaging.
Photon counting CT detectors using cadmium telluride and silicon substrates are rewriting the trade-off between spatial resolution and radiation dose. Academic medical centers in Switzerland and the Netherlands adopt these systems for pediatric and repeat-scan populations. The technology is rewriting procurement criteria as value-analysis committees prioritize lifetime dose accounting over initial capital expenditure.
FDA 510(k) premarket notification requirements now incorporate cybersecurity documentation for networked CT platforms under the Refuse to Accept policy. Manufacturers must submit software bill of materials and vulnerability management plans alongside traditional safety data. Radiology device divisions at Siemens Healthineers and GE Healthcare have restructured regulatory affairs teams to address these submissions, with first-mover advantage accruing to firms with established quality management system maturity.
Subscription-based service models for CT hardware and software are displacing traditional capital purchase arrangements in North American integrated delivery networks. Health systems in Texas and Florida now prioritize per-scan pricing with guaranteed uptime clauses over equipment ownership. This shift concentrates vendor risk in asset performance rather than manufacturing margin, favoring service infrastructure density over production scale.
Global Computed Tomography (CT) Market Segmentation
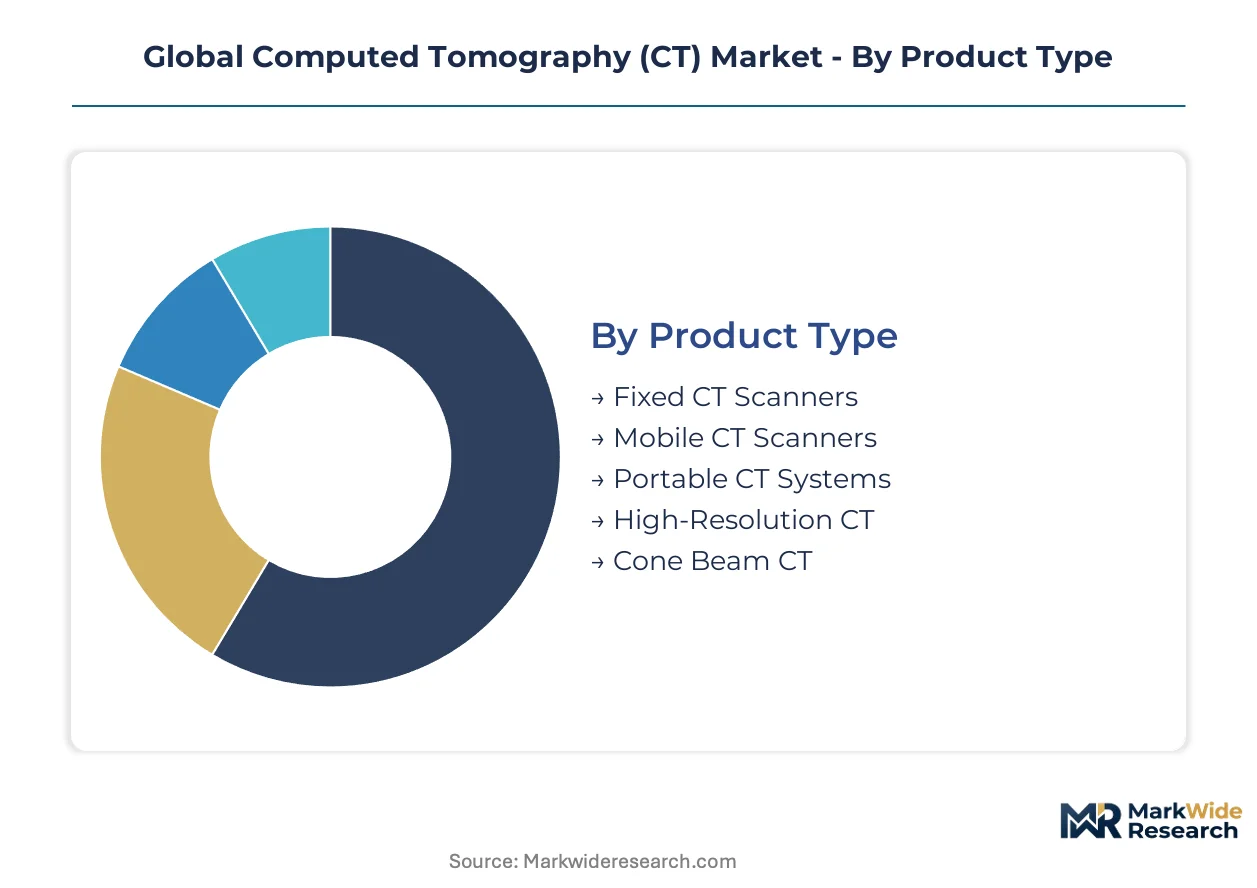
Computed tomography market segmentation reveals divergent capital deployment logic across healthcare infrastructure tiers. Procurement committees weight throughput capacity against mobility requirements, while reimbursement pathways determine technology tier selection.
Product Type:
Hospital capital committees prioritize installation footprint against patient volume elasticity when selecting scanner mobility class.
- Fixed CT Scanners:Permanent gantry installations with 64-slice to 320-slice detector arrays dominate stroke center and trauma bay accreditation requirements. United States hospital networks concentrate procurement in tier-one cities where emergency department throughput exceeds 50,000 annual visits.
- Mobile CT Scanners:Trailer-mounted or vehicle-integrated systems with self-contained power and climate control serve rural access programs and disaster response protocols. India's tier-two city expansion and Australia's remote stroke networks drive fastest deployment acceleration.
- Portable CT Systems:Compact head-dedicated units deploy directly into intensive care units for ventilated patient imaging.
- High-Resolution CT:Sub-millimeter slice thickness configurations target interstitial lung disease and temporal bone assessment.
- Cone Beam CT:Flat-panel detector geometry optimized for dental, maxillofacial, and extremity orthopedic applications.
Volume sits with Fixed CT Scanners; growth tilts toward Mobile CT Scanners.
Technology:
Detector architecture selection determines dose efficiency thresholds and spectral differentiation capabilities that reshape clinical protocol economics.
- Multi-Slice CT:Parallel detector rows enabling sub-second whole-body coverage constitute the installed base majority. German emergency departments and Chinese stroke centers mandate 128-slice minimum for coronary angiography protocols.
- Photon Counting CT:Direct energy-resolving detectors using cadmium telluride eliminate electronic noise and enable material decomposition. Swiss and Dutch academic centers pioneer adoption for pediatric and repeat-examination populations where cumulative dose accountability drives procurement.
- Single-Slice CT:Helical acquisition with single detector row serves veterinary and developing market budget constraints.
- Dual-Energy CT:Rapid kV switching or dual-source configuration generates material-specific images for gout and kidney stone characterization.
- Spectral CT:Layered detector or photon-counting approaches separate energy thresholds for iodine mapping and virtual non-contrast imaging.
Revenue concentrates in Multi-Slice CT; Photon Counting CT climbs the fastest.
Application:
Clinical indication determines scanner specification requirements from temporal resolution to field-of-view geometry.
- Cardiovascular Diagnostics:Coronary CT angiography demands sub-millisecond temporal resolution and robust arrhythmia rejection algorithms. United States intermediate-risk chest pain triage protocols and German preventive cardiology programs expand scanner utilization.
- Oncology Imaging:Whole-body staging and treatment response assessment require spectral capabilities and low-dose surveillance protocols. China's tier-one cancer centers and United Kingdom radiotherapy planning departments concentrate demand.
- Neurological Imaging:Perfusion and angiographic protocols for stroke and trauma command priority in emergency department configurations.
- Pulmonary Assessment:High-resolution parenchymal imaging and quantitative emphysema analysis drive dedicated thoracic protocols.
- Musculoskeletal Examination:Extremity and spine applications favor weight-bearing and wide-bore gantry designs.
Procedure volume aggregates in Cardiovascular Diagnostics; Oncology Imaging gains share fastest.
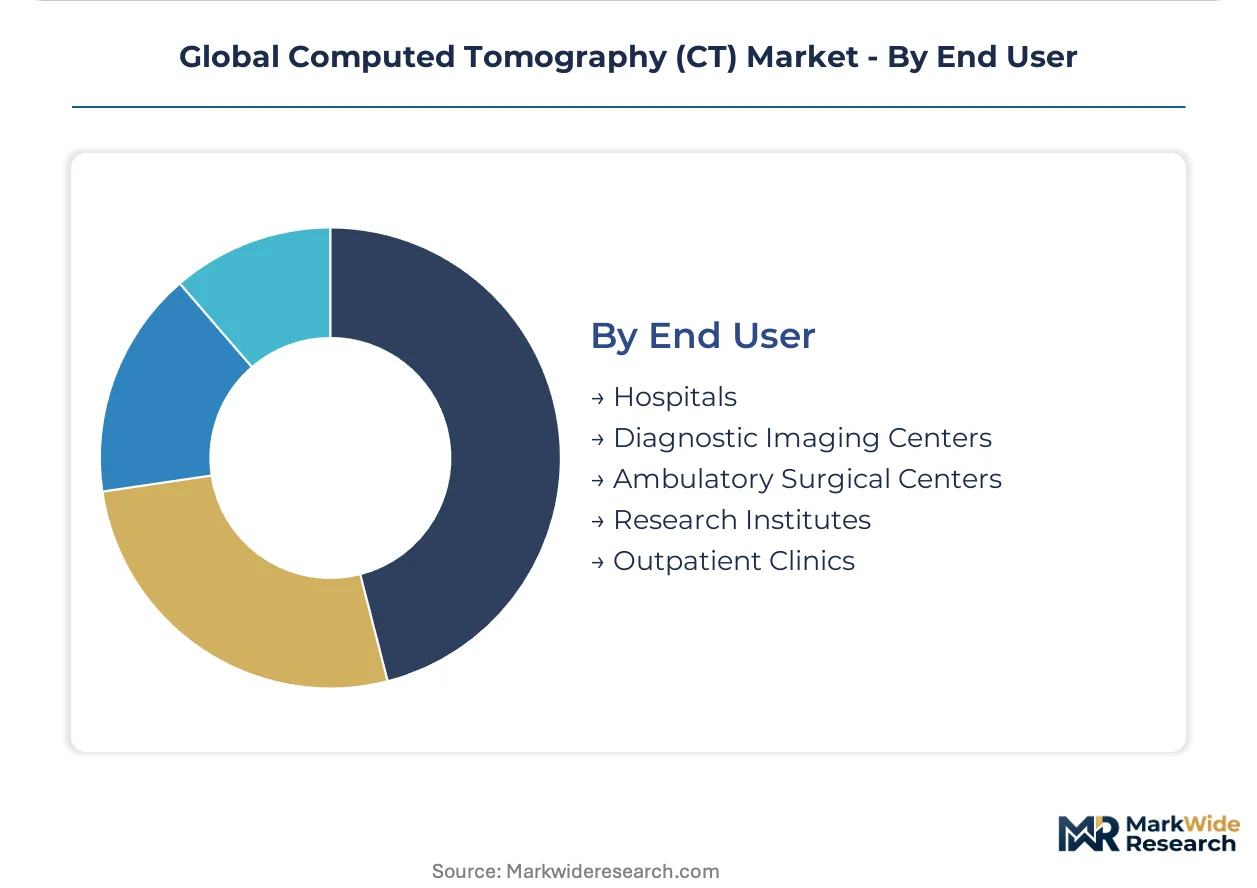
End User:
Capital allocation authority and reimbursement capture rates determine site-of-service migration patterns.
- Hospitals:Integrated emergency, inpatient, and surgical services command highest scanner duty cycles and technology tier access. Brazil's municipal hospital networks and Saudi Arabia's ministry-funded facilities anchor procurement volume.
- Diagnostic Imaging Centers:Freestanding outpatient facilities capture elective procedure migration from hospital cost structures. India's Ayushman Bharat reimbursement expansion and Brazil's decentralized care models accelerate greenfield development.
- Ambulatory Surgical Centers:Pre-operative planning and post-operative complication assessment create point-of-service imaging demand.
- Research Institutes:Spectral and photon-counting beta platforms support algorithm development and clinical trial imaging cores.
- Outpatient Clinics:Primary care-integrated imaging serves chronic disease surveillance in capitated payment environments.
Installed base value rests with Hospitals; expansion tilts toward Diagnostic Imaging Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tier-one cities concentrate CT procurement volume as municipal health commissions prioritize stroke center accreditation. United Imaging Healthcare and Neusoft Medical Systems anchor domestic supply chains in Shanghai and Beijing. Hospital procurement concentration is pivoting toward fragmented outpatient networks across emerging economies.
United States
Emergency departments mandate coronary CT angiography for intermediate-risk chest pain triage, expanding scanner utilization rates. FDA 510(k) premarket notification requirements now incorporate cybersecurity documentation for networked CT platforms. GE Healthcare leverages its installed base to sustain service revenue streams across Texas and Florida health systems.
Germany
German emergency departments mandate 128-slice minimum CT configurations for coronary angiography protocols. EU MDR streamlined conformity assessment procedures accelerate photon counting CT commercialization across European markets. Siemens Healthineers anchors European demand through photon counting CT development from its Erlangen operations.
China
Municipal health commissions in Shanghai, Beijing, and Guangzhou prioritize multi-slice CT procurement for stroke center accreditation. NMPA accelerates domestic innovation review tracks while enforcing GB standards for radiation exposure limits. United Imaging Healthcare and Neusoft Medical Systems dominate supply in tier-one cities where demand concentrates.
India
Government-funded Ayushman Bharat health insurance creates reimbursement pathways for CT diagnostics in tier-two and tier-three cities. CDSCO regulates medical device safety and clinical validation requirements for imported and domestic systems. Hospital procurement is pivoting toward outpatient diagnostic centers as decentralized care models expand.
Switzerland
Academic medical centers in Switzerland adopt photon counting CT systems for pediatric and repeat-scan populations. Swissmedic oversees medical device registration timelines alongside EU MDR alignment for market access. Swiss and Dutch academic centers pioneer adoption where cumulative dose accountability drives procurement decisions.
Global Computed Tomography (CT) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue spectral imaging and AI-enabled workflow specialization. The vendor base organizes around three strategic archetypes: diversified healthcare conglomerates with installed base leverage, regional specialists with high-resolution cardiovascular focus, and domestic champions capturing government procurement in emerging markets. Competitive moves concentrate on service infrastructure density for subscription-based pricing models and regulatory first-mover advantage in photon counting CT pathways.
Among diversified healthcare conglomerates, GE Healthcare and Siemens Healthineers exemplify the installed-base-leverage archetype through North American and European market presence. Canon Medical Systems occupies a position within the high-resolution cardiovascular specialization tier. United Imaging Healthcare represents the domestic champion archetype in China's tier-one hospital expansion. Neusoft Medical Systems sits within the same emerging-market champion category, anchoring supply chain proximity for municipal health commission procurement.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips |
| Canon Medical Systems Corporation |
| Neusoft Medical Systems |
| United Imaging Healthcare |
| FUJIFILM Holdings |
| Shimadzu Corporation |
| Carestream Health |
| Others |
Supply & Pricing Matrix
Photon counting detector manufacturing transitions from energy-integrating to direct-conversion architectures, simultaneously compressing per-unit production costs and concentrating supply among cadmium telluride substrate specialists in Japan and Germany. This technology shift rewards vendors with captive semiconductor foundry relationships while penalizing pure-play assemblers dependent on merchant detector supply.
Pricing Analysis
Volume concentrates in multi-slice CT systems where three-tier pricing structure across premium, standard, and economy levels separates 320-slice stroke-center configurations from 64-slice outpatient units and refurbished legacy platforms. Price differentiation hinges on slice count certification and AI reconstruction software bundling, with premium tiers commanding service-contract premiums. Pricing pressure stems from subscription-based per-scan models displacing capital purchases in North American health systems. Diagnostic imaging centers exhibit highest price sensitivity due to thin reimbursement margins, while academic medical centers prioritize dose-accounting metrics over acquisition cost.
Supply Chain Analysis
FDA 510(k) and EU MDR qualification requirements gate entry for photon counting CT detector substrates, favoring established semiconductor houses with quality management system maturity over merchant suppliers. Manufacturing concentrates in Japan, Germany, and the United States for precision gantry fabrication and detector array assembly. Raw material dependencies include high-purity cadmium telluride crystals, helium for cryogenic magnet cooling, and rare-earth scintillator ceramics. Single-source vulnerability runs through Qatar and Algeria for liquefied helium supply. Distribution runs through direct hospital sales forces in developed markets and government procurement channels in China and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CT market is becoming a vertical-integration race where detector substrate production and AI reconstruction algorithm development represent the decisive upstream and downstream levers. Players without captive semiconductor supply or regulatory-first-mover positioning face margin compression.
For Market Incumbents: To counter photon counting CT first-mover advantage by Siemens Healthineers and Canon Medical Systems, GE Healthcare and Philips must accelerate cadmium telluride detector backward integration through foundry partnerships or acquisition of substrate specialists. Service infrastructure density in North American integrated delivery networks remains the priority defensive lever, as subscription pricing models transfer asset-performance risk to vendors. For New Entrants and Emerging Players: Independent service organizations and AI workflow developers represent the most penetrable channel partner type for market entry without capital equipment manufacturing scale. White-space targets include tier-two and tier-three Indian cities under Ayushman Bharat reimbursement expansion, and mobile stroke unit retrofit opportunities in rural Australia. Go-to-market positioning should emphasize per-scan pricing with guaranteed uptime clauses to align with health system capital-light preferences. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified healthcare conglomerates seeking photon counting CT capabilities or AI-enabled workflow assets. Long-term viability favors vendors with installed base leverage in North America and regulatory first-mover status in photon counting pathways. Watch FDA reimbursement decisions for spectral imaging protocols as the inflection signal determining capital deployment priorities across hospital networks.| Strategic Initiative | Industry Significance |
|---|---|
| Photon Counting Detector Backward Integration | Captive cadmium telluride supply secures margin control against merchant substrate volatility. |
| EU MDR Conformity Assessment Acceleration | First-mover photon counting CT clearance captures European hospital replacement cycles. |
| Hospital System Partnership Expansion | Direct IDN relationships in Texas and Florida anchor subscription pricing adoption. |
| AI Reconstruction Software Development | FDA-cleared intracranial hemorrhage algorithms differentiate procurement decisions in the United Kingdom. |
| Mobile CT Service Infrastructure Buildout | Trailer-mounted deployment capability captures India's tier-two city reimbursement expansion. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and radiology group practice administrators. FDA 510(k) premarket notification databases, EU MDR conformity assessment records, and China NMPA registration filings provided device-level commercialization timelines. Bottom-up installed base modeling and top-down healthcare expenditure allocation triangulated market sizing across the projection horizon.
Data-stream reconciliation across hospital procurement databases, CMS Medicare claims data, and GPO contract disclosure filings enabled segmentation-level validation. The analytical framework modeled technology tier, mobility class, clinical application, and end-user facility type throughout the forecast period. CAGRs derived from equipment replacement cycle analysis and reimbursement pathway expansion assumptions, with specific inputs including stroke center accreditation mandates in Chinese tier-one cities and coronary CT angiography protocol adoption in United States emergency departments.
Caveats apply where helium supply quota restrictions, PMDA layer-specific review timeline extensions, or point-of-care ultrasound substitution in intensive care settings could materially shift the outlook. Forecasts reflect assumptions about regulatory clearance pacing and reimbursement decision timing that remain subject to revision. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Nuclear Magnetic Resonance Spectroscopy Market
Medical Imaging
India Nuclear Imaging Market
Medical Imaging
South America Digital X-Ray Devices Market
Medical Imaging
Magnetic Resonance Imaging Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Contrast Agents Market
Medical Imaging
US Interventional Radiology Market
Medical Imaging
Coronary Heart Disease Diagnostic Imaging Market
Medical Imaging
3D Medical and Surgical Imaging Market
Medical Imaging
Nuclear Imaging Devices Market
Medical Imaging
Cone Beam CT Scanner Market
Medical Imaging
Global CT Scanners Market
Medical Imaging
Spinal Imaging Market
Medical Imaging
South Africa Mammography Market
Medical Imaging
Pre-Clinical Imaging System Market
Medical Imaging
Imaging Agents Market
Medical Imaging
Brazil Digital Radiology Market