
 Digital Pathology Market | 2026-2036
Digital Pathology Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Pathology Market Intelligence
Diagnostic-grade resolution standards is collapsing the gap between traditional microscopy and fully digital workflows. Danaher Corporation leverages its life sciences platform to integrate imaging hardware with cloud-based informatics. Koninklijke Philips N.V. sustains technology leadership in whole slide imaging through continuous scanner innovation. Hamamatsu Photonics K.K. dominates high-sensitivity sensor technology that underpins image fidelity at speed.
Digital pathology encompasses the acquisition, management, and analysis of pathology information generated from digitized glass slides using whole slide scanners capable of producing images at resolutions of 0.25 micrometers per pixel or finer, with primary commercial purpose centered on enabling remote diagnosis, quantitative image analysis, and AI-assisted clinical decision support in oncology and histopathology. Whole slide imaging occupies the largest installed base among product categories, while artificial intelligence within the technology dimension captures the fastest expansion as laboratories seek computational assistance for biomarker quantification and cancer subtyping. Cloud-based solutions are gaining structural traction where diagnostic laboratories prioritize distributed access and storage economics over on-premise infrastructure.
The FDA maintains enforcement discretion for certain digital pathology devices, while the EU Medical Device Regulation imposes stricter conformity assessment on AI-enabled diagnostic software, creating divergent compliance burdens that shape product development roadmaps and market entry sequencing. ISO 15189 accreditation requirements for medical laboratories further standardize quality management expectations for digital workflow validation. Stakeholders must weigh regulatory pathway complexity against the margin potential of automated diagnostic platforms as reimbursement frameworks for AI-augmented pathology mature.
Market Dynamics
Diagnostic laboratories face intensifying pressure to reduce turnaround times for cancer biopsies while maintaining diagnostic accuracy, forcing capital allocation toward integrated digital workflow platforms that compress the path from specimen to report.
Growth Catalysts
- FDA Enforcement Discretion:The FDA's policy for certain digital pathology devices in the United States has reduced premarket submission burdens, accelerating commercial deployment timelines for whole slide imaging systems.
- Oncology Workload Expansion:Rising cancer screening volumes and precision medicine protocols are stretching conventional histopathology capacity, creating structural pull for automated image analysis and remote consultation capabilities.
- AI-Enabled Biomarker Quantification:Computational pathology algorithms for PD-L1 scoring, HER2 quantification, and tumor-infiltrating lymphocyte enumeration are driving scanner upgrades and informatics investment.
Market Restraints
- EU MDR Conformity Assessment:The European Union Medical Device Regulation imposes stricter clinical evidence requirements on AI-enabled diagnostic software, extending time-to-market and compliance costs for algorithm developers.
- High-Sensitivity Sensor Supply Concentration:Production of specialized CMOS and CCD sensors for sub-micron resolution scanning concentrates among Japanese and Dutch component suppliers, creating input bottleneck risk.
- Glass Slide Digitization Cost Structure:Capital expenditure for whole slide scanners, storage infrastructure, and workflow software creates adoption barriers for mid-sized hospital laboratories with constrained IT budgets.
Strategic Opportunities
- Community Pathology Networks:Underpenetrated regional hospital systems in the United States present white space for cloud-based digital pathology platforms that enable hub-and-spoke specialist consultation models.
- ISO 15189 Accreditation Tailwind:Medical laboratory quality management standardization creates compliance-driven replacement cycles for validated digital workflow systems in academic and commercial reference laboratories.
- Multiplex Imaging Convergence:Integration of whole slide imaging with spatial transcriptomics and multiplex immunofluorescence is opening new service revenue streams in biomarker discovery and clinical trial support.
Industry Challenges
- Computational Pathology Talent Scarcity:Shortage of professionals with combined expertise in histopathology, machine learning, and regulatory science slows algorithm development and clinical validation timelines.
- Legacy LIS Integration Complexity:Hospital information systems with decades-old architecture require costly middleware development to achieve seamless digital pathology workflow orchestration.
- Interoperability Standardization Delays:Fragmentation between DICOM Whole Slide Imaging and proprietary vendor formats complicates multi-site image exchange and archival retrieval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Pathology Market |
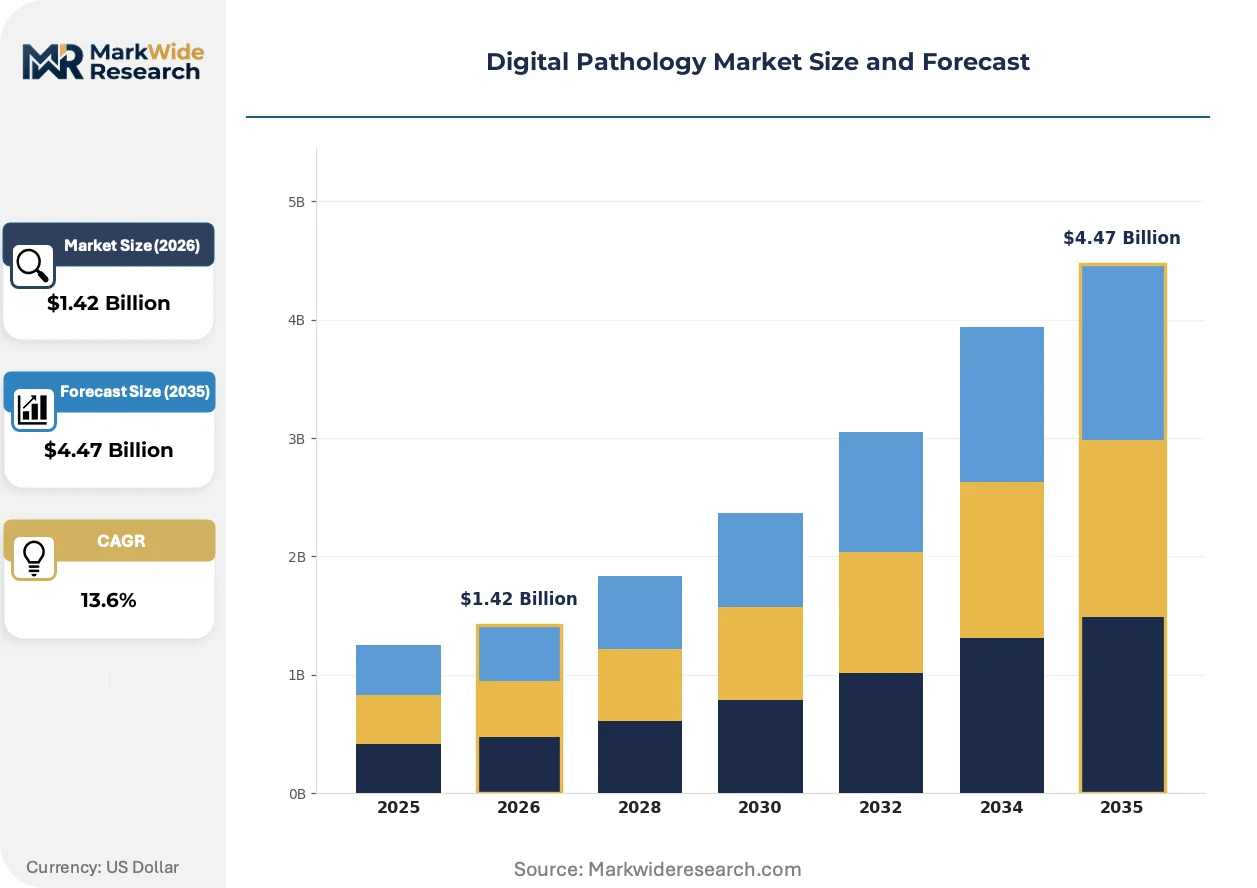
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $4.47 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Slide Imaging, Digital Image Analysis, Image Management Systems, Cloud-based Solutions Technology: Artificial Intelligence, Machine Learning, Telepathology, Digital Staining End User: Hospitals, Diagnostic Laboratories, Academic Institutions, Research Organizations Application: Cancer Diagnosis, Drug Development, Disease Research, Education |
| Companies Covered | Danaher Corporation, Koninklijke Philips N.V., F. Hoffmann-La Roche Ltd., Hamamatsu Photonics K.K., 3DHISTECH, Olympus Corporation, PathAI, Visiopharm A/S, Huron Digital Pathology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Pathology Market Strategic Shifts & Innovations
Artificial intelligence is restructuring how pathology laboratories process visual diagnostic information, shifting competitive advantage toward vendors that control both imaging hardware and algorithm development pipelines.
Deep learning-based cancer subtyping algorithms are fragmenting the traditional diagnostic workflow by enabling automated preliminary reads that pathologists subsequently validate rather than interpret de novo. Community hospital laboratories in the United States are adopting these tools fastest, driven by staffing constraints and case volume pressure. This capability compression is redrawing service boundaries between academic medical centers and regional pathology providers.
The EU AI Act's risk classification framework for medical device software is imposing new conformity obligations on European pathology AI developers, particularly for systems supporting cancer diagnosis. Manufacturers must now maintain quality management systems and post-market monitoring protocols that parallel pharmaceutical vigilance requirements. High-risk algorithm categories face the steepest documentation burdens, pushing some vendors toward lower-risk screening applications.
Subscription-based access models for image analysis software are displacing perpetual license structures in North American and European markets, aligning vendor revenue with laboratory utilization patterns. Diagnostic service companies favor this shift because it converts capital expenditure to operational spending and bundles continuous algorithm updates. Large commercial reference laboratories have negotiated the most favorable terms, using volume commitments to secure platform exclusivity arrangements.
Digital Pathology Market Segmentation
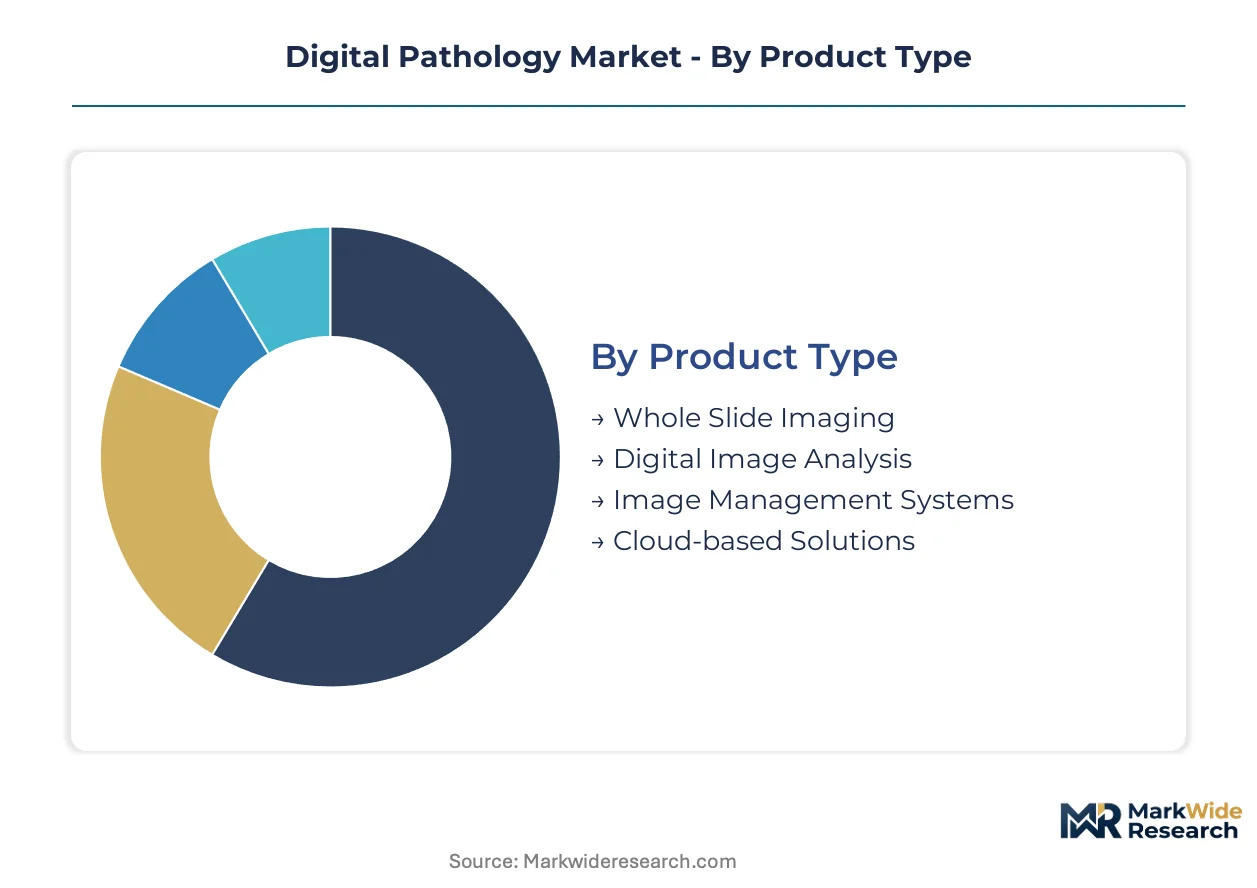
Segmentation in digital pathology reveals how capital flows concentrate around imaging hardware while software and services capture margin expansion. Channel dynamics vary sharply between capital-intensive scanner deployments and recurring cloud subscriptions.
Product Type:
Channel mix splits between direct capital equipment sales to hospital systems and subscription-based software licensing through diagnostic service networks.
- Whole Slide Imaging:High-resolution scanner hardware producing diagnostic-grade images at sub-micron resolution forms the foundational infrastructure layer. Demand concentrates in academic medical centers across the United States upgrading from legacy microscopy, driven by pathology workforce shortages requiring remote consultation capabilities.
- Digital Image Analysis:Algorithm-driven quantification tools for biomarker scoring and cellular enumeration automate previously manual interpretation tasks. Diagnostic laboratories in Germany and France prioritize these solutions to standardize PD-L1 and HER2 scoring consistency across pathologist panels.
- Image Management Systems:On-premise informatics platforms for storage, retrieval, and workflow orchestration serve hospitals with strict data sovereignty requirements.
- Cloud-based Solutions:Distributed access architectures with consumption-based pricing lower entry barriers for mid-sized regional laboratories.
Whole Slide Imaging dominates installed base. Cloud-based Solutions is where expansion concentrates.
Technology:
Cost tier stratification separates premium AI-enabled diagnostic platforms from standardized telepathology connectivity infrastructure.
- Artificial Intelligence:Deep learning algorithms for cancer subtyping, biomarker quantification, and prognostic scoring represent the highest-value technology layer. Academic medical centers in the United States and university hospitals in Switzerland deploy these tools fastest, compelled by precision medicine protocol complexity exceeding human interpretation capacity.
- Machine Learning:Supervised classification systems for tissue segmentation and quality control screening operate at lower regulatory risk classifications than diagnostic AI.
- Telepathology:Real-time image transmission and remote consultation platforms enable hub-and-spoke specialist access for community hospitals.
- Digital Staining:Computational color translation and virtual histochemistry reduce reagent costs and accelerate turnaround for immunohistochemistry workflows.
Artificial Intelligence captures premium pricing tiers. Telepathology shows broadest geographic penetration.
End User:
Customer type determines procurement sophistication, with consolidated health systems negotiating enterprise contracts versus fragmented research buyers accepting list pricing.
- Hospitals:Integrated delivery networks with captive pathology departments drive scanner fleet standardization and enterprise informatics deployment. Mayo Clinic, Cleveland Clinic, and Kaiser Permanente anchor North American demand through multi-site digital transformation initiatives.
- Diagnostic Laboratories:Commercial reference laboratories including Quest Diagnostics and LabCorp pursue automation at scale to process high cancer screening volumes with pathologist workforce constraints.
- Academic Institutions:Medical schools and teaching hospitals prioritize research-grade imaging platforms with algorithm development toolkits.
- Research Organizations:Pharmaceutical companies and contract research organizations utilize digital pathology for clinical trial endpoint adjudication and biomarker discovery.
Hospitals command largest transaction values. Diagnostic Laboratories is climbing the fastest.
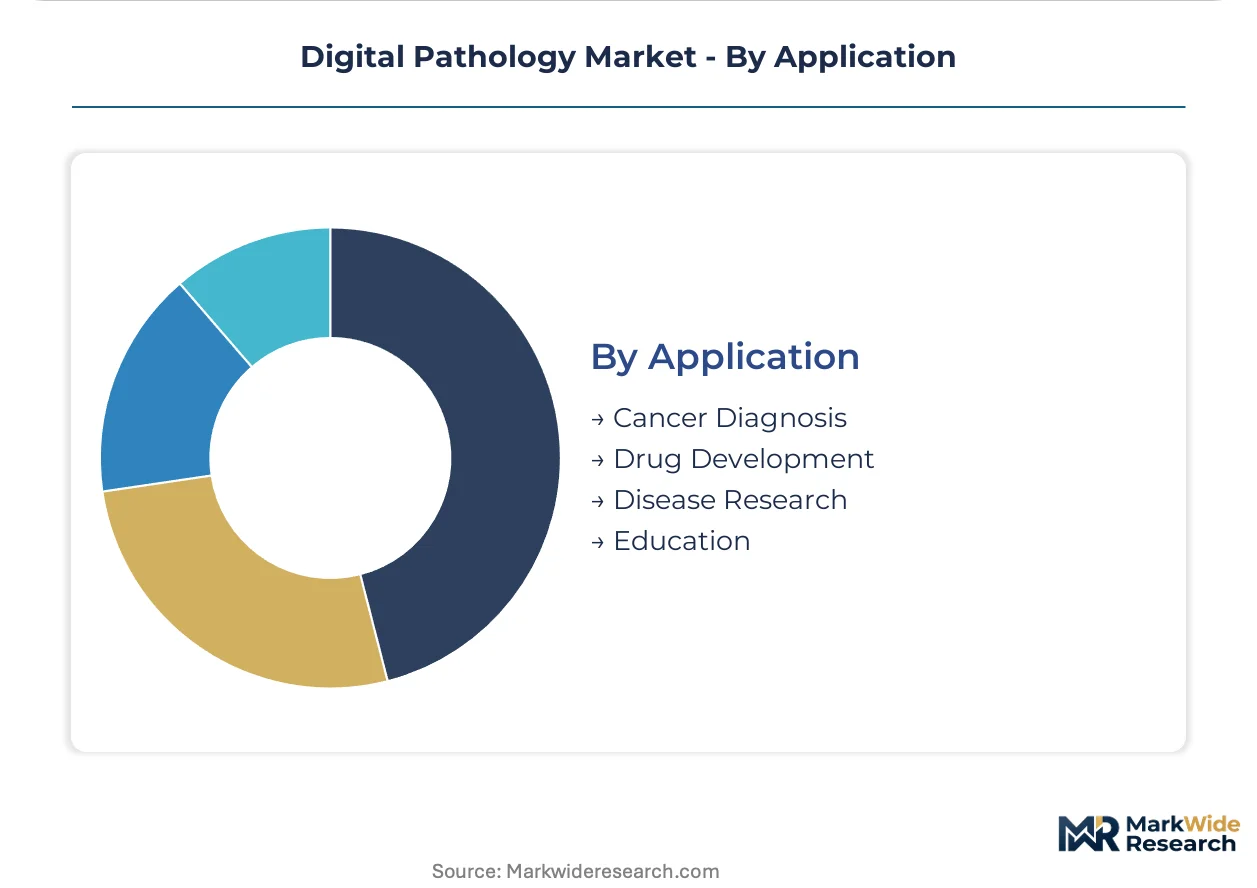
Application:
Application focus determines reimbursement pathway maturity and regulatory scrutiny intensity.
- Cancer Diagnosis:Histopathological confirmation and subtyping for oncology indications constitutes the primary clinical use case. United States health systems concentrate investment here due to concentrated Medicare reimbursement for digital diagnostic services and malpractice liability pressures demanding documentation fidelity.
- Drug Development:Pharmaceutical sponsors deploy digital pathology for companion diagnostic validation and clinical trial tissue biomarker analysis.
- Disease Research:Academic investigators apply whole slide imaging to rare disease tissue biobanks and longitudinal epidemiological studies.
- Education:Medical training programs replace physical slide sets with digital repositories for remote pathology curriculum delivery.
Cancer Diagnosis anchors revenue concentration. Drug Development shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized CMOS and CCD sensor manufacturing concentrates among Japanese and Dutch component suppliers, creating input dependencies that shape scanner production geography. Digital pathology adoption intensity varies sharply by reimbursement maturity and regulatory pathway clarity.
United States
Academic medical center networks and consolidated health systems drive scanner fleet standardization across Mayo Clinic, Cleveland Clinic, and Kaiser Permanente footprints. FDA enforcement discretion for certain digital pathology devices compresses premarket timelines versus jurisdictions with stricter conformity assessment. The Boston-Cambridge corridor anchors algorithm development talent concentration for computational pathology startups.
Germany
University hospitals in Heidelberg and Berlin prioritize PD-L1 and HER2 scoring standardization through algorithm-driven quantification tools. EU MDR imposes clinical evidence requirements on AI-enabled diagnostic software that extend time-to-market for algorithm developers. The Rhine-Main cluster around Frankfurt concentrates commercial reference laboratory automation investment.
Japan
Hamamatsu Photonics K.K. and other sensor specialists underpin domestic supply chain advantages for high-fidelity imaging hardware. PMDA regulatory frameworks align with international standards while maintaining distinct post-market surveillance protocols. Tokyo-Osaka metropolitan corridors host the densest installed base of whole slide imaging systems in Asia-Pacific.
Switzerland
Precision medicine protocol complexity at university hospitals in Zurich and Geneva exceeds human interpretation capacity, accelerating AI deployment. Swissmedic maintains alignment with EU MDR while preserving national notification procedures for software-as-medical-device products. The Basel pharmaceutical corridor drives demand for clinical trial endpoint adjudication platforms.
United Kingdom
NHS pathology network consolidation creates procurement scale for enterprise digital workflow platforms across England's hub-and-spoke diagnostic structures. MHRA post-Brexit regulatory autonomy permits divergence from EU MDR implementation timelines for software-based devices. London-Oxford-Cambridge golden triangle concentrates research-grade imaging platform development for biomarker discovery.
Digital Pathology Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with imaging hardware specialists competing against diversified life sciences conglomerates for scanner placement. The market structure separates premium-tier vendors with integrated algorithm pipelines from mid-market players competing on scanner throughput specifications. Two dominant archetypes emerge: diversified conglomerates leveraging platform synergies, and specialized imaging technology purists with captive sensor capabilities. Competitive moves concentrate on strategic partnerships between hardware vendors and algorithm developers, plus geographic expansion through distributor networks in underpenetrated regional hospital systems.
Among diversified life sciences conglomerates, Danaher Corporation and F. Hoffmann-La Roche Ltd. represent the integrated platform archetype, combining imaging hardware with downstream diagnostic consumables and informatics infrastructure. Koninklijke Philips N.V. and Hamamatsu Photonics K.K. exemplify the imaging technology specialist position, with the former emphasizing scanner innovation and the latter anchoring high-sensitivity sensor supply. PathAI occupies a position within the pure-play computational pathology tier, while 3DHISTECH and Visiopharm A/S sit within the European specialist segment focused on algorithm development and image analysis software.
| Leading Market Players |
|---|
| Danaher Corporation |
| Koninklijke Philips N.V. |
| F. Hoffmann-La Roche Ltd. |
| Hamamatsu Photonics K.K. |
| 3DHISTECH |
| Olympus Corporation |
| PathAI |
| Visiopharm A/S |
| Huron Digital Pathology |
| Others |
Cost & Logistics Intelligence
Scanner component lead times stretching beyond 180 days for high-sensitivity CMOS sensors concentrate pricing power with Japanese and Dutch suppliers, compressing margins for mid-tier whole slide imaging vendors while premium-tier players capture algorithm-enabled price premiums.
Pricing Analysis
FDA enforcement discretion dictates the pricing tier structure across the United States market, separating validated diagnostic platforms from research-grade systems. Three-tier pricing structure across premium, standard, and economy levels reflects algorithm maturity, ISO 15189 accreditation status, and after-sales service bundling. Cost compression in the economy tier intensifies because cloud-native entrants displace perpetual license models with subscription-based consumption. Community hospital laboratories exhibit highest price sensitivity, while academic medical centers prioritize performance specifications over procurement cost.
Supply Chain Analysis
Japan and the Netherlands anchor high-sensitivity sensor fabrication for sub-micron resolution scanning, with Hamamatsu Photonics K.K. and specialized Dutch component houses feeding upstream scanner assembly. Production draws from specialized CMOS and CCD wafer foundries, precision optical assemblies, and thermal management subsystems. Single-source vulnerability concentrates in sensor die supply, where qualified alternative sources require multi-year validation cycles. Distribution runs through direct capital equipment sales for hospital systems and value-added reseller networks for mid-sized diagnostic laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of professionals bridging histopathology expertise with machine learning engineering and regulatory science constrains algorithm development velocity, creating durable advantage for organizations that consolidate this scarce capability stack.
For Market Incumbents: Fortify algorithm-hardware integration through captive development of PD-L1 and HER2 quantification pipelines, defending against pure-play computational pathology entrants. Prioritize ISO 15189 accreditation pre-certification for cloud-based platforms to accelerate replacement cycles in European reference laboratories. Deepen backward integration into sensor specification to reduce dependency on Japanese and Dutch component suppliers. For New Entrants and Emerging Players: Remote consultation service gaps in United States community hospital networks offer the most penetrable entry point, where staffing constraints exceed capital budget limitations for scanner acquisition. Target hub-and-spoke specialist access models with consumption-based pricing that converts capital expenditure to operational spending. Pursue strategic partnerships with existing whole slide imaging hardware vendors to bypass sensor supply bottlenecks. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because algorithm-enabled diagnostics capture recurring revenue streams with higher retention than hardware-only vendors. Acquisition targets should demonstrate validated clinical evidence packages for cancer subtyping applications and established GPO contracts with consolidated health systems. Monitor FDA enforcement discretion policy continuity as the primary inflection signal for valuation multiples in United States-focused assets.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm-Hardware Integration | Danaher Corporation and Philips capture margin expansion through bundled AI-enabled scanner platforms. |
| Cloud-Native Platform Development | Subscription models align vendor revenue with laboratory utilization patterns across Quest Diagnostics and LabCorp networks. |
| ISO 15189 Accreditation Investment | Compliance-driven replacement cycles accelerate in European academic and commercial reference laboratories. |
| Sensor Supply Diversification | Backward integration into CMOS specification reduces vulnerability to Japanese and Dutch component concentration. |
| Community Hospital Network Partnership | Hub-and-spoke specialist access models unlock underpenetrated regional systems in the United States. |
Research Approach
Cross-validation between primary interviews with pathology department chairs, biomedical informatics officers, diagnostic laboratory operations directors, and regulatory affairs specialists and secondary validation through FDA 510(k) filings, EU MDR conformity assessment databases, hospital procurement records, and GPO contract disclosures anchors the qualitative findings. Bottom-up triangulation against scanner installation data and top-down reconciliation with capital expenditure disclosures from consolidated health systems ensures coverage completeness.
Sensitivity analysis across deployment model, end-user scale tier, algorithm regulatory status, and regional reimbursement maturity shapes the analytical framework over the projection horizon. CAGRs derive from installed base growth trajectories, replacement cycle compression, and attach rate expansion for software subscriptions. Forecast inputs incorporate pathology workforce shortage projections, precision medicine protocol adoption curves, and cloud infrastructure cost decline assumptions.
Underlying assumptions cover FDA enforcement discretion continuity, EU MDR implementation stability, and sensor supply chain resiliency, with deviation risk concentrated in algorithm reimbursement pathway delays and legacy LIS integration complexity. Recalibration cycles align with material shifts in regulatory guidance, health system consolidation patterns, and computational pathology talent availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Vendor Neutral Archive Market
Medical Imaging
Portable MRI Market
Medical Imaging
Structural Heart Imaging Market
Medical Imaging
Intraoperative Imaging Market
Medical Imaging
PET Radiotracer Market
Medical Imaging
Digital X-Ray Imaging Market
Medical Imaging
Medical Holography Market
Medical Imaging
Europe Medical Imaging Market
Medical Imaging
Contrast Media/Contrast Agents Market
Medical Imaging
Global Artificial Intelligence in MRI Market
Medical Imaging
North America Medical Imaging Software Market
Medical Imaging
Global Cardiac Imaging Software Market
Medical Imaging
South Korea Magnetic Resonance Imaging Market
Medical Imaging
China Digital X-Ray Market
Medical Imaging
United Kingdom Magnetic Resonance Imaging Market
Medical Imaging
Australia Digital Radiology Market