
 Coronary Heart Disease Diagnostic Imaging Market | 2026-2036
Coronary Heart Disease Diagnostic Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Coronary Heart Disease Diagnostic Imaging Market Insights
European and North American medical device manufacturing is hardening around precision cardiac imaging platforms. GE HealthCare leverages deep integration between CT hardware and AI reconstruction software to sustain installed base loyalty across major hospital networks. Siemens Healthineers anchors its position through advanced photon-counting CT detectors that differentiate image clarity for coronary plaque characterization. Koninklijke Philips competes on integrated catheterization lab-to-imaging workflow solutions that dominate interventional cardiology suites.
Coronary heart disease diagnostic imaging encompasses non-invasive and minimally invasive visualization technologies that detect myocardial ischemia, quantify coronary artery stenosis, and assess ventricular function using ionizing radiation, magnetic fields, or acoustic energy. These systems operate at spatial resolutions below one millimeter and temporal resolutions under 100 milliseconds to freeze cardiac motion during image acquisition. Computed tomography angiography leads modality revenue due to its established reimbursement for chest pain evaluation in emergency departments. Magnetic resonance imaging stress perfusion represents the fastest-growing segment as centers adopt radiation-free alternatives for serial patient monitoring. Nuclear imaging maintains stable demand in rural and budget-constrained settings where SPECT system depreciation cycles extend operational utility.
FDA premarket notification requirements for 510(k) cardiac imaging devices shape product development timelines and predicate selection strategies for manufacturers seeking US market entry. CE marking under the EU Medical Device Regulation imposes enhanced clinical evidence standards that filter out lower-capability entrants from European distribution. Japan's PMDA maintains distinct pharmaceutical and medical device agency review pathways that extend registration timelines but reward compliant firms with protected market access. Stakeholders must monitor evolving AI diagnostic criteria from regulators and decide whether to prioritize algorithm-first development or hardware-anchored platform strategies.
Market Dynamics
Photon-counting CT detectors are compressing scan times and radiation doses, forcing incumbent manufacturers to accelerate hardware refresh cycles across installed bases. This technology inflection is redrawing competitive moats around image reconstruction software and detector materials science.
Growth Catalysts
- Chest pain triage protocols:Emergency departments in the United States are embedding coronary CT angiography into accelerated diagnostic pathways, cutting observation stays and driving scanner utilization rates.
- Japan's PMDA fast-track review:The regulator's priority review designation for AI-enabled cardiac imaging algorithms is compressing premarket timelines and attracting algorithm developers to Tokyo's medical device cluster.
- Photon-counting detector materials:Cadmium telluride and silicon crystal advances are enabling sub-millimeter spatial resolution at lower tube currents, expanding eligible patient populations to higher BMI categories.
Market Restraints
- Helium supply concentration:Magnetic resonance imaging systems depend on helium for superconducting magnet cooling, with extraction concentrated in Qatar and Algeria creating price volatility and allocation risk.
- EU MDR clinical evidence requirements:The Medical Device Regulation's expanded predicate equivalence standards are extending CE marking timelines and filtering out lower-capability entrants from European distribution.
- Interventional cardiologist training pipelines:Fellowship programs produce insufficient operators for fractional flow reserve-guided CT interpretation, capping throughput at advanced imaging centers.
Strategic Opportunities
- Rural SPECT system refurbishment:Secondary markets in India present white space for certified pre-owned nuclear imaging systems, extending depreciation cycles where capital budgets constrain new equipment procurement.
- AI-integrated reporting workflows:Natural language processing algorithms automating structured coronary CT reports are opening channel partnerships between imaging software vendors and electronic health record platforms.
- Japan's regional medical care support system:METI subsidies for hub-and-spoke cardiology networks are creating demand for teleradiology-enabled CT systems linking tertiary centers to remote prefecture hospitals.
Industry Challenges
- Cross-modality credentialing:Radiologists trained on conventional angiography require substantial retraining for CT-FFR interpretation, creating workforce friction at hybrid imaging centers.
- Legacy PACS integration:Picture archiving and communication systems deployed in the 2010s lack bandwidth for AI-augmented 3D coronary reconstructions, forcing costly middleware deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coronary Heart Disease Diagnostic Imaging Market |
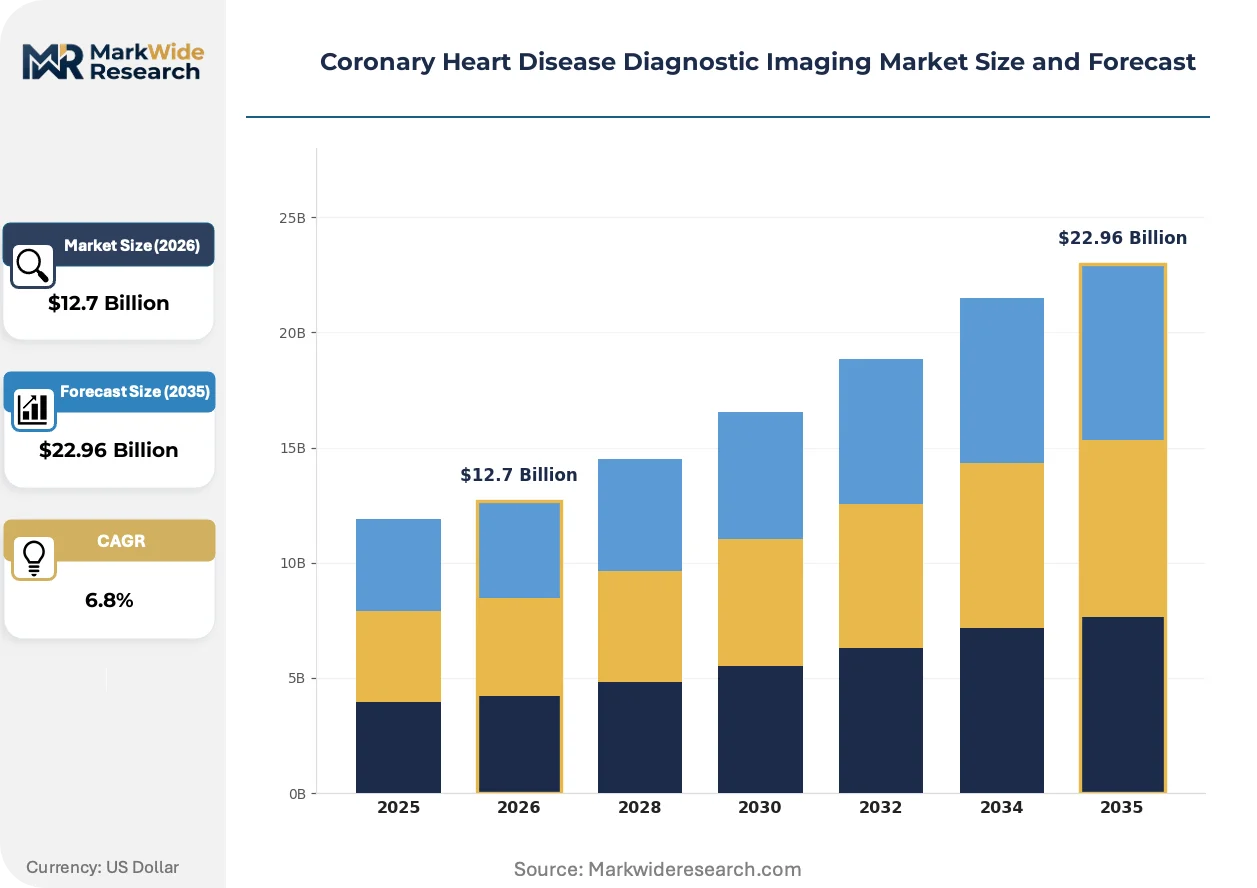
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $22.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Imaging Modality: Computed Tomography, Magnetic Resonance Imaging, Positron Emission Tomography, Ultrasound, Nuclear Imaging Application Type: Early Detection, Risk Assessment, Treatment Planning, Post-Treatment Monitoring End User: Cardiology Departments, Diagnostic Centers, Research Institutes, Outpatient Clinics, Specialty Hospitals Service Model: Inpatient Diagnosis, Outpatient Diagnosis, Mobile Imaging, Telemedicine Services |
| Companies Covered | GE HealthCare, Siemens Healthineers, Koninklijke Philips, FUJIFILM Holdings Corporation, Canon Medical Systems, Samsung Medison, Shimadzu Corporation, Hitachi, Mindray, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coronary Heart Disease Diagnostic Imaging Market Trends and Innovations
Computational reconstruction algorithms are displacing hardware-centric performance gains, shifting R&D investment toward software-defined imaging platforms. This inversion is compressing product development cycles and opening entry points for specialized algorithm developers.
Photon-counting detector technology is decentralizing high-resolution coronary imaging from academic medical centers to community hospital networks. Community cardiology groups in Germany and Japan are deploying these systems to capture chest pain referrals that previously transferred to tertiary centers. The structural consequence is fragmenting procedure volume and pressuring per-scan reimbursement at flagship institutions.
The EU AI Act's risk classification framework is mandating conformity assessments for diagnostic algorithms that influence clinical decisions. Cardiac CT analysis software falls under high-risk categories, requiring notified body involvement and post-market performance monitoring. Algorithm developers are responding by establishing European authorized representatives and clinical evidence dossiers ahead of 2026 enforcement deadlines.
Hospital procurement committees are unbundling equipment acquisition from service contracts, negotiating separate terms for hardware, software licenses, and predictive maintenance. This disaggregation is most visible in United States integrated delivery networks, where capital committees scrutinize total cost of ownership across 7-10 year holding periods. Vendors are responding with modular pricing architectures that separate detector upgrades from gantry replacements.
Coronary Heart Disease Diagnostic Imaging Market Segmentation
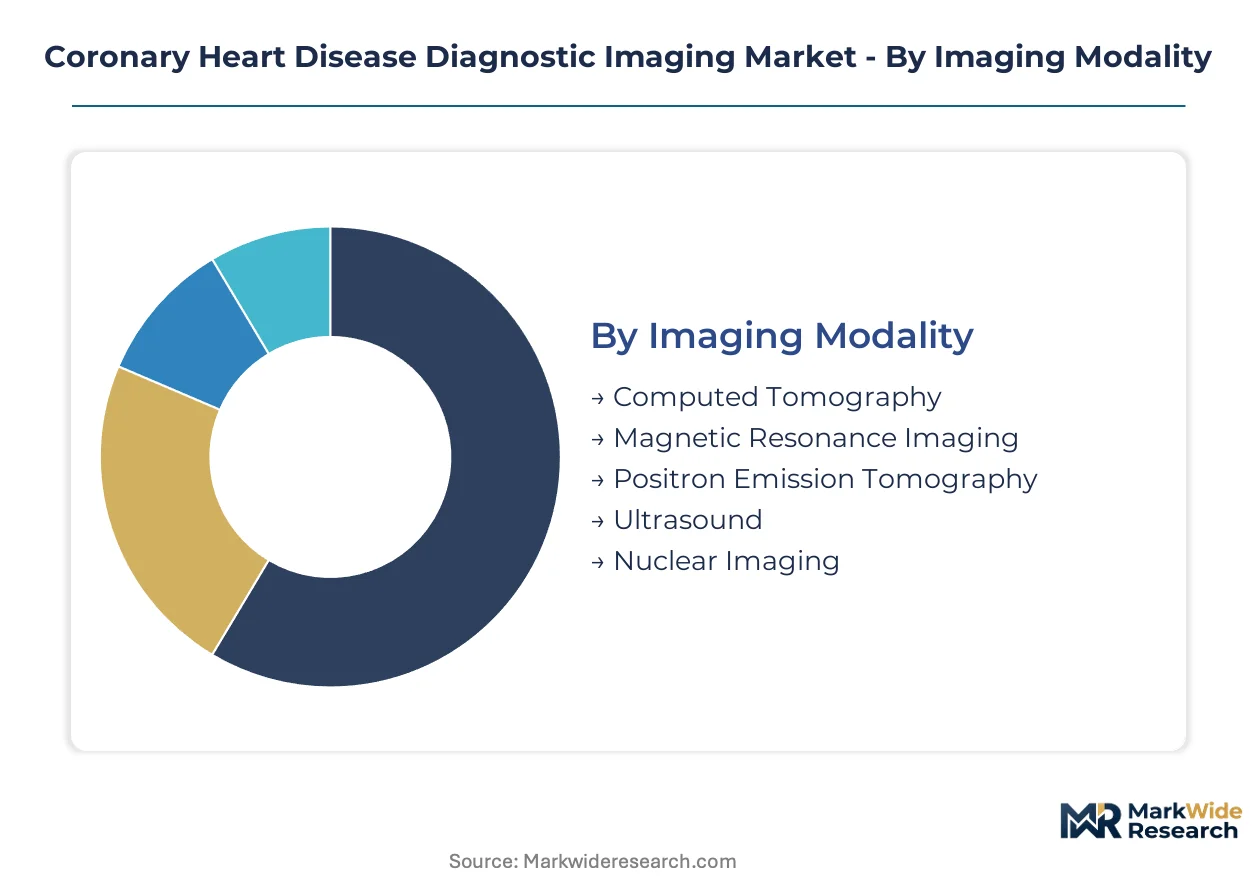
Coronary heart disease diagnostic imaging segments by modality, application, end user, and service delivery model. Each dimension shapes procurement priorities, reimbursement pathways, and technology investment cycles across hospital systems.
Imaging Modality:
Volume concentration favors established platforms with broad reimbursement coverage. Premium positioning clusters around detector innovations and radiation-free alternatives.
- Computed Tomography:Coronary CT angiography dominates emergency department chest pain triage with sub-millimeter spatial resolution and sub-100-millisecond temporal capture. United States hospital networks drive scanner utilization through accelerated diagnostic protocols, cutting observation stays.
- Magnetic Resonance Imaging:Stress perfusion MRI expands fastest as academic centers adopt radiation-free serial monitoring for repeat patient assessments. Germany's university hospitals anchor European demand for 3T systems with advanced coil arrays.
- Positron Emission Tomography:PET-CT hybrid systems quantify myocardial perfusion and metabolism simultaneously, serving ischemia-viability assessment in surgical planning.
- Ultrasound:Transthoracic and transesophageal echocardiography deliver portable, real-time functional assessment without ionizing radiation.
- Nuclear Imaging:SPECT systems maintain operational utility in budget-constrained settings where extended depreciation cycles defer capital replacement.
Mature deployment sits with Computed Tomography. Newer deployment is concentrated in Magnetic Resonance Imaging.
Application Type:
Clinical utility varies by reimbursement stage and evidence requirements for each indication.
- Early Detection:Asymptomatic screening protocols leverage calcium scoring and CT angiography for subclinical atherosclerosis identification. Japan's health checkup programs incorporate coronary CT into standardized cardiovascular risk assessments.
- Risk Assessment:Fractional flow reserve CT and plaque characterization algorithms stratify patients for invasive versus conservative management. United States insurers increasingly cover CT-FFR for intermediate stenosis evaluation.
- Treatment Planning:Pre-procedural imaging guides stent sizing, landing zone selection, and complication risk stratification for interventional cardiologists.
- Post-Treatment Monitoring:Serial imaging tracks stent patency, graft function, and disease progression following revascularization procedures.
Established reimbursement anchors Early Detection. Regulatory evidence requirements are expanding fastest for Risk Assessment.
End User:
Procurement authority and capital allocation cycles differ sharply across facility types.
- Cardiology Departments:Integrated imaging suites within hospital systems command the largest capital budgets for multi-modality platform deployment. United States academic medical centers lead photon-counting CT adoption.
- Diagnostic Centers:Independent imaging facilities compete on throughput and report turnaround time, favoring standardized protocols and teleradiology integration.
- Research Institutes:Clinical trial imaging cores require specialized quantification software and regulatory-compliant image management systems.
- Outpatient Clinics:Limited-service settings prioritize portable ultrasound and referral relationships with full-capability centers.
- Specialty Hospitals:Cardiovascular-focused institutions concentrate high-end hybrid operating room imaging for structural heart procedures.
Capital concentration sits with Cardiology Departments. Technology diffusion is accelerating fastest through Diagnostic Centers.
Service Model:
Revenue capture and cost structures diverge by care setting and patient flow design.
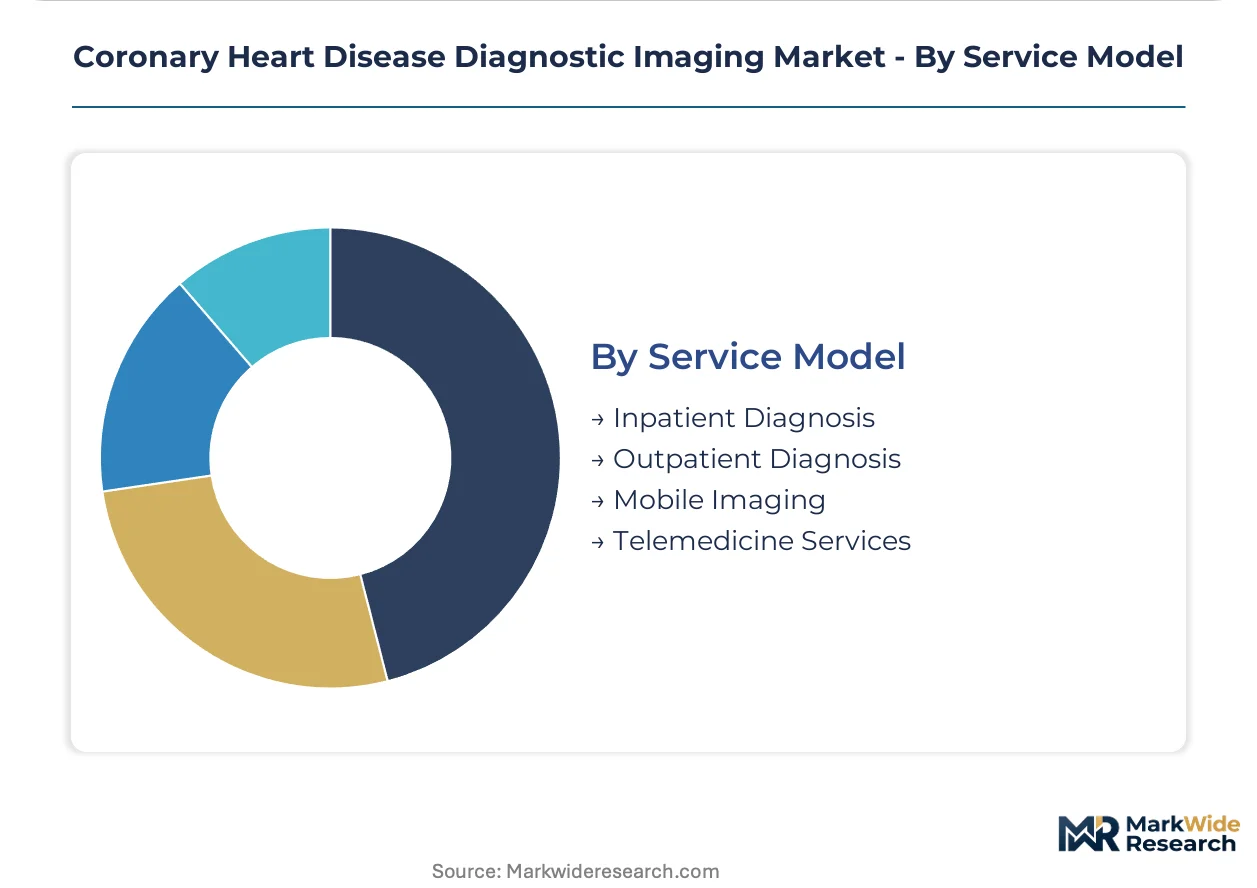
- Inpatient Diagnosis:Emergency department-embedded CT angiography captures chest pain admissions before transfer decisions. United States observation unit protocols drive same-day discharge rates.
- Outpatient Diagnosis:Scheduled elective imaging in dedicated centers achieves higher scanner utilization and lower per-scan overhead.
- Mobile Imaging:Trailer-mounted CT and PET systems extend service reach to rural and underserved markets without fixed infrastructure investment.
- Telemedicine Services:Hub-and-spoke teleradiology networks connect remote acquisition sites to centralized interpretation expertise, supported by Japan's METI regional medical care subsidies.
Established volume sits with Inpatient Diagnosis. Network expansion is concentrating fastest in Telemedicine Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helium extraction in Qatar and Algeria concentrates the cooling feedstock for MRI superconducting magnets, creating supply vulnerability that shapes procurement strategies across major imaging markets. Germany's cadmium telluride detector manufacturing anchors photon-counting CT supply chains. Japan's silicon crystal foundries enable next-generation semiconductor detector substrates.
United States
Emergency department chest pain triage protocols drive coronary CT angiography utilization at academic medical centers in Boston, Cleveland, and Houston. FDA 510(k) premarket notification pathways compress algorithm development timelines for AI-enabled plaque characterization tools. The Cleveland Clinic anchors photon-counting CT adoption through its cardiovascular imaging core.
Germany
University hospitals in Munich and Heidelberg deploy 3T MRI stress perfusion systems for radiation-free serial monitoring of coronary patients. CE marking under the EU Medical Device Regulation imposes enhanced clinical evidence standards that filter lower-capability entrants from European distribution. The Bavarian medical device cluster around Erlangen concentrates photon-counting detector engineering talent.
Japan
Aging demographics and METI regional medical care subsidies expand hub-and-spoke cardiology networks linking Tokyo tertiary centers to remote prefecture hospitals. PMDA fast-track review designations for AI-enabled cardiac imaging algorithms compress premarket timelines and attract developers to the Kanto medical device cluster. Osaka-based manufacturers supply teleradiology-enabled CT systems for distributed interpretation workflows.
China
Domestic CT scanner production scales to meet hospital procurement targets under the national health infrastructure expansion program. NMPA medical device registration pathways extend timelines for imported systems while accelerating approvals for locally manufactured platforms. The Yangtze River Delta medical device manufacturing corridor around Shanghai concentrates assembly capacity for mid-range diagnostic imaging systems.
India
Secondary and tertiary care hospitals in Maharashtra and Karnataka extend SPECT system depreciation cycles where capital budgets constrain new equipment procurement. CDSCO medical device registration requirements create compliance barriers for imported premium systems. The Delhi-NCR diagnostic imaging market concentrates independent imaging center chains competing on throughput and report turnaround time.
Coronary Heart Disease Diagnostic Imaging Market Competitive Landscape
Global majors compete with regional champions across hardware-software integration depth and installed base loyalty. The market structures around three tiers: integrated conglomerates with full modality portfolios, specialized cardiovascular imaging platform developers, and regional assemblers serving price-sensitive procurement committees. Dominant competitive moves include detector technology licensing agreements and AI algorithm co-development partnerships with academic medical centers.
Within the integrated systems tier, GE HealthCare, Siemens Healthineers, and Koninklijke Philips represent the archetype of hardware-software platform consolidation. These entities anchor competitive positioning through installed base relationships across major hospital networks rather than discrete product transactions. Regional specialists including Canon Medical Systems and Shimadzu Corporation occupy positions between global scale and local service responsiveness.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers |
| Koninklijke Philips |
| FUJIFILM Holdings Corporation |
| Canon Medical Systems |
| Samsung Medison |
| Shimadzu Corporation |
| Hitachi |
| Mindray |
| Others |
Pricing and Supply Chain Analysis
EU MDR sustainability disclosure mandates for medical device manufacturers gate both qualified component supply and premium-tier pricing access, forcing OEMs to document carbon footprints across detector materials and helium sourcing before qualifying for high-margin procurement contracts at United States academic medical centers.
Pricing Analysis
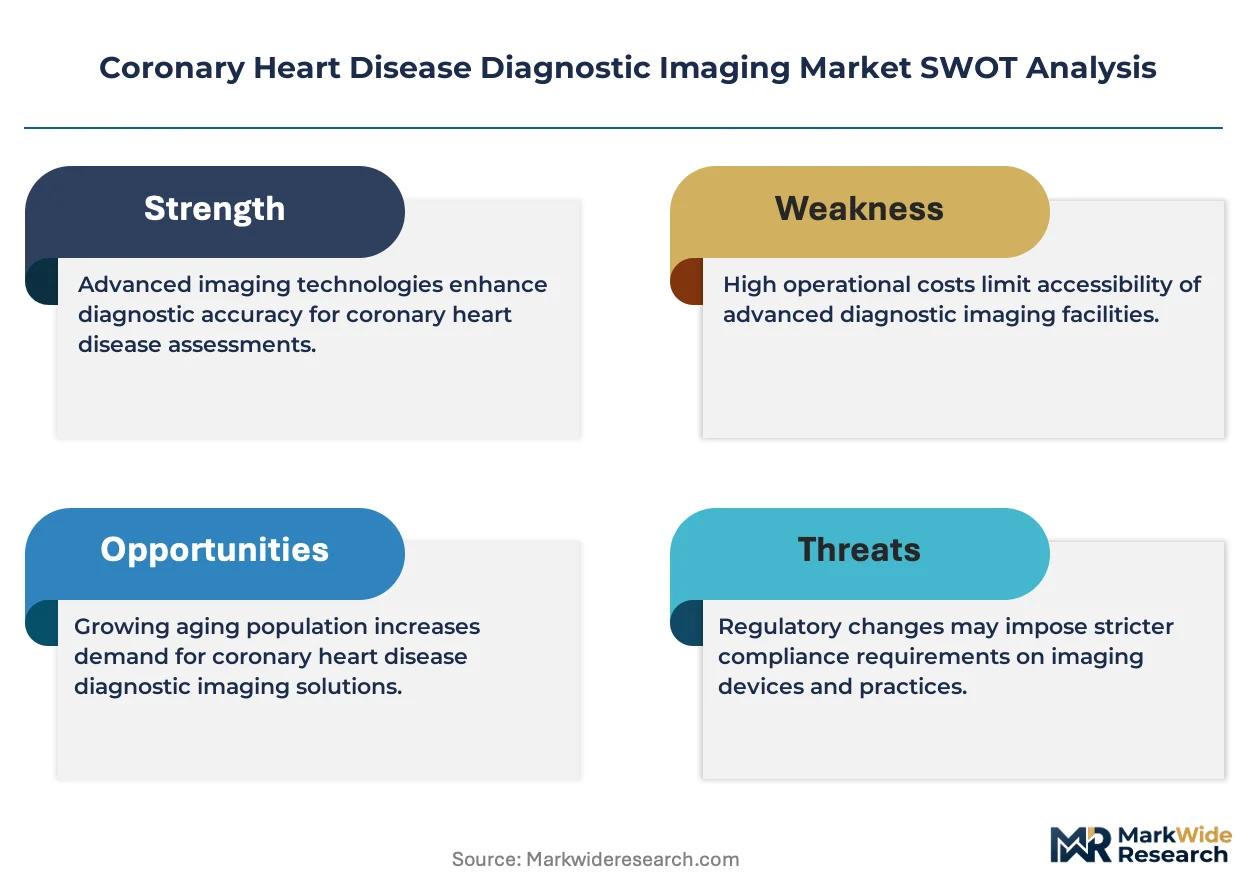
Warranty and predictive maintenance bundling now separates premium CT system contracts from unbundled hardware transactions at United States integrated delivery networks. Three-tier pricing structure across premium, standard, and economy levels reflects detector generation, AI reconstruction software licensing tiers, and service contract duration. Pricing pressure stems from hospital capital committees scrutinizing total cost of ownership across extended holding periods. Community hospital networks exhibit highest price sensitivity; academic medical centers with NIH funding streams demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States anchor hub-and-spoke patterns for photon-counting detector modules and superconducting magnet components. Manufacturing draws from cadmium telluride crystal growth in Bavaria, silicon semiconductor substrates from Kanto prefecture facilities, and helium liquefaction concentrated in Qatar and Algeria. Single-source vulnerability in helium feedstock creates allocation risk for MRI system production. Distribution runs through authorized dealer networks with factory-trained service engineers for installation and preventive maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race, with detector materials science and AI reconstruction software representing the critical upstream and downstream levers that determine margin capture.
For Market Incumbents: Lock in installed base loyalty through predictive maintenance contracts that extend photon-counting CT detector refresh cycles at major United States hospital networks. Deepen backward integration into cadmium telluride crystal growth to secure supply priority against emerging Asian detector manufacturers. Priority certification investment: EU AI Act conformity assessments for high-risk diagnostic algorithms ahead of enforcement deadlines.
For New Entrants and Emerging Players: Natural language processing algorithms for automated coronary CT reporting represent the most penetrable wedge into established workflows. Target teleradiology-enabled hub-and-spoke networks in Japan's regional prefectures where METI subsidies lower customer acquisition costs. Go-to-market angle: electronic health record platform partnerships that bypass capital equipment procurement committees.
For Investors and Strategic Acquirers: PMDA fast-track designations for AI-enabled cardiac imaging algorithms are the leading indicator that algorithm-first developers will command valuation premiums over hardware-anchored platforms. Long-term viability favors firms controlling both detector intellectual property and regulatory-cleared software companions. Acquisition target archetype: specialized cardiovascular quantification software vendors with FDA 510(k) clearances and academic medical center validation studies. Signal to watch: hospital procurement committee decisions to unbundle equipment from service contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting Detector Upgrade Programs | GE HealthCare and Siemens Healthineers accelerate refresh cycles at Cleveland Clinic and other academic anchors. |
| AI Algorithm Co-Development Partnerships | Software vendors collaborate with Mayo Clinic and Stanford for CT-FFR validation studies supporting FDA submissions. |
| Helium Recycling Infrastructure Investment | Philips deploys closed-loop magnet cooling systems to mitigate Qatar supply concentration risk at European installations. |
| Teleradiology Platform Integration | Osaka manufacturers connect Tokyo tertiary centers to remote prefecture hospitals under METI regional care subsidies. |
| CE Marking Pathway Acceleration | Algorithm developers establish European authorized representatives ahead of EU AI Act high-risk conformity deadlines. |
Research Methodology
Independent corroboration across FDA 510(k) premarket notification databases, PMDA approval registries, and EU MDR notified body certificates underwrites the qualitative findings on regulatory pathway compression. Primary interviews with interventional cardiologists, hospital purchasing committee chairs, biomedical engineers at academic medical centers, and GPO contracts managers combined with secondary validation from CMS Medicare reimbursement data, hospital procurement databases, and medical device trade flow records. Bottom-up scanner installation tracking and top-down manufacturer revenue analysis triangulate market sizing.
Comparable-period anchoring to historical CT and MRI replacement cycles across the projection horizon informs installed base evolution modeling. Segmentation dimensions include imaging modality, application type, end-user facility category, and service delivery model, with additional granularity on detector technology generation and AI software integration tier. CAGRs derive from logistic diffusion curves for photon-counting CT adoption and linear extrapolation of MRI stress perfusion expansion. Forecast inputs incorporate PMDA fast-track review velocity and EU MDR clinical evidence requirement stringency.
Several conditions sit outside the modeled scope, including sudden helium supply disruptions from Qatar geopolitical events, FDA algorithm enforcement discretion shifts, and radiologist workforce training pipeline collapses. Forecasts reflect documented assumptions on reimbursement stability and regulatory timeline adherence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market
Medical Imaging
Positron Emission Tomography Devices (PET) Market
Medical Imaging
Image Guided Radiotherapy Market
Medical Imaging
Digital Breast Tomosynthesis Market
Medical Imaging
Cone Beam Computed Tomography (CBCT) System Market
Medical Imaging
Imaging Agents Market
Medical Imaging
Nuclear Magnetic Resonance Spectroscopy Market
Medical Imaging
Mammography Detectors Market
Medical Imaging
Medical Imaging Displays Market
Medical Imaging
South Korea Nuclear Imaging Market
Medical Imaging
Digital Radiography Detectors Market
Medical Imaging
Germany Mammography Market
Medical Imaging
Mexico Mammography Market
Medical Imaging
Preclinical Ultrasound Systems Market
Medical Imaging
Canada Nuclear Imaging Market
Medical Imaging
Quantitative Pathology Imaging Market