
 North America Concrete Sealer Market | 2026-2036
North America Concrete Sealer Market Size, Share, and Industry Trends Forecast 2026-2036
North America Concrete Sealer Market Intelligence
Application-specific maintenance subscriptions for predictive re-coating schedules is pivoting how sealer value gets captured across project lifecycles. PPG Industries Inc. leverages its coatings distribution network to control specification channels for high-performance commercial installations. RPM International Inc. sustains R&D intensity in penetrating silane technologies for infrastructure exposed to freeze-thaw cycles. Sherwin-Williams Company anchors its position through backward integration into resin manufacturing and captive supply of acrylic intermediates.
Concrete sealer constitutes a liquid-applied protective barrier, typically formulated from acrylic resins, silane/siloxane oligomers, or polyurethane prepolymers at solids contents ranging from 10% to 40%, that penetrates or films over cured concrete substrates to repel water, chlorides, and carbon dioxide while permitting vapor transmission. Its primary commercial purpose extends service life of horizontal and vertical concrete elements in transportation, commercial, and industrial asset portfolios. Silane formulations command premium positioning in parking structures and bridge decks where deep penetration and alkali resistance define performance tiers. Acrylic waterborne systems lead volume in driveway and sidewalk applications where ease of application and cost accessibility shape contractor selection. Epoxy segments occupy the industrial facilities niche with highest film-build requirements for chemical spill protection.
EPA VOC regulations under 40 CFR Part 59 restrict solvent-borne sealer formulations in architectural coatings, compelling manufacturers to reformulate toward compliant waterborne and exempt-solvent chemistries. OSHA permissible exposure limits for isocyanates in polyurethane application influence contractor equipment investments and product substitution patterns on job sites. ASTM C309 and AASHTO specifications govern curing-compound and sealer performance for federally funded infrastructure, creating specification gatekeeping for qualified products. Stakeholders must monitor state-level low-carbon procurement mandates and evolving extended producer responsibility frameworks that could reshape material selection criteria and supplier qualification pathways.
Market Dynamics
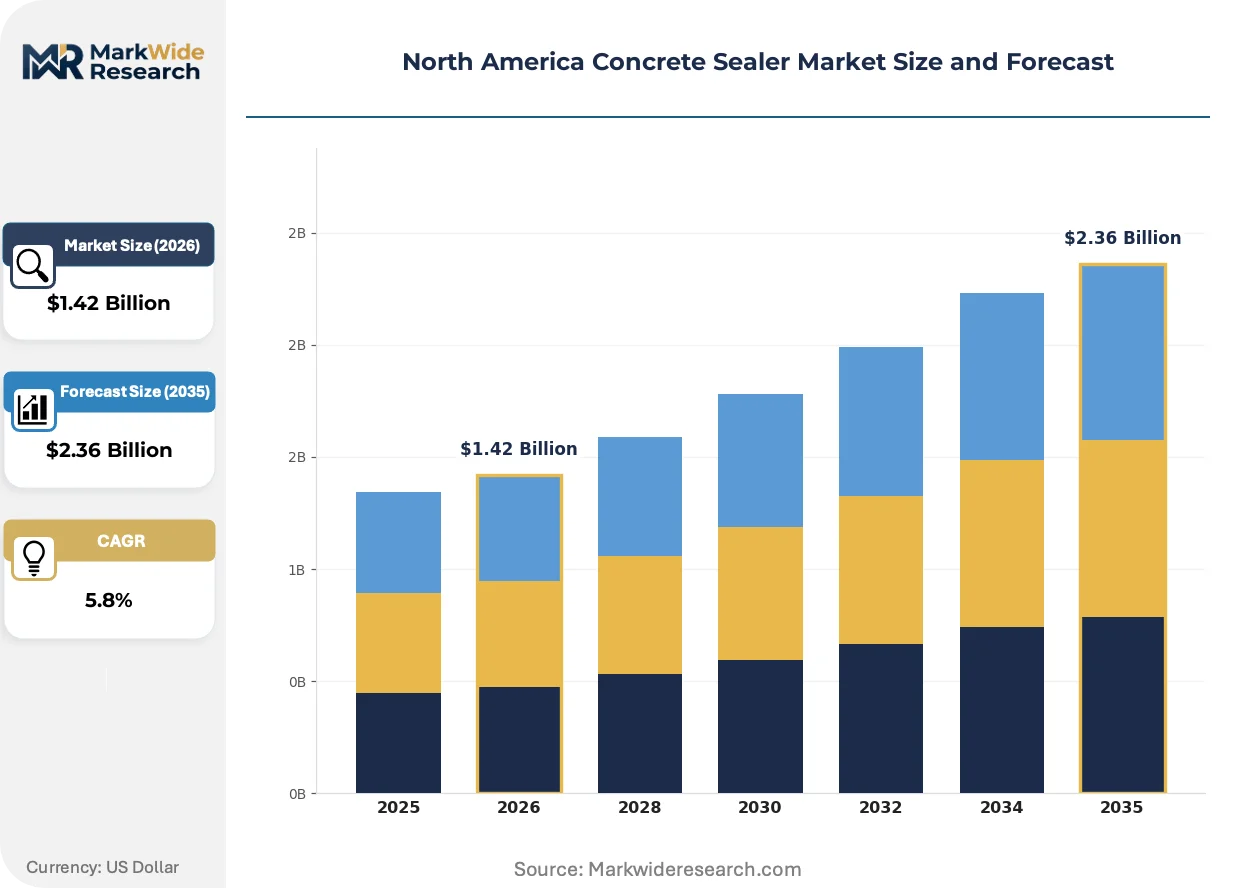
EPA VOC mandates under 40 CFR Part 59 are forcing solvent-borne formulation obsolescence while waterborne acrylic and silane substitutions capture specification share across municipal infrastructure and commercial construction channels.
Growth Catalysts
- Infrastructure rehabilitation cycles:Bridge deck and highway barrier maintenance budgets across the United States are expanding sealant procurement volumes for chloride-exposed concrete protection.
- 40 CFR Part 59 compliance pathways:Low-VOC formulation mandates are accelerating waterborne acrylic and silane substitutions in architectural coating applications.
- Coastal salt-exposure corridors:The Texas-California construction belt drives specification intensity for penetrating silane systems in warehouse and logistics facility foundations.
Market Restraints
- Petrochemical feedstock volatility:Acrylic resin and polyurethane prepolymer input costs fluctuate with crude oil derivatives, compressing margin stability for formulators.
- Freeze-thaw performance gaps:Waterborne acrylic films exhibit reduced durability in northern tier climates with deep thermal cycling, limiting geographic deployment.
- Isocyanate exposure controls:OSHA permissible exposure limits for polyurethane application add contractor equipment costs and slow job-site adoption.
Strategic Opportunities
- Predictive maintenance subscriptions:Application-specific re-coating schedule services create recurring revenue capture across project lifecycles beyond initial product sale.
- Extended producer responsibility frameworks:Emerging state-level mandates in California and New York could reshape material selection criteria and supplier qualification pathways.
- Silane-epoxy hybrid convergence:Deep-penetration silane substrates with epoxy topcoat film-build combine vapor transmission control with chemical spill resistance for industrial niches.
Industry Challenges
- Certification timeline compression:ASTM C309 and AASHTO qualification testing for federally funded infrastructure creates specification gatekeeping delays for new product introductions.
- Specialized applicator scarcity:Silane spray equipment calibration and film-thickness control require trained contractors, constraining deployment velocity in remote markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Concrete Sealer Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Polyurethane, Silane, Siloxane, Polyester Application: Commercial Buildings, Industrial Facilities, Parking Lots, Driveways, Sidewalks, Recreational Areas End User: Government Agencies, Property Managers, Construction Firms, Facility Owners, Contractors, Architects Distribution Channel: Specialty Stores, Online Retailers, Direct Sales, Distributors, Home Improvement Centers |
| Companies Covered | PPG Industries Inc., RPM International Inc., BASF SE, Mapei S.p.A., Evonik Industries AG, Sherwin-Williams Company, Prosoco Inc., Arkema, Sika AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Concrete Sealer Market Strategic Shifts & Innovations
Formulation chemistry and application methodology are converging to reduce solvent dependence while extending service intervals for high-traffic concrete assets.
Penetrating lithium-silicate densifiers paired with silane topcoats is automating the specification process for parking structure maintenance programs. Facility managers in multi-level garages across the United States are adopting these systems to eliminate topical film delamination callbacks. The technology is automating contractor selection criteria toward single-source warranty providers rather than commodity product bidding.
California Air Resources Board scoping plans for architectural coatings are tightening VOC limits beyond federal baselines, compelling manufacturers to reformulate with exempt solvents and waterborne oligomers. Industrial formulators are consolidating SKUs to maintain compliance across state-specific regulatory patchworks. High-solids silane concentrates now dominate specification in CARB-regulated jurisdictions.
Asset-owner procurement teams are unbundling material supply from application labor, creating direct specification relationships with formulators that bypass traditional distributor channels. Commercial property management firms in Texas and Arizona are negotiating multi-site master service agreements with sealer manufacturers. This disintermediation concentrates volume with vertically integrated suppliers capable of warranty-backed installation networks.
North America Concrete Sealer Market Segmentation
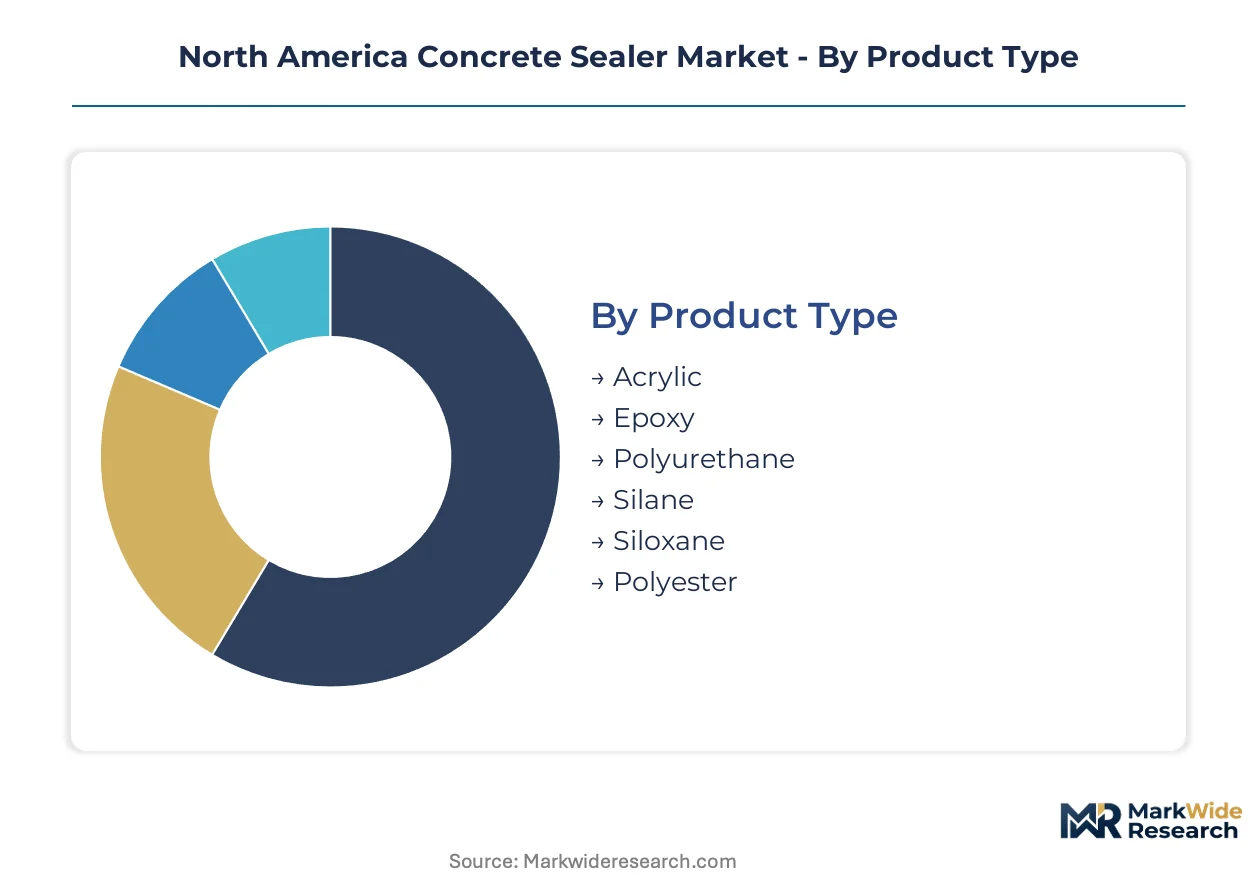
Concrete sealer procurement channels fragment across specification-driven infrastructure projects and commodity residential applications. ASTM C309 and AASHTO compliance requirements create divergent qualification burdens across product categories. Understanding these segmentation boundaries reveals where margin pools concentrate versus where price competition dominates.
Product Type:
ASTM C309 governs acrylic and silane formulations for federally funded infrastructure, while epoxy and polyurethane systems fall under industrial chemical resistance standards without unified federal certification. Siloxane and polyester segments operate with lighter regulatory burdens in residential and light commercial channels.
- Acrylic:Waterborne emulsion systems at 10-40% solids dominate driveway and sidewalk volume. Texas and California warehouse construction drives specification intensity for low-VOC compliant formulations under EPA 40 CFR Part 59.
- Silane:Deep-penetrating oligomer chemistry commands premium positioning in bridge decks and parking structures. Municipal infrastructure budgets across the United States concentrate procurement for chloride-exposed concrete protection where alkali resistance defines performance tiers.
- Epoxy:High film-build systems serve industrial chemical spill containment with specialized OSHA isocyanate exposure protocols.
- Polyurethane:Flexible aliphatic topcoats protect high-traffic horizontal surfaces in logistics facilities.
- Siloxane:Surface-reactive chemistry bridges penetration and film-forming characteristics for coastal salt-exposure applications.
- Polyester:UV-stable formulations serve recreational area installations with aesthetic finish requirements.
Acrylic sits at the top of the volume ranking, with silane climbing the fastest.
Application:
Commercial and industrial segments demand multi-decade service life warranties with predictive maintenance subscriptions. Residential applications prioritize initial cost accessibility over lifecycle value capture.
- Commercial Buildings:Property management firms negotiate multi-site master service agreements directly with formulators. Asset-owner procurement teams bypass traditional distributor channels for warranty-backed installation networks.
- Parking Lots:Lithium-silicate densifier paired with silane topcoat systems automate specification for multi-level garage maintenance programs. Facility managers adopt these to eliminate topical film delamination callbacks.
- Industrial Facilities:Chemical resistance specifications drive epoxy film-build requirements with specialized applicator certification.
- Driveways:Contractor selection centers on ease of application and cost accessibility in residential channels.
- Sidewalks:Municipal procurement emphasizes low-VOC compliance for public space applications.
- Recreational Areas:Aesthetic finish and UV stability shape product selection for parks and sports facilities.
Commercial buildings anchor revenue concentration, with parking lots expanding most quickly through predictive maintenance adoption.
End User:
Government agencies impose AASHTO qualification gatekeeping that filters supplier pools. Construction firms and contractors prioritize application speed and equipment compatibility over formulation sophistication.
- Government Agencies:Federal and state transportation departments mandate ASTM C309 compliance for bridge deck and highway barrier projects. Procurement cycles align with infrastructure rehabilitation budgets.
- Property Managers:Commercial real estate firms unbundle material supply from application labor. Texas and Arizona multi-site portfolios drive direct specification relationships with manufacturers.
- Construction Firms:Volume procurement for new commercial warehouse foundations concentrates in the Texas-California corridor.
- Facility Owners:Industrial asset portfolios prioritize chemical spill protection with extended service intervals.
- Contractors:Equipment calibration requirements for silane spray systems constrain deployment velocity in remote markets.
- Architects:Specification authority in high-performance commercial installations shapes product selection criteria.
Government agencies maintain the most rigid qualification requirements, while property managers are gaining specification influence fastest.
Distribution Channel:
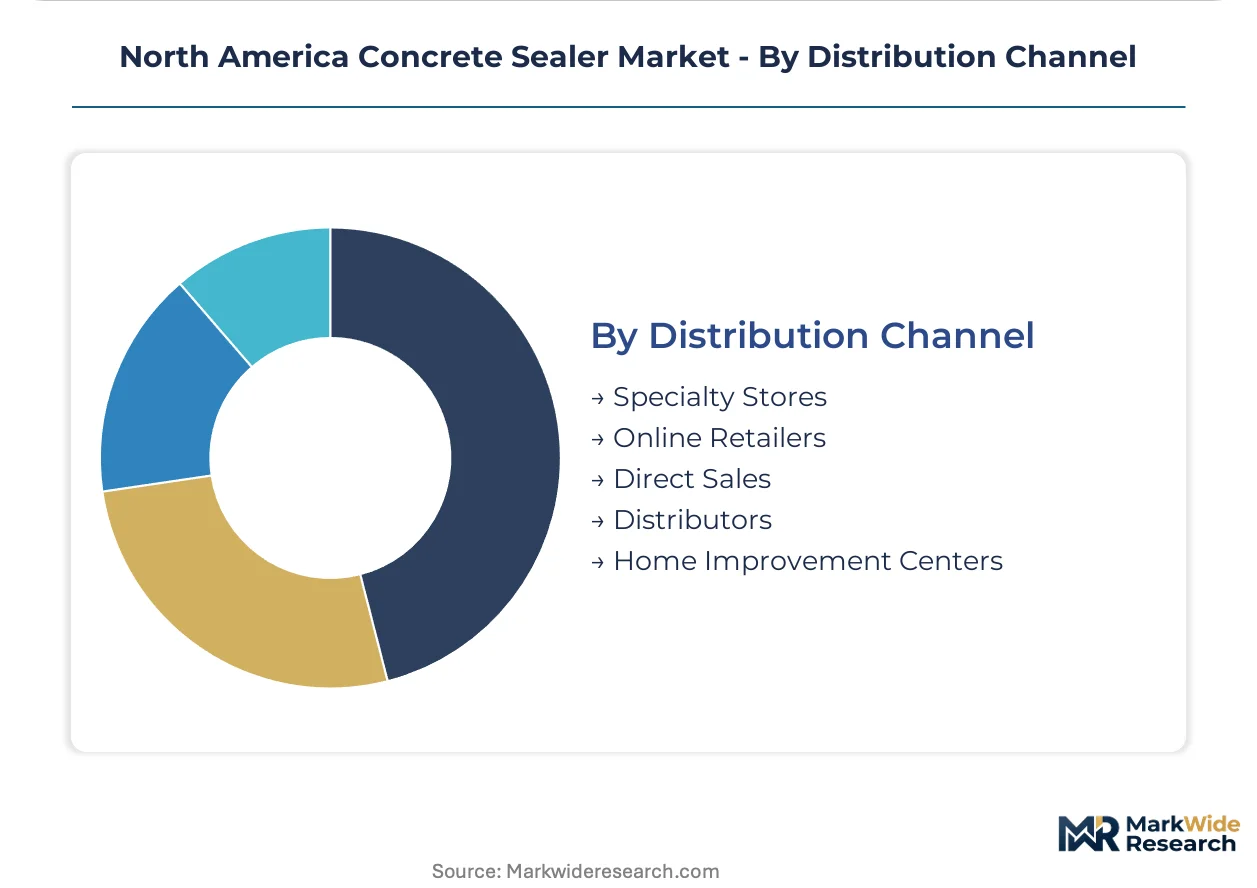
Specialty stores and direct sales channels capture premium specification value. Home improvement centers and online retailers compete on price accessibility for residential volume.
- Specialty Stores:Technical consultation and application training support contractor loyalty in silane and epoxy segments. These outlets capture margin from specification complexity.
- Direct Sales:Manufacturers negotiate master service agreements with commercial property management firms. This disintermediation concentrates volume with vertically integrated suppliers.
- Distributors:PPG Industries leverages coatings distribution networks to control specification channels for high-performance commercial installations.
- Home Improvement Centers:Acrylic waterborne systems for residential driveways and sidewalks dominate shelf space.
- Online Retailers:Product reviews and price transparency shape contractor selection for commodity applications.
Direct sales channels are expanding share fastest as asset owners unbundle procurement, though specialty stores retain the highest margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States outpaces Canada and Mexico in sealer consumption intensity, though infrastructure investment trajectories diverge across all three markets. Federal procurement standards and state-level environmental mandates create distinct specification environments. Cross-border supply chains concentrate resin manufacturing in the US Midwest while application services localize near coastal corrosion zones.
United States
Municipal bridge deck rehabilitation drives silane procurement across the Interstate highway system. EPA 40 CFR Part 59 VOC restrictions compel waterborne acrylic reformulation in architectural coatings. The Texas-California warehouse construction corridor concentrates specification intensity for penetrating sealers in logistics foundations.
Canada
Provincial infrastructure budgets prioritize freeze-thaw resistant formulations for parking structures and highway barriers. Health Canada and PMRA regulate chemical imports under the Canadian Environmental Protection Act. Ontario's Golden Horseshoe anchors commercial sealer demand from Toronto-Waterloo industrial development.
Mexico
Manufacturing facility construction in Nuevo León and Baja California generates specification demand for industrial-grade epoxy systems. SEMARNAT environmental standards govern solvent-borne formulation limits in border-adjacent states. Mexico City Metro infrastructure maintenance creates municipal procurement volume for concrete protection.
North America Concrete Sealer Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with specification-driven infrastructure channels favoring established formulators while residential applications tolerate private-label supply. The vendor base organizes into three tiers: integrated resin producers with captive raw material positions, regional formulators serving contractor networks, and specialty applicators bundling material with installation labor. Strategic moves concentrate on backward integration into acrylic intermediate production and direct contracting relationships with commercial property managers that disintermediate traditional distribution.
Among integrated coatings conglomerates, PPG Industries Inc., Sherwin-Williams Company, and RPM International Inc. exemplify archetypes of specification channel control through distribution network ownership, in-house resin manufacturing, and penetrating technology specialization respectively. These anchors occupy positions where vertical scope determines competitive viability rather than formulation alone.
| Leading Market Players |
|---|
| PPG Industries Inc. |
| RPM International Inc. |
| BASF SE |
| Mapei S.p.A. |
| Evonik Industries AG |
| Sherwin-Williams Company |
| Prosoco Inc. |
| Arkema |
| Sika AG |
| Others |
Cost & Logistics Intelligence
Petrochemical feedstock volatility in acrylic resin and polyurethane prepolymer markets transmits directly through formulation costs to contractor price sensitivity in residential driveway applications, while silane oligomer supply concentration buffers premium-tier pricing for infrastructure-grade specifications.
Pricing Analysis
Capacity additions in waterborne acrylic emulsion manufacturing across Texas and California are reshaping price floors for residential volume segments. Three-tier pricing structure across premium silane, standard acrylic, and economy waterborne levels separates ASTM C309-certified infrastructure formulations from commodity architectural coatings. Price differentiation hinges on VOC compliance grade under EPA 40 CFR Part 59 and volume scale in master service agreements. Pricing pressure stems from crude oil derivative volatility compressing margin stability for formulators. Residential contractors exhibit highest price sensitivity, while municipal transportation departments prioritize lifecycle performance over unit cost.
Supply Chain Analysis
ASTM C309 and AASHTO qualification testing creates specification gatekeeping that filters supplier pools for federally funded infrastructure projects. Acrylic resin production concentrates in the US Midwest, with silane oligomer manufacturing anchored in Germany and specialty chemical corridors along the US Gulf Coast. Raw material sourcing draws from crude oil derivatives, methyl methacrylate monomers, and organosilane precursors. Supply chain risk centers on single-source vulnerability for high-purity silane intermediates used in bridge deck applications. Distribution runs through PPG Industries' coatings networks for commercial specification control, with direct sales channels expanding share among property management firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through predictive maintenance subscription bundling that captures recurring revenue beyond initial product sale, while low-VOC formulation mandates shift specification share toward compliant premium tiers.
For Market Incumbents: Hedge against waterborne acrylic margin compression by deepening captive supply of silane intermediates and lithium-silicate densifiers. Secure AASHTO qualification pipelines for hybrid silane-epoxy systems ahead of infrastructure rehabilitation cycles. Control specification channels through warranty-backed installation networks that disintermediate distributor markups in commercial property management procurement.
For New Entrants and Emerging Players: Remote municipal contractors lacking silane spray equipment calibration expertise represent an underserved buyer archetype ripe for equipment-leasing and training-bundle propositions. Target freeze-thaw climate zones where incumbent waterborne acrylic films underperform, offering penetrating siloxane alternatives with simplified application protocols. Pursue direct master service agreements with Arizona and Texas commercial property firms unbundling material from labor procurement.
For Investors and Strategic Acquirers: Consolidation pressure builds where regional formulators lack backward integration into resin manufacturing and ASTM C309 certification infrastructure. Long-term viability favors vertically integrated suppliers with captive acrylic intermediate production and direct contracting relationships with asset owners. Watch California Air Resources Board scoping plan implementations as inflection indicators for exempt-solvent formulation demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Resin Production | Captive supply of methyl methacrylate intermediates insulates margin from petrochemical volatility. |
| Predictive Maintenance Subscription Launch | Recurring revenue capture across parking structure lifecycles transforms transactional product sales. |
| ASTM C309 Certification Pipeline Expansion | Federal infrastructure qualification gatekeeping filters competitor pools for bridge deck procurement. |
| Direct Master Service Agreement Negotiation | Texas and Arizona property management disintermediation concentrates volume with integrated suppliers. |
| Silane-Epoxy Hybrid Formulation Development | Industrial chemical resistance specifications merge with vapor transmission control for niche penetration. |
Research Approach
Direct dialogue with sealer formulators, municipal procurement officers, commercial property managers, and specialty applicators grounded qualitative assessment, cross-referenced with EPA 40 CFR Part 59 regulatory filings, ASTM C309 certification databases, AASHTO specification records, and SEC 10-K disclosures from coatings conglomerates. Bottom-up demand modeling across application segments triangulated with top-down supply-side capacity assessment.
Segment-level value projections across the analysis window incorporated product type, application end-use, and distribution channel dimensions with regional regulatory cluster overlays. CAGRs derived from historical consumption pattern analysis and infrastructure budget trajectory correlation. Forecast inputs included municipal rehabilitation cycle timing, VOC compliance phase-in schedules, and petrochemical feedstock price elasticity assumptions.
Underlying measurement precision varies by segment; ASTM C309-qualified infrastructure specifications carry tighter precision than residential commodity channels where contractor switching costs remain minimal. Forecasts reflect documented assumptions on regulatory enforcement intensity and infrastructure appropriation continuity. A model refresh is warranted upon material change in EPA VOC mandate implementation timelines or federal highway rehabilitation funding authorization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
US Prefabricated Steel Market
Building & Construction Materials
Germany Foam Insulation Market
Building & Construction Materials
North America Laminated Veneer Lumber Market
Building & Construction Materials
GCC Faucet Market
Building & Construction Materials
Manufactured Sand Market
Building & Construction Materials
Glass Tiles Market
Building & Construction Materials
US Steel Rebar Market
Building & Construction Materials
Curtain Wall Market
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
South America Ready Mix Concrete Market
Building & Construction Materials
Soil Stabilization Market
Building & Construction Materials
Noise Insulation Jackets Market
Building & Construction Materials
Clay Roof Tiles Market
Building & Construction Materials
Cement Grinding Aids Market
Building & Construction Materials
Pre-Insulated Pipes Market
Building & Construction Materials
Roof Coating Market