
 Glass Tiles Market | 2026-2036
Glass Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Tiles Market Intelligence
Specialty store networks and direct-to-contractor channels is reconfiguring how glass tile manufacturers reach specification-grade buyers. Mohawk Industries leverages its broad flooring distribution infrastructure to push bundled surfacing solutions that include glass mosaic lines. Saint-Gobain anchors European supply through its integrated flat glass-to-tile manufacturing chain, controlling raw material quality from float glass forward. RAK Ceramics competes across Middle Eastern and South Asian project markets with production scale that sustains cost positioning in bulk hospitality contracts.
Glass tiles are thin, vitreous surfacing units formed from silica sand, soda ash, and limestone, typically fired at temperatures exceeding 700°C to achieve translucency and chemical resistance; they serve primarily as decorative and protective cladding for interior walls, wet-area floors, and aquatic environments. Mosaic formats retain dominance in backsplash and accent applications where intricate patterning commands premium specification, while large-format porcelain-glass hybrids are capturing share in commercial flooring for their improved breakage resistance and reduced grout maintenance. The hospitality end-user segment generates concentrated margin pools as designers specify custom color lots and iridescent finishes for luxury property differentiation.
US-based projects face compliance thresholds set by EPA emissions guidelines for glass manufacturing facilities and OSHA silica exposure limits during tile cutting and installation, both of which elevate production and field-handling costs. European suppliers must navigate REACH chemical registration requirements for specialty glazes and pigments, plus CE marking conformity for structural adhesion in wet environments. Stakeholders must monitor how evolving green building certification schemes and embodied-carbon disclosure mandates reshape material selection criteria across residential and commercial specification channels.
Market Dynamics
Hospitality renovation cycles are compressing specification timelines for decorative glass surfacing, forcing manufacturers to compress color-matching lead times while maintaining translucency tolerances across large-format installations.
Growth Catalysts
- California Title 24 energy codes:Tighter thermal performance thresholds for interior finishes are disqualifying conventional ceramic alternatives in commercial retrofits across the US state.
- LEED v4.1 certification pathways:Material ingredient reporting credits are pulling specification toward glass tiles with verified recycled content in North American commercial construction.
- UAE mega-project pipeline:Dubai and Abu Dhabi developments are specifying large-format glass systems for aquatic and leisure infrastructure at volumes unmatched elsewhere.
Market Restraints
- Soda ash price volatility:Energy-intensive production of this core raw material concentrates cost exposure with Turkish and US domestic suppliers.
- Silica exposure compliance:OSHA's respirable crystalline silica limits during tile cutting elevate field-handling costs and contractor insurance premiums.
- Porcelain-glass hybrid substitution:Improved breakage resistance in these composites is capturing share in commercial flooring where grout maintenance reduction matters.
Strategic Opportunities
- Embodied-carbon disclosure mandates:France's RE2020 environmental regulation and similar EU frameworks are creating specification preference for low-carbon cladding materials.
- Direct-to-contractor digital channels:Project visualization tools are shortening specification cycles by connecting manufacturers with hospitality design firms.
- Biophilic wellness applications:Healthcare and senior living verticals are specifying iridescent glass accents for circadian lighting modulation.
Industry Challenges
- Specialized installer scarcity:Large-format glass tile application demands wet-saw precision and substrate preparation skills that outpace trade training pipelines.
- REACH glaze registration timelines:ECHA chemical compliance for specialty pigments stretches new product development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Tiles Market |
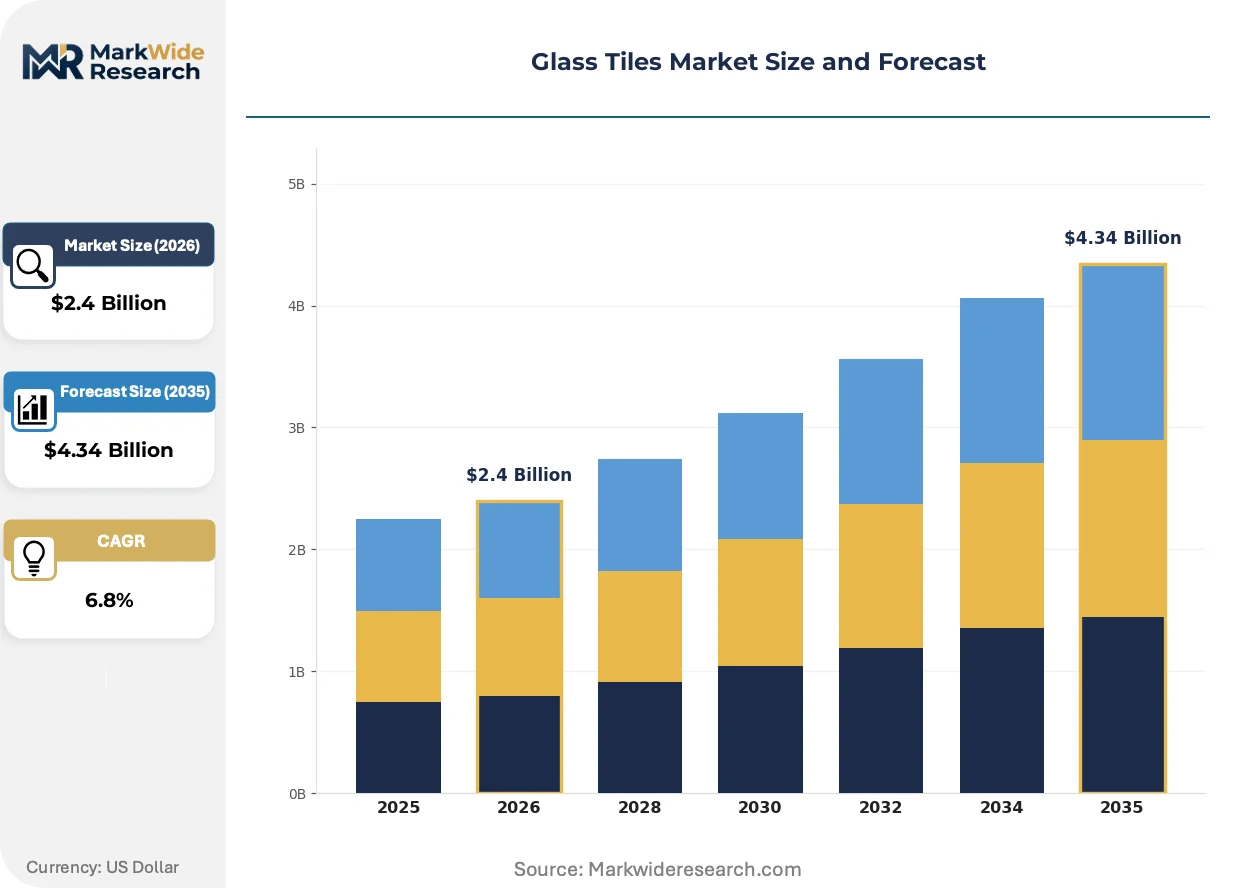
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic, Porcelain, Mosaic, Decorative Application: Wall Coverings, Flooring, Backsplashes, Pool Linings Distribution Channel: Online Retail, Wholesalers, Specialty Stores, Direct Sales End User: Residential, Commercial, Hospitality, Industrial |
| Companies Covered | Daltile, Emser Tile, Mohawk Industries, RAK Ceramics, Florim Group, Saint-Gobain, Porcelanosa Grupo, Interceramic, Arizona Tile, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Tiles Market Strategic Shifts & Innovations
Digital inkjet decoration and thin-film coating technologies are collapsing the cost gap between custom color lots and standard production runs, enabling mass customization at hospitality scale.
Recycled post-consumer glass feedstock is hybridizing with engineered frit systems to produce color-stable tiles with 40-70% cullet content. Luxury hotel chains are specifying these formulations for brand-aligned sustainability narratives. The resulting material is compressing price premiums against virgin-glass alternatives while maintaining chemical resistance thresholds.
REACH chemical registration requirements for specialty glazes are forcing reformulation of legacy pigment systems across European supply chains. Manufacturers are consolidating SKU portfolios to reduce compliance surface area. Wet-environment commercial segments are absorbing the transition costs most acutely, with project specifications increasingly requiring CE-marked adhesion conformity.
Specification-grade buyers are consolidating vendor relationships around bundled surfacing solutions that combine glass mosaics with porcelain field tile. Distributors are responding by credentialing preferred installer networks to capture project margin pools. This concentration is most visible in North American hospitality renovation channels, where single-source accountability reduces coordination friction.
Glass Tiles Market Segmentation
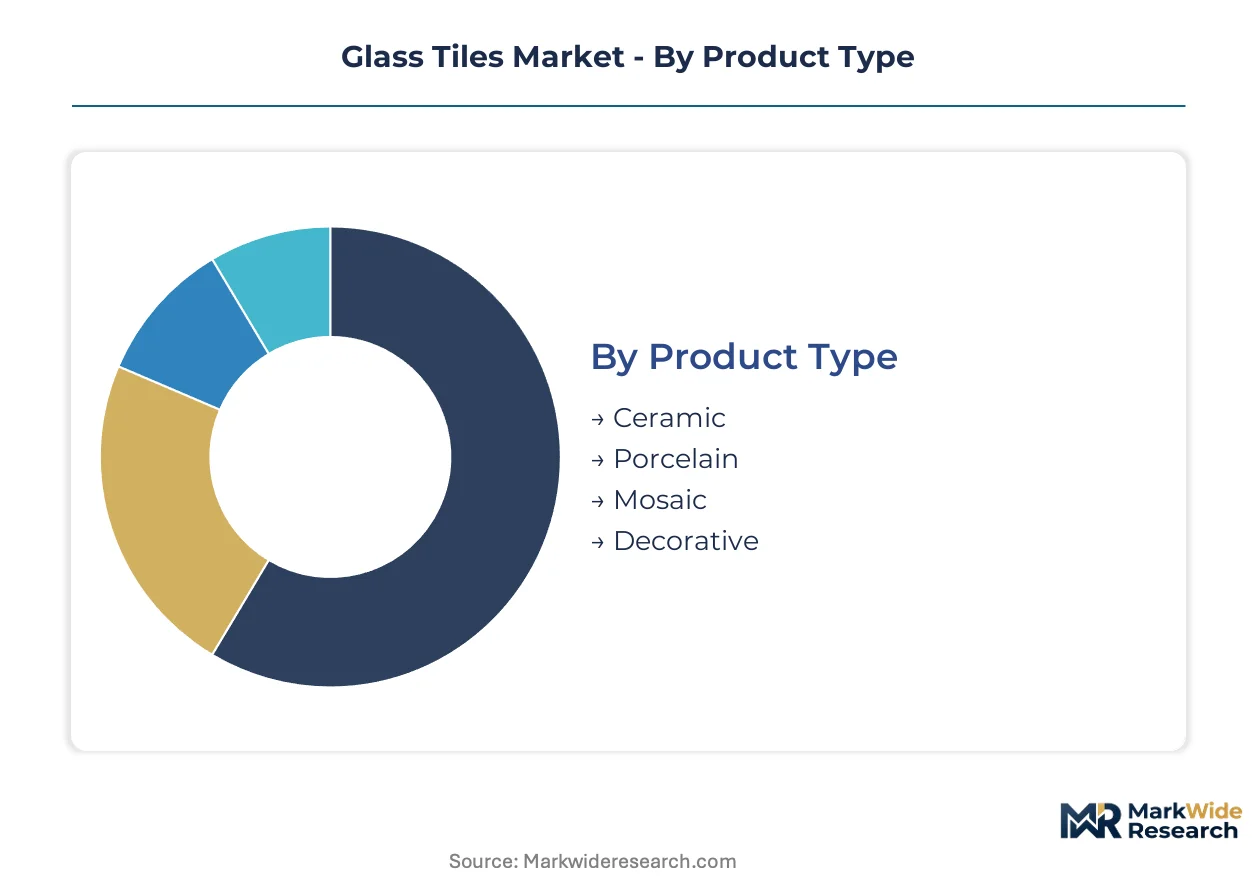
Glass tile procurement cycles vary dramatically across specification tiers, with hospitality renovation projects compressing lead times to under eight weeks while residential retrofits extend to six months. Understanding these velocity differentials enables manufacturers to calibrate inventory positioning and color-matching capabilities against margin profiles.
Product Type:
Renovation cycles compress fastest for small-format decorative lines, where hospitality designers rotate palettes seasonally, while large-format porcelain-glass hybrids move through specification pipelines lasting eighteen to twenty-four months.
- Mosaic:Small-format vitreous units, typically 20mm to 50mm, enable intricate patterning through mesh-mounted sheets. Hospitality designers in Dubai and Abu Dhabi specify iridescent mosaic systems for luxury aquatic environments, compressing color-matching lead times to meet compressed renovation windows.
- Decorative:Custom color lots and specialty finishes command premium positioning through digital inkjet decoration. California Title 24 compliance thresholds pull specification toward decorative glass with verified recycled content in commercial retrofits.
- Ceramic:Traditional clay-based formulations with glass glaze overlays serve cost-sensitive residential backsplash applications.
- Porcelain:Dense, low-absorption units offer improved breakage resistance for high-traffic commercial flooring.
Mosaic anchors the volume base while decorative gains share at the steepest rate.
Application:
Cost tiers stratify sharply across installation environments, with wet-area specifications demanding CE-marked adhesion conformity and dry-wall applications absorbing standard-grade alternatives.
- Pool Linings:Chemical-resistant vitreous surfacing for aquatic environments requires specialized frit systems to withstand chlorine exposure and thermal cycling. UAE mega-projects in Dubai specify large-format glass systems for leisure infrastructure at volumes unmatched elsewhere.
- Backsplashes:Mesh-mounted mosaic sheets dominate residential and commercial kitchen specifications where grout maintenance reduction drives material selection.
- Wall Coverings:Large-format panels serve commercial lobbies and hospitality corridors requiring rapid installation.
- Flooring:Porcelain-glass hybrids capture share in commercial settings where breakage resistance outweighs pure translucency.
Backsplashes concentrate procurement volume while pool linings expand most quickly.
Distribution Channel:
Customer proximity to specification-grade buyers determines channel viability, with direct-to-contractor digital platforms collapsing traditional distributor markups for hospitality-scale projects.
- Specialty Stores:Curated showroom environments enable tactile material evaluation and color-matching services. Mohawk Industries leverages broad flooring distribution infrastructure to push bundled surfacing solutions through this channel.
- Direct Sales:Manufacturer-to-contractor relationships capture project margin pools in North American hospitality renovation cycles.
- Online Retail:Project visualization tools shorten specification cycles for residential and light commercial buyers.
- Wholesalers:Volume aggregation serves mid-market contractors with standardized product lines and reduced technical support.
Specialty stores anchor the volume base while direct sales climbs the fastest.
End User:
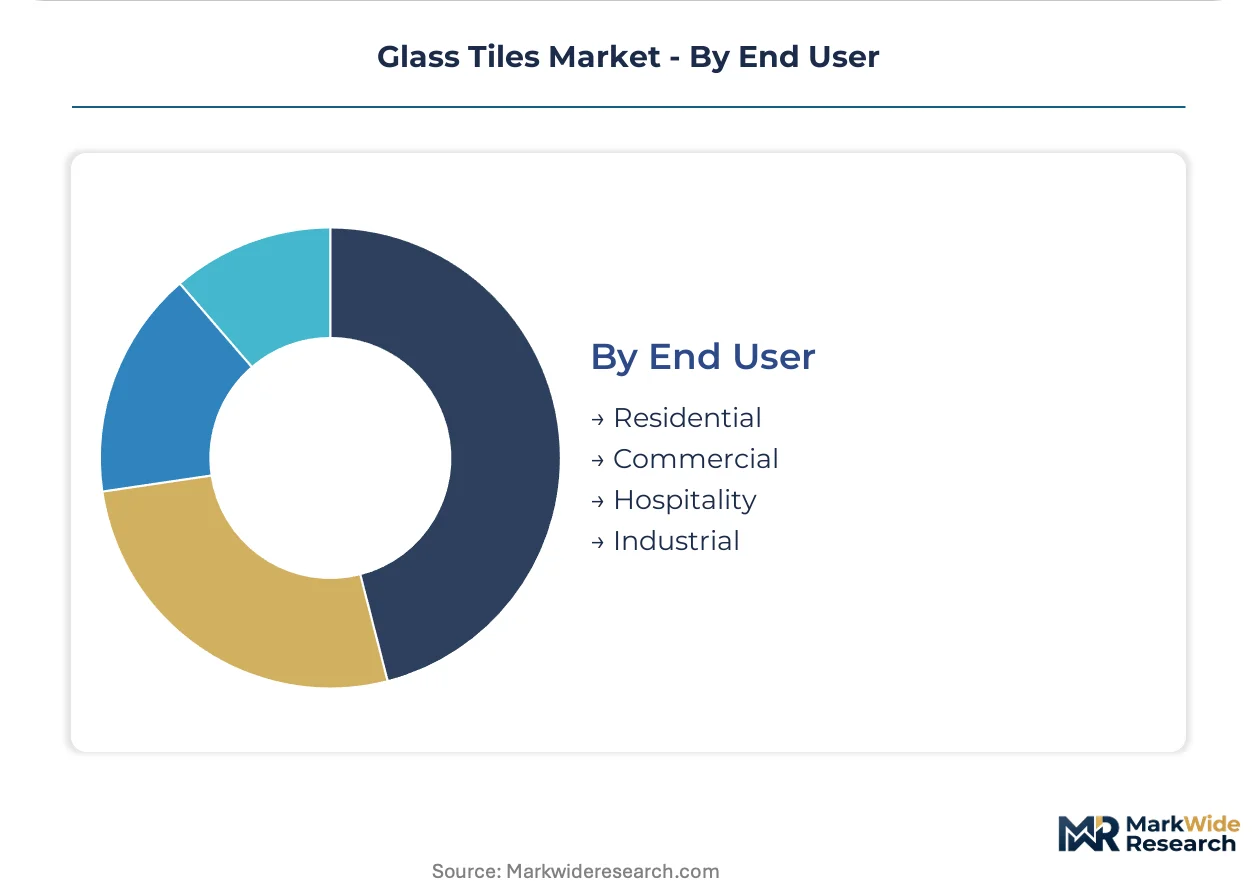
Margin structures diverge across customer types, with hospitality chains absorbing premium pricing for custom color lots while residential buyers prioritize standard-grade availability.
- Hospitality:Luxury hotel and resort renovation cycles generate concentrated margin pools through specification of iridescent finishes and brand-aligned sustainability narratives. RAK Ceramics competes across Middle Eastern project markets with production scale sustaining cost positioning in bulk contracts.
- Commercial:Office and retail fit-outs prioritize rapid installation and reduced grout maintenance.
- Residential:Kitchen and bathroom retrofits drive volume through backsplash and accent wall specifications.
- Industrial:Chemical-resistant cladding for food processing and pharmaceutical facilities demands specialized performance certification.
Residential anchors the volume base while hospitality gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Jebel Ali's container throughput capacity underwrites the UAE's dominance in glass tile distribution for Middle Eastern mega-projects. Mediterranean shipping lanes connecting Italian manufacturers to North African hospitality developments further shape procurement geography.
United States
California Title 24 energy codes and LEED v4.1 certification pathways pull specification toward recycled-content glass tiles in commercial retrofits. EPA emissions guidelines for glass manufacturing facilities elevate production costs for domestic suppliers. The Los Angeles-Long Beach port complex handles inbound specialty tile volumes for West Coast hospitality renovation cycles.
United Arab Emirates
Dubai and Abu Dhabi mega-projects specify large-format glass systems for aquatic and leisure infrastructure at volumes unmatched elsewhere. MOHAP building material standards enforce chemical resistance thresholds for wet-environment installations. The Jebel Ali industrial corridor concentrates warehousing and finishing operations for Gulf Cooperation Council distribution.
Germany
REACH chemical registration requirements for specialty glazes stretch new product development cycles across European supply chains. CE marking conformity for structural adhesion in wet environments filters specification toward certified suppliers. The Rhine-Ruhr industrial region anchors flat glass-to-tile manufacturing integration for continental export.
China
Dual carbon goals and GB standards for building materials are tightening embodied-carbon thresholds for interior finishes in commercial construction. MIIT industrial policy incentivizes recycled cullet integration in vitreous surfacing production. The Yangtze River Delta manufacturing belt concentrates digital inkjet decoration capacity for export-grade decorative tile.
India
BIS certification requirements for ceramic and glass tiles are harmonizing with LEED India pathways to pull specification toward verified sustainable materials. PLI scheme incentives for advanced manufacturing support technology upgrades in vitreous surfacing. The Morbi-Gujarat ceramic cluster is extending into glass mosaic finishing for hospitality export contracts.
Glass Tiles Market Key Industry Players
On the supply side, the industry is structured around three tiers: integrated flat glass producers with captive tile operations, specialized mosaic manufacturers with design-studio relationships, and regional fabricators serving contractor wholesale channels. Strategic archetypes include scale-driven bulk suppliers, premium-brand design houses, and installation-service integrators. Dominant competitive moves encompass backward integration into raw glass production and digital platform development for direct contractor engagement.
Among North American flooring conglomerates, Mohawk Industries exemplifies the scale-driven archetype through broad distribution infrastructure. Saint-Gobain occupies a position representing European integrated manufacturing from float glass forward. RAK Ceramics anchors the Middle Eastern project-market tier with production scale sustaining bulk hospitality contracts.
| Leading Market Players |
|---|
| Daltile |
| Emser Tile |
| Mohawk Industries |
| RAK Ceramics |
| Florim Group |
| Saint-Gobain |
| Porcelanosa Grupo |
| Interceramic |
| Arizona Tile |
| Others |
Cost & Logistics Intelligence
Turkish and US domestic soda ash suppliers concentrate upstream cost exposure for glass tile manufacturers, compressing margin pools downstream toward hospitality chains with bulk contract leverage. Pricing power fragments across specification tiers as raw material volatility feeds through to project-based quotations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with premium tiers capturing iridescent finishes and custom color lots for luxury hospitality while standard grades serve commercial retrofits. Price differentiation hinges on recycled-content certification tiers and volume scale, with California Title 24 compliance thresholds adding certification premiums. Cost compression in standard-grade mosaics is intensifying because porcelain-glass hybrid substitution erodes pure-glass positioning. Residential retrofit buyers exhibit highest price sensitivity, whereas hospitality chains absorb premium positioning for brand-aligned sustainability narratives.
Supply Chain Analysis
Export-control regimes on specialized digital inkjet decoration equipment constrain technology transfer to emerging manufacturing clusters, limiting production capacity expansion outside established bases. Supply concentrates in China, Italy, and the United Arab Emirates, with the Yangtze River Delta and Morbi-Gujarat clusters feeding global decorative tile flows. Raw material dependencies center on silica sand, soda ash, and engineered frit systems for color stability. Single-source vulnerability in specialty glaze pigments stretches lead times under REACH registration timelines. Distribution runs through specialty store networks and direct-to-contractor digital platforms for specification-grade buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified installer scarcity for large-format glass tile application creates a persistent capability gap that constrains market expansion and concentrates project execution risk with credentialed contractor networks.
For Market Incumbents: Insulate margin pools by credentialing preferred installer networks to capture hospitality renovation cycles, and deepen backward integration into float glass production to control translucency tolerances against soda ash price volatility. Porcelain-glass hybrid substitution threatens pure-glass share in commercial flooring; vertical integration into raw material quality control is the defensive priority. For New Entrants and Emerging Players: Establish a beachhead in healthcare and senior living biophilic wellness applications where iridescent glass accents for circadian lighting modulation face limited incumbent specialization. Direct-to-contractor digital channels with project visualization tools offer the most penetrable go-to-market angle against legacy distributor markups. For Investors and Strategic Acquirers: Capital is best deployed toward design-studio-linked mosaic manufacturers with hospitality relationships and digital decoration capabilities, as these assets compound across renovation cycle compression. Long-term viability rests on specification-grade buyer consolidation around bundled surfacing solutions. Watch for embodied-carbon disclosure mandate acceleration as the inflection signal for low-carbon cladding material preference.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Float Glass Production | Saint-Gobain's captive supply chain from raw glass forward controls quality thresholds for specification-grade buyers. |
| Digital Platform Development for Direct Contractor Engagement | Project visualization tools collapse distributor markups and compress specification timelines for hospitality design firms. |
| Recycled Cullet Feedstock Integration | Luxury hotel chains specify 40-70% post-consumer glass formulations for brand-aligned sustainability narratives. |
| CE Marking Conformity Investment | Wet-environment commercial segments increasingly require certified structural adhesion for pool lining specifications. |
| Preferred Installer Network Credentialing | Distributors capture project margin pools by addressing specialized scarcity in large-format glass tile application. |
Research Approach
A spread of perspectives from hospitality design directors, commercial contractor procurement leads, glass manufacturing plant managers, and specialty tile distributors converged on the working assumptions driving this analysis. Primary interviews combined with secondary validation from customs trade data, SEC 10-K filings of flooring conglomerates, and building code regulatory databases. Bottom-up project pipeline assessments triangulated against top-down material flow estimates across the analysis window.
Demand-supply-balance framing anchored the analytical approach, with segmentation modeled across product type, application environment, distribution channel, and end-user vertical throughout the forecast period. CAGRs derived from installation volume trajectories and specification value per square meter, incorporating hospitality renovation cycle compression and green building certification adoption curves as industry-specific inputs.
Sensitivities concentrate around soda ash price volatility, REACH registration timeline extensions for specialty pigments, and OSHA silica exposure enforcement intensity. Forecasts reflect documented assumptions on raw material cost pass-through rates and specification-grade buyer consolidation patterns. Material shifts in embodied-carbon disclosure mandate implementation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Quarry Tiles Market
Building & Construction Materials
Drainage System Market
Building & Construction Materials
Timber Construction Connectors Market
Building & Construction Materials
Travertine Tiles Market
Building & Construction Materials
Concrete Waterproofing with Crystalline Technology Market
Building & Construction Materials
North America Balustrade Market
Building & Construction Materials
North America Concrete Cellulose Fiber Reinforcement Market
Building & Construction Materials
Roofing Underlayment Market
Building & Construction Materials
Global Rainscreen Cladding Market
Building & Construction Materials
Gypsum and Drywall Market
Building & Construction Materials
Japan Cross Laminated Timber (CLT) Market
Building & Construction Materials
Decorative Concrete Market
Building & Construction Materials
Storefront Glass Market
Building & Construction Materials
Sheet Metal Market
Building & Construction Materials
Aerated Autoclaved Concrete (AAC) Market
Building & Construction Materials
Temporary Storage Buildings Market