
 Germany Foam Insulation Market | 2026-2036
Germany Foam Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Foam Insulation Market Foresight
Residential retrofit activity is restructuring demand patterns across Germany as homeowners respond to rising energy costs and stricter efficiency mandates. BASF SE leverages its integrated polyurethanes value chain to supply high-performance spray foam systems for both new construction and renovation projects. Armacell anchors the pipe insulation segment with specialized elastomeric foam solutions targeting industrial and HVAC applications. Covestro AG differentiates through advanced polyisocyanurate formulations that address fire safety and thermal bridging concerns in multi-story buildings.
Germany foam insulation encompasses rigid and semi-rigid cellular plastic materials manufactured through expansion processes using blowing agents, with densities ranging from 15 to 50 kg/m³ depending on end-use requirements. These materials trap gas within closed or open cell structures to reduce conductive and convective heat transfer in building envelopes, industrial equipment, and transportation systems. Polyurethane dominates installed volume due to its superior R-value per inch and adaptability to spray foam application, while polystyrene retains cost advantages in board-based wall and floor installations where moisture resistance matters. Phenolic foam occupies a premium niche in commercial and industrial settings demanding exceptional fire performance and low smoke emission profiles.
The German Building Energy Act (GEG), aligned with EU Energy Performance of Buildings Directive requirements, mandates minimum U-values that effectively phase out legacy insulation materials in favor of higher-performance foam systems. KBA energy efficiency labeling for construction products and DIBt (German Institute for Building Technology) certification create compliance gates that filter market access and shape R&D investment priorities. Stakeholders must monitor forthcoming revisions to F-Gas Regulation limits on hydrofluorocarbon blowing agents, as these chemical transitions will determine competitive positioning across polyurethane and polyisocyanurate supply chains.
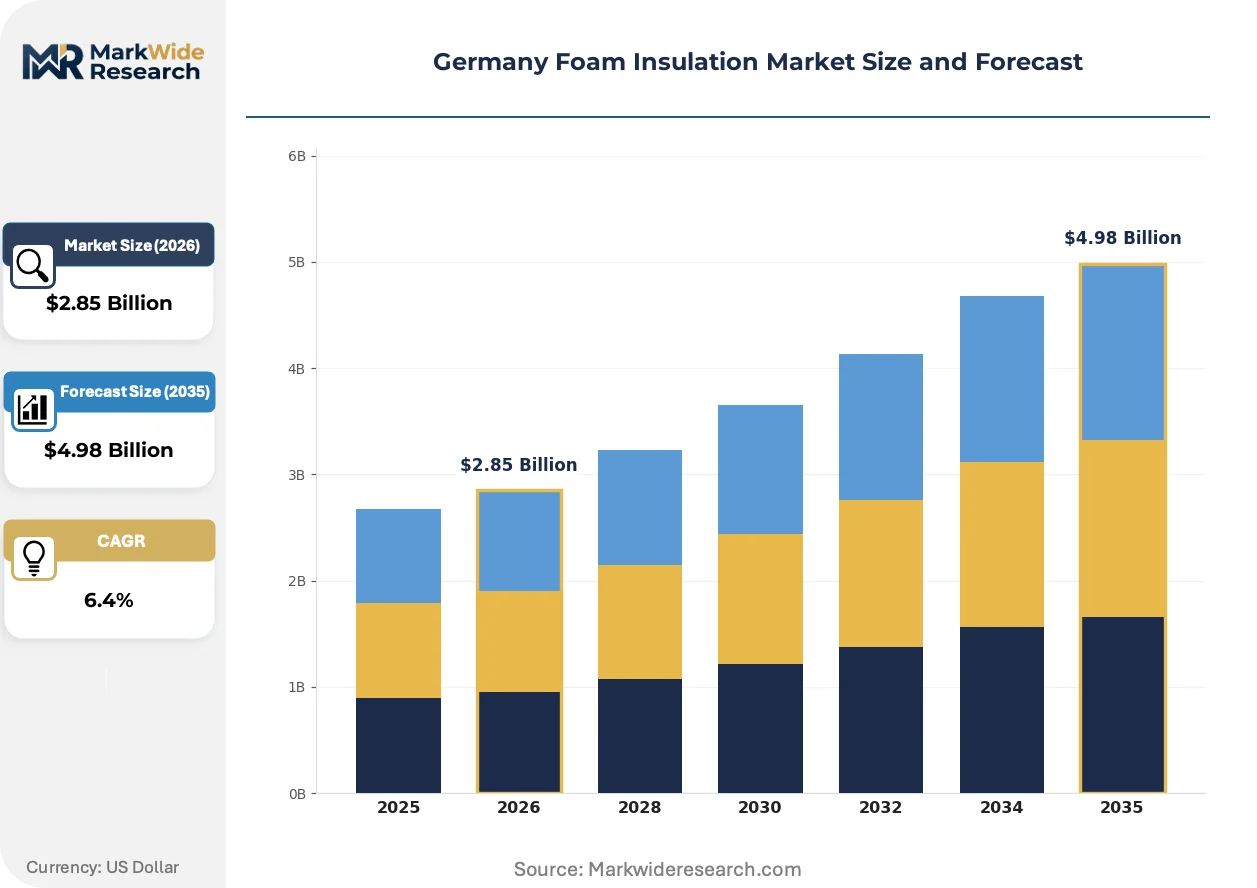
Market Dynamics
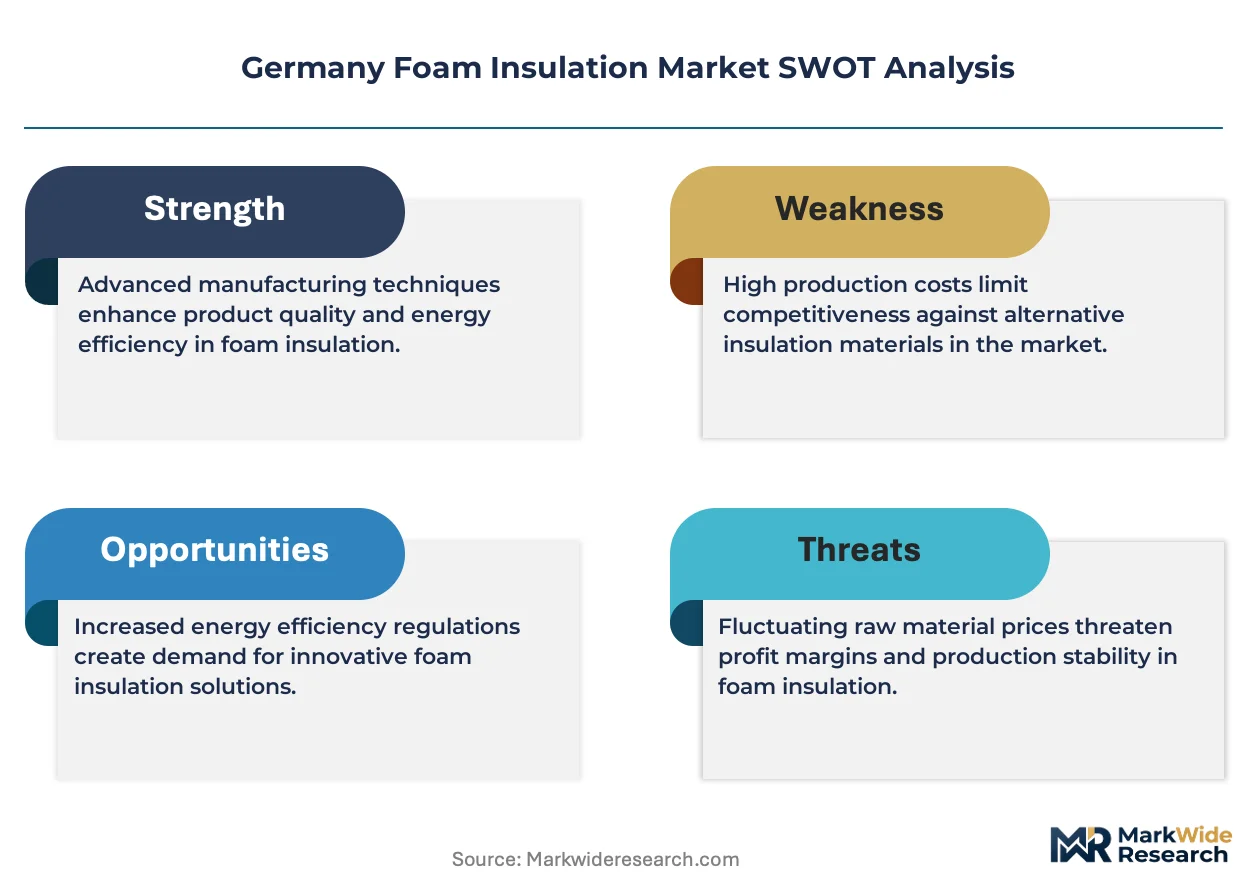
The German Building Energy Act (GEG) is compressing retrofit timelines and forcing rapid material substitution across residential and commercial envelopes. This regulatory pressure is restructuring procurement patterns, installer capacity allocation, and chemical supply chain priorities simultaneously.
Growth Catalysts
- GEG thermal performance mandates:Minimum U-value requirements are phasing out legacy insulation materials and accelerating specification of high-performance polyurethane and polyisocyanurate systems in renovation projects.
- Bavaria housing stock age:Concentrated post-war building stock in southern Germany creates overlapping envelope and HVAC retrofit demand that absorbs spray foam and board insulation volumes.
- F-Gas Regulation transition:Hydrofluorocarbon blowing agent phase-down is catalyzing R&D investment into hydro-olefin and CO₂-based alternatives that maintain thermal performance.
Market Restraints
- Polyol and isocyanate feedstock volatility:Crude oil and natural gas price swings transmit directly to polyurethane system costs, compressing installer margins and delaying project commitments.
- DIBt certification timelines:German Institute for Building Technology approval processes for new formulations extend 12-18 months, creating competitive lag for innovative products.
- Mineral wool substitution in fire-critical applications:Non-combustible stone wool retains specification preference in high-rise residential and commercial corridors despite thermal performance trade-offs.
Strategic Opportunities
- North Rhine-Westphalia industrial cluster retrofit:Dense manufacturing footprint and aging commercial building stock create concentrated demand for pipe and equipment insulation alongside envelope projects.
- Heat pump integration:Building system convergence between envelope insulation and heat pump deployment creates bundled specification opportunities for contractors.
- KBA energy efficiency labeling:Product differentiation through construction product labeling enables premium positioning for certified high-performance systems.
Industry Challenges
- Certified spray foam installer scarcity:GEG compliance requires trained applicators for complex building envelope geometries, creating capacity bottlenecks during peak retrofit seasons.
- Legacy building documentation gaps:Pre-1990s structures often lack as-built drawings, forcing costly on-site assessment and delaying accurate material quantification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Foam Insulation Market |
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Polystyrene, Polyisocyanurate, Phenolic, Carbon-Based Application: Wall Insulation, Roof Insulation, Pipe Insulation, Floor Insulation, HVAC Systems End User: Construction Contractors, Facility Managers, Industrial Plants, Commercial Complexes Installation Method: Spray Foam, Preformed Boards, Injection, Loose Fill, Laminated Panels |
| Companies Covered | Dow Chemical Company, Armacell, BASF SE, Owens Corning, Knauf Insulation, Saint-Gobain, Kingspan Group, Recticel NV/SA, Covestro AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Foam Insulation Market Shifts & Advancements
Material chemistry and application methods are converging to address fire safety, thermal bridging, and installation speed simultaneously. These developments are compressing the gap between laboratory performance and field-installed outcomes.
Bio-based polyol formulations derived from castor oil and rapeseed feedstocks are unifying sustainability credentials with mechanical performance in rigid polyurethane systems. Housing associations and municipal retrofit programs are specifying these materials at accelerating rates. This chemistry shift is unifying circular economy targets with procurement compliance, forcing petrochemical suppliers to reconfigure feedstock strategies.
EU F-Gas Regulation revision is tightening hydrofluorocarbon quotas for blowing agents through 2030. Chemical producers are reformulating polyisocyanurate and polyurethane systems around hydro-olefin and cyclopentane alternatives. Multi-story residential construction in Berlin and Hamburg faces the steepest compliance gradient, driving early adoption of next-generation formulations.
Energy service companies are bundling envelope insulation with heat pump and photovoltaic installations into single-contract building upgrades. Municipal housing corporations and commercial property managers are consolidating vendor relationships around these integrated offerings. Procurement compression is most visible in Saxony and Brandenburg, where district-level retrofit programs aggregate demand across housing portfolios.
Germany Foam Insulation Market Segmentation
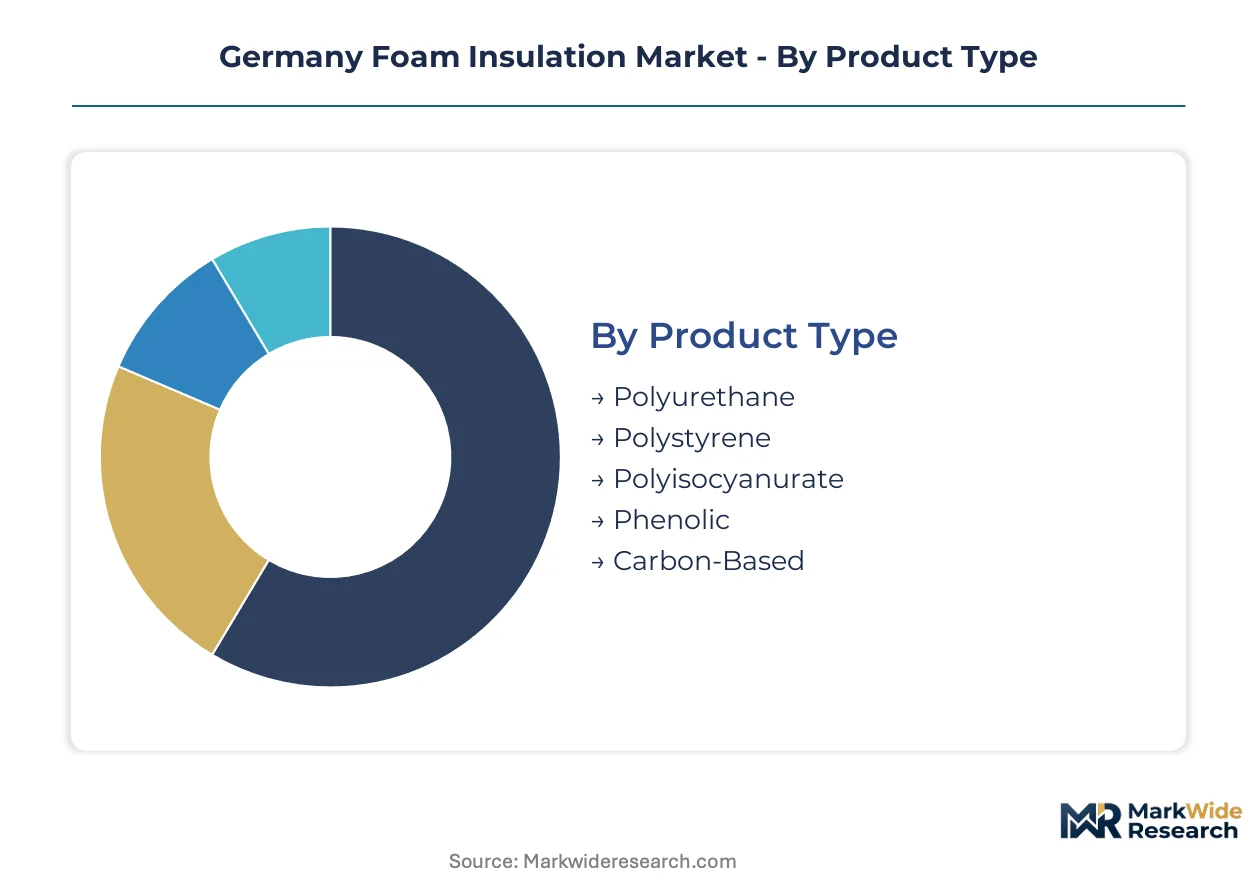
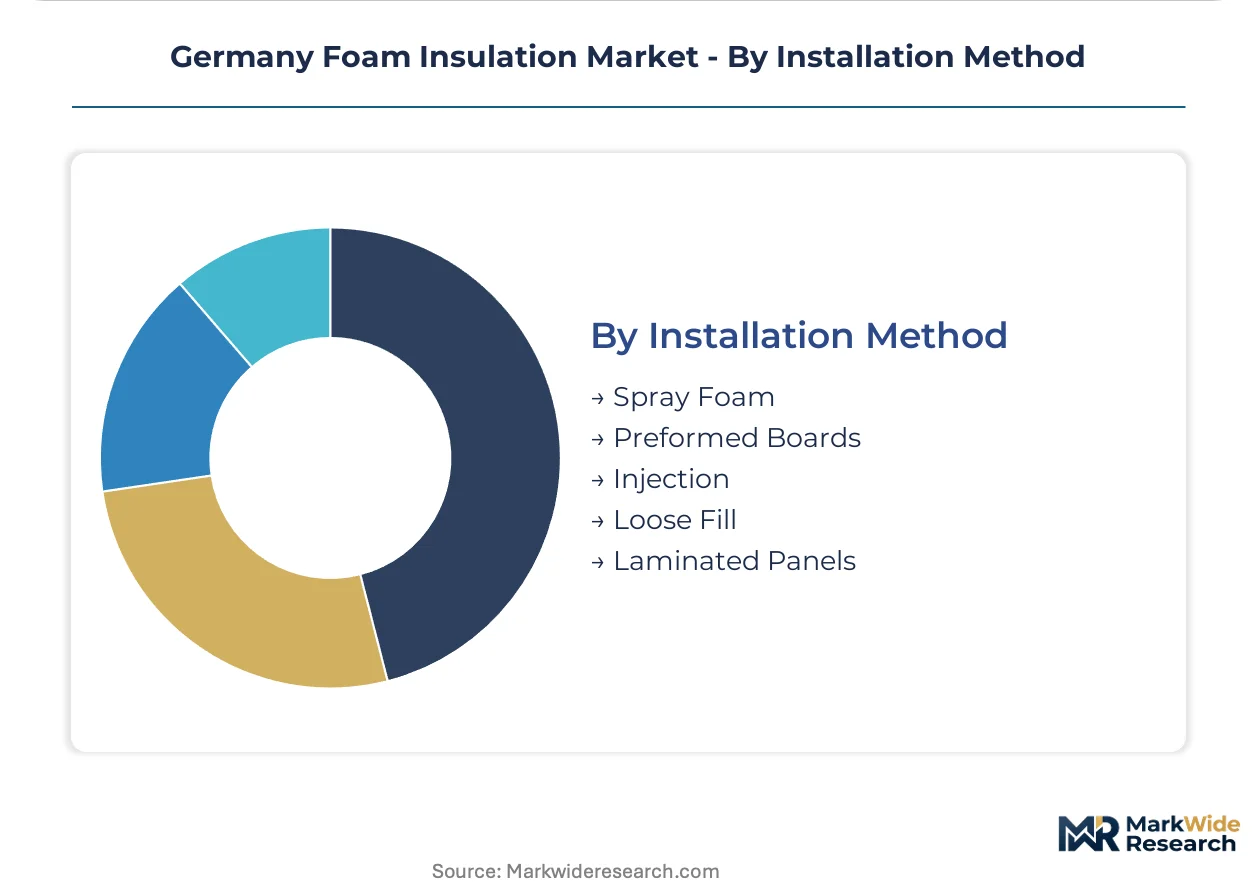
Germany's foam insulation market fragments across material chemistry, building system integration, and installation technique. Each segmentation axis carries distinct procurement patterns, certification requirements, and margin structures that shape supplier positioning.
Product Type:
Material selection spans the performance-cost spectrum from commodity polystyrene to specialized phenolic systems, with customization depth increasing toward high-R-value formulations.
- Polyurethane:Closed-cell rigid foam manufactured through reaction of polyols and isocyanates delivers the highest thermal resistance per inch among mass-market options. Demand concentrates in Bavaria residential retrofits where GEG U-value mandates favor space-efficient envelope solutions.
- Polystyrene:Expanded and extruded variants dominate below-grade and cavity wall applications where moisture resistance and cost efficiency outweigh thermal performance optimization. North Rhine-Westphalia commercial construction absorbs significant board volumes for perimeter insulation.
- Polyisocyanurate:Advanced formulations address fire safety and thermal bridging in multi-story residential construction across Berlin and Hamburg.
- Phenolic:Low-smoke emission characteristics command premium specification in commercial corridors and industrial facilities.
- Carbon-Based:Emerging graphene-enhanced systems target ultra-high-performance niche applications in passive house construction.
Leading the category by volume: Polyurethane. Expanding most quickly: Polyisocyanurate.
Application:
Building envelope position determines thermal load, moisture exposure, and accessibility constraints that filter material suitability.
- Wall Insulation:Cavity fill and external thermal insulation composite systems dominate residential retrofit activity. Post-war housing stock in southern Germany drives specification of both spray foam and rigid board configurations depending on substrate condition.
- Roof Insulation:Sloped and flat roof assemblies present distinct vapor control challenges that favor polyurethane spray applications in complex geometries. Municipal housing corporations in Saxony prioritize roof upgrades for heat pump compatibility.
- Pipe Insulation:Industrial process and district heating networks demand specialized elastomeric and rigid foam solutions.
- Floor Insulation:Basement and slab-edge applications favor moisture-resistant extruded polystyrene boards.
- HVAC Systems:Ductwork and equipment insulation requirements are tightening with GEG mechanical system efficiency mandates.
Dominating procurement spend: Wall Insulation. Gaining share fastest: Roof Insulation.
End User:
Buyer sophistication and project scale create tiered specification authority across the value chain.
- Construction Contractors:General and specialty contractors control material selection for new build and major renovation projects. DIBt certification requirements and installer training mandates filter supplier access to this channel.
- Facility Managers:Commercial and industrial building operators prioritize lifecycle cost and maintenance accessibility over first-cost optimization.
- Industrial Plants:Process equipment and building envelope upgrades follow capital investment cycles distinct from construction seasonality.
- Commercial Complexes:Property investment vehicles and REITs aggregate demand across portfolios, enabling bundled procurement.
Controlling largest project pipeline: Construction Contractors. Consolidating fastest: Commercial Complexes.
Installation Method:
Application technique determines labor skill requirements, equipment capital intensity, and quality assurance protocols.
- Spray Foam:On-site chemical reaction enables seamless monolithic envelopes in irregular cavities and complex roof geometries. Certified applicator scarcity constrains capacity during peak retrofit seasons.
- Preformed Boards:Factory-controlled dimensions and densities enable rapid installation in accessible cavities with predictable thermal performance.
- Injection:Retrofit cavity fill techniques target existing masonry construction without envelope disruption.
- Loose Fill:Open-cell particulate systems serve attic and floor applications where compression settling is manageable.
- Laminated Panels:Pre-finished structural insulated panels accelerate construction timelines in modular and prefabricated building systems.
Capturing highest value per square meter: Spray Foam. Scaling manufacturing investment: Laminated Panels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The German government's KfW subsidy zones channel retrofit investment toward eastern federal states and aging industrial corridors. Bavaria and North Rhine-Westphalia absorb disproportionate insulation volumes due to overlapping housing stock age and manufacturing density. Regional procurement patterns diverge sharply between southern homeowner-driven demand and northern municipal housing corporation aggregation.
Bavaria
Post-war residential stock concentrated around Munich and Nuremberg generates sustained envelope retrofit demand. The federal state's building code enforcement exceeds national GEG minimums through supplementary thermal bridge regulations. Housing associations in the Munich metropolitan region are bundling spray foam roof upgrades with heat pump installations.
North Rhine-Westphalia
Ruhr Valley industrial legacy infrastructure requires simultaneous pipe and building envelope insulation across chemical and steel processing sites. KBA energy efficiency labeling adoption runs highest here due to proximity to testing laboratories. The Cologne-Düsseldorf corridor concentrates commercial property manager procurement for multi-asset portfolio retrofits.
Baden-Württemberg
Automotive supplier clusters around Stuttgart drive specialized HVAC and cleanroom insulation specifications. The state energy agency's retrofit acceleration program compresses project timelines for small and medium residential buildings. Freiburg's passive house construction tradition sustains premium polyisocyanurate demand for ultra-low-energy new builds.
Lower Saxony
Offshore wind manufacturing at Cuxhaven and automotive plants in Wolfsburg create industrial process insulation demand distinct from residential seasonality. The state's coastal climate exposure favors moisture-resistant extruded polystyrene specifications in basement and foundation applications. Municipal housing corporations in Hanover aggregate district-level procurement for standardized retrofit packages.
Berlin-Brandenburg
Plattenbau prefabricated housing estates present standardized envelope retrofit opportunities at portfolio scale. The federal capital's 2030 climate neutrality target accelerates specification of next-generation low-GWP blowing agent formulations. Energy service companies in Potsdam are piloting bundled insulation-photovoltaic-heat pump contracts for municipal housing stock.
Germany Foam Insulation Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with system suppliers commanding premium positions in spray foam while board producers compete on manufacturing scale. The vendor base organizes into three tiers: integrated chemical producers controlling polyol-isocyanate value chains, specialized foam fabricators with DIBt-certified formulations, and regional distributors bundling installation services. Competitive dynamics center on blowing agent transition timing and certified applicator network density rather than price alone. M&A activity targets regional installers to secure GEG-compliant capacity, while chemical producers license next-generation low-GWP formulations to accelerate market access.
Among integrated chemical producers, BASF SE and Covestro AG exemplify the R&D-intensive archetype navigating F-Gas Regulation compliance timelines. Armacell occupies a specialized position in elastomeric pipe insulation distinct from rigid foam competitors. These three companies anchor distinct competitive vectors: polyurethane system innovation, polyisocyanurate fire-performance optimization, and industrial HVAC specialization respectively.
| Leading Market Players |
|---|
| Dow Chemical Company |
| Armacell |
| BASF SE |
| Owens Corning |
| Knauf Insulation |
| Saint-Gobain |
| Kingspan Group |
| Recticel NV/SA |
| Covestro AG |
| Others |
Supply & Pricing Matrix
Certified spray foam applicator scarcity in Bavaria and North Rhine-Westphalia widens pricing spreads between premium rush contracts and standard-schedule installations. Labor-cost differentials between union-trained GEG-compliant crews and uncertified generalist contractors create three distinct procurement tiers that chemical system suppliers exploit through differentiated distributor pricing.
Pricing Analysis
Short lead-time premiums command substantial markups as certified installer queues extend through peak retrofit seasons. The market runs a project-based contract structure with pricing stratifying across DIBt-certified premium systems, standard polyurethane formulations, and commodity polystyrene boards. Price differentiation hinges on KBA energy efficiency labeling tier and volume-scale procurement from municipal housing corporations. Cost compression in the standard tier is intensifying because polyol and isocyanate feedstock volatility transmits directly through system costs. Commercial property managers show greatest price sensitivity, while passive house developers prioritize thermal performance over unit economics.
Supply Chain Analysis
Reverse logistics for rigid foam board offcuts and spray foam drum returns flow through specialized construction waste processors for chemical recovery and mechanical recycling. Feedstock concentration centers on Belgium, the Netherlands, and Germany's own integrated chemical complexes along the Rhine. Raw material flows draw from crude oil and natural gas derivatives for polyols, isocyanates, and blowing agents. Single-source vulnerability around hydrofluorocarbon blowing agent quotas under EU F-Gas Regulation creates supply chain risk as reformulation timelines compress. Distribution runs through DIBt-certified system houses that blend chemicals and bundle applicator training.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where certified spray foam installer capacity bottlenecks prop pricing power for integrated chemical producers with captive training networks.
For Market Incumbents: Anticipate mineral wool substitution pressure in Berlin and Hamburg high-rise corridors by accelerating polyisocyanurate fire-performance certification investments. Secure backward integration into hydro-olefin blowing agent supply before F-Gas Regulation quotas tighten further. Channel control through exclusive distributor relationships with Bavarian housing associations represents the critical defensive lever against emerging system suppliers. For New Entrants and Emerging Players: The Building Energy Act (GEG) in Germany opens a window for specialized polyisocyanurate fabricators targeting thermal bridging remediation in Plattenbau estates. White-space concentration sits with municipal housing corporation aggregation in Saxony and Brandenburg, where bundled envelope-heat pump contracts lack sufficient certified applicator capacity. A go-to-market angle through energy service company partnerships bypasses direct installer recruitment constraints. For Investors and Strategic Acquirers: The window for entry favors regional spray foam installation specialists with established DIBt-certified crews and municipal procurement relationships. Long-term viability rests on capturing retrofit demand acceleration through the mid-2030s as GEG compliance deadlines compress. Acquisition targets should demonstrate proven heat pump integration bundling capabilities. The signal to monitor is KfW subsidy program expansion into eastern federal states, which would validate district-level procurement aggregation models.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blowing Agents | Captive supply of hydro-olefin alternatives insulates margins from F-Gas Regulation quota volatility. |
| Certified Installer Network Expansion | DIBt-compliant training capacity in Bavaria and North Rhine-Westphalia secures GEG-mandated project access. |
| Heat Pump Integration Bundling | Single-contract envelope-mechanical system offerings align with municipal housing corporation procurement consolidation. |
| Bio-based Polyol Formulation Investment | Castor oil and rapeseed feedstock chemistry meets circular economy specifications from housing associations. |
| Regional System House Acquisition | DIBt-certified blending and distribution assets in eastern Germany capture KfW subsidy zone demand acceleration. |
Research Methodology
Trade association publications from the German Chemical Industry Association (VCI), DIBt certification registries, and KBA energy efficiency labeling databases formed the secondary backbone of data collection. Primary interviews with polyurethane system house technical directors, certified spray foam applicators, municipal housing corporation procurement managers, and GEG compliance consultants validated demand assumptions. Customs data for polyol and isocyanate import flows supplemented bottom-up project pipeline analysis with top-down chemical consumption triangulation.
Historical trendline analysis of retrofit permit filings and insulation material production volumes established baseline growth trajectories across the projection horizon. The analytical framework modeled segmentation across material chemistry, building system position, end-user sophistication, and installation technique. CAGRs were synthesized from installer capacity expansion rates, GEG regulatory phase-in schedules, and KfW subsidy allocation patterns. Forecast inputs incorporated F-Gas Regulation blowing agent quota trajectories and heat pump deployment correlations.
The model assumes a particular technology adoption path; alternative pathways for CO₂-based blowing agent systems would alter the outlook if thermal performance gaps close faster than projected. Forecasts reflect assumptions about DIBt certification timeline stability and installer training throughput capacity. Practitioners should monitor GEG revision announcements and KfW program reallocations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Ready-Mix Concrete Market
Building & Construction Materials
Europe Industrial Flooring Market
Building & Construction Materials
Marble Market
Building & Construction Materials
North America Decks Market
Building & Construction Materials
Global Wooden Formwork Systems Market
Building & Construction Materials
North America Insulated Concrete Form (ICF) Market
Building & Construction Materials
Sawn and Profiled Wood Products Market
Building & Construction Materials
United States I-Joist Market
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
Liquid Applied Roofing Market
Building & Construction Materials
Girdle Plates Market
Building & Construction Materials
Europe Green Buildings Market
Building & Construction Materials
China Marble Market
Building & Construction Materials
Global Steel Service Centers Market
Building & Construction Materials
Egypt Prefab Wood Buildings Market
Building & Construction Materials
Europe Gypsum Board Market