
 Garage Doors Market | 2026-2036
Garage Doors Market Size, Share, and Industry Trends Forecast 2026-2036
Garage Doors Market Analysis
The gap between premium insulated steel systems and entry-grade uninsulated units is realigning distribution strategies across the channel. Wayne Dalton leverages its vertically integrated manufacturing network to control cost structures at the mid-tier. Hörmann anchors its position through German-engineered thermal performance ratings that command specification in high-end residential projects. Clopay differentiates via broad material breadth spanning steel, wood, and aluminum portfolios.
A garage door is a movable barrier system, typically constructed from interlocking steel, aluminum, wood, or fiberglass panels ranging from 1.375 to 2 inches in thickness, engineered to seal building openings against weather, intrusion, and thermal transfer while accommodating horizontal, vertical, or swing-plane actuation. Sectional doors occupy the dominant share due to their compatibility with automatic opener mechanisms and overhead track geometry that maximizes drive-through clearance. Smart garage systems represent the fastest-expanding technology segment as Wi-Fi-enabled openers with camera integration and mobile app control displace legacy radio-frequency remotes in new construction and retrofit alike. Steel remains the material backbone for volume production, though fiberglass gains specification share in coastal corrosion environments where salt exposure degrades conventional metal substrates.
The US DOE building energy codes and ENERGY STAR certification requirements are elevating minimum insulation R-values and driving specification upgrades in climate zones with heating-degree-day intensity. The EPA lead-safe renovation rules and OSHA fall-protection standards shape installation contractor compliance costs and training burdens across the residential service channel. Stakeholders must monitor evolving smart-home interoperability protocols and cybersecurity mandates as connected garage systems become entry points for whole-home automation platforms.
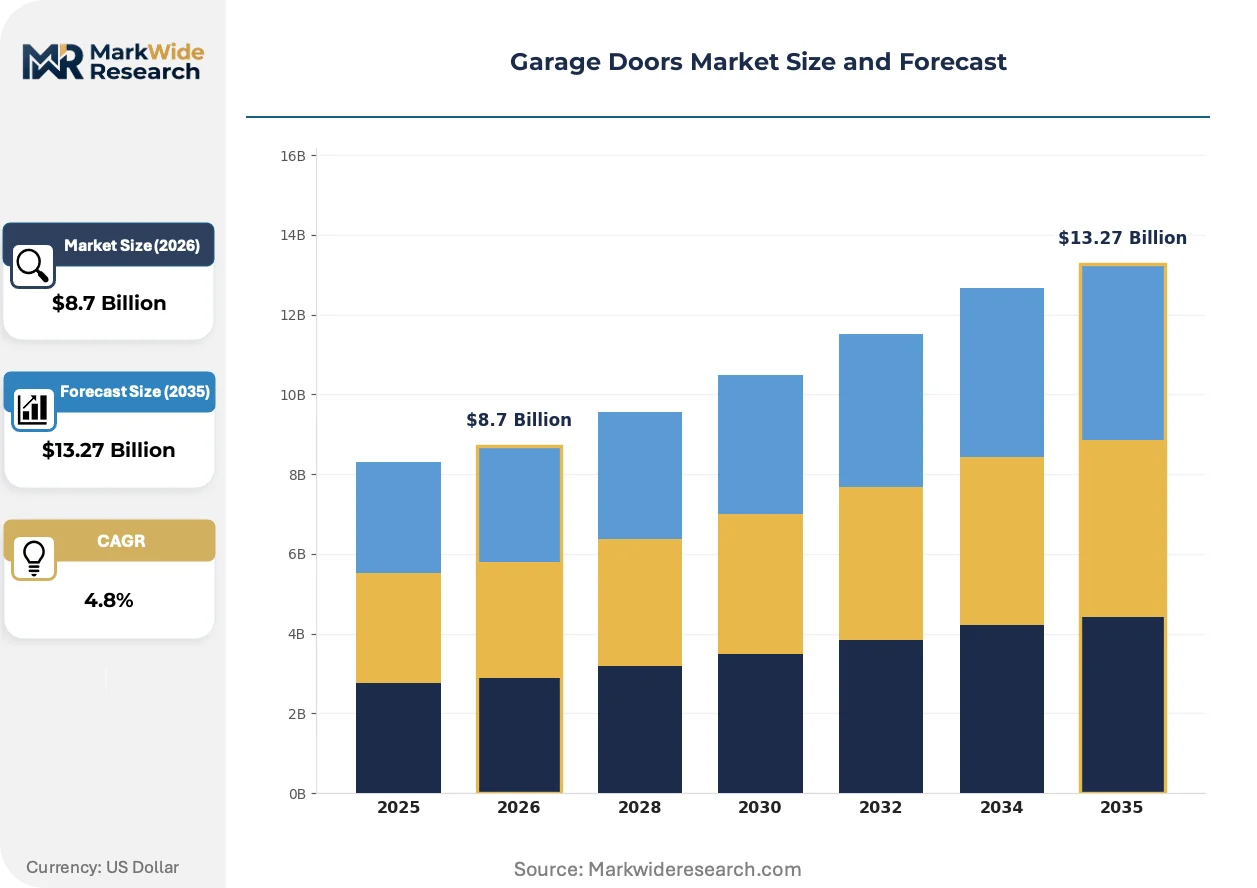
Market Dynamics
Retrofit replacement cycles in suburban North America are compressing as homeowners accelerate garage modernization ahead of resale activity, while US DOE insulation mandates force specification upgrades across climate zones with heating-degree-day intensity.
Growth Catalysts
- Building energy code escalation:US DOE thermal performance standards under climate-zone-specific R-value mandates are elevating minimum insulation specifications and driving premium product substitution in northern tier states.
- Smart-home platform convergence:Wi-Fi-enabled opener systems with camera integration and mobile app control are displacing legacy radio-frequency remotes in both new construction and retrofit channels.
- Sun Belt metropolitan expansion:Residential construction corridors across Texas, Florida, and Arizona are concentrating demand for corrosion-resistant fiberglass and aluminum substrates in coastal salt-exposure environments.
Market Restraints
- Steel input cost volatility:Galvanized steel coil prices fluctuate with scrap metal and zinc ingot markets, compressing margin stability for volume manufacturers dependent on commodity-grade substrates.
- Installation labor scarcity:EPA lead-safe renovation certification requirements and OSHA fall-protection training burdens are constraining contractor capacity expansion across the residential service channel.
- Technical limitation in legacy compatibility:Smart opener retrofits face integration friction with pre-1993 torsion spring systems lacking safety sensor infrastructure, slowing upgrade penetration in older housing stock.
Strategic Opportunities
- Underpenetrated coastal corrosion markets:Salt-exposure degradation of conventional steel substrates creates specification openings for fiberglass and aluminum composite systems in Florida and Gulf Coast corridors.
- Regulatory tailwind from ENERGY STAR expansion:EPA certification requirements for whole-building envelope performance are elevating garage door thermal ratings in utility rebate programs across northern climate zones.
- Technology convergence of access control and home security:Camera-equipped smart openers with biometric authentication and package delivery verification are integrating with whole-home automation platforms.
Industry Challenges
- Cybersecurity certification complexity:Connected garage systems face emerging FCC and state-level data privacy mandates for IoT device hardening, extending product development timelines and testing costs.
- Supply chain reconfiguration friction:Regionalization of steel coil sourcing and aluminum extrusion capacity is forcing logistics network redesigns for manufacturers with historically centralized distribution models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garage Doors Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sectional Doors, Roller Doors, Tilt-Up Doors, Sliding Doors Material: Steel, Wood, Aluminum, Fiberglass Technology: Automatic Opener, Manual Opener, Smart Garage Systems, Remote Control End User: Residential, Commercial, Industrial, Agricultural |
| Companies Covered | Wayne Dalton, Raynor Garage Doors, Clopay, Novoferm, C.H.I. Overhead Doors, Amarr, Overhead Door, Teckentrup, Hörmann, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garage Doors Market Emerging Trajectories
Product specification and channel economics are diverging as thermal performance mandates reshape material selection while smart-system integration redefines the competitive boundary between door hardware and home automation platforms.
Camera-enabled smart opener systems are integrating with whole-home security platforms through Wi-Fi connectivity and cloud-based access logging. High-end residential buyers and multi-family property managers are specifying these systems at accelerating rates. The technology is integrating previously separate door control, surveillance, and entry management functions into unified automation stacks, compressing standalone opener margins while expanding system-level revenue pools.
US DOE building energy codes are mandating climate-zone-specific minimum R-values for garage doors in new construction and major renovations. The regulations are forcing specification upgrades from uninsulated single-layer steel to polyurethane-foam-filled sandwich construction in heating-degree-day-intensive zones. Northern tier states and mountain region municipalities are responding with accelerated code adoption timelines and utility rebate programs tied to ENERGY STAR certification thresholds.
Homeowner procurement patterns are fragmenting across direct-to-consumer digital channels, pro-contractor wholesale networks, and big-box retail showrooms. The traditional dealer-installer channel faces disintermediation pressure from e-commerce platforms offering video-guided self-measurement and third-party installation marketplaces. This behavioral shift is most visible in suburban retrofit markets where younger homeowners prioritize price transparency and scheduling convenience over established contractor relationships.
Garage Doors Market Segmentation
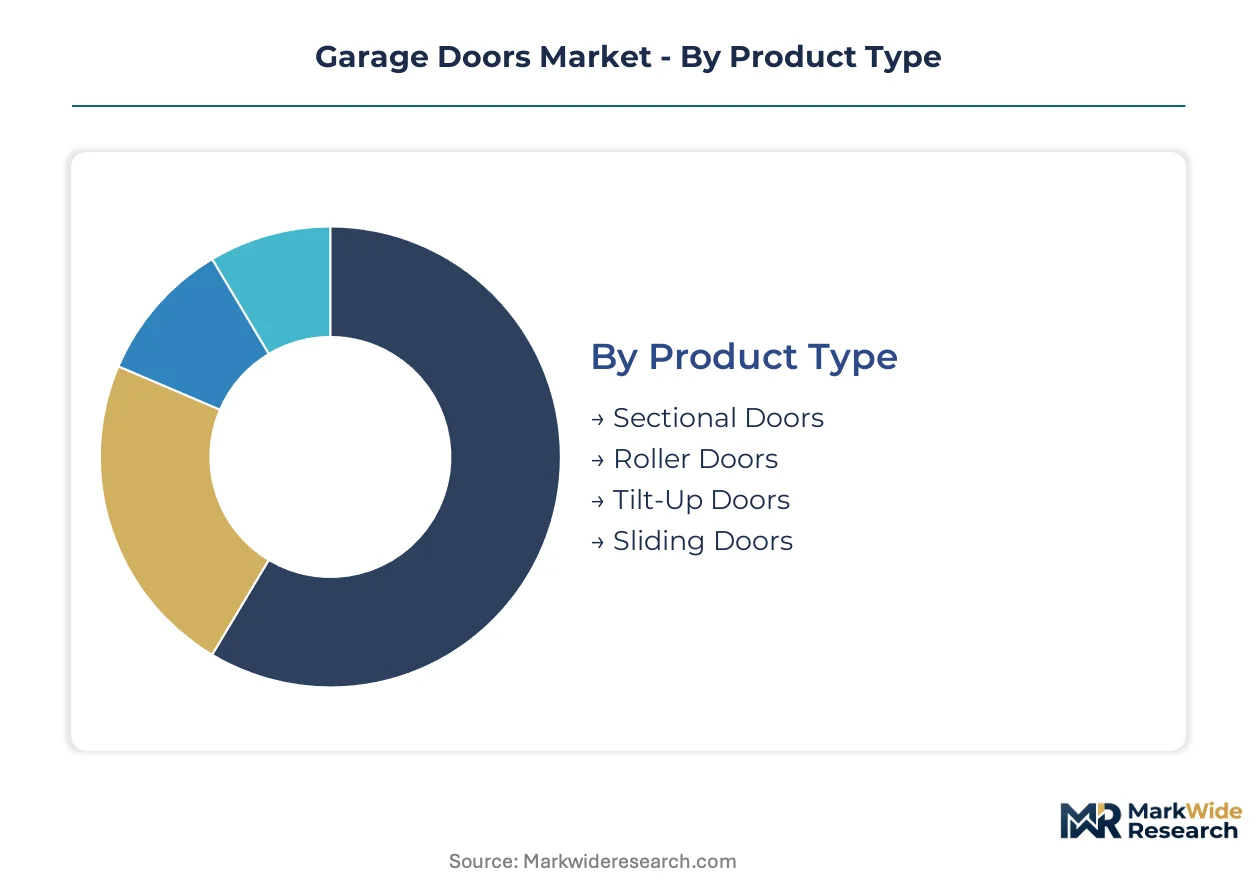
Garage door procurement splits sharply between volume-driven replacement cycles and specification-heavy new construction. Material selection and technology integration now determine margin capture more than raw installation volume.
Product Type:
Volume concentrates in overhead track systems compatible with automatic actuation, while premium positioning attaches to architectural statement designs with custom panel configurations.
- Sectional Doors:Interlocking horizontal panels ride on overhead track geometry that maximizes drive-through clearance. Demand clusters in suburban North American retrofit markets where homeowners prioritize opener compatibility and thermal sealing ahead of resale activity.
- Roller Doors:Curtain-style steel or aluminum slats coil around a drum assembly above the opening, minimizing headroom requirements. Commercial warehousing and light industrial facilities in Sun Belt metropolitan corridors specify these for high-cycle durability in salt-exposure environments.
- Tilt-Up Doors:Single rigid panels pivot outward on side-mounted hinges, demanding substantial driveway clearance.
- Sliding Doors:Horizontal track-mounted panels bypass the opening plane, common in agricultural outbuildings with wide span requirements.
Today's leader: Sectional Doors. Tomorrow's challenger: Roller Doors.
Material:
Cost tier stratification runs from commodity galvanized steel through specification-grade composites, with thermal performance ratings and corrosion resistance driving substitution patterns.
- Steel:Galvanized and painted coil stock forms the volume backbone, available in single-layer, double-skin, or polyurethane-foam-filled sandwich construction. US DOE climate-zone R-value mandates in northern tier states are forcing specification upgrades from uninsulated to insulated steel configurations.
- Fiberglass:Composite panels resist salt-degradation in coastal humidity, gaining specification share across Florida and Gulf Coast residential construction. The material commands premium positioning where metal substrate corrosion accelerates replacement cycles.
- Wood:Solid or engineered lumber panels serve high-end architectural specifications requiring stain-grade finishes.
- Aluminum:Lightweight extrusions with glass infill dominate contemporary residential aesthetics and commercial storefront applications.
Steel commands current volume. Fiberglass climbs the fastest on coastal corrosion tailwinds.
Technology:
Actuation methods are diverging as connected systems displace legacy radio-frequency infrastructure, with installation channel economics favoring integrated over standalone components.
- Smart Garage Systems:Wi-Fi-enabled openers with camera integration, mobile app control, and cloud-based access logging integrate with whole-home automation platforms. Residential new construction and affluent retrofit segments specify these at accelerating rates as biometric authentication and package delivery verification become standard.
- Automatic Opener:Chain, belt, or screw-drive motorized units with safety sensor infrastructure dominate volume replacement. Pre-1993 torsion spring systems lacking sensor compatibility create integration friction that slows upgrade penetration in older housing stock.
- Manual Opener:Spring-assisted or counterweighted systems persist in agricultural and detached outbuilding applications.
- Remote Control:Legacy radio-frequency transmitters face displacement by smartphone-based access management.
Automatic Opener holds installed base dominance. Smart Garage Systems represent the steepest expansion trajectory.
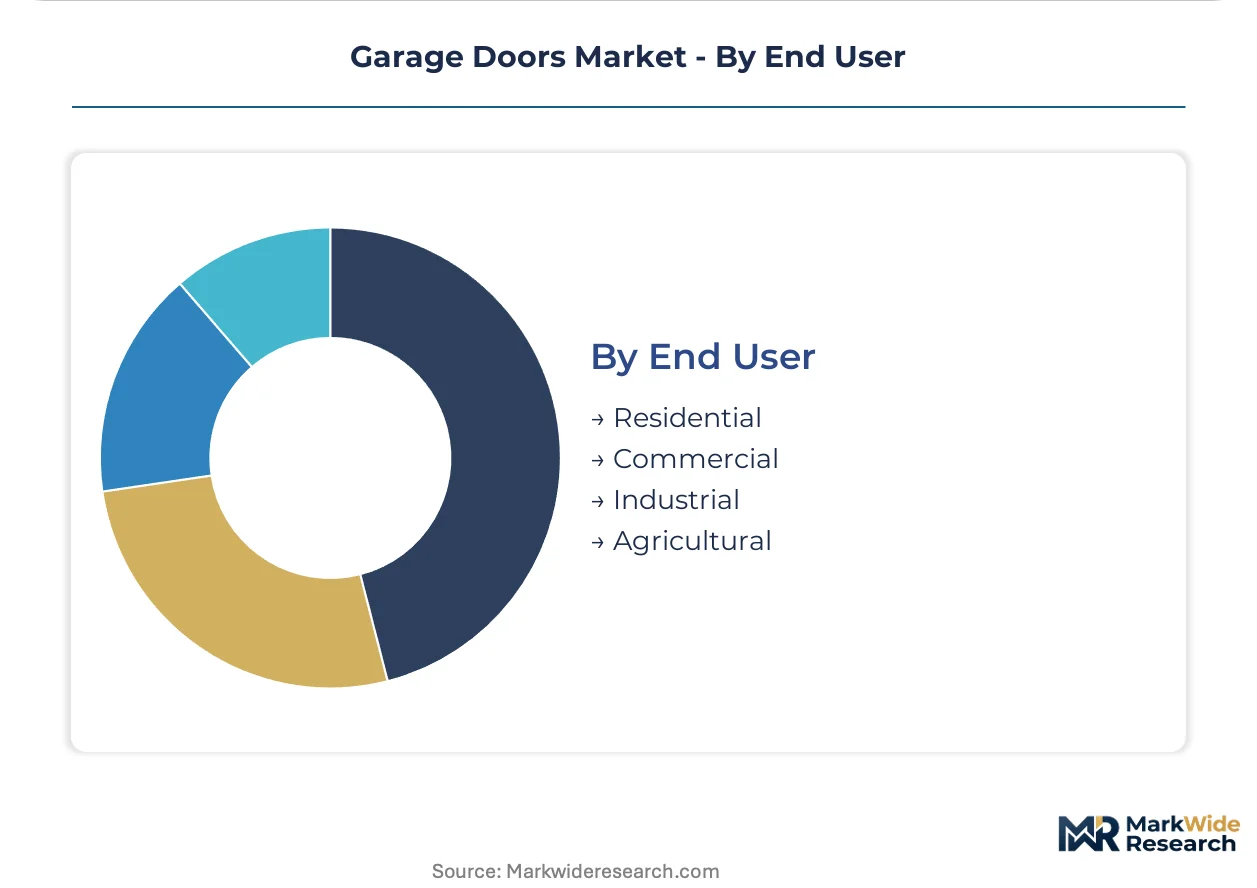
End User:
Customer type determines specification intensity, with commercial and industrial applications prioritizing cycle-life durability while residential procurement fragments across price transparency and convenience channels.
- Residential:Single-family and multi-family garage modernization drives replacement demand, with suburban North American homeowners accelerating upgrades ahead of resale. Procurement is fragmenting across direct-to-consumer digital channels, pro-contractor wholesale networks, and big-box retail showrooms.
- Commercial:Retail storefronts, fire stations, and municipal facilities demand high-cycle operation with minimal maintenance downtime. ENERGY STAR certification thresholds and utility rebate programs elevate thermal specification in climate zones with heating-degree-day intensity.
- Industrial:Manufacturing and warehousing facilities specify heavy-duty rolling steel or insulated sectional systems for security and environmental separation.
- Agricultural:Equipment storage and livestock facilities prioritize wide clearances and manual override reliability.
Residential commands volume concentration. Commercial offers the most attractive margin expansion on specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's retrofit replacement cycles lag the United States by approximately three to four years, while Germany's specification-grade thermal performance standards command premium positioning across Central European new construction corridors.
United States
Sun Belt metropolitan expansion across Texas, Florida, and Arizona concentrates demand for corrosion-resistant fiberglass substrates in coastal salt-exposure environments. The US DOE building energy codes mandate climate-zone-specific R-value minimums that elevate insulation specifications in northern tier states. Wayne Dalton and Clopay anchor manufacturing and distribution networks across suburban North American retrofit markets.
Germany
Engineered thermal performance ratings from Hörmann and Novoferm command specification in high-end residential projects across climate zones with heating-degree-day intensity. The EU Green Deal and national building energy efficiency regulations accelerate code adoption timelines for whole-building envelope performance. Industrial clusters in North Rhine-Westphalia and Baden-Württemberg concentrate precision manufacturing capacity for specification-grade door systems.
China
Rapid urbanization and middle-class residential construction expansion drive volume demand for steel sectional systems compatible with automatic opener mechanisms. GB standards for building energy efficiency and MIIT industrial upgrading policies shape local manufacturing specifications. Manufacturing gravity concentrates in the Yangtze River Delta and Pearl River Delta corridors serving domestic and export markets.
Japan
Aging housing stock modernization and space-constrained urban residential construction favor compact roller door systems with minimal headroom requirements. METI energy conservation standards and JIS product safety certifications elevate minimum performance thresholds for thermal sealing and durability. Industrial activity clusters in the Kanto and Kansai regions around Tokyo and Osaka metropolitan areas.
United Kingdom
Retrofit replacement demand strengthens across suburban residential markets as homeowners accelerate garage modernization ahead of property resale activity. UK building regulations Part L conservation of fuel and power mandates elevate thermal performance specifications for attached garage structures. Distribution and installation networks concentrate in the Southeast and Midlands regions serving Greater London commuter corridors.
Garage Doors Market Vendor Landscape
Top-tier vendors anchor premium specification channels, while mid-tier fabricators compete on cost structures and distribution reach. The vendor base stratifies across vertically integrated manufacturers with captive steel processing, regional specialists with curated installation networks, and technology-forward entrants converging smart-home platforms with door hardware. Consolidation pressure intensifies as scale advantages in procurement and logistics compress margins for non-integrated competitors. Dominant competitive moves include backward integration into steel coil sourcing and strategic partnerships with whole-home automation platforms.
Among German-engineered specialists, Hörmann GmbH and Novoferm Group exemplify the premium-tier archetype anchored by thermal performance certification and specification-grade product breadth. Wayne Dalton occupies a position representing vertically integrated North American manufacturing with control over mid-tier cost structures and suburban retrofit channel penetration. Clopay exemplifies material breadth diversification across steel, wood, and aluminum portfolios serving segmented residential and commercial demand.
| Leading Market Players |
|---|
| Wayne Dalton |
| Raynor Garage Doors |
| Clopay |
| Novoferm |
| C.H.I. Overhead Doors |
| Amarr |
| Overhead Door |
| Teckentrup |
| Hörmann |
| Others |
Supply Flow & Price Mechanics
ENERGY STAR certification thresholds gate qualified supply access and premium-tier pricing power for garage door manufacturers serving northern climate zones with heating-degree-day intensity. Contractors without EPA lead-safe renovation credentials face exclusion from federal stimulus-funded retrofit programs, compressing their bid competitiveness against certified installers who capture utility rebate-eligible projects.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for commodity-grade galvanized steel coil, forcing North American fabricators to defend margin structures through polyurethane-foam-filled sandwich construction upgrades. Pricing stratifies across premium, standard, and economy tiers based on thermal performance certification and after-sales installation bundling. Cost compression in entry-grade uninsulated steel runs through scrap metal and zinc ingot volatility. Big-box retail channels exhibit highest price sensitivity, while specification-driven commercial contractors prioritize cycle-life durability over unit cost.
Supply Chain Analysis
Freight cost escalation from centralized steel coil sourcing to dispersed suburban installation networks is accelerating regionalization of aluminum extrusion and composite panel production. Manufacturing gravity centers on the United States, Germany, and China, with each hub feeding distinct regulatory compliance requirements. Raw material dependencies rest on galvanized steel coil, polyurethane foam insulation, and aluminum extrusions. Single-source vulnerability concentrates in specialized torsion spring systems from legacy suppliers. Distribution runs through pro-contractor wholesale networks, big-box retail showrooms, and emerging direct-to-consumer digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where German-engineered thermal performance standards command 40-60% pricing premiums over North American mid-tier products, justified by differential ENERGY STAR certification stringency and EU Green Deal envelope performance mandates.
For Market Incumbents: Anticipate disintermediation pressure from direct-to-consumer digital channels by tightening captive installation network control and accelerating smart-home platform certification investments. Defensive consolidation through backward integration into polyurethane foam insulation production addresses raw material cost volatility. Channel control represents the priority lever against e-commerce entrants offering video-guided self-measurement tools. For New Entrants and Emerging Players: US DOE climate-zone-specific R-value mandates in northern tier states open a window for specification-grade insulated steel systems with ENERGY STAR certification. The most penetrable segment sits in suburban retrofit markets where homeowners accelerate garage modernization ahead of resale activity. A go-to-market angle through utility rebate program partnerships bypasses established contractor channel gatekeeping. For Investors and Strategic Acquirers: Roll-up economics work for regional installation specialists with EPA lead-safe renovation certification because contractor capacity constraints create pricing power in high-demand retrofit corridors. Long-term viability hinges on smart-home interoperability protocol adoption and cybersecurity compliance infrastructure. The signal to watch is FCC IoT device hardening mandate implementation timelines as connected garage systems become whole-home automation entry points.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Insulation Production | Captive polyurethane foam supply stabilizes margin structures against petrochemical feedstock volatility. |
| Smart-Home Platform Certification | Wi-Fi-enabled opener integration with Amazon Alexa and Google Home expands specification in new construction. |
| Regional Manufacturing Footprint Expansion | Localized aluminum extrusion capacity reduces freight exposure to Sun Belt metropolitan construction corridors. |
| Utility Rebate Program Partnership | ENERGY STAR-certified product positioning unlocks consumer incentives in northern climate zones. |
| EPA Lead-Safe Renovation Certification Investment | Certified contractor networks capture federal stimulus-funded retrofit demand in suburban replacement cycles. |
Methodological Framework
Direct dialogue with garage door manufacturing executives, regional distribution channel managers, EPA-certified installation contractors, and smart-home platform engineers grounded qualitative findings in operational reality. Secondary validation drew from US DOE building energy code filings, ENERGY STAR product certification databases, OSHA fall-protection compliance records, and SEC 10-K disclosures from publicly traded building products companies. Bottom-up demand modeling from housing starts and retrofit replacement cycle data triangulated against top-down market sizing from trade association shipments.
Segmented volume and value estimates across product type, material substrate, actuation technology, and end-user category structured the analytical framework across the projection horizon. CAGRs derived from regression analysis against macro housing indicators, energy price elasticity, and regulatory adoption timelines. Industry-specific forecast inputs incorporated heating-degree-day intensity by climate zone and smart-home penetration rates by household income tier.
Revisions become necessary when US DOE building energy code adoption timelines accelerate, galvanized steel coil price volatility exceeds historical bands, or FCC cybersecurity mandates for IoT devices extend product development cycles. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Noise Insulation Jackets Market
Building & Construction Materials
Global Convertible Roof System Market
Building & Construction Materials
Warm Mix Asphalt Market
Building & Construction Materials
Sheet Piling Market
Building & Construction Materials
Plumbing Components Market
Building & Construction Materials
Geofoam Market
Building & Construction Materials
Carbon Textile Reinforced Concrete Market
Building & Construction Materials
Latex Caulk Market
Building & Construction Materials
Welded Wire Mesh Market
Building & Construction Materials
Italy Prefab Wood Buildings Market
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
Laminated Veneer Lumber (LVL) Market
Building & Construction Materials
Asphalt Shingles Market
Building & Construction Materials
US Steel Rebar Market
Building & Construction Materials
Roofing Underlay Market
Building & Construction Materials
Elevated Water Storage Tanks Market