
 Soil Stabilization Market | 2026-2036
Soil Stabilization Market Size, Share, and Industry Trends Forecast 2026-2036
Soil Stabilization Market Outlook
The soil stabilization industry is recalibrating around a sharp split between premium polymer and geosynthetic systems and commodity cement-lime blends. Sika AG leverages its polymer chemistry depth to command specification-driven road contracts. SNF Holding Company anchors water-soluble polymer supply for large ground improvement programs. BASF SE differentiates through tailored bitumen emulsion formulations for airfield applications.
Soil stabilization encompasses mechanical, chemical, biological, and geosynthetic techniques that alter soil engineering properties to increase load-bearing capacity, reduce permeability, or control shrink-swell behavior in subgrade and embankment applications. Portland cement and lime remain dominant by volume, though polymer stabilization achieves superior performance in expansive clay regions at elevated material cost. The technology dimension shows mechanical and chemical methods maturing while geosynthetics capture margin pools in infrastructure resilience specifications. Application demand skews heavily toward road construction, with ground improvement fastest-growing as urban densification drives soft-soil remediation beneath high-rise clusters.
EPA guidelines in the United States restrict leachable heavy metals in cementitious stabilizers for environmental remediation sites. India's BIS mandates compressive strength benchmarks for lime-stabilized subgrades on national highway projects. China's MEE enforces carbon intensity disclosures for binder production, reshaping material selection on state-funded rail corridors. Stakeholders must track evolving geotechnical specification tiers across jurisdictions to align product portfolios with procurement gate criteria.
Market Dynamics
The soil stabilization market pivots on tightening carbon accounting rules that force contractors to document embodied emissions across binder supply chains. China's MEE carbon intensity disclosures and India's dual carbon goals under MEE guidelines are compressing specification windows for traditional cement-lime blends while elevating polymer and geosynthetic alternatives.
Growth Catalysts
- High-speed rail corridors:China's state-funded rail projects deploy geosynthetics at accelerating rates for subgrade reinforcement and embankment stability. MEE carbon accounting favors lower-emission stabilization methods on these contracts.
- Polymer chemistry advancement:Water-soluble polymers achieve superior load-bearing capacity in expansive clay regions where cement-lime blends crack and fail. Performance specifications on Indian national highways increasingly mandate polymer modification under BIS compressive strength benchmarks.
- Urban densification:Soft-soil remediation beneath high-rise clusters in coastal Chinese cities drives ground improvement demand. Geotechnical engineers specify deep soil mixing with cementitious binders to support tower foundations on reclaimed land.
Market Restraints
- Petrochemical feedstock volatility:Polymer stabilizers depend on acrylamide and acrylic acid derivatives whose prices fluctuate with crude oil markets. Margins compress unpredictably for specialty chemical suppliers.
- Portland cement supply concentration:Clinker production clusters in China, India, and Vietnam create regional supply vulnerabilities. Infrastructure stimulus in any major economy tightens local availability and extends lead times.
- Heavy metal leaching limits:EPA guidelines restrict cementitious stabilizers containing leachable chromium, arsenic, and cadmium at environmental remediation sites in the United States. Compliance testing adds cost and timeline risk.
Strategic Opportunities
- Bio-based binder development:Enzyme-induced carbonate precipitation and lignin-derived geopolymers offer carbon-negative alternatives to Portland cement. Research programs in the Netherlands and California advance pilot-scale deployment.
- Airfield pavement specifications:FAA standards for runway subgrade stabilization increasingly recognize polymer-modified bitumen emulsions. Formulators tailoring products for freeze-thaw resistance capture specification-driven contracts.
- Performance-based contracting:Highway authorities in Australia and Canada pilot design-build-maintain contracts where stabilizer suppliers guarantee subgrade performance over 20-year horizons. Risk transfer creates margin pools for proven technologies.
Industry Challenges
- Geotechnical engineer shortage:Specialized expertise in ground improvement design concentrates in aging practitioner pools. Universities produce fewer soil mechanics specialists than infrastructure programs require.
- ISO certification timelines:Geosynthetic manufacturers face 18-24 month approval cycles for ISO 10319 tensile testing and ISO 13438 durability standards. Product launches stall awaiting third-party verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soil Stabilization Market |
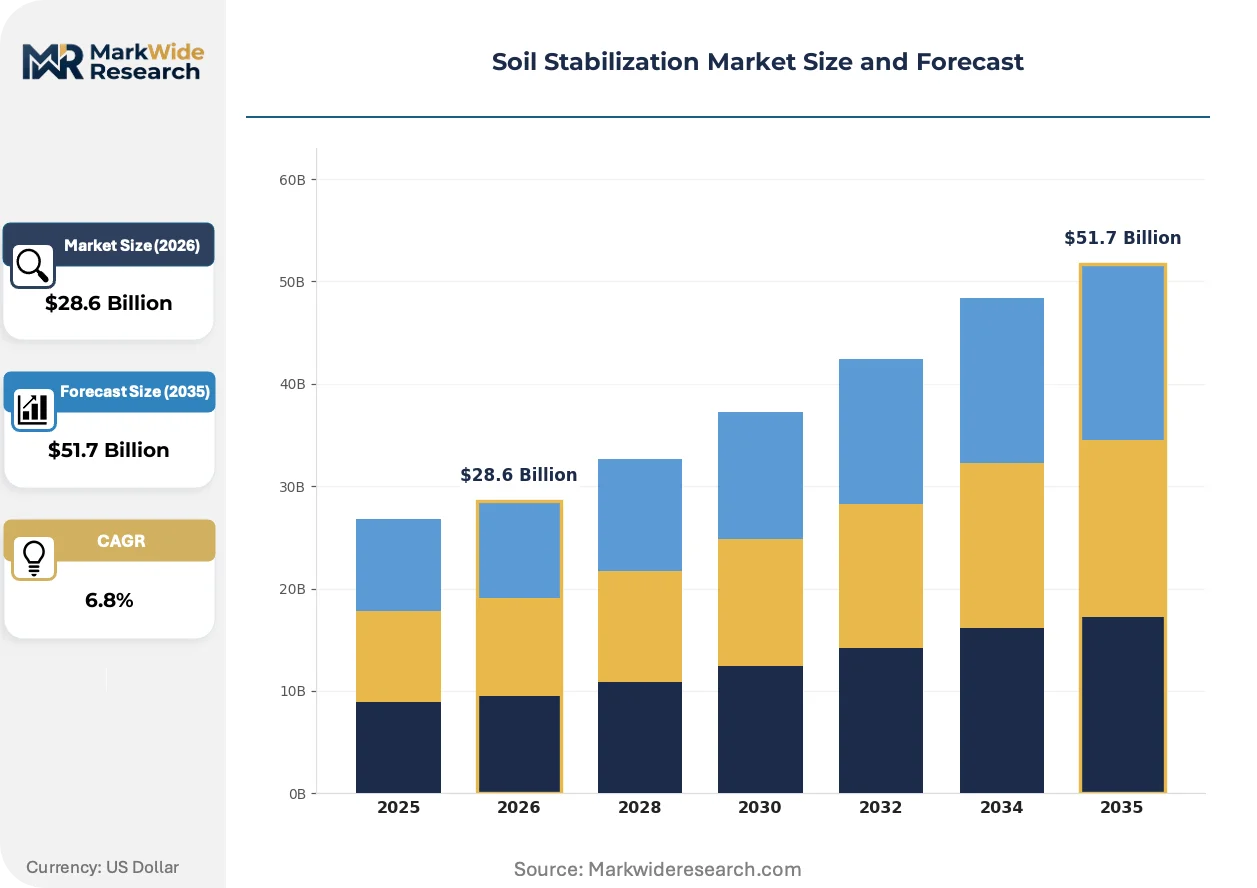
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cement, Lime, Polymer, Bitumen Application: Road Construction, Airfields, Retaining Walls, Ground Improvement Technology: Mechanical Method, Chemical Method, Geosynthetics, Biological Method End User: Construction Companies, Government Agencies, Road Authorities, Environmental Consultants |
| Companies Covered | CEMEX S.A.B. de C.V., Wirtgen Group, Sika AG, SNF Holding Company, Caterpillar Inc., BASF SE, Holcim Ltd, Soilworks LLC, The Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soil Stabilization Market Strategic Shifts
Real-time compaction monitoring and intelligent mixing equipment are compressing quality assurance timelines while reducing material over-application. Specification writers increasingly embed technology readiness requirements into contract documents.
Intelligent compaction systems equipped with accelerometer-based density sensors and GPS mapping is automating quality control on highway subgrade projects. Contractors in Germany and Japan deploy these systems to eliminate manual nuclear gauge testing. The technology is automating documentation workflows while reducing binder over-dosage by fifteen to twenty percent on average jobs.
REACH restrictions on microplastics are forcing geosynthetic manufacturers to reformulate polypropylene and polyester fibers with biodegradable coatings. European producers face 2026 deadlines for alternative chemistries that maintain tensile strength. Nonwoven geotextile categories serving erosion control and drainage applications absorb the most compliance cost.
Consolidated procurement through national infrastructure funds is concentrating buyer power in fewer hands. China's state rail corporation and India's NHAI now negotiate master supply agreements spanning multi-year programs. Brazil's federal highway authority recently adopted similar centralized purchasing, displacing fragmented state-level tendering.
Soil Stabilization Market Segmentation
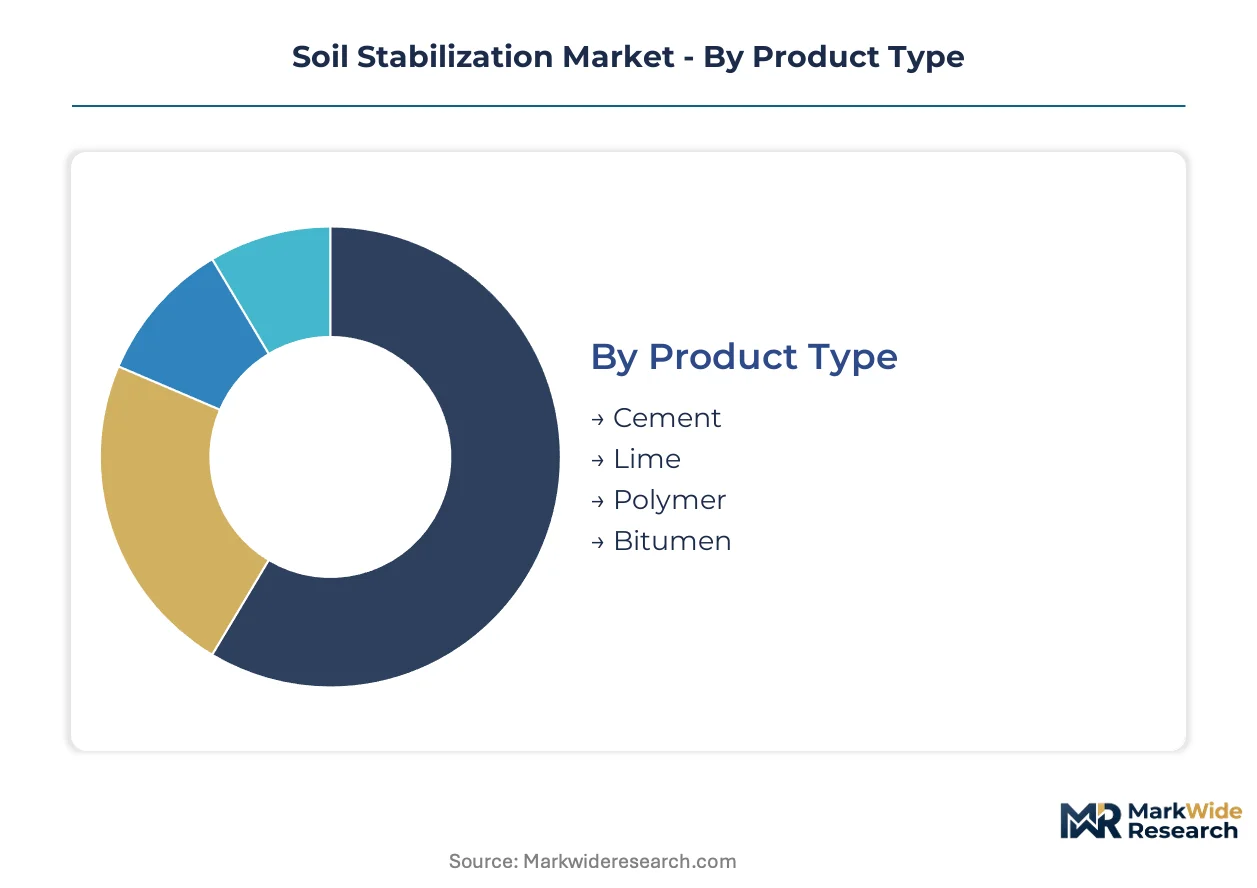
Soil stabilization procurement splits sharply between commodity binders specified on cost-driven highway contracts and engineered systems selected for performance-critical infrastructure. Specification tiers diverge by load-bearing requirements, environmental exposure, and carbon accounting rules that reshape material selection across project types.
Product Type:
Cement and lime function as standalone additives mixed directly into subgrade soils, while polymer and bitumen systems integrate as surface-sealing or deep-treatment chemistries requiring specialized application equipment.
- Cement:Portland cement dominates volume through its established supply chains and predictable strength development. Indian national highway contracts under BIS compressive strength benchmarks specify cement stabilization for expansive clay subgrades where polymer alternatives remain cost-prohibitive at scale.
- Polymer:Water-soluble acrylamide-based polymers achieve superior load-bearing capacity in high-plasticity soils where cement-lime blends crack under cyclic loading. China's high-speed rail corridor projects specify polymer modification for embankment stability where MEE carbon intensity disclosures favor lower-emission alternatives to clinker-based binders.
- Lime:Quicklime and hydrated lime remain preferred for clay soil modification through cation exchange and pozzolanic reactions. Supply concentrates in regional lime kiln networks serving road authorities in the United States and India.
- Bitumen:Cutback and emulsified bitumen formulations stabilize granular soils and provide water-repellent surface seals. FAA runway specifications increasingly recognize polymer-modified bitumen emulsions for freeze-thaw resistance.
Volume placements concentrate in Cement; the faster expansion belongs to Polymer.
Application:
Application segments arrange by structural load intensity, from distributed traffic loads on highway subgrades to concentrated bearing pressures beneath airfield pavements and high-rise foundations.
- Road Construction:Highway subgrade stabilization consumes the largest binder volumes globally. India's NHAI master supply agreements consolidate procurement across multi-year national highway programs, compressing specification windows for traditional cement-lime blends.
- Ground Improvement:Deep soil mixing and jet grouting beneath high-rise clusters in coastal Chinese cities drives demand for cementitious binders in soft-soil remediation. Urban densification accelerates fastest here as reclaimed land requires engineered support for tower foundations.
- Airfields:Runway and taxiway subgrades demand stabilized layers capable of withstanding aircraft gear loads and fuel spillage. FAA standards for subgrade stabilization increasingly specify performance-grade bitumen emulsions.
- Retaining Walls:Mechanically stabilized earth walls and reinforced soil slopes deploy geosynthetics for tensile reinforcement. MEE carbon accounting in China favors geosynthetic alternatives to concrete facing elements on state-funded rail projects.
Contract value concentrates in Road Construction; Ground Improvement climbs the fastest as urban vertical construction intensifies.
Technology:
Technology segments separate by intervention depth—surface modification through mechanical or chemical means versus embedded reinforcement systems that redistribute stresses through soil mass.
- Chemical Method:Binder injection and soil mixing alter soil engineering properties through pozzolanic cementation or ionic modification. REACH restrictions on leachable heavy metals constrain cementitious stabilizer formulations at European environmental remediation sites.
- Geosynthetics:Polypropylene and polyester geogrids, geotextiles, and geomembranes provide tensile reinforcement, separation, and filtration. China's state rail corporation deploys geosynthetics at accelerating rates for subgrade reinforcement and embankment stability on carbon-accounted contracts.
- Mechanical Method:Compaction, vibroflotation, and dynamic consolidation densify granular soils without chemical additives. Intelligent compaction systems with accelerometer-based density sensors automate quality control in Germany and Japan.
- Biological Method:Enzyme-induced carbonate precipitation and microbial cementation offer emerging carbon-negative alternatives. Research programs in the Netherlands and California advance pilot-scale deployment for low-load applications.
Specification frequency concentrates in Chemical Method; Geosynthetics gain share fastest as infrastructure resilience standards tighten.
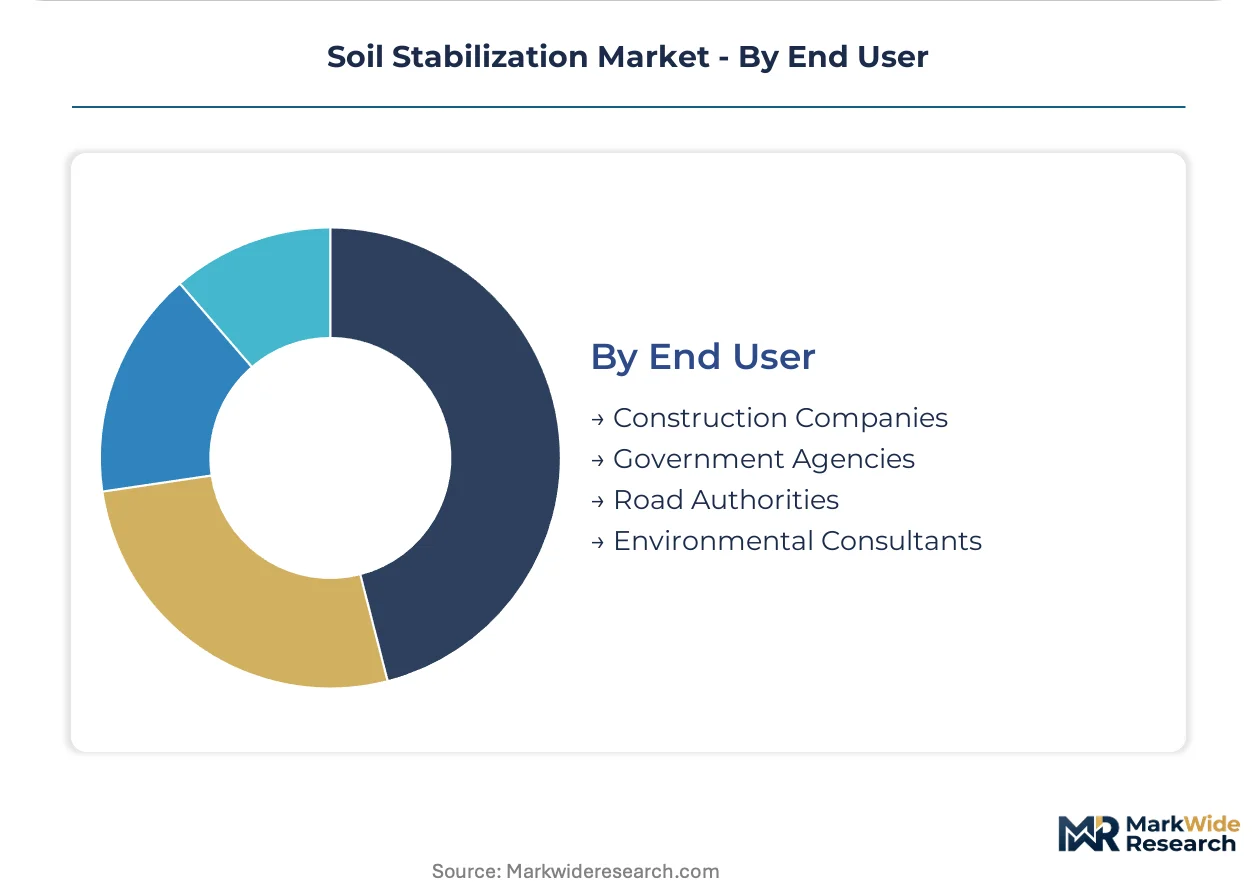
End User:
End user segments reflect procurement concentration—fragmented construction contractors bidding project-by-project versus consolidated government authorities negotiating master supply agreements.
- Government Agencies:National infrastructure funds in China, India, and Brazil consolidate buyer power through multi-year master supply agreements. These entities now negotiate directly with binder manufacturers, displacing fragmented state-level tendering.
- Road Authorities:Dedicated highway agencies in Australia and Canada pilot design-build-maintain contracts where stabilizer suppliers guarantee subgrade performance over extended horizons. Risk transfer creates margin pools for proven technologies.
- Construction Companies:General and specialty contractors execute stabilization work under specification-driven contracts. These firms face margin compression from petrochemical feedstock volatility in polymer stabilizer supply chains.
- Environmental Consultants:Remediation specialists specify stabilizers for contaminated site capping and brownfield redevelopment. EPA guidelines on leachable heavy metals constrain material selection at United States environmental remediation sites.
Procurement volume concentrates in Government Agencies; performance-based contracting expands fastest among Road Authorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beijing anchors the soil stabilization procurement landscape through China's state rail corporation and MEE carbon accounting mandates on high-speed rail corridors. India's NHAI master supply agreements and BIS compressive strength benchmarks reshape material selection on national highway programs. Germany deploys intelligent compaction systems on Autobahn subgrade projects while REACH restrictions constrain cementitious formulations.
China
High-speed rail corridor construction consumes geosynthetics for subgrade reinforcement and embankment stability. MEE carbon intensity disclosures favor lower-emission stabilization methods on state-funded contracts. Coastal cities including Shanghai and Shenzhen drive soft-soil remediation demand beneath high-rise clusters on reclaimed land.
India
National highway expansion under NHAI master supply agreements concentrates procurement across multi-year programs. BIS mandates compressive strength benchmarks for lime-stabilized subgrades on trunk road projects. Western states Gujarat and Maharashtra host polymer-modified soil programs advancing under MEE-aligned dual carbon goals.
United States
Airfield pavement reconstruction drives specification-grade bitumen emulsion demand for freeze-thaw resistance. EPA guidelines restrict leachable heavy metals in cementitious stabilizers at environmental remediation sites. Texas and California DOTs pilot intelligent compaction systems on interstate subgrade contracts.
Germany
Autobahn maintenance programs deploy accelerometer-based density sensors to automate quality control workflows. REACH restrictions on leachable chromium and cadmium constrain cementitious stabilizer formulations. Bavarian construction consortiums integrate real-time compaction monitoring to reduce binder over-dosage.
Brazil
Federal highway authority centralized purchasing displaces fragmented state-level tendering for stabilization binders. ANVISA-aligned environmental assessments shape material selection on infrastructure corridors. São Paulo and Rio de Janeiro metro extensions drive ground improvement demand for soft-soil remediation.
Soil Stabilization Market Competitive Environment
Premium-margin players sit above commodity-margin players across specification intensity and carbon accounting compliance. The vendor base organizes into three tiers: multinational chemical conglomerates with polymer chemistry depth, specialized geosynthetic and equipment fabricators, and regional cement-lime distributors serving cost-driven highway contracts. Dominant competitive moves include portfolio diversification into bio-based binders and strategic partnerships with intelligent compaction technology providers.
Within the multinational chemical tier, Sika AG and BASF SE exemplify premium-margin positioning through specification-driven road and airfield contracts. SNF Holding Company anchors water-soluble polymer supply for large ground improvement programs. Among equipment and materials specialists, Soilworks LLC occupies a position in site-specific stabilization services, while CEMEX S.A.B. de C.V. and Holcim Ltd represent volume-scale cementitious supply.
| Leading Market Players |
|---|
| CEMEX S.A.B. de C.V. |
| Wirtgen Group |
| Sika AG |
| SNF Holding Company |
| Caterpillar Inc. |
| BASF SE |
| Holcim Ltd |
| Soilworks LLC |
| The Dow Chemical Company |
| Others |
Value Chain & Pricing Dynamics
Petrochemical feedstock volatility in acrylamide and acrylic acid derivatives cascades through polymer stabilizer pricing tiers, compressing margins for specialty chemical suppliers while cement-lime blends hold firmer on clinker production clusters in China, India, and Vietnam.
Pricing Analysis
Subgrade performance guarantees anchor value-based pricing for polymer-modified systems on Indian national highway contracts under BIS compressive strength benchmarks. Three-tier pricing structure across premium polymer-geosynthetic, standard cement-lime, and economy unmodified soil tiers separates specification-driven road authorities from cost-sensitive state-level contractors. Cost compression in polymer stabilizers is intensifying because crude oil derivative prices swing unpredictably. Government agencies with master supply agreements exhibit lowest price sensitivity; fragmented construction contractors bidding project-by-project face acute margin pressure.
Supply Chain Analysis
Refurbishment flows for intelligent compaction equipment and geosynthetic deployment machinery create secondary supply channels in Germany and Japan where accelerometer-based density sensors extend equipment lifecycle. Clinker production concentrates in China, India, and Vietnam; water-soluble polymer manufacturing draws from petrochemical complexes in the United States and Western Europe. Single-source vulnerability runs through China's state rail corporation procurement concentration for high-speed rail corridor geosynthetics. Distribution runs through national infrastructure funds negotiating multi-year master supply agreements directly with binder manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon accounting mandates from China's MEE and India's dual carbon goals are compressing specification windows for traditional cement-lime blends, forcing commodity-margin distributors to exit or consolidate.
For Market Incumbents: Deploy specification-grade polymer chemistry depth to defend road and airfield contracts against emerging bio-based binder entrants. Sika AG and BASF SE anchor premium positioning through tailored bitumen emulsion formulations for FAA freeze-thaw resistance standards. Backward integration into petrochemical feedstock hedges margin compression from acrylamide price volatility. For New Entrants and Emerging Players: Capture bio-based binder white space in the Netherlands and California pilot programs where enzyme-induced carbonate precipitation advances carbon-negative positioning. Ground improvement applications beneath coastal Chinese high-rise clusters offer the most penetrable segment for geotechnical engineering specialists. Partner with intelligent compaction technology providers to bundle equipment-stabilizer offerings for design-build-maintain contracts. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional cement-lime distributors in Brazil and India facing margin squeeze from centralized NHAI and federal highway authority procurement. Five-to-ten year viability hinges on portfolio diversification into polymer modification or geosynthetic systems. Monitor MEE carbon intensity disclosure enforcement as the inflection signal for accelerated specification tier shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Feedstock | Captive acrylamide supply shields SNF Holding Company from crude oil derivative price swings. |
| Green Manufacturing Transition | Enzyme-induced carbonate precipitation programs in the Netherlands advance carbon-negative positioning against REACH restrictions. |
| Long-term Supply Agreement | Master supply agreements with China's state rail corporation lock in geosynthetic volumes for high-speed rail corridors. |
| Joint Venture | Strategic partnerships with intelligent compaction providers bundle equipment-stabilizer offerings for German Autobahn contracts. |
| Certification Investment | ISO 10319 tensile testing and ISO 13438 durability standards accelerate geosynthetic product launches for European erosion control. |
Study Parameters
Independent corroboration across geotechnical engineering directors, road authority procurement leads, polymer R&D specialists, and construction contractor operations managers underwrites the qualitative findings. Primary interviews with soil mechanics practitioners and ground improvement program executives combined with secondary validation from BIS compressive strength benchmarks, MEE carbon intensity disclosures, EPA leachable heavy metal guidelines, and SEC 10-K filings from multinational chemical conglomerates. Bottom-up project pipeline tracking and top-down infrastructure budget allocation triangulation anchor volume estimates.
Comparable-period anchoring to historical cement-lime blend penetration rates and polymer modification adoption curves structured the forecast window across the analysis window. Segmentation dimensions modeled include product type tier, application load intensity, technology intervention depth, and end-user procurement concentration. CAGRs derived from slope analysis of specification shift trajectories and carbon accounting policy implementation timelines. Industry-specific inputs incorporated REACH microplastic restriction deadlines and FAA bitumen emulsion specification revisions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical feedstock price trajectories and geotechnical engineer supply constraints. Forecasts reflect documented assumptions on MEE enforcement intensity and BIS benchmark expansion. Practitioners should monitor centralized procurement fund negotiations and bio-based binder pilot-scale deployment for early signals of specification tier migration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
US Terracotta Cladding Market
Building & Construction Materials
GCC Concrete Blocks Market
Building & Construction Materials
Concrete Repair Product Market
Building & Construction Materials
Building Vibration Isolation Market
Building & Construction Materials
Balustrade Market
Building & Construction Materials
United States Roofing Market
Building & Construction Materials
Steel Sandwich Panels Market
Building & Construction Materials
Plasterboard Market
Building & Construction Materials
EPS Sandwich Panels Market
Building & Construction Materials
Facade Materials Market
Building & Construction Materials
Construction Bolts Market
Building & Construction Materials
North America Plywood Market
Building & Construction Materials
Autoclaved Aerated Concrete (AAC) Blocks Market
Building & Construction Materials
Point Fixing Glass Curtain Wall Market
Building & Construction Materials
Architectural Window Films Market
Building & Construction Materials
Middle-East and Africa Gypsum Board Market