
 Warehouse Freight Elevators Market | 2026-2036
Warehouse Freight Elevators Market Size, Share, and Industry Trends Forecast 2026-2036
Warehouse Freight Elevators Market Outlook
Heavy-duty 5000 kg capacity specifications is reorganizing competitive dynamics in warehouse freight elevators. Otis Elevator Company leverages its global service infrastructure to dominate aftermarket modernization contracts. ThyssenKrupp anchors European demand through specialized hydraulic systems for cold-storage facilities. Schindler Group differentiates via IoT-enabled predictive maintenance platforms integrated into distribution center workflows.
Warehouse freight elevators are industrial vertical transportation systems engineered to move palletized goods, bulk materials, and heavy equipment between facility floors, typically operating at speeds of 30-150 feet per minute with reinforced car platforms and dual-brake safety architectures. Electric traction systems lead installed base volumes due to energy efficiency and height flexibility, while hydraulic units retain margin concentration in low-rise heavy-lift applications below six stories. Prefabricated and modular installation types are gaining share as developers compress construction schedules for logistics centers.
ASME A17.1 standards in the United States, EN 81-20/50 in Europe, and GB 7588 in China govern load-testing protocols, door-locking mechanisms, and emergency braking systems, creating compliance-driven replacement cycles for pre-2015 installations. OSHA workplace safety directives and EU machinery directives further mandate operator training and periodic inspection intervals. Facility operators must evaluate total cost of ownership across energy consumption, maintenance contracts, and regulatory upgrade timelines when specifying new vertical transport infrastructure.
Market Dynamics
ASME A17.1 and EN 81-20/50 compliance deadlines are forcing facility operators into accelerated replacement cycles, compressing the effective lifespan of pre-2015 hydraulic and traction installations across major logistics corridors.
Growth Catalysts
- E-commerce fulfillment density:Same-day delivery networks in the United States and Germany require vertical transport systems capable of 100+ cycles daily. Automated storage and retrieval systems cannot function without synchronized freight elevator throughput.
- EN 81-20/50 retrofit mandates:European cold-storage facilities must upgrade door-locking mechanisms and emergency braking systems by fixed compliance windows. This creates non-discretionary demand for modernization contracts.
- Prefabricated modular installation:Developers constructing logistics centers in China compress construction schedules by 40% using factory-assembled hoistway modules. This method reduces on-site welding and concrete curing time.
Market Restraints
- Steel and copper input volatility:Car platform reinforcement and traction motor windings depend on commodity metals with 18-month price swings. Manufacturers cannot fully pass through material cost spikes in competitive bidding environments.
- Specialized hydraulic component concentration:High-pressure cylinder seals and precision valves for heavy-lift applications source from a narrow German and Japanese supplier base. Disruption risks concentrate in sub-6-story cold-storage specifications.
- Substitution by high-capacity spiral conveyors:Palletized goods below 2,000 kg increasingly move via continuous vertical conveyors in new-build distribution centers. These systems eliminate shaft construction and reduce energy consumption.
Strategic Opportunities
- India logistics corridor penetration:The country's PLI scheme for warehousing infrastructure creates first-mover advantage for traction system providers. Current installed base remains below 15% of addressable stock.
- Predictive maintenance convergence:IoT sensor arrays and machine learning analytics combine to forecast brake wear and rope degradation. This shifts revenue from reactive service calls to subscription-based uptime guarantees.
- GB 7588 modernization wave:China's 2015 safety code revisions trigger replacement demand in tier-one manufacturing zones. Local facility operators prioritize energy-efficient permanent magnet motors over legacy DC systems.
Industry Challenges
- Certified elevator technician scarcity:ASME QEI-1 qualified inspectors and licensed mechanics cannot scale with retrofit demand in the United States. Training pipeline gaps extend project commissioning timelines.
- Legacy control system integration:Warehouse management software protocols from the 1990s lack API compatibility with modern destination dispatch algorithms. Custom middleware development consumes 15-20% of project engineering hours.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warehouse Freight Elevators Market |
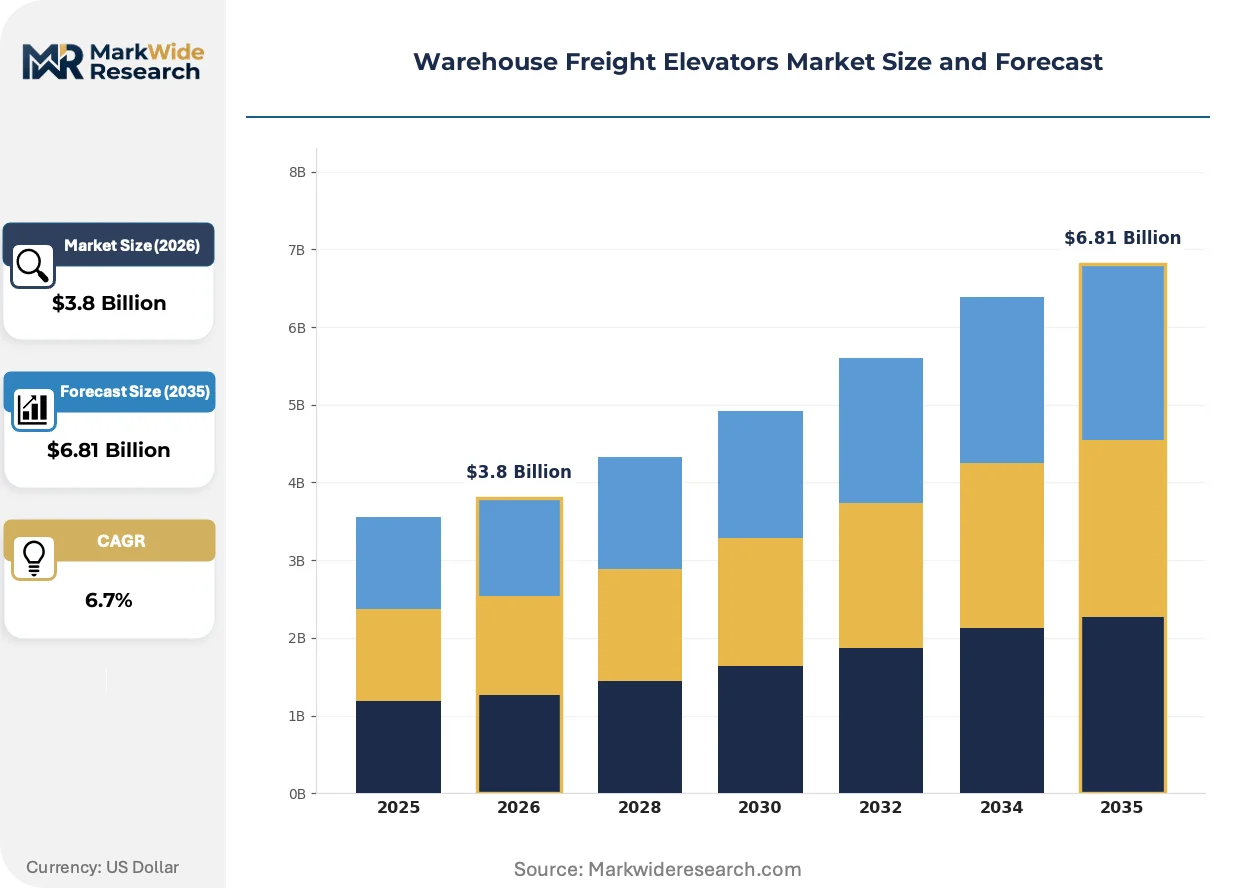
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Electric, Pneumatic, Chain Driven Installation Type: Onsite, Prefabricated, Modular, Custom-Built End User: Warehouses, Logistics Centers, Distribution Centers, Manufacturing Facilities Capacity: 500 kg, 1000 kg, 2000 kg, 5000 kg |
| Companies Covered | Mitsubishi Electric, Fujitec, Otis Elevator Company, Stanley Elevator, Hyundai Elevator, Kone, ThyssenKrupp, American Custom Lifts, Schindler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warehouse Freight Elevators Market Strategic Shifts
Permanent magnet synchronous motor technology is decomposing the traditional tradeoff between energy efficiency and heavy-load capacity. This shift enables new performance tiers that reshape competitive bidding criteria.
Machine-room-less traction drives eliminate the overhead penthouse requirement, reclaiming 200-400 square feet per shaft for revenue-generating storage. Third-party logistics operators in Germany and the Netherlands adopt these systems for brownfield retrofits where ceiling height constraints previously blocked modernization. The technology is decomposing the distinction between new construction and retrofit specifications.
OSHA's updated powered industrial truck operator training standards indirectly elevate freight elevator safety requirements. Facilities must demonstrate coordinated lockout-tagout procedures between lift systems and loading equipment. Distribution centers in the United States respond by specifying dual-redundant brake architectures and infrared door protection edges that exceed minimum code.
Buyer consolidation among mega-warehouse developers concentrates procurement authority with firms operating 10+ million square foot portfolios. These entities unbundle equipment supply from installation and maintenance, issuing separate RFPs for each phase. The practice is most visible in China's Yangtze River Delta logistics cluster, where state-backed developers standardize on specific traction motor specifications across multiple facilities.
Warehouse Freight Elevators Market Segmentation
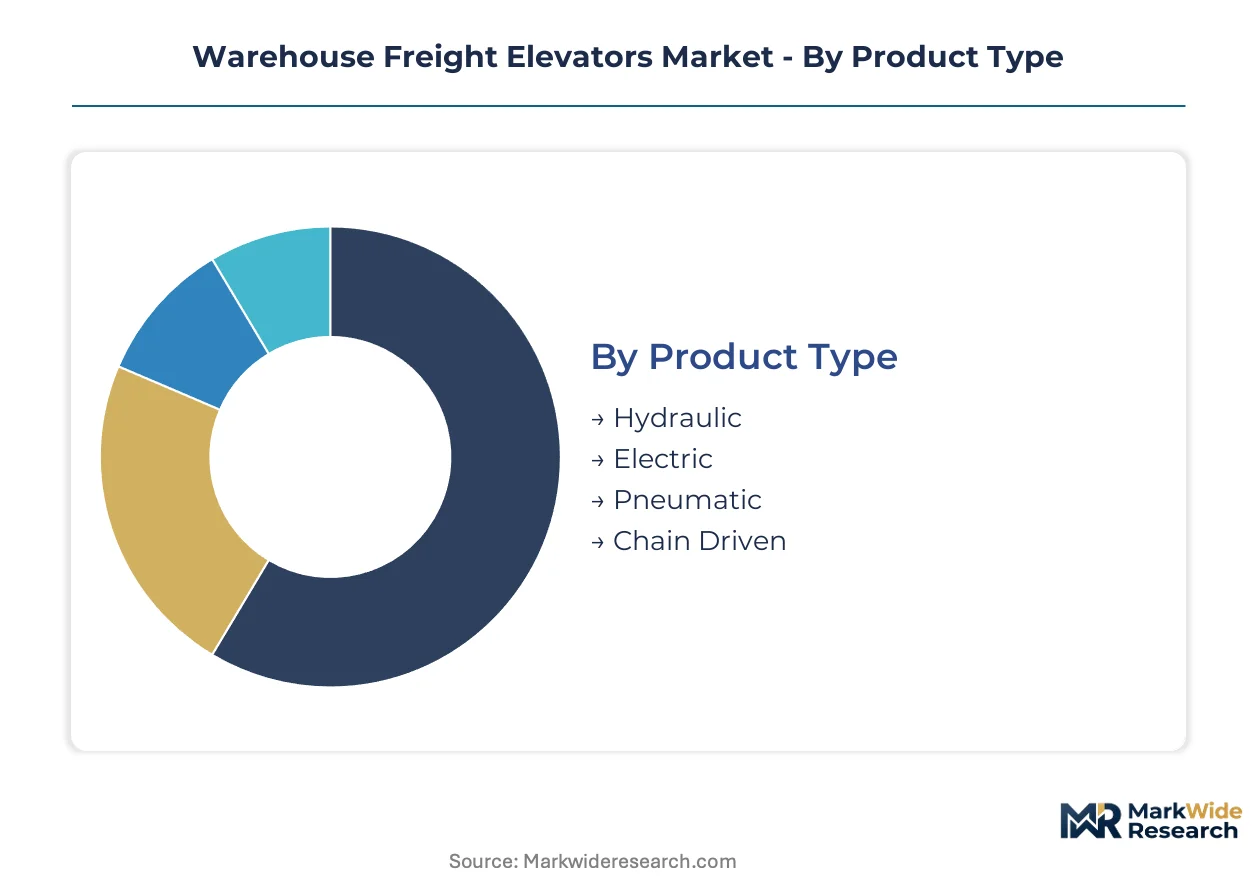
Warehouse freight elevator procurement decisions pivot on facility height, load profile, and construction timeline. Segment boundaries blur as machine-room-less traction systems encroach on hydraulic territory and modular installation methods compress traditional build schedules.
Product Type:
Margin pools concentrate in electric traction systems where permanent magnet motor technology commands pricing premiums over legacy DC architectures.
- Hydraulic:High-pressure piston-cylinder assemblies excel in low-rise heavy-lift applications below six stories. Cold-storage facilities in Germany specify these systems for 5000 kg pallet loads where precise floor leveling prevents condensation ingress.
- Electric:Traction sheave and counterweight configurations dominate installations above four stories. United States e-commerce fulfillment centers specify these for 100+ daily cycles where energy recovery drives reduce operating costs.
- Pneumatic:Vacuum-driven tube systems serve document and small-parts transport in mixed-use facilities. Limited penetration in pure warehouse environments due to 200 kg maximum payload constraints.
- Chain Driven:Roller chain and sprocket mechanisms occupy niche applications with extreme temperature swings. Found in unheated storage annexes where hydraulic fluid viscosity would compromise performance.
Electric holds installed capacity. Hydraulic is rotating up the share rankings in cold-chain specifications.
Installation Type:
Construction velocity requirements are fragmenting the traditional onsite fabrication model across logistics corridor developments.
- Onsite:Conventional steel hoistway erection and concrete pit construction remain standard for retrofits with irregular shaft dimensions. Skilled welding crews extend commissioning timelines by 6-8 weeks versus factory alternatives.
- Prefabricated:Complete hoistway modules arrive with pre-installed guide rails and landing doors. Yangtze River Delta logistics clusters in China deploy these to compress build schedules by 40%.
- Modular:Interlocking panel systems permit phased capacity expansion. Third-party logistics operators in the Netherlands favor these for brownfield conversions where future mezzanine additions are probable.
- Custom-Built:Engineered-to-order specifications address non-standard ceiling heights or seismic zones. Premium pricing reflects structural engineering validation for ASME A17.1 special applications.
Onsite retains retrofit dominance. Prefabricated is climbing the fastest in new-build logistics parks.
End User:
Automation intensity varies sharply across facility types, dictating integration complexity and service contract structures.
- Warehouses:General storage operations with intermittent vertical transport needs. Lower cycle counts permit simpler two-speed door operators and standard brake configurations.
- Logistics Centers:Multi-tenant facilities with heterogeneous load profiles. Destination dispatch algorithms prioritize throughput over individual tenant preferences.
- Distribution Centers:Same-day fulfillment networks synchronize elevator cycles with automated storage and retrieval systems. United States operators specify redundant controllers to prevent single-point-of-failure downtime.
- Manufacturing Facilities:Heavy equipment transport between production floors. GB 7588 compliance in China's tier-one manufacturing zones drives replacement demand for pre-2015 installations.
Distribution centers command specification authority. Manufacturing facilities are gaining share fastest on safety code retrofit waves.
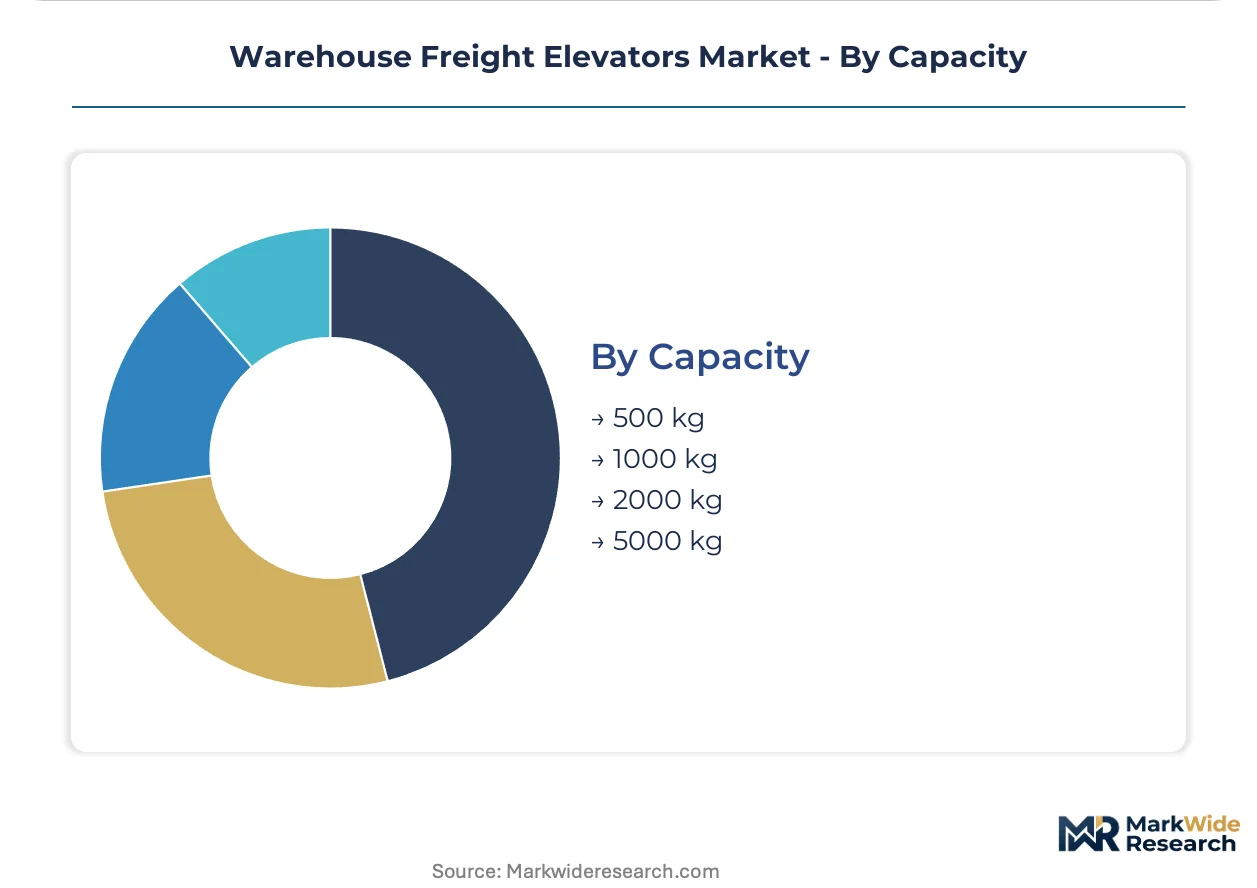
Capacity:
Load rating selection directly determines motor sizing, brake thermal capacity, and platform reinforcement costs.
- 500 kg:Document totes and parcel sacks in administrative mezzanines. Limited warehouse penetration as pallet dimensions typically exceed this threshold.
- 1000 kg:Single-pallet transport with manual jack loading. Mid-size logistics centers in India specify these for PLI scheme warehousing infrastructure where capital constraints prevail.
- 2000 kg:Dual-pallet or powered industrial truck compatibility. European cold-storage facilities pair these with EN 81-20/50 compliant door-locking upgrades.
- 5000 kg:Heavy machinery and bulk material handling. Otis and ThyssenKrupp compete intensely for these specifications where service contract attach rates exceed 80%.
2000 kg anchors volume shipments. 5000 kg is expanding most quickly on automation density requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturing clusters in Germany and China drive net positive trade balances in heavy-lift vertical transport equipment, while import-dependent logistics markets in India and the United States absorb foreign-sourced traction systems and hydraulic components.
United States
OSHA workplace safety directives and same-day delivery fulfillment networks generate demand for 100+ daily cycle elevators. ASME A17.1 compliance deadlines force accelerated replacement of pre-2015 hydraulic installations. The Inland Empire logistics corridor in Southern California concentrates new-build distribution center specifications for redundant controller architectures.
Germany
EN 81-20/50 retrofit mandates and cold-storage automation density anchor European demand. The country's national machinery regulator enforces strict door-locking mechanism upgrades by fixed compliance windows. The Ruhr industrial belt hosts brownfield modernization projects where machine-room-less traction systems reclaim penthouse space for revenue-generating storage.
China
GB 7588 safety code revisions trigger replacement waves in tier-one manufacturing zones. The Ministry of Industry and Information Technology prioritizes energy-efficient permanent magnet motors over legacy DC systems. Yangtze River Delta logistics clusters deploy prefabricated hoistway modules to compress construction schedules by 40 percent.
India
PLI scheme warehousing infrastructure creates first-mover opportunity for traction system providers. The Bureau of Indian Standards establishes load-testing protocols for emerging logistics corridors. Maharashtra and Gujarat industrial zones specify 1000 kg capacity units where capital constraints limit heavy-lift specifications.
Japan
Automated storage and retrieval system integration demands synchronized freight elevator throughput. METI efficiency standards accelerate permanent magnet synchronous motor adoption. Osaka-Kobe manufacturing belt facilities specify precision floor leveling for semiconductor and electronics component transport.
Warehouse Freight Elevators Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and service infrastructure dimensions. The vendor base organizes around three tiers: diversified industrial conglomerates with full vertical portfolios, elevator-specific manufacturers with regional density, and component specialists supplying hydraulic cylinders and traction motors. Strategic moves concentrate on predictive maintenance platform development and prefabricated installation capability acquisition.
Within the diversified conglomerate tier, Mitsubishi Electric and ThyssenKrupp exemplify scale-driven positioning through integrated manufacturing and service networks. Otis Elevator Company occupies a distinctive position between listed industrial parent structures and pure-play vertical transport focus. These three anchors represent divergent approaches to aftermarket revenue capture and modernization contract attach rates.
| Leading Market Players |
|---|
| Mitsubishi Electric |
| Fujitec |
| Otis Elevator Company |
| Stanley Elevator |
| Hyundai Elevator |
| Kone |
| ThyssenKrupp |
| American Custom Lifts |
| Schindler Group |
| Others |
Value Chain & Pricing Dynamics
Permanent magnet synchronous motor substitution for legacy DC traction systems simultaneously relocates manufacturing gravity toward East Asian motor suppliers and compresses pricing premiums previously commanded by European drive specialists. This input transition reshapes procurement economics as buyers reassess total cost of ownership across energy recovery performance and maintenance contract structures.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for warehouse freight elevator systems. Three-tier pricing structure across premium, standard, and economy levels separates ASME A17.1-certified installations with predictive maintenance bundles from basic EN 81-20/50 compliant configurations. Price differentiation centers on certification grade and after-sales service bundling. Cost compression in standard-tier specifications is intensifying because Chinese manufacturers are scaling permanent magnet motor production. Third-party logistics operators with 10+ million square foot portfolios demonstrate highest price sensitivity through unbundled RFPs, while cold-storage facilities in Germany show lowest sensitivity due to EN 81-20/50 compliance mandates.
Supply Chain Analysis
Strategic stockpiling of high-pressure hydraulic cylinder seals distinguishes German and Japanese suppliers from just-in-time component flows in electric traction assembly. Geographic supply concentration centers on China for permanent magnet motors, Germany for precision hydraulic valves, and Japan for traction sheave bearings. Raw material dependencies draw from copper for motor windings, steel for car platform reinforcement, and rare earth elements for magnet production. Single-source vulnerability concentrates in sub-6-story cold-storage hydraulic specifications where German seal suppliers dominate. Distribution runs through OEM-direct channels for major logistics developers and regional elevator contractors for retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-capacity spiral conveyors threaten palletized goods transport below 2,000 kg, forcing elevator incumbents to defend heavy-lift positioning above this threshold. Substitution defense requires demonstrating total cost superiority across shaft construction, energy consumption, and integration complexity.
For Market Incumbents: Secure predictive maintenance platform attach rates above 80% in 5000 kg capacity specifications where Otis and ThyssenKrupp currently compete. Acquire prefabricated installation capabilities to compress commissioning timelines against modular construction methods. Backward integration into permanent magnet motor production reduces exposure to Chinese supplier concentration and supports pricing power in energy-efficient specifications. For New Entrants and Emerging Players: ASME QEI-1 certification fast-track programs open procurement access to United States distribution center retrofits where qualified inspector scarcity extends incumbent project timelines. Target India's PLI scheme warehousing infrastructure where traction system penetration remains below 15% of addressable stock. Pursue machine-room-less traction specifications for brownfield European conversions where ceiling height constraints previously blocked modernization. For Investors and Strategic Acquirers: The market sits at a compliance-driven replacement phase that favors service infrastructure scale over pure manufacturing capacity. Long-term viability over the next decade rests on aftermarket modernization contract density rather than new-build equipment margins. Acquisition candidates should demonstrate predictive maintenance platform deployment and regional technician training pipeline control. Watch EN 81-20/50 retrofit deadline extensions as inflection indicator for European demand timing.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Deployment | IoT sensor arrays at Kone and Schindler shift revenue from reactive calls to subscription uptime guarantees. |
| Prefabricated Hoistway Capability Acquisition | Factory-assembled modules compress Yangtze River Delta construction schedules by 40 percent versus onsite welding. |
| Permanent Magnet Motor Manufacturing Scale-Up | Mitsubishi Electric and Hyundai Elevator reduce rare earth dependency through magnet recycling partnerships. |
| ASME QEI-1 Technician Training Pipeline Expansion | Stanley Elevator addresses certified inspector scarcity extending United States project commissioning timelines. |
| Cold-Storage Hydraulic Specialization Investment | ThyssenKrupp defends margin concentration in German EN 81-20/50 retrofit mandates below six stories. |
Study Parameters
A spread of perspectives from facility maintenance directors, OEM procurement teams, elevator contractor operations managers, and aftermarket service heads converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through ASME A17.1 compliance filings, EN 81-20/50 regulatory updates, GB 7588 revision notices, SEC 10-K equipment disclosures, and customs trade data for vertical transport machinery. Bottom-up installation volume estimates triangulated against top-down logistics construction spending across the United States, Germany, China, and India.
Segmentation dimensions modeled include drive type, installation method, end-user facility category, load capacity tier, and regional regulatory framework across the projection horizon. CAGRs derived from logistic facility construction pipelines, e-commerce fulfillment network expansion, and safety code compliance deadline clustering. Industry-specific forecast inputs incorporate permanent magnet motor adoption curves and prefabricated hoistway penetration rates in new-build logistics parks.
Decision-makers should treat outputs as directional under assumptions of continued e-commerce fulfillment density growth and fixed ASME A17.1/EN 81-20/50 compliance windows; material deviation would warrant model refresh. Forecasts reflect base-case regulatory enforcement and commodity price stability assumptions. Specific risk factors include steel and copper input volatility, certified technician training pipeline gaps, and spiral conveyor substitution acceleration in sub-2,000 kg applications. Revision becomes warranted when high-capacity vertical conveyor penetration crosses 15 percent of new-build distribution center specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Wagon Tipplers Market
Material Handling Equipment
Stacker Crane Market
Material Handling Equipment
Eye and Eye Turnbuckle Market
Material Handling Equipment
Industrial Belt Drives Market
Material Handling Equipment
Manual Lifting Mobile Light Tower Market
Material Handling Equipment
Conveying Equipment Market
Material Handling Equipment
Pharmaceutical Material Handling Equipment Market
Material Handling Equipment
Scraper Conveyor Market
Material Handling Equipment
Pipelayer Market
Material Handling Equipment
Sweep Depalletizers Market
Material Handling Equipment
Linear Slides Market
Material Handling Equipment
Global Loading Dock Bumpers Market
Material Handling Equipment
Material Rack Correction Machine Market
Material Handling Equipment
Trencher Attachments Market
Material Handling Equipment
Heavy Duty Ramp Market
Material Handling Equipment
Rotating Fork Clamp Market