
 Cement Grinding Aids Market | 2026-2036
Cement Grinding Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Cement Grinding Aids Market Analysis
Polymer-based additive formulations is rewriting the economics of cement finish grinding, enabling producers to hit target Blaine fineness at reduced energy intensity. CHRYSO leverages its vertical integration into raw material supply to control formulation consistency across European and African markets. Sika AG anchors its position through R&D intensity focused on alkanolamine chemistry and compatibility with supplementary cementitious materials. BASF SE differentiates via global manufacturing scale that supports just-in-time delivery to multinational cement producers operating across multiple continents.
Cement grinding aids are surface-active chemical additives, typically comprising triethanolamine, triisopropanolamine, or glycol-based compounds, dosed at 0.01–0.05% by weight of cement to reduce agglomeration during ball mill and vertical roller mill operations. Their primary industrial purpose is to lower specific energy consumption per ton of cement while improving early-age compressive strength development. Ready-mix cement applications dominate volume consumption as contractors prioritize pumpability and extended slump retention in large-scale pours. Infrastructure end-use represents the fastest-expanding demand pool, driven by highway, dam, and rail projects requiring high-durability concrete with specified 28-day strength grades.
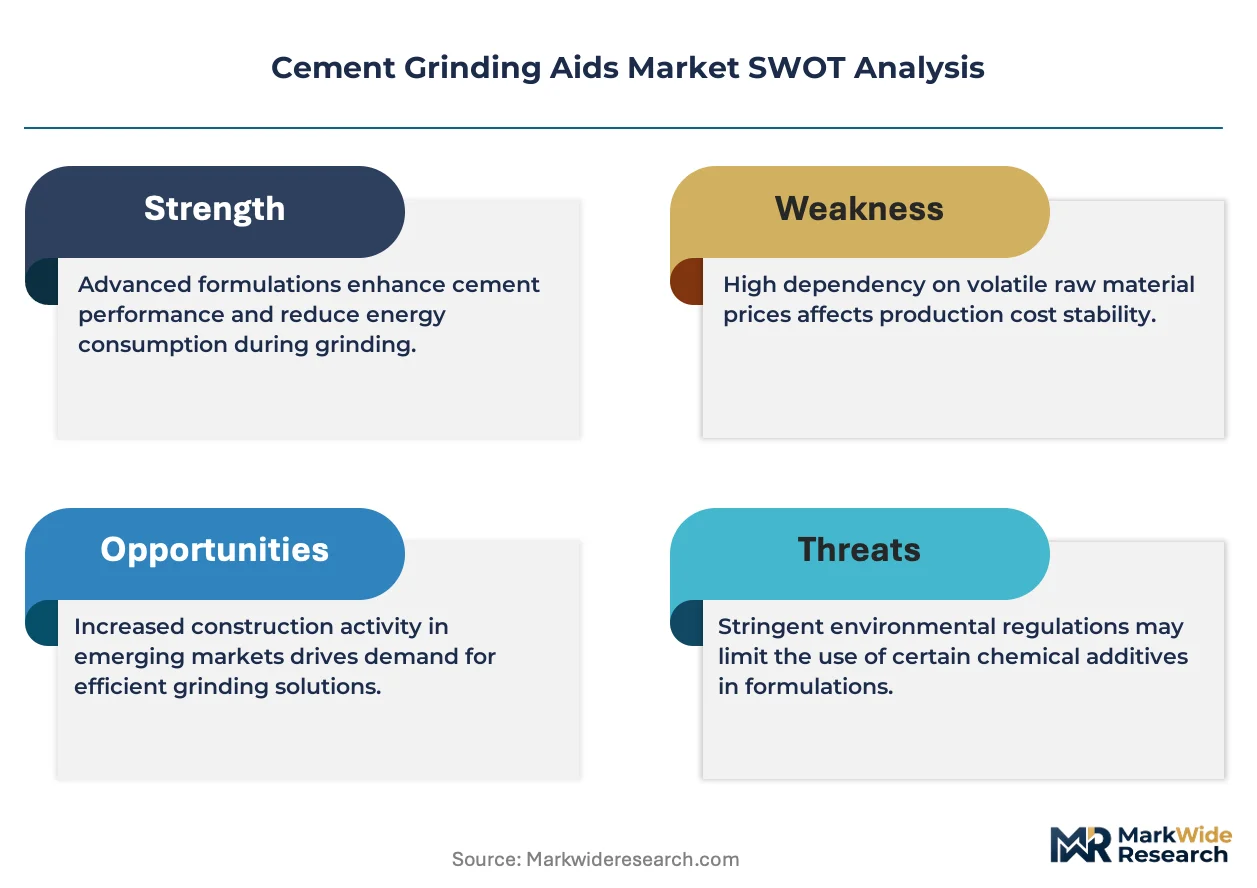
The EU Green Deal and REACH frameworks restrict volatile organic compound content in construction chemicals, compelling reformulation toward bio-derived and low-emission grinding aid chemistries. EPA regulations in the United States govern air emissions from cement kilns and associated material handling, indirectly shaping additive selection through energy-efficiency mandates. India's BIS certification requirements for admixtures establish performance benchmarks that filter market access for imported formulations. Stakeholders must monitor how carbon border adjustment mechanisms and evolving clinker substitution targets reshape the technical specifications that grinding aid suppliers must meet.
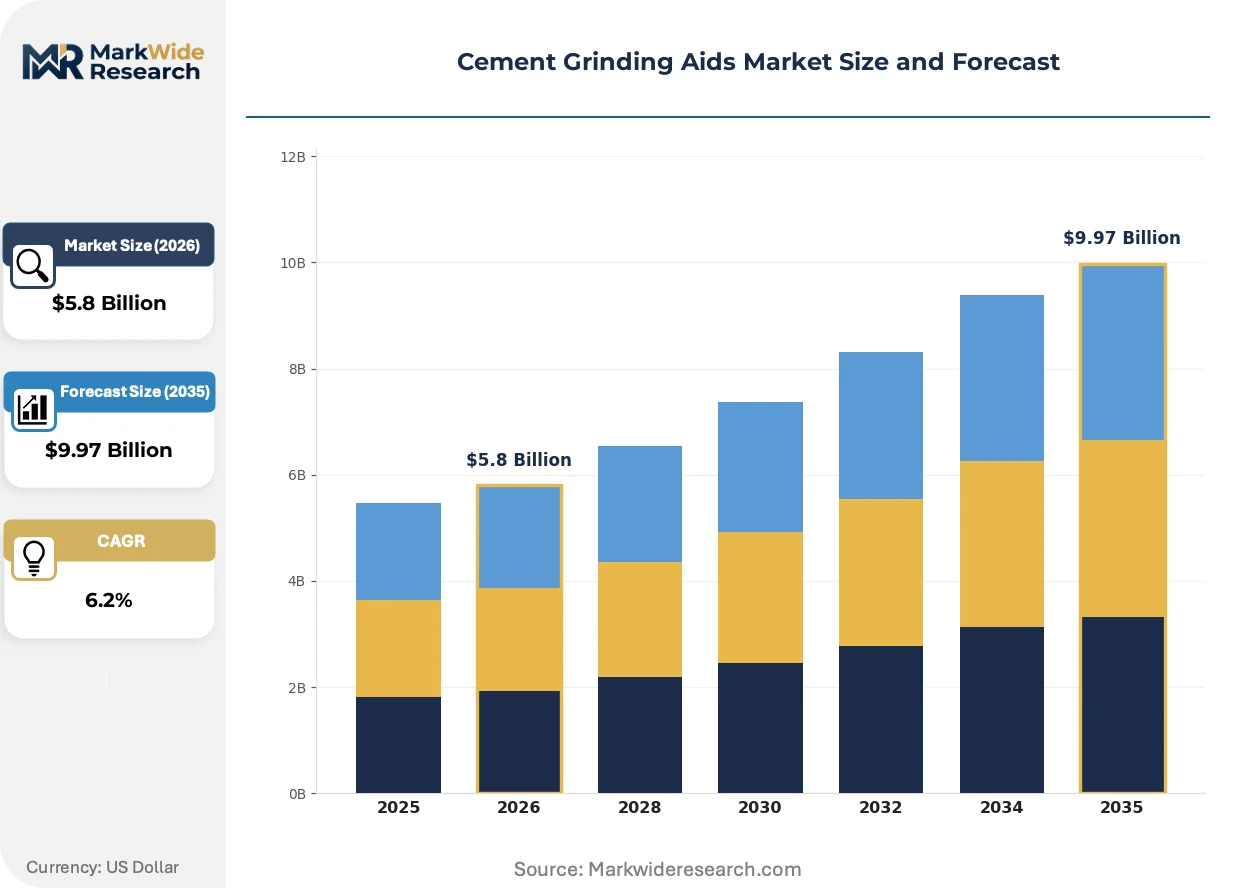
Market Dynamics
Clinker substitution mandates under the EU Green Deal are forcing grinding aid suppliers to reformulate for lower-carbon cement blends, compressing margins while opening premium positioning for bio-compatible chemistries.
Growth Catalysts
- India's National Infrastructure Pipeline:Record cement consumption across transportation corridors is pulling grinding aid volumes into ready-mix and precast applications.
- REACH framework evolution:ECHA's tightening volatile organic compound limits are accelerating adoption of bio-derived alkanolamine alternatives in European finish grinding operations.
- Vertical roller mill penetration:Southeast Asian producers upgrading from ball mills require specialized additive packages optimized for high-pressure grinding bed dynamics.
Market Restraints
- Ethylene oxide feedstock volatility:Triethanolamine production costs swing with petrochemical cracking margins, squeezing formulation economics for mid-tier suppliers.
- Chinese glycol overcapacity:Concentrated diethylene glycol supply from Shandong and Jiangsu provinces creates price instability that distorts regional procurement decisions.
- Technical ceiling on clinker reduction:Current alkanolamine chemistries hit performance limits below 50% clinker ratios, capping emission reduction claims.
Strategic Opportunities
- Vietnam's Mekong Delta megaprojects:Underpenetrated grinding aid adoption in provincial cement plants serving Can Tho and Long An infrastructure corridors.
- Carbon border adjustment mechanism:EU CBAM implementation creates first-mover advantage for suppliers certifying cradle-to-gate carbon intensity of additive packages.
- Polycarboxylate-grinding aid hybrids:Convergence of concrete superplasticizer and finish-grinding chemistries enables single-dose solutions for integrated cement-concrete producers.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in cement-admixture compatibility testing is concentrated among retiring European technical staff.
- BIS certification timelines:India's 90-120 day admixture approval process delays market entry for imported grinding aid innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cement Grinding Aids Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.97 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-Mix Cement, Precast Concrete, Portland Cement, Specialty Cements Application: Residential, Commercial, Infrastructure, Industrial End User: Contractors, Builders, Engineers, Construction Companies Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | CHRYSO, Thermax Global, Sika AG, GCP Applied Technologies, Master Builders Solutions, Fosroc, BASF SE, Akkim Kimya, MAPEI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cement Grinding Aids Market Emerging Trajectories
Grinding aid innovation is pivoting from energy-efficiency claims toward carbon-accounting transparency, with formulation chemistry and certification protocols converging to meet procurement specifications from decarbonization-focused infrastructure developers.
Biopolymer-derived grinding aids synthesized from lignin sulfonate and agricultural waste streams are rendering obsolete petroleum-based triethanolamine formulations in European and North American markets. Multinational cement producers with Science Based Targets initiative commitments are specifying these chemistries in tender documents. The shift is compressing addressable volume for conventional alkanolamine suppliers while fragmenting procurement across sustainability-tiered supply tiers.
REACH Annex XVII restrictions on N,N-dimethylethanolamine and related tertiary amines are compelling reformulation toward secondary alkanolamines and amino alcohol blends with lower aquatic toxicity profiles. German and French cement producers face the tightest compliance deadlines under national implementation schedules. Grinding aid suppliers are responding by accelerating registration dossiers for alternative chemistries under the EU's updated classification, labelling and packaging regulation.
Buyers are consolidating additive procurement under long-term performance contracts that bundle grinding aids with technical service and mill optimization audits. Integrated cement producers in India and Indonesia are displacing spot-market purchasing with multi-year agreements tying pricing to energy savings guarantees. This shift is most visible in infrastructure-focused subsidiaries of Holcim and Heidelberg Materials operating across Southeast Asian markets.
Cement Grinding Aids Market Segmentation
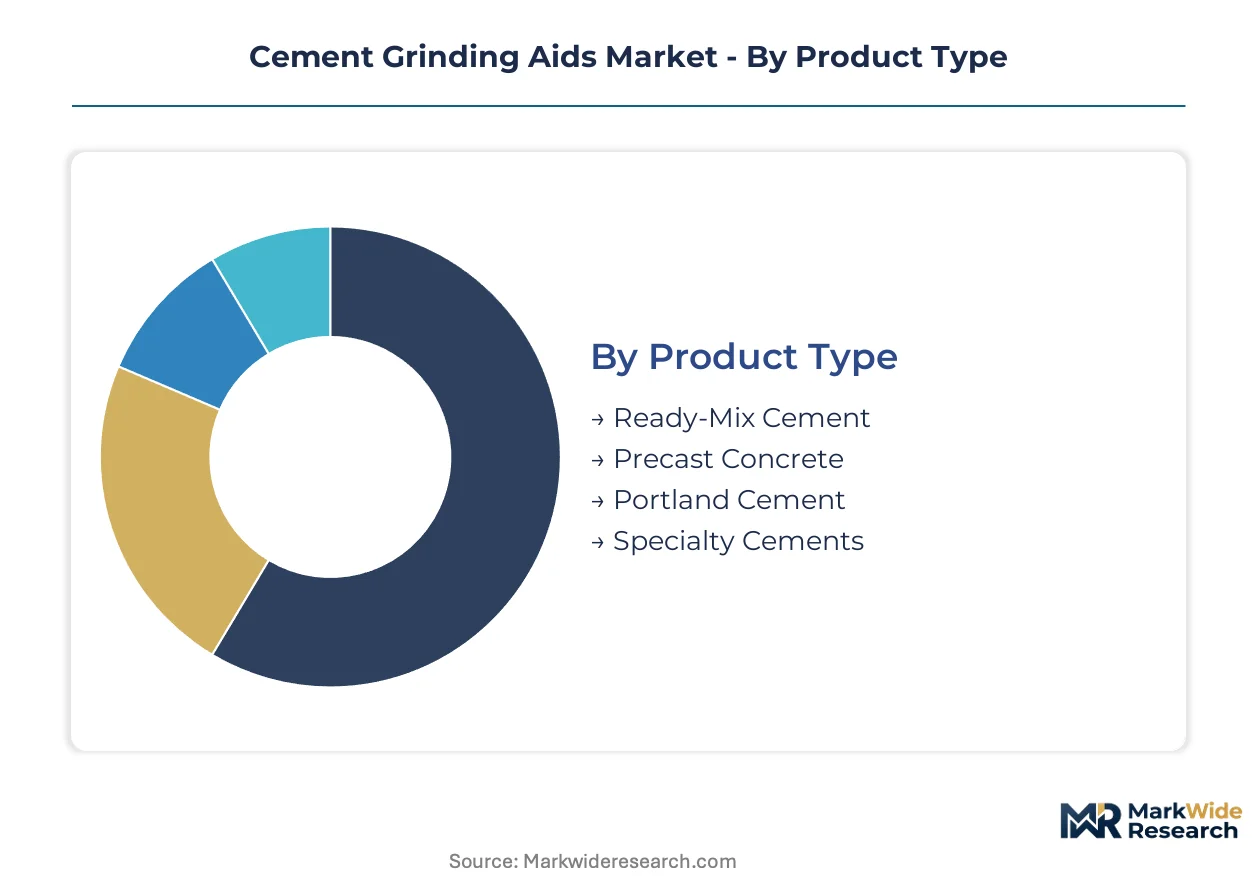
Cement grinding aids segment across formulation chemistry, application intensity, and procurement patterns. Each dimension carries distinct margin profiles and technical service requirements that reshape supplier engagement models.
Product Type:
Mature commodity formulations coexist with emerging specialty blends engineered for low-clinker cement systems.
- Ready-Mix Cement:Glycol-alkanolamine blends dominate this segment, optimized for extended slump retention and pumpability in large-scale pours. Demand concentrates in India's National Infrastructure Pipeline corridors, where contractors specify grinding aids compatible with fly ash and slag blends for transportation megaprojects.
- Precast Concrete:High-early-strength formulations featuring triisopropanolamine chemistry enable rapid form stripping and accelerated curing cycles. European producers under EU Green Deal clinker reduction mandates are pulling specialized additive packages for carbon-reduced precast elements in commercial building envelopes.
- Portland Cement:Conventional triethanolamine-based grinding aids serve ball mill operations with standard fineness targets.
- Specialty Cements:Oil-well and sulfate-resistant cement variants require customized additive packages with controlled setting behavior.
Ready-Mix Cement handles the majority of throughput; Specialty Cements is climbing the fastest on share as decarbonization specifications proliferate.
Application:
Volume scale separates infrastructure-grade procurement from fragmented residential spot purchasing.
- Infrastructure:Highway, dam, and rail projects specify grinding aids certified for 28-day strength grades and durability metrics. Southeast Asian megaprojects in Vietnam's Mekong Delta and Indonesia's Trans-Java corridor are absorbing premium additive volumes under performance-guaranteed supply contracts.
- Commercial:High-rise concrete demands grinding aids compatible with polycarboxylate superplasticizers for extended workability windows. German and French cement producers specify REACH-compliant bio-derived formulations for commercial developments targeting Science Based Targets initiative commitments.
- Residential:Cost-sensitive single-family construction drives commodity glycol-based grinding aid consumption.
- Industrial:Mining and manufacturing floor slabs require abrasion-resistant cement systems with specialized additive packages.
Infrastructure commands the largest volume position; Commercial is expanding most quickly as green building certifications reshape specification criteria.
End User:
Technical sophistication divides specification authority between design engineers and field contractors.
- Construction Companies:Integrated cement-concrete producers like Holcim and Heidelberg Materials subsidiaries bundle grinding aids with mill optimization audits under multi-year performance contracts. India's infrastructure-focused construction companies are displacing spot-market purchasing with energy-savings-guaranteed agreements.
- Engineers:Structural designers specify grinding aid chemistries in tender documents to achieve target compressive strength development curves. European engineering consultancies are embedding cradle-to-gate carbon intensity requirements for additive packages into infrastructure tender specifications.
- Contractors:Ready-mix operators prioritize pumpability and slump retention in daily procurement decisions.
- Builders:Small-scale residential developers rely on distributor recommendations for commodity formulations.
Construction Companies represent the dominant procurement volume; Engineers are gaining specification influence fastest as performance-based contracting spreads.
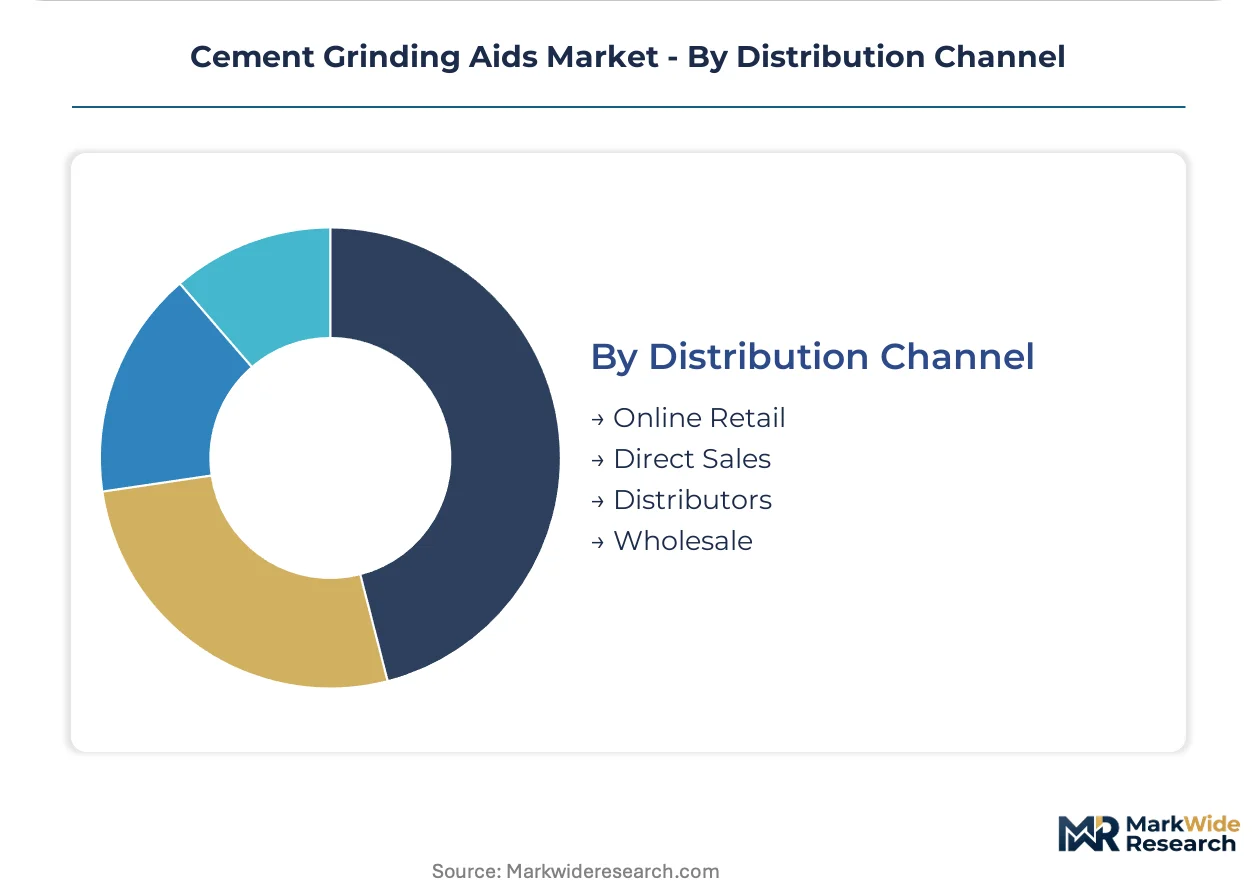
Distribution Channel:
Supply chain configuration separates technical service-intensive direct sales from transactional wholesale movement.
- Direct Sales:Multinational cement producers procure grinding aids through technical service partnerships including mill audits and formulation customization. BASF SE and Sika AG anchor this channel with global manufacturing scale supporting just-in-time delivery across multiple continents.
- Distributors:Regional chemical distributors serve mid-tier cement plants with standardized alkanolamine formulations and local inventory buffers. Indian distributors navigate BIS certification timelines to bridge imported grinding aid innovations to domestic producers.
- Online Retail:Emerging digital procurement platforms aggregate small-volume orders from independent ready-mix operators.
- Wholesale:Bulk glycol and amine commodity traders supply price-sensitive provincial cement plants.
Direct Sales captures the highest-value transactions; Distributors maintain the broadest geographic coverage across emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated cement-concrete producers and construction consortiums dominate procurement across high-volume markets, with specification authority concentrating among multinational subsidiaries operating under energy-savings-guaranteed contracts.
India
The National Infrastructure Pipeline drives record cement consumption across transportation corridors and urban development zones. BIS certification requirements for admixtures establish performance benchmarks that filter market access for imported formulations. Grinding aid volumes concentrate in Maharashtra and Gujarat, where ready-mix and precast applications absorb premium additive packages under multi-year agreements.
Germany
EU Green Deal clinker reduction mandates force producers to reformulate grinding aids for lower-carbon cement blends. REACH Annex XVII restrictions on tertiary amines accelerate adoption of secondary alkanolamine alternatives with lower aquatic toxicity. Industrial demand clusters in North Rhine-Westphalia and Bavaria, where cement producers face the tightest national compliance deadlines.
United States
EPA air emission regulations from cement kilns indirectly shape additive selection through energy-efficiency mandates. Infrastructure investment packages sustain demand for high-durability concrete in highway and rail megaprojects. Procurement concentrates in Texas and California, where integrated producers bundle grinding aids with technical service contracts.
Vietnam
Mekong Delta megaprojects in Can Tho and Long An corridors drive underpenetrated grinding aid adoption among provincial cement plants. Vertical roller mill upgrades from legacy ball mill operations require specialized additive packages for high-pressure grinding bed dynamics. Supply expansion targets plants serving the Trans-Asia Railway and coastal highway networks.
United Arab Emirates
Carbon border adjustment anticipation shapes procurement specifications from decarbonization-focused infrastructure developers. Megaproject concrete demand from NEOM and Red Sea developments specifies certified low-carbon additive packages. Specification authority concentrates in Dubai and Abu Dhabi, where engineering consultancies embed cradle-to-gate carbon intensity requirements into tender documents.
Cement Grinding Aids Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply configurations. The vendor base separates into multinational chemical conglomerates with captive raw material positions, regional formulators serving mid-tier cement plants, and niche specialists targeting low-clinker cement systems. Two strategic archetypes dominate: backward-integrated suppliers controlling formulation consistency through in-house production of key intermediates, and technical-service-intensive operators bundling additives with mill optimization audits. Competitive moves concentrate on geographic expansion through distributor partnerships and portfolio diversification into polycarboxylate-grinding aid hybrids.
Among the multinational chemical conglomerates, BASF SE and Sika AG exemplify scale-driven positioning with global manufacturing footprints supporting just-in-time delivery. CHRYSO occupies a position within the backward-integrated tier, leveraging captive supply of raw materials to control formulation consistency across European and African markets. These three entities represent the dominant competitive archetypes shaping procurement dynamics for multinational cement producers operating across multiple continents.
| Leading Market Players |
|---|
| CHRYSO |
| Thermax Global |
| Sika AG |
| GCP Applied Technologies |
| Master Builders Solutions |
| Fosroc |
| BASF SE |
| Akkim Kimya |
| MAPEI |
| Others |
Supply Flow & Price Mechanics
Ethylene oxide feedstock volatility determines both pricing tier spreads and supply chain shape, compressing margins for mid-tier formulators while rewarding backward-integrated suppliers with captive amine production. This chemical input concentration forces procurement managers to index long-term contracts against petrochemical cracking margins, creating a structural divide between price-stable premium tiers and spot-market-exposed commodity supply.
Pricing Analysis
Cost-plus contracts with ethylene oxide indexation dominate multinational procurement, insulating premium-tier suppliers from feedstock swings while exposing standard-economy tiers to margin erosion. Price differentiation hinges on REACH compliance certification and bundled technical service intensity, with bio-derived formulations commanding premiums over conventional alkanolamines. Cost compression in the standard tier intensifies as Chinese glycol overcapacity floods spot markets. Residential contractors exhibit highest price sensitivity; infrastructure developers under Science Based Targets initiative commitments show lowest.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier financing arrangements for provincial cement plants in Vietnam and Indonesia. Manufacturing concentrates in Germany, China, and India, with Shandong and Jiangsu provinces dominating diethylene glycol output. Raw material dependencies rest on ethylene oxide, triethanolamine intermediates, and lignin sulfonate biopolymers. Single-source vulnerability runs through concentrated petrochemical cracking capacity in the US Gulf Coast. Distribution runs through technical service partnerships for multinationals and regional chemical distributors for mid-tier plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grinding aid procurement is shifting toward service-attach models where mill optimization audits and energy-savings guarantees generate recurring revenue expanding faster than additive volume growth. Technical service contracts now represent the fastest-growing revenue layer as integrated cement producers displace spot purchasing.
For Market Incumbents: Build formulation IP moats around polycarboxylate-grinding aid hybrids to defend against specialty chemical entrants targeting low-clinker cement systems. Deepen backward integration into amino alcohol intermediates to neutralize ethylene oxide cost volatility threatening mid-tier margin positions. Anchor capacity in India to capture National Infrastructure Pipeline volume concentration.
For New Entrants and Emerging Players: Establish a beachhead in Vietnam's Mekong Delta provincial plants where grinding aid penetration remains underdeveloped among vertical roller mill upgrades. Target carbon-accounting certification services as a differentiated entry wedge, bundling cradle-to-gate carbon intensity verification with additive supply. Lead with bio-derived formulations to bypass REACH compliance barriers blocking conventional alkanolamine competitors.
For Investors and Strategic Acquirers: EU CBAM implementation reshapes the acquisition landscape toward suppliers with certified low-carbon additive packages and European manufacturing footprints. Long-term viability centers on formulators capable of serving multinational cement producers with Science Based Targets initiative commitments across the next decade. Acquisition target archetype: regional specialists with BIS certification and Indian distributor relationships. Signal to monitor: carbon border adjustment mechanism enforcement timelines triggering specification cascade.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amino Alcohol Intermediates | Captive supply of triethanolamine precursors neutralizes ethylene oxide cost volatility squeezing mid-tier competitors. |
| Carbon Intensity Certification Program | Cradle-to-gate carbon accounting meets EU CBAM procurement specifications from decarbonization-focused infrastructure developers. |
| Polycarboxylate-Grinding Aid Hybrid Development | Single-dose chemistry convergence captures integrated cement-concrete producers seeking simplified additive procurement. |
| Long-term Technical Service Partnership | Energy-savings-guaranteed contracts displace spot purchasing among Holcim and Heidelberg Materials subsidiaries. |
| Joint Venture with Regional Distributor | BIS certification navigation accelerates market entry for imported grinding aid innovations in Maharashtra and Gujarat corridors. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, combining structured interviews with cement plant managers, procurement leads at integrated producers, formulation chemists, and regional chemical distributors with secondary validation from customs data, SEC filings of multinational chemical conglomerates, and BIS certification registries. Bottom-up volume modeling triangulated against top-down value estimates derived from trade flow analysis and ECHA registration dossiers.
Calibration against historical energy consumption trends in finish grinding operations anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry tier, application intensity, end-user specification authority, and regional regulatory cluster. CAGRs were synthesized from installed cement capacity expansion trajectories and clinker substitution mandate enforcement timelines. Forecast inputs incorporated vertical roller mill penetration rates and bio-derived formulation adoption curves under REACH Annex XVII.
Stress conditions across ethylene oxide price bands, EU Green Deal clinker reduction enforcement, and Indian infrastructure spending cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation timelines and technology substitution rates. Macroeconomic contraction, accelerated carbon border adjustment mechanisms, or breakthrough grinding aid chemistries would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Seal Coat Market
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
Global Fire-Rated Medium Density Fiberboard Market
Building & Construction Materials
Insulating Glass Window Market
Building & Construction Materials
Facade Materials Market
Building & Construction Materials
Russia Ceramic Tiles Market
Building & Construction Materials
North America Rainscreen Cladding Market
Building & Construction Materials
Italy Ceramic Tiles Market
Building & Construction Materials
PVC Window Market
Building & Construction Materials
Artificial Marble Market
Building & Construction Materials
Global Floor and Wall Glazed Tiles Market
Building & Construction Materials
Rubber Expansion Joints Market
Building & Construction Materials
China UPVC Doors and Windows Market
Building & Construction Materials
Asia-Pacific Ceramic Sanitary Ware Market
Building & Construction Materials
Global Convertible Roof System Market
Building & Construction Materials
Steel Casing Pipes Market