
 Global Mobile Concrete Mixer Market | 2026-2036
Global Mobile Concrete Mixer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Concrete Mixer Market Outlook
Road contractors is reorganizing procurement patterns across the mobile concrete mixer landscape, shifting volume toward flexible fleet configurations over traditional long-term leases. Sany Group leverages its integrated manufacturing base to dominate domestic supply chains in Asia. Liebherr-International AG anchors European demand through specialized high-capacity truck-mounted designs. Oshkosh Corporation competes in North American municipal segments with severe-duty chassis expertise.
A mobile concrete mixer combines cement, aggregate, and water within a rotating drum mounted on a vehicle chassis, typically achieving mixing capacities between 3 and 12 cubic meters while maintaining slump consistency during transit to prevent premature setting. Truck-mounted configurations command the largest revenue share due to their indispensability in large-scale infrastructure pours, while telemetric technology represents the fastest-expanding segment as fleet operators prioritize real-time drum rotation monitoring and dispatch optimization. Manual systems retain residual share in emerging markets where capital constraints limit automation uptake.
The EPA enforces Tier 4 Final emissions standards that compel engine retrofits or replacements across diesel-powered fleets, while the EU Green Deal's carbon border adjustments threaten non-compliant imports into European job sites. China's MIIT mandates GB-standard fuel consumption limits that reshape product development priorities for manufacturers serving state construction tenders. Stakeholders must weigh regulatory compliance timelines against residual equipment value when structuring replacement cycles.
Market Dynamics
Telemetric drum monitoring systems are compressing dispatch cycles and redefining fleet utilization benchmarks across road construction networks. The EU Green Deal's emissions architecture is forcing synchronous engine retrofits and hybrid platform development.
Growth Catalysts
- State-Led Urbanization in China:MIIT-mandated equipment procurement quotas for state construction tenders sustain continuous fleet replacement cycles in municipal infrastructure.
- EPA Tier 4 Final Compliance:Engine retrofit mandates across diesel-powered fleets create replacement demand for compliant truck-mounted configurations in North American municipal segments.
- Telemetric Integration:Real-time slump monitoring and GPS-enabled dispatch optimization are pulling fleet operators toward connected drum systems.
Market Restraints
- Steel Input Volatility:Chassis and drum fabrication costs fluctuate with regional steel pricing, compressing margin buffers for OEMs serving price-sensitive emerging markets.
- EU Carbon Border Adjustments:Non-compliant imports face escalating entry barriers into European job sites, fragmenting supplier access for manufacturers outside the regulatory perimeter.
- Manual System Residual Share:Capital constraints in select geographies sustain demand for non-automated mixing controls, limiting addressable market expansion for sensor-rich platforms.
Strategic Opportunities
- India Infrastructure Build-Out:National highway expansion programs and smart city initiatives are opening fleet procurement channels for truck-mounted units with telemetric readiness.
- Hybrid-Electric Convergence:Battery-electric chassis paired with optimized drum drives offer pathways to zero-emission compliance in urban pour zones facing congestion charges.
- Equipment-as-Service Models:Pay-per-pour contracts and managed fleet services are penetrating European road contractor segments previously locked into ownership structures.
Industry Challenges
- Telemetric Technician Scarcity:Fleet maintenance networks lack sufficient field engineers trained in IoT sensor diagnostics and cloud-platform troubleshooting.
- GB Standard Certification Timelines:China's fuel consumption testing protocols extend product validation cycles, delaying market entry for new chassis configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Concrete Mixer Market |
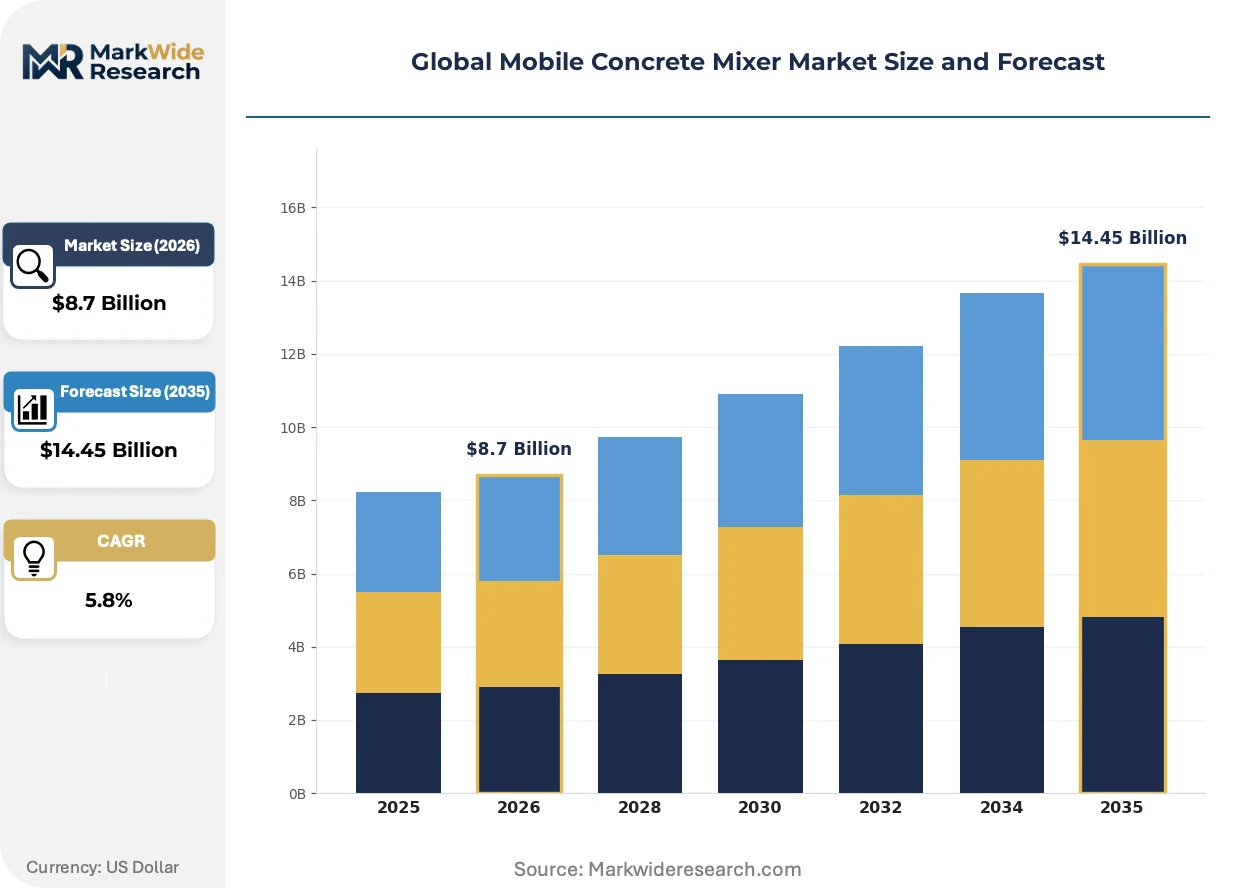
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Loading, Portable, Stationary, Truck-Mounted End User: Construction Companies, Road Contractors, Industrial Projects, Residential Developers Technology: Automated, Manual, Hybrid, Telemetric Capacity: Small, Medium, Large, Extra-Large |
| Companies Covered | AB Volvo, Liebherr-International AG, Sany Group, Zoomlion Heavy Industry Science and Technology Co., Ltd., Oshkosh Corporation, Schwing Stetter Group, Navistar Inc., KYB Corporation, Tata Motors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Concrete Mixer Market Strategic Shifts
Sensor-embedded drum architectures and predictive maintenance algorithms are compressing equipment downtime and reshaping service revenue streams. Regulatory emissions architectures are accelerating powertrain diversification beyond conventional diesel platforms.
On-board telemetric systems is miniaturizing sensor packages for drum rotation monitoring, temperature tracking, and slump consistency measurement. Road contractors in Germany and the Netherlands are adopting these platforms at accelerating rates to optimize pour scheduling. The technology is miniaturizing hardware footprints while expanding data granularity, enabling retrofit installations on legacy chassis without full platform replacement.
REACH chemical compliance and F-Gas refrigerant restrictions are tightening material specifications for hydraulic systems and climate-controlled operator cabs. European manufacturers are reformulating fluid compositions and sealing technologies to maintain certification eligibility. High-capacity truck-mounted units with extended duty cycles face the steepest reformulation costs, prompting selective platform retirement.
Rental and short-term lease structures are displacing traditional ownership models among mid-sized road contractors facing capital rationing. Equipment financiers and OEM captive lenders are expanding managed fleet offerings with bundled maintenance and telemetric access. This shift concentrates most visibly in France and the United Kingdom where municipal budget volatility discourages long-term asset commitments.
Global Mobile Concrete Mixer Market Segmentation
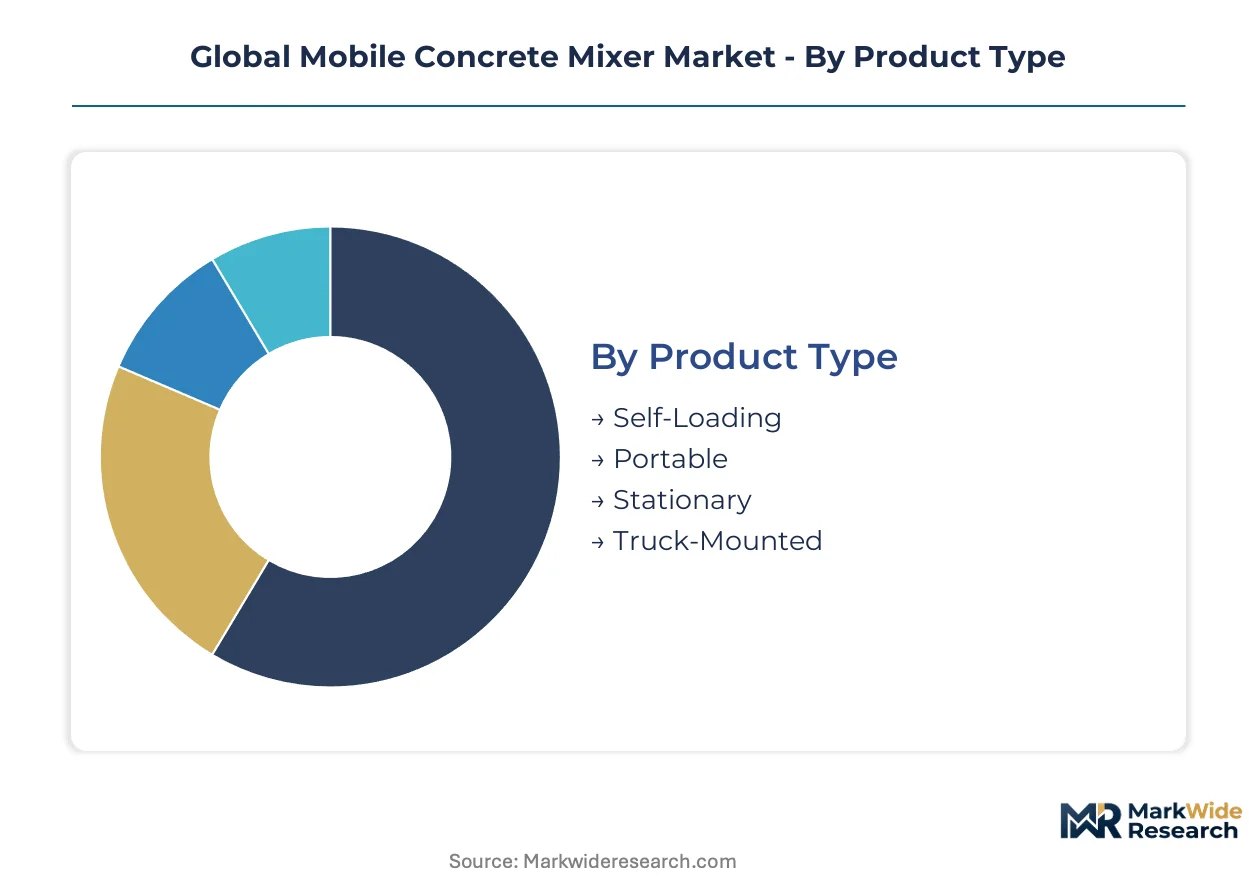
Segmentation in the mobile concrete mixer market reveals how procurement priorities diverge across project scales, regulatory environments, and fleet automation levels. Understanding these divides allows manufacturers to align chassis configurations and drum technologies with specific contractor workflows and compliance requirements.
Product Type:
Truck-mounted configurations face substitution pressure from self-loading units in emerging markets where capital constraints limit fleet standardization, while portable systems erode stationary demand in remote pour zones lacking fixed batching infrastructure.
- Truck-Mounted:These units integrate high-capacity rotating drums onto severe-duty chassis, achieving transit mixing volumes up to 12 cubic meters while maintaining slump consistency across extended haul routes. Road contractors in Germany and the Netherlands specify these configurations for municipal infrastructure pours where pour scheduling precision outweighs capital costs.
- Self-Loading:Compact units combine material loading arms with integrated mixing drums, enabling single-operator deployment on remote job sites lacking fixed batching plants. Demand concentrates in India's national highway expansion programs where labor availability fluctuates and site access limits larger equipment deployment.
- Portable:Modular drum assemblies mount on towable frames for rapid relocation between small-scale residential pours.
- Stationary:Fixed-site batching systems serve centralized concrete supply hubs with limited mobility requirements.
Truck-mounted configurations retain volume leadership; self-loading units hold the steepest expansion curve.
End User:
Cost tier stratification separates fleet procurement patterns, with road contractors commanding premium telemetric platforms while residential developers prioritize entry-level manual systems.
- Road Contractors:These stakeholders operate the largest fleet deployments, specifying truck-mounted units with real-time drum monitoring and GPS-enabled dispatch optimization to compress pour cycles on state-funded infrastructure projects. EPA Tier 4 Final compliance mandates in the United States accelerate replacement demand among municipal fleet operators.
- Construction Companies:Diverse project portfolios drive mixed fleet configurations spanning manual and automated platforms. Sany Group serves this segment in China through integrated manufacturing bases that shorten delivery timelines for state construction tenders.
- Industrial Projects:Extended duty cycles and high-volume continuous pours characterize demand in this segment.
- Residential Developers:Smaller pour volumes and dispersed job sites favor portable and self-loading configurations.
Road contractors dominate fleet value; construction companies generate the broadest platform diversification.
Technology:
Application requirements dictate automation depth, with urban pour zones facing congestion charges pulling battery-electric hybrid platforms while capital-constrained geographies sustain manual system residual demand.
- Telemetric:Sensor-embedded drum architectures enable real-time slump monitoring, temperature tracking, and predictive maintenance algorithms that compress equipment downtime. Fleet operators in France and the United Kingdom adopt these platforms fastest as rental and managed service models displace ownership structures.
- Hybrid:Battery-electric chassis paired with optimized drum drives offer zero-emission compliance pathways in urban zones facing EU Green Deal emissions architecture. Liebherr-International AG anchors European demand through specialized high-capacity designs integrating hybrid powertrains.
- Automated:Programmable mixing controls standardize slump consistency across variable aggregate inputs.
- Manual:Non-automated mixing controls persist in emerging markets where technician scarcity and capital constraints limit IoT sensor diagnostics deployment.
Telemetric systems are gaining share fastest; manual platforms retain residual demand in price-sensitive procurement channels.
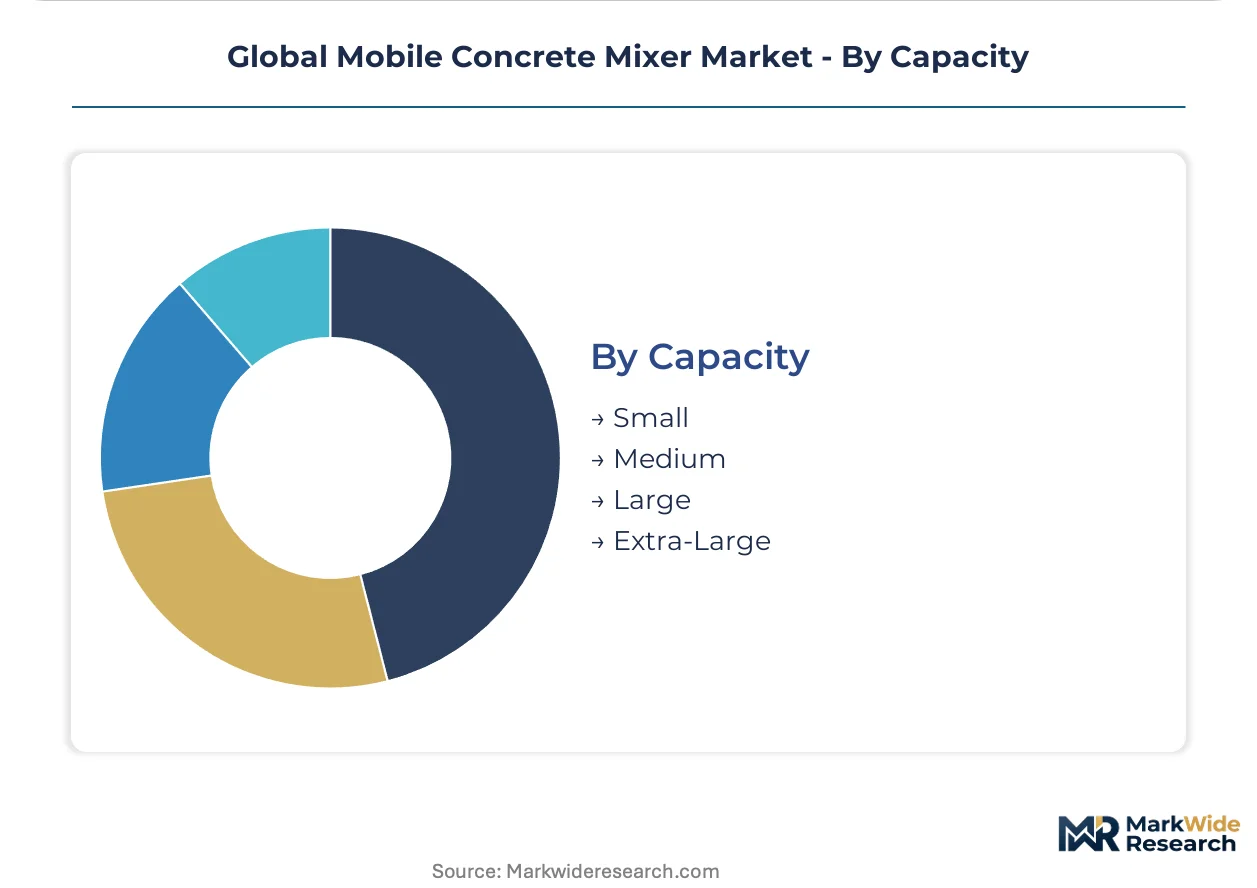
Capacity:
Customer type and project scale align directly with drum volume specifications, with municipal infrastructure demanding extra-large platforms while residential segmentation clusters around small and medium configurations.
- Large:Drum volumes between 8 and 12 cubic meters serve continuous pour requirements on highway expansion and bridge construction projects. China's MIIT-mandated equipment procurement quotas for state construction tenders sustain replacement cycles for these configurations.
- Extra-Large:Extended-duty drum systems exceeding 12 cubic meters address industrial project demands with minimal transit interruptions. REACH chemical compliance and F-Gas refrigerant restrictions tighten material specifications for hydraulic systems in these high-capacity European deployments.
- Medium:Versatile drum volumes balance mobility and output for mixed commercial and residential applications.
- Small:Compact drum systems serve restricted-access urban pours and small-scale residential foundations.
Large-capacity units anchor municipal fleet procurement; extra-large configurations are climbing the fastest in industrial project segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Belt and Road Initiative's transcontinental corridor projects underwrite China's centrality to mobile concrete mixer procurement, while the Rhine-Alpine freight corridor anchors European equipment circulation patterns.
China
State construction tenders for high-speed rail and urban metro expansion sustain fleet replacement cycles at unprecedented scale. MIIT-mandated GB-standard fuel consumption limits compress product development timelines for domestic OEMs. The Yangtze River Delta manufacturing cluster around Shanghai concentrates chassis fabrication and drum assembly capacity for export markets.
Germany
Federal highway maintenance programs and bridge rehabilitation contracts drive demand for telemetric-enabled truck-mounted units. REACH chemical compliance and F-Gas refrigerant restrictions tighten hydraulic system specifications for extended-duty platforms. The North Rhine-Westphalia industrial corridor hosts specialized chassis integrators serving Benelux infrastructure networks.
United States
EPA Tier 4 Final emissions mandates accelerate diesel fleet turnover among municipal road contractors. Federal infrastructure spending through the Infrastructure Investment and Jobs Act expands state procurement budgets for severe-duty configurations. The Texas Triangle metroplex generates concentrated demand for high-capacity units serving petrochemical and energy corridor construction.
India
National highway expansion programs under the Bharatmala Pariyojana framework open fleet procurement channels for self-loading and truck-mounted configurations. BIS certification requirements for construction equipment reshape import substitution patterns for domestic manufacturers. The Delhi-Mumbai Industrial Corridor anchors equipment deployment for smart city and logistics infrastructure development.
United Arab Emirates
NEOM and Red Sea Project mega-developments sustain premium-tier demand for extra-large capacity units with telemetric integration. The country's national construction regulator enforces equipment safety standards that favor certified European and Asian OEM platforms. Dubai's Jebel Ali industrial zone concentrates regional distribution and aftermarket service infrastructure for Gulf Cooperation Council markets.
Global Mobile Concrete Mixer Market Competitive Environment
Concentration sits with diversified industrial conglomerates possessing captive chassis supply and integrated manufacturing ecosystems. The vendor base spans three discernible tiers: heavy machinery conglomerates with construction equipment portfolios, specialized concrete machinery fabricators, and regional chassis assemblers serving price-sensitive procurement channels. Strategic differentiation flows from backward integration into drum metallurgy and hydraulic system production, alongside telemetric platform development partnerships with fleet management software providers.
Within the heavy machinery conglomerate tier, Sany Group and Zoomlion Heavy Industry Science and Technology Co., Ltd. exemplify integrated manufacturing structures spanning chassis fabrication through drum assembly. Liebherr-International AG occupies a position among specialized European fabricators emphasizing high-capacity configurations for infrastructure-scale pours. Oshkosh Corporation anchors North American municipal segments through severe-duty chassis expertise. These three archetypes represent distinct competitive vectors: scale-driven vertical integration, premium-tier specialization, and regional chassis-dominant positioning.
| Leading Market Players |
|---|
| AB Volvo |
| Liebherr-International AG |
| Sany Group |
| Zoomlion Heavy Industry Science and Technology Co., Ltd. |
| Oshkosh Corporation |
| Schwing Stetter Group |
| Navistar Inc. |
| KYB Corporation |
| Tata Motors |
| Others |
Value Chain & Pricing Dynamics
Project-based equipment procurement contracts lock in chassis fabrication slots at Yangtze River Delta foundries while insulating fleet operators from quarterly steel price swings. These structures bind volume commitments to MIIT-mandated GB-standard compliance timelines, embedding regulatory certification costs into multi-year pricing visibility.
Pricing Analysis
Volume-discount tiering structures stratify across premium telemetric platforms, standard EPA Tier 4 Final-compliant configurations, and economy manual-drum units. Price differentiation hinges on after-sales service bundling and certification grade, with EU Green Deal emissions architecture compressing margins on non-hybrid imports. Cost compression in economy tiers is intensifying because capital-constrained emerging markets resist sensor-rich premiums. Residential developers exhibit highest price sensitivity; road contractors in Germany and the Netherlands absorb premiums for real-time dispatch optimization.
Supply Chain Analysis
Strait of Malacca transit underwrites steel alloy shipments from South Korea and Japan to drum fabrication facilities in China and India. Chassis assembly draws from high-strength steel plate, hydraulic sealing compounds, and telemetric sensor packages. Single-source vulnerability concentrates in European F-Gas-compliant refrigerant suppliers for climate-controlled cabs. Distribution runs through OEM captive financing arms and regional equipment lessors serving municipal fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telemetric platform subscriptions and predictive maintenance contracts are expanding faster than hardware unit sales, reframing OEM economics around recurring revenue attachment. Service revenue per installed drum is displacing upfront equipment margins as the primary value capture mechanism.
For Market Incumbents: Fortify backward integration into drum metallurgy and hydraulic system production to defend against steel input volatility. Lock in GB-standard certification pipelines for Chinese state tenders while expanding managed fleet service contracts in France and the United Kingdom. Sany Group's integrated manufacturing base demonstrates how captive chassis supply neutralizes margin compression from commodity price swings. For New Entrants and Emerging Players: EPA Tier 4 Final fast-track certification opens municipal procurement channels in the United States where incumbent diesel fleet turnover accelerates replacement demand. Target India's Bharatmala highway expansion with self-loading configurations optimized for labor-scarce remote sites. Partner with European telemetric software providers to bypass captive R&D development cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among OEMs with bundled maintenance and telemetric access contracts displacing traditional ownership structures. Long-term viability favors platforms with hybrid-electric chassis development pipelines and service network density in urban congestion-charge zones. Monitor EU Carbon Border Adjustment implementation timelines as inflection indicators for import-dependent supplier valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetric Platform Integration | Real-time drum monitoring compresses dispatch cycles for German road contractors. |
| Hybrid-Electric Chassis Development | Battery-electric configurations satisfy EU Green Deal emissions architecture in urban pour zones. |
| Equipment-as-Service Model Expansion | Pay-per-pour contracts penetrate French municipal segments locked into ownership structures. |
| Backward Integration into Drum Metallurgy | In-house steel fabrication buffers OEM margins from regional pricing volatility. |
| GB-Standard Certification Investment | MIIT compliance pipelines secure access to China's state construction tender volumes. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC equipment manufacturer filings, and EU emissions registry disclosures. Fleet maintenance directors, municipal procurement officers, and aftermarket service heads provided operational validation. OEM platform engineers and telemetric software integration specialists supplied technical architecture perspectives. Bottom-up equipment shipment tallies triangulate against top-down infrastructure spending allocations across the analysis window.
Segmentation dimensions modeled include product type, end-user category, technology tier, and drum capacity specifications alongside regional regulatory cluster variations. CAGRs derive from equipment replacement cycle analysis and fleet expansion trajectories tied to infrastructure budget appropriations. Steel price elasticity coefficients and emissions compliance cost pass-through rates inform price trajectory assumptions throughout the forecast period.
Decision-makers should treat outputs as directional under stable infrastructure spending and regulatory enforcement assumptions; material deviation in commodity input costs or trade policy would warrant model refresh. Practitioners should keep alternative scenarios live as EU Carbon Border Adjustment mechanisms and China's dual carbon policy implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Electric Hot Chamber Die Casting Machines Market
Construction Equipment
Ceramic Tile Printing Machine Market
Construction Equipment
Earthing Equipment Market
Construction Equipment
Industrial Hydraulic Equipment Market
Construction Equipment
Industrial Steam Washer Market
Construction Equipment
Construction Power Rental Market
Construction Equipment
Overhead Cranes Market
Construction Equipment
Southern Africa Construction Equipment Rental Market
Construction Equipment
Asia-Pacific Completion Equipment and Services Market
Construction Equipment
All-Terrain Crane Market
Construction Equipment
Crane Rail Market
Construction Equipment
Snow Removal Equipment Market
Construction Equipment
Gear Grinding Machine Market
Construction Equipment
Latin America Construction Equipment Market
Construction Equipment
GCC Construction Machinery Market
Construction Equipment
Construction Camera [Time Lapse Camera] Market