
 Clay Roof Tiles Market | 2026-2036
Clay Roof Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Clay Roof Tiles Market Outlook
A shift from single-source to multi-source clay procurement is pivoting how manufacturers secure kaolin and shale feedstocks across fragmented regional deposits. Wienerberger AG leverages its vertically integrated quarry network to sustain cost predictability across Central European plants. Ludowici Roof Tile anchors its position through artisan-grade production controls in the United States. MCA Clay Roof Tile competes on volume scale across the southwestern United States and Mexico.
Clay roof tiles are fired ceramic roofing units, typically manufactured from natural clay, shale, or kaolin at kiln temperatures exceeding 1,000 degrees Celsius, producing interlocking or overlapping units that shed precipitation while permitting passive ventilation beneath the roof deck. Their primary purpose is to provide durable, non-combustible weather protection with service lifespans frequently spanning multiple decades in residential and commercial structures. Unglazed tiles dominate volume across cost-sensitive renovation channels where natural patina development aligns with aesthetic preferences. Glazed variants command premium positioning in new construction segments requiring colorfast guarantees and enhanced surface impermeability. Machine-made tiles lead throughput efficiency while handmade categories occupy artisan niches with elongated lead times and higher margin structures.
EPA stormwater management guidelines and NHTSA-adjacent state building codes in the United States shape permeability and load-bearing specifications for roofing assemblies. REACH chemical compliance and CE marking requirements within Europe govern clay composition thresholds and factory emissions controls. BMI Group and Marley Roofing navigate these dual regulatory architectures through dedicated certification laboratories in Germany and the United Kingdom. Stakeholders must monitor evolving embodied-carbon disclosure rules under the EU Green Deal and corresponding state-level amendments in California and New York.
Market Dynamics
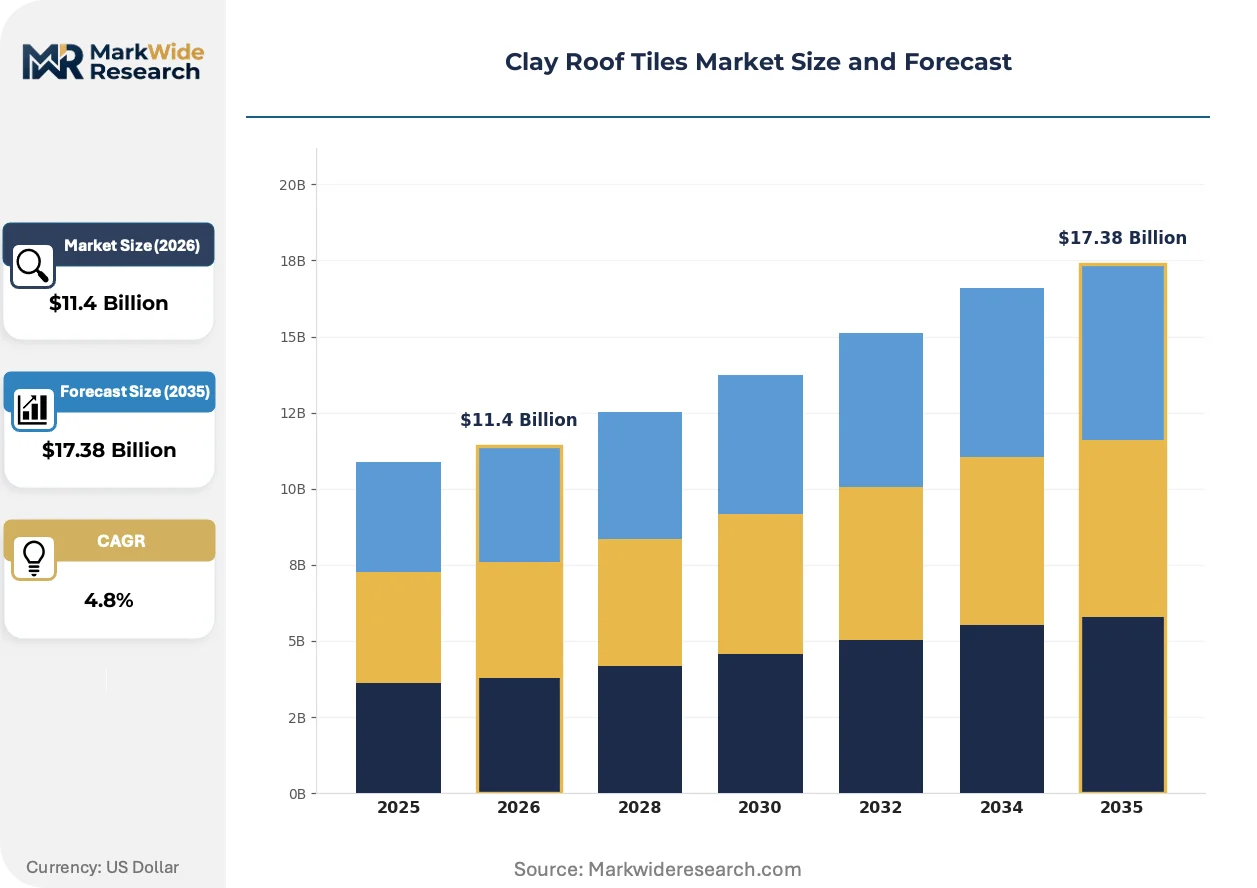
The EU Green Deal is tightening embodied-carbon disclosure requirements for construction materials, forcing clay tile manufacturers to reconfigure kiln operations and feedstock sourcing across Mediterranean Europe.
Growth Catalysts
- EU Green Deal building performance standards:Energy-efficiency mandates for roofing assemblies are pulling specification-grade clay tiles into residential renovation pipelines across Spain, Italy, and Portugal.
- Passive ventilation architecture:Terracotta roof systems enable natural airflow beneath roof decks, aligning with net-zero building designs in Mediterranean climate zones.
- Cultural heritage preservation ordinances:Historic district regulations in Andalusia, Tuscany, and the Algarve mandate traditional clay roofing materials for aesthetic continuity.
Market Restraints
- Natural gas price volatility:Kiln firing at temperatures exceeding 1,000 degrees Celsius ties production economics to European energy markets, compressing margins during supply shocks.
- Fragmented kaolin deposit access:Quality feedstock concentrates in specific regional quarries, creating procurement bottlenecks for manufacturers lacking backward integration into mining operations.
- Concrete and metal roofing substitution:Lower-cost alternatives capture volume in cost-sensitive commercial segments where service lifespan is deprioritized.
Strategic Opportunities
- CSRD-mandated sustainability reporting:Corporate sustainability disclosure requirements create demand for ESG-certified clay tiles among institutional real estate developers.
- Cool roof technology convergence:Surface glazing innovations combining solar reflectance with traditional terracotta aesthetics open specification channels in warm-climate North American markets.
- Direct-to-contractor digital platforms:Bypassing traditional distributor layers enables margin capture and shorter lead times for mid-scale residential builders.
Industry Challenges
- Kiln operator skill scarcity:Firing curve expertise for color consistency and structural integrity is concentrating among aging workforces in traditional manufacturing clusters.
- CE marking compliance timelines:Factory emissions testing and clay composition verification create certification backlogs that delay market entry for new product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clay Roof Tiles Market |
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glazed Tiles, Unglazed Tiles, Handmade Tiles, Machine-Made Tiles Installation Type: New Construction, Renovation, Roof Replacement, DIY Installation End User: Residential, Commercial, Industrial, Agricultural Distribution Channel: Direct Sales, Online Retail, Wholesale, Specialty Stores |
| Companies Covered | Wienerberger AG, Ludowici Roof Tile, MCA Clay Roof Tile, Terreal, Monier, BMI Group, Marley Roofing, Boral Limited, Kajaria Ceramics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clay Roof Tiles Market Strategic Shifts
Digital firing control systems and surface engineering advances are compressing quality variance while expanding the addressable market for clay roofing beyond traditional Mediterranean architecture.
Computer-vision kiln monitoring is automating temperature curve adjustments in real-time, reducing thermal gradient defects that previously required manual operator intervention. Large-scale Spanish and Italian manufacturers are deploying these systems fastest, cutting rework rates and stabilizing batch-to-batch color matching for glazed variants. This automation is compressing the quality gap between machine-made volume production and artisan-grade handmade categories.
REACH chemical compliance is tightening allowable heavy metal content in clay formulations and glaze applications, forcing reformulation of traditional colorants across European manufacturing bases. The regulation's industrial consequence is elevated R&D expenditure for compliant pigment chemistry. Unglazed natural terracotta segments face lower adaptation burdens than saturated-color glazed lines, shifting competitive advantage toward mineral-sourcing capabilities.
Architects and developers are bundling roofing material selection with whole-building lifecycle carbon accounting, elevating locally sourced clay over imported alternatives regardless of upfront cost differentials. This specification behavior is disrupting traditional distributor relationships where price-driven tile selection dominated. The shift is most visible in French and German commercial construction, where environmental product declarations increasingly gate eligibility for public procurement contracts.
Clay Roof Tiles Market Segmentation
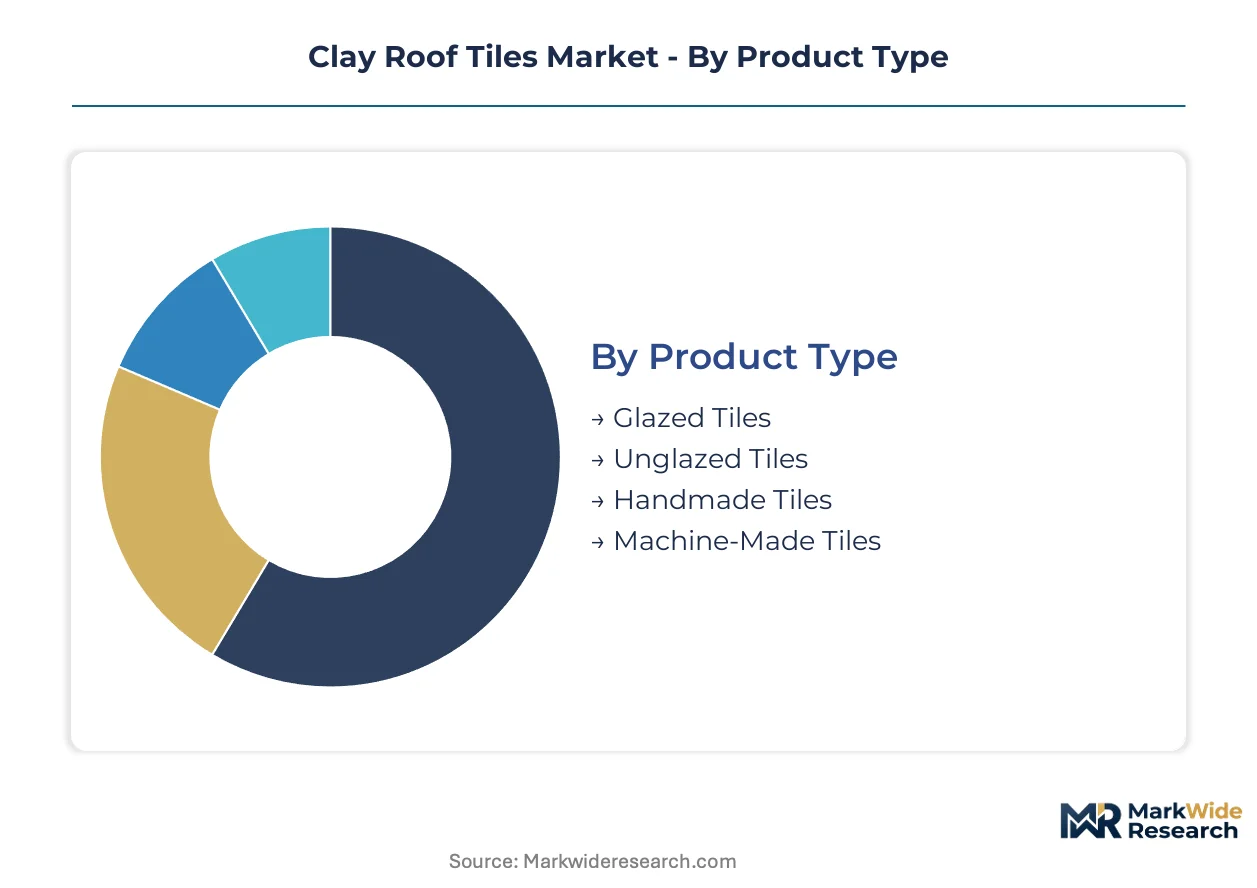
Clay roof tile segmentation reveals how regulatory certification burdens, firing technology choices, and channel economics partition addressable demand across residential and commercial construction verticals. Understanding these fault lines clarifies where margin concentrates and which specifications gate market access.
Product Type:
CE marking requirements under REACH govern surface chemistry thresholds, creating divergent compliance costs across glazed versus unglazed formulations.
- Unglazed Tiles:Natural terracotta fired without surface coating develops protective patina through weathering. Demand clusters in Mediterranean renovation channels across Spain, Italy, and Portugal where heritage ordinances mandate traditional aesthetics and property owners prioritize lifecycle cost over upfront expenditure.
- Machine-Made Tiles:Automated pressing and firing delivers dimensional consistency at volume scale. Spanish and Italian manufacturers deploy computer-vision kiln controls to compress quality variance, capturing specification-grade demand from mid-market residential developers in warm-climate North American construction.
- Glazed Tiles:Surface vitrification provides colorfast guarantees and enhanced impermeability, commanding premium positioning in new construction segments.
- Handmade Tiles:Artisan-grade production with elongated lead times occupies niche markets requiring aesthetic customization.
Machine-made tiles sit at the top of the volume ranking, with glazed tiles climbing the fastest as energy-efficiency mandates pull specification-grade products into renovation pipelines.
Installation Type:
Project scale and contractor certification requirements segment demand between professional installation and self-directed procurement channels.
- New Construction:Developer-specified clay roofing integrates with whole-building lifecycle carbon accounting, elevating locally sourced materials in French and German commercial segments where environmental product declarations gate public procurement eligibility.
- Renovation:EU Green Deal building performance standards tighten energy-efficiency requirements for roofing assemblies across residential retrofit activity in Spain, Italy, and Portugal.
- Roof Replacement:Storm damage and end-of-life cycles drive reactive demand with compressed decision timelines.
- DIY Installation:Small-format accessories and repair kits serve homeowner maintenance without professional labor.
Renovation captures the largest addressable base, with new construction expanding most quickly as institutional developers embed ESG criteria into material selection protocols.
End User:
Service lifespan expectations and fire-resistance ratings differentiate specification behavior across building typologies.
- Residential:Single-family and multi-family housing development across Mediterranean Europe sustains traditional clay roofing adoption, with passive ventilation properties aligning with net-zero building designs.
- Commercial:Office and retail construction bundles roofing selection with embodied-carbon disclosure requirements under CSRD-mandated sustainability reporting.
- Industrial:Warehousing and manufacturing facilities deprioritize aesthetic specifications in favor of functional weather protection.
- Agricultural:Barns and storage structures utilize clay tiles where fire resistance and durability outweigh cost sensitivity.
Residential maintains volume leadership, while commercial segments gain share fastest as environmental product declarations become mandatory for public contracts.
Distribution Channel:
Channel margin structure and lead time compression potential segment procurement behavior across project scales.
- Direct Sales:Manufacturer-to-contractor relationships bypass distributor markups, enabling margin capture for mid-scale residential builders in fragmented European markets.
- Wholesale:Regional distributors aggregate volume across smaller contractors, concentrating inventory risk in traditional Mediterranean manufacturing clusters.
- Specialty Stores:Showroom-based specification support serves architect-driven projects requiring color matching and sample validation.
- Online Retail:Digital platforms expand access to standard formats for repair and small-project demand.
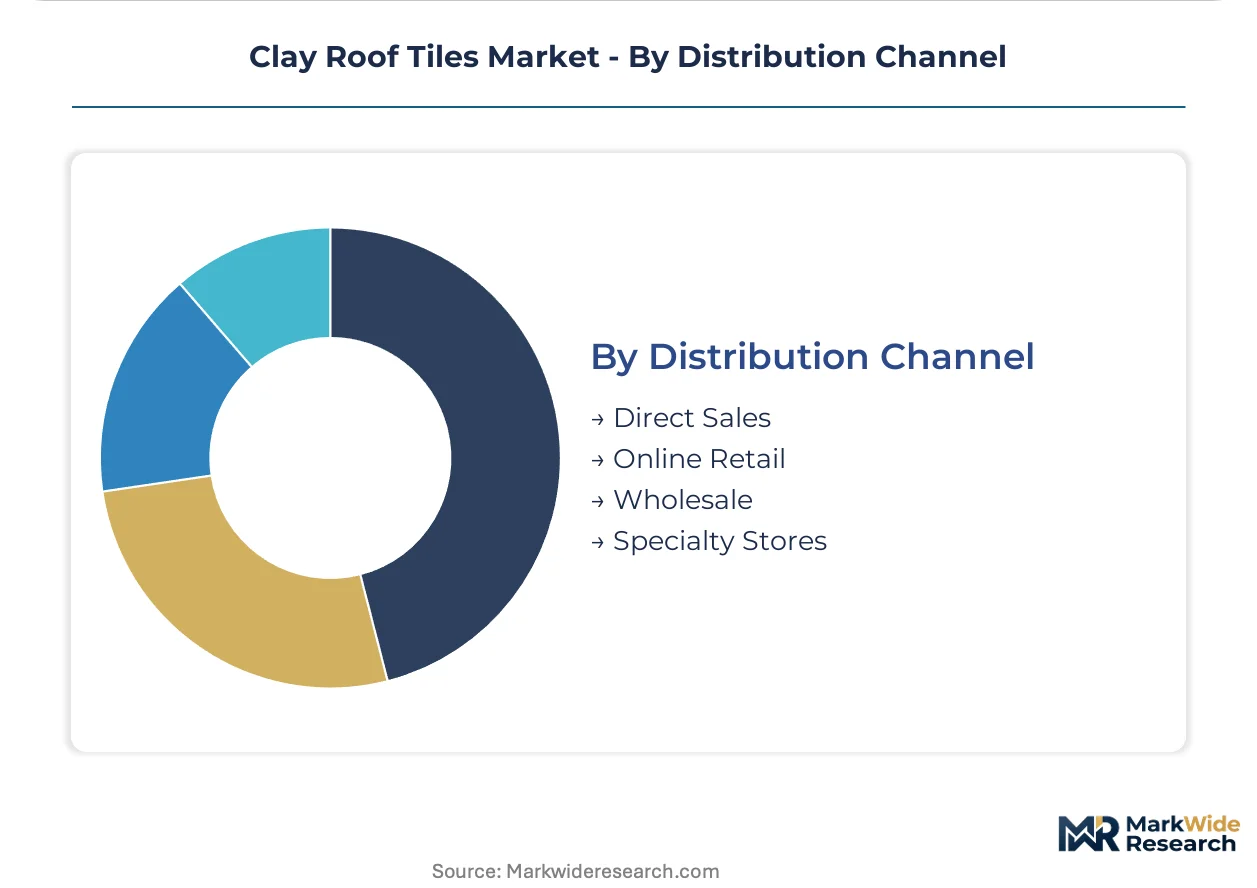
Wholesale retains the highest transaction volume, with direct sales gaining traction fastest among developers seeking supply chain transparency for carbon accounting disclosure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian terracotta manufacturing clusters in Tuscany and Emilia-Romagna anchor global clay roof tile production heritage, with regional output patterns reflecting divergent regulatory regimes and construction cycle timing across mature economies.
Italy
Historic preservation ordinances in Tuscany and Umbria mandate traditional clay roofing for aesthetic continuity in protected districts. EU Green Deal building performance standards tighten energy-efficiency requirements for renovation activity across central and southern regions. The Sassuolo ceramic district maintains concentrated artisan and industrial capacity for both domestic supply and premium export markets.
Spain
Andalusian and Valencian residential development sustains demand for Mediterranean-style terracotta systems with passive ventilation properties. REACH chemical compliance governs allowable heavy metal content in clay formulations and glaze applications. Seville and Valencia host vertically integrated manufacturing operations serving Iberian Peninsula construction and North African export channels.
United States
Warm-climate residential construction in Florida, Arizona, and California pulls specification-grade clay tiles into new development pipelines. EPA stormwater management guidelines and state-level building codes shape permeability and load-bearing specifications for roofing assemblies. Ludowici Roof Tile anchors artisan-grade production controls from its Ohio base while southwestern manufacturers compete on volume scale.
Portugal
Algarve coastal development and Lisbon metropolitan renovation sustain adoption of traditional roofing materials aligned with cultural heritage preservation. EU Green Deal embodied-carbon disclosure requirements elevate locally sourced clay over imported alternatives in public procurement. Northern Portuguese manufacturing clusters near Aveiro supply domestic demand and Spanish cross-border markets.
France
Commercial construction in Île-de-France and Provence-Alpes-Côte d'Azre bundles roofing selection with whole-building lifecycle carbon accounting under CSRD-mandated sustainability reporting. CE marking requirements and environmental product declarations gate eligibility for institutional developer contracts. Traditional manufacturing centers in Burgundy and Languedoc maintain capacity for heritage-compatible renovation materials.
Clay Roof Tiles Market Competitive Environment
Global majors compete with regional champions across feedstock access and kiln technology specialization, producing a tiered structure where scale-driven volume producers coexist with artisan-grade specialists serving heritage-sensitive segments. European manufacturers leverage vertically integrated quarry networks to sustain cost predictability, while North American competitors anchor positions through production controls and regional distribution density. Two strategic archetypes dominate: backward-integrated material specialists with captive clay deposits, and specification-focused artisans competing on aesthetic customization and lead-time flexibility. Competitive moves concentrate on certification laboratory investments for dual regulatory architectures and digital platform development to bypass traditional distributor layers.
Within the European integrated tier, Wienerberger AG represents the vertically consolidated archetype with quarry-to-kiln control across Central European operations. Ludowici Roof Tile and MCA Clay Roof Tile occupy differentiated positions in North American markets, with the former exemplifying artisan-grade production disciplines and the latter representing volume-scale manufacturing across southwestern states and adjacent Mexican markets. These three anchors illustrate how geographic concentration and production philosophy stratify competitive positioning without requiring uniform strategic approaches.
| Leading Market Players |
|---|
| Wienerberger AG |
| Ludowici Roof Tile |
| MCA Clay Roof Tile |
| Terreal |
| Monier |
| BMI Group |
| Marley Roofing |
| Boral Limited |
| Kajaria Ceramics |
| Others |
Value Chain & Pricing Dynamics
Kiln operator expertise concentration in Tuscany and Emilia-Romagna creates labor-cost differentials that widen pricing-tier spreads between artisan handmade and automated machine-made clay roof tile categories across Mediterranean markets.
Pricing Analysis
Input-cost pass-through from natural gas-fired kiln operations shapes transaction economics across European manufacturing bases. Three-tier pricing structure across premium, standard, and economy levels separates glazed specification-grade tiles from unglazed natural terracotta and basic machine-made volume products. Price differentiation rests on certification grade and geographic delivery cost, with CE-marked glazed variants commanding substantial premiums over unglazed renovation channels. Cost compression in economy tiers is intensifying because concrete and metal roofing substitution erodes volume leverage. Commercial developers exhibit highest price sensitivity, while heritage-mandated residential renovation demonstrates lowest elasticity due to regulatory compliance requirements.
Supply Chain Analysis
Reverse-logistics flows for clay roof tiles center on end-of-life collection networks and crushed-tile recycling into aggregate feedstock, with limited refurbishment economics due to firing irreversibility. Geographic supply concentrates in Italy, Spain, and Portugal, with secondary capacity in France and southwestern United States. Raw material dependencies draw from regional kaolin deposits, shale quarries, and natural gas supply contracts. Single-source vulnerability in quality clay deposits creates procurement bottlenecks for manufacturers lacking backward integration. Distribution runs through regional wholesale aggregators serving fragmented contractor bases, with direct-to-contractor digital platforms emerging as margin-capture alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
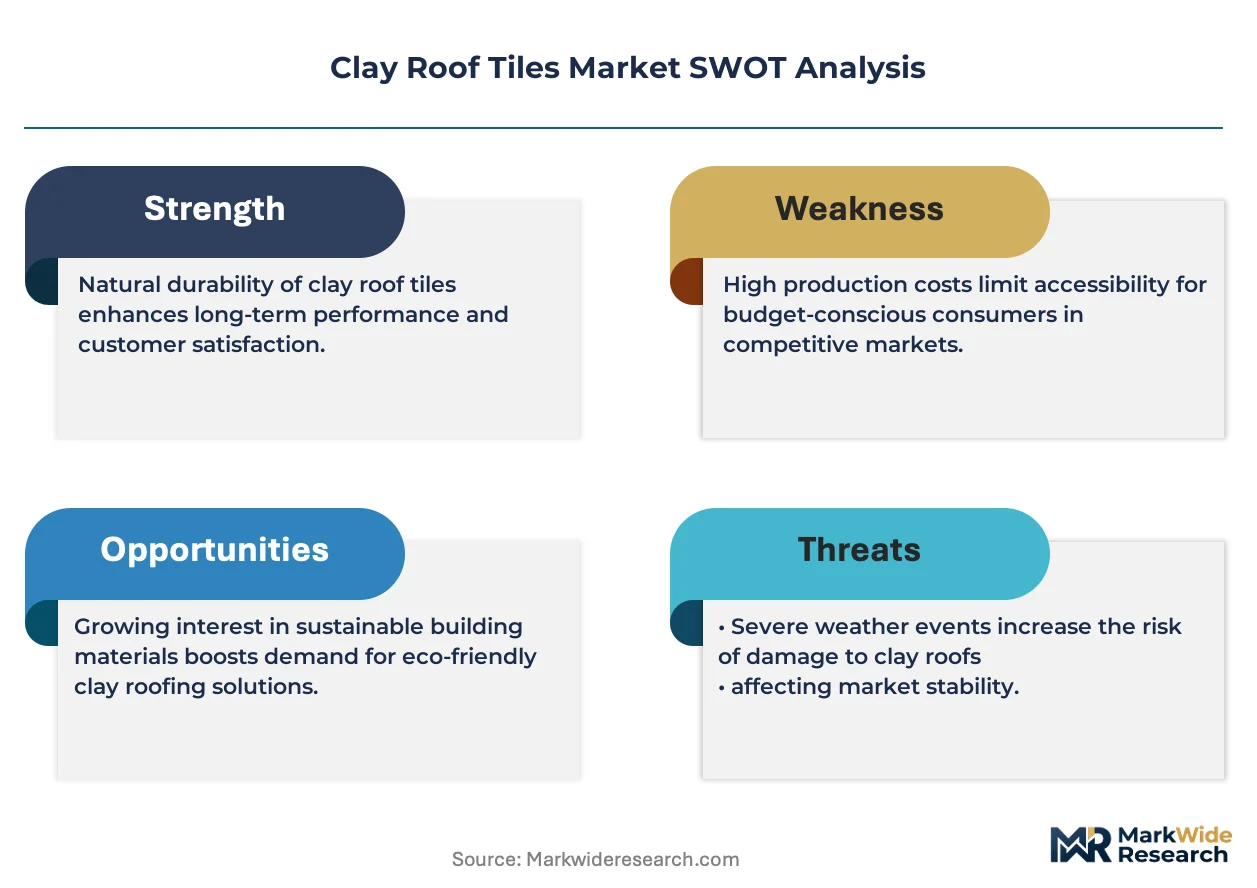
The clay roof tiles market functions as a stable compounder, with EU Green Deal building performance standards and cultural heritage preservation mandates generating durable specification demand across Mediterranean residential renovation cycles.
For Market Incumbents: Cement feedstock security through quarry network consolidation or long-term kaolin supply agreements, while accelerating computer-vision kiln automation to offset aging workforce constraints in Italian and Spanish manufacturing clusters. Concrete and metal roofing substitution threatens volume-tier margins, requiring defensive certification investments for CE marking and environmental product declarations to maintain specification access in French and German commercial segments. For New Entrants and Emerging Players: Cool roof technology convergence with solar-reflective glazing formulations offers a technology-first wedge into warm-climate North American new construction markets where traditional terracotta aesthetics face limited incumbent penetration. Target mid-scale residential builders in Florida, Arizona, and California through direct-to-contractor digital platforms that bypass established wholesale layers and compress lead times for specification-grade glazed variants. For Investors and Strategic Acquirers: Building materials conglomerates with Mediterranean presence represent the most active acquirer in this space, seeking quarry-to-kiln vertical consolidation to secure cost predictability. Long-term viability hinges on CSRD-mandated sustainability reporting and embodied-carbon disclosure rules elevating ESG-certified clay tiles in institutional real estate procurement. Monitor natural gas price volatility and REACH chemical compliance reformulation costs as inflection indicators for margin compression across glazed product lines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kaolin Quarries | Captive feedstock supply insulates Wienerberger AG and regional Italian producers from procurement bottlenecks. |
| Computer-Vision Kiln Automation | Spanish and Italian manufacturers deploy real-time temperature curve adjustments to compress batch-to-batch color variance. |
| Cool Roof Glazing Development | Solar-reflective surface engineering opens specification channels in California and Arizona residential construction. |
| Direct-to-Contractor Digital Platforms | Bypassing wholesale distributor layers enables margin capture and lead-time compression for mid-scale builders. |
| Environmental Product Declaration Certification | EPD documentation gates eligibility for French and German public procurement contracts under CSRD reporting. |
Study Parameters
Direct dialogue with plant managers at Italian and Spanish manufacturing clusters, procurement leads at French and German commercial developers, distribution channel partners across Mediterranean markets, and technical R&D directors specializing in ceramic surface engineering grounded qualitative findings. Secondary validation drew from EU Green Deal regulatory filings, REACH chemical compliance documentation, CE marking certification databases, and customs trade data for clay and ceramic product categories. Bottom-up volume estimates triangulated with top-down construction spending allocation models.
Bottom-up demand modeling aggregated segment-level projections across product type, installation category, end-user vertical, and distribution channel dimensions throughout the forecast period. Top-down validation cross-referenced construction output indices, residential renovation permit data, and commercial real estate investment flows across Spain, Italy, Portugal, France, Germany, and southwestern United States markets. CAGRs derived from regression analysis of historical volume patterns against regulatory implementation timelines and energy-efficiency mandate adoption curves. Industry-specific inputs included kiln capacity utilization rates, natural gas price correlation coefficients, and heritage preservation ordinance coverage expansion.
The model holds under stable EU Green Deal implementation trajectories and continued natural gas supply normalization; deviation in REACH chemical compliance timelines or abrupt energy price shocks would shift volume and value projections. Forecasts reflect assumptions regarding certification backlog resolution and workforce replacement rates in traditional manufacturing clusters. Practitioners should monitor embodied-carbon disclosure rule amendments and CSRD reporting adoption intensity among institutional real estate developers for early signals of specification-grade demand acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Steel Sections Market
Building & Construction Materials
North America Ready-Mix Concrete Market
Building & Construction Materials
US Parking Deck Coatings Market
Building & Construction Materials
Electrochromic Glass for Construction Market
Building & Construction Materials
Roof Window Market
Building & Construction Materials
Hollow Concrete Block Market
Building & Construction Materials
Egypt Prefab Wood Buildings Market
Building & Construction Materials
Latex Caulk Market
Building & Construction Materials
Middle-East and Africa Gypsum Board Market
Building & Construction Materials
Acoustic Doors Market
Building & Construction Materials
Roofing Tiles Market
Building & Construction Materials
Education Building Design Market
Building & Construction Materials
Asia-Pacific Ceramic Sanitary Ware Market
Building & Construction Materials
Global Raised Access Floor Systems Market
Building & Construction Materials
Reclaimed Lumber Market
Building & Construction Materials
Articulated Concrete Block Mattresses Market