
 US Steel Rebar Market | 2026-2036
US Steel Rebar Market Size, Share, and Industry Trends Forecast 2026-2036
US Steel Rebar Market Intelligence
The increasing use of public-private partnerships for funding major infrastructure projects is tilting the competitive landscape toward large-scale producers. Nucor leverages its extensive network of electric arc furnace mills to supply these projects efficiently. Gerdau S.A. differentiates through its focus on specialized rebar products for complex construction. CMC Steel sustains its market position through strong regional distribution and fabrication services, anchoring its presence in key construction markets across the southern United States.
Steel rebar is a steel bar or mesh of steel wires used as a tension device in reinforced concrete and reinforced masonry structures to strengthen and hold the concrete in tension. Most rebar is deformed, featuring ribs or lugs that improve the bond with the concrete, and is typically produced via a hot-rolled process. Deformed rebar constitutes the largest product segment due to its superior bonding properties. Demand from the infrastructure end-user segment represents the fastest-growing application, driven by public works spending.
Product quality and performance are governed by standards from ASTM International, such as ASTM A615 for carbon-steel rebar. The Environmental Protection Agency (EPA) regulations on emissions from steel mills and OSHA workplace safety rules also shape production costs and practices. Navigating domestic sourcing requirements tied to federal funding and investing in lower-carbon production technologies are key strategic decisions for manufacturers seeking to secure long-term contracts.
Market Dynamics
The US steel rebar market's trajectory is fundamentally shaped by the domestic sourcing requirements mandated by federal infrastructure spending. This legislative framework concentrates demand toward domestic producers, influencing capacity investment decisions and supply chain configurations across the country.
Growth Catalysts
- Infrastructure Investment:The Infrastructure Investment and Jobs Act (IIJA) provides substantial, long-term funding for public works, directly stimulating demand for steel rebar in bridge, highway, and water system projects nationwide.
- Regional Construction Activity:Large-scale civil and commercial construction projects in high-growth states, particularly Texas and Florida, create concentrated pockets of demand that support regional production and distribution networks.
- Deformed Rebar Dominance:The superior bonding characteristics of deformed rebar with concrete make it the default specification for nearly all reinforced concrete applications, ensuring its continued dominance as the primary product segment.
Market Restraints
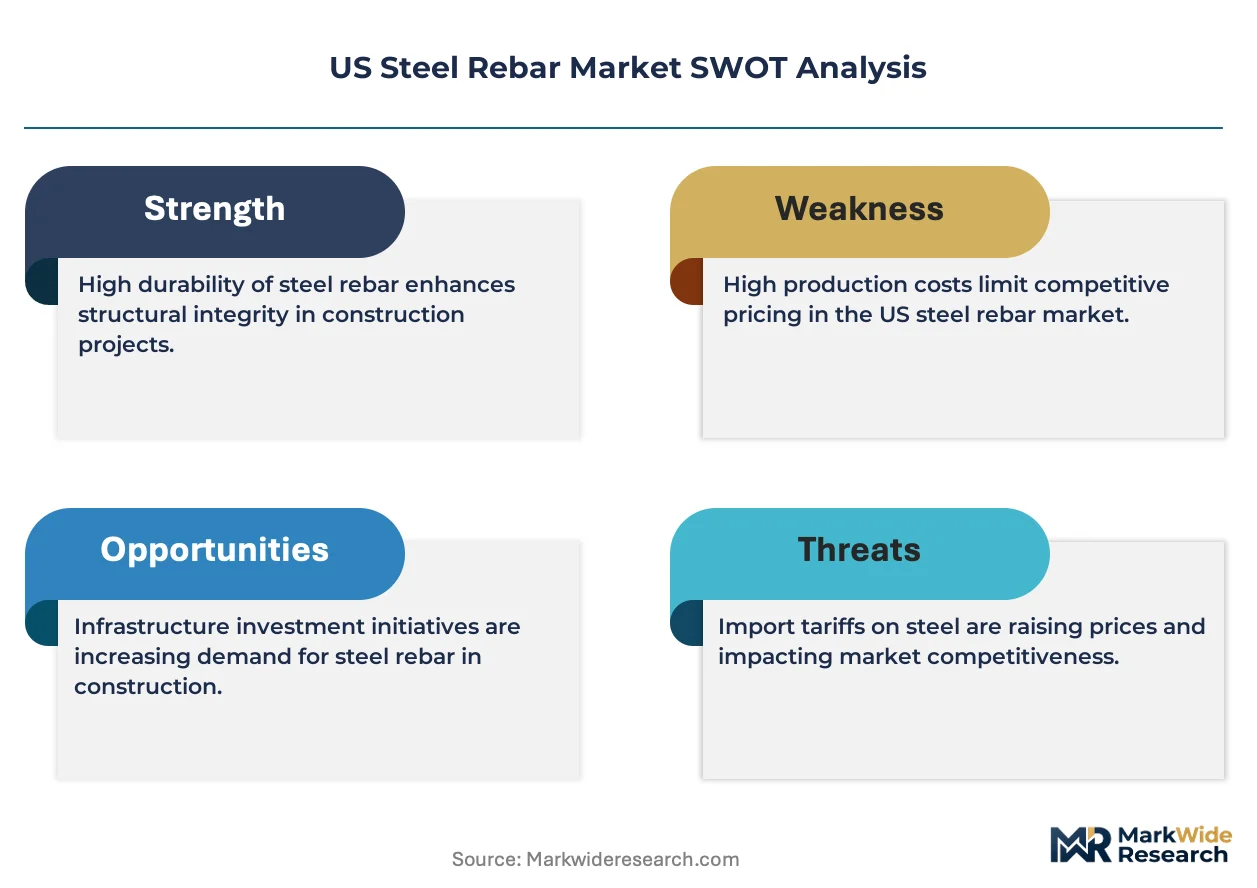
- Input Cost Volatility:Prices for scrap steel and electricity, the primary inputs for the electric arc furnace (EAF) method used by most US producers, are subject to significant fluctuations that can compress manufacturer margins.
- Regulatory Compliance Costs:Adherence to Environmental Protection Agency (EPA) air quality standards and Occupational Safety and Health Administration (OSHA) workplace safety regulations adds significant overhead to steel production operations.
- Logistical Hurdles:The high weight and bulk of steel rebar result in substantial transportation costs, creating logistical challenges in serving construction sites located far from production mills or distribution hubs.
Strategic Opportunities
- Low-Carbon Steel Production:Investing in technologies that reduce the carbon footprint of steel manufacturing creates an opportunity to win contracts from public and private clients with explicit sustainability and ESG procurement goals.
- Specialized Product Development:There is an opening for producing higher-margin, specialized rebar, such as corrosion-resistant or high-strength variants, for use in demanding applications like coastal infrastructure or complex architectural designs.
- Value-Added Fabrication Services:Expanding from raw material supply into downstream fabrication and detailing services allows producers to capture more value and forge deeper partnerships with large construction contractors.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of skilled tradespeople, including certified welders and ironworkers, creates bottlenecks at construction sites and within fabrication shops, potentially delaying project timelines.
- Capital-Intensive Modernization:Upgrading or building new mills with advanced EAF technology and environmental controls requires immense capital investment, posing a significant barrier to entry and a challenge for smaller operators.
- Domestic Sourcing Complexity:Navigating the intricate "Buy America" provisions attached to federal funding requires sophisticated supply chain management and documentation, adding an administrative burden for manufacturers and contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Steel Rebar Market |
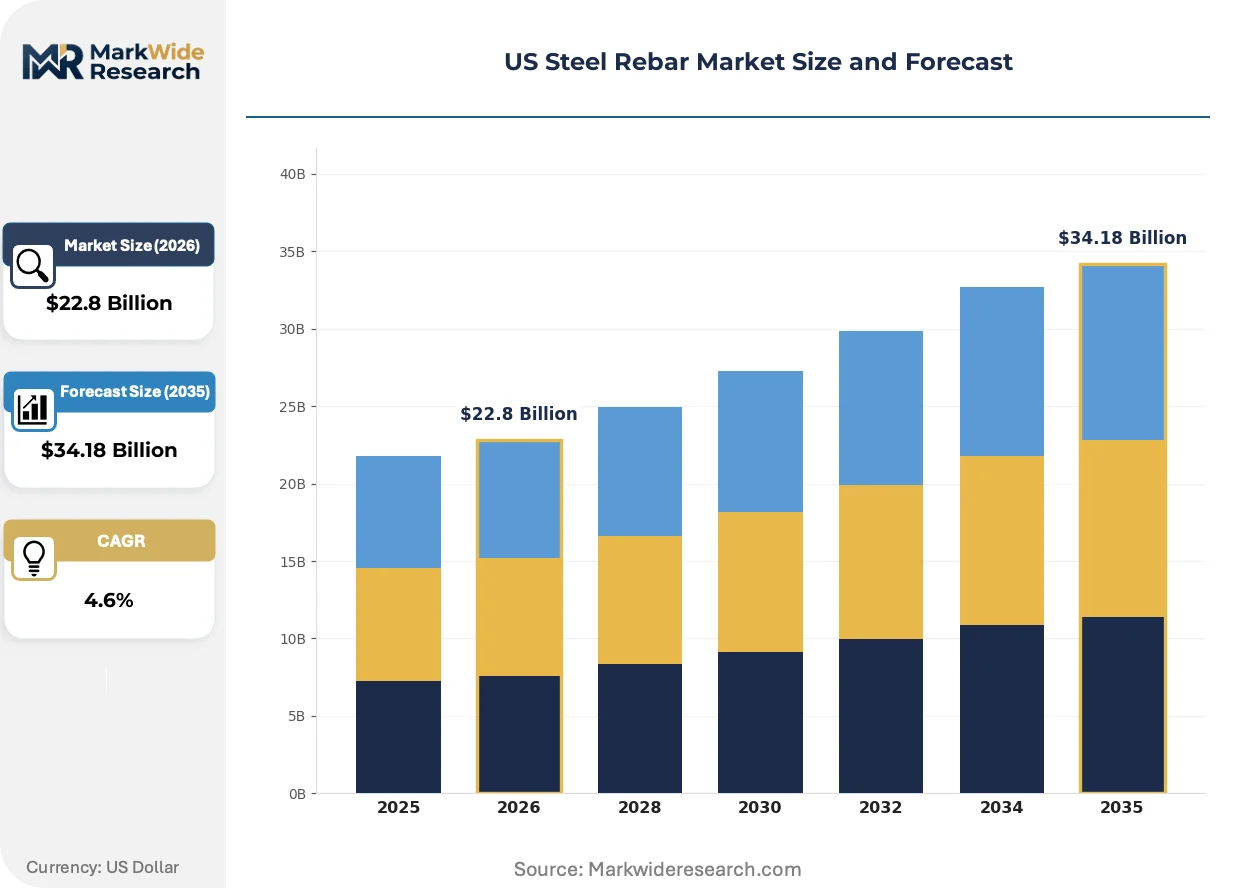
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $34.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deformed Rebar, Smooth Rebar, Epoxy Coated Rebar, Stainless Steel Rebar End User: Construction, Infrastructure, Manufacturing, Energy Technology: Hot Rolled, Cold Rolled, Bending, Cutting Distribution Channel: Direct Sales, Wholesale, Online Retail, Others |
| Companies Covered | ArcelorMittal, EVRAZ U.S., Inc, Nucor, Liberty Steel USA, Acerinox S.A, CMC Steel, Gerdau S.A, Schnitzer Steel Industries, Inc, Steel Dynamics, Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Steel Rebar Market Strategic Shifts & Innovations
The convergence of digitalization and sustainability is redefining operational standards and competitive benchmarks within the steel rebar industry. Producers are increasingly evaluated not just on product quality and cost, but also on their environmental footprint and integration with digital construction workflows.
Building Information Modeling (BIM) provides a digital 3D model-based process for construction project management. General contractors and engineering firms are accelerating their adoption of BIM, particularly for complex public infrastructure undertakings. This technology is virtualizing the rebar detailing, fabrication, and scheduling process, which significantly reduces on-site errors and material waste.
Environmental Protection Agency (EPA) regulations on industrial emissions are becoming more stringent for the steel sector. This forces producers to invest in cleaner manufacturing processes, primarily by enhancing the efficiency and environmental controls of electric arc furnaces. Mills that can demonstrate a lower carbon footprint gain a distinct advantage when bidding for government-funded projects that include sustainability criteria.
A notable behavioral shift involves project owners prioritizing life-cycle cost analysis over initial procurement price. This change in purchasing criteria disrupts the commodity-based sales model, creating preference for higher-performance products like epoxy-coated or stainless steel rebar. This trend is most visible in coastal states like Florida, where saltwater exposure makes long-term corrosion resistance a critical factor.
US Steel Rebar Market Segmentation
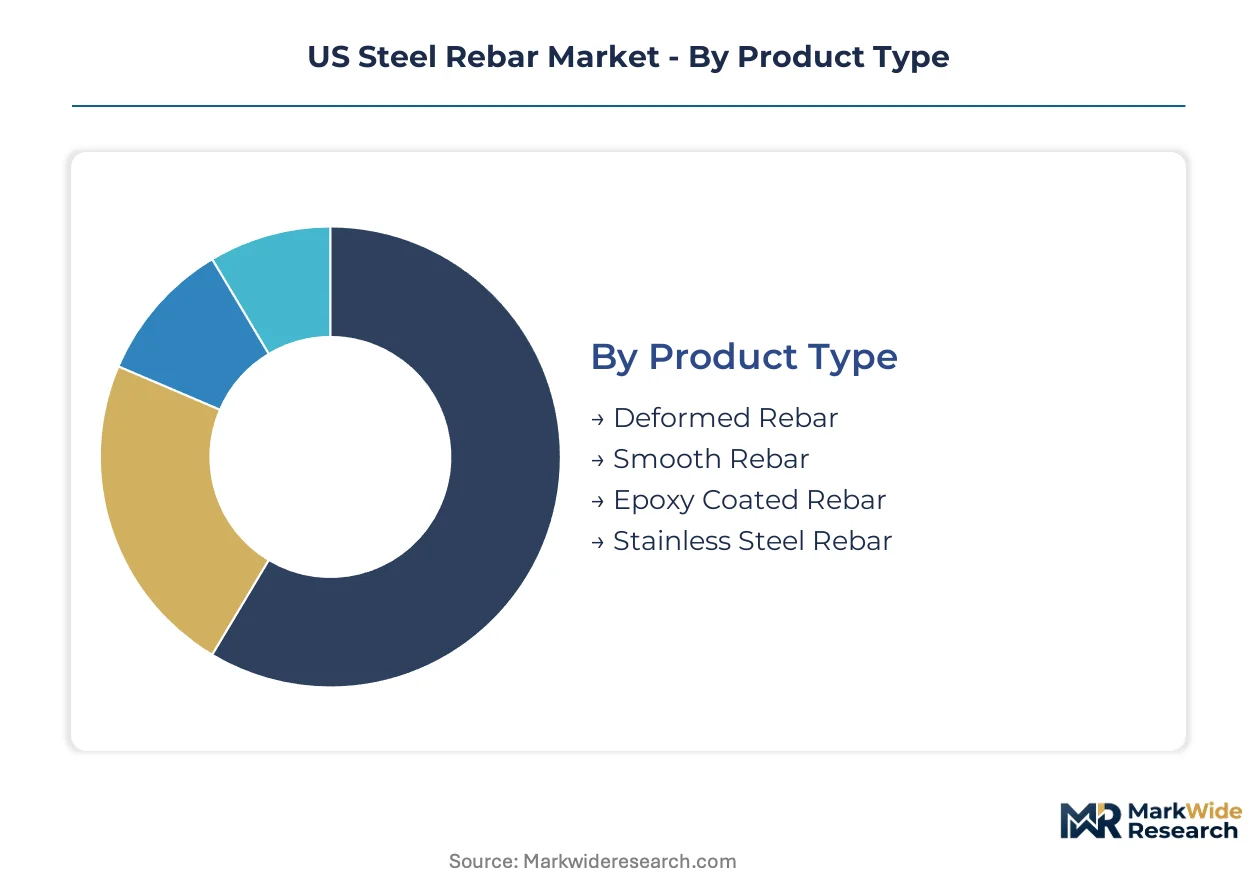
Understanding the segmentation within the US steel rebar market is essential for identifying specific demand patterns and strategic investment areas. This detailed breakdown highlights how product characteristics, end-user requirements, processing technologies, and distribution methods collectively shape market dynamics across the country.
Product Type:
After-sales-service intensity for steel rebar products is often dictated by the specific performance requirements of the application, influencing material selection and processing.
- Deformed Rebar:This steel bar features ribs or lugs along its surface, significantly enhancing its mechanical bond with concrete in reinforced structures. Demand from large-scale infrastructure projects, particularly federal highway and bridge construction, drives its widespread use due to superior bonding properties.
- Epoxy Coated Rebar:A carbon steel rebar protected by an epoxy resin coating, this variant offers enhanced corrosion resistance crucial for structures exposed to aggressive environments. Coastal infrastructure in states like Florida utilizes this product to extend service life and reduce maintenance costs.
- Smooth Rebar:Lacking deformations, this rebar type is primarily used for specialized applications such as dowel bars in concrete pavements or as ties and spirals in concrete columns.
- Stainless Steel Rebar:Offering exceptional corrosion resistance and high strength, this premium product is specified for critical structures where long-term durability and minimal maintenance are paramount, such as in highly corrosive marine environments.
By volume, Deformed Rebar leads. By growth pace, Epoxy Coated Rebar represents the fastest-growing trajectory.
End User:
Cost tier considerations heavily influence the selection of rebar end-user applications, balancing initial expenditure with long-term structural integrity.
- Infrastructure:This segment encompasses public works such as bridges, highways, dams, and water treatment facilities, which require substantial quantities of steel rebar for structural reinforcement. The Infrastructure Investment and Jobs Act provides significant funding, directly stimulating demand for rebar in these critical projects.
- Construction:Covering residential, commercial, and industrial building projects, this broad segment utilizes rebar for foundations, slabs, columns, and beams. Regional construction activity in high-growth states like Texas drives considerable rebar consumption.
- Manufacturing:Rebar finds application in the production of precast concrete products, including pipes, panels, and modular building components, contributing to off-site construction efficiencies.
- Energy:This sector uses rebar in the construction of power plants, oil and gas facilities, and renewable energy infrastructure, demanding robust materials for long-term operational stability.
Application complexity dictates product choice. Infrastructure projects demand robust rebar solutions, while Construction requires versatility across building types.
Technology:
Volume requirements significantly shape the choice of rebar production and processing technologies, impacting operational scale and efficiency.
- Hot Rolled:This is the predominant manufacturing method for rebar, involving heating steel billets to high temperatures and passing them through rollers to achieve the desired shape and size. Most US producers employ this cost-effective process for bulk rebar production.
- Bending:This technology involves shaping rebar into specific angles and forms according to architectural and engineering specifications, reducing on-site fabrication time. Value-added fabrication services often incorporate advanced bending capabilities for complex project designs.
- Cold Rolled:Produced by rolling steel at room temperature, cold-rolled rebar typically offers higher tensile strength and a smoother surface finish, suitable for specific precast concrete applications.
- Cutting:Rebar cutting technology enables precise sizing of steel bars to meet project-specific lengths, optimizing material usage and minimizing waste at construction sites.
Maturity levels vary across process technologies. Hot Rolled production is a foundational method, contrasting with specialized Bending services.
Distribution Channel:
Supply concentration within distribution channels directly impacts market access and logistical efficiency for steel rebar products across the United States.
- Direct Sales:Major rebar producers often engage in direct sales to large construction contractors and infrastructure project developers, facilitating bulk orders and long-term supply agreements. Nucor leverages its mill network for these direct relationships.
- Wholesale:Wholesalers act as intermediaries, purchasing rebar in large quantities from mills and distributing it to smaller contractors, fabricators, and local construction projects. This channel provides regional market access and inventory management.
- Online Retail:Emerging as a channel for smaller volume purchases or specialized rebar types, online platforms offer convenience for specific project needs and remote procurement.
- Others:This category includes specialized distributors, fabricators who also resell, and direct sales through construction material suppliers that are not primary wholesalers.
Customer type significantly influences channel selection. Large contractors prefer Direct Sales, whereas smaller businesses often utilize Wholesale options.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US steel rebar market exhibits a complex interplay of domestic production and imports, with regional demand patterns heavily influencing supply chain logistics. Domestic sourcing requirements from federal legislation prioritize US-produced rebar for public works. This dynamic shapes investment decisions and capacity utilization across key states.
Texas
Large-scale civil and commercial construction projects, alongside significant population growth, drive substantial rebar demand in Texas. The Infrastructure Investment and Jobs Act (IIJA) provides substantial funding for highway and bridge upgrades across the state. Houston's industrial base drives significant rebar consumption for energy infrastructure and urban development projects.
Florida
Florida's coastal infrastructure development, residential construction, and hurricane-resistant building codes create specific rebar requirements. Environmental Protection Agency (EPA) regulations influence material choices for corrosion resistance in the state's marine environments. Miami and Tampa Bay areas experience substantial demand for epoxy-coated rebar in high-rise and critical bridge construction.
California
California's extensive public transit projects, seismic retrofitting requirements, and renewable energy infrastructure initiatives necessitate considerable rebar volumes. The state's strict environmental policies impact production costs for steel mills operating within its borders. Los Angeles and San Francisco metropolitan areas drive demand for specialized rebar in complex architectural and engineering projects.
Northeast Corridor
Aging bridge and tunnel repair, urban redevelopment initiatives, and port infrastructure upgrades characterize rebar demand in the Northeast Corridor. Occupational Safety and Health Administration (OSHA) workplace safety rules directly affect construction site practices and rebar fabrication processes. New York City and Boston's dense urban environments require substantial quantities of rebar for deep foundations and high-rise structures.
US Steel Rebar Market Key Industry Players
On the supply side, the industry is moderately consolidated, with several large-scale producers dominating the market for bulk rebar across the United States. These major players often operate integrated mill networks, leveraging efficient electric arc furnace production methods to serve high-volume demand. Strategic archetypes include large-volume domestic producers, specialized product manufacturers, and regional fabricators with strong local ties. Dominant competitive moves involve capacity expansion to meet infrastructure demand and strategic partnerships with large construction contractors.
Among the large-volume domestic producers, Nucor exemplifies a company leveraging its extensive network of electric arc furnace mills to efficiently supply major infrastructure projects and meet significant federal demand. Gerdau S.A. anchors the specialized product manufacturing archetype, differentiating its offerings through a focus on advanced rebar variants designed for demanding construction applications and unique structural requirements. CMC Steel represents a key regional fabricator, sustaining its market position through robust localized distribution and comprehensive fabrication services, anchoring its presence in key construction markets across the southern United States.
| Leading Market Players |
|---|
| ArcelorMittal |
| EVRAZ U.S., Inc |
| Nucor |
| Liberty Steel USA |
| Acerinox S.A |
| CMC Steel |
| Gerdau S.A |
| Schnitzer Steel Industries, Inc |
| Steel Dynamics, Inc |
| Others |
Cost & Logistics Intelligence
Domestic scrap steel availability and efficient electric arc furnace operations directly influence profit margins for US rebar producers. This upstream concentration dictates cost structures that impact downstream project pricing.
Pricing Analysis
Large construction contractors anchor project-based pricing for steel rebar, often through long-term supply agreements. Price differentiation stems from product quality, such as corrosion-resistant epoxy-coated rebar, and geographic delivery costs to remote construction sites. Pricing pressure stems from volatile scrap steel and electricity input costs, compressing manufacturer margins. Smaller regional contractors and fabricators exhibit higher price sensitivity compared to large infrastructure developers with long-term contract needs.
Supply Chain Analysis
Major rebar producers like Nucor and Gerdau hold significant production capacity, shaping the US supply landscape. Geographic supply concentrates within key industrial states like Ohio, Pennsylvania, and Texas, where major mills operate. The supply chain relies on scrap steel and electricity as primary inputs for electric arc furnaces. Commodity price volatility for these inputs presents a structural risk, while distribution runs through direct sales to large contractors and wholesale channels for smaller projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US steel rebar market reflects a buyer-power shift, driven by the consolidation of large-scale infrastructure projects under federal funding initiatives. This concentrates purchasing power among a few major civil engineering firms and state DOTs.
For Market Incumbents: Entrench market leadership by expanding electric arc furnace capacity in high-growth regions like Texas to meet sustained infrastructure demand. Secure long-term supply contracts with major federal project contractors to counter input cost volatility. Invest in advanced EAF technology to reduce emissions, mitigating EPA regulatory pressures. Control regional distribution and fabrication services to protect market share against smaller, localized competitors.
For New Entrants and Emerging Players: Specialized rebar products for demanding applications, particularly in coastal states like Florida, represent a penetrable entry point. Focus on developing high-strength or corrosion-resistant variants for complex architectural and engineering projects. Offer value-added fabrication and detailing services to integrate deeper into construction workflows. A direct-to-engineering firm sales approach can capture niche demand for these higher-margin products.
For Investors and Strategic Acquirers: Capital is best deployed toward regional fabricators with strong localized distribution networks or EAF producers investing in lower-carbon production technologies for long-term viability. These targets offer resilience against logistical hurdles and align with evolving sustainability procurement goals. Acquire companies with established relationships with major civil engineering contractors. The signal to watch is the sustained allocation of federal infrastructure funding under the IIJA, indicating continued market stability.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in EAF Mills | Increases supply for large-scale infrastructure projects, leveraging efficient electric arc furnace technology. |
| Low-Carbon Production Investment | Aligns with EPA regulations and secures contracts from public clients prioritizing sustainability criteria. |
| Specialized Product Development | Captures higher-margin demand for corrosion-resistant rebar in coastal infrastructure applications. |
| Fabrication Services Integration | Deepens partnerships with construction contractors by offering value-added detailing and bending. |
| Regional Distribution Network Enhancement | Improves logistical efficiency and market access for rebar products across key construction markets. |
Research Approach
Desk research of ASTM standards, EPA reports, and construction association data preceded structured interviews with mill operators, civil engineers, procurement managers, and rebar fabricators. This primary fieldwork provided qualitative insights into market dynamics and competitive strategies. Secondary validation through company SEC filings and industry publications ensured data integrity. A rigorous bottom-up and top-down triangulation approach reconciled granular market observations with macro-level trends.
Assumptions regarding stable federal infrastructure spending and consistent economic growth were held fixed across the analysis window. The analytical framework modeled market dynamics by product type, end-user segment, processing technology, and distribution channel. Compound annual growth rates were derived from historical data trends and projected demand from major construction projects. Key industry-specific forecast inputs included anticipated Infrastructure Investment and Jobs Act disbursements and scrap steel price stability.
Macroeconomic conditions sit as an overlay; deviation in GDP growth or interest rates would shift the trajectory of construction activity. Forecasts reflect assumptions about regulatory stability and the continued implementation of infrastructure projects. Geopolitical events affecting raw material supply present a significant risk. Quarterly review of federal funding allocations and commodity price indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Elastomeric Expansion Joint Market
Building & Construction Materials
North America Cast-In-Place Concrete Flooring Market
Building & Construction Materials
North America Concrete Sealer Market
Building & Construction Materials
India Roofing Market
Building & Construction Materials
Architectural Window Films Market
Building & Construction Materials
Global Formwork Market
Building & Construction Materials
Plastic Door and Window Market
Building & Construction Materials
Spray Foam Insulation Market
Building & Construction Materials
Cement Grinding Aids Market
Building & Construction Materials
Asia-Pacific Construction Adhesives Market
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
Global Panelized and Modular Building System Market
Building & Construction Materials
Gulf Corporation Council Cement Market
Building & Construction Materials
US Parking Deck Coatings Market
Building & Construction Materials
North America Concrete Cellulose Fiber Reinforcement Market
Building & Construction Materials
Poland Ceramic Tiles Market