
 Manufactured Sand Market | 2026-2036
Manufactured Sand Market Size, Share, and Industry Trends Forecast 2026-2036
Manufactured Sand Market Foresight
Ready-mix concrete supply chains is reconfiguring around manufactured sand as batching plants seek consistent gradation and lower moisture variance. Holcim leverages vertical integration into aggregate quarries to secure feedstock for its crushing operations across multiple continents. Heidelberg Materials anchors its position through dense terminal networks that blend manufactured sand with supplementary cementitious materials. CEMEX competes by operating coastal distribution hubs that reduce inland freight costs for high-volume concrete producers.
Manufactured sand consists of angular particles produced by crushing hard rock deposits and screening to precise gradation bands, typically conforming to Zone II fineness modulus for structural concrete applications. Concrete Production absorbs the largest volume share as engineers specify manufactured sand to meet IS 383 and ASTM C33 durability targets in aggressive exposure classes. Road Infrastructure represents the fastest-expanding application segment as national highway authorities mandate crushed stone sand in flexible pavement base courses to reduce plastic deformation under heavy axle loads.
India's Central Pollution Control Board enforces emission caps on crushing plants, while the Bureau of Indian Standards certifies gradation compliance through mandatory IS 383 testing protocols. The US EPA regulates particulate matter from aggregate processing under New Source Performance Standards, pushing operators toward enclosed crushing circuits and wet suppression systems. Stakeholders must monitor evolving cement-to-sand ratio specifications in green building codes and decide whether to invest in air classification upgrades or modular washing plants to meet anticipated chloride and silt thresholds.
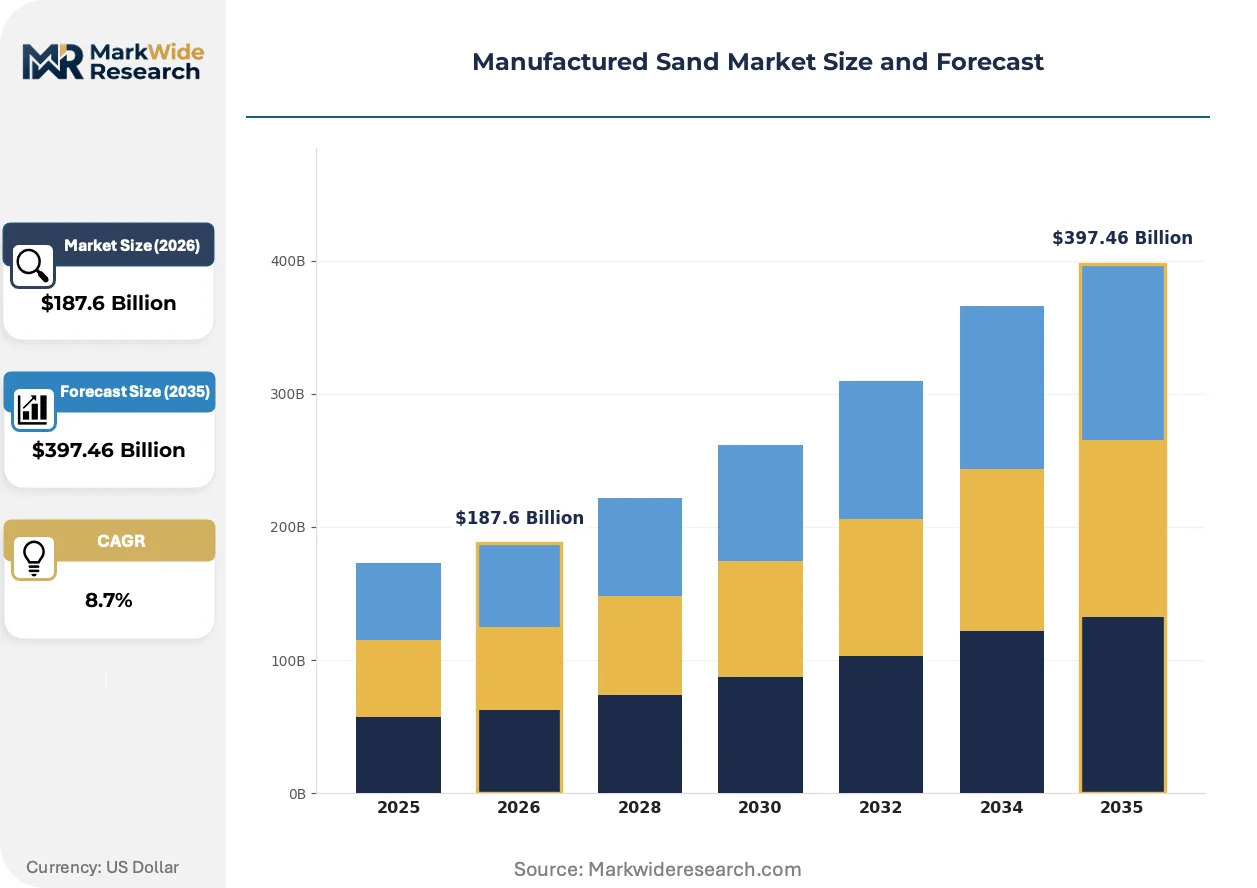
Market Dynamics
India's environmental clearance moratoriums on river sand mining are forcing concrete producers to retool batching specifications around manufactured sand gradation bands. This structural supply compression is redrawing procurement hierarchies across infrastructure corridors.
Growth Catalysts
- IS 383 Mandate Expansion:India's Bureau of Indian Standards now requires manufactured sand certification for all government-funded concrete projects above specified volume thresholds, locking in institutional demand.
- Coastal Infrastructure Corridors:Dense highway and port development along India's western seaboard concentrates offtake from Gujarat through Maharashtra crushing zones.
- Wet Suppression Systems:Advanced dust control technology enables crushing plants to operate within Central Pollution Control Board emission caps without production interruptions.
Market Restraints
- Diesel Price Volatility:Quarry haulage costs swing with fuel pricing, compressing margins for inland crushing operations serving distant batching plants.
- Hard Rock Deposit Concentration:Quality feedstock clusters in Karnataka and Andhra Pradesh, creating supply vulnerability for northern Indian concrete producers.
- Natural Sand Subsistence:Illicit riverbed extraction persists in regulatory gaps, undercutting manufactured sand price floors in informal construction markets.
Strategic Opportunities
- Rajasthan Desert Sand Processing:Dune sand beneficiation technology opens feedstock reserves previously excluded from structural concrete specifications.
- Pre-cast Concrete Vertical:Factory-controlled manufacturing environments favor manufactured sand's moisture consistency over variable natural sand.
- PLI Scheme Alignment:India's production-linked incentive framework for construction materials rewards capital investment in automated crushing and classification equipment.
Industry Challenges
- Gradation Control Expertise:Crushing plant operators lack sufficient process engineers to maintain Zone II fineness modulus consistency across variable feedstock hardness.
- Batching Plant Retrofit Costs:Legacy concrete mixing infrastructure requires sensor and calibration upgrades to handle manufactured sand's angular particle geometry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manufactured Sand Market |
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $397.46 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crushed Stone, Crushed Gravel, Recycled Sand, Concrete Sand Application: Construction, Road Infrastructure, Concrete Production, Mortars Distribution Channel: Direct Sales, Online Sales, Retail Outlets, Distributors End User: Construction Companies, Infrastructure Developers, Concrete Manufacturers, Road Contractors |
| Companies Covered | Holcim, Heidelberg Materials, CEMEX, CRH plc, Vulcan Materials Company, Martin Marietta Materials, CDE Global, Metso Outotec, Adani Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manufactured Sand Market Shifts & Advancements
Processing technology and specification science are converging to elevate manufactured sand from substitute material to preferred input for durability-critical concrete applications.
Air classification systems with real-time particle size feedback are rendering obsolete manual screening and stockpile blending methods. Large infrastructure contractors in Maharashtra and Karnataka are adopting these systems at greenfield crushing installations. The technology compresses quality variance to half the tolerance bands acceptable under older processing regimes.
India's Central Pollution Control Board is tightening particulate matter thresholds for crushing plant operations in designated airshed zones. Operators must enclose primary and secondary crushing circuits or face production halts during winter air quality emergencies. Western Indian plants near Mumbai and Pune metropolitan regions face the steepest compliance timelines.
Engineers now specify manufactured sand by performance grade rather than origin source in tender documents. State public works departments in Tamil Nadu and Telangana have rewritten standard specifications to reference IS 383 durability classes directly. This behavioral shift transfers specification authority from quarry geologists to concrete mix designers at project engineering firms.
Manufactured Sand Market Segmentation
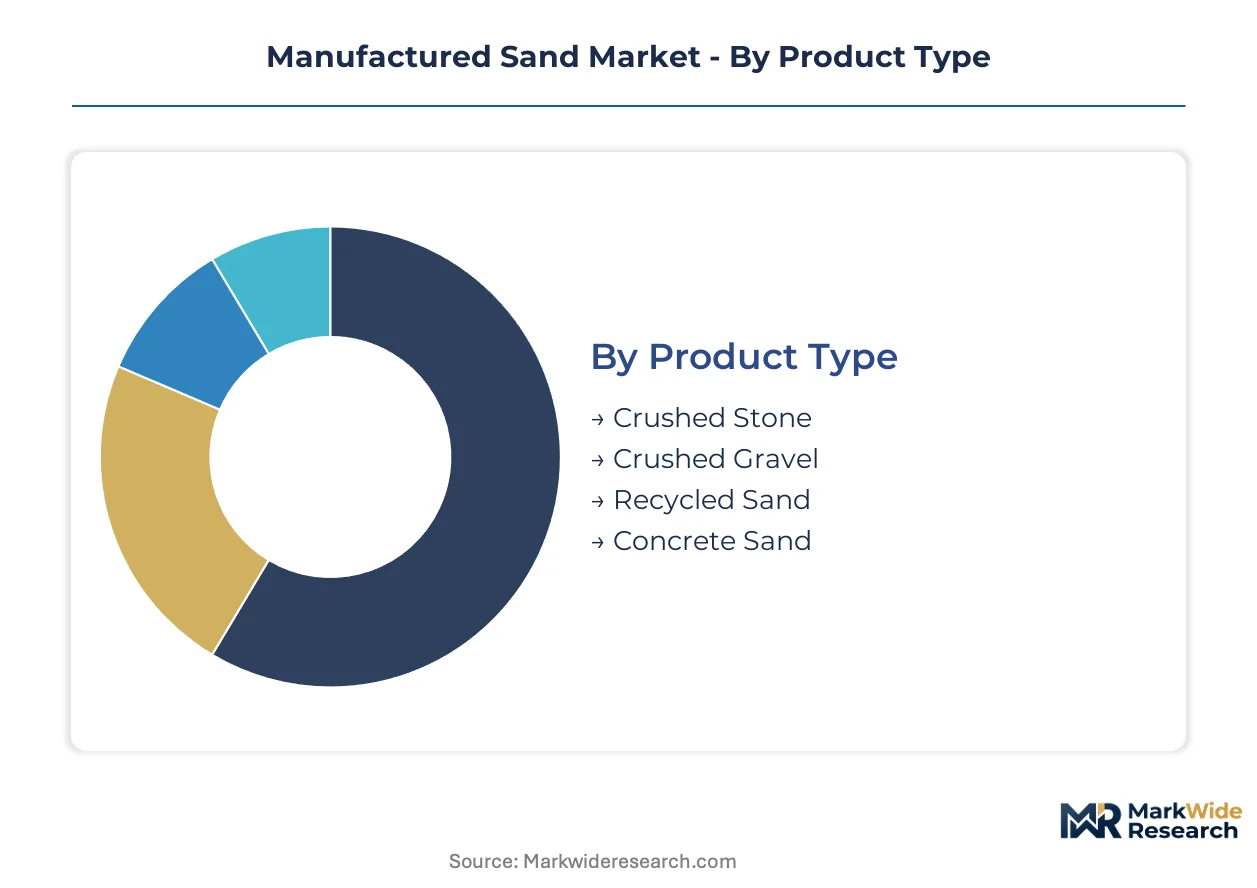
Manufactured sand procurement patterns diverge sharply across product specifications and end-use requirements. Engineers specify particle geometry and gradation bands differently for structural concrete versus road base courses. Distribution economics shift with haulage distances and batching plant automation levels.
Product Type:
Mature crushing technologies dominate high-volume segments while emerging beneficiation methods unlock marginal feedstocks.
- Crushed Stone:Angular particles produced from hard rock deposits deliver Zone II fineness modulus for structural concrete. Western Indian infrastructure corridors concentrate procurement as Maharashtra and Gujarat highway authorities mandate IS 383 compliance for all flexible pavement projects.
- Crushed Gravel:Pebble-derived material offers lower crushing energy requirements and reduced flakiness index. Karnataka and Andhra Pradesh quarry clusters supply this grade to pre-cast concrete factories seeking consistent moisture content for automated batching systems.
- Recycled Sand:Construction and demolition waste beneficiation yields secondary aggregate for non-structural fill applications. Delhi NCR municipalities incentivize procurement through landfill diversion credits.
- Concrete Sand:Premium-processed material with controlled chloride and silt content meets aggressive exposure class specifications. Tamil Nadu coastal infrastructure projects specify this grade for marine environment durability.
Crushed stone retains volume leadership; recycled sand holds the steepest expansion curve.
Application:
End-use specifications create tiered demand intensity based on performance liability and durability exposure.
- Concrete Production:Ready-mix and pre-cast manufacturers specify manufactured sand for compressive strength consistency and reduced cement factor. Mumbai and Pune metropolitan batching plants retool mix designs around angular particle geometry as river sand supply contracts.
- Road Infrastructure:National highway authority mandates for flexible pavement base courses drive specification adoption. Western Indian corridor development from Gujarat through Maharashtra concentrates offtake from coastal crushing zones.
- Construction:General building applications absorb variable-grade material for masonry and plastering. Informal markets in northern India face price pressure from illicit natural sand extraction.
- Mortars:Factory-mixed and site-mixed applications require controlled gradation for workability. Pre-mixed mortar plants in Telangana and Karnataka specify manufactured sand for consistent bonding properties.
Concrete production commands the largest volume share; road infrastructure is climbing the fastest.
Distribution Channel:
Channel selection tracks customer scale, technical service requirements, and logistics infrastructure maturity.
- Direct Sales:Large infrastructure contractors and ready-mix chains procure truckload volumes from crushing plant gate. Western Indian producers near Mumbai bypass intermediaries for metropolitan batching plant contracts.
- Distributors:Regional aggregators stockpile blended grades for mid-size construction firms lacking direct quarry access. Rajasthan and Madhya Pradesh distribution networks extend reach to inland markets.
- Retail Outlets:Small-lot sales serve individual builders and repair contractors through construction material yards. Urban centers maintain higher outlet density than rural corridors.
- Online Sales:Digital procurement platforms emerge for standardized grade matching and transparent pricing. Early adoption concentrates among organized real estate developers in Bangalore and Hyderabad.
Direct sales retains volume leadership; online sales is gaining share fastest.
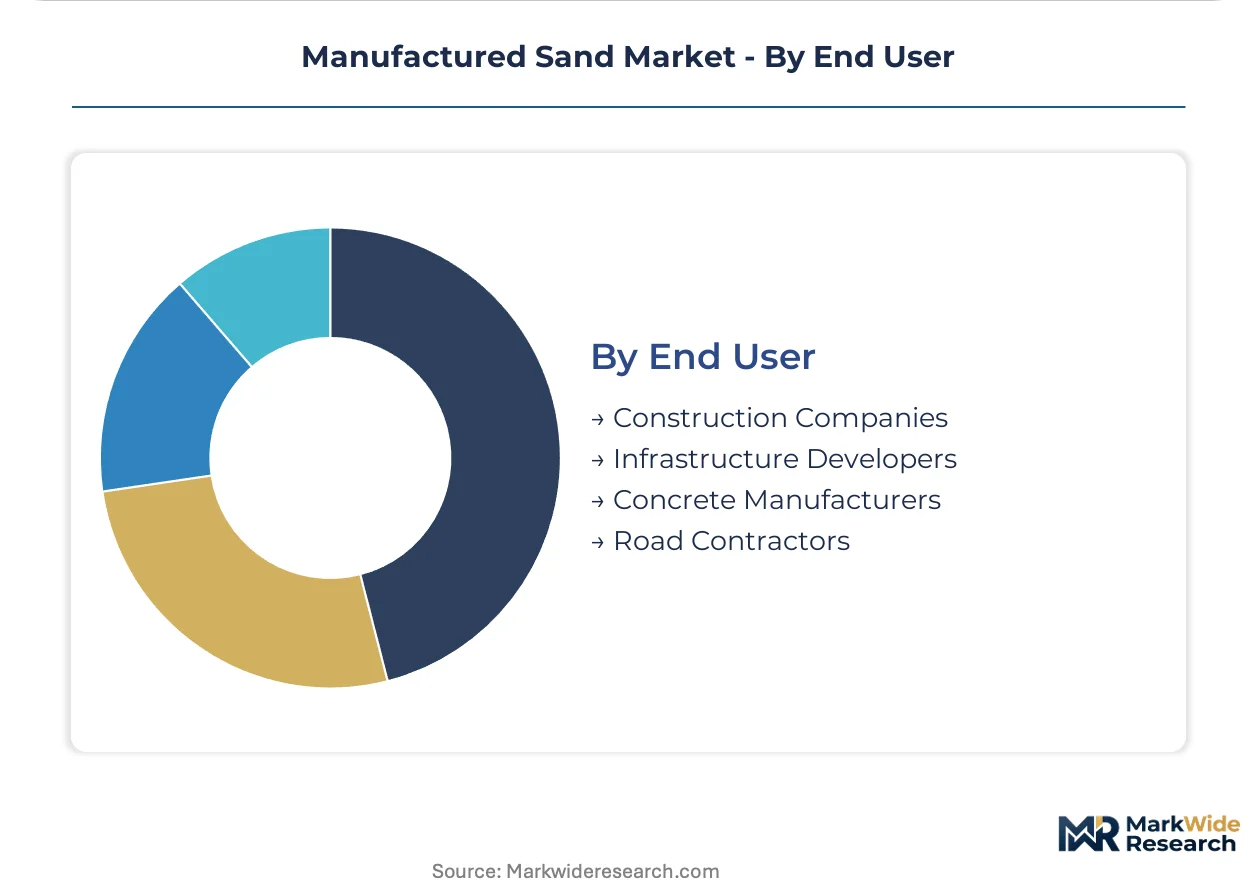
End User:
Customer technical capability determines specification stringency and quality assurance protocols.
- Concrete Manufacturers:Ready-mix and pre-cast producers maintain in-house testing laboratories for IS 383 compliance verification. Automated batching infrastructure in Maharashtra and Gujarat demands consistent moisture variance below manual processing thresholds.
- Infrastructure Developers:Large-scale highway and port projects specify performance-graded material with durability class certification. Coastal corridor developers in Tamil Nadu and Andhra Pradesh enforce chloride content limits for marine exposure.
- Construction Companies:General building contractors balance cost and workability for structural and non-structural applications. Tier-one firms specify manufactured sand; smaller operators face price competition from informal natural sand markets.
- Road Contractors:Flexible pavement specialists procure crushed stone sand for base course stability under heavy axle loads. National highway authority mandates accelerate specification adoption across western and southern India.
Concrete manufacturers command the largest procurement volumes; infrastructure developers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in western India exceeds northern hinterland markets by substantial margins due to coastal infrastructure density and regulatory enforcement gaps elsewhere. This asymmetry shapes investment flows toward crushing corridor development along dense highway networks.
India
Maharashtra and Gujarat infrastructure corridors absorb the highest manufactured sand volumes as state public works departments enforce IS 383 compliance for all government concrete procurement. The Central Pollution Control Board emission caps on crushing plants accelerate wet suppression system adoption near Mumbai and Pune metropolitan regions. Coastal highway development from Bharuch through Thane concentrates crushing capacity within 150 kilometers of batching plant clusters.
United States
Texas and California infrastructure spending drives specification adoption as state transportation departments rewrite base course material standards. The US EPA New Source Performance Standards push aggregate processors toward enclosed crushing circuits and continuous emissions monitoring systems. Vulcan Materials and Martin Marietta quarry clusters across the Southeast and Southwest supply manufactured sand to metropolitan ready-mix networks.
China
Yangtze River Delta and Pearl River Delta urbanization absorbs premium-processed manufactured sand for high-rise concrete specifications. The Ministry of Ecology and Environment particulate matter thresholds force Yangtze basin crushing plants toward wet processing retrofits. Zhejiang and Jiangsu province quarry operators invest in air classification systems to meet Shanghai municipal quality standards.
Germany
Baden-Württemberg and Bavaria construction activity specifies manufactured sand for pre-cast concrete and road base applications as natural gravel deposits deplete. The EU Green Deal circular economy targets incentivize construction and demolition waste beneficiation for secondary aggregate production. Heidelberg Materials quarry networks along the Rhine corridor supply processed material to Stuttgart and Munich metropolitan batching plants.
United Arab Emirates
Dubai and Abu Dhabi megaproject development specifies manufactured sand for marine environment concrete as dune sand fails durability testing. The Ministry of Climate Change and Environment regulates aggregate processing emissions in designated airshed zones near metropolitan centers. NEOM and Red Sea Project corridors in the northwest anchor greenfield crushing investments with automated classification infrastructure.
Manufactured Sand Market Competitive Landscape
Vertically integrated building materials conglomerates and specialized aggregate processors split the market along specification intensity lines. The structure concentrates around three archetypes: multinational cement producers with captive quarry networks, independent aggregate specialists with regional crushing density, and equipment technology providers licensing processing systems. Capacity expansion near infrastructure corridors and strategic partnerships with batching plant operators constitute the dominant competitive moves.
Among multinational building materials conglomerates, Holcim, Heidelberg Materials, and CEMEX exemplify the vertically integrated archetype through quarry-to-concrete supply chain control. Holcim represents the scale-driven model with crushing operations spanning multiple continents. Heidelberg Materials anchors European manufactured sand supply through dense terminal networks blending processed aggregates with supplementary cementitious materials. CEMEX occupies a coastal distribution position that reduces inland freight costs for high-volume concrete producers.
| Leading Market Players |
|---|
| Holcim |
| Heidelberg Materials |
| CEMEX |
| CRH plc |
| Vulcan Materials Company |
| Martin Marietta Materials |
| CDE Global |
| Metso Outotec |
| Adani Group |
| Others |
Supply & Pricing Matrix
Maharashtra's coastal crushing corridor anchors pricing power across western India as capacity concentration near Mumbai and Pune metropolitan batching plants compresses haulage costs. This geographic clustering enables producers to command premiums for IS 383-certified grades while inland operators absorb diesel volatility.
Pricing Analysis
The customization-premium spread separates Zone II fineness modulus certified material from variable-grade construction sand. Three-tier pricing structure across premium, standard, and economy levels tracks certification stringency and moisture consistency. Pricing pressure stems from illicit river sand extraction in regulatory gaps, eroding price floors in informal northern Indian markets. Large ready-mix chains exhibit lowest price sensitivity due to specification lock-in, while small construction contractors face acute cost pressure.
Supply Chain Analysis
Tariff exposure between India and equipment-importing jurisdictions dominates supply chain risk for crushing plant operators sourcing Metso Outotec and CDE Global processing systems. Geographic supply concentration centers on Karnataka and Andhra Pradesh hard rock deposits, with secondary clusters in Gujarat and Rajasthan. Raw material dependencies include quarry explosives, wear-resistant manganese steel for crushing liners, and flocculants for wet processing circuits. Distribution runs through direct gate sales to large contractors, regional distributor stockpiles for mid-tier builders, and emerging digital platforms for organized real estate developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection as digital procurement platforms aggregate fragmented buyer demand and standardize grade matching, shifting power toward transparent price discovery.
For Market Incumbents: Pre-empt margin compression from digital intermediaries by locking long-term offtake agreements with metropolitan ready-mix chains. Anchor backward integration into captive quarry networks to secure feedstock against Karnataka deposit depletion. Invest in automated air classification systems to defend specification premiums against emerging beneficiation competitors.
For New Entrants and Emerging Players: Build out Rajasthan dune sand beneficiation capacity as regulatory acceptance of desert sand processing creates new feedstock economics. Target pre-cast concrete verticals in Telangana and Karnataka where moisture consistency commands specification premiums. Pursue equipment-leasing partnerships with CDE Global to minimize capital intensity at greenfield installations.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because emission enforcement by India's Central Pollution Control Board will strand sub-scale crushing capacity. Target mid-sized operators with wet suppression retrofit capabilities and coastal corridor logistics access. Monitor BIS certification audit backlogs as the inflection signal for regulatory capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hard Rock Quarries | Secures feedstock against Karnataka and Andhra Pradesh deposit concentration. |
| Wet Suppression System Retrofit | Enables Central Pollution Control Board compliance without production halts. |
| Air Classification Technology Deployment | Compresses Zone II fineness modulus variance below manual screening tolerances. |
| Digital Procurement Platform Partnership | Aggregates fragmented construction demand for transparent grade matching. |
| Pre-cast Concrete Vertical Specialization | Captures moisture-consistency premiums from automated batching systems. |
Research Methodology
Initial hypotheses were tested against primary input from crushing plant operators, ready-mix concrete procurement managers, state public works department engineers, and Bureau of Indian Standards certification auditors and refined through secondary validation. Sources included customs data on quarry equipment imports, Central Pollution Control Board emission compliance records, IS 383 testing protocol documentation, and infrastructure project tender specifications. Bottom-up capacity modeling triangulated against top-down demand estimates from highway authority concrete volume projections.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed product type gradation bands, application durability classes, distribution channel automation levels, and end-user technical capability tiers. CAGRs derived from capacity expansion pipelines, regulatory enforcement trajectories, and substitution elasticity between manufactured and river sand. Industry-specific inputs included diesel price volatility assumptions and wet suppression technology adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Adani Group or Aditya Birla Group would shift outcomes through price-led market share capture. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Sheet Piling Market
Building & Construction Materials
Precast Concrete Pile Market
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
Poland Cement Market
Building & Construction Materials
North America Cross-Laminated Timber Market
Building & Construction Materials
India Ceramic Tiles Market
Building & Construction Materials
Polished Concrete Market
Building & Construction Materials
Turkey Ceramic Tiles Market
Building & Construction Materials
Drywall and Gypsum Board Market
Building & Construction Materials
US Steel Rebar Market
Building & Construction Materials
United Kingdom Timber Cladding Market
Building & Construction Materials
Global Wooden Formwork Systems Market
Building & Construction Materials
US Retractable Roofing System Market
Building & Construction Materials
Autoclave Aerated Concrete Market
Building & Construction Materials
Plastic Decking Market
Building & Construction Materials
Global Raised Access Floor Systems Market