
 Curtain Wall Market | 2026-2036
Curtain Wall Market Size, Share, and Industry Trends Forecast 2026-2036
Curtain Wall Market Analysis
Buyer concentration among property developers is shifting toward a smaller pool of institutional investors and sovereign wealth funds funding megaprojects. Schüco leverages its European engineering base to dominate premium unitized systems for climate-sensitive envelopes. Yuanda Holding Group anchors its position through manufacturing scale across China's coastal provinces. YKK AP competes on precision extrusion capabilities that reduce field labor for stick-built installations.
A curtain wall is a non-load-bearing exterior cladding system comprising aluminum framing, infill panels, and glazing, engineered to resist wind loads and thermal transfer while accommodating structural movement. The system seals the building envelope, controls daylight penetration, and manages interstitial moisture through pressure-equalized rainscreen principles. Unitized systems command premium margins due to factory-controlled quality and compressed site schedules, while stick-built methods retain share in retrofit and constrained-access projects. Aluminum framing leads volume, though fiber reinforced polymer is gaining traction where thermal bridging penalties intensify under evolving energy codes.
China's GB standards and the EU's Energy Performance of Buildings Directive tighten thermal transmittance thresholds, forcing specification upgrades in glazing and thermal breaks. The US EPA and ICC code cycles push envelope commissioning requirements that elevate documentation burdens for contractors. Japan's METI building efficiency guidelines and local fire safety codes in Dubai and Singapore add compliance layers for international project portfolios. Stakeholders must monitor regulatory divergence between performance-based and prescriptive standards when selecting system suppliers for multi-jurisdiction pipelines.
Market Dynamics
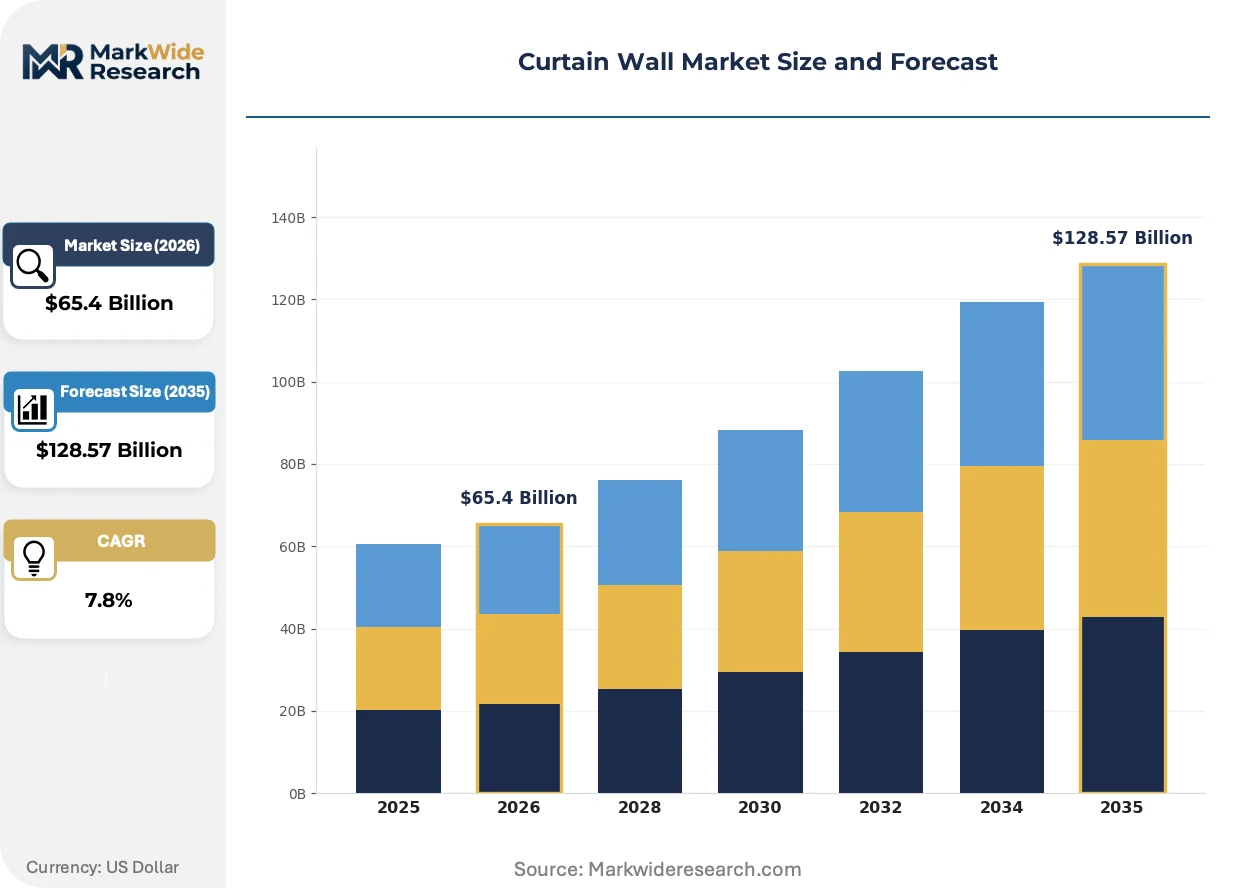
China's GB 55015-2021 building energy efficiency standard and the EU's Energy Performance of Buildings Directive are forcing specification upgrades across thermal breaks and glazing packages, compressing margins for contractors unable to certify performance.
Growth Catalysts
- Supertall construction clusters:China's tier-one cities—Shanghai, Shenzhen, Beijing—anchor demand for unitized systems engineered to resist wind loads exceeding 200 km/h at altitude. These projects require factory-controlled quality that stick-built methods cannot replicate.
- GB 55015-2021 thermal transmittance thresholds:China's national building code mandates stricter envelope performance, compelling developers to specify triple-glazed units with warm-edge spacers and polyamide thermal breaks.
- Pressure-equalized rainscreen engineering:Advanced cavity ventilation designs are displacing face-sealed systems in humid subtropical climates, reducing warranty claims and accelerating adoption across Southeast Asian commercial portfolios.
Market Restraints
- Primary aluminum price volatility:London Metal Exchange aluminum contract swings directly compress framing system margins, with no viable substitution for structural mullions in unitized curtain walls.
- Float glass supply concentration:Chinese state-owned enterprises control 60% of global architectural glass capacity, creating single-source risk for international project pipelines.
- Structural silicone sealant cure-time limitations:Factory glazing requires 14-21 day cure cycles that cannot compress further without compromising shear adhesion, constraining unitized panel throughput.
Strategic Opportunities
- India's commercial real estate acceleration:Bangalore and Hyderabad office construction is adopting unitized systems for the first time, creating first-mover advantage for suppliers with local fabrication partnerships.
- Retrofit rainscreen overcladding:Aging 1970s curtain wall stock in Frankfurt and London presents white-space demand for lightweight fiber-reinforced polymer panels that improve thermal performance without structural reinforcement.
- EU Green Deal renovation wave:The 2050 climate neutrality mandate triggers public funding for envelope upgrades, directing specification toward certified Passive House-compatible curtain wall assemblies.
Industry Challenges
- Facade engineer talent scarcity:Computational fluid dynamics modeling for wind-driven rain and thermal bridging analysis requires specialized expertise concentrated in Düsseldorf and Tokyo consultancies.
- Multi-jurisdiction certification timelines:Projects spanning Dubai's Civil Defence requirements and Singapore's SCDF fire safety codes face 8-12 month approval cycles that delay construction mobilization.
- Legacy building interface complexity:Retrofit curtain wall installation demands precise tolerance management against existing structural frames, often requiring custom steel anchorage fabrication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Curtain Wall Market |
| Market Size in 2026 | $65.4 Billion |
| Market Size in 2035 | $128.57 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stick-built, Unitized, Semi-unitized, Structural Glazing Material: Aluminum, Glass, Steel, Fiber Reinforced Polymer Application: Commercial Buildings, Residential Towers, Institutional Structures, Mixed-use Developments End User: Architects, Contractors, Property Developers, Building Owners |
| Companies Covered | Kawneer (Arconic), Schüco, Permasteelisa, Josef Gartner, Enclos, Yuanda Holding Group, YKK AP, Reynaers Aluminium, Jangho Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Curtain Wall Market Emerging Trajectories
Active glazing technologies and bio-based insulation materials are converging with digital fabrication workflows to redefine performance expectations and procurement economics across commercial envelope specification.
Vacuum-insulated glass panels with center-of-glass U-values below 0.4 W/m²K are expanding into Nordic commercial construction, where developers in Oslo and Stockholm specify these units to meet nearly zero-energy building standards without thick triple-glazed profiles. The technology compresses structural framing depth by 40%, enabling slimmer sightlines that architects prioritize for premium office towers.
The EU's F-Gas Regulation phase-down is forcing manufacturers to abandon SF6-filled insulating glass units in favor of krypton and xenon alternatives, raising unit costs but eliminating regulatory liability. German fabricators are responding fastest, with Rhine-Ruhr suppliers already certifying krypton-filled lines under CE marking protocols that other EU member states are adopting.
Developer procurement teams are consolidating specification authority into centralized technical departments, displacing architect-led material selection on megaprojects above 50,000 m². This concentration is most visible across Middle Eastern sovereign wealth fund developments, where in-house facade engineers now issue performance-based tenders that pre-qualify only three system suppliers per project.
Curtain Wall Market Segmentation
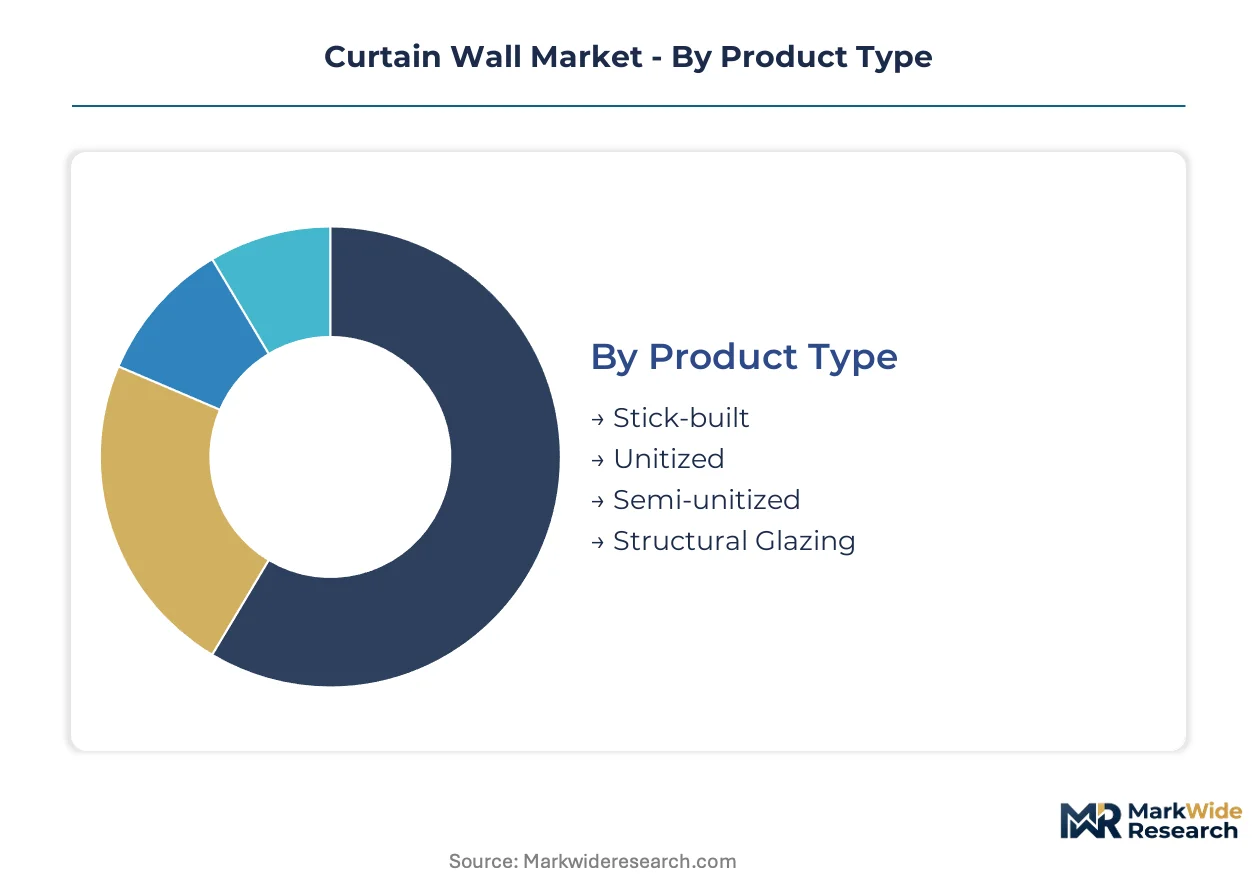
Curtain wall specification decisions cascade through project economics, thermal performance mandates, and installation logistics. Each segmentation dimension reveals distinct buyer priorities that reshape competitive positioning across the supply base.
Product Type:
Project schedule compression and site labor availability drive system selection more than first-cost considerations.
- Stick-built:Field-assembled aluminum mullions and transoms accommodate irregular geometries and constrained urban sites where crane access is limited. Retrofit demand in Frankfurt and London relies on this flexibility for 1970s building stock upgrades.
- Unitized:Factory-glazed panels with integrated thermal breaks and pressure-equalized cavities dominate supertall construction in Shanghai and Shenzhen. GB 55015-2021 thermal transmittance thresholds compel developers to specify these systems for quality assurance at altitude.
- Semi-unitized:Hybrid approaches blend factory-glazed vision panels with field-installed spandrel sections, balancing throughput speed with customization for mid-rise commercial towers.
- Structural Glazing:Silicone-bonded glass fins eliminate visible metal framing, serving architect-driven premium office specifications where sightline minimalism commands priority.
Unitized systems lead on scale; structural glazing leads on momentum in architecturally significant towers.
Material:
Energy code stringency is forcing substitution decisions that trade thermal performance against structural properties.
- Aluminum:Extruded 6063-T6 alloy mullions provide the strength-to-weight ratio required for unitized panel lifting and wind load resistance. London Metal Exchange price volatility compresses margins without viable substitution for primary structural members.
- Glass:Triple-glazed units with warm-edge spacers and low-emissivity coatings satisfy EU Energy Performance of Buildings Directive thresholds in Oslo and Stockholm commercial construction.
- Steel:Cold-formed framing penetrates fire-rated spandrel zones where aluminum's 660°C melting point fails building code requirements.
- Fiber Reinforced Polymer:Pultruded profiles eliminate thermal bridging penalties in Passive House-certified retrofits across Germany's Rhine-Ruhr corridor.
Aluminum dominates volume; fiber reinforced polymer expands most quickly under tightening thermal codes.
Application:
Building typology determines envelope performance risk exposure and warranty liability concentration.
- Commercial Buildings:Speculative office towers in Bangalore and Hyderabad drive first-time unitized system adoption as institutional investors demand accelerated construction schedules.
- Residential Towers:High-rise multifamily construction in China's tier-one cities specifies pressure-equalized rainscreen engineering to manage interstitial moisture in humid subtropical climates.
- Institutional Structures:Government and healthcare projects in Dubai face Civil Defence fire safety codes that extend certification timelines.
- Mixed-use Developments:Sovereign wealth fund megaprojects above 50,000 m² consolidate procurement authority into centralized technical departments that issue performance-based tenders.
Commercial buildings anchor demand; mixed-use developments concentrate specification innovation.
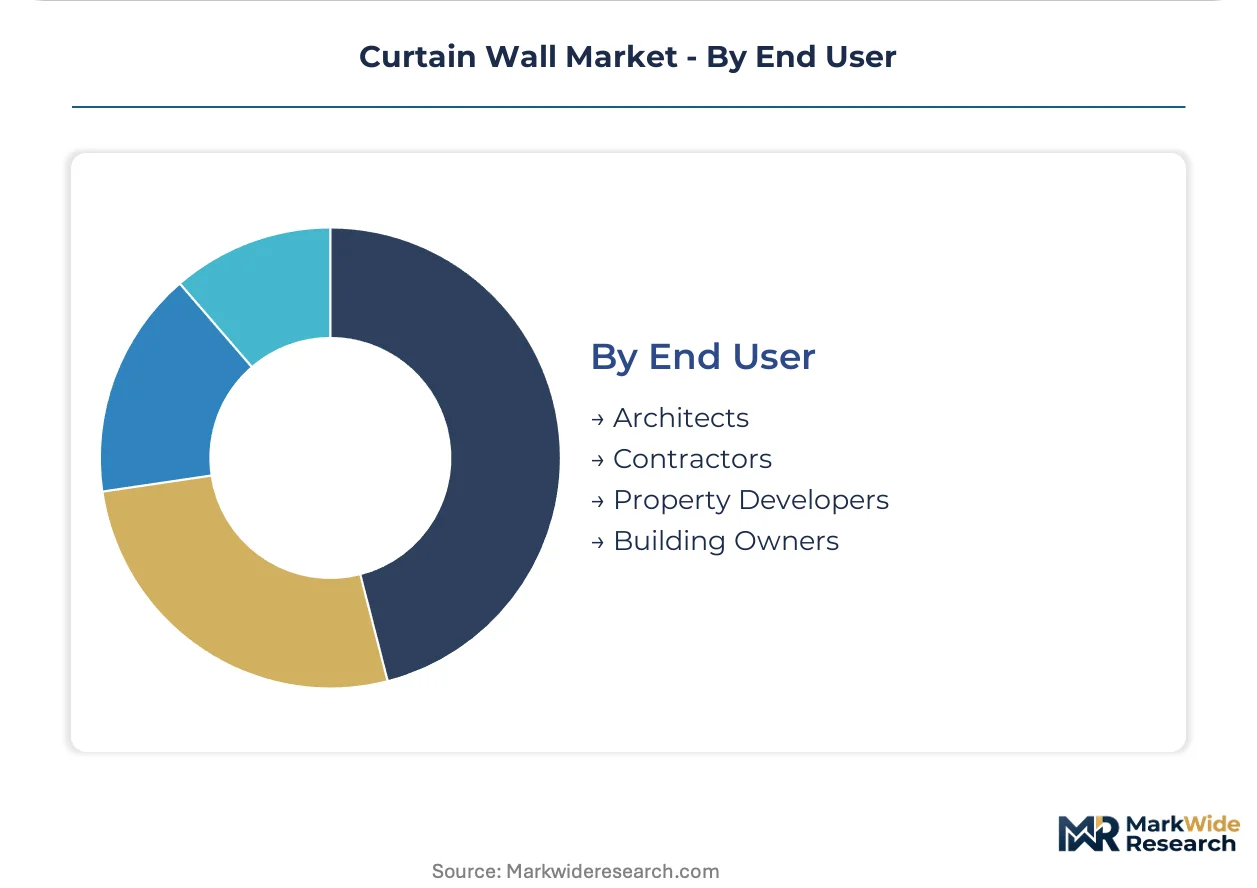
End User:
Technical authority over material selection is migrating from design teams to construction-phase stakeholders.
- Architects:Design-phase specification of glazing performance criteria and sightline aesthetics faces erosion as developer procurement teams consolidate authority.
- Contractors:Envelope commissioning requirements under US EPA and ICC code cycles elevate documentation burdens, favoring contractors with certified facade engineering capabilities.
- Property Developers:Institutional investors and sovereign wealth funds now pre-qualify only three system suppliers per megaproject, compressing the viable vendor pool.
- Building Owners:Post-occupancy energy cost liability drives retrofit rainscreen overcladding decisions for aging 1970s curtain wall stock.
Property developers lead on procurement scale; contractors gain momentum through commissioning compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facade engineering talent concentrates in Düsseldorf, Tokyo, and Shanghai consultancies, anchoring regional technical capability clusters that service adjacent construction markets. This expertise distribution shapes where advanced curtain wall systems achieve specification dominance.
China
Supertall construction in Shanghai, Shenzhen, and Beijing drives unitized system adoption for wind loads exceeding 200 km/h at altitude. GB 55015-2021 thermal transmittance thresholds compel triple-glazed units with warm-edge spacers and polyamide thermal breaks. Yuanda Holding Group leverages manufacturing scale across coastal provinces to anchor domestic supply.
Germany
The Rhine-Ruhr corridor leads Passive House-certified retrofit demand for fiber-reinforced polymer panels that eliminate thermal bridging penalties. EU F-Gas Regulation phase-down forces krypton-filled insulating glass certification under CE marking protocols. Schüco dominates premium unitized systems through its European engineering base.
United States
Envelope commissioning requirements under EPA and ICC code cycles elevate documentation burdens for contractors with certified facade engineering capabilities. Commercial high-rise construction concentrates specification authority among institutional investors funding megaprojects. Enclos occupies a position within the specialized engineering tier serving altitude-sensitive installations.
Japan
METI building efficiency guidelines tighten thermal performance expectations for commercial envelopes in Tokyo and Osaka. YKK AP competes on precision extrusion capabilities that reduce field labor for stick-built installations. Kanto region fabricators supply pressure-equalized rainscreen systems for humid subtropical climate management.
India
Bangalore and Hyderabad office construction adopts unitized systems for the first time as institutional investors demand accelerated construction schedules. CEA electrical safety codes intersect with envelope performance for mixed-use towers. Jangho Group exemplifies the cross-border specialist archetype establishing local fabrication partnerships for first-mover advantage.
Curtain Wall Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: European engineering-led premium system houses, Asian manufacturing-scale fabricators, and North American installation-specialized contractors. Consolidation pressures intensify as developer procurement teams pre-qualify shrinking supplier pools per megaproject. Dominant competitive moves include backward integration into aluminum extrusion capacity and technology licensing for thermal break innovation.
Among European-based fabricators, Schüco and Reynaers Aluminium exemplify the engineering-intensive archetype dominating climate-sensitive envelope specification. Kawneer represents the North American installation-specialized tier with Arconic corporate backing. Josef Gartner occupies a position within the German precision-fabrication cluster serving architecturally significant towers. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Kawneer (Arconic) |
| Schüco |
| Permasteelisa |
| Josef Gartner |
| Enclos |
| Yuanda Holding Group |
| YKK AP |
| Reynaers Aluminium |
| Jangho Group |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation phase-down gates qualified supply for krypton-filled insulating glass units while reserving premium-tier pricing access to fabricators with certified CE marking protocols. This environmental mandate compresses the viable supplier pool for climate-sensitive envelopes and stratifies pricing power between compliant and non-compliant system houses.
Pricing Analysis
Engineering-and-installation bundling versus component-only supply splits pricing structures across project scales. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under GB 55015-2021 and EU Energy Performance of Buildings Directive thresholds, with factory-controlled unitized systems commanding substantial premiums over field-assembled stick-built alternatives. Cost compression in economy-tier stick-built segments is intensifying because London Metal Exchange aluminum volatility erodes contractor margins without substitution options for structural mullions. Property developers funding megaprojects exhibit lowest price sensitivity, while independent contractors serving retrofit markets face acute margin pressure.
Supply Chain Analysis
Regional distribution centers in Shanghai, Düsseldorf, and Dubai anchor hub-and-spoke patterns that position finished panels within crane-reachable distances of supertall construction sites. Primary aluminum smelting concentrates in China, Russia, and Canada, while architectural glass production draws from Chinese state-owned enterprises controlling majority global capacity. Structural silicone sealant and polyamide thermal break materials hinge on petrochemical feedstocks exposed to commodity price swings. Single-source vulnerability pervades float glass supply, where concentration among Chinese producers creates pipeline risk for international projects. Distribution runs through fabricator-owned technical service subsidiaries that manage field installation quality.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Curtain wall economics favor margin expansion through specification upgrades toward Passive House-compatible assemblies and factory-controlled unitized systems that reduce field labor exposure and warranty liability.
For Market Incumbents: Hedge aluminum price exposure through long-term London Metal Exchange contract hedging or captive extrusion capacity in coastal Chinese provinces. Deepen thermal break engineering capabilities to meet GB 55015-2021 and EU Energy Performance of Buildings Directive thresholds that emerging competitors cannot certify. Consolidate position in pressure-equalized rainscreen engineering where specialized cavity ventilation design expertise creates defendable differentiation.
For New Entrants and Emerging Players: Direct-to-developer digital specification platforms bypass architect-led material selection and connect fabricators directly with procurement teams at sovereign wealth funds. Target India's Bangalore and Hyderabad commercial corridors where first-time unitized system adoption creates white-space without entrenched incumbent relationships. Pursue local fabrication partnerships rather than greenfield capacity to compress market entry timelines.
For Investors and Strategic Acquirers: Valuations sit cheapest among installation-specialized contractors lacking backward integration into aluminum extrusion or thermal break technology. Long-term viability centers on envelope commissioning compliance capabilities under tightening EPA and ICC code cycles. Watch for inflection when developer procurement teams reduce pre-qualified supplier pools below three per megaproject, triggering consolidation premiums for scaled fabricators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive 6063-T6 alloy supply hedges London Metal Exchange volatility for unitized panel production. |
| Thermal Break Technology Licensing | Polyamide and polyurethane thermal break patents unlock GB 55015-2021 and EU directive compliance premiums. |
| Regional Fabrication Partnership | Local panel assembly in Bangalore and Hyderabad accelerates India's first-time unitized system adoption. |
| Facade Engineering Talent Acquisition | Düsseldorf and Tokyo computational fluid dynamics expertise enables wind-driven rain modeling for supertall projects. |
| Passive House Certification Program | Certified assemblies capture EU Green Deal renovation wave funding for envelope upgrade specifications. |
Methodological Framework
Coverage spans China, Germany, the United States, Japan, and India, with primary inputs from each market cluster through structured interviews with facade engineering consultants, curtain wall procurement managers at property developers, aluminum extrusion plant managers, and envelope commissioning specialists. Secondary validation draws from GB standard filings, EU Energy Performance of Buildings Directive submissions, EPA enforcement databases, and ICC code cycle documentation. Bottom-up project pipeline tracking triangulates against top-down construction spending forecasts to anchor volume estimates.
Rate-of-change decomposition separates volume growth from specification mix shifts and price-level adjustments across the projection horizon. Segmentation dimensions include system type, material composition, application typology, and end-user technical authority. CAGRs derive from fitted trend extrapolation moderated by regulatory inflection points and raw material cycle positioning. Industry-specific forecast inputs incorporate supertall construction pipeline data from Shanghai, Shenzhen, and Beijing, plus EU Green Deal renovation wave funding allocations for envelope upgrades.
The model assumes a particular technology adoption path; alternative pathways for vacuum-insulated glass or fiber-reinforced polymer substitution would alter the outlook for aluminum framing dominance. Forecasts reflect stated assumptions regarding GB standard enforcement timelines, London Metal Exchange aluminum price bands, and sovereign wealth fund megaproject commitment levels. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Asia-Pacific Construction Adhesives Market
Building & Construction Materials
Asia-Pacific Particle Board Market
Building & Construction Materials
Marble Market
Building & Construction Materials
North America Insulated Concrete Form (ICF) Market
Building & Construction Materials
Vapor Barriers Market
Building & Construction Materials
Decorative Tiles Market
Building & Construction Materials
Concrete Form Oil Market
Building & Construction Materials
Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Poland Ceramic Tiles Market
Building & Construction Materials
North America Gypsum Board Market
Building & Construction Materials
Gypsum Concrete Market
Building & Construction Materials
Italy Oriented Strand Board Market
Building & Construction Materials
US Retractable Roofing System Market
Building & Construction Materials
Global Elastic Rail Fasteners Market
Building & Construction Materials
Air Barrier Market
Building & Construction Materials
Customized Shopfitting Materials Market