
 Roof Coating Market | 2026-2036
Roof Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Roof Coating Market Intelligence
The historical distinction between new-build specification and retrofit application is collapsing, with Facility Maintainers and Property Managers now driving procurement cycles for building lifecycle extension. Sika AG leverages its strong presence in construction chemicals to offer integrated waterproofing and coating systems for large-scale commercial projects. The Sherwin-Williams Company competes through its extensive distribution network, reaching both professional contractors and property management firms directly.
Roof coating refers to a monolithic, fluid-applied membrane that cures to form a seamless, elastic layer over a roof substrate. It primarily provides waterproofing and reflects solar radiation to extend a roof's service life and improve building energy efficiency. Acrylic formulations lead market volume due to cost, but silicone and polyurethane coatings capture significant value with superior waterproofing and durability. Demand from commercial buildings far outweighs other applications, focusing on extending the asset life of existing structures.
The US EPA's ENERGY STAR program and the EU Green Deal create specific demand for coatings with high solar reflectivity and emissivity values. Local building codes, including California's Title 24 and similar standards in Australia, establish performance benchmarks that coatings must meet for market entry. Formulators now face a strategic choice between specializing in high-margin polyurethane systems or achieving scale in the cost-competitive acrylics segment.
Market Dynamics
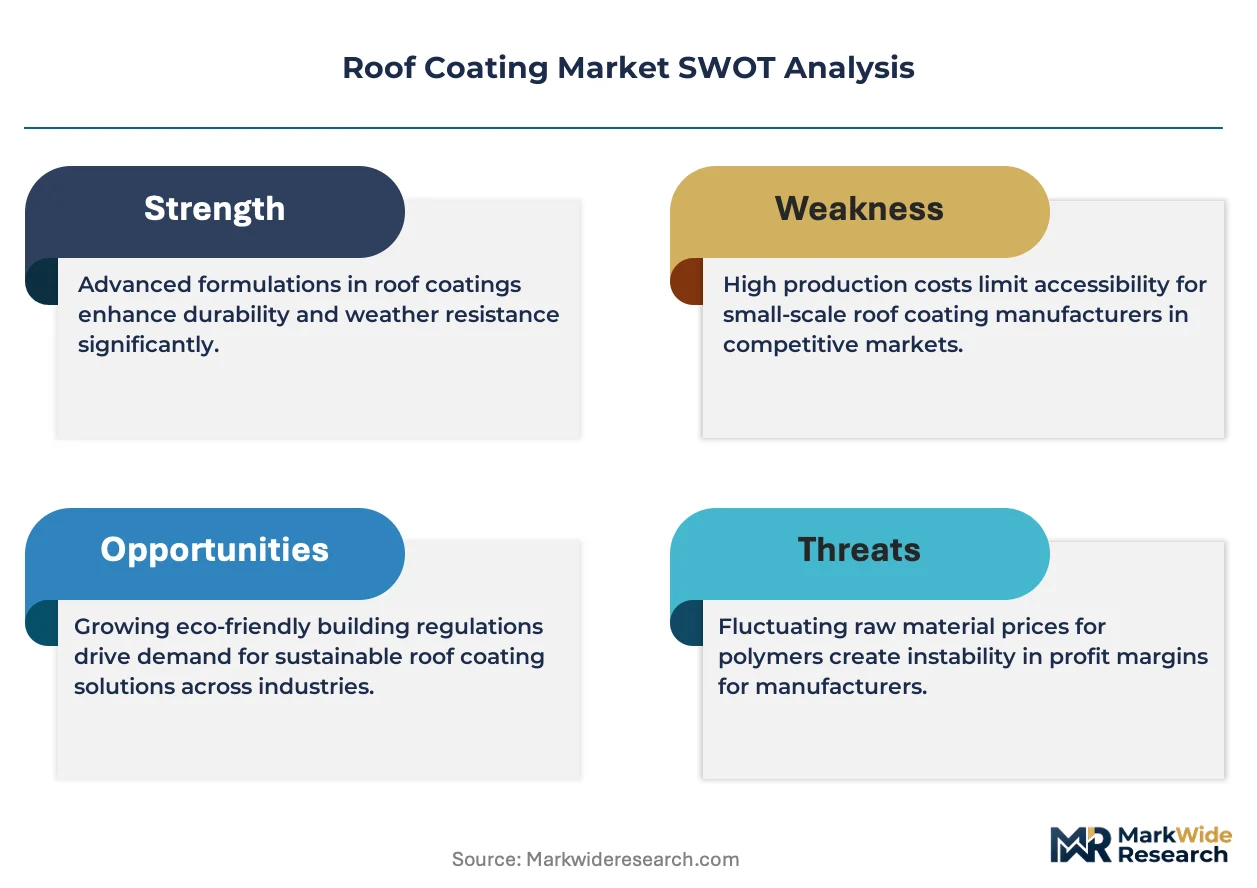
The central force shaping the roof coating market is the convergence of stringent energy efficiency regulations and a demand shift toward building lifecycle extension. Mandates like the EU Green Deal and performance standards from the US EPA are compelling property owners to adopt reflective technologies, moving procurement decisions beyond simple waterproofing to long-term asset management.
Growth Catalysts
- Energy Efficiency Mandates:Regulatory frameworks, including the EU Green Deal and California's Title 24, create non-discretionary demand for cool roof coatings with high solar reflectivity, particularly for commercial buildings in urban centers.
- Commercial Retrofit Demand:Facility managers of large-scale commercial properties are increasingly specifying coatings to defer costly roof replacements, extend asset life, and improve building envelope performance, especially in Germany and the United States.
- Material Science Advances:The development of durable and cost-effective acrylic formulations, alongside high-performance silicone and polyurethane systems, provides a range of solutions catering to different climatic conditions and budget constraints.
Market Restraints
- Raw Material Volatility:The price and availability of key inputs, such as acrylic polymers, titanium dioxide, and isocyanates for polyurethane systems, are subject to fluctuations in the petrochemical market, impacting formulator margins.
- Substrate Condition Dependency:The performance of any roof coating is highly dependent on the condition of the underlying roof substrate, requiring extensive and costly surface preparation that can deter some building owners.
- Competition from Single-Ply Membranes:In the new construction segment, fluid-applied coatings face significant competition from single-ply roofing systems like TPO and PVC, which offer integrated waterproofing solutions from the outset.
Strategic Opportunities
- Bio-Based Formulations:Developing coatings from renewable or bio-based raw materials presents an opportunity to meet corporate sustainability goals and appeal to environmentally conscious asset owners, creating a new premium product tier.
- Expansion in Data Center Construction:The global build-out of data centers, which have critical cooling requirements and vast, low-slope roofs, offers a significant, high-value application for advanced reflective and waterproof coating systems.
- Integration with Building Automation:There is an opportunity to bundle cool roof coatings with smart building sensors and management systems to provide property owners with verifiable data on energy savings and roof performance.
Industry Challenges
- Applicator Skill Gap:A shortage of trained and certified contractors who can correctly prepare substrates and apply high-performance silicone and polyurethane systems limits the market penetration of these premium technologies.
- Performance Verification and Standardization:Ensuring long-term, real-world performance matches laboratory-tested values for solar reflectivity and emissivity remains a challenge, leading to a need for more rigorous, third-party field validation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roof Coating Market |
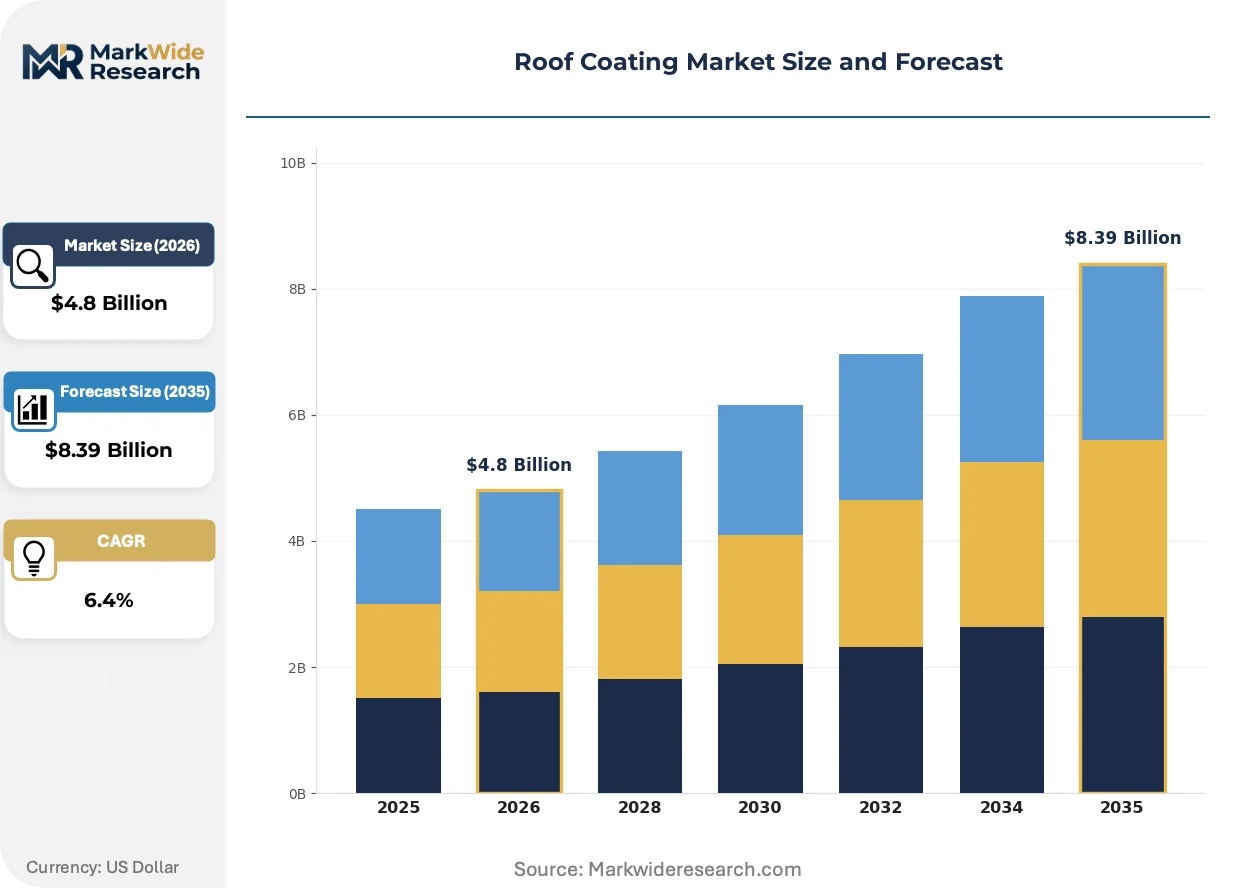
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Silicone, Polyurethane, Bitumen, Elastomeric Application: Commercial Buildings, Residential Properties, Industrial Facilities, Agricultural Structures Technology: Reflective, Insulative, Waterproof, Anti-Corrosion, UV Resistant End User: Construction Companies, Property Managers, Facility Maintainers, Renovation Firms |
| Companies Covered | PPG Industries, Carlisle Construction Materials, GAF Materials Corporation, Akzo Nobel N.V., RPM International Inc., Sika AG, The Sherwin-Williams Company, Owens Corning, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roof Coating Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from basic waterproofing toward multifunctional systems that deliver quantifiable energy savings and integrate with broader building asset management strategies. This shift elevates coatings from a maintenance expense to a strategic investment in operational efficiency and sustainability.
Hybrid formulations combining different polymer technologies, such as silicone-modified acrylics, are gaining traction. Commercial building owners and facility managers are the primary adopters, seeking a balance between the affordability of acrylics and the superior waterproofing of silicones. The proliferation of these blended products is fragmenting the traditional market structure, creating a distinct mid-tier performance category between commodity and premium solutions.
Local and regional energy codes are setting de facto technical standards for the entire industry. California's Title 24, for example, establishes strict Solar Reflectance Index (SRI) requirements for low-slope commercial roofs, making reflective coatings a baseline specification. This forces formulators to engineer products that specifically meet or exceed these benchmarks, directly influencing R&D priorities within the acrylic and silicone segments.
A notable shift in purchasing behavior involves the adoption of total cost of ownership (TCO) analysis by institutional asset owners. This model prioritizes long-term performance, warranty coverage, and energy savings over the lowest initial application cost, disrupting the traditional contractor-led bidding process. The trend is most visible within large commercial real estate portfolios and public sector buildings across the United States and Western Europe.
Roof Coating Market Segmentation
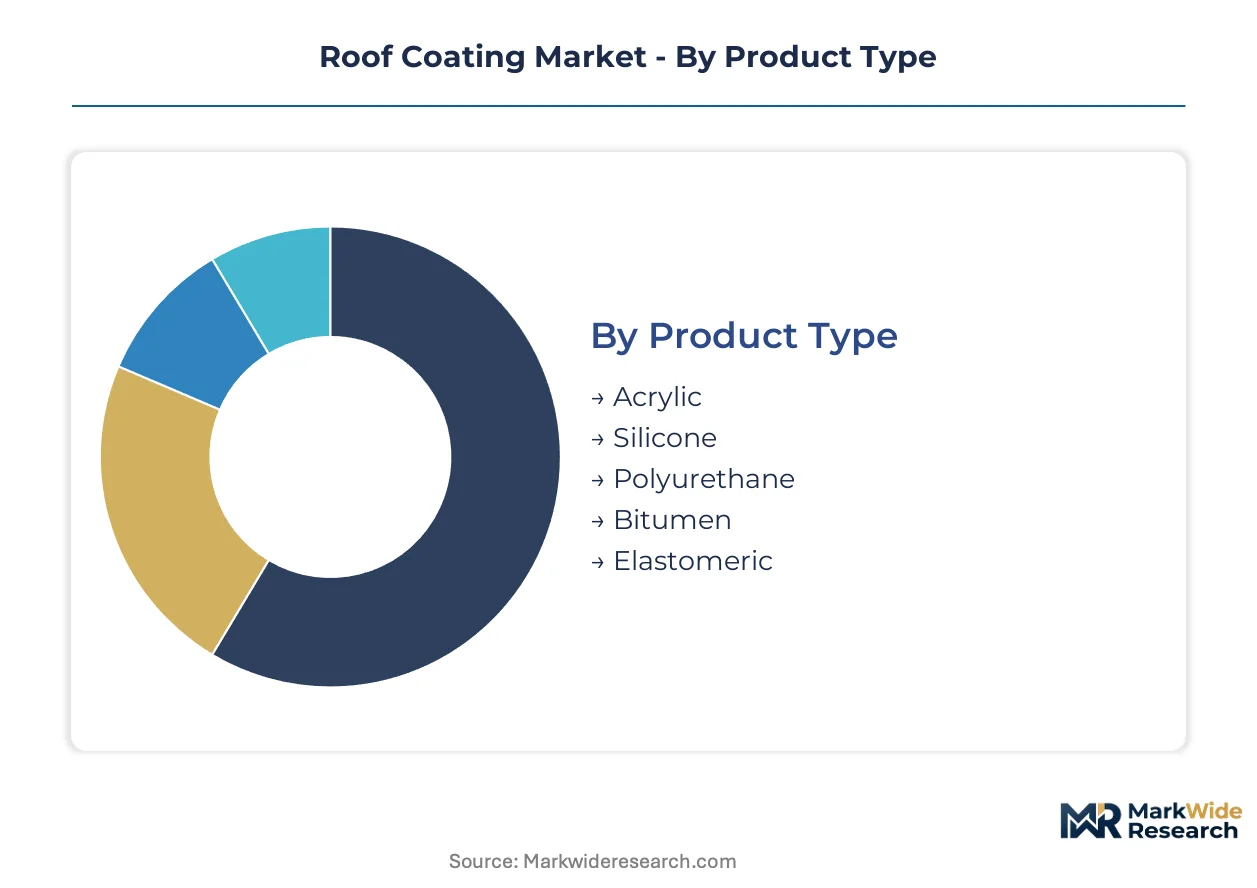
Roof coating market segmentation provides a granular view of product types, applications, and end-user dynamics. This detailed classification helps stakeholders understand specific demand drivers and the performance characteristics valued across different projects. Each segment reflects distinct purchasing criteria and operational requirements.
Product Type:
The market's product type segmentation reveals distinct distribution channels, with commodity solutions often moving through broad retail and premium offerings requiring specialized contractor networks.
- Acrylic:Acrylic coatings are water-based formulations known for cost-effectiveness and ease of application. Demand concentrates in commercial buildings across the United States for large-scale retrofit projects due to budget considerations.
- Silicone:Silicone coatings provide superior waterproofing and UV resistance, maintaining elasticity over a broad temperature range. These systems find significant value in data center construction due to critical cooling requirements and long-term performance needs.
- Polyurethane:Polyurethane coatings offer exceptional abrasion resistance and durability, suitable for high-traffic or impact-prone roof surfaces.
- Bitumen:Bitumen-based coatings provide traditional waterproofing properties, often used for repair and maintenance of existing asphaltic roofs.
- Elastomeric:Elastomeric coatings are highly flexible, accommodating structural movement and preventing cracks in various climatic conditions.
Acrylic dominates the installed base for roof coatings. Silicone is where expansion concentrates, driven by performance demands.
Application:
Application segmentation highlights where specific performance attributes are prioritized, influencing material selection and project scope across diverse building types.
- Commercial Buildings:Commercial buildings represent the largest application segment, driven by the need for energy efficiency and asset life extension. Regulatory mandates like the EU Green Deal compel owners to adopt reflective systems.
- Residential Properties:Residential applications focus on aesthetic appeal, basic waterproofing, and moderate energy savings for homeowners. This segment often prioritizes ease of application.
- Industrial Facilities:Industrial facilities require robust, durable coatings to withstand harsh environmental conditions and chemical exposure. These applications frequently demand anti-corrosion and specialized waterproofing solutions.
- Agricultural Structures:Agricultural structures utilize coatings for weather protection, temperature regulation, and preservation of stored goods or livestock environments.
Commercial buildings drive the largest demand volume for roof coatings. Industrial facilities show consistent, specialized growth with specific performance requirements.
Technology:
Technology segmentation showcases the functional differentiation of roof coating solutions, directly impacting building performance and longevity.
- Reflective:Reflective coatings incorporate pigments that bounce solar radiation away from the roof surface, reducing heat absorption. The US EPA's ENERGY STAR program drives demand for these systems in urban centers to mitigate heat island effects.
- Insulative:Insulative coatings contain micro-spheres or other additives to reduce heat transfer through the roof, contributing to interior temperature stability. This technology supports energy savings in both hot and cold climates.
- Waterproof:Waterproof coatings form a monolithic, seamless barrier over the roof substrate, preventing water ingress. This foundational technology remains critical for asset protection in regions with heavy precipitation.
- Anti-Corrosion:Anti-corrosion coatings protect metal roof substrates from rust and degradation, extending the structural integrity of the building.
- UV Resistant:UV resistant coatings prevent degradation from prolonged sun exposure, maintaining the coating's integrity and reflective properties over time.
Reflective technologies demonstrate the steepest expansion trajectory due to energy mandates. Waterproofing remains a fundamental requirement across all roof coating applications.
End User:
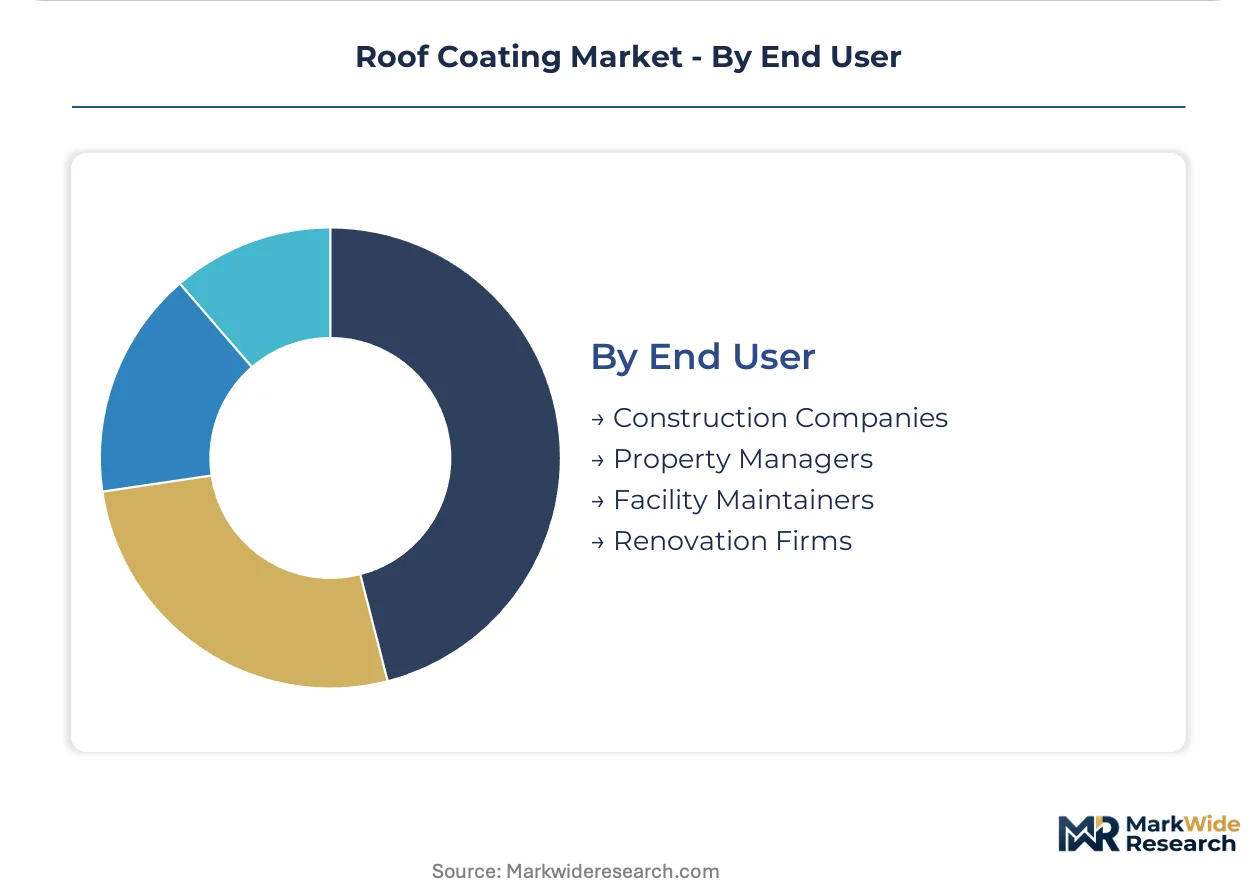
End-user segmentation reveals the evolving procurement landscape, with decision-making shifting towards long-term asset management rather than initial construction.
- Construction Companies:Construction companies integrate roof coatings into new build projects as part of the initial building envelope specification. They often prioritize material compatibility and application efficiency.
- Property Managers:Property managers increasingly specify roof coatings for portfolio-wide asset protection and energy cost reduction. Their procurement cycles prioritize total cost of ownership and verifiable performance data.
- Facility Maintainers:Facility maintainers drive demand for coatings that extend the service life of existing structures and minimize operational disruption. Their focus includes ease of application and long-term durability.
- Renovation Firms:Renovation firms utilize roof coatings to upgrade existing structures, improving energy performance and extending the lifespan of older roofs.
Property managers and facility maintainers exert substantial influence on procurement decisions. Construction companies integrate coatings for project completion and initial waterproofing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized coating formulations developed in European research hubs often find significant application in the commercial building sectors of North America and Asia. This global flow of material science and application expertise drives innovation across diverse climatic zones. Property owners in high-density urban areas prioritize solutions that enhance energy efficiency and extend roof asset life.
United States
Demand for roof coatings in the United States is primarily driven by commercial retrofit projects and stringent energy efficiency goals. The US EPA's ENERGY STAR program and California's Title 24 mandate the adoption of cool roof technologies. Urban centers like Los Angeles and New York City actively implement reflective coatings to mitigate heat island effects and reduce cooling loads.
Germany
German commercial building owners increasingly specify roof coatings for long-term asset management and sustainability objectives. The EU Green Deal and national energy efficiency standards compel property upgrades. Major cities such as Berlin and Munich are upgrading existing large-scale structures to meet performance benchmarks for energy consumption.
Japan
Japanese urban areas show strong demand for roof coatings to combat the urban heat island effect and preserve building integrity. Local building codes and national energy conservation laws promote reflective and insulative solutions. Tokyo and Osaka prioritize reflective coatings for high-density commercial properties, focusing on energy savings and tenant comfort.
China
China's rapid urbanization and focus on energy conservation fuel significant demand for advanced roof coating systems. The country's dual carbon goals and national building energy efficiency standards are driving widespread adoption. Yangtze River Delta cities like Shanghai are adopting advanced roofing systems for large industrial and commercial facilities.
India
Indian demand for roof coatings stems from the need for cooling load reduction and expansive infrastructure development. National building codes increasingly promote green building practices and energy-efficient materials. Metropolitan areas such as Mumbai and Delhi are seeing increased use of reflective coatings for large commercial and institutional complexes.
Roof Coating Market Key Industry Players
Player mix skews toward a blend of large, diversified chemical companies and specialized coating manufacturers. The market structure exhibits a tiered approach, with premium offerings from global players and cost-effective solutions from regional specialists. Key strategic archetypes include integrated solution providers and extensive distribution network operators. Dominant competitive moves involve portfolio diversification into comprehensive systems and geographic expansion to capture retrofit demand.
Global chemical conglomerates like Sika AG, a Switzerland-based company, occupy a significant position in the market. This entity often provides integrated waterproofing and coating systems for large commercial projects, leveraging its construction chemicals expertise across various building applications. Specialized coating manufacturers such as The Sherwin-Williams Company and US-based PPG Industries exemplify extensive distribution networks, reaching a broad base of professional contractors and property management firms with diverse product portfolios. These firms serve both new construction and critical retrofit segments.
| Leading Market Players |
|---|
| PPG Industries |
| Carlisle Construction Materials |
| GAF Materials Corporation |
| Akzo Nobel N.V. |
| RPM International Inc. |
| Sika AG |
| The Sherwin-Williams Company |
| Owens Corning |
| BASF SE |
| Others |
Cost & Logistics Intelligence
Three-month lead times for specialized silicone polymers directly influence the pricing power of premium roof coating manufacturers, reflecting tight supply-side control over key performance inputs. This inventory dynamic shapes strategic procurement decisions across the market.
Pricing Analysis
The pricing gap between commodity acrylics and advanced silicone/polyurethane systems defines market value. Project-based pricing dominates for large commercial applications, with price differentiation stemming from coating durability and specific regulatory certifications like ENERGY STAR. Pricing softness in the acrylic segment reflects intense competition from regional specialists. Commercial property managers, focused on total cost of ownership, exhibit lower price sensitivity than residential homeowners who prioritize initial application cost.
Supply Chain Analysis
Increased inbound logistics costs, particularly for specialty chemicals sourced from Asia, impact formulator margins for advanced roof coatings. Supply concentrates in Germany for high-performance polymers and the United States for acrylic resins. The market relies on titanium dioxide, acrylic polymers, and isocyanates for polyurethane systems. Raw material volatility poses a significant structural risk. Distribution runs through specialized contractor networks for premium products and broad retail channels for commodity solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The roof coating market presents a significant opportunity for value creation, yet a critical applicator skill gap limits the adoption of high-performance systems. This scarcity of trained professionals demands strategic interventions from all market participants.
For Market Incumbents: Shield existing market share by investing in applicator training and certification programs, counteracting the skill gap that limits premium product adoption. Consolidate smaller regional players to expand geographic reach and capture retrofit demand, especially given the competition from single-ply membranes. Leverage R&D into bio-based formulations to differentiate against traditional petrochemical-reliant offerings.
For New Entrants and Emerging Players: Anchor in the data center construction segment, which offers high-value application for advanced reflective and waterproof coating systems. Target underpenetrated urban centers in India and China, focusing on commercial retrofit projects driven by energy efficiency mandates. A direct-to-property-manager sales approach, emphasizing verifiable energy savings data, provides a strong go-to-market angle.
For Investors and Strategic Acquirers: Carve-out targets emerge from large chemical conglomerates looking to divest non-core coating divisions, offering specialized product lines with established distribution. The long-term viability of the roof coating market is strong, driven by persistent energy efficiency mandates and building lifecycle extension needs. Focus on acquiring vertically integrated mid-cap specialists with strong regional applicator networks. The signal to watch is the increasing adoption rate of smart building integration features.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Bio-Based Formulations | This initiative meets corporate sustainability goals and appeals to environmentally conscious asset owners in Germany. |
| Expand Applicator Training Programs | Addressing the applicator skill gap enhances market penetration for high-performance silicone and polyurethane systems. |
| Integrate with Building Automation Systems | Bundling cool roof coatings with smart sensors provides property owners with verifiable energy savings data. |
| Acquire Regional Retrofit Specialists | Consolidation strengthens market position in commercial retrofit segments across the United States. |
| Invest in Advanced Reflective Pigment R&D | This innovation supports compliance with stringent energy efficiency regulations like California's Title 24. |
Research Approach
A standing panel of facility managers, property developers, and coating formulators provided ongoing calibration for primary data collection. This involved extensive interviews with industry stakeholders across key geographies, complemented by rigorous secondary validation. Secondary sources included regulatory filings, national building codes like California's Title 24, and reports from the US EPA. The analysis employed both bottom-up market sizing and top-down validation through expert consensus.
Forecast outputs were consistently checked against external benchmarks, including regional construction spending and energy efficiency investment trends across the analysis window. The analytical framework modeled market dynamics across product type, application, end-user, and regional regulatory mandates. Compound Annual Growth Rates were derived from historical data trends and projected adoption rates of cool roof technologies. Key forecast inputs included projected commercial retrofit activity and raw material availability.
Decision-makers should treat outputs as directional under current energy policy stability and raw material supply chain assumptions; material deviation would warrant model refresh. Forecasts reflect these base assumptions, but significant shifts in petrochemical pricing or regulatory enforcement could alter projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
US Prefabricated Steel Market
Building & Construction Materials
Global Steel Sections Market
Building & Construction Materials
Industrial Thermal Insulation Market
Building & Construction Materials
PVC Window Market
Building & Construction Materials
Acoustic Plasterboard Market
Building & Construction Materials
Composite Roof Shingle Market
Building & Construction Materials
Balustrade Market
Building & Construction Materials
Global Roofing Market
Building & Construction Materials
India Ready-Mix Concrete Market
Building & Construction Materials
Concrete Sealer Market
Building & Construction Materials
Global Formwork Market
Building & Construction Materials
Vitrified Tiles Market
Building & Construction Materials
ASEAN Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
France Oriented Strand Board Market
Building & Construction Materials
Sheet Metal Market
Building & Construction Materials
Thinset Mortar Market